
 Sea Skimmer Missile Market | 2026-2036
Sea Skimmer Missile Market Size, Share, and Industry Trends Forecast 2026-2036
Sea Skimmer Missile Market Outlook
Extended-range precision tiers is bifurcating the competitive landscape between legacy arsenals and next-generation procurements. MBDA leverages its network of European manufacturing sites to sustain supply continuity across multiple NATO navies. BrahMos Aerospace anchors its position through in-house production of ramjet propulsion systems. Raytheon Technologies differentiates via integrated seeker-to-shooter data-link architectures that compress engagement timelines.
A sea skimmer missile is a guided weapon engineered to maintain sustained flight within three to ten meters above the water surface, exploiting radar clutter and earth-curvature masking to penetrate layered ship defenses; its propulsion typically integrates solid-rocket boost with turbojet or ramjet sustainment to achieve Mach 0.8–3.0 terminal velocity against moving maritime targets. The anti-ship missile segment retains the largest revenue pool due to fleet modernization cycles in Pacific and Atlantic theaters, while submarine-launched variants represent the fastest-expanding category as nations prioritize concealed launch platforms for first-strike credibility. Surface ship launch platforms dominate operational inventories, though aircraft deployment is gaining traction where carrier aviation extends strike radius beyond shore-based sensor coverage.
The US Department of Defense imposes MIL-STD-461 and MIL-STD-464 electromagnetic compatibility requirements that constrain subsystem vendor selection and extend qualification timelines for new entrants. European procurement through OCCAR and national defense ministries applies STANAG interoperability protocols that favor modular seeker architectures compatible across allied launch platforms. Export control regimes under the Wassenaar Arrangement and national munitions lists restrict technology transfer for terrain-mapping correlators and dual-use guidance chipsets. Stakeholders must weigh sovereign production mandates against access to integrated Allied datalink ecosystems when positioning for forthcoming multi-year naval acquisition programs.
Market Dynamics
Ramjet propulsion miniaturization is compressing engagement timelines and forcing legacy solid-rocket architectures toward obsolescence in littoral warfare scenarios.
Growth Catalysts
- Indo-Pacific littoral expansion:Archipelagic navies in Indonesia and the Philippines prioritize sea-skimming weapons for area-denial against surface combatants operating within exclusive economic zones.
- MIL-STD-461/464 compliance mandates:US electromagnetic compatibility standards force subsystem upgrades that improve seeker resilience against electronic countermeasures, driving replacement cycles.
- Terrain-following correlator diffusion:Commercial dual-use guidance chipsets from semiconductor foundries enable indigenous development programs in multiple sovereign defense industrial bases.
Market Restraints
- Rare-earth magnet supply concentration:Chinese dominance in neodymium processing creates vulnerability in ramjet motor control systems and fin actuator mechanisms.
- Wassenaar Arrangement export controls:Terrain-mapping correlators and precision gyroscopes face multilateral restriction, fragmenting supplier access for non-aligned nations.
- Ramjet thermal management complexity:Sustained Mach 2+ flight demands exotic alloys that extend manufacturing lead times and inflate unit economics beyond solid-rocket alternatives.
Strategic Opportunities
- Submarine vertical launch integration:Concealed undersea platforms in Australia and Vietnam seek encapsulated canister systems for first-strike credibility without surface signature.
- OCCAR modular seeker protocols:European STANAG interoperability creates openings for sensor-agnostic guidance packages compatible across Franco-Italian and German-Spanish launch platforms.
- AI-actuated terminal homing:Machine-vision discrimination algorithms converging with millimeter-wave seekers enable cluttered-environment target recognition previously unreachable by pure radar.
Industry Challenges
- Systems integration engineering deficit:Prime contractors struggle to recruit guidance-law specialists capable of blending inertial, radar, and electro-optical sensor fusion.
- Qualification timeline compression:MIL-STD-464 electromagnetic environmental effects testing demands anechoic chamber access that bottlenecks new entrant certification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea Skimmer Missile Market |
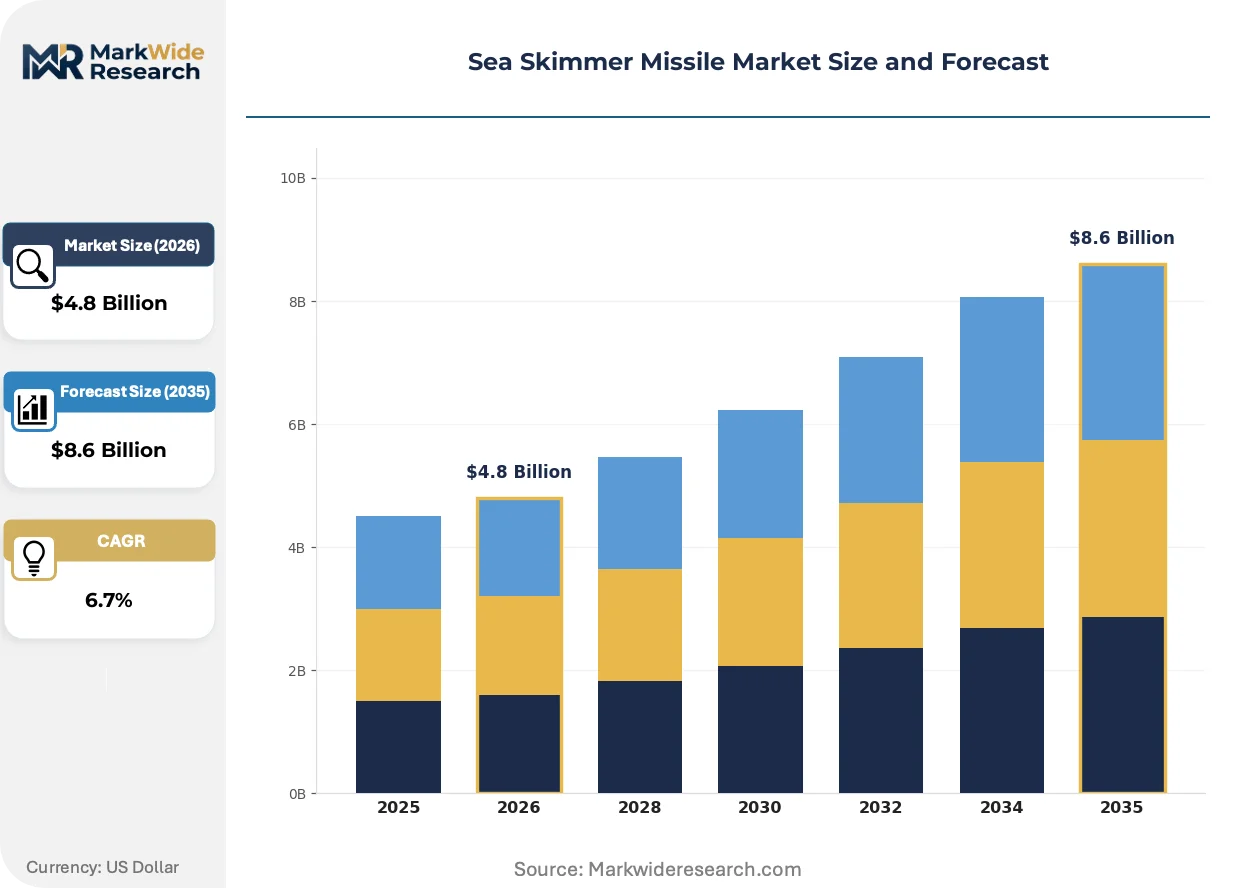
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Ship Missiles, Cruise Missiles, Tactical Missiles, Submarine-Launched Missiles Launch Platform: Surface Ships, Aircraft, Submarines, Ground Launchers Range Category: Short Range, Medium Range, Long Range, Extended Range End User: Military, Defense Contractors, Coast Guards, Naval Forces |
| Companies Covered | MBDA, Kongsberg Gruppen AS, Boeing Company, Northrop Grumman Corporation, Raytheon Technologies, Saab AB, BrahMos Aerospace, Lockheed Martin, Israel Aerospace Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea Skimmer Missile Market Strategic Shifts
Active electronically scanned array seekers are fragmenting traditional monopulse radar architectures and enabling simultaneous multi-target tracking against saturated defenses.
Ramjet sustainment technology is decomposing the historical solid-rocket dominance in anti-ship propulsion. Naval ordnance divisions in France and India field ramjet-powered variants achieving Mach 2.8 terminal velocity with range extensions beyond 400 kilometers. This propulsion shift is decomposing the cost-per-kilometer tradeoffs that previously favored subsonic turbojet alternatives in budget-constrained procurement.
EU Green Deal defense procurement amendments impose lifecycle carbon accounting on munitions manufacturing. MBDA and Rheinmetall reconfigure supply chains to document embodied emissions in propellant production and seeker electronics. Surface-launched variants face stricter scrutiny than air-launched counterparts due to larger booster motor propellant masses.
Fleet modernization cycles are compressing platform-missile integration timelines. Procurement officers in Japan and South Korea demand six-month qualification windows for new seeker software drops, displacing traditional 24-month hardware certification protocols. This tempo shift favors modular open-architecture designs over proprietary closed systems in contested western Pacific theaters.
Sea Skimmer Missile Market Segmentation
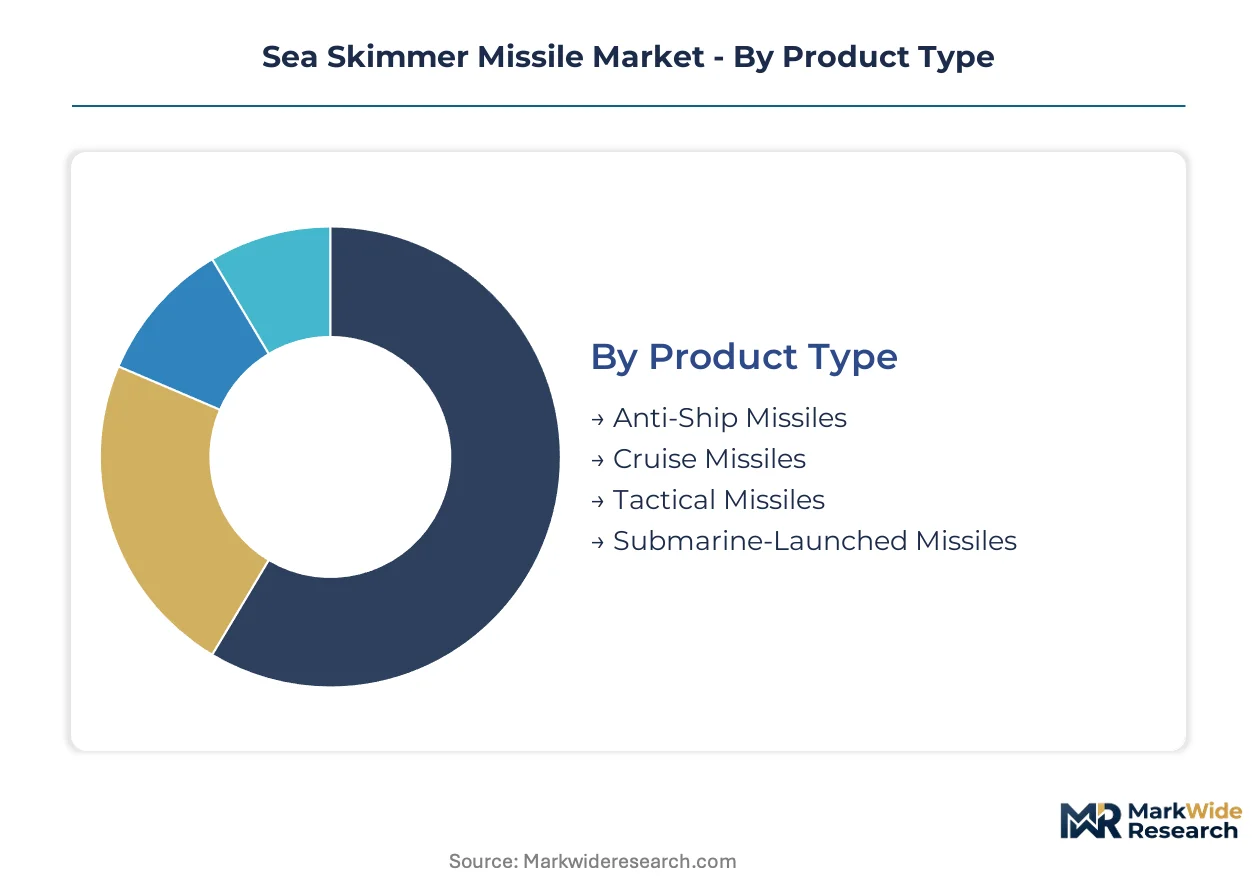
Segmentation in the sea skimmer missile market reveals how propulsion architectures, launch modalities, and range envelopes align with distinct operational doctrines across littoral theaters. Procurement officers weight terminal velocity against platform integration costs when matching missile categories to fleet modernization priorities.
Product Type:
Ramjet-powered variants are displacing solid-rocket architectures in contested littoral zones, forcing legacy product lines toward obsolescence.
- Anti-Ship Missiles:These weapons integrate active radar seekers with sea-skimming flight profiles to penetrate layered ship defenses. Demand concentrates in Indo-Pacific navies where archipelagic geography favors low-altitude approaches against surface combatants operating within exclusive economic zones.
- Submarine-Launched Missiles:Encapsulated canister systems enable concealed undersea launch for first-strike credibility. Australia and Vietnam prioritize vertical launch integration from concealed platforms, compressing development timelines for encapsulated propulsion modules.
- Cruise Missiles:Turbojet sustainment delivers subsonic loitering capability against fixed coastal targets.
- Tactical Missiles:Short-range variants prioritize rapid deployment from mobile coastal batteries.
Anti-ship missiles anchor the volume base while submarine-launched variants gain share at the steepest rate.
Launch Platform:
Platform selection determines electromagnetic signature management and sensor-to-shooter datalink architecture requirements.
- Surface Ships:Vertical launch systems and deck-mounted canisters dominate operational inventories across NATO and Pacific fleets. Japan and South Korea demand six-month software qualification windows, displacing traditional hardware certification protocols.
- Aircraft:Carrier-based strike extends engagement radius beyond shore-based sensor coverage. Integration with network-centric targeting systems compresses engagement timelines against maneuvering maritime targets.
- Submarines:Concealed launch platforms minimize pre-launch detection probability.
- Ground Launchers:Mobile coastal batteries provide area-denial coverage for archipelagic territories.
Surface ships retain the largest deployment share while aircraft integration expands most quickly in carrier-operating navies.
Range Category:
Range envelope selection trades propulsion mass against standoff distance in layered defense environments.
- Extended Range:Ramjet sustainment achieves Mach 2.8 terminal velocity beyond 400 kilometers. France and India field variants that decompose historical cost-per-kilometer tradeoffs favoring subsonic alternatives.
- Long Range:Turbojet architectures balance fuel efficiency against flight duration for missions exceeding 200 kilometers.
- Medium Range:Solid-rocket boost with glide sustainment addresses budget-constrained procurement.
- Short Range:Compact motors prioritize rapid reaction against fast-attack craft in congested waterways.
Extended range systems command premium procurement allocations while medium range variants sustain volume in coastal defense programs.
End User:
End-user categories reflect divergent certification requirements and operational tempo expectations.
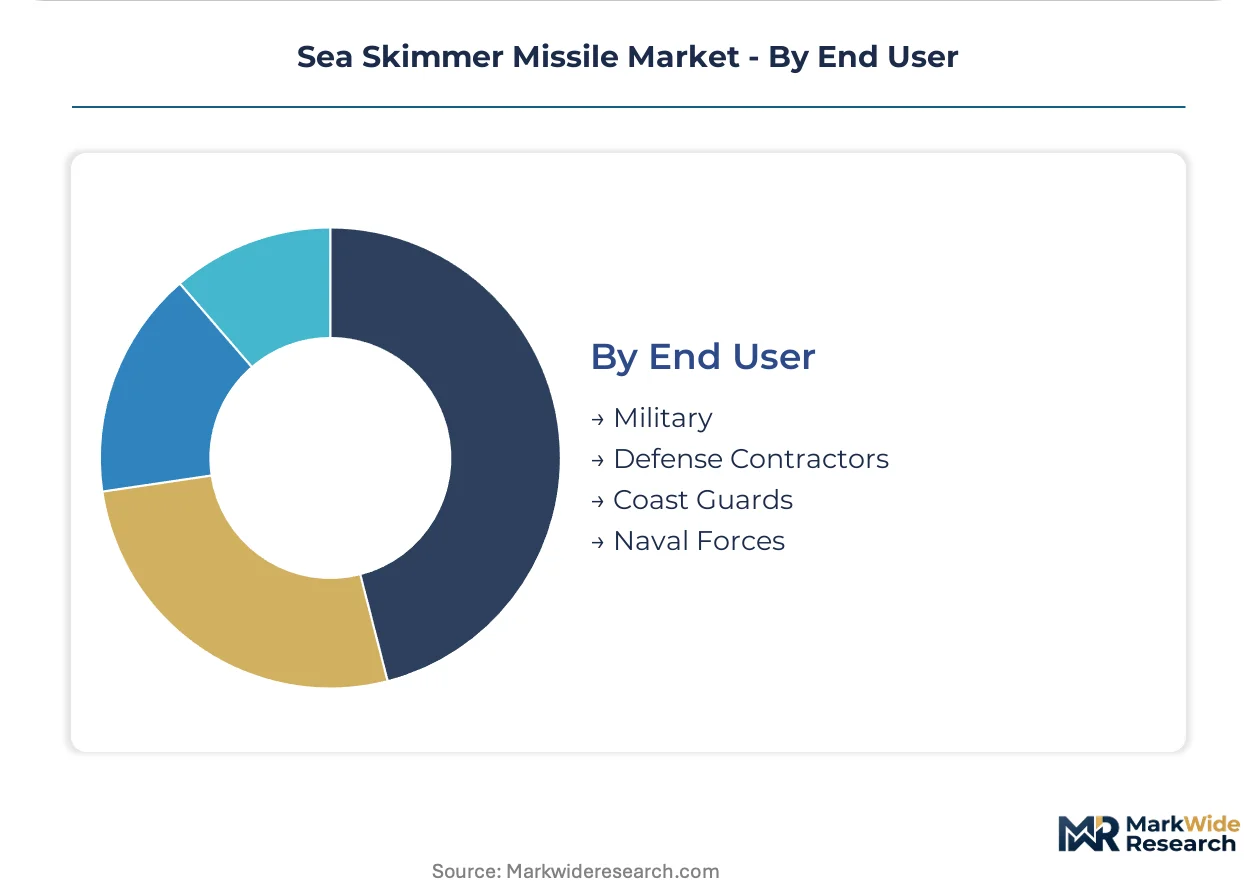
- Naval Forces:Fleet modernization cycles drive replacement of legacy monopulse radar seekers with active electronically scanned array architectures. MIL-STD-461 and MIL-STD-464 compliance mandates force subsystem upgrades that improve resilience against electronic countermeasures.
- Military:Joint-service procurement consolidates seeker development across surface and air launch platforms.
- Defense Contractors:Prime vendors integrate OCCAR modular seeker protocols for STANAG interoperability across European launch platforms.
- Coast Guards:Law enforcement applications prioritize identification friend-or-foe discrimination in cluttered traffic environments.
Naval forces dominate acquisition volume while defense contractors capture expanding systems integration scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ramjet propulsion supply chains concentrate in sovereign defense industrial bases with captive metallurgy capabilities. Procurement patterns diverge between NATO-aligned standardization mandates and indigenous development programs in littoral states.
United States
MIL-STD-461 and MIL-STD-464 compliance mandates drive subsystem replacement cycles across Navy surface fleets. The Department of Defense imposes electromagnetic compatibility requirements that constrain vendor selection and extend qualification timelines. Raytheon Technologies and Northrop Grumman anchor development clusters in Arizona and Virginia, integrating seeker-to-shooter datalink architectures for compressed engagement timelines.
France
Naval Group and MBDA sustain ramjet-powered variant production for Mach 2.8 terminal velocity missions exceeding 400 kilometers. OCCAR procurement applies STANAG interoperability protocols favoring modular seeker architectures across allied launch platforms. The Brittany and Provence-Alpes-Côte d'Azur regions host integrated manufacturing sites supplying multiple NATO navies with network-centric targeting systems.
India
BrahMos Aerospace anchors indigenous production through in-house ramjet propulsion manufacturing, reducing import dependency for terrain-following correlators. The Defence Research and Development Organisation accelerates qualification timelines for submarine vertical launch integration. Hyderabad and Bengaluru clusters concentrate guidance-law specialists blending inertial, radar, and electro-optical sensor fusion.
Japan
Japan Maritime Self-Defense Force procurement officers demand six-month software qualification windows, displacing traditional 24-month hardware certification protocols. METI coordinates dual-use semiconductor foundry access for indigenous terrain-mapping correlator development. The Kanto and Kansai industrial corridors concentrate on modular open-architecture designs compatible with network-centric fleet modernization.
Australia
The AUKUS security pact drives encapsulated canister system procurement for concealed undersea launch platforms. Defence export control harmonization with Wassenaar Arrangement protocols fragments supplier access for precision gyroscope components. South Australia and Western Australia host integration facilities for submarine-launched variants prioritizing first-strike credibility without surface signature.
Sea Skimmer Missile Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the sea skimmer missile ecosystem. European consortium structures concentrate modular seeker development under multilateral procurement frameworks, while Indo-Russian joint ventures exploit sovereign production mandates for propulsion system autonomy. Three archetypes dominate: vertically integrated prime contractors with captive ramjet metallurgy, modular subsystem specialists supplying STANAG-compatible packages, and state-backed entities prioritizing indigenous guidance chipset fabrication. Competitive positioning hardens around strategic partnerships for electromagnetic environmental effects testing access and anechoic chamber qualification bottlenecks.
Among European consortium structures, MBDA exemplifies the vertically integrated archetype with distributed manufacturing across multiple NATO member states. Raytheon Technologies occupies a position representing integrated datalink architecture specialization within US defense procurement frameworks. BrahMos Aerospace anchors the state-backed joint venture model, demonstrating how Indo-Russian collaboration exploits sovereign production mandates while navigating Wassenaar Arrangement terrain-mapping correlator restrictions.
| Leading Market Players |
|---|
| MBDA |
| Kongsberg Gruppen AS |
| Boeing Company |
| Northrop Grumman Corporation |
| Raytheon Technologies |
| Saab AB |
| BrahMos Aerospace |
| Lockheed Martin |
| Israel Aerospace Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
MIL-STD-461 and MIL-STD-464 electromagnetic compatibility mandates gate both subsystem vendor qualification and price differentiation simultaneously, compressing margins for non-compliant suppliers while rewarding primes with anechoic chamber access. The interaction between certification bottlenecks and rare-earth magnet supply concentration creates tiered procurement economics across NATO and Indo-Pacific naval programs.
Pricing Analysis
MIL-STD-464 dictates the pricing tier structure across sea skimmer missile procurement, separating STANAG-certified European consortium offerings from non-aligned indigenous programs. Three-tier pricing structure across extended-range ramjet, long-range turbojet, and solid-rocket coastal defense variants reflects propulsion complexity and seeker sophistication. Cost compression in medium-range solid-rocket tiers is intensifying because commercial dual-use guidance chipsets democratize terrain-following correlator access. Coast guard and littoral defense ministries exhibit highest price sensitivity, while carrier-operating navies prioritize performance over unit economics.
Supply Chain Analysis
Port congestion along Indo-Pacific trade lanes elevates inbound logistics costs for neodymium magnet shipments from Chinese processing facilities to European and Indian assembly plants. Ramjet propulsion manufacturing draws from captive metallurgy capabilities in France, India, and Russia, with precision gyroscope fabrication resting on semiconductor foundry access in Japan and South Korea. Single-source vulnerability in Chinese rare-earth processing creates supply chain risk for fin actuator mechanisms and motor control systems. Distribution runs through sovereign defense industrial bases with OCCAR-coordinated European pooling and AUKUS-aligned Pacific corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as AI-actuated terminal homing and machine-vision seekers threaten to displace traditional radar-dependent architectures. The shift toward software-defined seeker upgrades compresses hardware replacement cycles and opens white-space for modular subsystem specialists.
For Market Incumbents: Secure anechoic chamber qualification capacity ahead of MIL-STD-464 revision cycles, locking out new entrants from electromagnetic environmental effects certification. Deepen backward integration into ramjet metallurgy to offset Chinese rare-earth magnet supply concentration, while anchoring STANAG interoperability protocols across Franco-Italian and German-Spanish launch platforms to entrench modular seeker standards.
For New Entrants and Emerging Players: Differentiate on AI-actuated terminal homing integration with millimeter-wave seekers, targeting cluttered-environment target recognition gaps unreachable by pure radar architectures. The submarine vertical launch segment in Vietnam and Australia presents the most penetrable white-space, with encapsulated canister system demand outpacing qualified supplier capacity. Pursue OCCAR modular seeker protocol certification as the primary go-to-market angle for European naval procurement access.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ramjet propulsion manufacturing as exotic alloy requirements extend production lead times and inflate fixed asset bases. Long-term viability favors acquisition targets with captive terrain-following correlator fabrication and sovereign semiconductor foundry relationships. The signal to watch is Japanese METI dual-use export licensing velocity, which gates indigenous guidance chipset proliferation and determines competitive pressure on European modular seeker pricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Ramjet Metallurgy Backward Integration | Captive neodymium processing in France and India insulates against Chinese supply disruption. |
| AI-Seeker Software Certification | Japan's six-month qualification windows favor modular open-architecture over proprietary systems. |
| Submarine Canister Joint Venture | AUKUS-aligned Australian facilities address Vietnam's concealed launch platform demand. |
| OCCAR Modular Protocol Adoption | STANAG interoperability enables sensor-agnostic packages across NATO allied launchers. |
| Anechoic Chamber Capacity Expansion | MIL-STD-464 bottleneck relief accelerates new entrant electromagnetic qualification timelines. |
Study Parameters
A spread of perspectives from naval procurement officers, guidance-law specialists at prime contractors, electromagnetic effects test engineers, and OCCAR program managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews across these stakeholder categories with secondary validation from Wassenaar Arrangement export control documentation, national munitions list amendments, and electromagnetic compatibility certification registries. Bottom-up triangulation of subsystem vendor capacity data with top-down naval modernization budget allocations anchored volume and value estimates.
Segmentation dimensions modeled span propulsion architecture, launch platform modality, range envelope, and end-user certification tier across the projection horizon. The analytical framework derived CAGRs from fleet replacement cycle timing, sovereign production mandate intensity, and terrain-following correlator diffusion rates. Industry-specific forecast inputs incorporated ramjet thermal management yield curves and dual-use semiconductor foundry capacity utilization for guidance chipset fabrication.
The analysis sits within stated boundaries; outcomes outside sustained Indo-Pacific littoral tension levels or relaxed Wassenaar Arrangement terrain-mapping restrictions would require recalibration. Forecasts reflect documented assumptions regarding electromagnetic compatibility standard stability and rare-earth magnet supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Anti-Ship Missile Defense System Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Naval Radar Market
Naval Warfare
Anti-Submarine Warfare Market
Naval Warfare
Naval Radar Systems Market
Naval Warfare
Naval Gas Turbine Market
Naval Warfare
Littoral Warship Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Amphibious Landing Craft Market
Naval Warfare
Asia-Pacific Naval Vessels Market
Naval Warfare
Marine Penetrators Market
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Fast Attack Craft (FAC) Market