
 Naval Vessel Defense Systems Market | 2026-2036
Naval Vessel Defense Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Naval Vessel Defense Systems Market Foresight
Multi-source contracting for combat system integration is restructuring how prime contractors allocate subsystem risk across naval programs. Lockheed Martin leverages its Aegis combat system franchise to dominate integrated air and missile defense contracts across multiple hull classes. BAE Systems sustains trans-Atlantic electronic warfare and naval gun positions through UK and US facility networks. Thales competes in sonar and command-and-control segments where European sovereignty requirements favor domestic sourcing.
Naval vessel defense systems encompass layered hardware and software suites designed to detect, track, engage, and defeat aerial, surface, and subsurface threats against warships and auxiliaries, typically integrating radar cross-section thresholds below 0.1 square meter for stealth-compatible mast designs. Missile defense and electronic warfare segments command the largest current procurement volumes, reflecting destroyer and frigate modernization cycles across Western and Indo-Pacific fleets. Anti-submarine warfare represents the fastest-expanding technology category as diesel-electric and nuclear submarine proliferation in contested littorals drives demand for towed array and hull-mounted sonar upgrades.
The US Navy's NAVAIR and NAVSEA organizations enforce MIL-STD-461 and MIL-STD-464 electromagnetic compatibility and survivability standards that dictate system architecture choices for any platform entering US service. European procurement through OCCAR and national ministries applies the EU Permanent Structured Cooperation framework and CE marking for dual-use components, while Australia's Defence Strategic Review mandates sovereign industrial capability thresholds for AUKUS-related systems. Stakeholders must monitor how classified data-sharing protocols between Five Eyes partners reshape subcontractor eligibility and technology transfer boundaries for integrated naval defense architectures.
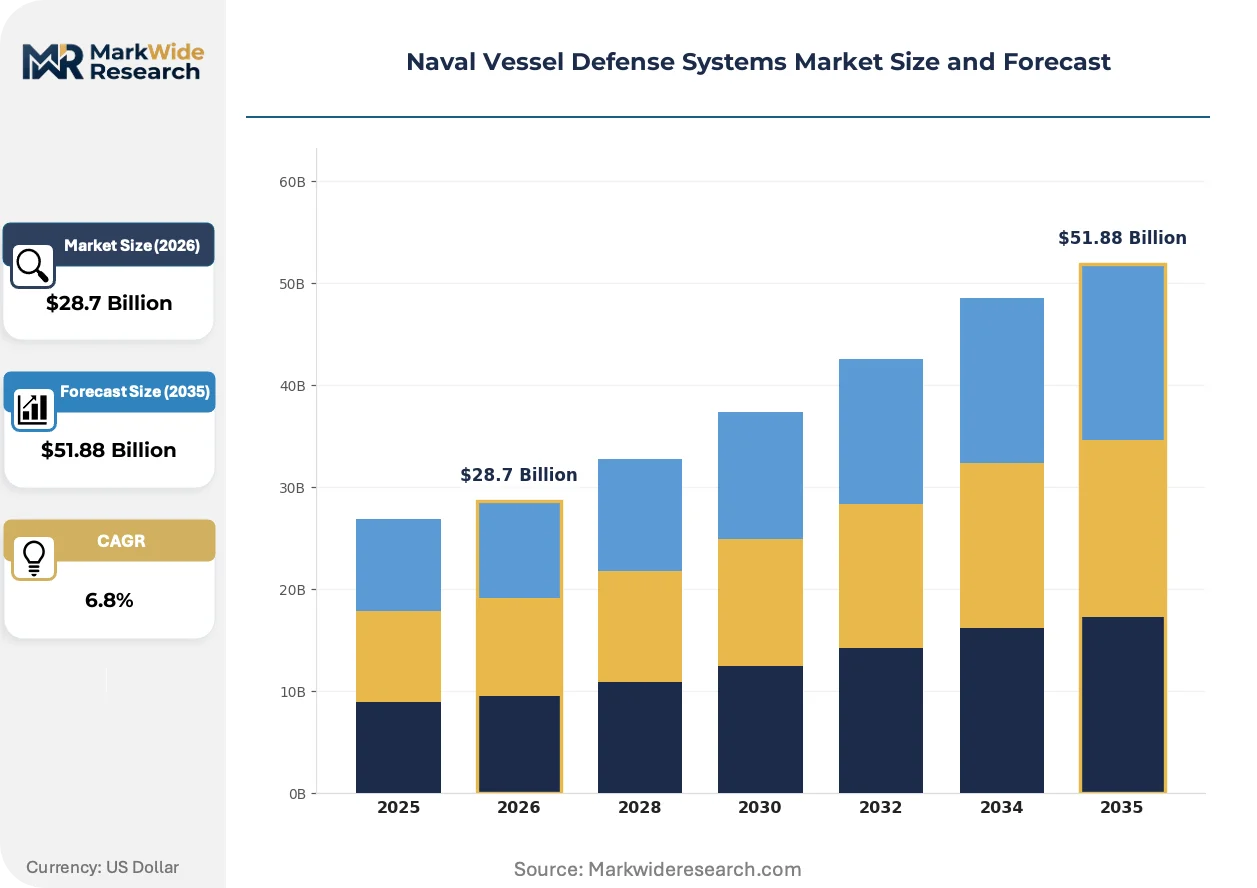
Market Dynamics
Distributed maritime operations doctrine is fragmenting platform procurement across smaller hull classes, forcing defense primes to modularize combat systems for frigate and unmanned surface vessel integration rather than optimizing solely for destroyer-scale architectures.
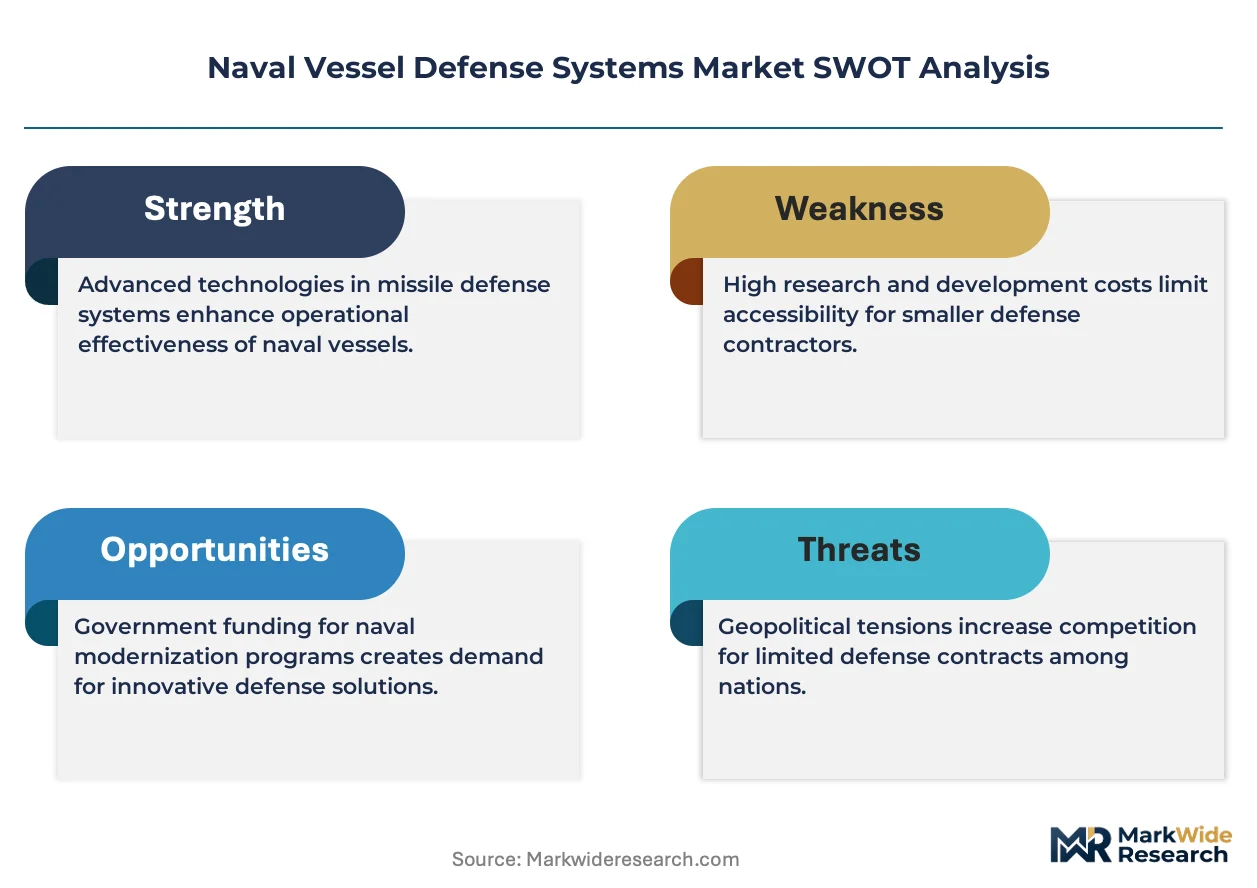
Growth Catalysts
- AUKUS submarine pathway:Australia's Defence Strategic Review mandates sovereign industrial capability thresholds that accelerate local production of integrated sonar and combat management systems for nuclear-powered attack submarines.
- MIL-STD-464 survivability mandates:US Navy electromagnetic compatibility standards compel platform-wide hardening against high-altitude electromagnetic pulse and directed energy threats across all new construction programs.
- Diesel-electric submarine proliferation:Contested littoral environments in the Indo-Pacific drive procurement of variable-depth sonar and towed array systems for littoral combat ships and frigates.
Market Restraints
- Gallium nitride foundry concentration:Active electronically scanned array radar production depends on single-source domestic suppliers for high-purity substrate material, creating vulnerability in transmit-receive module supply chains.
- ITAR-controlled data protocols:US International Traffic in Arms Regulations restrict subsystem integration across Five Eyes partners, fragmenting combat system architectures and duplicating qualification costs.
- Hull-form acoustic signature limits:Existing frigate designs impose physical constraints on sonar dome size and array configuration that degrade detection performance against advanced air-independent propulsion submarines.
Strategic Opportunities
- Unmanned surface vessel integration:Distributed sensor networks enable offboard towed arrays and cooperative engagement capabilities that extend detection ranges beyond manned platform acoustic limits.
- EU Permanent Structured Cooperation:PESCO naval projects create pooled procurement mechanisms for European frigate programs, opening consolidated combat system competitions to qualified non-domestic suppliers.
- Laser weapon system maturation:Solid-state directed energy converges with existing fire control radars to provide close-in defense against swarming unmanned aerial vehicles without magazine depth constraints.
Industry Challenges
- Systems engineering talent scarcity:Combat system integration requires specialized expertise in real-time software architecture and electromagnetic interference mitigation that outpaces naval-focused university program output.
- Legacy analog sonar obsolescence:Hull-mounted arrays on mid-life frigates use proprietary signal processing architectures that resist modular upgrade without platform-level electrical system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naval Vessel Defense Systems Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Missile Defense, Electronic Warfare, Naval Gun Systems, Anti-Submarine Warfare Technology: Radar Systems, Sonar Technology, Command and Control, Cybersecurity Solutions End User: Navies, Coast Guards, Defense Contractors, Commercial Operators Deployment: On-Board Systems, Shore-Based Systems, Mobile Platforms, Integrated Solutions |
| Companies Covered | Lockheed Martin Corporation, General Dynamics Corporation, RTX Corporation, BAE Systems plc, Northrop Grumman Corporation, Thales Group, Israel Aerospace Industries, MBDA, Leonardo S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naval Vessel Defense Systems Market Shifts & Advancements
Artificial intelligence inference at the tactical edge is compressing sensor-to-shooter timelines while exposing classification and training data vulnerabilities that reshape how navies field autonomous engagement systems.
Synthetic aperture sonar processing is converging with machine-learned target classification algorithms to enable automated contact recognition in high-clutter littoral environments. Royal Australian Navy Anzac-class frigate upgrades and US Navy Littoral Combat Ship anti-submarine warfare mission packages are adopting these fused sensor-to-decision architectures. The compression of operator-in-the-loop requirements is forcing command-and-control vendors to revalidate human-machine interface protocols under NATO STANAG 4153 interoperability standards.
EU F-Gas Regulation phase-down mandates are accelerating transition from sulfur hexafluoride switchgear to vacuum-interruptor technology in naval high-voltage distribution systems. Shipbuilders in France, Italy, and Germany must certify new combatant electrical architectures under tightened greenhouse gas footprint thresholds. This regulatory pressure most affects integrated power and propulsion system suppliers serving Horizon-class and FREMM frigate programs, who are redesigning fault protection schemes around alternative insulation media.
Five Eyes partners are consolidating combat system software sustainment under multi-decade performance-based logistics contracts that unbundle traditional hardware procurement from lifecycle engineering support. Canada's Halifax-class modernization and New Zealand's Anzac-class upgrade programs now specify availability-based payment structures rather than fixed-price platform deliveries. This contracting evolution concentrates most visibly in Anglo-Pacific navies seeking to offset personnel shortages through vendor-managed readiness assurance.
Naval Vessel Defense Systems Market Segmentation
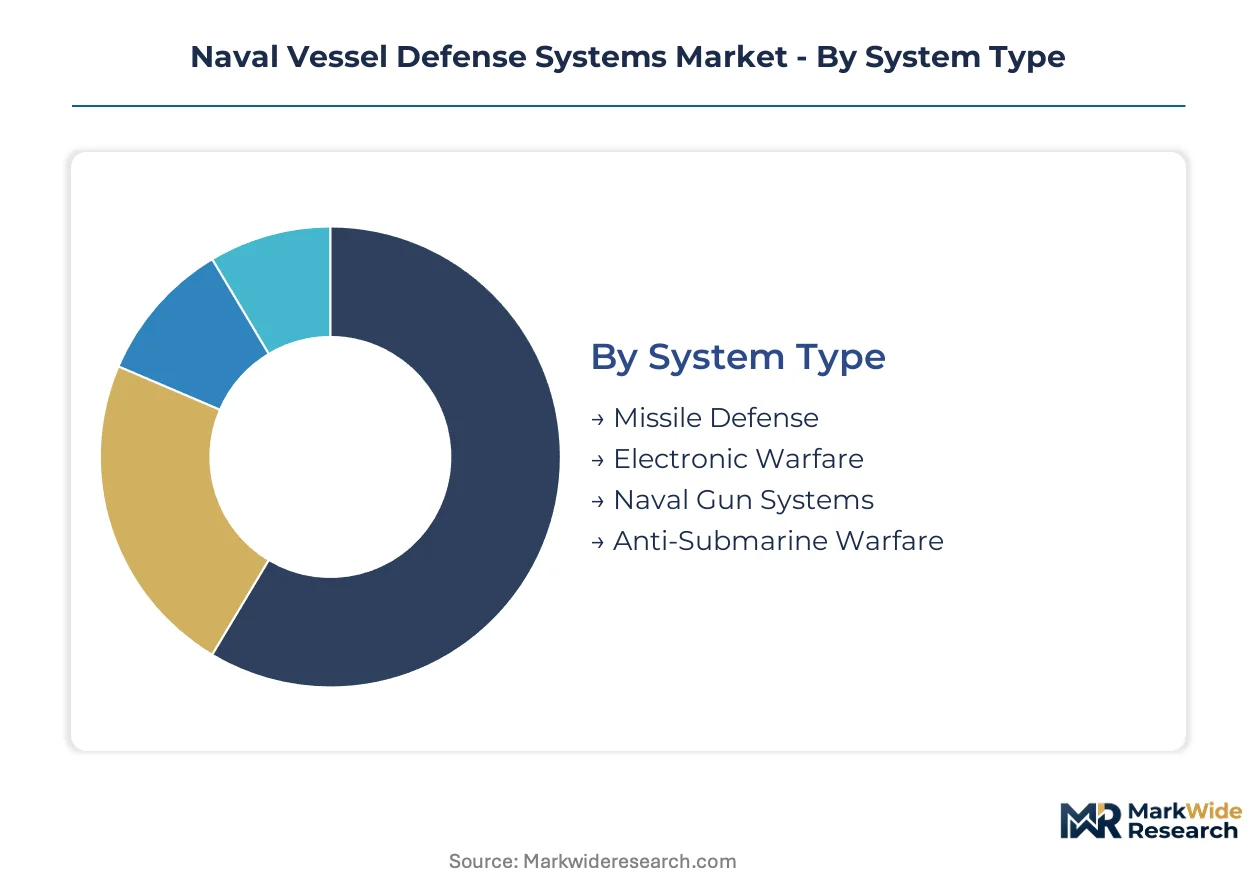
Defense procurement fragmentation across NATO-aligned navies and AUKUS partners creates distinct demand profiles by system maturity and platform integration complexity. Segmentation reveals where primes must modularize architectures versus where legacy upgrade cycles dominate contract flow.
System Type:
Missile defense and electronic warfare command premium contract values, while anti-submarine warfare climbs fastest on diesel-electric submarine proliferation.
- Missile Defense:Layered air and missile defense suites integrate phased-array radar with vertical launch systems for area defense against anti-ship ballistic threats. US Navy destroyer modernization and Japan's Maya-class procurement concentrate demand for Aegis-compatible architectures.
- Electronic Warfare:Radio-frequency countermeasure systems and signals intelligence suites provide soft-kill protection against radar-guided munitions. Royal Navy Type 26 frigate and US Navy Next Generation Jammer programs drive procurement of integrated electronic attack and support functions.
- Naval Gun Systems:5-inch and 76mm naval artillery with guided munitions capability address surface and littoral targets.
- Anti-Submarine Warfare:Towed array sonar, variable-depth sensors, and torpedo defense systems expand fastest on Indo-Pacific submarine fleet growth.
Today's leader: Missile Defense. Tomorrow's challenger: Anti-Submarine Warfare.
Technology:
Radar and sonar hardware anchors near-term procurement, while cybersecurity and AI-enabled command systems capture modernization budgets.
- Radar Systems:Active electronically scanned array technology with gallium nitride transmit-receive modules enables simultaneous air, surface, and ballistic missile tracking. Australia's Hunter-class frigate and US Navy Constellation-class programs specify AN/SPY-6 derivative architectures.
- Sonar Technology:Hull-mounted, towed, and dipping sonar arrays with synthetic aperture processing detect advanced air-independent propulsion submarines. Norway's Type 212CD and Netherlands' ASW frigate programs prioritize multi-static active sonar suites.
- Command and Control:Combat management systems integrate sensor fusion and cooperative engagement for distributed maritime operations.
- Cybersecurity Solutions:Platform hardening against cyber-physical attacks protects navigation, propulsion, and weapons systems from remote exploitation.
Hardware procurement dominates current spending. Software-defined architectures are gaining share fastest in modernization programs.
End User:
Naval service procurement outvolumes all other segments, though coast guard and contractor categories expand on constabulary and export market growth.
- Navies:Blue-water and littoral fleet modernization drives integrated combat system procurement across destroyer, frigate, and submarine platforms. US, UK, Australian, and Japanese naval budgets concentrate spending on multi-domain defense suites aligned with distributed maritime operations doctrine.
- Defense Contractors:Prime integrators and subsystem vendors procure reference architectures and qualification units for foreign military sales programs.
- Coast Guards:Offshore patrol vessel programs require scaled-down sensor and weapon packages for law enforcement and search-rescue missions.
- Commercial Operators:Privately owned vessels in high-threat regions procure defensive systems under government licensing frameworks.
Sovereign naval forces set technical specifications. Contractor and coast guard segments follow with derivative requirements.
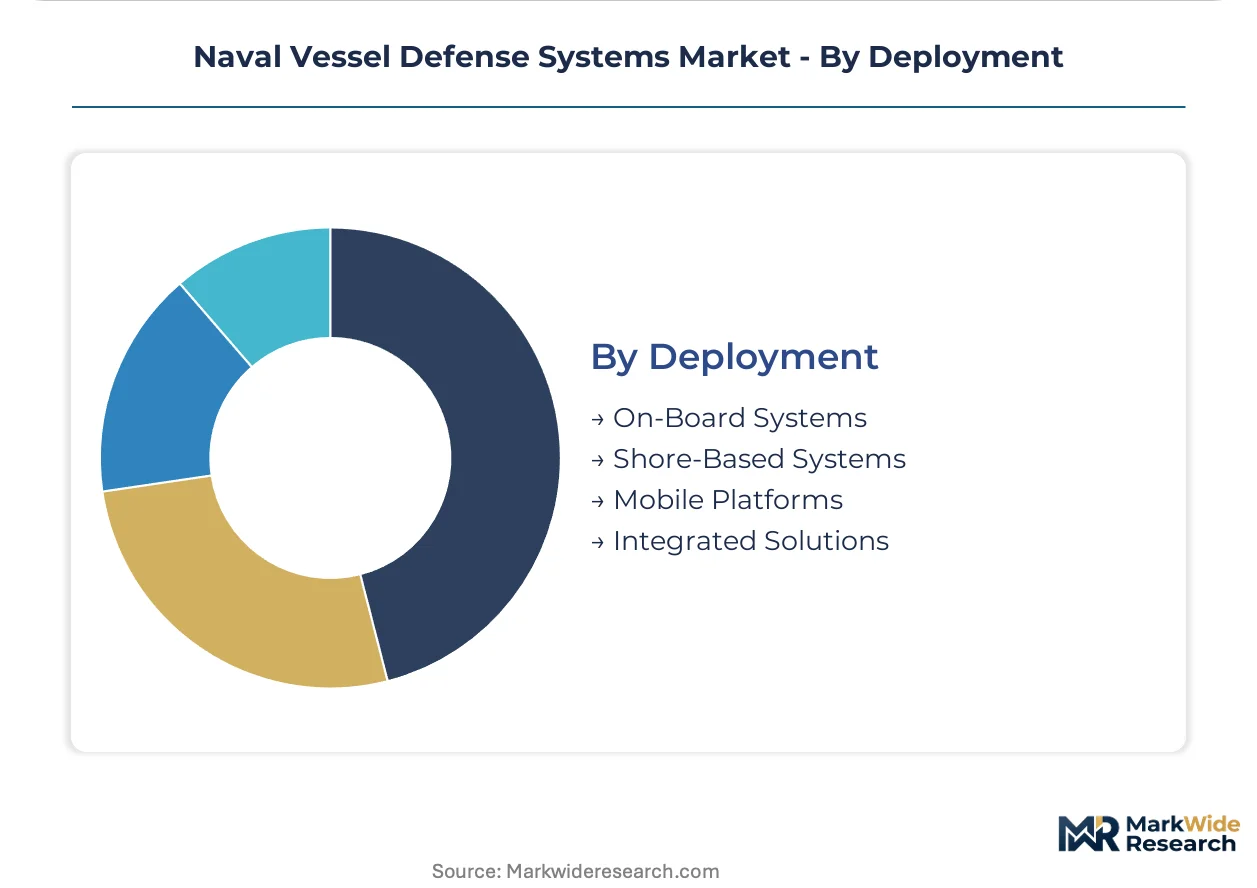
Deployment:
On-board integration captures platform construction budgets, while shore-based and mobile categories expand on network-centric warfare concepts.
- On-Board Systems:Permanently installed radar, sonar, electronic warfare, and weapon systems constitute the core of vessel defense architecture. Platform construction programs in Australia, Canada, and the UK specify integrated mast and combat system packages delivered as complete modules.
- Integrated Solutions:Networked sensor and shooter architectures link multiple platforms for cooperative engagement and distributed fire control. US Navy's Project Overmatch and NATO's Allied Command Transformation experiments validate multi-platform kill chains.
- Shore-Based Systems:Harbor defense sonar, coastal radar, and land-based electronic warfare extend protection to vessels in port and chokepoint transit.
- Mobile Platforms:Containerized and rapidly deployable defense systems provide expeditionary capability for contingency operations.
Fixed platform integration remains the revenue anchor. Networked distributed architectures are climbing fastest on operational concept evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement regulations diverge sharply across NATO-aligned jurisdictions, creating compliance-cost arbitrage that concentrates combat system integration in countries with established naval industrial bases and streamlined export-control frameworks.
United States
The US Navy's distributed maritime operations doctrine drives procurement of multi-domain sensor networks across destroyer and frigate programs. MIL-STD-464 electromagnetic survivability mandates enforce platform-wide hardening standards that shape system architecture choices. Huntington Ingalls Industries and General Dynamics Bath Iron Works anchor surface combatant production in Virginia and Maine, integrating Aegis-derived combat systems for domestic and foreign military sales.
United Kingdom
The Royal Navy's Type 26 frigate and Dreadnought submarine programs sustain demand for integrated sonar and electronic warfare suites. UK Defence and Security Industrial Strategy mandates sovereign capability thresholds for combat system components. BAE Systems' Glasgow shipyard and submarine manufacturing complex in Barrow-in-Furness concentrate production of naval defense architectures aligned with Five Eyes data-sharing protocols.
Australia
AUKUS submarine pathway commitments accelerate local production of nuclear-powered attack submarine combat systems under Defence Strategic Review sovereign industrial capability mandates. TGA and Defence export control frameworks govern technology transfer boundaries for integrated architectures. Osborne Naval Shipyard in South Australia and Henderson Maritime Precinct in Western Australia host Hunter-class frigate and AUKUS infrastructure development.
Japan
Japan Maritime Self-Defense Force Maya-class destroyer procurement concentrates demand for Aegis-compatible air and missile defense systems. METI and Ministry of Defense guidelines enforce local content requirements for critical combat system components. Mitsubishi Heavy Industries' Nagasaki and Yokohama facilities integrate domestic radar and fire control systems with US-supplied subsystem technologies.
Germany
German Navy F126 frigate and Type 212CD submarine programs drive procurement of multi-static active sonar and integrated mast systems. EU Permanent Structured Cooperation and national industrial policy favor domestic sourcing for combat management architectures. Thyssenkrupp Marine Systems' Kiel shipyard and Atlas Elektronik's Bremen operations anchor submarine and surface ship defense system integration.
Naval Vessel Defense Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue unmanned platform integration and software-defined architectures as pathways to contract participation. The market structures around a concentrated prime integrator base controlling combat system franchises, with tiered specialist suppliers filling subsystem niches. Three archetypes dominate: full-spectrum integrators leveraging combat system platforms, regional champions capturing sovereign procurement mandates, and technology specialists supplying sensor or effector components. Competitive dynamics center on multi-decade performance-based logistics contracting and cross-border joint ventures to navigate ITAR and export control fragmentation.
Among US-based defense conglomerates, Lockheed Martin Corporation, General Dynamics Corporation, and RTX Corporation exemplify full-spectrum integration archetypes. Lockheed Martin's Aegis combat system franchise anchors integrated air and missile defense positioning across multiple hull classes. General Dynamics represents the shipyard-integrated model where platform construction and combat system installation converge. RTX Corporation occupies the sensor and effector specialist tier with radar and electronic warfare subsystem penetration. European counterparts BAE Systems plc and Thales Group capture regional procurement through UK and French sovereign industrial bases, with BAE sustaining trans-Atlantic electronic warfare positions and Thales competing in sonar segments where domestic sourcing requirements apply.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| RTX Corporation |
| BAE Systems plc |
| Northrop Grumman Corporation |
| Thales Group |
| Israel Aerospace Industries |
| MBDA |
| Leonardo S.p.A |
| Others |
Supply & Pricing Matrix
Congressional funding mandates for distributed maritime operations are compressing platform procurement timelines and forcing primes to absorb qualification costs upfront, shifting contract structures toward multi-decade performance-based logistics with availability-linked payment terms that redistribute risk across the supply base.
Pricing Analysis
Input-cost pass-through from gallium nitride substrate shortages and ITAR compliance overhead is intensifying price pressure on active electronically scanned array radar modules. Three-tier pricing structure across Aegis-integrated, NATO-interoperable, and national-sovereignty combat system tiers reflects certification complexity and data-sharing protocol depth. Margins are tightening in sonar upgrade cycles where legacy analog architectures resist modular replacement without platform-level electrical system overhaul. Coast guard and export customers exhibit highest price sensitivity; US Navy and AUKUS partners prioritize performance assurance over unit cost.
Supply Chain Analysis
Regional distribution centers in Virginia, Glasgow, and Adelaide coordinate hub-and-spoke logistics for combat system modules bound for shipyard integration. Manufacturing concentrates in the United States, United Kingdom, and Australia under Five Eyes data-sharing protocols that restrict subsystem sourcing geography. High-purity gallium nitride substrates, specialized sonar transducer ceramics, and MIL-STD-461 qualified cable assemblies draw from single-source domestic foundries. Single-source vulnerability in transmit-receive module supply chains creates qualification bottleneck risk. Distribution runs through prime integrator-managed vendor consignment at naval shipyards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Naval vessel defense systems function as a stable compounder anchored by sovereign procurement cycles that refresh combat system architectures across multi-decade platform lifespans regardless of near-term budget volatility.
For Market Incumbents: Cement Aegis combat system franchise positioning through backward integration into gallium nitride foundry capacity and exclusive performance-based logistics contracts with Australian and Canadian navies. ITAR fragmentation threatens cross-border subsystem integration; prioritize in-house production of fire control software to preserve margin against emerging software-defined architecture vendors.
For New Entrants and Emerging Players: EU Permanent Structured Cooperation in Europe opens a window for non-domestic combat system suppliers to access pooled procurement mechanisms for frigate programs. Unmanned surface vessel integration and shore-based expeditionary systems represent the most penetrable white-space segments. Pursue cooperative engagement capability certification as go-to-market entry point.
For Investors and Strategic Acquirers: Asymmetric upside sits with sonar signal processing specialists possessing synthetic aperture algorithm portfolios and synthetic training data pipelines. Long-term viability hinges on multi-decade sovereign sustainment contracts rather than platform construction cyclicality. Watch for AUKUS submarine pathway production rate announcements as inflection indicator for integrated combat system demand scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Combat System Modularization | Enables frigate and unmanned vessel integration under distributed maritime operations doctrine. |
| Gallium Nitride Foundry Investment | Secures transmit-receive module supply for AN/SPY-6 derivative radar architectures. |
| Performance-Based Logistics Contracting | Locks in multi-decade revenue streams with Australian and Canadian naval modernization programs. |
| Synthetic Aperture Sonar Development | Addresses diesel-electric submarine proliferation in contested Indo-Pacific littorals. |
| Laser Weapon System Integration | Converges directed energy with existing fire control for close-in defense against unmanned aerial swarms. |
Research Methodology
Multiple input streams — program executive interviews, shipyard procurement director discussions, naval systems engineering lead consultations, and congressional budget justification document analysis — were reconciled against defense contract award databases and foreign military sales notification records. Primary engagement with combat system integrators, subsystem vendors, and naval research laboratory technology transition officers combined with secondary validation through US Navy NAVAIR technical directives, UK Defence and Security Industrial Strategy publications, and Australian Defence Strategic Review implementation updates. Bottom-up platform procurement forecasts and top-down defense budget allocation triangulation anchored market sizing.
Cross-referencing historical program execution patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include system type, technology layer, end-user category, and deployment architecture, with additional weighting for sovereign industrial capability thresholds and ITAR-controlled data protocol applicability. CAGRs were derived from program-of-record funding profiles and platform delivery schedules. Forecast inputs incorporated AUKUS submarine pathway production ramp assumptions and EU Permanent Structured Cooperation project pipeline maturation.
Revisions become necessary when congressional appropriation delays, gallium nitride foundry capacity constraints, or Five Eyes data-sharing protocol renegotiations materialize differently than assumed. Forecasts reflect documented program-of-record commitments and stated sovereign procurement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Military Frigate Market
Naval Warfare
Sea-Based Remote Weapon Systems Market
Naval Warfare
Naval Radar Market
Naval Warfare
Anti-Submarine Warfare Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Naval Vessels and Surface Combatants Market
Naval Warfare
Naval Combat Systems Market
Naval Warfare
Africa Undersea Warfare Systems Market
Naval Warfare
Naval Combat Weapons Market
Naval Warfare
Sea Based C4ISR Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Anti-Ship Missile Defense System Market
Naval Warfare
Marine Radar Market
Naval Warfare
Asia-Pacific Naval Vessels Market
Naval Warfare
Global Naval Vessel MRO Market
Naval Warfare
Coastal Patrol Military Vessels Market