
 Lime Manufacturing Market | 2026-2036
Lime Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Lime Manufacturing Market Foresight
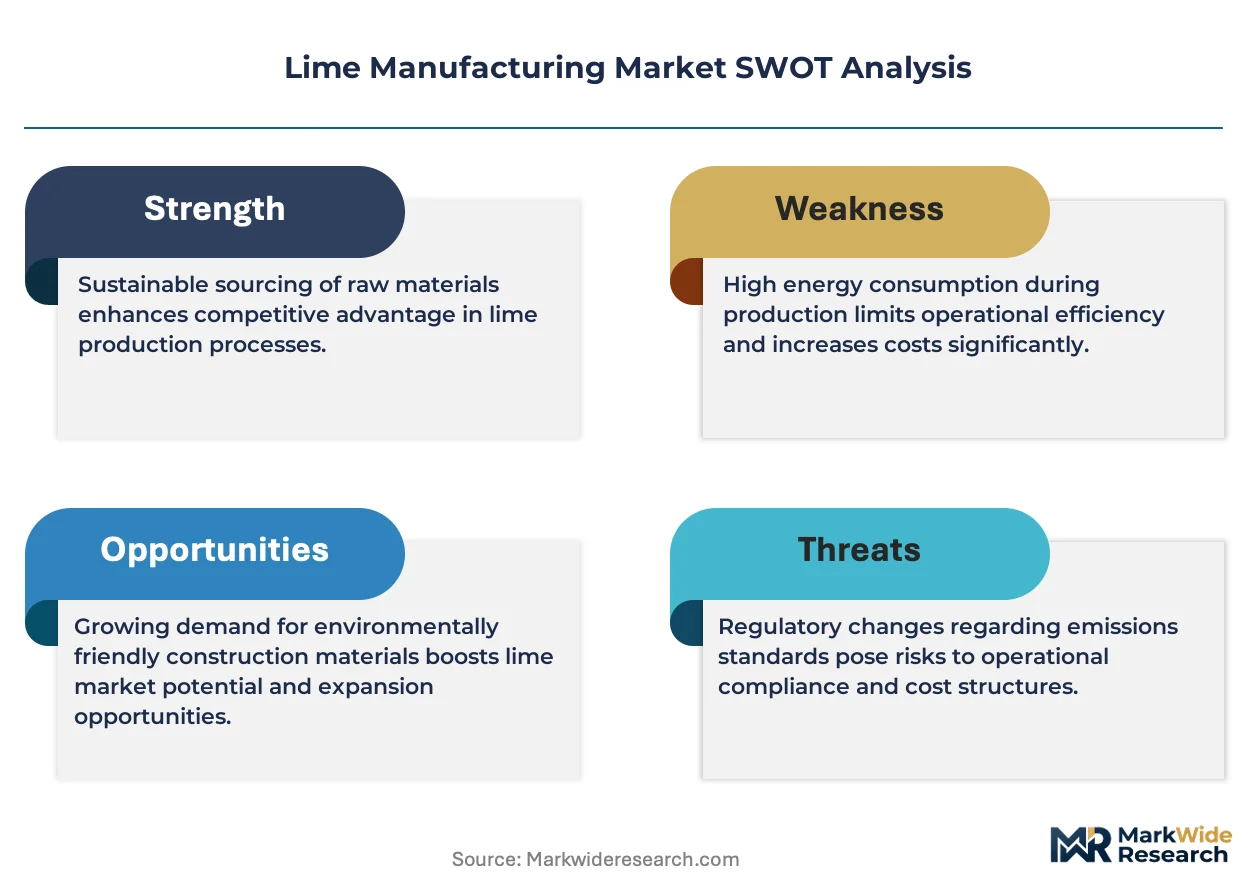
Environmental compliance buyers are gaining share as steelmakers and water utilities is reorganizing procurement priorities around sulfur capture and effluent neutralization. Carmeuse dominates North American quicklime supply through extensive limestone quarry networks and captive kiln capacity. Lhoist Group differentiates via specialized dolomitic lime formulations for European steel desulfurization. Mississippi Lime Company anchors Midwest hydrated lime distribution through direct rail-to-plant logistics.
Lime manufacturing produces calcium oxide (CaO) and calcium hydroxide (Ca(OH)₂) through calcination of limestone at temperatures exceeding 900°C, yielding products with 90-95% purity for industrial alkalinity control. Quicklime commands the largest volume share in steel slag conditioning and construction soil stabilization, while hydrated lime is expanding fastest in water treatment flocculation due to safer handling profiles. Bulk packaging occupies the dominant share in cement industry procurement, though bagged formats are growing in agricultural pH correction for smaller farm operations.
The EPA enforces Maximum Achievable Control Technology standards that mandate lime-based scrubbing for coal-fired utilities and industrial boilers, directly expanding hydrated lime demand. OSHA and MSHA regulate crystalline silica exposure in lime crushing and slaking operations, shaping workplace safety investments and product handling protocols. Stakeholders must monitor evolving state-level carbon capture mandates that could redirect quicklime volumes toward direct air capture sorbent applications.
Market Dynamics
EPA effluent limitation guidelines are forcing municipal water utilities and coal-fired power generators to expand lime-based scrubbing capacity, redirecting procurement volumes toward hydrated lime suppliers with certified emission control formulations.
Growth Catalysts
- Maximum Achievable Control Technology (MACT) standards:Coal-fired utilities must install lime-based flue gas desulfurization systems, creating sustained demand for high-purity hydrated lime in sulfur capture applications.
- Steel slag conditioning:Electric arc furnace operators are expanding quicklime consumption to neutralize acidic slag and improve metal recovery rates in secondary steelmaking.
- Soil stabilization for infrastructure:Highway agencies in the United States are specifying quicklime-treated subgrade for road construction projects requiring rapid strength gain and moisture reduction.
Market Restraints
- Natural gas price volatility:Calcination kilns consume substantial natural gas, and input cost spikes compress margins for producers without long-term fuel hedging contracts.
- Quarry reserve depletion:High-calcium limestone deposits are concentrating in fewer geographies, raising transportation costs for plants distant from quality feedstock sources.
- Precipitated calcium carbonate substitution:Paper manufacturers are shifting toward PCC for filler applications, displacing some hydrated lime volumes in pulp processing.
Strategic Opportunities
- Direct air capture sorbents:Emerging carbon removal projects are testing quicklime-derived calcium oxide for atmospheric CO₂ capture, opening a novel demand vertical.
- Bagged agricultural lime:Smaller farming operations are driving demand for packaged hydrated lime formats, creating channel expansion potential beyond bulk industrial supply.
- EU Green Deal carbon border adjustments:European lime producers with lower-carbon kiln technologies can capture premium positioning as import tariffs penalize emission-intensive competitors.
Industry Challenges
- Kiln operator skill shortages:Experienced calcination technicians are retiring faster than training programs can replace them, threatening operational consistency at aging plants.
- OSHA crystalline silica compliance:Crushing and slaking operations face intensified exposure monitoring requirements, demanding capital investment in dust suppression and ventilation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lime Manufacturing Market |
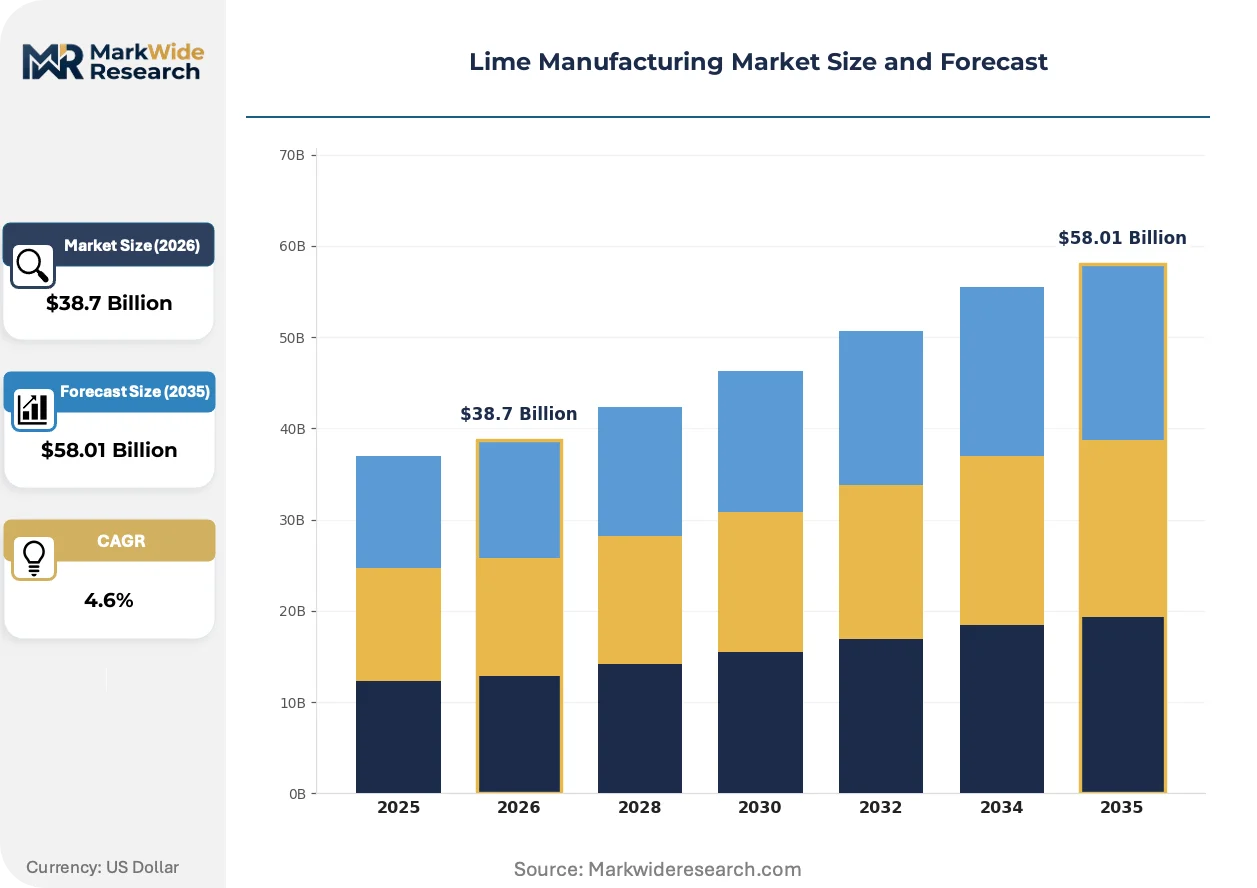
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quicklime, Hydrated Lime, Dolomitic Lime, Others Application: Construction, Steel Manufacturing, Water Treatment, Agriculture End User: Cement Industry, Chemical Production, Environmental Services, Glass Manufacturing Packaging Type: Bags, Bulk, Drums, Containers |
| Companies Covered | Carmeuse, Lhoist Group, Graymont Limited, United States Lime & Minerals, Mississippi Lime Company, Cheney Lime & Cement Company, Linwood Mining & Minerals, Pete Lien & Sons, Minerals Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lime Manufacturing Market Shifts & Advancements
Calcination technology advances and emission control mandates are reshaping how lime producers configure kiln operations and serve end-use specifications. Digital process control and alternative fuel integration are emerging as competitive differentiators.
Maerz parallel-flow regenerative kiln technology is decomposing limestone at lower specific fuel consumption rates than traditional long rotary kilns. European producers are retrofitting plants with PFR systems to meet EU ETS carbon cost thresholds. This efficiency gain is compressing the cost gap between established and marginal producers in carbon-regulated markets.
EPA's updated effluent limitation guidelines for steam electric power generators mandate zero liquid discharge for certain waste streams. Coal plant operators are expanding hydrated lime precipitation systems to meet selenium and nitrate removal requirements. The industrial boiler segment is responding by locking in multi-year supply contracts with qualified lime suppliers.
Water treatment utilities are consolidating procurement through regional cooperative purchasing agreements. Municipal buyers are bypassing distributor intermediaries to negotiate direct rail-delivered volumes with captive quarry producers. This concentration is most visible across the Great Lakes states, where combined sewer overflow remediation projects are aggregating demand from multiple agencies.
Lime Manufacturing Market Segmentation
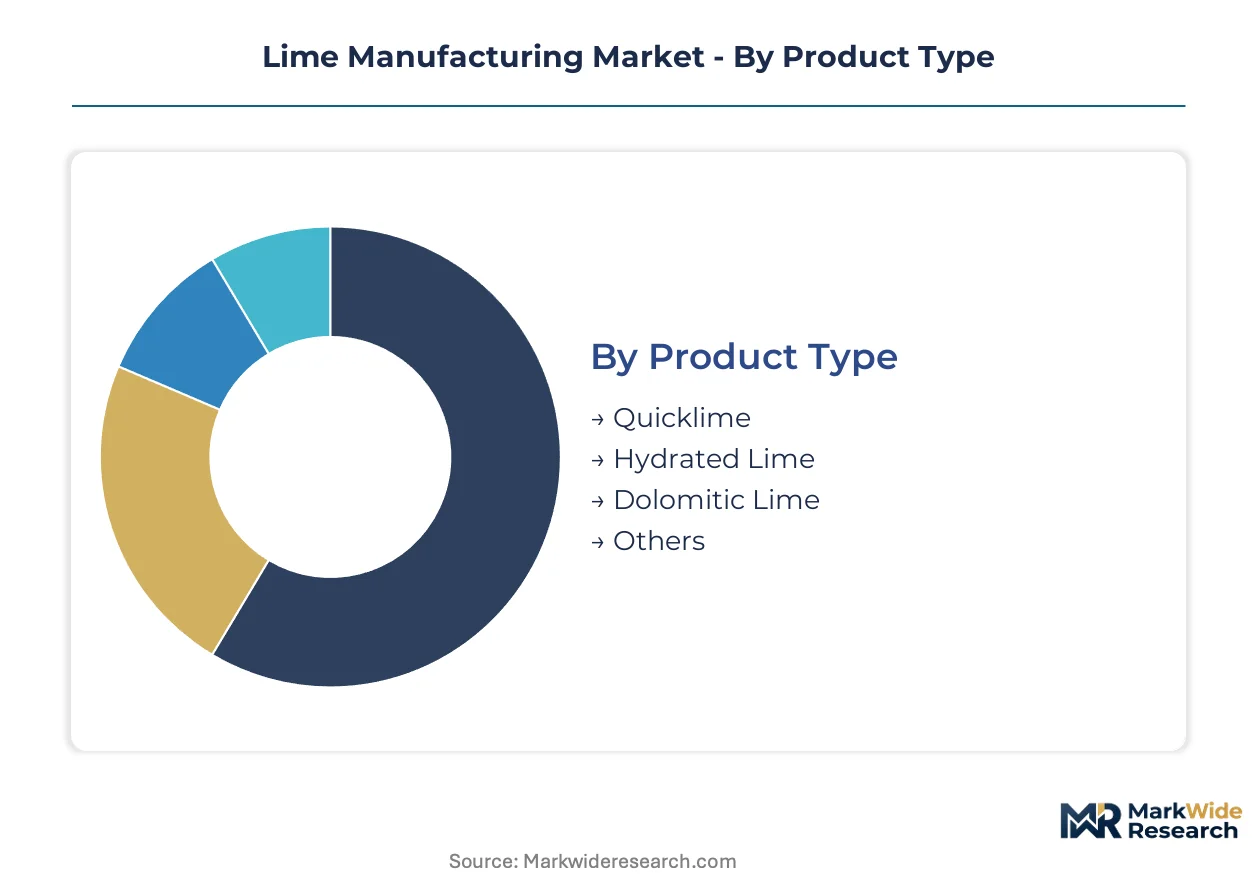
Product differentiation in lime manufacturing determines kiln configuration, logistics economics, and customer switching costs. Segmentation reveals where producers capture value through purity grades, reactivity specifications, and delivery formats tailored to end-use requirements.
Product Type:
Hydrated lime commands the widest margin expansion as environmental compliance buyers prioritize handling safety and reactivity control.
- Quicklime:Calcium oxide produced at calcination temperatures exceeding 900°C yields 90-95% purity grades essential for steel slag conditioning. Electric arc furnace operators in the United States are expanding offtake to neutralize acidic slag and improve metal recovery rates in secondary steelmaking.
- Hydrated Lime:Calcium hydroxide formed through controlled slaking of quicklime delivers safer handling profiles for water treatment flocculation. Municipal utilities across the Great Lakes states are consolidating procurement through regional cooperative purchasing agreements for direct rail-delivered volumes.
- Dolomitic Lime:Magnesium-calcium oxide blends from dolomite limestone calcination serve specialized steel desulfurization formulations in European markets.
- Others:Hydraulic lime and specialty refractory grades address niche construction and industrial applications with limited volume scale.
Quicklime holds installed capacity. Hydrated lime is rotating up the share rankings.
Application:
Steel manufacturing anchors volume throughput while water treatment is climbing fastest on regulatory tailwinds.
- Steel Manufacturing:Slag conditioning and fluxing applications consume high-calcium quicklime for sulfur and phosphorus removal. EPA Maximum Achievable Control Technology standards mandate lime-based scrubbing for emission control, sustaining demand for metallurgical-grade formulations.
- Water Treatment:pH neutralization and heavy metals precipitation in municipal and industrial effluent systems. Coal-fired utilities facing updated effluent limitation guidelines are expanding hydrated lime precipitation capacity for selenium and nitrate removal.
- Construction:Soil stabilization and masonry mortar applications specify quicklime-treated subgrade for highway projects requiring rapid strength gain.
- Agriculture:pH correction for acidic soils drives demand for bagged hydrated lime formats among smaller farming operations.
Steel manufacturing holds installed capacity. Water treatment is rotating up the share rankings.
End User:
Cement industry procurement concentrates in bulk formats while environmental services is expanding most quickly on compliance spending.
- Environmental Services:Flue gas desulfurization and wastewater treatment operations specify certified emission control formulations. Coal plant operators are locking in multi-year supply contracts with qualified lime suppliers to meet zero liquid discharge mandates.
- Cement Industry:Clinker production and soil stabilization applications consume bulk quicklime through direct quarry-to-plant logistics arrangements.
- Chemical Production:Alkali manufacturing and calcium compound synthesis require consistent reactivity specifications for process integration.
- Glass Manufacturing:Flux and stabilizer applications in soda-lime glass production utilize controlled-purity grades.
Cement industry holds installed capacity. Environmental services is rotating up the share rankings.
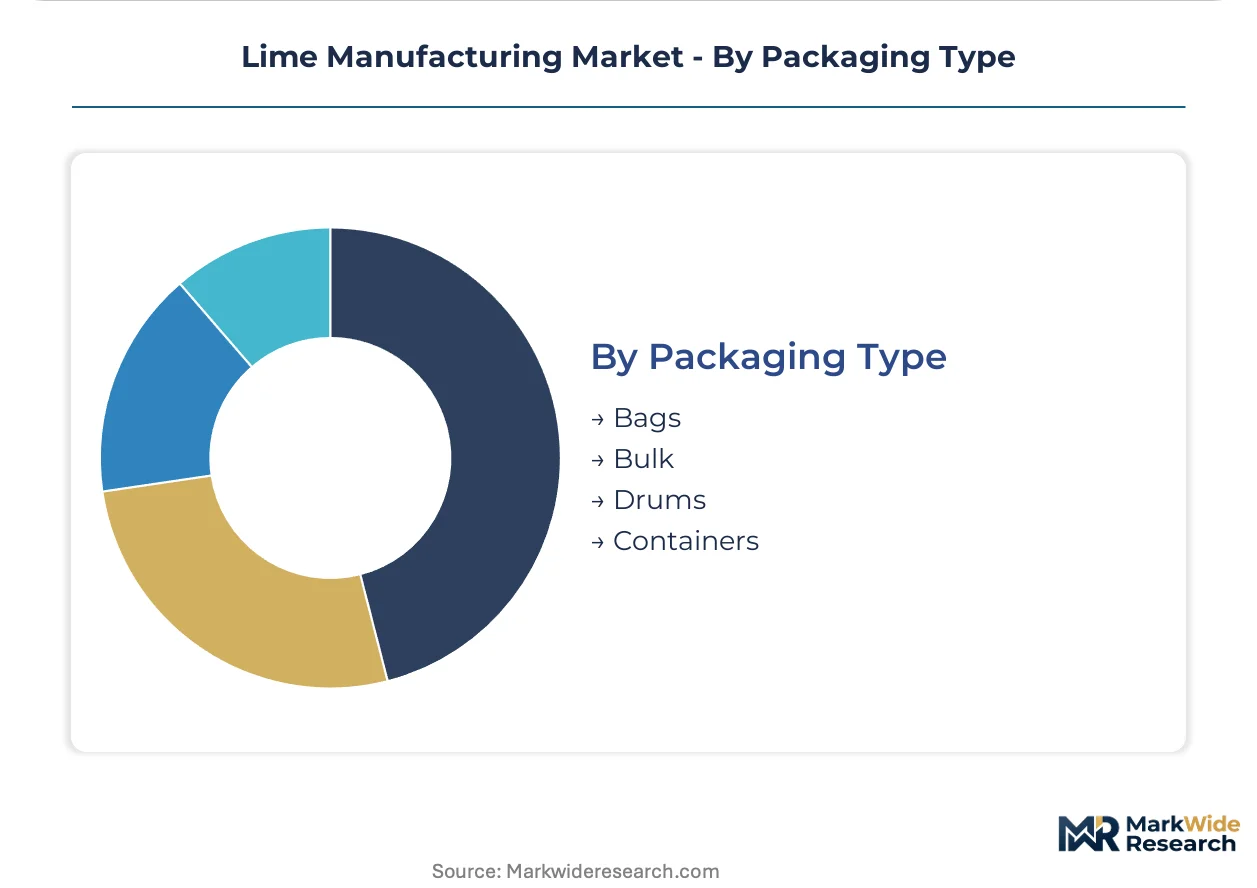
Packaging Type:
Bulk delivery dominates industrial procurement economics while bagged formats are penetrating agricultural and small-scale construction segments.
- Bulk:Rail and pneumatic truck delivery to captive industrial consumers minimizes handling costs and ensures continuous kiln offtake. Highway agencies and cement producers specify bulk quicklime for large-volume soil stabilization and clinker operations.
- Bags:Multi-wall paper and polypropylene packaging serves agricultural pH correction and small contractor markets. Smaller farming operations are driving channel expansion beyond bulk industrial supply.
- Drums:Steel and fiber containers address specialty chemical and laboratory applications with strict contamination controls.
- Containers:Intermediate bulk containers and totes facilitate mid-scale water treatment and construction site delivery.
Bulk holds installed capacity. Bags is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steelmakers and water utilities in the United States concentrate procurement volumes for environmental compliance applications. European electric arc furnace operators and coal plant scrubbing retrofits drive parallel demand patterns. Asian construction and chemical sectors sustain bulk quicklime offtake for infrastructure and process alkalinity.
United States
EPA Maximum Achievable Control Technology standards mandate lime-based flue gas desulfurization for coal-fired utilities. The Great Lakes states host municipal water treatment cooperatives consolidating direct rail procurement from captive quarry producers. Pittsburgh and Cleveland steel corridors expand quicklime consumption for electric arc furnace slag conditioning.
Germany
EU ETS carbon cost thresholds accelerate Maerz parallel-flow regenerative kiln retrofits among calcination operators. The country's national environmental regulator enforces stricter industrial emission benchmarks for sulfur capture systems. Ruhr industrial basin steelmakers source specialized dolomitic lime formulations for secondary metallurgy desulfurization.
China
Dual carbon goals and industrial emission reduction targets redirect quicklime volumes toward flue gas treatment retrofits. The Ministry of Ecology and Environment enforces stricter effluent standards for coal power and chemical manufacturing. Shandong Peninsula limestone quarries supply construction soil stabilization projects along high-speed rail corridors.
India
Central Pollution Control Board mandates expand lime-based scrubbing capacity for coal-fired thermal power stations. Bureau of Indian Standards certification requirements shape hydrated lime specifications for municipal water treatment procurement. Gujarat and Maharashtra industrial clusters anchor steel and chemical sector quicklime demand.
Brazil
Agricultural pH correction drives bagged hydrated lime consumption among smaller farming operations in soybean and corn belts. The national agricultural regulator oversees fertilizer and soil amendment quality standards for lime product registration. São Paulo state construction sector specifies quicklime-treated subgrade for highway infrastructure projects.
Lime Manufacturing Market Competitive Landscape
Player mix skews toward integrated quarry-to-kiln operators with captive limestone reserves and direct rail distribution networks. Three to five producers control majority installed capacity across North American and European markets. Strategic archetypes include: vertically integrated quarry-kiln operators, regional hydrated lime specialists with direct utility relationships, and diversified construction materials conglomerates with lime divisions. Competitive moves concentrate on kiln technology retrofits for carbon efficiency and multi-year supply contract lock-ins with environmental compliance buyers.
Among North American integrated producers, Carmeuse, Graymont Limited, and Mississippi Lime Company occupy positions exemplifying the quarry-captive archetype. Carmeuse represents extensive limestone reserve networks with direct rail-to-plant logistics. Graymont Limited sits within the multi-regional coverage tier serving steel and construction sectors. Mississippi Lime Company anchors Midwest hydrated lime distribution through utility-direct procurement relationships. Lhoist Group and United States Lime & Minerals exemplify specialized and regional-scale positioning respectively. Cheney Lime & Cement Company, Linwood Mining & Minerals, and Pete Lien & Sons represent mid-tier family-operated structures with localized market focus. Minerals Technologies occupies a position bridging specialty chemical and lime manufacturing competencies.
| Leading Market Players |
|---|
| Carmeuse |
| Lhoist Group |
| Graymont Limited |
| United States Lime & Minerals |
| Mississippi Lime Company |
| Cheney Lime & Cement Company |
| Linwood Mining & Minerals |
| Pete Lien & Sons |
| Minerals Technologies |
| Others |
Supply & Pricing Matrix
EPA Maximum Achievable Control Technology certification gates both supplier qualification and price differentiation in lime procurement, forcing coal-fired utilities and steelmakers to pay premiums for emission-control-grade formulations while marginal producers face exclusion from multi-year contract pools.
Pricing Analysis
Maerz parallel-flow regenerative kiln technology commands price premiums over traditional long rotary kiln output, while conventional calcination equipment faces margin compression from carbon cost exposure in regulated markets. Contract-based long-term offtake dominates industrial procurement, with price differentiation resting on reactivity certification and direct rail delivery capability. Cost compression in standard-grade quicklime is intensifying because natural gas price volatility erodes unhedged producer margins. Environmental services buyers show lowest price sensitivity due to compliance mandates, while agricultural distributors exhibit highest sensitivity to bagged product pricing.
Supply Chain Analysis
The United States anchors high-calcium quicklime production through captive quarry networks in the Great Lakes and Appalachian regions, while Germany and China supply specialized dolomitic formulations and mass-market construction grades respectively. Limestone feedstock, natural gas fuel, and rail logistics constitute the three critical input dependencies. Single-source vulnerability concentrates in high-purity limestone reserves, where transportation costs escalate for plants distant from quality deposits. Distribution runs through direct rail-to-plant arrangements for bulk industrial consumers, with regional distributors handling bagged agricultural and small contractor volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for kiln optimization and slaking system maintenance are expanding faster than base chemical sales, creating recurring revenue layers that attach to initial equipment and supply agreements.
For Market Incumbents: Compound defensive positioning through backward integration into captive limestone reserves and Maerz kiln retrofits that lock in carbon-efficient cost structures against EU ETS exposure. Prioritize multi-year supply contract lock-ins with coal-fired utilities facing zero liquid discharge mandates to secure volume commitments before precipitated calcium carbonate substitution accelerates in pulp processing. For New Entrants and Emerging Players: Differentiate on bagged agricultural lime distribution to smaller farming operations in Brazil and the United States Midwest, where channel fragmentation creates white-space opportunities beyond bulk industrial supply. Target regional water treatment cooperatives consolidating procurement through direct rail agreements, leveraging flexible slaking capacity to serve municipal selenium and nitrate removal projects without quarry-captive infrastructure. For Investors and Strategic Acquirers: EPA effluent limitation guideline enforcement reshapes the acquisition landscape toward integrated quarry-kiln operators with certified emission control formulations and established utility relationships. Five-to-ten-year viability favors producers with limestone reserve life exceeding twenty years and PFR kiln technology already deployed. Watch for state-level carbon capture mandate adoption as the signal indicating quicklime sorbent demand inflection for direct air capture applications.| Strategic Initiative | Industry Significance |
|---|---|
| Maerz Kiln Retrofit Program | Reduces specific fuel consumption below EU ETS carbon cost thresholds for European calcination operators. |
| Direct Rail Logistics Expansion | Bypasses distributor intermediaries for municipal water treatment cooperatives consolidating procurement volumes. |
| Bagged Agricultural Channel Buildout | Captures smaller farming operations in soybean and corn belts beyond bulk industrial supply economics. |
| Hydrated Lime Certification Investment | Qualifies suppliers for coal plant zero liquid discharge mandates and multi-year scrubbing contracts. |
| Limestone Reserve Acquisition | Secures high-calcium feedstock proximity as quarry depletion concentrates quality deposits geographically. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with calcination plant managers, utility procurement leads, and water treatment agency engineers; and secondary validation through EPA effluent guideline filings, EIA industrial fuel consumption data, and SEC 10-K disclosures from integrated producers. Bottom-up volume estimates from kiln capacity utilization and top-down demand segmentation from end-use industry consumption patterns underwent cross-triangulation to reconcile discrepancies.
Across the projection horizon, the analytical framework modeled lime manufacturing through grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived from segment-level demand elasticity analysis against regulatory compliance spending trajectories. Forecast inputs incorporated natural gas price scenarios, limestone reserve depletion curves, and MACT standard implementation timelines without binding to specific calendar years.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement of effluent limitation guidelines or accelerated precipitated calcium carbonate substitution in paper manufacturing would require recalibration. Recalibration cycles align with material shifts in carbon border adjustment implementation, kiln technology adoption rates, and municipal procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Pelletized Activated Carbon Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Non-PVC Waterstop Market
Industrial Chemicals
Blown Oils Market
Industrial Chemicals
Global Specialty Oils Market
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Europe Molecular Sieve Market
Industrial Chemicals
2-Ethoxy Propene Market
Industrial Chemicals
Metal Treatment Chemical Market