
 Essential Oil Isolates Market | 2026-2036
Essential Oil Isolates Market Size, Share, and Industry Trends Forecast 2026-2036
Essential Oil Isolates Market Foresight
The essential oil isolates category is pivoting on a widening gap between pharmaceutical-grade monoterpenes and commodity aromatic compounds. Young Living Essential Oils leverages captive distillation networks across multiple continents to secure raw material streams. NOW Foods anchors its position through bulk supply contracts with North American supplement manufacturers. Flavex Naturextrakte GmbH differentiates via supercritical CO2 extraction capabilities that yield higher-purity isolates for regulated applications.
Essential oil isolates are single-molecule fractions distilled or extracted from botanical essential oils, typically achieving purity thresholds above 90 percent through fractional distillation, molecular distillation, or chromatographic separation; these compounds serve as standardized inputs where batch-to-batch consistency determines product performance in downstream formulations. Monoterpenes and sesquiterpenes dominate volume flows due to their established roles in fragrance compounding and topical therapeutics, while aromatic compounds command margin premiums in pharmaceutical applications where USP-grade certification applies. The food and beverage application segment shows structural expansion as clean-label flavoring regulations tighten across import jurisdictions.
REACH registration requirements in Europe, FDA food additive specifications under CFR Title 21, and FSSAI labeling mandates in India collectively elevate compliance costs for isolate suppliers seeking multi-regional market access. ISO 17025 laboratory accreditation has become a de facto threshold for contract negotiations with multinational personal care brands. Stakeholders must monitor evolving pharmacopeial monographs and extraction solvent restrictions to anticipate which isolate categories face supply constraints or qualification barriers.
Market Dynamics
Fractional distillation capacity concentration in Karnataka and Kerala processing clusters is creating supply bottlenecks for pharmaceutical-grade monoterpenes, while REACH purity mandates force smaller European extractors to exit or consolidate.
Growth Catalysts
- Pharmaceutical-grade demand:Formulators of topical therapeutics and transdermal delivery systems now specify isolates above 95% purity, creating dedicated supply contracts that bypass commodity aromatic channels.
- REACH registration tiering:ECHA's substance volume bands incentivize tonnage-scale producers to invest in full dossier preparation, locking out sub-threshold competitors and consolidating compliant supply.
- Supercritical CO2 extraction:This solvent-free technology yields isolates meeting USP-grade certification without residual hexane concerns, opening pharmaceutical formulator procurement to botanical-derived inputs previously excluded.
Market Restraints
- Feedstock volatility:Climate stress on Mentha arvensis and Citrus reticulata plantations in India and Brazil generates 18-24 month price cycles that isolate processors cannot pass through to fixed-contract fragrance houses.
- Chromatographic purification capex:Preparative HPLC and simulated moving bed systems required for 98%+ purity isolates demand seven-figure equipment investments that sub-scale distillers cannot finance.
- Synthetic terpene substitution:Petrochemical-derived limonene and pinene from crackers in Texas and Rotterdam undercut botanical isolates on price in non-pharmaceutical applications, capping volume expansion.
Strategic Opportunities
- Clean-label flavoring mandates:FSSAI's tightening natural flavoring definitions in India create first-mover advantage for isolate suppliers achieving 99% single-molecule certification for beverage applications.
- Biotechnology convergence:Microbial fermentation of terpene backbones combined with botanical finishing is electrifying new production pathways that bypass agricultural yield constraints entirely.
- Direct-to-compounder distribution:E-commerce platforms serving mid-tier cosmetic formulators in South Korea and Australia disintermediate traditional distributor markups for sub-tonnage orders.
Industry Challenges
- Analytical chemist scarcity:ISO 17025 accreditation requires gas chromatography-mass spectrometry specialists capable of validating chiral purity and enantiomeric ratios, a skill set concentrated in Basel and Mumbai contract labs.
- Pharmacopeial lag:USP and EP monograph updates for novel isolates lag commercial availability by 3-5 years, forcing suppliers to fund proprietary reference standard development for customer qualification.
- Batch-to-batch variance:Seasonal variation in essential oil feedstock composition complicates isolate yield prediction, requiring buffer inventory strategies that compress working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Essential Oil Isolates Market |
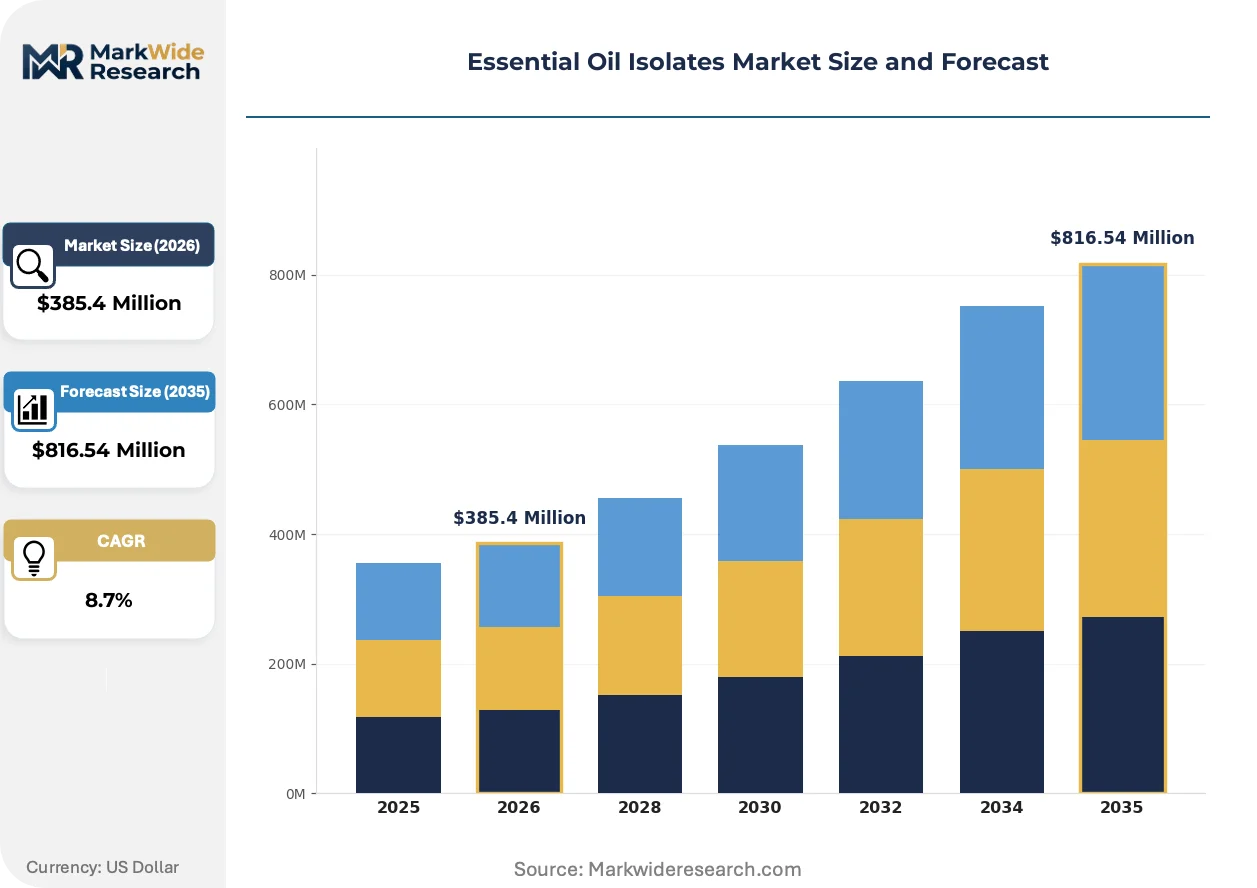
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoterpenes, Sesquiterpenes, Aromatic Compounds, Alcohols Application: Cosmetics, Pharmaceuticals, Food & Beverages, Aromatherapy End User: Personal Care, Healthcare, Food Industry, Retail Distribution Channel: Online, Offline, Direct Sales, Retail Outlets |
| Companies Covered | Young Living Essential Oils, DoTerra, NOW Foods, Flavex Naturextrakte GmbH, Advanced Biotech, The Lebermuth Company, Plant Therapy, Cedarome, India Essential Oils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Essential Oil Isolates Market Shifts & Advancements
Molecular distillation and preparative chromatography are converging with digital process control to transform isolate production from batch craft to continuous manufacturing, compressing qualification timelines for regulated end-uses.
Simulated moving bed chromatography is electrifying the economics of high-purity isolate production by enabling continuous separation of enantiomers at industrial scale. Pharmaceutical formulators in Basel and Research Triangle Park now specify SMB-derived isolates for chiral API synthesis, displacing traditional fractional crystallization that required multiple solvent-intensive steps. This technology compression is enabling Indian processors to compete for European pharmaceutical contracts previously reserved for European specialists.
REACH Annex XVII restrictions on extraction solvents are tightening residual limits for hexane and dichloromethane in isolates destined for cosmetic applications. ECHA's 2023 update to entry 28 now triggers mandatory testing for sub-ppm detection thresholds, forcing processors to validate alternative extraction pathways or absorb third-party analytical costs. Fragrance compounders in Grasse and Geneva are responding by dual-sourcing from CO2 and ethanol extraction facilities to maintain formulation flexibility.
Formulator procurement teams now mandate certificate-of-analysis transparency with full chromatographic traceability rather than accepting supplier-generated summary data. Mid-tier cosmetic brands in Seoul and São Paulo are displacing traditional distributor relationships with direct technical partnerships that include quarterly audit rights and shared reference standard libraries. This verification-driven preference shift is most visible in South Korea, where MFDS cosmetic safety filings now require isolate-level ingredient disclosure that batch-level essential oil sourcing cannot satisfy.
Essential Oil Isolates Market Segmentation
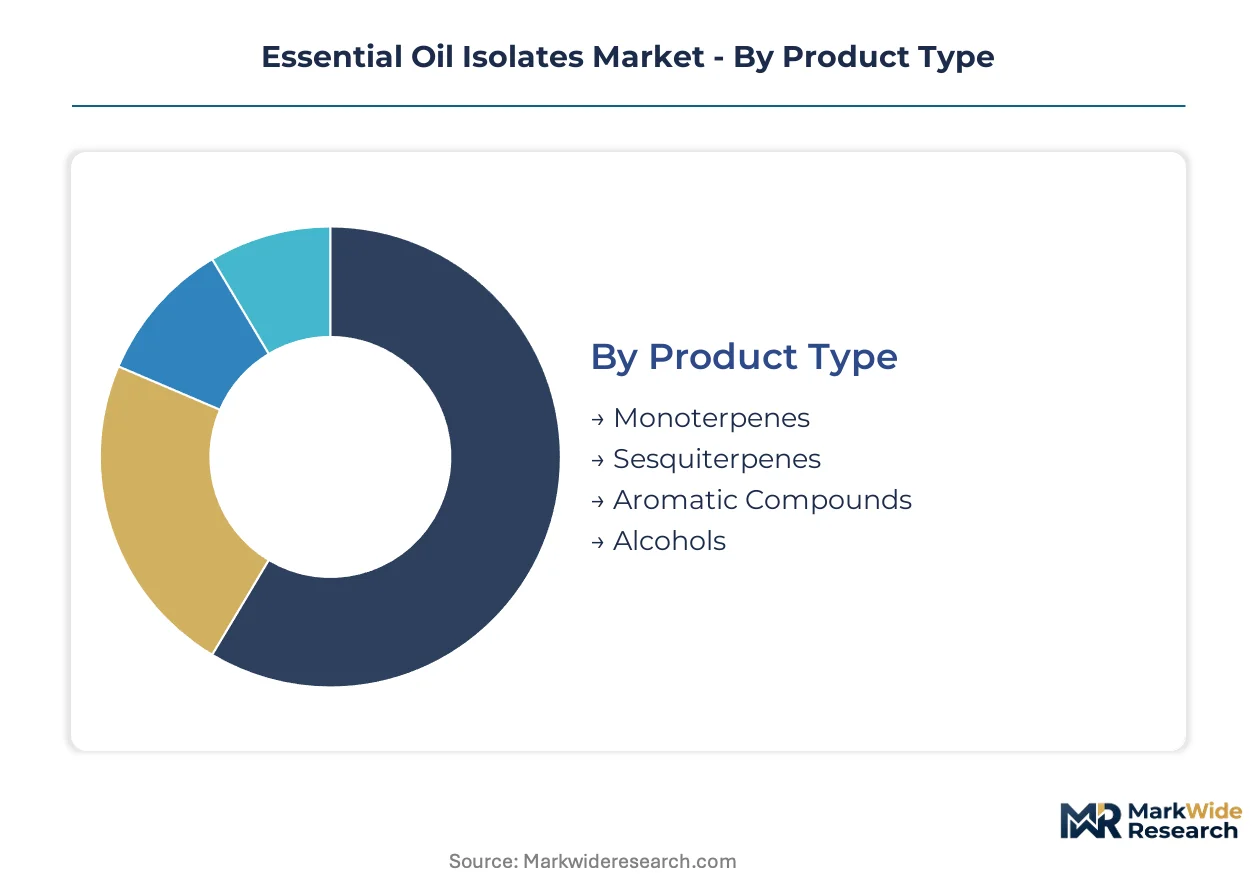
Essential oil isolates serve both as standalone active ingredients and as embedded inputs within complex formulations. Segmentation reveals where purity premiums command pricing power versus where commodity arbitrage dominates procurement decisions.
Product Type:
Monoterpenes and sesquiterpenes function predominantly as embedded intermediates within fragrance and therapeutic formulations, while aromatic compounds and alcohols increasingly appear as standalone certified actives in regulated applications.
- Monoterpenes:These C10 hydrocarbon fractions—limonene, pinene, and myrcene—constitute the volume backbone of isolate production. Personal care formulators in Grasse and Geneva specify monoterpenes at 95%+ purity for fragrance compounding, though REACH solvent restrictions now disqualify hexane-extracted supplies from cosmetic pipelines.
- Sesquiterpenes:Heavier C15 structures including caryophyllene and humulene command margin premiums in topical therapeutic applications. Swissmedic-registered transdermal patch manufacturers now source sesquiterpene isolates through dedicated supply contracts that bypass commodity channels entirely.
- Aromatic Compounds:Phenylpropanoid-derived molecules such as eugenol and thymol serve pharmaceutical API synthesis and antimicrobial formulations.
- Alcohols:Linalool, geraniol, and citronellol fractions meet USP-grade specifications for parenteral applications.
Monoterpenes lead volumes today; aromatic compounds are gaining share fastest.
Application:
Cosmetics and pharmaceuticals absorb isolates at markedly different purity thresholds, with food and beverage and aromatherapy applications occupying intermediate specification bands.
- Cosmetics:Fragrance compounders demand isolates with sub-ppm residual solvent profiles under ECHA Annex XVII. Grasse-based houses now dual-source from supercritical CO2 and ethanol extraction facilities to maintain formulation flexibility across regulatory jurisdictions.
- Pharmaceuticals:USP-grade certification and chiral purity validation separate qualified suppliers from commodity distillers. Basel-based API manufacturers specify enantiomeric ratios through SMB-derived isolates, displacing traditional fractional crystallization.
- Food & Beverages:FSSAI tightening of natural flavoring definitions in India drives certification investments for beverage applications.
- Aromatherapy:Wellness brands source isolates for standardized diffusion products with batch-traceable chromatographic documentation.
Cosmetics dominates current offtake; pharmaceuticals shows steepest expansion trajectory.
End User:
Personal care and healthcare procurement teams operate at opposing ends of the specification spectrum, while food industry and retail buyers prioritize cost efficiency over analytical depth.
- Personal Care:Multinational brands mandate ISO 17025-accredited certificate-of-analysis with full chromatographic traceability. Seoul-based cosmetic formulators now require quarterly audit rights and shared reference standard libraries.
- Healthcare:Hospital systems and pharmaceutical manufacturers specify isolates through pharmacopeial monographs with proprietary reference standard development.
- Food Industry:Flavor houses prioritize volume scale and supply continuity over enantiomeric purity documentation.
- Retail:Direct-to-consumer wellness brands source through e-commerce platforms that disintermediate traditional distributor markups.
Personal care leads procurement volumes; healthcare commands highest purity premiums.
Distribution Channel:
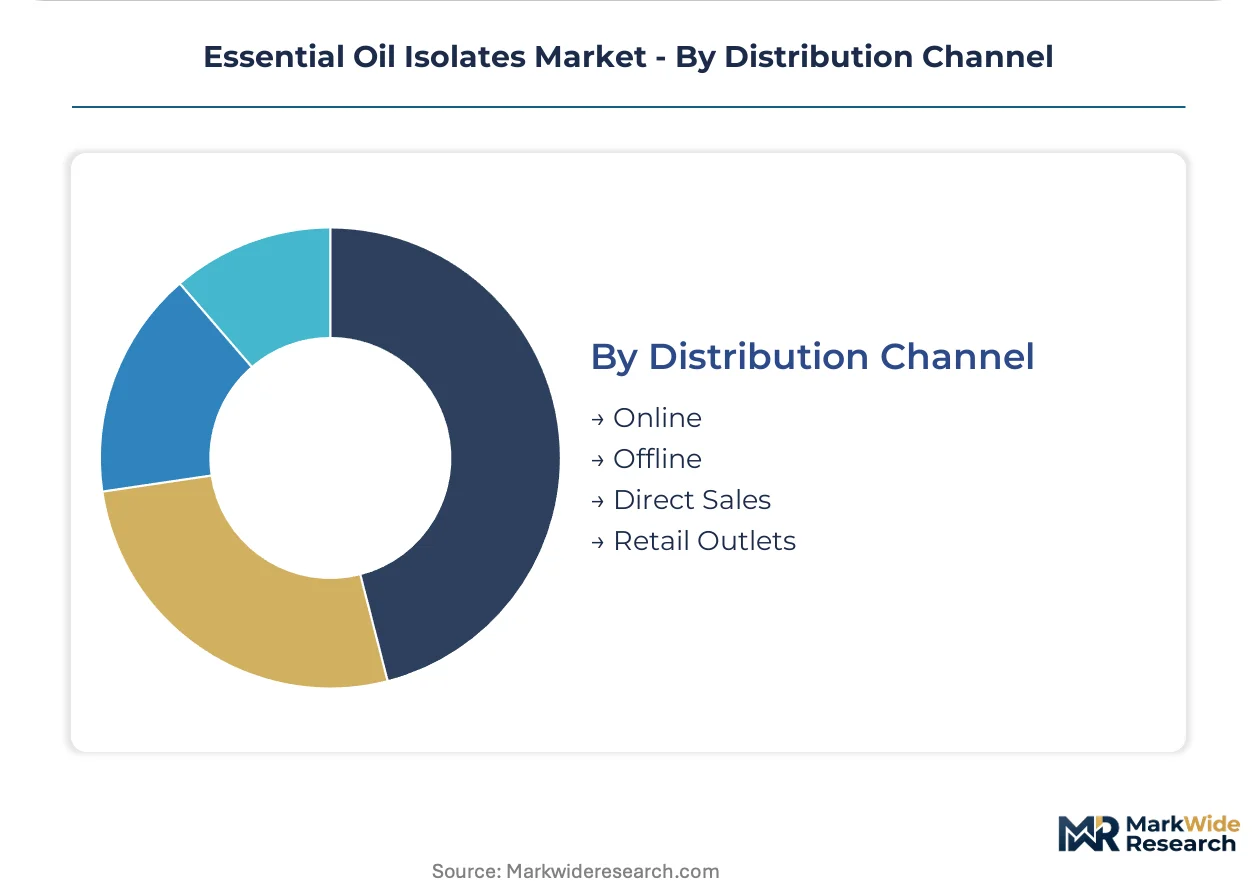
Channel selection correlates directly with order scale and technical service requirements, with direct sales capturing pharmaceutical accounts and online platforms penetrating mid-tier formulators.
- Online:E-commerce platforms serving South Korean and Australian cosmetic formulators enable sub-tonnage orders with technical documentation packages. These channels disintermediate traditional distributor markups for mid-tier compounders.
- Offline:Established distributor networks retain pharmaceutical and fragrance house relationships requiring dedicated account management and custom synthesis capabilities.
- Direct Sales:Tonnage-scale pharmaceutical manufacturers negotiate captive supply agreements with Karnataka and Kerala processing clusters.
- Retail Outlets:Wellness and aromatherapy brands distribute finished isolate products through specialty retail with consumer-facing purity claims.
Direct sales anchors pharmaceutical volumes; online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized extraction chemists cluster in Basel, Mumbai, and Seoul, anchoring quality control networks that pharmaceutical and cosmetic formulators depend on for isolate certification.
United States
Pharmaceutical formulators in Research Triangle Park and New Jersey drive demand for USP-grade monoterpenes in transdermal delivery systems. FDA CFR Title 21 food additive specifications tighten residual solvent thresholds for isolates entering beverage applications. Texas-based petrochemical producers of synthetic terpenes compete aggressively on price with botanical distillers.
Germany
Fragrance compounders in Hamburg and Geneva source high-purity aromatic isolates for cosmetic formulations. ECHA REACH registration tiering favors tonnage-scale producers with full dossier capabilities, forcing smaller extractors to consolidate. Supercritical CO2 extraction facilities in Bavaria now supply pharmaceutical-grade isolates without hexane residuals.
India
Karnataka and Kerala processing clusters supply global fragrance houses with monoterpene fractions from Mentha arvensis and Citrus reticulata feedstocks. FSSAI tightening of natural flavoring definitions drives certification investments for beverage-grade isolates. Climate stress on plantation yields generates 18-24 month price volatility that processors struggle to pass through.
Switzerland
Swissmedic-registered transdermal patch manufacturers in Basel specify sesquiterpene isolates through dedicated supply contracts with enantiomeric ratio validation. ECHA Annex XVII solvent restrictions trigger mandatory sub-ppm testing for cosmetic-bound isolates. Simulated moving bed chromatography specialists now compete for European pharmaceutical contracts previously reserved for German processors.
South Korea
Cosmetic formulators in Seoul mandate ISO 17025-accredited certificates with full chromatographic traceability and quarterly audit rights. MFDS cosmetic safety filings now require isolate-level ingredient disclosure that batch-level sourcing cannot satisfy. E-commerce platforms serving mid-tier compounders disintermediate traditional distributor markups for sub-tonnage orders.
Essential Oil Isolates Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade certification networks, while commodity distillers compete on volume scale for fragrance applications. The vendor base stratifies across three tiers: integrated processors with captive cultivation, specialized extraction houses with chromatographic capabilities, and regional distillers serving local aromatherapy markets. Dominant competitive moves include backward integration into cultivation assets and technology licensing for supercritical CO2 systems.
Within the integrated processing tier, Young Living Essential Oils and DoTerra exemplify archetypes combining captive distillation networks with direct-to-consumer distribution channels. NOW Foods occupies a position representing bulk supply contracting with North American supplement manufacturers. Flavex Naturextrakte GmbH anchors the specialized extraction segment, exemplifying European houses with advanced purification capabilities for regulated pharmaceutical applications.
| Leading Market Players |
|---|
| Young Living Essential Oils |
| DoTerra |
| NOW Foods |
| Flavex Naturextrakte GmbH |
| Advanced Biotech |
| The Lebermuth Company |
| Plant Therapy |
| Cedarome |
| India Essential Oils |
| Others |
Supply & Pricing Matrix
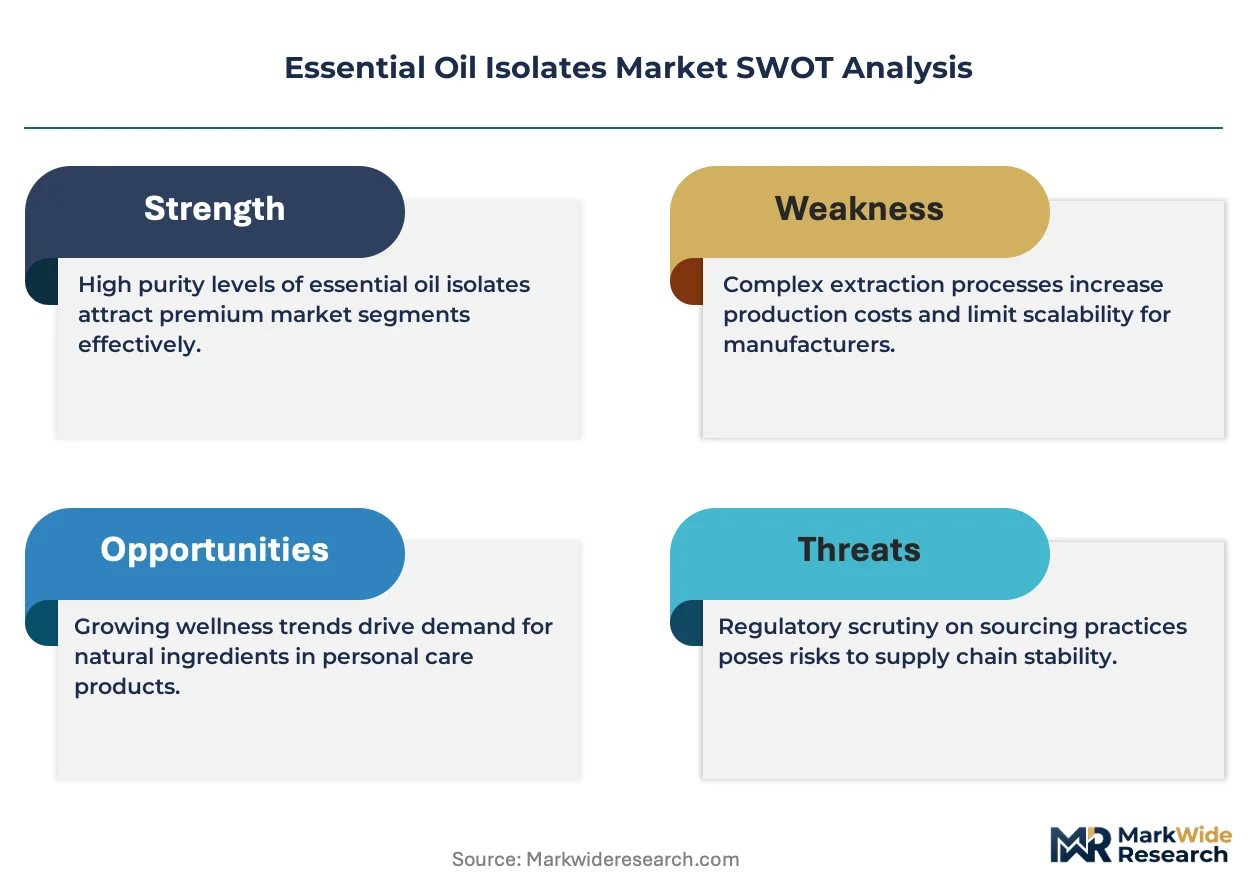
Supercritical CO2 extraction adoption simultaneously compresses production costs for pharmaceutical-grade isolates and consolidates supply among processors capable of seven-figure capital deployment, locking out hexane-dependent distillers from REACH-compliant cosmetic channels while concentrating margin capture in Karnataka and Kerala clusters.
Pricing Analysis
Certification-bundled versus unbundled supply splits the market into three distinct tiers. Premium-mid-economy pricing differentiation separates USP-grade pharmaceutical isolates with full chromatographic documentation from fragrance-grade monoterpenes sold on spot contracts. Price differentiation rests on ISO 17025 accreditation status and REACH dossier completeness. Cost compression in mid-tier aromatic compounds is intensifying because Texas and Rotterdam petrochemical producers undercut botanical supplies. Fragrance houses in Grasse exhibit highest price sensitivity; Basel pharmaceutical formulators show least.
Supply Chain Analysis
Qualification gating through ISO 17025 and REACH registration tiering concentrates compliant supply among Indian, German, and Swiss processors with full analytical capabilities. Raw material flows draw from Mentha arvensis plantations in Karnataka, Citrus reticulata orchards in Kerala, and lavender fields in Provence. Single-source vulnerability runs through climate-stressed Indian feedstock regions subject to 18-24 month yield cycles. Distribution runs through direct sales for pharmaceutical tonnage and e-commerce platforms for mid-tier cosmetic compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA's 2023 Annex XVII solvent restriction update forces processor consolidation and creates qualification premiums for compliant suppliers.
For Market Incumbents: To counter synthetic terpene substitution from Texas and Rotterdam petrochemical producers, secure captive cultivation contracts in Karnataka and Kerala while investing in simulated moving bed chromatography capabilities for enantiomeric purity validation. Backward integration into Mentha arvensis and Citrus reticulata plantations insulates feedstock volatility exposure. For New Entrants and Emerging Players: Begin with FSSAI-compliant beverage-grade isolates in India where natural flavoring mandate tightening outpaces domestic certification capacity. South Korean cosmetic formulators present the most penetrable mid-tier segment through e-commerce platforms with bundled technical documentation and quarterly audit rights. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distillers lacking ISO 17025 accreditation yet possessing fractional distillation assets in proximity to Karnataka and Kerala feedstock clusters. Long-term viability hinges on REACH dossier completion and USP-grade certification pathways. The signal to watch is pharmacopeial monograph adoption timelines for novel isolates.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Completion | Full registration unlocks European pharmaceutical and cosmetic contracts previously closed to sub-threshold competitors. |
| Supercritical CO2 Capacity Expansion | Solvent-free extraction secures USP-grade certification without residual hexane concerns for Basel formulators. |
| Cultivation Asset Acquisition | Captive Mentha arvensis and Citrus reticulata supply buffers 18-24 month climate-driven price volatility cycles. |
| Simulated Moving Bed Chromatography Licensing | Continuous enantiomer separation technology enables Indian processors to compete for European pharmaceutical contracts. |
| E-Commerce Platform Partnership | Direct technical relationships with Seoul and São Paulo mid-tier formulators disintermediate traditional distributor markups. |
Research Methodology
Direct dialogue with extraction plant managers, fragrance compounders in Grasse and Geneva, pharmaceutical procurement leads in Basel, FSSAI compliance officers, and Karnataka processing cluster operators grounded the qualitative framework. Secondary validation drew from ECHA REACH registration databases, USP monograph publications, FSSAI flavoring regulation updates, and Indian customs export records. Bottom-up volume estimates from individual processor capacities triangulated against top-down demand projections from end-use industry consumption patterns.
Bottom-up modeling aggregated individual facility capacities across Karnataka, Kerala, Bavaria, and Basel processing clusters, while top-down analysis calibrated against fragrance compounding, pharmaceutical API synthesis, and beverage flavoring demand segments. Segmentation dimensions included isolate purity grade, extraction technology type, end-use application, and regional regulatory compliance tier. CAGRs were derived from slope analysis of fitted demand curves incorporating REACH implementation timelines and FSSAI mandate phase-ins. Forecast inputs included climate yield models for Indian feedstock regions and petrochemical terpene pricing from Texas and Rotterdam crackers.
Several conditions sit outside the modeled scope, including unannounced pharmacopeial monograph revisions, abrupt ECHA solvent restriction updates, and synthetic biology breakthroughs enabling microbial terpene fermentation at scale. Forecasts reflect documented assumptions about regulatory implementation timelines and feedstock yield stability. A model refresh is warranted upon material change in ECHA Annex XVII enforcement intensity or FSSAI natural flavoring definition finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Organic Herbal Extracts Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Gum Turpentine Oil Market
Extracts
Wild Yam Powder Market
Extracts
Global Marigold Flower Extract Market
Extracts
Marine Algae Polysaccharides Market
Extracts
Nigella Sativa Extract Market
Extracts
Organic Extracts Market
Extracts
White Willow Bark Extract Market
Extracts
Pennyroyal Oil Market
Extracts
Flower Extract Market
Extracts
Glycerol Extracts Market
Extracts
Agmatine Market
Extracts
Hydroglycolic Extracts Market
Extracts
Saffron Extract Market
Extracts
Botanicals Market