
 PACVD-Based Coatings Market | 2026-2036
PACVD-Based Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
PACVD-Based Coatings Market Outlook
REACH compliance is decoupling European suppliers from legacy precursor supply chains. IHI Ionbond AG leverages captive precursor synthesis to sustain margin stability across its Swiss-German operations. Oerlikon Balzers anchors high-volume automotive coating contracts through dedicated production cells in Liechtenstein. Applied Materials Inc competes in semiconductor-facing PACVD equipment with proprietary chamber designs.
Plasma-assisted chemical vapor deposition (PACVD) deposits thin functional films from ionized gas-phase precursors at substrate temperatures typically below 400°C, enabling coating of temperature-sensitive substrates such as hardened steels and polymers. The process generates dense, adherent coatings for wear protection, friction reduction, and chemical barrier applications across precision engineering sectors. Diamond-like carbon dominates cutting tool applications where extreme hardness and low coefficient of friction justify premium positioning. Silicon nitride leads optical coatings due to its tunable refractive index and infrared transparency. Titanium nitride retains stronghold in decorative finishes despite mature growth trajectories.
EMA's evolving substance restrictions under REACH reshape acceptable precursor chemistries for European coating houses. EPA oversight of fluorinated greenhouse gas emissions in the United States narrows process gas options for domestic producers. ISO 18562 biocompatibility standards govern PACVD coatings in medical devices, creating certification barriers for non-specialized entrants. Stakeholders must evaluate precursor substitution timelines against equipment retrofit cycles to preserve operational continuity.
Market Dynamics
EU F-Gas Regulation is forcing fluorinated precursor substitution across European coating houses, triggering simultaneous equipment retrofit cycles and chemistry requalification timelines that compress operating margins while locking in competitive positions.
Growth Catalysts
- Powertrain DLC Adoption:Automotive OEM specifications for diamond-like carbon on valve train components and fuel injection systems are expanding addressable coating volumes in Stuttgart and Wolfsburg manufacturing clusters.
- REACH Precursor Substitution:ECHA substance restrictions are decoupling compliant suppliers from legacy supply chains, creating captive synthesis advantages for vertically integrated European coating houses.
- Medical Device Biocompatibility:ISO 18562 certification requirements for implantable cardiovascular and orthopedic devices are filtering non-specialized coating providers from surgical instrument and implant supply chains.
Market Restraints
- Perfluorinated Gas Cost Volatility:Tetrafluoromethane and hexafluoroethane pricing swings under EU quota allocations are compressing process economics for non-integrated coating service providers.
- German Equipment Concentration:PACVD system manufacturing clusters around Munich and Dresden create single-source dependency risks for coating houses seeking chamber expansion or replacement.
- Thermal Spray Substitution:High-velocity oxygen fuel and atmospheric plasma spray processes retain cost advantages for thick-film wear protection on non-temperature-sensitive substrates.
Strategic Opportunities
- India Precision Manufacturing:BIS certification alignment with ISO standards and PLI scheme incentives for automotive component exports are opening coating service contracts for cutting tool and transmission gear producers in Pune and Chennai.
- Semiconductor Chamber Coatings:Convergence of PACVD with atomic layer deposition process flows is enabling single-source qualification for etch chamber protective films and wafer handling component coatings.
- Fluorine-Free Chemistry Mandates:EU Green Deal timelines for perfluorinated compound phase-out are accelerating competitive repositioning around silane-based and hydrocarbon precursor platforms.
Industry Challenges
- Plasma Physics Specialist Scarcity:Process engineering talent capable of tuning pulsed-DC and microwave plasma configurations for multi-layer optical stacks remains concentrated among German and Swiss technical universities.
- Dual Certification Timelines:Concurrent ECHA REACH substance authorization and ISO 13485 medical device quality management audits are extending new coating formulation commercialization cycles by 18-24 months.
- Legacy System Integration:Retrofitting 1990s-era batch chambers with fluorine-free gas delivery and exhaust abatement systems requires custom mechanical engineering that strains maintenance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PACVD-Based Coatings Market |
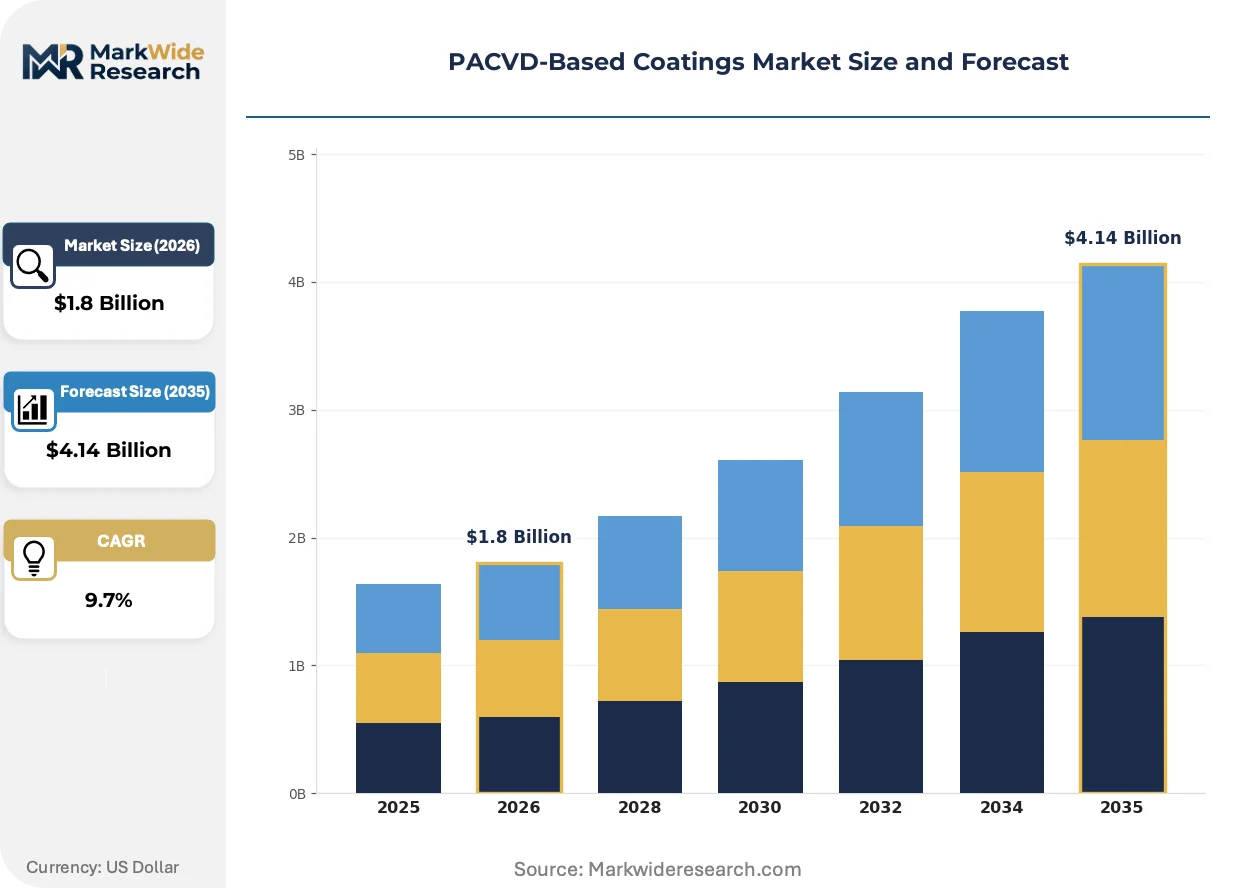
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Nitride, Titanium Nitride, Diamond-Like Carbon, Silicon Carbide End User: Aerospace, Automotive OEMs, Electronics, Medical Devices Technology: Low-Pressure Chemical Vapor Deposition, Atmospheric Pressure Chemical Vapor Deposition, Plasma-Enhanced Chemical Vapor Deposition, Thermal Chemical Vapor Deposition Application: Cutting Tools, Optical Coatings, Decorative Finishes, Corrosion Resistance |
| Companies Covered | IHI Ionbond AG, Adeka Corporation, Kurt J Lesker Company, Veeco Instruments Inc, Tokyo Electron Limited, Plasma Therm LLC, Applied Materials Inc, Oerlikon Balzers, Ulvac Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PACVD-Based Coatings Market Strategic Shifts
Process architecture standardization and precursor chemistry diversification are compressing equipment qualification cycles while fragmenting competitive advantage away from proprietary chamber designs toward operational execution and regulatory compliance velocity.
Hybrid PACVD-PECVD process architectures are modularizing across semiconductor equipment maintenance providers, enabling single-platform deposition of graded silicon carbide-silicon nitride stacks for plasma etch chamber components. Foundry maintenance contractors in Hsinchu and Dresden are adopting these configurations to reduce vendor qualification overhead. Equipment modularity is compressing capital deployment timelines from 18 months to 8 months for chamber refurbishment lines.
EPA fluorinated greenhouse gas emission reporting requirements under the American Innovation and Manufacturing Act are narrowing process gas portfolios for US-based coating operations serving aerospace and defense supply chains. Domestic producers are accelerating methane and acetylene-based DLC process validation to preserve contract eligibility for Department of Defense component programs. California-based medical device coating houses face the most acute compliance compression due to overlapping CARB and federal reporting thresholds.
Automotive tier-one suppliers are consolidating coating procurement under single-source technical service agreements that bundle process development, production volume, and field failure analysis. This model displaces transactional spot-buying of coated components and favors coating houses with captive metrology and tribology testing capabilities. Procurement concentration is most visible in Germany's Baden-Württemberg automotive supplier corridor, where transmission and engine component contracts now specify 10-year coating performance warranties.
PACVD-Based Coatings Market Segmentation
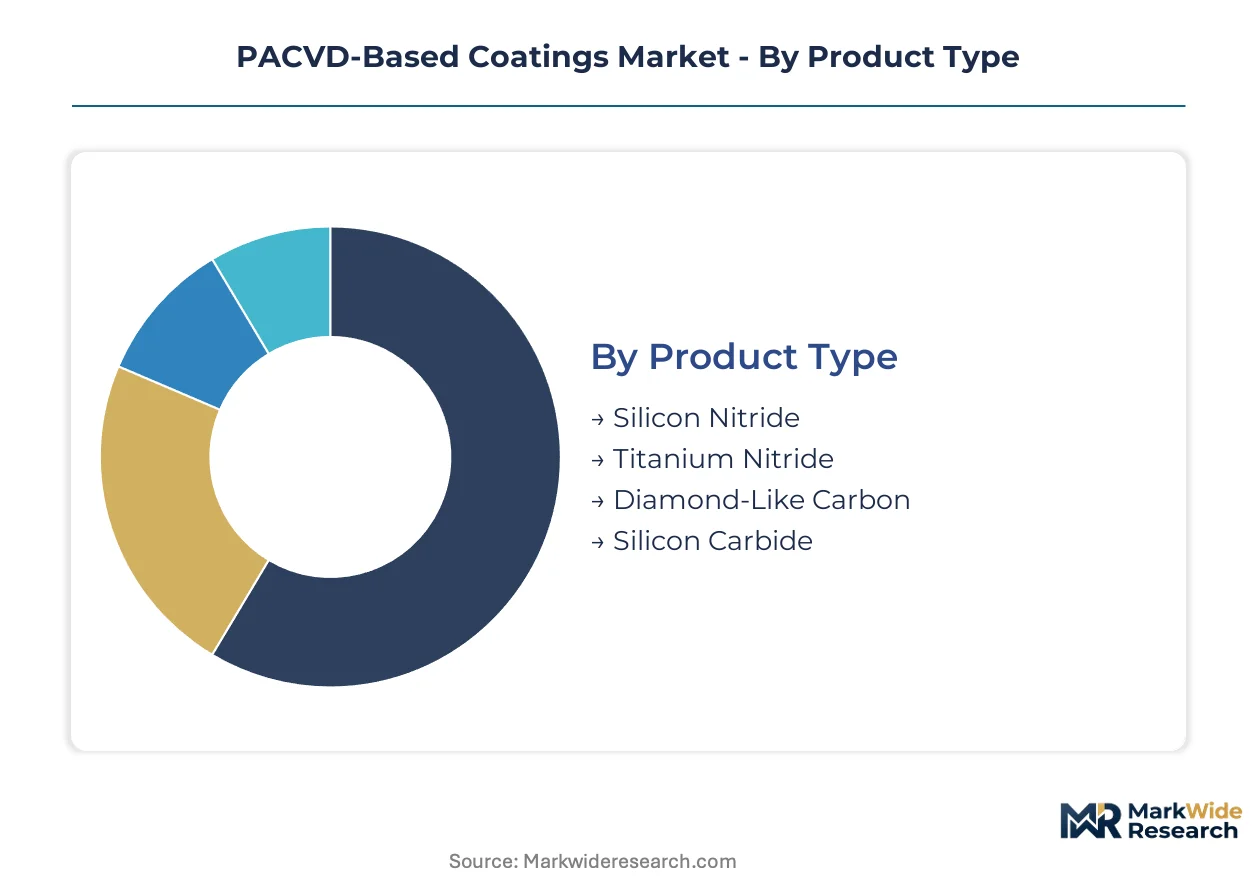
PACVD coating specifications diverge sharply across end-use sectors, with automotive powertrain demands for tribological performance driving fundamentally different precursor portfolios than medical device biocompatibility requirements. Segmentation clarity enables coating houses to align equipment configurations and regulatory compliance investments with specific revenue pools.
Product Type:
Customization intensity spans from commodity decorative films to highly engineered multi-layer optical stacks, with process complexity and margin structure inversely correlated to standardization potential.
- Diamond-Like Carbon:Amorphous carbon films with sp3-bonded domains deliver extreme hardness exceeding 20 GPa and friction coefficients below 0.1. Demand concentrates in Stuttgart and Wolfsburg automotive clusters where valve train and fuel injection specifications mandate 10-year performance warranties. EU F-Gas Regulation is accelerating hydrocarbon precursor substitution for fluorinated methane chemistries.
- Silicon Nitride:Stoichiometric Si3N4 films with tunable refractive index from 1.8 to 2.1 dominate infrared optical window applications. German precision optics manufacturers in Jena and Oberkochen anchor volume demand for thermal imaging and laser system components. REACH precursor authorization timelines are filtering non-integrated coating providers from qualified supplier lists.
- Titanium Nitride:Golden-colored ceramic coating for decorative hardware and consumer goods with mature growth trajectories.
- Silicon Carbide:Graded SiC-Si3N4 stacks for semiconductor plasma etch chamber protection in Hsinchu and Dresden foundry maintenance operations.
Leading the category by volume: Diamond-Like Carbon. Growing fastest: Silicon Carbide.
End User:
Customer concentration follows regulatory stringency gradients, with medical device and aerospace certification barriers creating protected margin pools distinct from automotive volume plays.
- Automotive OEMs:Transmission gear, engine component, and fuel system coating contracts specify integrated tribology testing and field failure analysis capabilities. Procurement consolidation under single-source technical service agreements in Baden-Württemberg favors coating houses with captive metrology infrastructure.
- Medical Devices:ISO 18562 biocompatibility and ISO 13485 quality management certifications govern implantable cardiovascular and orthopedic device coatings. Dual audit timelines extend new formulation commercialization by 18-24 months, concentrating supply among specialized European and Swiss coating houses.
- Aerospace:EPA fluorinated greenhouse gas reporting under the American Innovation and Manufacturing Act constrains process gas portfolios for US-based operations serving Department of Defense programs.
- Electronics:Semiconductor chamber component coatings converge PACVD with atomic layer deposition process flows for single-source qualification.
Automotive OEMs command the largest revenue share. Medical Devices posts the steepest expansion trajectory.
Technology:
Equipment architecture selection determines substrate temperature limits, deposition rate economics, and precursor chemistry flexibility across application portfolios.
- Plasma-Enhanced Chemical Vapor Deposition:Ionized gas-phase activation enables film growth below 400°C for temperature-sensitive hardened steels and polymer substrates. Pulsed-DC and microwave plasma configurations require specialized process engineering talent concentrated at German and Swiss technical universities.
- Low-Pressure Chemical Vapor Deposition:Thermal activation at reduced pressure delivers superior film conformality for complex geometries. Munich and Dresden equipment manufacturing clusters create single-source dependency risks for chamber expansion.
- Atmospheric Pressure Chemical Vapor Deposition:Eliminates vacuum infrastructure requirements for cost-sensitive large-area coating applications.
- Thermal Chemical Vapor Deposition:High-temperature processes retain cost advantages for thick-film wear protection on non-temperature-sensitive substrates.
Plasma-Enhanced Chemical Vapor Deposition dominates installed capacity. Atmospheric Pressure Chemical Vapor Deposition is climbing the fastest.
Application:
Performance specification granularity separates premium technical coatings from commodity decorative films, with cutting tool and optical applications demanding metrology investments that bar casual entrants.
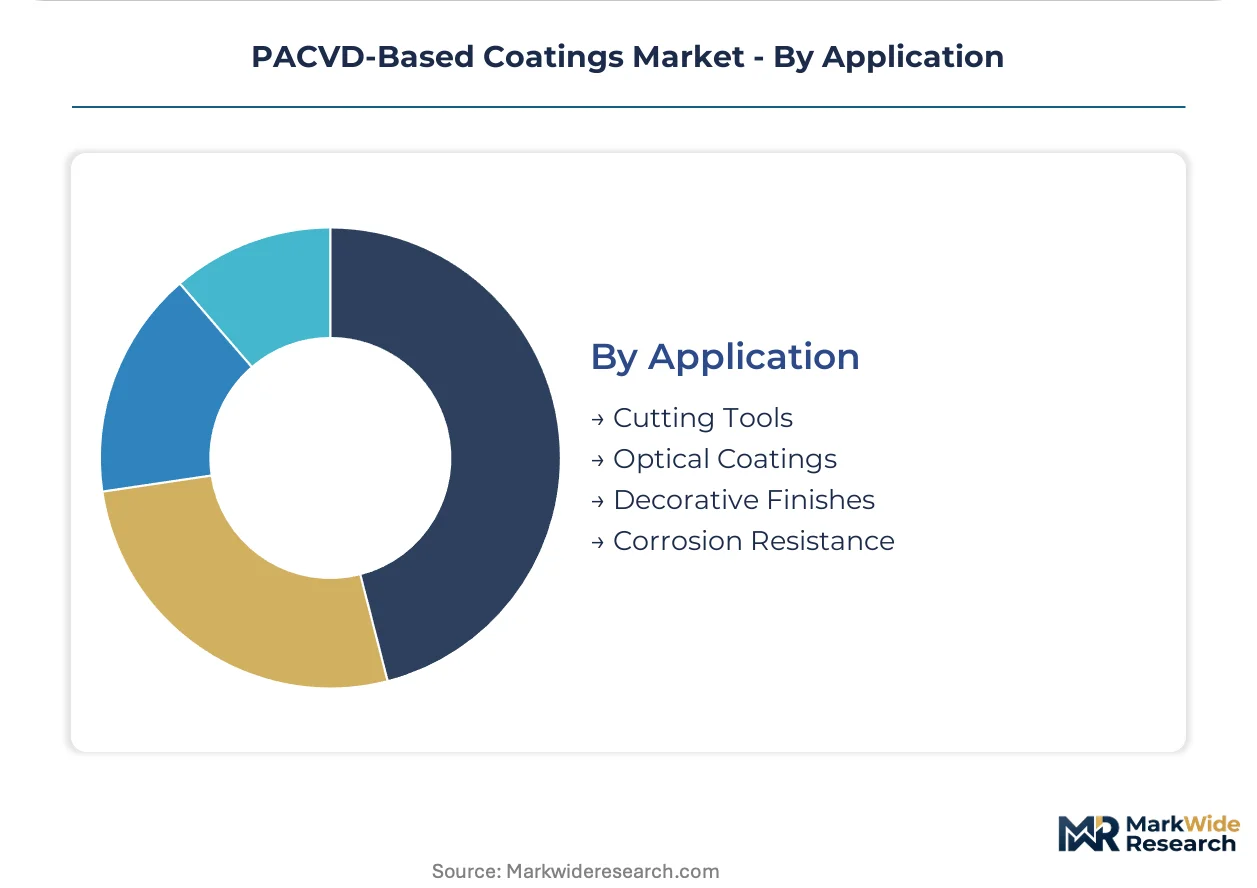
- Cutting Tools:Diamond-like carbon films with extreme hardness and low friction justify premium positioning for high-speed machining applications. German tool manufacturers in Stuttgart and Aachen precision manufacturing corridors specify coating adhesion and wear life guarantees.
- Optical Coatings:Silicon nitride and graded silicon carbide-silicon nitride stacks require precise refractive index control for infrared transparency and laser damage threshold specifications. Jena and Oberkochen optics clusters anchor European demand.
- Decorative Finishes:Titanium nitride golden aesthetic coatings for hardware and consumer goods with compressed margins and limited technical differentiation.
- Corrosion Resistance:Barrier films for chemical processing equipment and marine components with application-specific thickness and porosity requirements.
Cutting Tools leads the category by volume. Optical Coatings gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs concentrate demand for diamond-like carbon coatings on powertrain components, while Swiss precision manufacturers anchor high-value optical coating volumes. Regulatory divergence across major economies is fragmenting precursor supply chains and equipment qualification timelines.
Germany
Automotive transmission and engine component specifications from Stuttgart and Wolfsburg manufacturing clusters drive diamond-like carbon coating volumes. EU F-Gas Regulation accelerates fluorinated precursor substitution, compressing operating margins during chemistry requalification. The precision manufacturing corridor around Aachen anchors cutting tool coating demand with stringent adhesion and wear life guarantees.
United States
EPA fluorinated greenhouse gas reporting under the American Innovation and Manufacturing Act constrains process gas portfolios for aerospace and defense coating operations. California-based medical device coating houses face overlapping CARB and federal compliance thresholds. Department of Defense component programs are accelerating methane and acetylene-based DLC process validation to preserve contract eligibility.
Switzerland
Captive precursor synthesis capabilities sustain margin stability for coating houses serving European medical device and precision engineering markets. Swissmedic biocompatibility requirements align with ISO 18562 standards, creating certification barriers for non-specialized entrants. The Swiss-German operations corridor leverages vertical integration to decouple from legacy supply chains disrupted by REACH substance restrictions.
Japan
Semiconductor equipment maintenance providers in Tokyo and Osaka adopt hybrid PACVD-PECVD configurations for plasma etch chamber component coatings. METI industrial standards govern process gas emissions and equipment safety certifications. Nagoya-area automotive suppliers specify integrated tribology testing for transmission gear coatings under extended performance warranties.
India
BIS certification alignment with ISO standards and PLI scheme incentives for automotive component exports open coating service contracts for cutting tool and transmission gear producers. Pune and Chennai precision manufacturing clusters anchor initial demand for wear-resistant films on hardened steel substrates. CDSCO medical device regulations are beginning to replicate European biocompatibility certification requirements for implantable components.
PACVD-Based Coatings Market Competitive Environment
German and Swiss producers anchor the premium coating services tier; Japanese and American equipment specialists hold the semiconductor-facing equipment segment. The vendor base concentrates around three strategic archetypes: vertically integrated European coating houses with captive precursor synthesis, modular equipment manufacturers with standardized chamber designs, and specialized medical device coating providers with dual ISO certification capabilities. Competitive positioning hardens through M&A consolidation of regional coating service networks and strategic partnerships between equipment makers and foundry maintenance contractors.
Within the vertically integrated European tier, IHI Ionbond AG and Oerlikon Balzers exemplify the captive precursor synthesis model that insulates margin stability from REACH supply chain disruptions. Applied Materials Inc occupies a position among semiconductor equipment providers competing through proprietary chamber architectures. These three entities represent divergent competitive vectors: European coating service integration, Swiss-German manufacturing concentration, and American semiconductor equipment specialization.
| Leading Market Players |
|---|
| IHI Ionbond AG |
| Adeka Corporation |
| Kurt J Lesker Company |
| Veeco Instruments Inc |
| Tokyo Electron Limited |
| Plasma Therm LLC |
| Applied Materials Inc |
| Oerlikon Balzers |
| Ulvac Inc |
| Others |
Value Chain & Pricing Dynamics
Tetrafluoromethane spot price volatility under EU quota allocations cascades through European coating houses into three distinct pricing tiers: captive-synthesis specialists in Switzerland and Germany command premium positioning, non-integrated service providers absorb margin compression, and spot-market buyers face contract renegotiation cycles.
Pricing Analysis
Volume-driven automotive DLC contracts in Stuttgart and Wolfsburg trade at compressed margins against medical device coatings where ISO 18562 certification creates scarcity pricing. Price differentiation hinges on REACH-compliant precursor access and captive tribology testing infrastructure. Cost compression in standard automotive tiers intensifies as fluorinated chemistry substitution extends equipment retrofit timelines. Tier-one automotive suppliers exhibit lowest price sensitivity due to 10-year performance warranty requirements, while decorative finish buyers face acute spot-market pressure.
Supply Chain Analysis
REACH substance authorization and ISO 13485 dual certification gating concentrates qualified precursor supply among German, Swiss, and Japanese integrated producers. Silane-based and hydrocarbon precursor platforms draw from specialty chemical manufacturers in Germany and Japan, while PACVD system fabrication rests on Munich and Dresden equipment clusters. Single-source vulnerability in German chamber manufacturing creates expansion bottleneck risk for coating houses seeking capacity adds. Distribution runs through technical service agreements bundling process development, production volume, and field failure analysis.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PACVD-Based Coatings Market functions as a cost-of-compliance arena where EU F-Gas Regulation and REACH substance restrictions erect capital-intensive barriers that protect incumbents with captive synthesis and dual certification capabilities.
For Market Incumbents: To counter fluorine-free chemistry requalification timelines compressing operating margins, accelerate backward integration into silane-based precursor platforms and consolidate regional coating service networks through selective acquisition of REACH-compliant facilities in Germany's Baden-Württemberg corridor. For New Entrants and Emerging Players: BIS certification alignment with ISO standards in India opens a window for coating service contracts targeting Pune and Chennai precision manufacturing clusters, with automotive transmission gear producers as the most penetrable segment and integrated tribology testing as the required go-to-market anchor. For Investors and Strategic Acquirers: Distressed-cycle entries favor Swiss-German coating houses with captive precursor synthesis and dual ISO 18562/ISO 13485 certification during EU chemistry requalification waves, with fluorine-free process validation timelines as the inflection signal to monitor for margin recovery pacing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Precursor Synthesis Expansion | Insulates margin stability from REACH supply chain disruptions for European coating houses. |
| Dual Certification Investment | Extends competitive moats in medical device supply chains governed by ISO 18562 and ISO 13485. |
| Fluorine-Free Chemistry Platform Shift | Preserves EU market access under F-Gas Regulation timelines for perfluorinated compound phase-out. |
| Hybrid PACVD-PECVD Equipment Modularity | Compresses capital deployment timelines for semiconductor chamber refurbishment lines in Hsinchu and Dresden. |
| India Market Entry with BIS Alignment | Captures PLI scheme incentives for automotive component export coating contracts in Pune and Chennai. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews of coating house operations directors, automotive Tier 1 procurement managers, medical device quality assurance leads, and semiconductor foundry maintenance contractors. ECHA REACH substance databases, EPA greenhouse gas emission reports under the American Innovation and Manufacturing Act, and BIS certification registries supplied regulatory validation. Bottom-up equipment installation counts and top-down precursor consumption estimates were reconciled through iterative triangulation.
Data-stream reconciliation across product type, end user, technology, and application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing tier concentration. Fluorinated precursor quota allocations, EU F-Gas Regulation phase-out timelines, and automotive OEM specification adoption curves served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for hydrocarbon-based DLC deposition would alter the outlook if fluorine-free chemistry validation accelerates beyond baseline assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and equipment retrofit cycle pacing. A model refresh is warranted upon material change in EU Green Deal perfluorinated compound phase-out schedules or REACH substance authorization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Water-Based Coatings Market
Coatings
UV Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
China Marine Coatings Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
Fire Retardant Coatings Market
Coatings
Coating Binders Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Conductive Shielding Coatings for Battery Management Systems Market
Coatings
Thermal Barrier Coatings Market
Coatings
Metallic Powder Coating Market
Coatings
North America Hydrocarbon Fire Intumescent Coating Services Market
Coatings
Thermal Insulation Coating Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
US Protective Coatings Market