
 North America Copper Sulphate Market | 2026-2036
North America Copper Sulphate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Copper Sulphate Market Intelligence
Technical support and soil-testing subscription bundles is decoupling copper sulphate from pure commodity sales across the North American farm channel. Old Bridge Minerals anchors its position through backward integration into copper scrap recovery, while Jost Chemical Co. differentiates via USP-grade manufacturing for pharmaceutical and nutritional applications. Allan Chemical Corporation leverages regional blending facilities to control logistics costs in the Great Lakes corridor.
Copper sulphate refers to inorganic copper(II) salt compounds, with pentahydrate (CuSO₄·5H₂O, 25.47% Cu content) representing the dominant commercial form produced via copper scrap dissolution in sulfuric acid followed by crystallization; the material functions primarily as a micronutrient supplement, algicide, and electroplating bath constituent. Pentahydrate crystals command the largest volume share given their solubility profile and handling characteristics in agricultural spray tanks. Agricultural grade formulations carry the deepest margin pools due to custom blending requirements and seasonal offtake patterns tied to planting calendars. Electroplating applications sustain premium pricing through stringent purity thresholds and technical service dependencies.
EPA pesticide registration under FIFRA governs fungicidal and algal control claims, while OSHA permissible exposure limits shape workplace handling protocols during blending and bagging operations. The USDA organic program allows restricted copper sulphate use in certified crop production, creating a dual-track compliance environment for suppliers. Stakeholders must monitor state-level water quality discharge rules, as Great Lakes and Chesapeake Bay watershed regulations increasingly restrict copper runoff from agricultural and industrial sources.
Market Dynamics
EPA's ongoing re-evaluation of copper-based pesticide tolerances under FIFRA is compressing product registration timelines and forcing reformulation investments across the agricultural supply chain. This regulatory pressure is reshaping competitive positioning between legacy pentahydrate producers and specialty formulation houses.
Growth Catalysts
- USDA Organic Program:Restricted copper sulphate use in certified crop production creates a dual-track compliance environment that premiumizes agricultural-grade formulations.
- Soil micronutrient testing:Subscription-based agronomic services in the Midwest corn-soy belt are embedding copper sulphate into recurring input bundles rather than spot commodity purchases.
- Copper deficiency mapping:Precision agriculture platforms are identifying untreated acreage across Nebraska and Iowa, expanding addressable demand for pentahydrate soil amendments.
Market Restraints
- Sulfuric acid feedstock volatility:Copper scrap dissolution costs fluctuate with acid pricing and scrap availability, squeezing margin predictability for crystallization-based producers.
- Great Lakes watershed discharge rules:State-level copper runoff restrictions in Michigan and Ohio are narrowing permitted application windows for agricultural fungicide uses.
- Synthetic fungicide substitution:Triazole and strobilurin chemistry advances in crop protection are displacing copper sulphate in certain high-value fruit and vegetable segments.
Strategic Opportunities
- USP-grade pharmaceutical channel:Nutritional supplement and veterinary applications command 3-4x agricultural pricing with lower seasonality.
- Electroplating bath regeneration services:Closed-loop copper recovery contracts with automotive and electronics finishers create recurring revenue streams.
- Algae control in precision aquaculture:Recirculating aquaculture systems in Canada and the US Northeast are adopting controlled-dose copper protocols for biofouling management.
Industry Challenges
- FIFRA registration timeline compression:EPA data call-ins for ecological toxicity studies are extending product approval cycles to 36-48 months.
- Blending facility capital intensity:Seasonal demand spikes require redundant tankage and bagging lines that sit idle 6-8 months annually.
- Legacy ERP integration:Soil-testing subscription platforms require API connectivity that many mid-size copper sulphate distributors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Copper Sulphate Market |
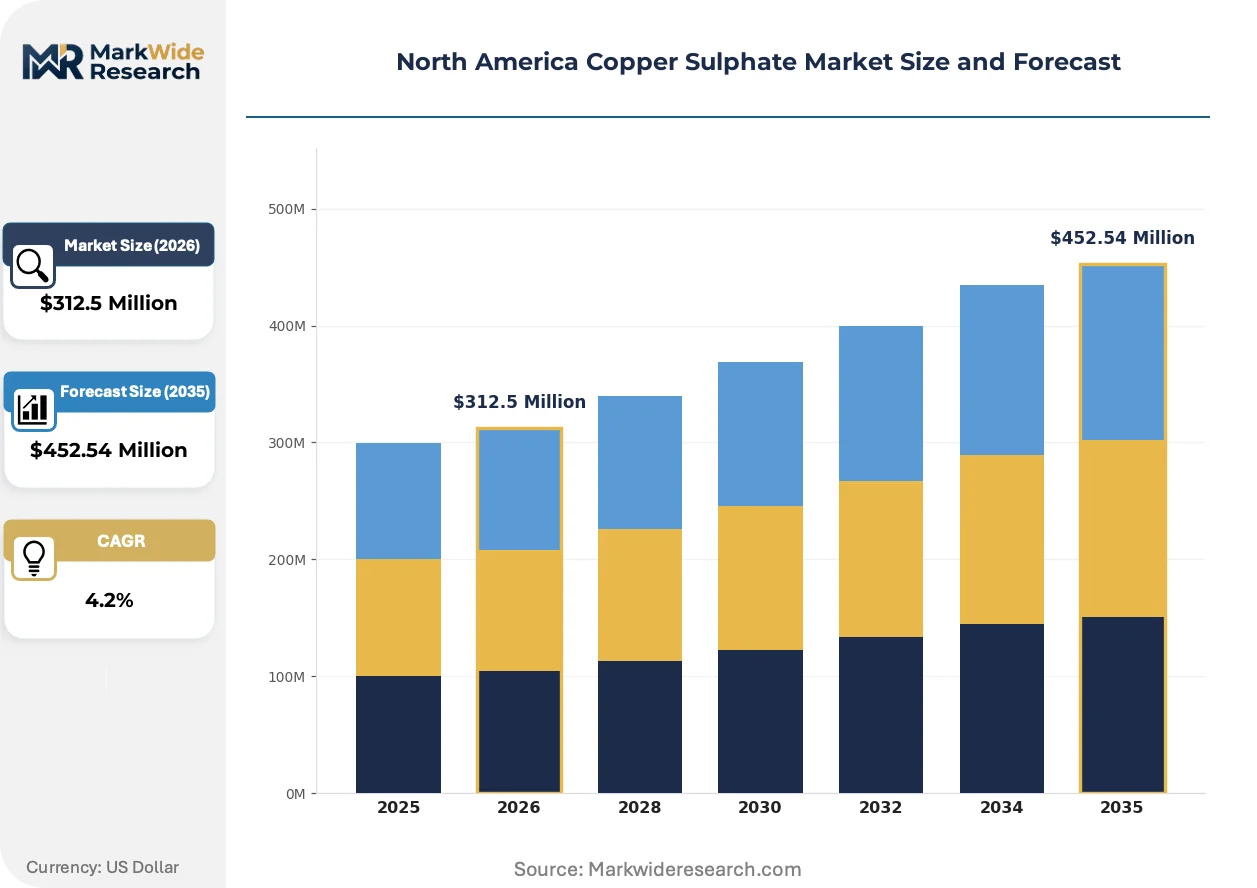
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $452.54 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous, Pentahydrate, Corrosion Inhibitors, Feed Grade End User: Agriculture, Mining, Water Treatment, Chemical Industry Application: Fungicide, Herbicide, Algal Control, Electroplating Grade: Industrial Grade, Agricultural Grade, Food Grade, Pharmaceutical Grade |
| Companies Covered | Old Bridge Minerals, Jost Chemical Co., Allan Chemical Corporation, NOAH Technologies Corp., Sulcona, Beneut Enterprise, Highnic Group, Univertical Corp., Wego Chemical Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Copper Sulphate Market Strategic Shifts & Innovations
Formulation technology and service bundling are displacing commodity trading as the dominant value-capture mechanism. Producers are racing to embed copper sulphate into recurring agronomic workflows rather than competing on spot price alone.
Encapsulated controlled-release copper sulphate is modularizing application timing flexibility for growers. Specialty coating technologies from agricultural input suppliers allow single-pass planting and micronutrient delivery. Large-scale corn operations in Illinois and Indiana are adopting these formulations to reduce field passes during compressed planting windows. The technology is modularizing what were previously separate soil amendment and crop protection applications into unified input bundles.
EPA's ecological risk assessment for copper-based pesticides is tightening aquatic toxicity thresholds for agricultural uses. The agency's 2024-2026 registration review cycle is demanding additional mesocosm studies for pentahydrate formulations. Fungicide suppliers serving the Chesapeake Bay watershed are preemptively reformulating with lower-dose chelated copper alternatives to secure label retention.
Subscription-based agronomic advisory is displacing independent crop input purchasing across the US Midwest. Grower cooperatives and regional retailers are bundling soil testing, prescription mapping, and micronutrient delivery into per-acre service contracts. This model concentrates procurement authority with fewer buyers who negotiate multi-year supply agreements. The shift is most visible in Iowa and Minnesota, where co-op agronomy programs now cover 40% of corn acreage.
North America Copper Sulphate Market Segmentation
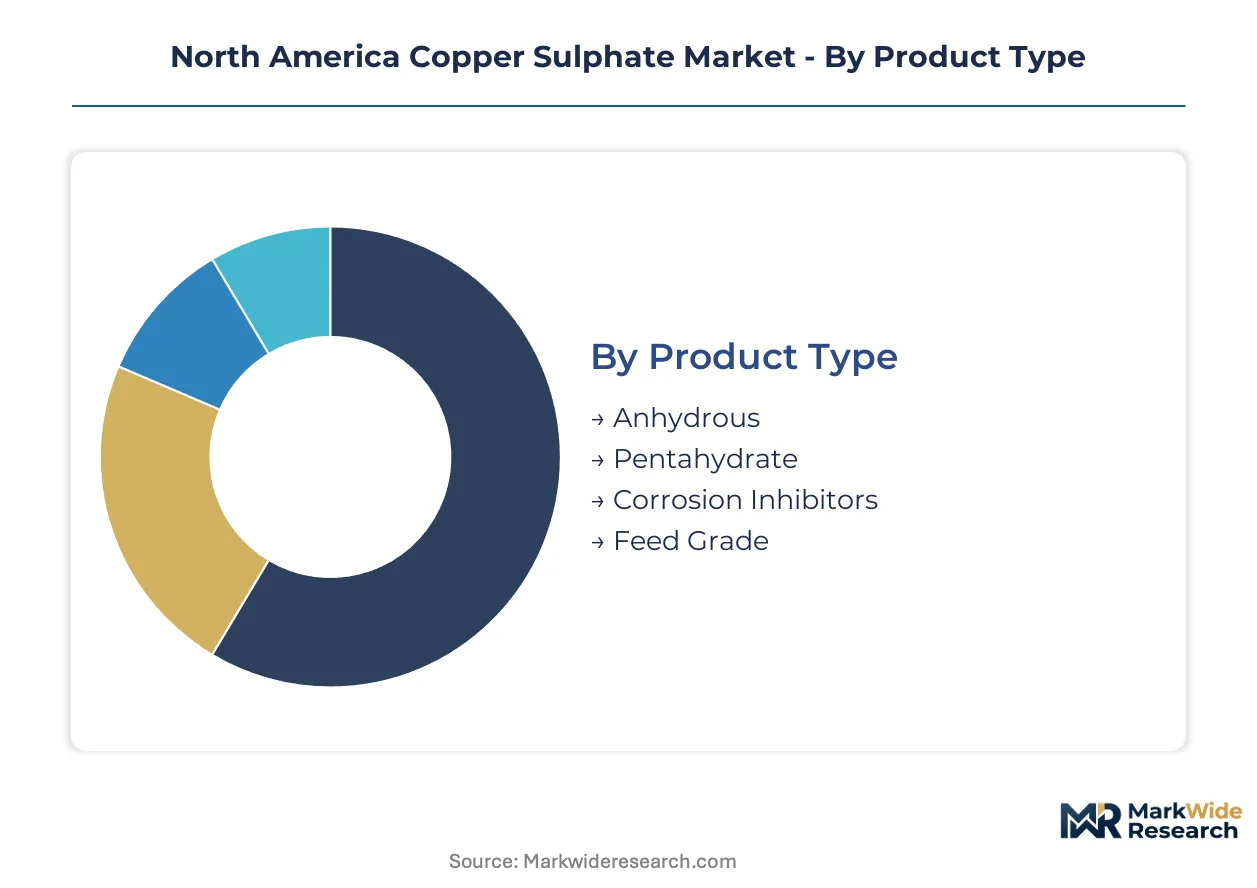
Copper sulphate segmentation in North America reflects divergent certification burdens across EPA, FDA, and USP compliance pathways. Product differentiation hinges on purity thresholds that determine accessible end-use markets and margin capture potential.
Product Type:
EPA FIFRA registration dominates pentahydrate and corrosion inhibitor segments, while feed-grade production triggers FDA Center for Veterinary Medicine oversight and AAFCO nutrient profile compliance.
- Anhydrous:Dehydrated copper(II) sulfate with 39.81% copper content serves electroplating bath formulations requiring precise concentration control. Demand clusters in Michigan and Ohio automotive finishing corridors where bath regeneration contracts specify anhydrous feedstock purity. Sulfuric acid feedstock volatility squeezes crystallization economics for this segment.
- Pentahydrate:CuSO₄·5H₂O crystals with 25.47% copper content deliver optimal solubility for agricultural spray tank compatibility. The US Midwest corn-soy belt consumes the largest volumes for soil micronutrient supplementation tied to precision agriculture subscription bundles. EPA registration review cycles compressing to 36-48 months constrain formulation innovation timelines.
- Corrosion Inhibitors:Blended formulations for industrial water systems require NSF/ANSI 60 drinking water additive certification in Great Lakes watershed jurisdictions.
- Feed Grade:Nutritional premixes for livestock and poultry integrate copper sulphate as a trace mineral supplement under FDA 21 CFR 582.80 compliance.
Leading the category by volume: Pentahydrate. Growing fastest: Corrosion Inhibitors.
End User:
Customer procurement authority concentrates through distinct channels—cooperative agronomy programs, mining chemical distributors, municipal water authorities, and specialty chemical blenders—each imposing unique specification and service requirements.
- Agriculture:Grower cooperatives in Iowa and Minnesota now cover 40% of corn acreage with bundled soil-testing and micronutrient prescription services. Subscription-based procurement displaces spot commodity purchasing across the US Midwest. USDA organic program compliance creates dual-track formulation requirements for certified crop production.
- Mining:Flotation reagent applications in Arizona and Nevada copper extraction operations demand consistent particle size distribution and low insoluble content. Leaching circuit operators negotiate multi-year supply agreements with penalty clauses for assay variance.
- Water Treatment:Municipal algae control programs in the US Northeast and Canada face tightening copper discharge limits under state-level water quality rules.
- Chemical Industry:Electroplating bath manufacturers and specialty salt producers in the Great Lakes corridor require technical service support for bath chemistry optimization.
Dominant procurement channel: Agriculture. Expanding most quickly: Water Treatment.
Application:
Application-level segmentation tracks divergent efficacy standards—agricultural fungicide claims demand EPA ecological toxicity data, while electroplating performance hinges on American Electroplaters and Surface Finishers Society specifications.
- Fungicide:Protectant spray applications on fruit and vegetable crops face displacement pressure from triazole and strobilurin synthetic chemistry advances. Chesapeake Bay watershed regulations preemptively drive reformulation toward lower-dose chelated copper alternatives to secure label retention.
- Herbicide:Burndown and desiccant uses in no-till soybean systems require precise timing to avoid phytotoxicity and copper accumulation in surface runoff.
- Algal Control:Recirculating aquaculture systems in Canada and the US Northeast adopt controlled-dose copper protocols for biofouling management in precision aquaculture operations.
- Electroplating:Bath constituent applications sustain premium pricing through stringent purity thresholds and technical service dependencies for bath analysis and additive adjustment.
Highest volume application: Fungicide. Steepest expansion trajectory: Algal Control.
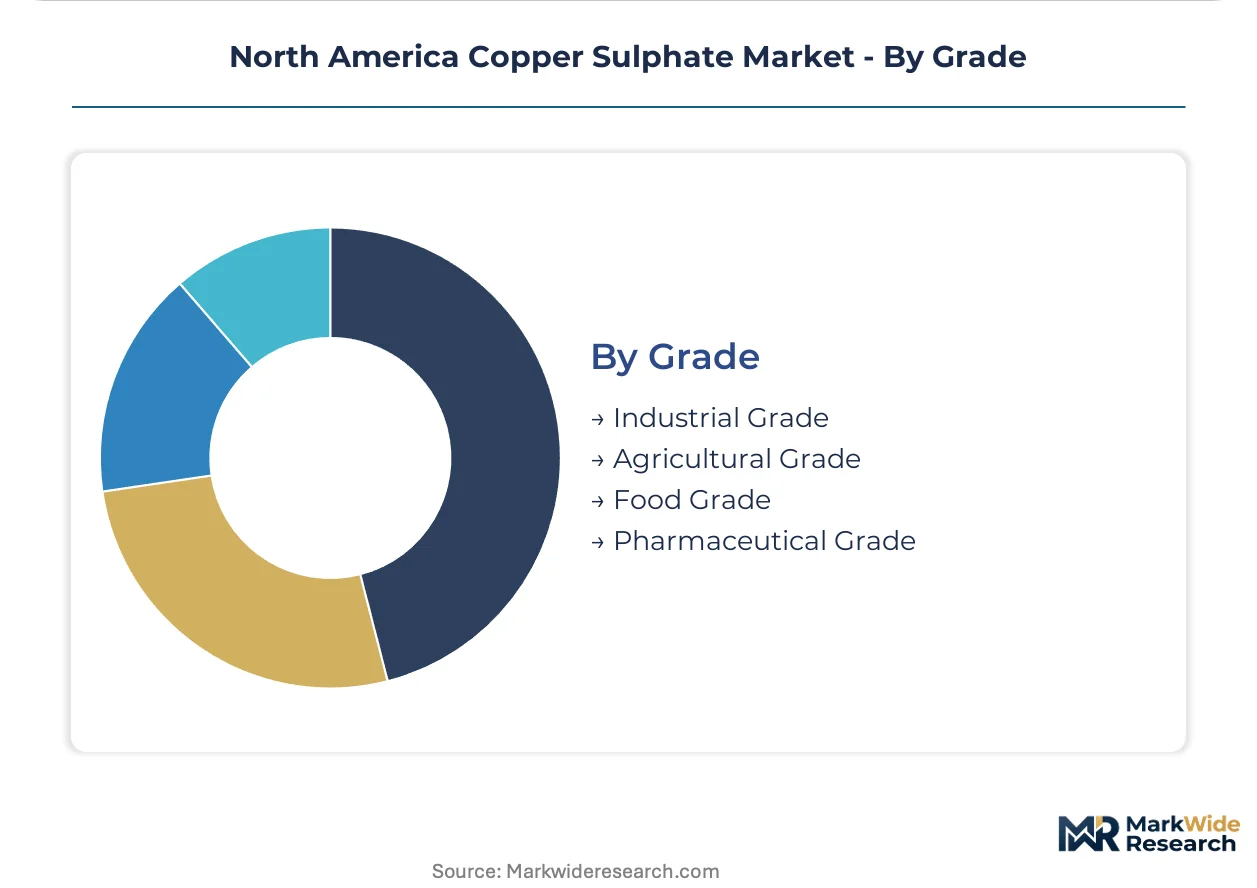
Grade:
Grade stratification determines margin architecture—pharmaceutical and food grades command 3-4x agricultural pricing through USP and FCC certification investments, while industrial grades compete on logistics efficiency and regional blending proximity.
- Industrial Grade:Standard purity specifications for mining flotation and basic chemical synthesis prioritize cost minimization over trace element control. Regional blending facilities in the Great Lakes corridor compete on bagging flexibility and railcar logistics.
- Agricultural Grade:Custom blending requirements for specific crop and soil conditions generate the deepest margin pools despite seasonal demand spikes that idle tankage 6-8 months annually. Pentahydrate crystals dominate given handling characteristics in farm spray equipment.
- Food Grade:FCC-compliant production for nutritional fortification and food processing applications requires dedicated manufacturing lines and audit documentation.
- Pharmaceutical Grade:USP monograph compliance for injectable and oral dosage forms demands validated processes and batch release testing that insulates producers from agricultural commodity cycles.
Widest margin pool: Agricultural Grade. Gaining share fastest: Pharmaceutical Grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic crystallization capacity concentrates in the Great Lakes industrial corridor, while agricultural consumption concentrates in the Midwest corn-soy belt. Canadian mining operations and Mexican electroplating clusters complete the regional demand map.
United States
The Midwest corn-soy belt drives pentahydrate consumption through precision agriculture subscription bundles covering 40% of Iowa and Minnesota corn acreage. EPA FIFRA registration reviews compressing to 36-48 months constrain formulation innovation timelines for fungicidal applications. Illinois and Indiana large-scale operations adopt encapsulated controlled-release formulations to reduce field passes during compressed planting windows.
Canada
Recirculating aquaculture systems in the Northeast and Great Lakes provinces adopt controlled-dose copper protocols for biofouling management in precision aquaculture operations. Health Canada PMRA pesticide registrations align with EPA ecological toxicity thresholds while maintaining distinct label requirements. Ontario mining flotation reagent applications demand consistent particle size distribution and low insoluble content for leaching circuit operators.
Mexico
Automotive finishing corridors in Nuevo León and the Bajío Region sustain anhydrous demand for electroplating bath formulations requiring precise concentration control. Mexican environmental regulations under SEMARNAT increasingly restrict copper discharge from industrial sources, narrowing permitted application windows. Guanajuato and Querétaro electronics manufacturing clusters negotiate multi-year supply agreements with penalty clauses for assay variance.
North America Copper Sulphate Market Key Industry Players
Top-tier vendors anchor backward integration into copper scrap recovery and USP-grade manufacturing, while regional blenders compete on logistics proximity and bagging flexibility. The vendor base splits between crystallization-based producers with captive acid supply and formulation houses specializing in custom agricultural blends. Strategic archetypes include scrap-integrated miners, pharmaceutical-grade specialists, and cooperative-linked distributors. Dominant competitive moves encompass M&A for regional blending assets and API integration with soil-testing subscription platforms.
Within the scrap-integrated tier, Old Bridge Minerals exemplifies upstream control over copper feedstock, while Jost Chemical Co. occupies the USP-grade pharmaceutical channel. Allan Chemical Corporation anchors regional blending capabilities in the Great Lakes corridor. These three represent the structural segmentation between raw material security, certification premium capture, and logistics efficiency.
| Leading Market Players |
|---|
| Old Bridge Minerals |
| Jost Chemical Co. |
| Allan Chemical Corporation |
| NOAH Technologies Corp. |
| Sulcona |
| Beneut Enterprise |
| Highnic Group |
| Univertical Corp. |
| Wego Chemical Group |
| Others |
Cost & Logistics Intelligence
Subscription-based agronomic procurement across Iowa and Minnesota co-ops is forcing crystallization producers into multi-year contract structures that compress spot-market premiums and lock in sulfuric acid feedstock exposure. This buyer consolidation concentrates pricing power with fewer procurement officers who negotiate bundled soil-testing and micronutrient delivery contracts, eroding legacy spot-sale margins.
Pricing Analysis
Margin tightening in agricultural-grade pentahydrate reflects sulfuric acid feedstock volatility and EPA registration cost absorption. Three-tier pricing structure across USP-grade pharmaceutical, custom-blended agricultural, and industrial mining grades anchors the market. Cost-down pressure on agricultural formulations accelerates because grower cooperatives now cover 40% of Midwest corn acreage with volume-committed service contracts. Mining flotation reagent buyers exhibit lowest price sensitivity due to penalty clauses for assay variance, while regional agricultural distributors face the highest squeeze.
Supply Chain Analysis
Railcar logistics from Great Lakes crystallization corridors to Midwest farm channels dominate delivered cost structures for bagged pentahydrate. Supply concentrates in Michigan and Ohio industrial corridors, with Canadian mining chemical distributors and Mexican automotive finishing clusters completing the regional map. Raw material flows draw from copper scrap recovery networks, captive sulfuric acid production, and specialty coating inputs for controlled-release formulations. Single-source vulnerability sits with EPA-registered formulation houses facing 36-48 month registration review cycles. Distribution runs through cooperative agronomy programs, regional blending facilities, and direct mine-site contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crystallization capacity idling 6-8 months annually on seasonal agricultural demand props pricing across all grade tiers, creating structural margin support for integrated producers.
For Market Incumbents: Hedge sulfuric acid exposure through backward integration into captive acid production or long-term offtake agreements with Gulf Coast refiners. Secure EPA registration data packages ahead of 2024-2026 review cycles to defend label retention against chelated copper substitutes. Prioritize API integration with soil-testing subscription platforms to lock in cooperative procurement channels before competitor formulation houses capture agronomist relationships. For New Entrants and Emerging Players: Encapsulated controlled-release coating technology offers entry into Illinois and Indiana large-scale corn operations seeking single-pass planting efficiency. Target recirculating aquaculture systems in Canada and the US Northeast with precision-dose copper protocols for biofouling management. Pursue USP-grade pharmaceutical certification to escape agricultural commodity cycles and capture 3-4x pricing multiples through nutritional supplement channels. For Investors and Strategic Acquirers: The window for entry favors scrap-integrated crystallization assets with captive feedstock security and existing EPA FIFRA registrations. Mid-tier regional blenders in the Great Lakes corridor present consolidation targets for logistics network augmentation. Watch EPA ecological toxicity threshold tightening in Chesapeake Bay and Great Lakes watersheds as the signal for chelated copper substitution acceleration and pentahydrate demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Scrap Recovery | Old Bridge Minerals anchors feedstock security against acid price volatility and scrap availability swings. |
| USP-Grade Pharmaceutical Certification | Jost Chemical Co. captures premium pricing through validated batch release testing for injectable dosage forms. |
| API Integration with Soil-Testing Platforms | Allan Chemical Corporation embeds pentahydrate into recurring agronomic workflows rather than spot commodity sales. |
| Controlled-Release Formulation Development | Specialty coating technologies modularize soil amendment and crop protection into unified input bundles for compressed planting windows. |
| Regional Blending Facility Expansion | Great Lakes corridor assets control logistics costs and bagging flexibility for seasonal demand spikes. |
Research Approach
Independent corroboration across EPA registration databases, USDA organic program filings, and state-level water quality discharge records underwrites the qualitative findings. Primary interviews with crystallization plant managers, cooperative agronomy directors, and mining chemical procurement leads combined with secondary validation from customs trade data, American Chemistry Council reports, and SEC 10-K disclosures. Bottom-up volume modeling triangulates against top-down value estimates across grade tier, end-use industry, and regional production hub dimensions.
Rate-of-change decomposition separates volume growth from pricing trajectory across the projection horizon. Segmentation dimensions modeled include product type, end user, application, and grade tier alongside regulatory compliance pathway. CAGRs derive from historical trend extrapolation adjusted for EPA registration timeline compression and precision agriculture subscription penetration. Industry-specific forecast inputs incorporate sulfuric acid feedstock cost curves and copper scrap recovery rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA data call-in delays or accelerated chelated copper substitution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Europe Lithium Chloride Market
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Borates Market
Bulk Chemicals
Global Sodium Phosphate Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Stilbene Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
North America Acetic Acid Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
Castor Wax Market