
 Global Hydroiodic Acid (Hydriodic Acid) Market | 2026-2036
Global Hydroiodic Acid (Hydriodic Acid) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydroiodic Acid (Hydriodic Acid) Market Foresight
Asset-light leasing arrangements for specialty chemical infrastructure is narrowing the capital barrier for mid-scale producers seeking hydriodic acid capacity. Iofina plc leverages vertical integration from brine extraction through iodine derivatives to sustain cost advantages in feedstock supply. Nippoh Chemicals Co. Ltd. anchors its position through decades of technical grade specialization across Asian pharmaceutical corridors. Merck KGaA differentiates via reagent grade certification that commands premium positioning in analytical laboratories worldwide.
Hydroiodic acid is an aqueous solution of hydrogen iodide, typically formulated at concentrations from 47% to 57% by weight with a strong reducing character and significant corrosivity toward most metals. Manufacturers produce it through direct synthesis from hydrogen and iodine or via redox reaction of iodine with reducing agents such as hydrogen sulfide or phosphorus, with the resulting solution serving primarily as a powerful reducing agent and iodine source across pharmaceutical, electronics, and fine chemical industries. Concentrated grades dominate volume flows into chemical reduction processes where stoichiometric efficiency matters most, while reagent grade variants capture disproportionate margin pools in pharmaceutical synthesis applications requiring batch-level traceability. Battery electrolytes represent the fastest-expanding application segment as lithium-ion and emerging solid-state battery chemistries incorporate hydriodic acid derivatives for interfacial stability.
EPA hazardous substance regulations in the United States govern transport thresholds and spill reporting protocols that elevate compliance costs for cross-border suppliers. ECHA REACH registration requirements in Europe mandate comprehensive toxicity dossiers that filter out uncertified producers from continental supply chains. China's MEE enforces wastewater discharge standards affecting on-site acid recovery economics at domestic manufacturing plants. Stakeholders must monitor evolving battery electrolyte purity specifications as automotive OEMs tighten supplier qualification criteria ahead of next-generation chemistry transitions.
Market Dynamics
China's domestic battery electrolyte manufacturing is concentrating demand for high-purity hydriodic acid, forcing Western suppliers to requalify under stricter automotive OEM purity protocols or exit the segment entirely.
Growth Catalysts
- Battery Electrolyte Derivatives:Lithium-ion and solid-state battery manufacturers in China are scaling hydriodic acid consumption for interfacial stability layers, pulling volume from traditional pharmaceutical applications.
- REACH Registration Thresholds:ECHA's comprehensive toxicity dossier requirements filter uncertified producers from European supply chains, consolidating volume among qualified registrants.
- Pharmaceutical Synthesis Expansion:Drug manufacturers are expanding hydriodic acid use in active ingredient production, particularly for iodine-containing intermediates requiring batch-level traceability.
Market Restraints
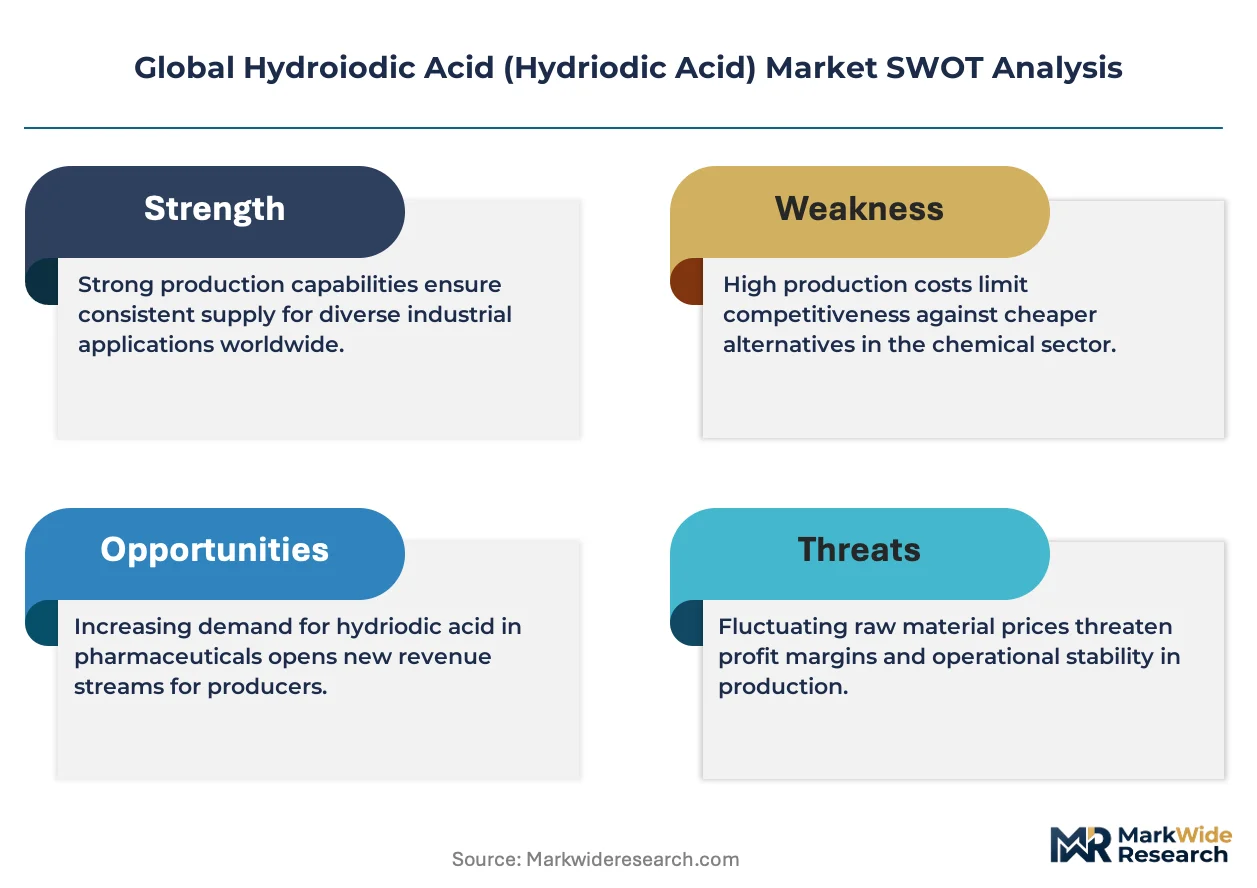
- Iodine Feedstock Volatility:Chilean and Japanese iodine concentrate supply disruptions transmit directly into hydriodic acid production cost instability, compressing margins for non-integrated producers.
- Transport Regulatory Burden:EPA hazardous substance thresholds in the United States elevate compliance costs for cross-border suppliers through mandatory spill reporting protocols and specialized container requirements.
- Phosphorus Redox Substitution:Alternative reducing agents in fine chemical synthesis threaten technical-grade volume in applications where stoichiometric precision is secondary to cost minimization.
Strategic Opportunities
- Indian Pharmaceutical Corridors:CDSCO's streamlined active pharmaceutical ingredient registration creates entry pathways for reagent-grade suppliers serving domestic generic drug manufacturing clusters.
- Asset-Light Infrastructure Leasing:Specialty chemical equipment leasing arrangements reduce capital barriers for mid-scale producers seeking hydriodic acid capacity without greenfield investment.
- Solid-State Battery Chemistry Convergence:Emerging sulfide-based electrolyte formulations incorporating hydriodic acid derivatives for lithium-metal interface stabilization open premium pricing tiers.
Industry Challenges
- Analytical Laboratory Certification Timelines:Reagent-grade batch certification for pharmaceutical applications requires extended validation cycles that strain working capital for smaller producers.
- Wastewater Recovery Economics:China's MEE discharge standards force on-site acid recovery investments that alter plant-level unit economics, particularly for older manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydroiodic Acid (Hydriodic Acid) Market |
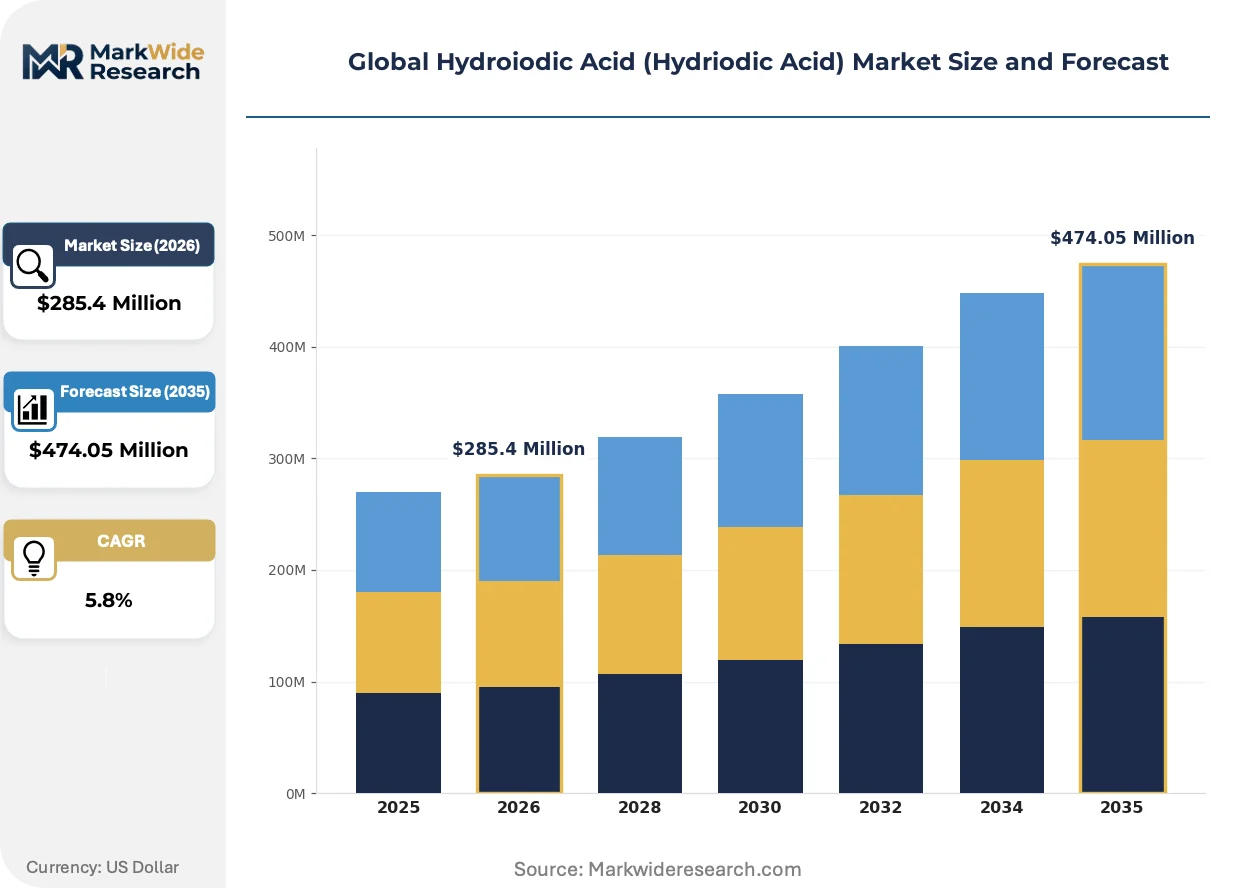
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
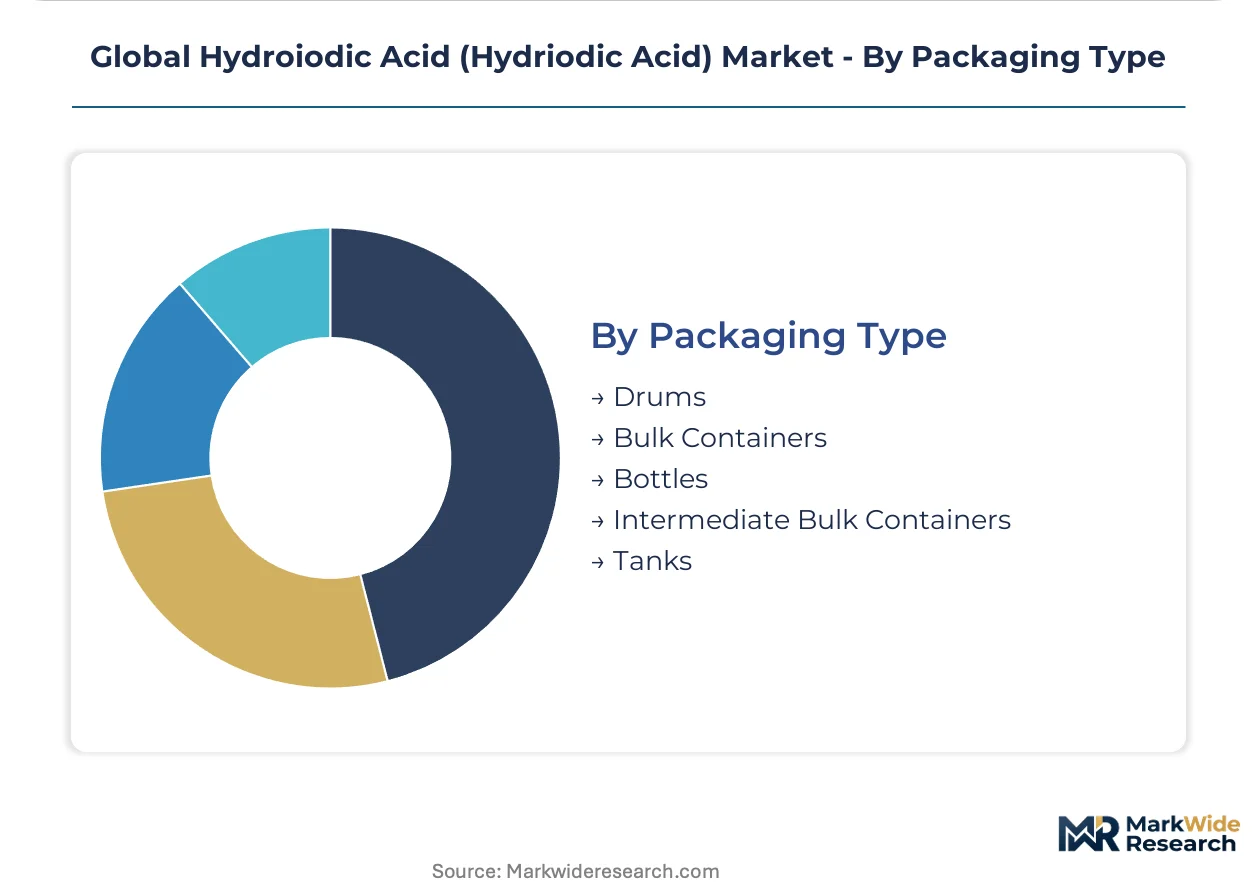
| Segmentation | Product Type: Concentrated, Dilute, Stabilized, Reagent Grade, Technical Grade Application: Pharmaceutical Synthesis, Chemical Reduction, Catalyst, Battery Electrolytes, Dye Manufacturing End User Industry: Pharmaceutical Companies, Chemical Manufacturers, Electronics Fabricators, Textile Producers, Agrochemical Firms Packaging Type: Drums, Bulk Containers, Bottles, Intermediate Bulk Containers, Tanks |
| Companies Covered | Iofina plc, Nippoh Chemicals Co. Ltd., Ajay Europe SARL, GHW International, ITW Reagents, Deepwater Chemicals Inc., Merck KGaA, Infinium Pharmachem Pvt. Ltd., GODO SHIGEN Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydroiodic Acid (Hydriodic Acid) Market Shifts & Advancements
Continuous processing technologies and purity verification methods are restructuring how hydriodic acid is manufactured, tested, and qualified for downstream battery and pharmaceutical applications.
Membrane-based iodine recovery systems are migrating from batch redox production methods toward continuous-flow architectures. Battery electrolyte manufacturers in South Korea and China are adopting these systems at pilot scale. The shift is compressing capital intensity per ton while tightening impurity profiles beyond legacy specification limits.
ECHA's REACH authorization list expansion is forcing reformulation of hydriodic acid derivatives containing residual phosphorus-based reducing agents. European pharmaceutical and electronics chemical distributors are requalifying supply chains around halogen-free reduction pathways. Reagent-grade producers with pre-certified alternative synthesis routes capture displaced volume from non-compliant competitors.
Automotive OEMs are unbundling electrolyte component certification from cell manufacturer qualification, creating direct procurement relationships with hydriodic acid suppliers. Tier-one battery material distributors in Germany and Japan are losing intermediation margin as OEM technical teams conduct on-site audits of acid purification operations. This channel compression is most visible in solid-state battery pilot lines where traceability requirements exceed standard commercial specifications.
Global Hydroiodic Acid (Hydriodic Acid) Market Segmentation
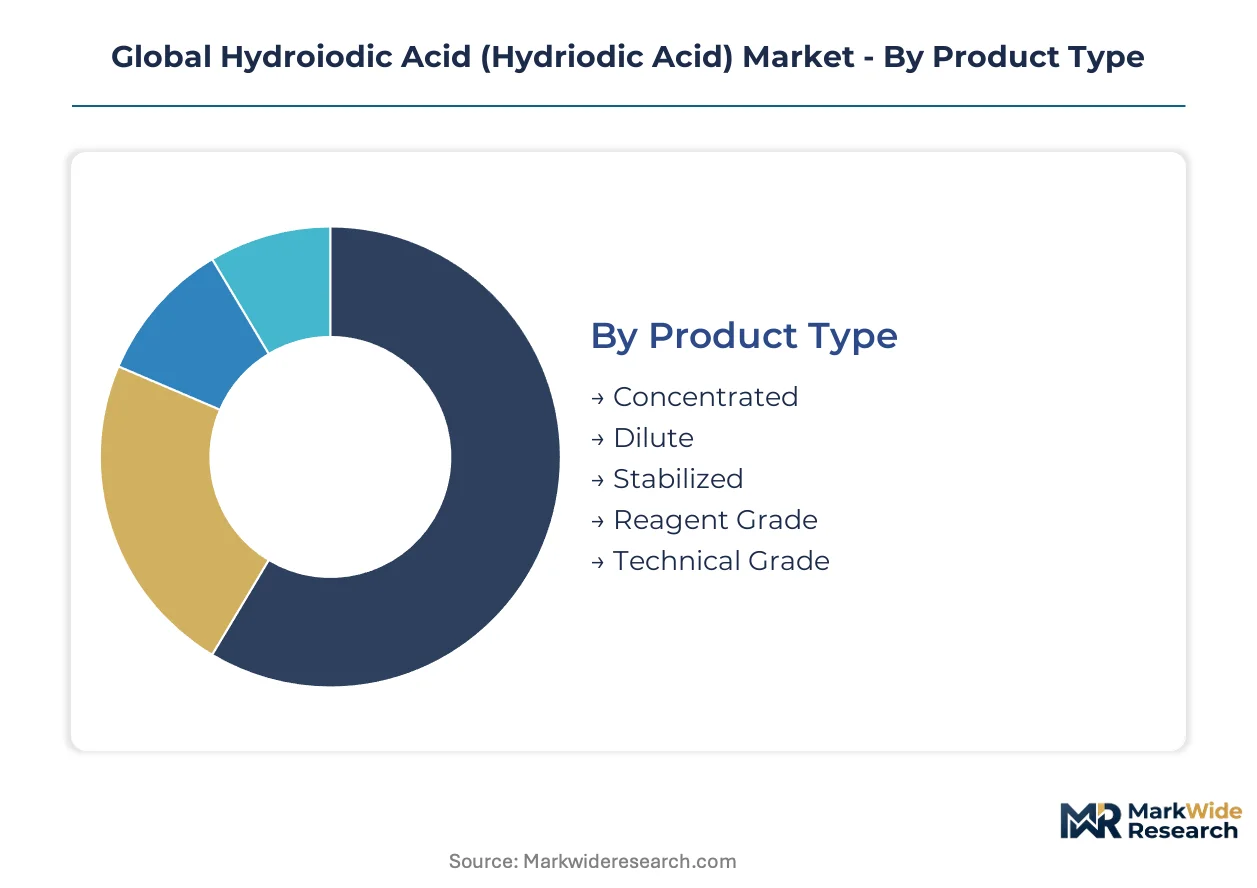
Hydroiodic acid specifications diverge sharply across end-use requirements, with battery electrolyte manufacturers demanding impurity profiles below pharmaceutical thresholds. Segmentation reveals how purity grades and packaging formats partition margin pools and supplier qualification barriers.
Product Type:
Cost tier differentiation separates captive pharmaceutical producers from merchant market suppliers serving fragmented chemical reduction applications.
- Concentrated:Formulations at 47-57% by weight deliver maximum reducing equivalents per unit volume. Electronics fabricators in South Korea and China are pulling concentrated grades for battery electrolyte precursor manufacturing where stoichiometric efficiency governs unit economics.
- Reagent Grade:Batch-certified purity with full traceability documentation commands premium positioning. Pharmaceutical synthesis applications in Germany and Switzerland require this grade for iodine-containing active ingredient intermediates under EMA and Swissmedic oversight.
- Dilute:Lower concentration variants reduce handling hazards for small-batch pharmaceutical operations. CDSCO-registered Indian generic manufacturers specify dilute grades for cost-sensitive intermediate production.
- Stabilized:Additive-inhibited formulations extend shelf life for distributors serving remote chemical reduction facilities. Mining reagent applications in Chile and Australia specify stabilized grades for extended supply chain transits.
- Technical Grade:Standard commercial purity serves bulk chemical reduction where traceability is secondary to cost minimization. Textile dye manufacturers in Turkey and Bangladesh consume technical grades for iodine-based colorant synthesis.
Concentrated holds installed capacity. Reagent Grade is rotating up the share rankings.
Application:
Application mix determines supplier certification depth, with automotive OEM electrolyte qualification now exceeding pharmaceutical batch documentation requirements.
- Battery Electrolytes:Hydriodic acid derivatives stabilize lithium-metal interfaces in sulfide-based solid-state formulations. Chinese cell manufacturers are scaling procurement volumes ahead of European automotive OEM qualification timelines.
- Pharmaceutical Synthesis:Iodine source for corticosteroid and thyroid hormone intermediates requiring batch-level impurity profiling. FDA and EMA inspection protocols mandate dedicated manufacturing lines for this application.
- Chemical Reduction:Stoichiometric reducing agent for nitroaromatic and carbonyl compounds across fine chemical manufacturing. German and Japanese specialty chemical houses specify high-purity concentrated grades for pharmaceutical precursor synthesis.
- Catalyst:Acidic promoter for esterification and polymerization reactions in industrial chemical processes. Indian and Thai petrochemical operators utilize hydriodic acid catalysts for biodiesel and synthetic rubber production.
- Dye Manufacturing:Iodine incorporation into vat and reactive dye chromophores. Turkish and Pakistani textile chemical producers consume technical grades for denim and wool dye formulations.
Pharmaceutical Synthesis retains qualification infrastructure. Battery Electrolytes is gaining share fastest.
End User Industry:
Customer type concentration in Chinese battery supply chains is compressing distributor margins and forcing direct supplier-OEM technical relationships.
- Electronics Fabricators:Lithium-ion and solid-state battery manufacturers in China, South Korea, and Japan constitute the demand expansion frontier. These buyers specify sub-ppm metallic impurity limits exceeding reagent-grade pharmaceutical standards.
- Pharmaceutical Companies:Multinational drug manufacturers and Indian generic houses drive reagent-grade volume with batch certification requirements. Swiss and German operations anchor this segment under stringent EMA and Swissmedic GMP frameworks.
- Chemical Manufacturers:Fine chemical and agrochemical producers consume technical and concentrated grades for reduction and iodination processes. Brazilian and Argentine operations source through regional distributors under ANVISA chemical substance regulations.
- Textile Producers:Dye and finishing chemical manufacturers in Turkey, India, and Bangladesh specify technical-grade volumes for colorant synthesis. These buyers prioritize cost positioning over traceability documentation.
- Agrochemical Firms:Iodine-containing biocide and fertilizer additive manufacturers in Israel and the United States utilize stabilized grades for agricultural chemical formulations under EPA and national pesticide regulator oversight.
Electronics Fabricators holds capacity expansion. Pharmaceutical Companies is defending share through certification barriers.
Packaging Type:
Packaging configuration tracks shipment scale and hazard classification, with bulk formats concentrating in integrated battery material campuses.
- Bulk Containers:ISO tank and flexitank deliveries serve high-volume battery electrolyte manufacturers with dedicated unloading infrastructure. Chinese and South Korean cell material campuses specify bulk to minimize per-unit handling costs.
- Drums:Standard 200-liter steel drums dominate pharmaceutical and fine chemical procurement where lot segregation matters. European and North American distributors maintain drum-based stocking programs for mid-scale chemical reduction customers.
- Intermediate Bulk Containers:1000-liter IBC totes bridge drum and bulk economics for regional chemical manufacturers. Indian and Southeast Asian specialty chemical houses specify IBC formats for multi-batch pharmaceutical precursor campaigns.
- Bottles:Laboratory and pilot-scale packaging serves analytical reagent and R&D applications. Reagent-grade suppliers in Germany and the United States bottle certified lots for global laboratory distribution networks.
- Tanks:Dedicated tanker deliveries support captive consumption at vertically integrated iodine derivative producers. Chilean and Japanese operations with on-site acid recovery systems utilize tank-based internal transfers.
Bulk Containers holds capacity concentration. Intermediate Bulk Containers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics fabricators in China command the dominant share of high-purity hydriodic acid procurement, while pharmaceutical manufacturers in Germany and Switzerland anchor reagent-grade demand through stringent certification requirements.
China
Battery electrolyte manufacturers in Ningde and Shenzhen are scaling hydriodic acid consumption for solid-state cell production. The Ministry of Ecology and Environment enforces wastewater discharge standards that reshape on-site acid recovery economics at domestic plants. Yangtze River Delta fabricators concentrate the nation's lithium-ion material supply chain.
Germany
EMA-registered pharmaceutical synthesis operations in Ludwigshafen and Frankfurt drive reagent-grade volume for iodine-containing active ingredients. ECHA REACH authorization requirements filter non-compliant producers from continental supply chains. Bavarian chemical clusters specialize in fine chemical reduction processes.
United States
EPA hazardous substance regulations govern transport thresholds and spill reporting protocols for cross-border hydriodic acid shipments. Deepwater Chemicals and regional distributors serve Texas and Louisiana petrochemical corridors. Gulf Coast specialty chemical houses consume technical grades for catalyst applications.
Japan
PMDA oversight and METI industrial standards shape pharmaceutical and electronics chemical qualification timelines. Osaka-based iodine derivative producers leverage captive brine extraction for feedstock cost control. Kansai-region fabricators supply South Korean battery material manufacturers.
India
CDSCO streamlined API registration creates entry pathways for reagent-grade suppliers serving Gujarat and Maharashtra generic drug clusters. Domestic pharmaceutical manufacturers expand hydriodic acid use in corticosteroid intermediate production. Hyderabad and Ahmedabad house concentrated iodination chemistry capabilities.
Global Hydroiodic Acid (Hydriodic Acid) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered certification levels. The market structure consolidates around qualified registrants in Europe and vertically integrated feedstock controllers in Asia. Three archetypes dominate: brine-to-derivative integrators, reagent-grade certification specialists, and regional technical-grade merchants. Competitive moves center on automotive OEM qualification timelines and REACH-compliant synthesis route patents.
Among UK-based iodine specialists, Iofina plc occupies a position representing captive brine extraction advantages. Japanese chemical houses including Nippoh Chemicals Co. Ltd. and GODO SHIGEN Co. Ltd. exemplify technical-grade specialization across Asian pharmaceutical corridors. German life science conglomerate Merck KGaA anchors the premium reagent-grade tier through analytical laboratory certification networks. These three archetypes illustrate how feedstock control, geographic specialization, and certification depth partition competitive positioning.
| Leading Market Players |
|---|
| Iofina plc |
| Nippoh Chemicals Co. Ltd. |
| Ajay Europe SARL |
| GHW International |
| ITW Reagents |
| Deepwater Chemicals Inc. |
| Merck KGaA |
| Infinium Pharmachem Pvt. Ltd. |
| GODO SHIGEN Co. Ltd. |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta battery material cluster concentrates high-purity hydriodic acid capacity, transmitting pricing power downstream to reagent-grade suppliers serving pharmaceutical corridors in Germany and Switzerland. Iodine feedstock volatility from Chilean and Japanese brine operations feeds directly into contract renegotiation cycles, compressing margins for non-integrated merchants while captive producers maintain cost stability.
Pricing Analysis
Cost-plus contracts indexed to iodine concentrate spot benchmarks dominate long-term supply agreements between integrated producers and battery electrolyte manufacturers. Three-tier pricing structure across reagent-grade, concentrated, and technical tiers separates pharmaceutical batch certification premiums from bulk chemical reduction economics. Pricing pressure stems from phosphorus-based reducing agent substitution in fine chemical synthesis, eroding technical-grade volume. CDSCO-registered Indian generic manufacturers exhibit highest price sensitivity, while German EMA-certified operations absorb premiums for traceability documentation.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Chinese battery material distributors are restructuring working capital requirements for mid-scale acid producers. Feedstock supply concentrates in Chile, Japan, and the United States through brine extraction and caliche ore processing. Manufacturing capacity draws from China, South Korea, and Germany for high-purity grades. Single-source vulnerability runs through Chilean iodine concentrate disruptions. Distribution runs through direct procurement relationships between automotive OEM technical teams and acid purification operations, bypassing traditional tier-one distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service and ongoing regulatory compliance support represent faster-expanding revenue layers than commodity acid volume, as automotive OEMs and pharmaceutical manufacturers outsource qualification documentation and batch validation to specialized providers.
For Market Incumbents: Insulate reagent-grade margin pools through REACH-compliant alternative synthesis route patents that preempt ECHA authorization list expansions. Deepen captive brine extraction or long-term iodine concentrate offtakes to neutralize feedstock volatility threats from Chilean supply disruptions. Prioritize automotive OEM direct qualification timelines ahead of solid-state battery chemistry convergence.
For New Entrants and Emerging Players: Pursue CDSCO-registered Indian pharmaceutical corridors where streamlined API registration creates entry pathways against entrenched European certification specialists. Target asset-light equipment leasing arrangements for mid-scale concentrated-grade capacity serving Southeast Asian chemical reduction markets. Lead with wastewater recovery technology packages that address China's MEE discharge standards for older manufacturing facilities.
For Investors and Strategic Acquirers: Long-term, this sits as a feedstock-control play because iodine brine extraction rights and captive derivative production determine sustainable cost positioning across battery and pharmaceutical demand cycles. Acquisition targets cluster around vertically integrated specialists with pre-certified REACH alternative synthesis routes and established automotive OEM technical relationships. Watch for solid-state battery pilot line qualification failures as the signal indicating chemistry transition delays or accelerated incumbent consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Iodine Feedstock | Captive brine extraction in Chile and Japan neutralizes concentrate price volatility transmitted to acid production costs. |
| REACH-Compliant Synthesis Route Patenting | Pre-certified halogen-free reduction pathways capture volume displaced from phosphorus-based competitors under ECHA expansion. |
| Automotive OEM Direct Qualification | Bypassing tier-one distributors secures premium positioning in solid-state battery electrolyte supply chains under OEM technical audits. |
| Asset-Light Infrastructure Leasing | Specialty chemical equipment arrangements reduce capital barriers for mid-scale producers entering concentrated-grade markets. |
| Wastewater Recovery System Deployment | On-site acid recovery investments align with China's MEE discharge standards while altering plant-level unit economics. |
Research Methodology
A spread of perspectives from plant managers at iodine derivative facilities, procurement leads at battery electrolyte manufacturers, distribution channel partners in European pharmaceutical corridors, and technical R&D directors at specialty chemical houses converged on the working assumptions. Primary interview insights triangulated against customs and trade data, Cefic and ACC industry reports, SEC 10-K filings from listed chemical producers, and ECHA REACH registration databases. Bottom-up capacity and consumption estimates reconciled with top-down market sizing across grade tiers and end-use applications.
Demand-supply-balance modeling anchored projections across the analysis window, with segmentation across purity grades, packaging formats, end-use industries, and regional production hubs. CAGRs derived from weighted average of historical trajectory and forward-looking capacity announcements, adjusted for automotive OEM qualification timeline risks and pharmaceutical synthesis batch certification cycle lengths. Forecast inputs incorporated iodine concentrate supply elasticity, solid-state battery chemistry adoption curves, and regulatory authorization pathway timelines.
Sensitivities concentrate around Chilean caliche ore production disruptions, ECHA REACH authorization list expansion timing, and automotive OEM electrolyte component unbundling acceleration. Forecasts reflect documented assumptions on feedstock supply continuity, regulatory compliance cost trajectories, and battery chemistry transition pathways. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
North America Caustic Potash Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Bulk Liquid Containers Market
Bulk Chemicals
Global Sodium Sulfate Market
Bulk Chemicals
Sodium Thiosulphate Market
Bulk Chemicals
Global Acrolein Market
Bulk Chemicals
Tin Fluoborate Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
Methyl Gluceth-10 Market
Bulk Chemicals
China Starch and Starch Derivatives Market