
 Global Lithium Derivatives Market | 2026-2036
Global Lithium Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lithium Derivatives Market Foresight
ISO 14040 lifecycle assessment certification is unwinding competitive access for junior lithium derivative suppliers unable to document Scope 3 emissions. Albemarle Corporation leverages its Kings Mountain, North Carolina, processing complex to sustain domestic battery supply chain qualification. SQM anchors its cost position through direct shipping ore integration with Chilean caliche assets. Jiangxi Ganfeng Lithium competes via captive spodumene offtake from Mount Marion and Pilbara operations.
Lithium derivatives encompass refined chemical compounds derived from brine evaporation or hard-rock ore processing, with battery-grade lithium hydroxide requiring sub-20 ppm sodium content and specific particle morphology for cathode precursor integration. These materials serve as irreplaceable inputs in high-nickel cathode manufacturing, ceramics fluxing, and pharmaceutical mood stabilizer synthesis. Lithium hydroxide commands premium positioning as electric vehicle manufacturers shift toward nickel-rich NMC and NCA cathode chemistries demanding lower sintering temperatures. Lithium carbonate retains volume dominance in ceramics and glass production where technical specifications tolerate broader impurity bands. Battery Manufacturing as an application segment concentrates margin pools at the high-purity end, while Pharmaceuticals maintains stable offtake through long-term contractual structures.
The EPA oversees hazardous waste classification for lithium extraction tailings under RCRASubtitle C, while REACH mandates full substance registration for EU-imported lithium compounds above one-tonne annual thresholds. China's MEE enforces wastewater discharge limits on Qinghai and Sichuan processing zones, redirecting capacity expansion toward compliant industrial parks. Stakeholders must monitor evolving carbon border adjustment mechanisms and cathode chemistry pivots that could abruptly regrade lithium hydroxide premiums against carbonate alternatives.
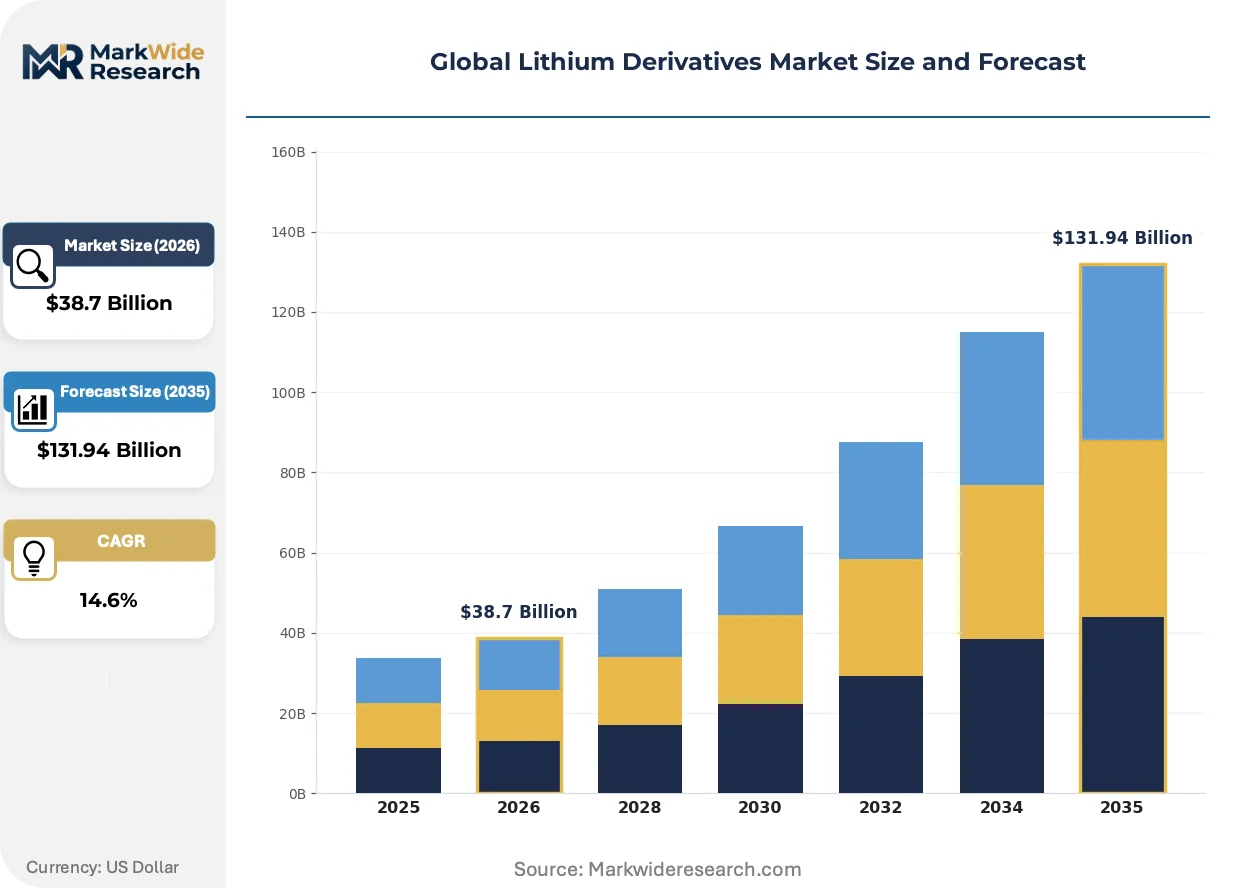
Market Dynamics
High-nickel cathode chemistry migration is compressing sintering temperature requirements and elevating battery-grade lithium hydroxide premiums above carbonate alternatives. This technical specification shift concentrates margin capture among processors with sub-20 ppm sodium purification capabilities.
Growth Catalysts
- EU Battery Regulation carbon disclosure mandates:OEMs now require documented Scope 3 emissions from cathode precursor suppliers, accelerating qualification of certified processing assets.
- Direct shipping ore integration:Hard-rock spodumene operations in Western Australia are shortening concentrate-to-hydroxide conversion cycles through captive mine-to-plant logistics.
- Pharmaceutical mood stabilizer offtake:Long-term API contracts with institutional buyers provide baseload demand insulation against battery-grade price volatility.
Market Restraints
- Atacama brine concentration risk:Chilean salar water rights disputes threaten expansion timelines for carbonate-dominant producers serving ceramics and glass markets.
- Spodumene concentrate cost volatility:Australian hard-rock miners face diesel and explosives input inflation that transmits directly to hydroxide conversion economics.
- REACH registration friction:EU substance registration thresholds above one tonne annually delay market entry for experimental derivative grades from junior processors.
Strategic Opportunities
- North American battery supply chain localization:The US Inflation Reduction Act domestic content credits incentivize hydroxide processing investments in the Southeast industrial corridor.
- Solid-state electrolyte precursor demand:Sulfide and oxide solid-state battery chemistries require ultra-dry lithium derivatives with moisture specifications below 100 ppm.
- Direct-to-cathode-plant distribution:Bypassing merchant chemical traders through dedicated pipeline or rail spurs to NMC precursor facilities captures 8-12% logistics cost savings.
Industry Challenges
- ISO 14040 lifecycle assessment certification timelines:Documenting Scope 3 emissions across multi-tier brine evaporation and ore concentration supply chains extends qualification periods.
- High-purity crystallization capex intensity:Battery-grade hydroxide production requires continuous stirred-tank reactors and membrane filtration trains with 4-6 year depreciation horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lithium Derivatives Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $131.94 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Carbonate, Lithium Hydroxide, Lithium Chloride, Lithium Fluoride, Lithium Bromide Application: Battery Manufacturing, Ceramics, Glass Production, Lubricants, Pharmaceuticals End User Industry: Electric Vehicle Manufacturers, Electronics Producers, Chemical Manufacturers, Grease Producers Distribution Channel: Direct Sales, Distributors, Online Platforms, Chemical Traders |
| Companies Covered | Albemarle Corporation, SQM, Jiangxi Ganfeng Lithium, Tianqi Lithium, Arcadium Lithium, FMC Corporation, SICHUAN BRIVO LITHIUM MATERIALS CO., LTD., Livent Corporation, Orocobre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lithium Derivatives Market Shifts & Advancements
Direct lithium extraction technologies are disrupting conventional brine evaporation economics by compressing production cycles from 18 months to under 30 days. This process intensification is attracting capital toward geothermal brine and oilfield wastewater feedstocks previously uneconomical.
Membrane-based selective adsorption is displacing traditional solar evaporation ponds in Chilean and Argentine salar operations. Albemarle and SQM are piloting these systems at commercial scale, targeting 90% water consumption reductions. The technology is displacing acreage-intensive evaporation infrastructure and enabling expansion in water-stressed jurisdictions.
China's GB standards for battery-grade lithium hydroxide now mandate particle morphology specifications that exceed legacy carbonate purity frameworks. MIIT enforcement of these technical parameters is forcing export-oriented processors to retrofit crystallization circuits. Domestic cathode manufacturers in Jiangsu and Fujian provinces are the most affected, with qualification failures blocking supply to NMC 811 precursor lines.
Automotive OEMs are consolidating cathode precursor procurement through direct offtake agreements with lithium derivative processors, bypassing traditional merchant chemical distributors. BMW, Tesla, and Volkswagen have established 3-5 year volume commitments with named suppliers. This channel compression is most visible in European and North American markets where supply security concerns override spot price optimization.
Global Lithium Derivatives Market Segmentation
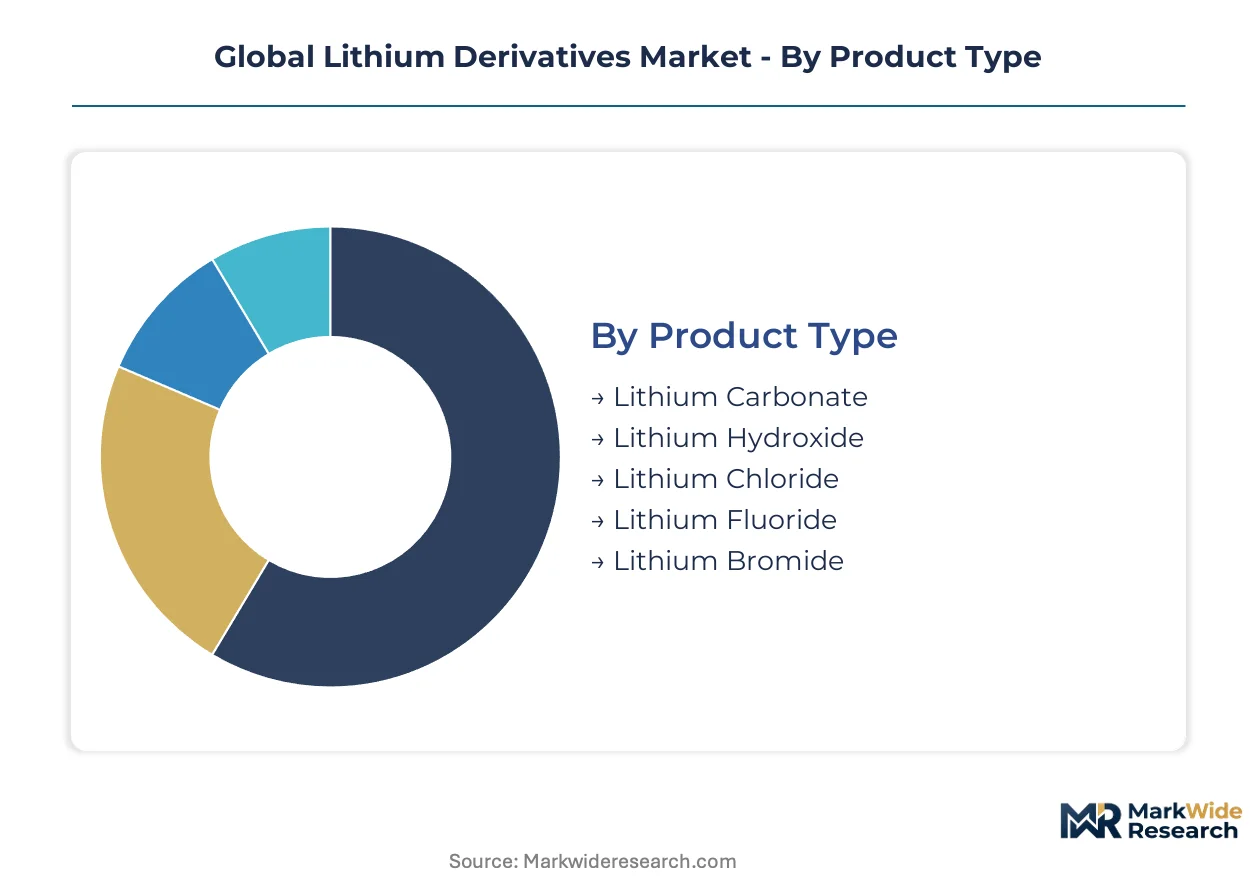
Lithium derivative procurement channels bifurcate between long-term direct offtake and spot merchant markets. Cathode precursor manufacturers dominate volume flows through dedicated supply agreements, while ceramics and pharmaceutical buyers fragment across distributor networks.
Product Type:
Channel concentration varies sharply by derivative chemistry. Battery-grade hydroxide moves predominantly through direct sales to cathode plants, while carbonate and specialty salts retain heavier distributor penetration.
- Lithium Hydroxide:Sub-20 ppm sodium battery-grade specifications command premium positioning for NMC and NCA cathode integration. Demand concentrates in Qinghai and Sichuan processing zones serving domestic Chinese cathode manufacturers, with qualification failures blocking supply to NMC 811 precursor lines under enforced GB standards.
- Lithium Carbonate:Broader impurity tolerance suits ceramics fluxing and glass production where technical specifications permit wider sodium bands. Volume concentrates in Chile's Atacama operations, though water rights disputes threaten expansion timelines for carbonate-dominant producers.
- Lithium Chloride:Air conditioning desiccant and industrial drying applications sustain steady offtake through chemical trader channels.
- Lithium Fluoride:Aluminum smelting flux and optical glass manufacturing drive demand from metallurgical processors.
- Lithium Bromide:Absorption chiller systems in commercial HVAC sustain niche demand through specialized refrigerant distributors.
By volume, Lithium Carbonate leads. By growth pace, Lithium Hydroxide is climbing the fastest.
Application:
Margin tiering separates battery-grade qualification from industrial commodity offtake. Pharmaceutical and battery applications capture value through certification barriers, while ceramics and lubricants compete on cost efficiency.
- Battery Manufacturing:High-nickel cathode chemistry migration compresses sintering temperature requirements and elevates hydroxide premiums. OEMs now require documented Scope 3 emissions from cathode precursor suppliers, accelerating qualification of certified processing assets.
- Pharmaceuticals:Long-term API contracts with institutional buyers provide baseload demand insulation against battery-grade price volatility. Mood stabilizer synthesis maintains stable offtake through contractual structures that span regulatory approval cycles.
- Ceramics:Fluxing applications tolerate broader impurity bands, sustaining carbonate volume through price-sensitive industrial procurement.
- Glass Production:Thermal expansion control in specialty glass manufacturing drives consistent lithium derivative consumption.
- Lubricants:Grease thickening applications compete on formulation cost against alternative metal soaps.
Battery Manufacturing captures the steepest expansion trajectory. Pharmaceuticals maintains the most stable contractual pricing.
End User Industry:
Customer scale determines procurement modality. Automotive OEMs consolidate through direct offtake agreements, while fragmented grease and electronics producers rely on distributor intermediation.
- Electric Vehicle Manufacturers:BMW, Tesla, and Volkswagen have established multi-year volume commitments with named lithium derivative suppliers. This channel compression bypasses traditional merchant chemical distributors in European and North American markets where supply security concerns override spot price optimization.
- Electronics Producers:Portable device battery demand concentrates in Jiangsu and Fujian province cathode supply chains, with qualification requirements blocking non-compliant processors.
- Chemical Manufacturers:Industrial derivative consumers fragment procurement across distributor networks without volume consolidation leverage.
- Grease Producers:Lubricant formulators source through regional chemical traders with limited backward integration into lithium supply.
Electric Vehicle Manufacturers dominate volume absorption. Electronics Producers shows the most rapid demand acceleration.
Distribution Channel:
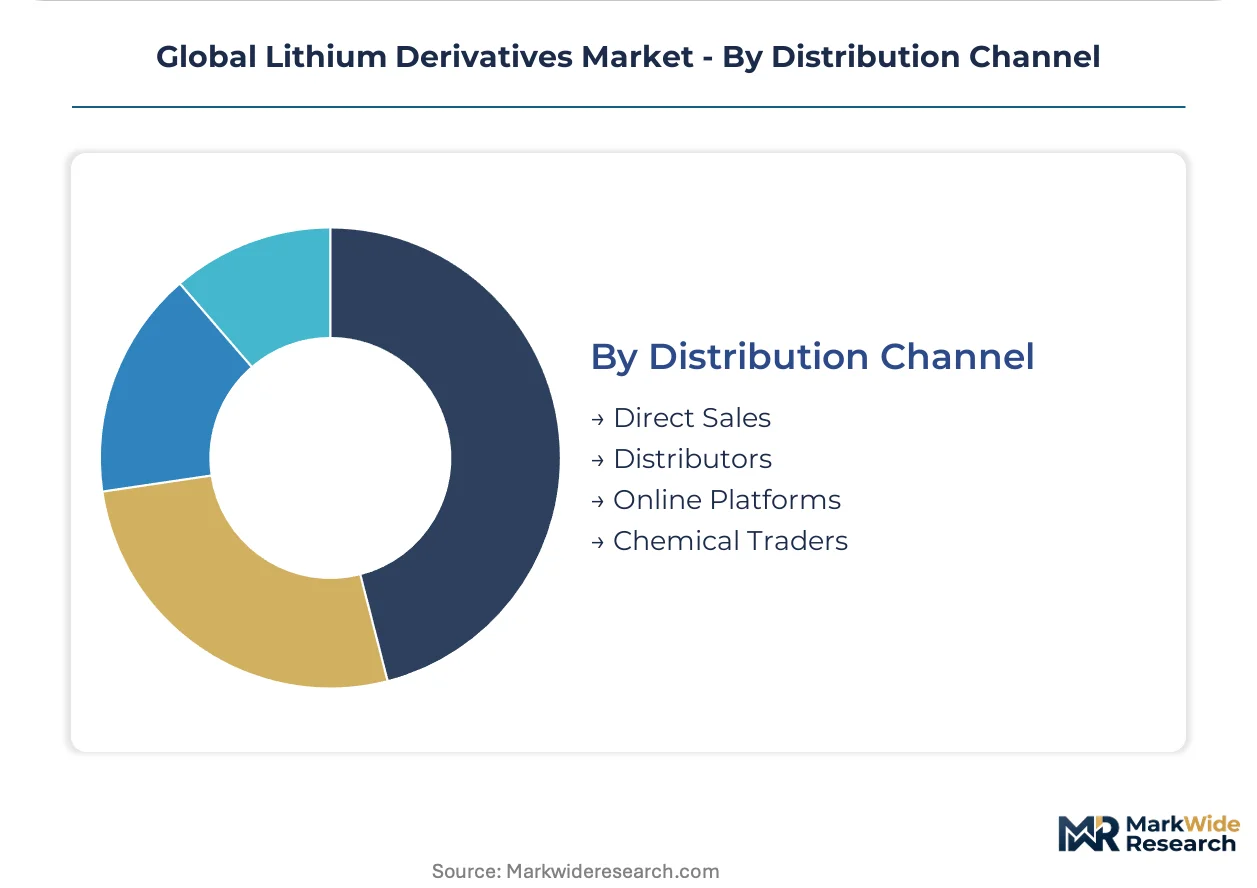
Channel structure reflects customer concentration and certification requirements. Direct sales capture battery-grade volumes, while spot markets serve price-sensitive industrial buyers.
- Direct Sales:Automotive OEMs and cathode precursor manufacturers consolidate procurement through 3-5 year offtake agreements with named suppliers. Dedicated pipeline or rail spurs to NMC precursor facilities capture logistics cost savings unavailable through merchant channels.
- Distributors:Regional chemical distributors serve fragmented ceramics, glass, and lubricant customers without qualification-intensive battery-grade requirements.
- Chemical Traders:Spot market intermediation persists for carbonate grades where specification tolerance permits supplier switching.
- Online Platforms:Specialty salt procurement for research and small-batch industrial applications migrates toward digital channels with limited current volume.
Direct Sales commands the largest revenue share. Distributors retain the broadest customer reach across industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act domestic content credits are accelerating hydroxide processing investments in the Southeast industrial corridor, while China's MIIT enforces GB standards that block non-compliant processors from NMC 811 precursor supply chains.
United States
Automotive OEMs including Tesla and BMW have established multi-year offtake agreements with named suppliers to secure battery-grade lithium hydroxide for domestic cathode production. The IRA's domestic content credits incentivize processing investments in North Carolina and the broader Southeast. Albemarle Corporation leverages its Kings Mountain processing complex to sustain domestic battery supply chain qualification for electric vehicle manufacturers.
China
Domestic cathode manufacturers in Jiangsu and Fujian provinces drive concentrated demand for battery-grade lithium hydroxide with sub-20 ppm sodium specifications. MIIT enforcement of GB standards for particle morphology forces export-oriented processors to retrofit crystallization circuits. Qinghai and Sichuan processing zones face MEE wastewater discharge limits that redirect capacity expansion toward compliant industrial parks.
Chile
Atacama salt flat operations anchor carbonate-dominant production serving ceramics and glass markets with broader impurity tolerance. Water rights disputes threaten expansion timelines for brine evaporation infrastructure. SQM anchors its cost position through direct shipping ore integration with Chilean caliche assets.
Australia
Hard-rock spodumene districts in Western Australia shorten concentrate-to-hydroxide conversion cycles through captive mine-to-plant logistics. Diesel and explosives input inflation transmits directly to hydroxide conversion economics for concentrate producers. Pilbara operations supply captive offtake to Chinese processors including Jiangxi Ganfeng Lithium.
Germany
Automotive OEMs including Volkswagen consolidate cathode precursor procurement through direct offtake agreements that bypass traditional merchant chemical distributors. REACH mandates full substance registration for EU-imported lithium compounds above one-tonne annual thresholds. The EU Battery Regulation carbon disclosure requirements accelerate qualification of certified processing assets serving European electric vehicle production.
Global Lithium Derivatives Market Competitive Landscape
Player mix skews toward integrated brine operators and hard-rock concentrate processors with captive mine assets. The structure concentrates margin capture among processors with sub-20 ppm sodium purification capabilities and ISO 14040 lifecycle assessment certification. Two strategic archetypes dominate: integrated salar/brine operators with evaporation infrastructure, and hard-rock spodumene processors with Australian mine-to-plant logistics. Competitive moves center on capacity expansion in compliant industrial parks and strategic partnerships with automotive OEMs for direct offtake agreements.
Among integrated brine operators, Albemarle Corporation and SQM exemplify the archetype of salar-based processors with South American evaporation assets. Jiangxi Ganfeng Lithium occupies a position within the hard-rock processor tier, representing Chinese operators with captive spodumene offtake from Australian concentrate operations. These three companies anchor the competitive structure through their respective positions in brine evaporation, direct shipping ore integration, and hard-rock concentrate supply chains.
| Leading Market Players |
|---|
| Albemarle Corporation |
| SQM |
| Jiangxi Ganfeng Lithium |
| Tianqi Lithium |
| Arcadium Lithium |
| FMC Corporation |
| SICHUAN BRIVO LITHIUM MATERIALS CO., LTD. |
| Livent Corporation |
| Orocobre |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with take-or-pay clauses lock in supply access and price visibility for cathode precursor manufacturers sourcing battery-grade lithium hydroxide. These structures insulate qualified processors from spot market volatility while exposing non-compliant juniors to margin compression under EU Battery Regulation carbon disclosure mandates.
Pricing Analysis
Cost-plus contracts indexed to spodumene concentrate benchmarks dominate battery-grade hydroxide procurement. Three-tier pricing structure across battery-grade, technical-grade, and industrial-grade levels separates sub-20 ppm sodium certification from broader impurity tolerance. Cost compression in technical-grade carbonate is intensifying because Australian diesel and explosives inflation transmits directly to concentrate conversion economics. Ceramics and glass buyers exhibit highest price sensitivity, while automotive OEMs prioritize supply security over spot optimization.
Supply Chain Analysis
Chile and Australia anchor lithium derivative supply through contrasting extraction modalities. Chilean Atacama brine operations draw from solar evaporation infrastructure with 18-month production cycles. Australian hard-rock spodumene districts rest on diesel-intensive mining with captive mine-to-plant logistics. Single-source vulnerability concentrates in Chilean water rights disputes threatening carbonate expansion timelines. Distribution runs through direct pipeline and rail spurs to NMC precursor facilities, bypassing merchant chemical traders for qualified battery-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct lithium extraction technologies are compressing production cycles from 18 months to under 30 days, disrupting incumbent brine economics and regrading asset valuations across the supply chain.
For Market Incumbents: Consolidate qualification advantages by accelerating ISO 14040 certification coverage across Scope 3 emissions documentation. Lock in captive spodumene offtake from Pilbara operations to defend processing margins against concentrate cost volatility. Expand capacity in compliant Southeast US industrial parks to capture IRA domestic content credits before qualification windows narrow. For New Entrants and Emerging Players: Solid-state electrolyte precursor demand represents an underserved service layer where moisture specifications below 100 ppm exceed incumbent crystallization capabilities. Target geothermal brine and oilfield wastewater feedstocks previously uneconomical under conventional evaporation economics. Partner with automotive OEMs on 3-5 year direct offtake agreements to bypass merchant distributor qualification barriers. For Investors and Strategic Acquirers: Hard-rock processors with Australian mine-to-plant logistics and sub-20 ppm sodium purification capabilities offer acquisition exposure to battery-grade margin pools. Monitor MIIT enforcement of GB particle morphology standards as an inflection indicator for retrofit capital deployment cycles across Qinghai and Sichuan processing zones.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Lithium Extraction Scale-Up | Membrane-based selective adsorption at Albemarle and SQM pilots targets 90% water consumption reductions in Atacama operations. |
| Backward Integration into Spodumene Concentrate | Jiangxi Ganfeng Lithium's captive offtake from Mount Marion insulates hydroxide conversion economics from Australian diesel inflation. |
| ISO 14040 Certification Investment | Lifecycle assessment documentation unlocks EU Battery Regulation qualification for cathode precursor supply to BMW and Volkswagen. |
| North American Processing Capacity Expansion | IRA domestic content credits accelerate hydroxide investments in North Carolina's Kings Mountain industrial corridor. |
| Solid-State Electrolyte Precursor Development | Ultra-dry lithium derivatives with sub-100 ppm moisture specifications address sulfide and oxide solid-state battery chemistry requirements. |
Research Methodology
A spread of perspectives from cathode precursor procurement managers, lithium processing plant engineers, automotive OEM supply chain directors, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from SEC 10-K filings, customs and trade databases, Chilean water rights tribunal records, and MIIT GB standard enforcement notices. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume assumptions across the analysis window.
Segmentation dimensions modeled include derivative chemistry grade, end-use application intensity, cathode chemistry migration pathway, and regional regulatory compliance cluster. CAGRs were derived through intensity-factor scaling against electric vehicle production forecasts and cathode chemistry adoption curves. Forecast inputs incorporated spodumene concentrate cost pass-through coefficients and brine evaporation yield assumptions.
Material uncertainties — water rights adjudication outcomes in Chile, REACH registration timeline delays for junior processors, and abrupt cathode chemistry pivots away from high-nickel formulations — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and OEM qualification persistence. Recalibration cycles align with material shifts in EU carbon border adjustment mechanism implementation and solid-state battery commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Rubidium Bromide Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Global Internal Olefins Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Carbon Disulfide Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Diketene Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market