
 Europe Calcium Nitrate Market | 2026-2036
Europe Calcium Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Calcium Nitrate Market Foresight
A capital-intensity divergence between integrated ammonia producers and downstream blenders is reorganizing competitive tiers across the Europe calcium nitrate landscape. Yara International ASA leverages its Norwegian ammonia backbone to control feedstock costs across North Sea corridors. EuroChem Group anchors its position through captive phosphate-nitrate integration at Russian-European border facilities. Haifa Group specializes in high-purity crystalline grades for fertigation systems, competing on solubility metrics rather than volume scale.
Calcium nitrate denotes the inorganic salt Ca(NO₃)₂, typically manufactured via neutralization of nitric acid with limestone or via the Odda process yielding a double salt with ammonium nitrate, with commercial grades specifying water-soluble calcium content between 15.5% and 19% by weight and hygroscopicity below defined thresholds for storage stability. The compound serves primarily as a calcium source correcting blossom-end rot in tomatoes and peppers under protected cultivation, plus as an additive in concrete set-acceleration and wastewater denitrification. Granular formulations dominate volume throughput for broad-acre broadcasting, while liquid concentrates capture margin pools in Dutch and Spanish drip-fertigation networks where dissolution labor costs prove prohibitive. Agricultural end users represent the structural demand anchor, though water treatment applications in German municipal utilities show faster growth velocity as phosphate precipitation regulations tighten discharge standards.
The EU Fertilizing Products Regulation (2019/1009) and REACH frameworks govern cadmium limits and contaminant thresholds for nitrate fertilizers placed on European Economic Area markets, with ECHA maintaining substance evaluation protocols that directly shape formulation chemistries and import eligibility. Germany's KBA and France's ANSM exercise parallel oversight where calcium nitrate enters construction admixture or pharmaceutical supply chains, fragmenting compliance architectures across end-use boundaries. Stakeholders must monitor the interplay between EU-wide harmonization momentum and member-state enforcement heterogeneity when allocating certification investments across product registrations.
Market Dynamics
The EU Fertilizing Products Regulation is compressing formulation margins while simultaneously advantaging producers with in-house nitric acid and limestone integration, rewiring competitive tiers across the continent.
Growth Catalysts
- Precision fertigation adoption:Dutch and Spanish greenhouse operators are converting from granular broadcasting to liquid calcium nitrate concentrates, pulling volume toward solubility-optimized grades.
- REACH cadmium thresholds:ECHA substance evaluation protocols for nitrate fertilizers are disqualifying low-purity imports, creating protected demand pools for compliant European producers.
- Blossom-end rot correction:Protected cultivation of tomatoes and peppers in Almería and Murcia requires continuous calcium supplementation, locking in structural offtake.
Market Restraints
- Ammonia feedstock volatility:Natural gas price swings at TTF hubs transmit directly to nitric acid costs, eroding margin predictability for non-integrated blenders.
- Import concentration at Baltic terminals:Russian-origin ammonium nitrate-calcium nitrate double salt flows through limited port capacity, exposing buyers to single-point disruption risk.
- Concrete admixture substitution:Calcium formate and lithium-based accelerators are capturing specification share in German construction where set-time flexibility outweighs cost.
Strategic Opportunities
- Polish precision agriculture emergence:Masovian and Greater Poland voivodeships are deploying drip irrigation at scale, creating new calcium nitrate concentrate demand outside established Dutch-Spanish corridors.
- Wastewater denitrification mandate:German municipal utilities under tightened phosphate precipitation regulations are expanding calcium nitrate dosing for biological nutrient removal.
- Liquid-to-farm direct channels:Cooperative purchasing platforms in Denmark are disintermediating traditional distributor networks, capturing margin through tanker-truck direct delivery.
Industry Challenges
- Dual-use registration complexity:Producers supplying both agricultural and construction admixture grades must maintain parallel KBA and REACH dossiers, doubling compliance overhead.
- Crystallization engineering scarcity:High-purity granular production requires Odda-process expertise concentrated among retired cohorts at legacy Norwegian and Belgian plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Calcium Nitrate Market |
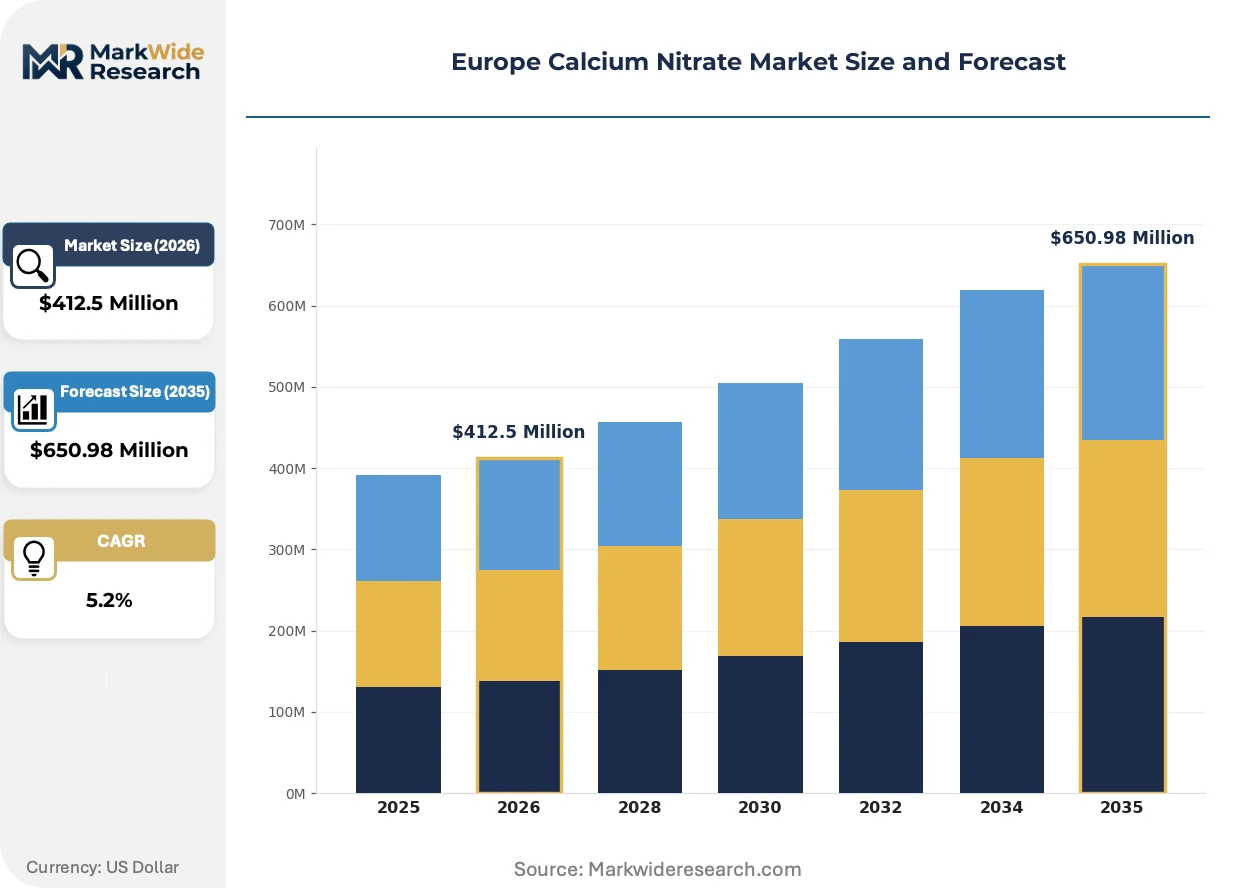
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $650.98 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powder, Prilled Application: Agriculture, Fertilizers, Water Treatment, Pharmaceuticals End User: Agricultural Companies, Chemical Manufacturers, Water Utilities, Research Institutions Distribution Channel: Direct Sales, Retail, E-commerce, Distributors |
| Companies Covered | Yara International ASA, EuroChem Group, BASF SE, OCI Nitrogen, Haifa Group, K+S AG, Agroferti, URALCHEM JSC, Van Iperen International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Calcium Nitrate Market Shifts & Advancements
Formulation chemistry and distribution logistics are diverging simultaneously, with producers forced to choose between commodity scale and specialty margin capture.
Controlled-release calcium nitrate coatings are fragmenting application protocols across protected cultivation. Polymer-encapsulated granules from BASF and Evonik development pipelines extend nutrient availability from days to weeks. Spanish cooperatives in Huelva are piloting these formulations for cherry tomato cycles, compressing labor input while commanding 40% price premiums over standard soluble grades.
REACH Annex XVII updates on nitrate contamination thresholds are forcing reformulation investments. ECHA's 2023 substance evaluation protocol for calcium nitrate salts tightened cadmium limits to 60 mg/kg, rendering several Turkish and Egyptian import streams non-compliant. German blenders are responding by sourcing limestone feedstock exclusively from Styrian quarries with certified low-heavy-metal geology.
Buyer consolidation through grower cooperatives is restructuring procurement power. In the Netherlands, ZLTO and CZAV agricultural cooperatives now contract directly with Yara's Sluiskil facility for liquid calcium nitrate, bypassing traditional agrochemical distributors. This channel compression is most advanced in North Brabant and Limburg, where glasshouse density supports dedicated tanker logistics.
Europe Calcium Nitrate Market Segmentation
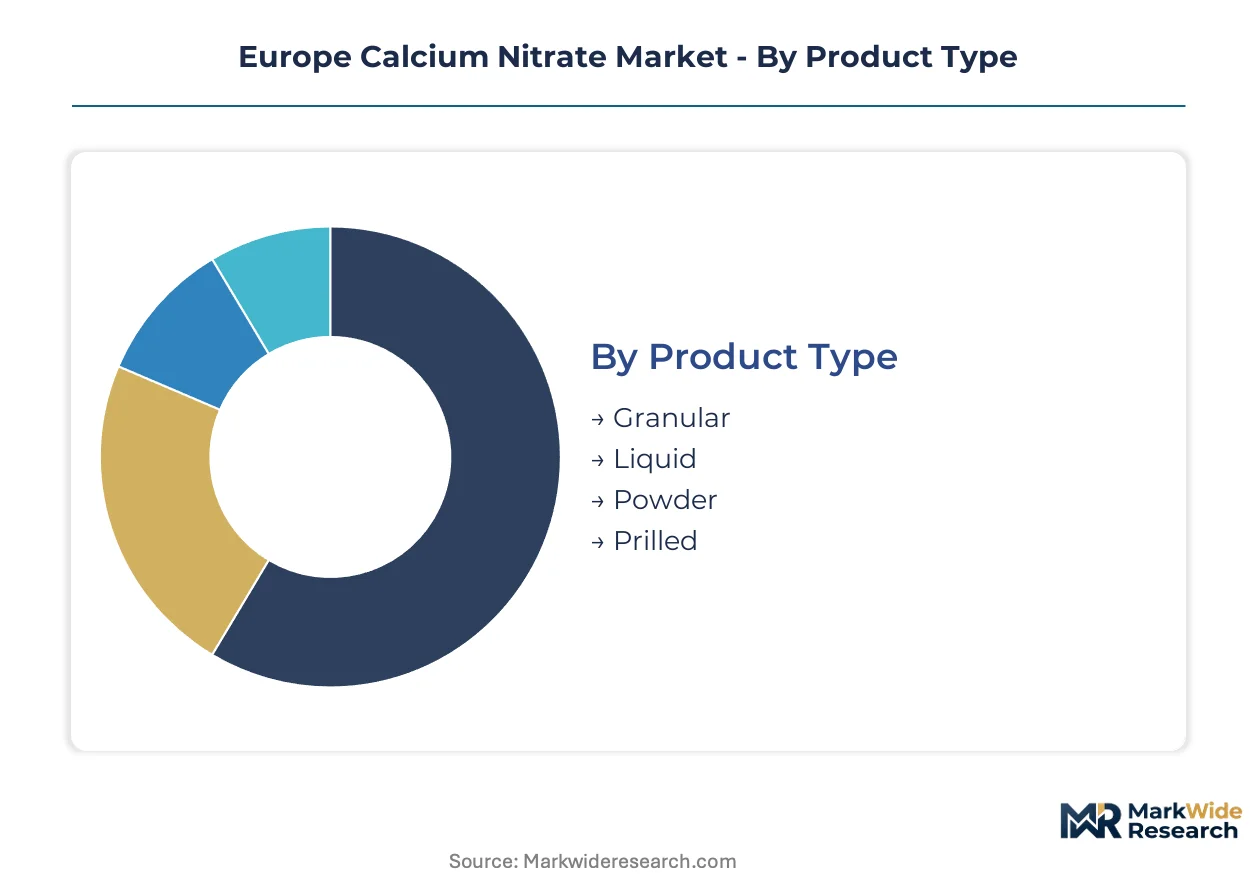
Calcium nitrate's functional versatility across agriculture, construction, and water treatment creates distinct demand profiles that reward formulation specificity. Segmentation reveals where substitution threats concentrate and where captive demand locks in structural offtake.
Product Type:
Liquid concentrates face the strongest substitution pressure from calcium chloride and calcium formate in concrete acceleration, while granular grades defend position through broadcasting economics in broad-acre farming.
- Granular:Dense, free-flowing pellets with 15.5-17% water-soluble calcium content suit mechanical spreaders in Polish and Romanian field crops. Protected cultivation in Spain's Almería province still specifies granular for base dressing before drip conversion.
- Liquid:Clear or pale yellow solutions at 8-10% calcium concentration eliminate dissolution labor in Dutch and Danish fertigation networks. Haifa Group's crystalline liquid grades command specification in high-value greenhouse tomato production.
- Powder:Fine milled particles below 2mm diameter serve pharmaceutical compounding and specialty concrete admixture blending in Germany's industrial corridor.
- Prilled:Spherical beads produced via spray tower atomization minimize dust generation during pneumatic handling at Baltic import terminals.
Granular anchors the volume base while liquid gains share at the steepest rate.
Application:
Margin concentration follows application-specific certification burdens, with REACH fertilizer registration costs filtering low-volume competitors from agricultural supply.
- Agriculture:Blossom-end rot correction in solanaceous crops drives continuous calcium supplementation protocols. Dutch glasshouse operators meter liquid calcium nitrate through drip lines at 1-2 mmol/liter irrigation water.
- Fertilizers:Compound NPK blending incorporates calcium nitrate as secondary nutrient source, with Yara's Sluiskil facility supplying downstream formulators across Benelux.
- Water Treatment:German municipal utilities dose calcium nitrate for biological nutrient removal under tightened phosphate discharge limits. Berliner Wasserbetriebe operates the largest continuous-denitrification installation.
- Pharmaceuticals:European Pharmacopoeia-grade material serves dialysis solutions and wound irrigation, with ANSM oversight governing French manufacturing sites.
Agriculture commands the revenue base while water treatment climbs fastest on regulatory mandate expansion.
End User:
Procurement sophistication varies sharply across end-user categories, with agricultural cooperatives consolidating purchasing power faster than fragmented chemical manufacturers.
- Agricultural Companies:Spanish cooperatives in Huelva and Murcia contract directly with producers for tanker-delivered liquid concentrate, disintermediating traditional distributor networks.
- Chemical Manufacturers:Construction admixture blenders in Germany's Rhine-Ruhr region source technical-grade powder for calcium formate co-formulation.
- Water Utilities:Municipal operators in Bavaria and Baden-Württemberg specify certified-low-cadmium grades under ECHA substance evaluation protocols.
- Research Institutions:Wageningen University and INIA Spain purchase analytical-grade material for hydroponic nutrient solution development.
Agricultural companies dominate volume procurement while water utilities expand specification fastest on compliance-driven quality premiums.
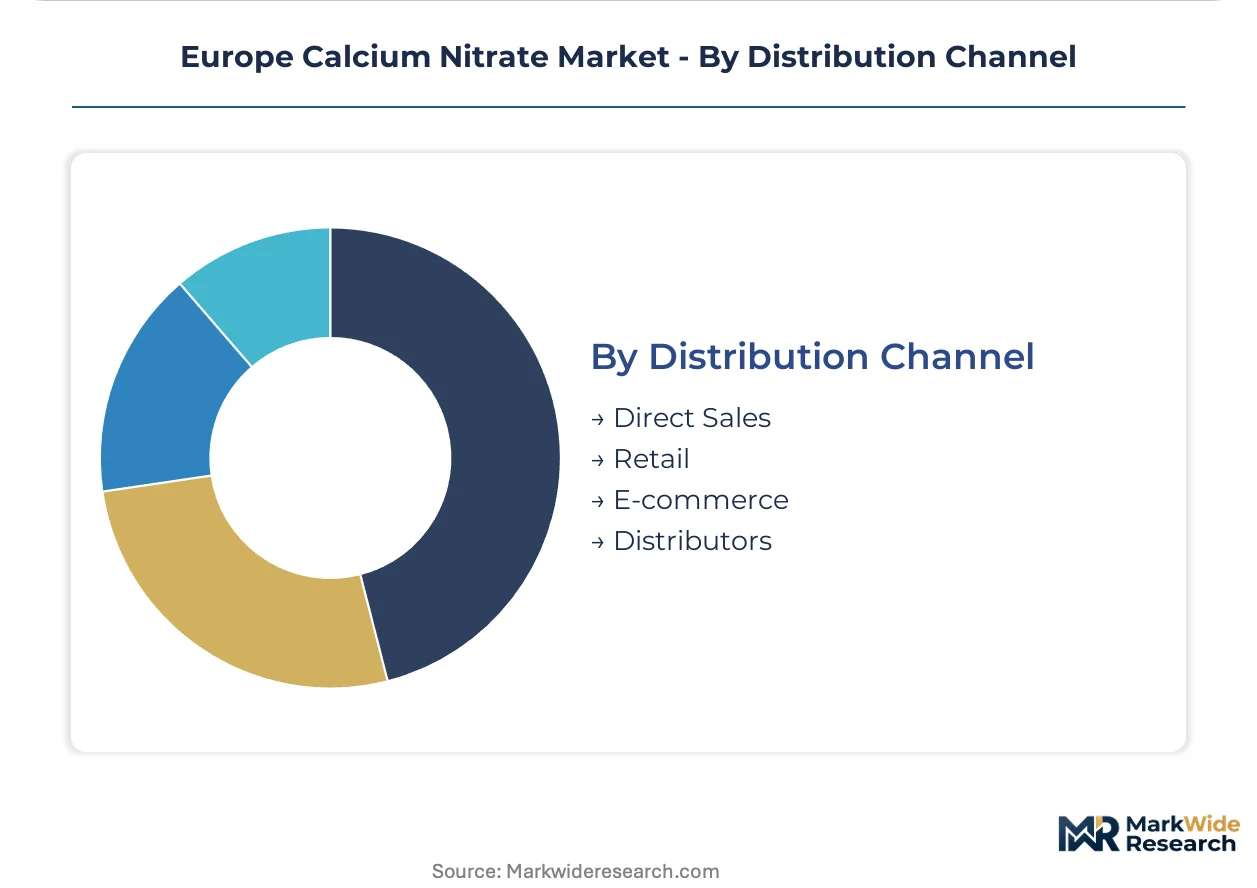
Distribution Channel:
Channel economics fragment across geography, with dense greenhouse clusters supporting direct delivery while dispersed broad-acre farming retains distributor intermediation.
- Direct Sales:Producer-to-farm tanker contracts capture margin in North Brabant and Limburg glasshouse corridors where ZLTO cooperative volumes justify dedicated logistics.
- Retail:Agricultural supply stores in Poland's Masovian voivodeship stock bagged granular for smallholder potato and vegetable producers.
- E-commerce:Online platforms serve hobby greenhouse operators and research laboratories requiring sub-pallet quantities with rapid delivery.
- Distributors:Traditional agrochemical wholesalers retain role in fragmented French and Italian markets where grower consolidation lags Benelux levels.
Direct sales anchor volume throughput in mature markets while e-commerce posts the steepest expansion trajectory in specialty and small-lot demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain and the Netherlands consume calcium nitrate through divergent pathways—Spanish growers broadcast granular for soil correction while Dutch operators meter liquid concentrates through precision drip networks, reflecting infrastructure maturity gaps across Mediterranean and North Sea corridors.
Spain
Almería and Murcia provinces drive calcium nitrate consumption through intensive greenhouse tomato and pepper cultivation requiring continuous blossom-end rot prevention. The Ministry of Agriculture's National Plan for Greenhouse Modernization subsidizes fertigation conversion from granular to liquid systems. Huelva cooperatives are piloting polymer-encapsulated controlled-release formulations for cherry tomato cycles.
Netherlands
North Brabant and Limburg glasshouse clusters anchor European demand for high-solubility liquid calcium nitrate concentrates. The EU Fertilizing Products Regulation's cadmium thresholds filter non-compliant imports, protecting domestic blenders. ZLTO and CZAV agricultural cooperatives now contract directly with producers for tanker-truck delivery, bypassing traditional distributor networks.
Germany
Bavarian and Baden-Württemberg municipal utilities dose calcium nitrate for biological nutrient removal under tightened phosphate discharge regulations. The KBA governs construction admixture grades where calcium formate and lithium accelerators compete for specification share. Berliner Wasserbetriebe operates the continent's largest continuous-denitrification installation using certified low-cadmium grades.
Poland
Masovian and Greater Poland voivodeships are deploying drip irrigation infrastructure at scale, creating new calcium nitrate concentrate demand outside established Dutch-Spanish corridors. Poland's national precision agriculture program funds cooperative purchasing platforms that disintermediate traditional agrochemical distributors. Retail agricultural supply stores in rural districts still stock bagged granular for smallholder potato producers.
Belgium
The port of Antwerp handles significant calcium nitrate import volumes for distribution across continental hinterlands. ANSM oversight governs pharmaceutical-grade material for dialysis solutions and wound irrigation manufactured at Walloon facilities. Legacy Odda-process expertise concentrates among retired cohorts at Belgian plants, constraining high-purity granular production capacity expansion.
Europe Calcium Nitrate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with ammonia-nitrate backward integration determining feedstock cost control across North Sea and Baltic corridors. Three archetypes dominate: Norwegian ammonia backbone operators leveraging captive nitric acid supply, Russian-European border integrators with phosphate-nitrate co-production assets, and Israeli crystalline-grade specialists competing on solubility metrics. Capacity rationalization and cooperative direct-channel partnerships constitute the dominant competitive moves reshaping distribution economics.
Among integrated producers with ammonia backbone control, Yara International ASA exemplifies the scale-driven archetype through its Sluiskil facility serving Benelux glasshouse corridors. EuroChem Group anchors the border-integration model with captive phosphate-nitrate assets. Haifa Group occupies the specialty-tier position, representing crystalline-grade specialists competing on dissolution performance rather than volume throughput. These three entities collectively illustrate how feedstock integration depth and formulation specificity divide competitive positioning across agricultural and industrial end-use segments.
| Leading Market Players |
|---|
| Yara International ASA |
| EuroChem Group |
| BASF SE |
| OCI Nitrogen |
| Haifa Group |
| K+S AG |
| Agroferti |
| URALCHEM JSC |
| Van Iperen International |
| Others |
Supply & Pricing Matrix
Sluiskil-scale nitric acid capacity utilization above 85 percent locks in feedstock cost advantages that compress price floors for non-integrated blenders across Benelux corridors. This scale concentration simultaneously concentrates supply power among Norwegian ammonia backbone operators while forcing smaller compounders toward specialty-grade margin pools.
Pricing Analysis
After-sales service contracts for tanker-truck direct delivery now drive lifetime value capture in Dutch glasshouse corridors. Three-tier pricing structure across pharmaceutical-grade, REACH-compliant fertilizer-grade, and technical construction-grade separates Haifa's crystalline solubility premiums from Yara's volume-scale liquid concentrates. Cost compression in standard fertilizer-grade intensifies because TTF-linked ammonia feedstock volatility transmits directly to nitric acid costs. Agricultural cooperatives in North Brabant exhibit lowest price sensitivity due to disintermediated direct contracts, while Polish retail channel buyers remain most responsive to per-kilogram bagged granular pricing.
Supply Chain Analysis
Inventory cycles at Baltic import terminals stretch to 6-8 weeks during peak spring application windows, exposing buyers to single-point disruption risk. Supply concentrates in Norway, the Netherlands, and Russia-European border zones, with nitric acid and high-purity limestone drawing from captive North Sea ammonia and Styrian quarry sources respectively. Tariff exposure on ammonium nitrate-calcium nitrate double salt flows through limited Latvian and Estonian port capacity creates structural vulnerability. Distribution runs through cooperative direct channels in mature Benelux markets while retaining traditional agrochemical distributor networks in fragmented French and Italian territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
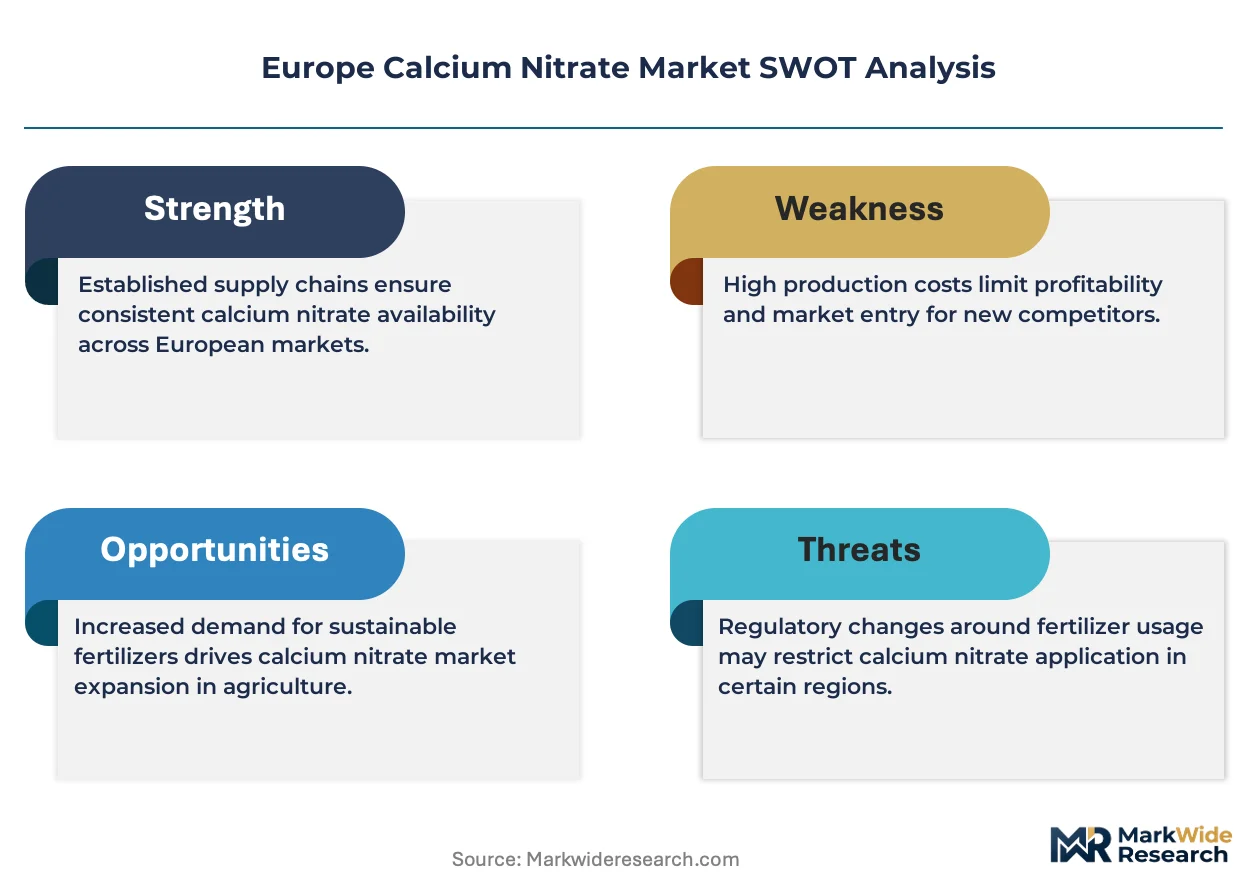
This market functions as a regulatory-entrenchment defensive moat where REACH cadmium thresholds and ECHA substance evaluation protocols create non-replicable compliance barriers against low-purity import competition.
For Market Incumbents: Fortify backward integration into nitric acid capacity at Sluiskil-scale facilities to neutralize TTF feedstock volatility, while accelerating Odda-process crystallization engineering recruitment to offset retiring Belgian cohort expertise. Calcium formate substitution in German construction admixtures and cooperative channel compression in the Netherlands represent immediate threats requiring certification investment in pharmaceutical-grade diversification. For New Entrants and Emerging Players: Direct-to-farm liquid concentrate logistics gaps in Poland's Masovian and Greater Poland voivodeships offer white-space entry outside established Dutch-Spanish corridor dominance. Wastewater denitrification specification in German municipal utilities presents the most penetrable application segment given tightening phosphate discharge regulations. Partner with emerging cooperative purchasing platforms to bypass entrenched distributor networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among liquid concentrate producers with tanker-truck direct contracts to agricultural cooperatives, locking in offtake visibility across seasonal demand swings. Long-term viability favors acquisition targets with captive nitric acid integration and certified low-cadmium limestone feedstock sourcing. Monitor ECHA substance evaluation protocol amendments as the critical inflection signal for import eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitric Acid | Captive ammonia-nitrate production at Sluiskil-scale insulates margin from TTF hub volatility. |
| REACH Certification Investment | ECHA cadmium threshold compliance secures protected demand pools against Turkish import displacement. |
| Cooperative Direct Channel Partnership | ZLTO and CZAV tanker contracts bypass distributor margin capture in North Brabant. |
| Odda-Process Crystallization Expansion | High-purity granular capacity addresses pharmaceutical-grade and fertigation solubility premiums. |
| Wastewater Denitrification Specification | Berliner Wasserbetriebe-scale municipal utility contracts anchor industrial application growth. |
Research Methodology
Initial hypotheses were tested against primary input from nitric acid plant managers, Dutch glasshouse operations directors, German municipal utility procurement leads, and agricultural cooperative purchasing managers, then refined against customs trade data, Cefic fertilizer statistics, ECHA substance evaluation protocols, and SEC filings from listed chemical producers. Bottom-up volume builds across granular, liquid, powder, and prilled product categories triangulated with top-down macroeconomic demand modeling.
Variance decomposition across grade tier, end-use application, and regional production hub dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling calibrated to regulatory mandate expansion rates and precision agriculture adoption curves. Nitric acid feedstock cost pass-through coefficients and REACH compliance threshold implementation timelines served as industry-specific forecast inputs.
Underlying assumptions cover TTF natural gas price band stability and ECHA cadmium limit enforcement continuity, with deviation risk concentrated in Russian-origin import flow disruptions and Odda-process engineering capacity constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Formate Brine Market
Bulk Chemicals
Europe Calcium Chloride Market
Bulk Chemicals
Stilbene Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
White Charcoal Powder Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Triammonium Citrate Market
Bulk Chemicals
Calcium Carbonate Market
Bulk Chemicals
Vacuum Salts Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Ethylene Glycol Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Ammonium Carbonate Market
Bulk Chemicals
Sodium Thiosulphate Market
Bulk Chemicals
Sodium Sulfide Market
Bulk Chemicals
Meta Tartaric Acid Market