
 Organic Tissue Paper Market | 2026-2036
Organic Tissue Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Tissue Paper Market Analytics
The EU Green Deal is recalibrating sourcing obligations for tissue manufacturers serving European buyers. Essity AB leverages its integrated Nordic pulp network to secure certified fiber streams. Kimberly-Clark Corporation anchors North American retail presence through club-store partnerships and pharmacy distribution. Metsä Group specializes in bioproduct mill integration, converting wood residues into tissue-grade pulp with reduced chemical inputs.
Organic tissue paper denotes disposable hygiene products manufactured from certified organic fibers—typically bamboo, recycled paper, or virgin pulp sourced without synthetic pesticides—processed under restricted chlorine bleaching protocols and meeting compostability thresholds. Facial tissue and toilet paper dominate current output volumes, while bamboo-based material commands premium positioning due to faster renewability cycles and lower irrigation requirements. Online retail channels are expanding fastest among distribution pathways, though supermarkets still control the bulk of household purchasing touchpoints.
REACH chemical restrictions and the EU F-Gas Regulation shape manufacturing inputs for European producers, while FDA oversight governs product safety claims in the United States. The EU AI Act's supply-chain transparency mandates will soon require automated traceability for organic certification documentation. Stakeholders must monitor evolving compostability standards and retailer-specific chemical exclusion lists to maintain market access across jurisdictions.
Market Dynamics
EU Green Deal due diligence requirements are forcing tissue manufacturers to restructure pulp procurement networks and invest in certified fiber traceability systems that satisfy automated documentation mandates.
Growth Catalysts
- EU Green Deal sourcing mandates:European buyers now require certified organic fiber documentation, pulling manufacturers toward accredited supply chains.
- Hospitality procurement conversion:North American hotel chains are rewriting supplier contracts to specify organic-grade tissue for guest amenities.
- Bamboo renewability cycles:Fast-growing bamboo varieties reach harvest maturity in 3-5 years versus 25-30 years for softwood pulp, reducing land-use pressure.
Market Restraints
- Certified pulp supply concentration:Nordic and Canadian boreal forests dominate FSC-certified virgin fiber availability, creating geographic dependency.
- Chlorine-free bleaching cost premium:Oxygen-based and ozone-based whitening processes add 15-25% to chemical input costs versus elemental chlorine.
- Compostability testing bottlenecks:EN 13432 and ASTM D6400 certification timelines stretch 6-12 months, delaying product launches.
Strategic Opportunities
- EU AI Act traceability mandates:Automated certification documentation systems will become mandatory, favoring early adopters with digitized supply chains.
- German private-label shelf conversion:Retailers are displacing conventional brands with store-brand organic lines, opening private-label manufacturing contracts.
- Online retail channel expansion:Direct-to-subscription models for household tissue bypass supermarket intermediaries and capture recurring revenue.
Industry Challenges
- Multi-jurisdiction chemical exclusion compliance:Retailers maintain divergent restricted substance lists beyond REACH and FDA baselines, forcing SKU proliferation.
- Compostability standard fragmentation:Home versus industrial composting certifications lack harmonization across EU member states and US municipalities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Tissue Paper Market |
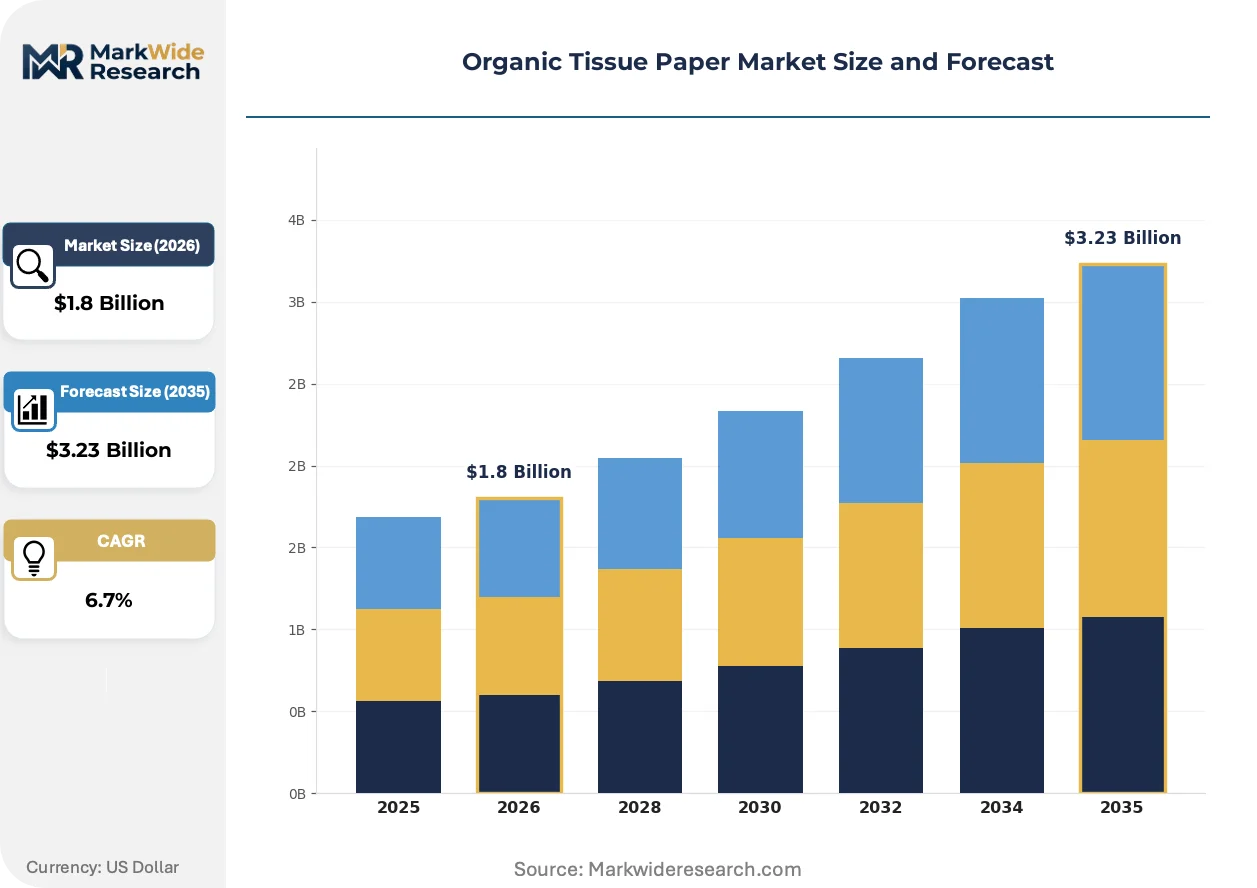
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Tissue, Toilet Paper, Paper Towels, Napkins End User: Household, Commercial, Industrial, Healthcare Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Distributors Material: Bamboo, Recycled Paper, Virgin Pulp, Wood-Free |
| Companies Covered | Georgia-Pacific LLC, Metsä Group, Essity AB, WEPA Hygieneprodukte GmbH, Cascades Inc., Kimberly-Clark Corporation, Sofidel Group, CMPC Tissue S.A., Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Tissue Paper Market Evolving Landscape
Digital traceability platforms are converging with bioproduct mill integration to reshape how organic tissue manufacturers verify and communicate fiber provenance to institutional buyers.
Bioproduct mill technology is unifying wood residue conversion with tissue-grade pulp production. Nordic manufacturers are retrofitting existing facilities to process bark, sawdust, and logging residues into certified organic pulp streams. This integration is compressing raw material costs while satisfying EU Green Deal circular economy criteria.
REACH chemical restrictions and the EU F-Gas Regulation are tightening allowable inputs for European tissue production. Manufacturers serving EU markets must reformulate process chemicals and document alternatives assessments. German and French retail channels are most affected, with buyers demanding third-party verification of chlorine-free bleaching protocols.
Subscription-based household purchasing is displacing supermarket stock-up behavior among urban consumers. Direct-to-consumer platforms offer scheduled delivery of certified organic tissue bundles, bypassing traditional retail markup structures. This pattern is most visible in metropolitan Germany and the Netherlands, where logistics density supports cost-effective last-mile fulfillment.
Organic Tissue Paper Market Segmentation
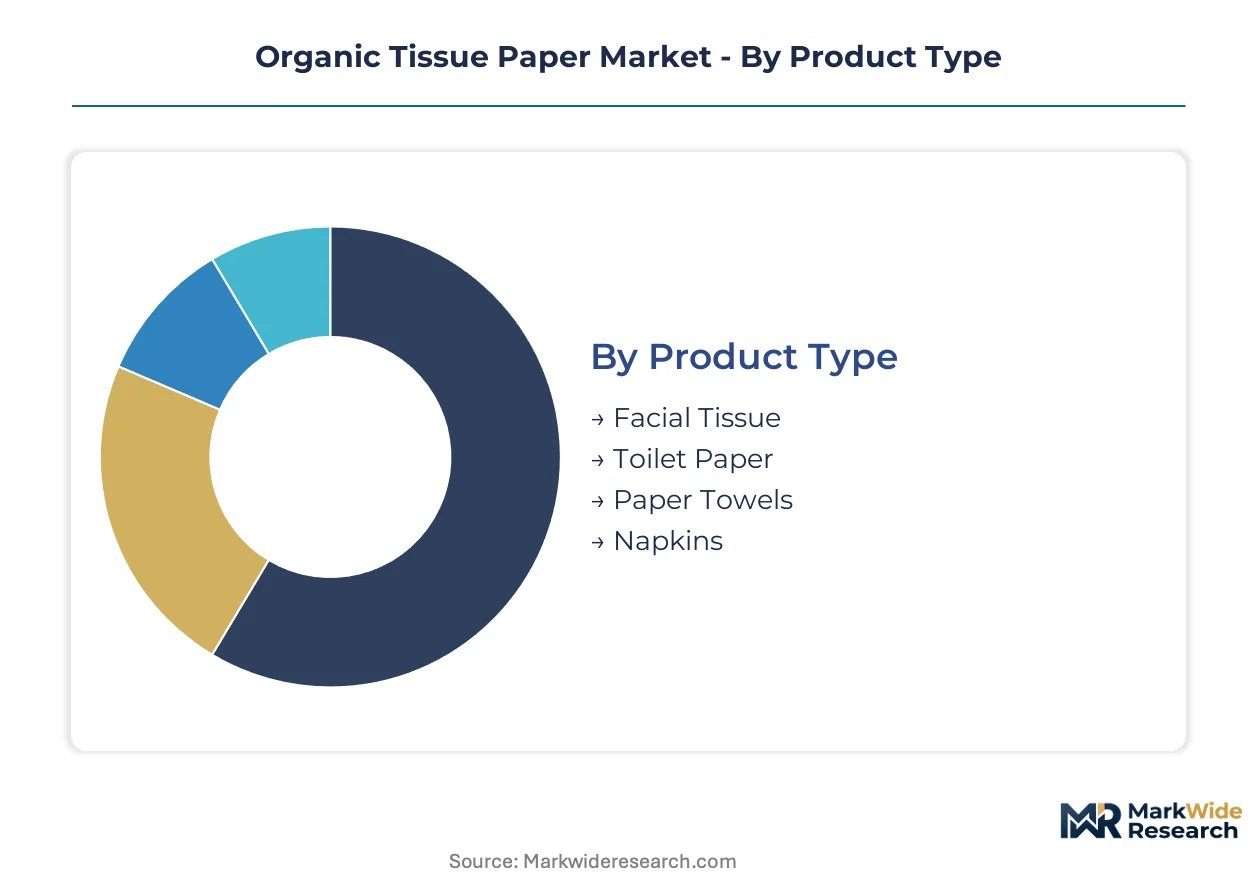
Segmentation in organic tissue paper reveals divergent margin profiles across material grades and channel economics. Manufacturers must align fiber certification levels with end-use price sensitivity and distribution cost structures.
Product Type:
Volume concentration favors high-frequency replenishment categories, while premium positioning concentrates in specialty formats with certification visibility.
- Toilet Paper:Rolls manufactured from certified organic pulp or bamboo fiber dominate household procurement frequency. Demand clusters in German and Dutch supermarket private-label programs where organic certification commands shelf space displacement.
- Facial Tissue:Boxed and pocket formats utilize chlorine-free bleaching protocols with enhanced softness specifications. North American hospitality chains are converting amenity contracts to certified organic grades, pulling supply toward FSC-documented fiber streams.
- Paper Towels:Multi-ply absorbent sheets for kitchen and commercial use, typically manufactured with higher recycled content tolerance.
- Napkins:Single-use table linens for foodservice and household dining occasions, with compostability certification driving institutional procurement.
Mature deployment sits with toilet paper. Newer deployment is concentrated in facial tissue.
End User:
Procurement authority separates consumer-driven household purchasing from contract-negotiated institutional volumes with divergent certification requirements.
- Household:Individual consumers purchasing through retail or subscription channels, prioritizing softness and packaging sustainability claims. Online retail expansion is displacing supermarket stock-up behavior in metropolitan Germany and the Netherlands.
- Commercial:Hospitality, foodservice, and office facilities specifying organic grades for guest and employee amenities. EU Green Deal due diligence requirements are forcing contract rewrites toward certified fiber documentation.
- Healthcare:Medical and eldercare facilities with stringent hygiene protocols and disposable product mandates.
- Industrial:Manufacturing and logistics operations utilizing tissue products for process cleaning and worker hygiene stations.
Contract volume concentrates in commercial. Fastest expansion is appearing in household subscription models.
Distribution Channel:
Channel selection determines margin capture versus certification communication effectiveness, with digital platforms enabling direct provenance storytelling.
- Supermarkets:Mass-market retail commanding bulk household purchasing through shelf-dominant private-label organic lines. German retailers are displacing conventional brands with store-brand certified offerings.
- Online Retail:Direct-to-consumer platforms and subscription services bypassing traditional retail markups. Scheduled delivery bundles are climbing the fastest among urban consumer segments with logistics density advantages.
- Convenience Stores:Impulse and emergency replenishment purchasing with limited organic SKU availability.
- Distributors:B2B procurement intermediaries serving institutional buyers with contract-negotiated volume pricing.
Established volume flows through supermarkets. Emerging share is concentrating in online retail.
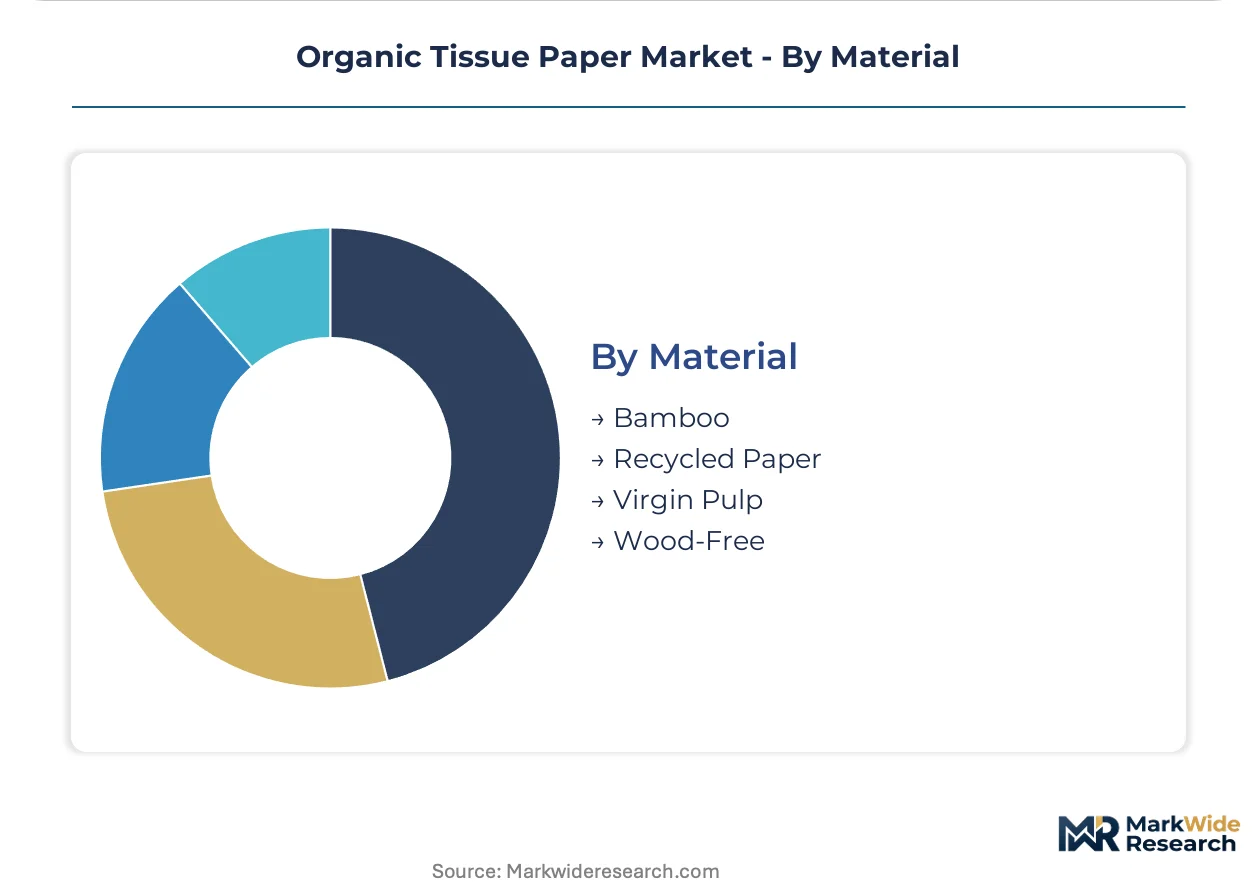
Material:
Raw material selection governs renewability credentials, chemical input requirements, and geographic sourcing dependencies for certified fiber streams.
- Bamboo:Fast-growing grass species reaching harvest maturity in 3-5 years with minimal irrigation requirements. Premium positioning in North American and European markets leverages lower land-use pressure narratives.
- Recycled Paper:Post-consumer fiber streams processed under restricted chlorine protocols, satisfying circular economy criteria in EU procurement mandates.
- Virgin Pulp:Certified organic wood fiber from FSC-accredited Nordic and Canadian boreal forest operations, creating geographic supply concentration.
- Wood-Free:Alternative fiber sources including agricultural residues and non-wood plant materials for specialty applications.
Certified supply concentrates in virgin pulp. Steepest expansion trajectory is appearing in bamboo-based material.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors European organic tissue procurement, with German retailers driving private-label shelf conversion and hospitality chains across the Rhine-Ruhr corridor rewriting supplier contracts for certified amenities.
Germany
Supermarket private-label programs and hospitality procurement conversion dominate demand. The EU Green Deal's due diligence requirements force manufacturers to document certified fiber streams. The Rhine-Ruhr industrial corridor hosts bioproduct mill retrofits processing wood residues into tissue-grade pulp.
United States
Club-store partnerships and pharmacy distribution networks concentrate household purchasing. FDA oversight governs product safety claims and chemical disclosure protocols. The Pacific Northwest pulp cluster supplies FSC-certified virgin fiber to North American tissue converters.
Sweden
Integrated Nordic pulp networks secure certified fiber streams for European export markets. REACH chemical restrictions and the EU F-Gas Regulation shape allowable manufacturing inputs. The Värmland and Västerbotten forest regions concentrate sustainable harvesting operations.
France
Retail channels demand third-party verification of chlorine-free bleaching protocols. ANSM and CNIL frameworks intersect with product safety and data transparency mandates. The Grand Est region hosts specialty converters serving Parisian hospitality procurement.
Canada
Boreal forest operations supply FSC-certified virgin pulp to North American and European buyers. Health Canada and PMRA regulations govern chemical inputs in tissue manufacturing. The Quebec-Ontario border region concentrates sustainable fiber harvesting and mill integration.
Organic Tissue Paper Market Competitive Landscape
The competitive structure tilts toward integrated pulp-to-tissue specialists with captive fiber supply. Consolidation pressures favor players with certified sourcing networks and automated traceability capabilities. Three archetypes dominate: Nordic integrated forest products groups, North American consumer goods conglomerates with club-store anchoring, and European private-label specialists with retail channel penetration. Capacity expansion in bioproduct mill technology and strategic partnerships for digital certification platforms represent the dominant competitive moves.
Among Nordic integrated groups, Metsä Group and Essity AB exemplify the bioproduct mill archetype with wood residue conversion capabilities. WEPA Hygieneprodukte GmbH occupies a position within the European private-label tier, anchoring German retail channel penetration. These three represent distinct strategic postures: captive pulp integration, retail partnership density, and geographic sourcing concentration.
| Leading Market Players |
|---|
| Georgia-Pacific LLC |
| Metsä Group |
| Essity AB |
| WEPA Hygieneprodukte GmbH |
| Cascades Inc. |
| Kimberly-Clark Corporation |
| Sofidel Group |
| CMPC Tissue S.A. |
| Procter & Gamble |
| Others |
Value Network & Pricing Analysis
Hospitality procurement managers and German supermarket category buyers concentrate purchasing authority, anchoring contract-based long-term offtake agreements that compress margin capture for converters lacking certified fiber integration.
Pricing Analysis
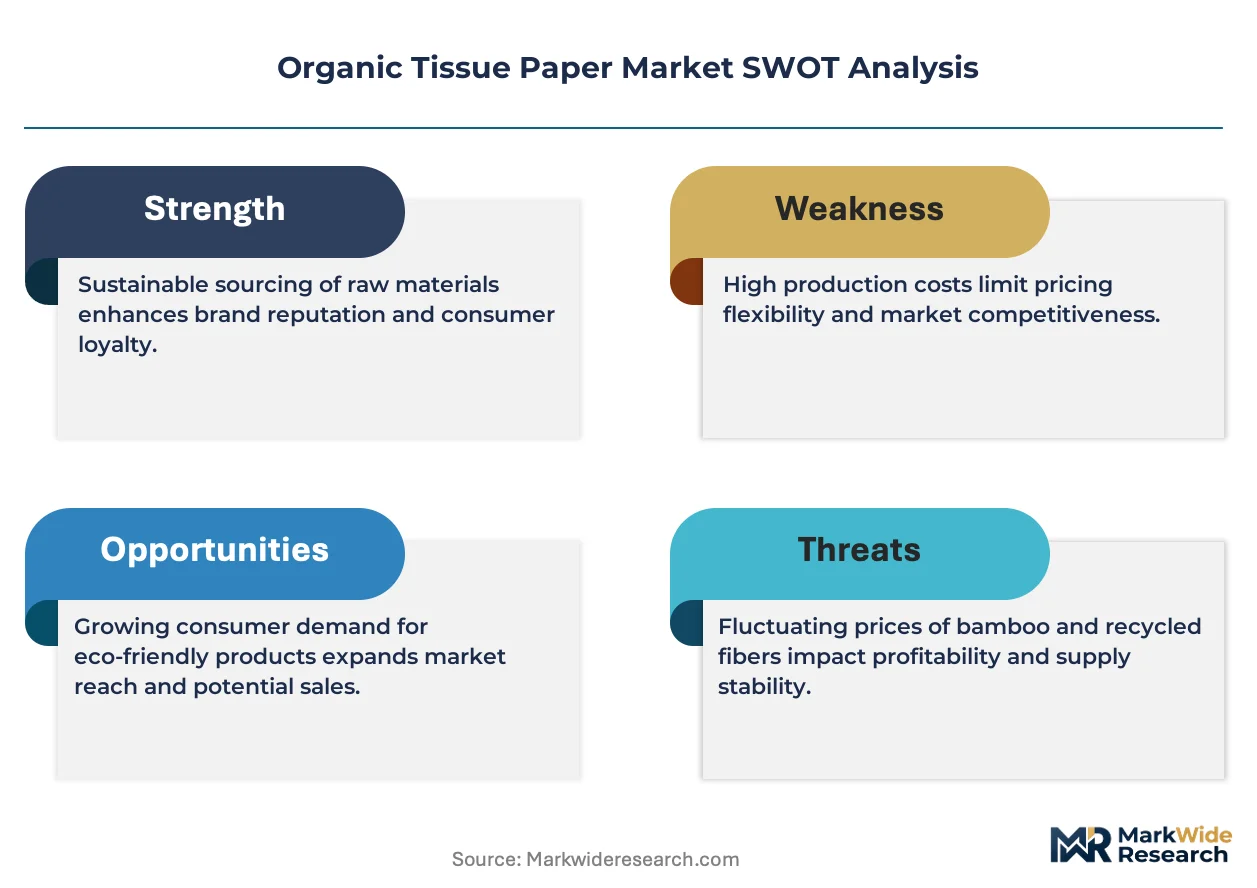
Certification-grade outcomes anchor value-based pricing tiers, with FSC-documented fiber streams commanding 15-25% premiums over conventional grades. Three-tier pricing structure across premium bamboo, standard recycled-content, and economy virgin-pulp levels stratifies the market. Cost compression in standard-tier recycled fiber is intensifying because Nordic pulp supply bottlenecks are redirecting demand toward lower-grade alternatives. Household subscription buyers exhibit highest price sensitivity, while North American hospitality chains prioritize certification visibility over unit cost.
Supply Chain Analysis
Freight costs from Nordic and Canadian boreal forest operations to European converters represent 8-12% of landed pulp expense, compressing margin for non-integrated manufacturers. Supply concentrates in Sweden, Finland, and Canada for FSC-certified virgin fiber, while bamboo feedstock flows from China and Southeast Asia. Raw material dependencies encompass chlorine-free bleaching chemicals, compostability certification testing, and automated traceability software. Single-source vulnerability in Nordic pulp supply creates structural risk for European converters. Distribution runs through supermarket private-label programs, direct-to-subscription platforms, and hospitality distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified organic pulp supply scarcity props pricing power for integrated manufacturers, creating a supply-constrained market structure that favors early movers with captive fiber networks.
For Market Incumbents: To counter emerging private-label specialists from Germany, secure backward integration into Nordic bioproduct mill capacity and accelerate EN 13432 compostability certification timelines. Prioritize automated traceability platform deployment ahead of EU AI Act mandates. Channel control through exclusive hospitality distributor partnerships represents the secondary defensive lever. For New Entrants and Emerging Players: The premium-to-economy price-point gap in North American facial tissue offers white-space entry for bamboo-based specialty converters. Target underpenetrated metropolitan subscription markets in the Netherlands with direct-to-consumer bundling. Compostability certification for foodservice napkin applications provides the most penetrable institutional segment. For Investors and Strategic Acquirers: The window for entry favors integrated Nordic forest products groups with bioproduct mill retrofit capabilities and established FSC supply relationships. Long-term viability hinges on fiber traceability infrastructure and EU regulatory compliance depth. Watch German private-label shelf conversion velocity as the inflection signal for European market structure consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Bioproduct Mill Retrofit | Wood residue conversion into certified pulp satisfies EU Green Deal circular economy criteria. |
| Automated Traceability Platform | Digital certification documentation aligns with EU AI Act supply-chain transparency mandates. |
| Direct-to-Subscription Launch | Recurring revenue models bypass supermarket markup structures in German urban markets. |
| Compostability Certification Investment | EN 13432 and ASTM D6400 credentials unlock institutional foodservice procurement contracts. |
| Hospitality Distributor Partnership | Exclusive amenity supply agreements anchor volume commitments from North American hotel chains. |
Research Methodology
Independent corroboration across procurement executives at hospitality chains, category buyers at German supermarket retailers, and technical directors at Nordic pulp mills underwrites the qualitative findings. Primary interviews with tissue manufacturing plant managers, sustainability officers at consumer goods conglomerates, and distribution channel partners were cross-referenced against customs trade data, FSC certification databases, and EU regulatory filings. Bottom-up volume triangulation against top-down macroeconomic indicators validated segment-level outputs.
Comparable-period anchoring to historical procurement contract cycles and retail shelf-space conversion timelines structured the projection horizon. The analytical framework modeled product type, material grade, distribution channel, and end-user vertical dimensions across the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating EU Green Deal compliance cost pass-through and bamboo fiber substitution rates.
Inputs from hospitality procurement databases and German retail audit panels were available through the study window; gaps in real-time compostability certification backlog data introduce uncertainty bands around product launch timing assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Pulp and Paper Market
Paper Products
Paper and Board Technologies Market
Paper Products
Recovered Paper Market
Paper Products
Global Electrical Insulation Paper Market
Paper Products
Europe Coated Paper Market
Paper Products
Printing Paper Market
Paper Products
BPA Free Thermal Paper Market
Paper Products
Paper Glass Market
Paper Products
Thermal Paper Market
Paper Products
Household Paper Market
Paper Products
Sawn Wood Market
Paper Products
Fluff Pulp Market
Paper Products
White Line Chipboard Market
Paper Products
Acrylic Paper Market
Paper Products
Chemical Pulp Market
Paper Products
Global Wood Pulp Market