
 Aluminum Nitrate Nonahydrate Market | 2026-2036
Aluminum Nitrate Nonahydrate Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Nitrate Nonahydrate Market Outlook
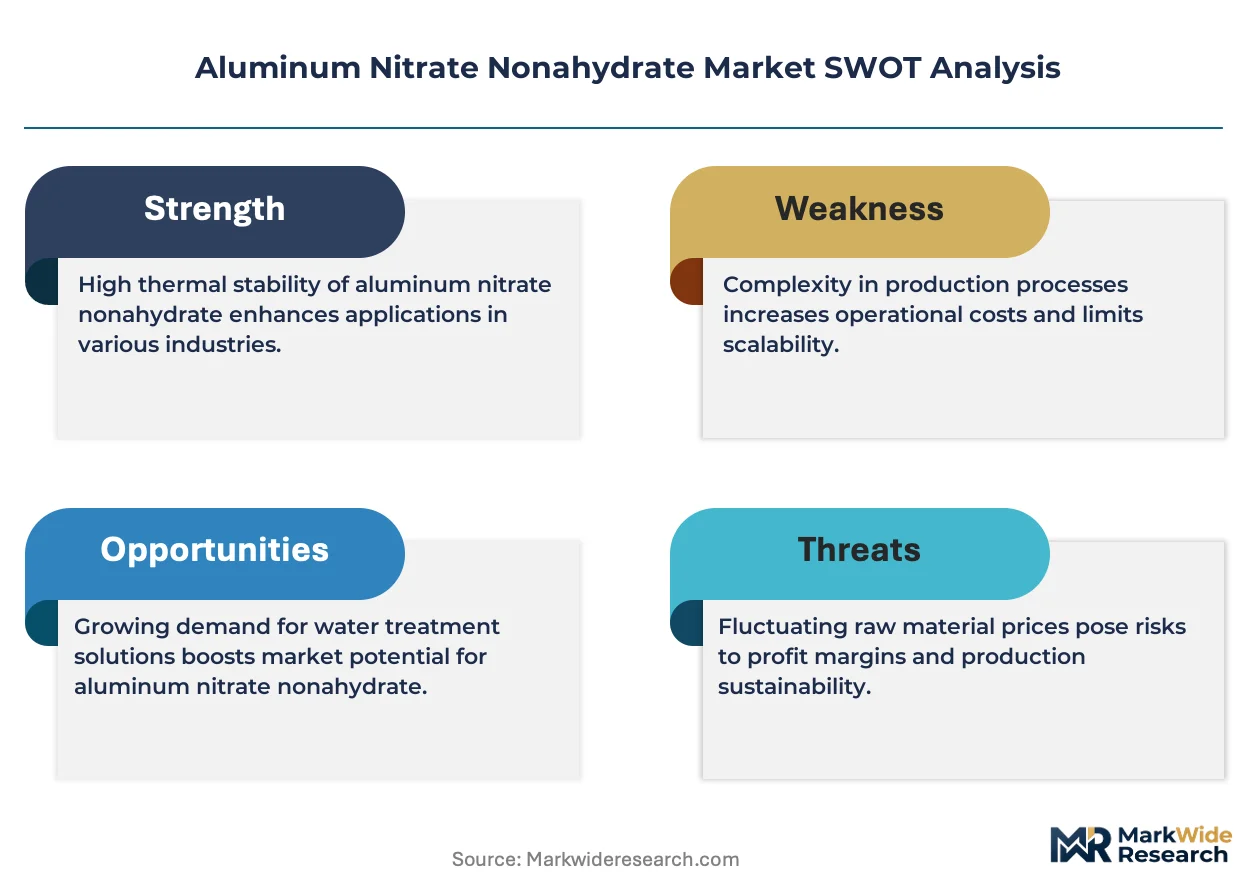
Chinese specialty chemical producers is shifting capacity toward higher-purity aluminum nitrate nonahydrate grades for pharmaceutical and electronics applications. XiaXian Yunli leverages integrated nitric acid supply chains to control feedstock costs across Shanxi Province. Strem Chemicals sustains niche positions in high-specification laboratory and research segments through stringent quality protocols. Taiyuan Xinyufeng anchors regional distribution networks serving northern China's industrial water treatment sector.
Aluminum nitrate nonahydrate is a hydrated aluminum salt with the formula Al(NO₃)₃·9H₂O, typically produced through the reaction of aluminum metal or aluminum hydroxide with nitric acid followed by controlled crystallization; it serves primarily as a precursor for alumina-based catalysts, a coagulating agent in water purification, and a mordant in textile dyeing processes. The nonahydrate crystalline form dominates commercial supply due to its stability under standard storage conditions and favorable solubility profile for aqueous industrial processes. Pharmaceutical-grade specifications command premium positioning within end-user segments, while water treatment applications anchor volume demand through municipal and industrial procurement cycles. Fertilizer applications represent a mature growth pathway with established supply relationships to agricultural chemical distributors.
China's Ministry of Ecology and Environment enforces discharge limits that elevate demand for high-performance coagulants in industrial wastewater systems. EPA regulations in the United States mandate stringent effluent standards for heavy metals, reinforcing aluminum-based treatment chemical procurement across municipal utilities. REACH compliance requirements in Europe restrict impurity profiles in imported aluminum salts, shaping export qualification protocols for Asian manufacturers. Stakeholders must monitor evolving PFAS contamination standards that could redirect coagulant selection criteria across key municipal water contracts.
Market Dynamics
China's GB standards for industrial wastewater discharge are compressing product specifications across the aluminum nitrate nonahydrate supply base, forcing crystallization process upgrades and purity threshold elevations that favor integrated nitric acid producers over merchant chemical compounders.
Growth Catalysts
- MEE discharge mandates:China's Ministry of Ecology and Environment enforces tightening effluent limits that elevate aluminum-based coagulant procurement across Shandong Province's chemical manufacturing corridor.
- Electronics-grade purity demand:Semiconductor precursor applications require sub-ppm impurity profiles, opening premium positioning for crystallization-optimized production lines.
- Shanxi feedstock integration:Captive nitric acid supply chains reduce raw material cost volatility for producers anchoring capacity near coal-chemical hubs.
Market Restraints
- Nitric acid price volatility:Ammonia oxidation feedstock costs fluctuate with natural gas benchmarks, squeezing margin stability for non-integrated compounders.
- REACH impurity protocols:European ECHA restrictions on heavy metal content in imported aluminum salts create qualification barriers for standard-grade exporters.
- Polyaluminum chloride substitution:Pre-hydrolyzed coagulant alternatives gain traction in municipal water treatment, displacing conventional aluminum salt dosing in some procurement cycles.
Strategic Opportunities
- Pharmaceutical-grade certification:USP-grade specifications for diagnostic reagent applications command 3-5x pricing multiples over industrial grades.
- Textile mordant premiumization:Digital printing ink compatibility requirements in East Asian fabric processing create specification differentiation opportunities.
- Catalyst precursor convergence:Zeolite synthesis for fluid catalytic cracking units links aluminum nitrate demand to refinery capacity expansions in the Middle East.
Industry Challenges
- Crystallization engineering expertise:Controlled nonahydrate formation requires precise supersaturation management that few technical teams outside legacy producers have mastered.
- Multi-jurisdiction certification timelines:Pharmaceutical and food-contact registrations across FDA, EMA, and NMPA jurisdictions extend commercialization cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Nitrate Nonahydrate Market |
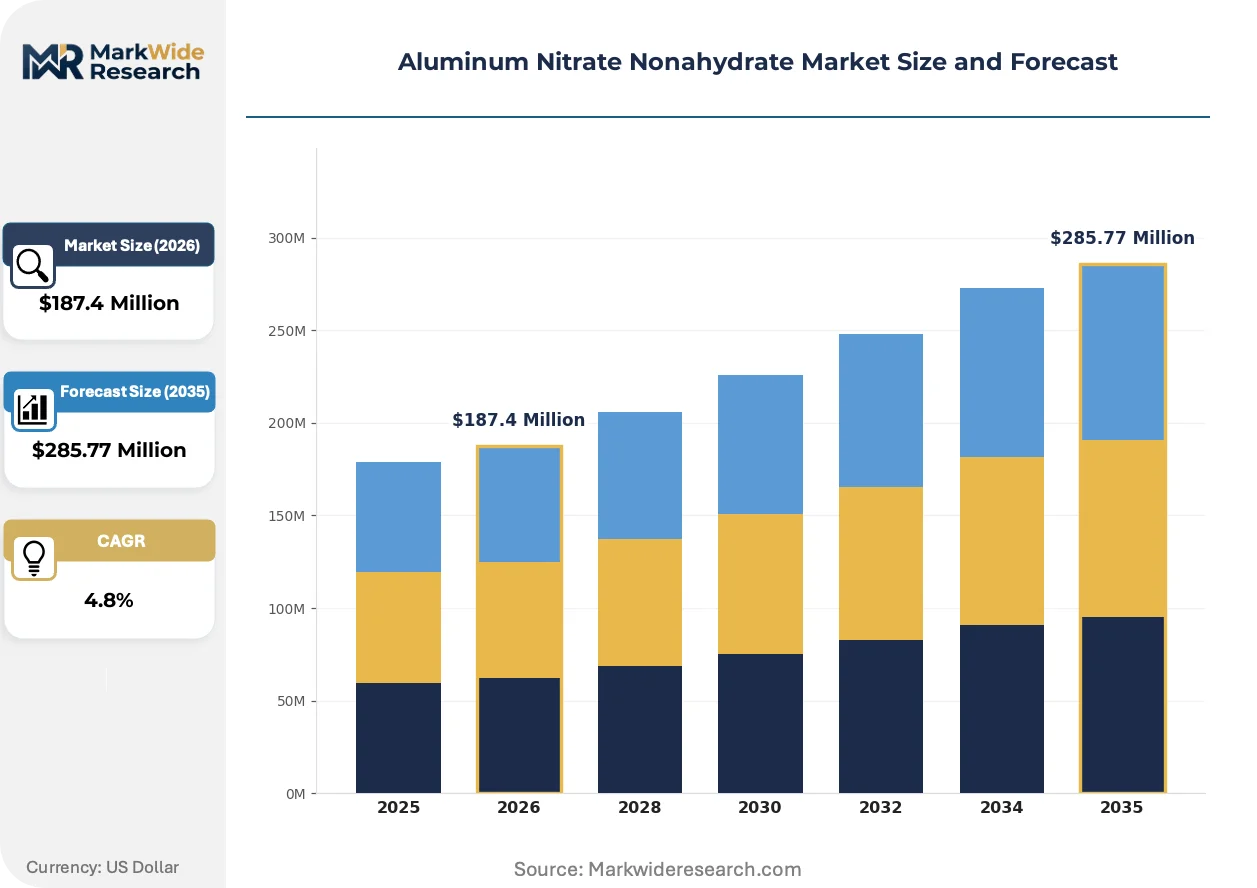
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hexahydrate, Nonahydrate, Dihydrate, Pentahydrate End User: Pharmaceuticals, Agriculture, Water Treatment, Chemicals Application: Fertilizers, Coagulants, Catalysts, Additives Packaging Type: Bags, Drums, Bulk Containers, Jars |
| Companies Covered | XiaXian Yunli, Strem Chemicals, Taiyuan Xinyufeng, Orrion Chemicals, Nithyasri Chemicals, Chongqing Hua'nan Chemical, Taiyuan Bohui Chemical, Thatcher Group, Shijiazhuang Xuanran Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Nitrate Nonahydrate Market Strategic Shifts
Continuous crystallization technology is displacing batch processes across the aluminum nitrate nonahydrate manufacturing base, enabling real-time purity monitoring and reducing energy intensity per ton of hydrate produced.
Membrane filtration integration is automating impurity removal in high-purity production streams. Specialty chemical producers serving electronics applications adopt ceramic ultrafiltration modules that reduce manual sampling protocols by seventy percent. This automation compresses batch-to-batch variation and accelerates qualification timelines for semiconductor precursor contracts.
EPA effluent guideline revisions for coal-fired power plant wastewater mandate zero liquid discharge configurations that favor aluminum-based coagulant systems. Utilities across the Ohio River Valley retrofit treatment trains to meet ELG limitations on selenium and mercury. Procurement specifications now emphasize rapid flocculation kinetics that aluminum nitrate formulations deliver against polymeric alternatives.
Specification-driven purchasing is consolidating vendor relationships among municipal water treatment authorities. Buyers in the Yangtze River Delta region now require documented impurity profiles and chain-of-custody documentation that favors direct manufacturer relationships over distributor intermediaries. This disintermediation compresses pricing transparency and accelerates technical service response cycles for complex influent conditions.
Aluminum Nitrate Nonahydrate Market Segmentation
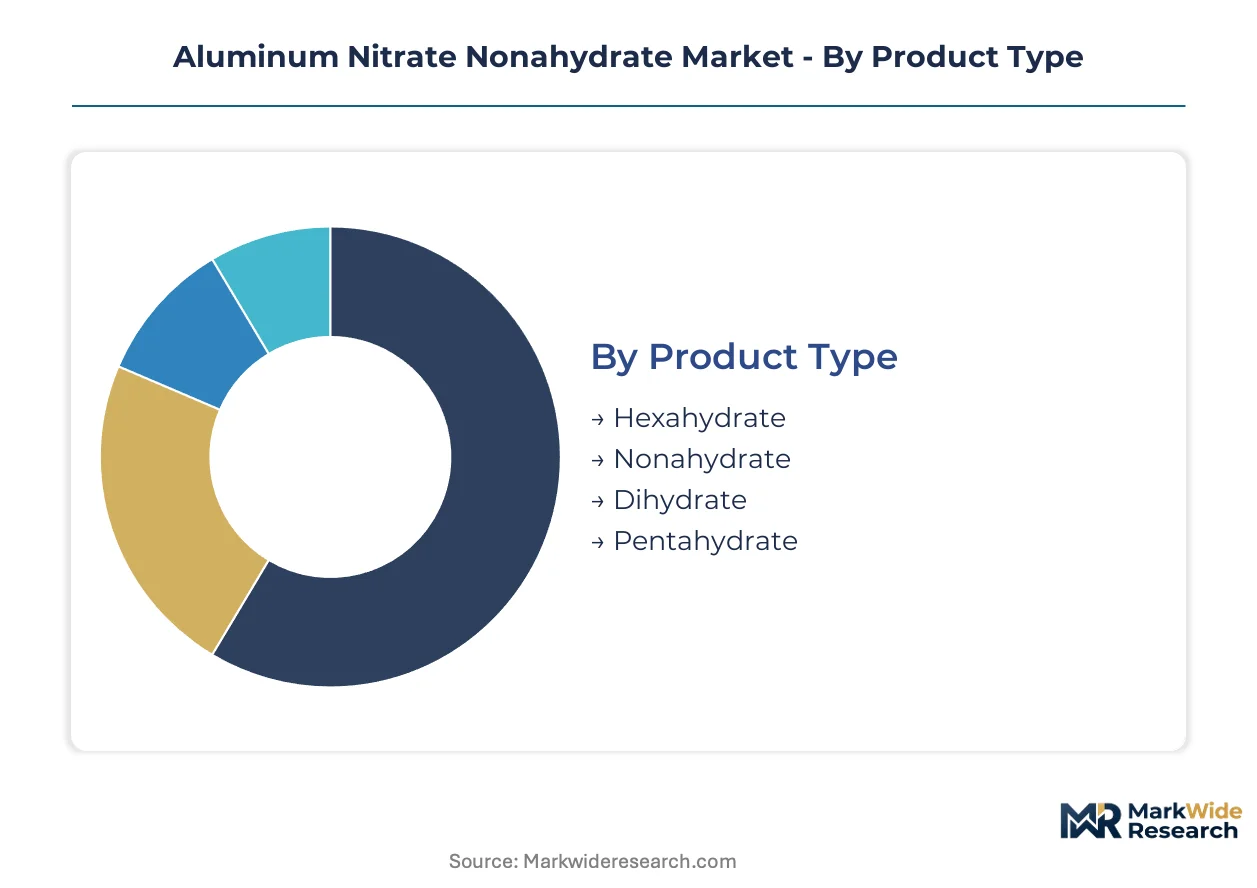
Aluminum nitrate nonahydrate procurement patterns diverge sharply across specification grades, with pharmaceutical and electronics applications demanding sub-ppm purity thresholds while water treatment sectors prioritize volume economics. Understanding these segment boundaries clarifies where crystallization expertise and feedstock integration translate into sustainable margin capture.
Product Type:
Customization intensity spans from commodity hydrates to precision-controlled crystalline forms, with stability under storage and dissolution kinetics determining specification premiums.
- Nonahydrate:The Al(NO₃)₃·9H₂O crystalline structure delivers superior aqueous solubility and shelf stability under standard warehouse conditions. Municipal water treatment facilities across China's Shandong Province specify this grade for rapid flocculation deployment in high-throughput systems.
- Hexahydrate:Lower water content reduces shipping costs per active aluminum unit, attracting agricultural fertilizer compounders in Shanxi Province's coal-chemical corridor where freight economics dominate procurement calculus.
- Dihydrate:Minimal hydrate form suits high-temperature catalyst precursor applications where residual moisture disrupts zeolite synthesis kinetics.
- Pentahydrate:Intermediate stability profile serves niche textile mordant formulations requiring controlled hydrolysis rates during digital fabric printing.
Most installed capacity flows through Nonahydrate. Expansion is steepest in Hexahydrate.
End User:
Customer archetypes range from price-sensitive bulk procurers to certification-intensive specialty buyers, with regulatory jurisdiction determining qualification barriers.
- Water Treatment:Municipal utilities and industrial discharge facilities deploy aluminum nitrate as primary coagulant for heavy metal precipitation, with China's MEE effluent mandates accelerating procurement across the Yangtze River Delta.
- Pharmaceuticals:USP-grade specifications for diagnostic reagent manufacturing command stringent impurity protocols and 18-36 month multi-jurisdiction registration timelines.
- Agriculture:Fertilizer blenders incorporate aluminum nitrate as micronutrient carrier, with established distributor relationships anchoring volume procurement in mature supply chains.
- Chemicals:Specialty compounders serving electronics and catalyst sectors require documented chain-of-custody and real-time purity monitoring capabilities.
Water Treatment captures the dominant volume share. Pharmaceuticals is climbing the fastest on value terms.
Application:
Functional differentiation separates commodity chemical roles from performance-critical industrial processes, with specification stringency scaling accordingly.
- Coagulants:Rapid flocculation kinetics in aluminum-based water treatment systems address EPA effluent guidelines for selenium and mercury removal across Ohio River Valley utilities.
- Catalysts:Zeolite synthesis precursors for fluid catalytic cracking units link demand to refinery capacity expansions in Middle Eastern processing hubs.
- Fertilizers:Mature application pathway with established agricultural chemical distributor networks and limited specification differentiation.
- Additives:Textile mordant and leather tanning auxiliary functions require compatibility with digital printing ink chemistries in East Asian fabric processing.
Coagulants absorb the majority of production volume. Catalysts is gaining share fastest on specification premiums.
Packaging Type:
Logistics configuration reflects customer scale and handling automation, with bulk formats dominating industrial procurement and unitized packaging serving laboratory and specialty segments.
- Bulk Containers:Intermediate bulk containers and tanker deliveries minimize per-unit handling costs for high-volume water treatment procurement in China's chemical manufacturing corridors.
- Drums:Standard 200-liter steel drums balance mobility and storage efficiency for mid-scale chemical processing operations.
- Bags:Multi-layer laminated sacks with moisture barriers protect hydrate stability during extended storage in humid climates.
- Jars:Laboratory-scale packaging serves research institutions and pharmaceutical quality control laboratories requiring precise lot traceability.
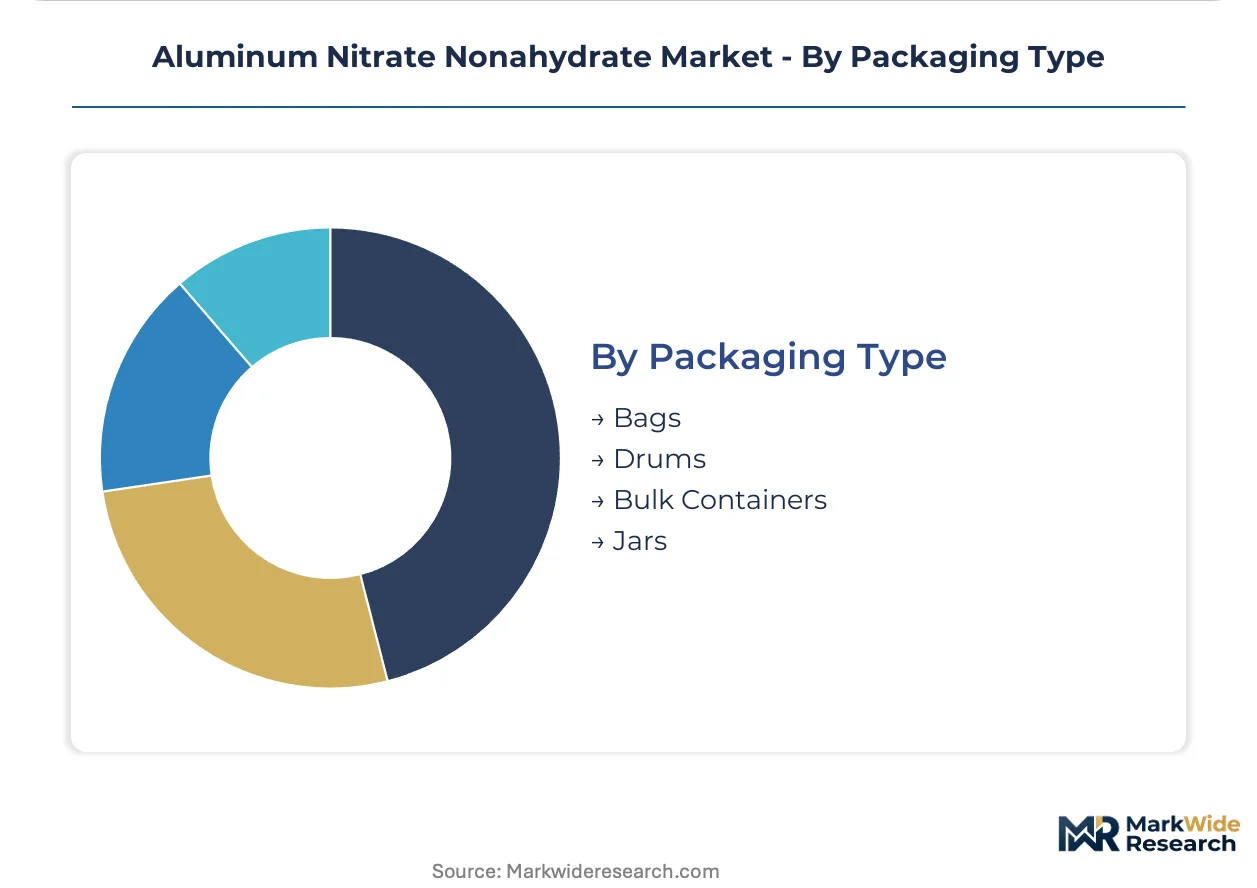
Bulk Containers move the largest tonnage. Jars is expanding most quickly on pharmaceutical and electronics sample demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting aluminum nitrate nonahydrate production toward jurisdictions with integrated feedstock chains and lower compliance-cost structures. Producers in coal-chemical corridors exploit captive nitric acid supply to offset tightening effluent mandates elsewhere.
China
Shandong Province's chemical manufacturing corridor absorbs the dominant volume share as MEE discharge mandates accelerate coagulant procurement. GB standards for industrial wastewater reshape product specifications toward higher-purity grades. XiaXian Yunli leverages Shanxi Province's coal-chemical hub to control nitric acid feedstock costs.
United States
EPA effluent guideline revisions for coal-fired power plant wastewater drive retrofit demand across the Ohio River Valley. Zero liquid discharge configurations favor aluminum-based coagulant systems for selenium and mercury removal. Thatcher Group anchors regional supply relationships serving municipal utilities in the Midwest.
Germany
REACH compliance requirements restrict impurity profiles in imported aluminum salts, creating qualification barriers for standard-grade exporters. ECHA protocols elevate procurement standards for electronics-grade specifications. Specialty chemical distributors in the Rhine-Ruhr region consolidate vendor relationships around documented chain-of-custody capabilities.
India
Water treatment infrastructure expansion across industrial corridors elevates coagulant demand amid tightening discharge norms. BIS standards for chemical quality reshape import qualification protocols. Nithyasri Chemicals exemplifies domestic production capacity serving regional textile processing clusters in Gujarat and Maharashtra.
Japan
Semiconductor precursor applications require sub-ppm impurity profiles, opening premium positioning for crystallization-optimized imports. METI industrial standards govern electronics-grade chemical specifications. Osaka-based specialty distributors manage qualification timelines for domestic wafer fabrication facilities.
Aluminum Nitrate Nonahydrate Market Competitive Environment
Chinese producers anchor the volume tier through integrated coal-chemical supply chains; European and North American specialists hold premium positions in pharmaceutical and electronics grades. The vendor base separates into three functional tiers: commodity compounders serving water treatment, integrated producers with captive nitric acid, and certification-intensive specialists. Strategic moves concentrate on crystallization technology licensing and backward integration into nitric acid production.
Within the integrated-production archetype, XiaXian Yunli and Taiyuan Xinyufeng occupy positions near Shanxi Province's coal-chemical infrastructure. Strem Chemicals represents the specialty-grade tier, anchoring laboratory and research segments through stringent quality protocols. These three exemplify how geographic feedstock access and certification depth determine competitive positioning across specification tiers.
| Leading Market Players |
|---|
| XiaXian Yunli |
| Strem Chemicals |
| Taiyuan Xinyufeng |
| Orrion Chemicals |
| Nithyasri Chemicals |
| Chongqing Hua'nan Chemical |
| Taiyuan Bohui Chemical |
| Thatcher Group |
| Shijiazhuang Xuanran Chemical |
| Others |
Value Chain & Pricing Dynamics
China's MEE discharge mandates for industrial wastewater are compressing product specifications toward higher-purity grades, forcing crystallization process upgrades that favor integrated nitric acid producers over merchant compounders and widening price spreads between specification tiers.
Pricing Analysis
Distributor margins absorb three to five percentage points in standard-grade water treatment channels, while direct manufacturer relationships in pharmaceutical and electronics segments eliminate intermediary markups entirely. Three-tier pricing structure across premium, standard, and economy levels separates USP-certified pharmaceutical grades from industrial water treatment specifications, with certification level and volume scale as primary differentiation drivers. Cost compression in standard-grade coagulant tiers is intensifying because polyaluminum chloride substitution pressures conventional aluminum salt procurement. Municipal utilities anchor the most price-sensitive demand segment, while semiconductor precursor buyers exhibit minimal elasticity for sub-ppm purity assurance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Shandong Province's water treatment facilities, while specialty distributors manage qualification-intensive pharmaceutical and electronics procurement. Supply concentrates in China, Germany, and the United States, with Shanxi Province's coal-chemical corridor anchoring captive nitric acid production. Raw material dependencies center on ammonia oxidation feedstocks, aluminum metal or hydroxide precursors, and crystallization process chemicals. Single-source vulnerability in pharmaceutical-grade certification creates supply chain risk for qualified producers serving FDA and EMA jurisdictions. Distribution runs through regional chemical distributors in mature markets and direct manufacturer relationships in specification-driven segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's integrated coal-chemical producers exploit captive nitric acid supply to offset tightening effluent mandates in export markets, creating geographic-arbitrage opportunities against European and North American compounders facing higher compliance-cost structures.
For Market Incumbents: Lock in crystallization engineering expertise through technical team retention and process documentation protocols that few merchant compounders have replicated. Defend against polyaluminum chloride substitution by anchoring rapid flocculation performance claims in documented Ohio River Valley utility retrofit outcomes. Prioritize backward integration into nitric acid production near Shanxi coal-chemical infrastructure to sustain feedstock cost advantages. For New Entrants and Emerging Players: Specialty distributors serving Japan's semiconductor fabrication facilities represent the most accessible channel partner type for qualification-intensive electronics-grade market entry. White-space targets include textile mordant premiumization for digital printing ink compatibility and catalyst precursor convergence with Middle Eastern refinery capacity expansions. Agricultural fertilizer compounders in Shanxi Province offer volume penetration pathways with lower certification barriers than pharmaceutical or electronics segments. For Investors and Strategic Acquirers: Asymmetric upside sits with crystallization-optimized producers possessing documented USP-grade certification and established NMPA registration timelines. Long-term viability over the analysis window favors integrated producers with captive nitric acid supply chains and multi-jurisdiction pharmaceutical registrations. Acquisition target archetypes include regional Chinese compounders with MEE-compliant production lines and underdeveloped export qualification protocols. Watch EPA effluent guideline revision implementation timelines across coal-fired power plant wastewater systems as inflection indicators for coagulant demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive nitric acid production near Shanxi coal-chemical hubs insulates margin stability from ammonia oxidation feedstock volatility. |
| Pharmaceutical-Grade Certification | USP-grade specifications for diagnostic reagent applications command pricing multiples that justify extended FDA and EMA registration timelines. |
| Continuous Crystallization Technology | Real-time purity monitoring and reduced energy intensity per ton produced separate technical leaders from batch-process competitors. |
| Long-term Supply Agreement | Municipal water treatment authorities in China's Yangtze River Delta consolidate vendor relationships around documented chain-of-custody capabilities. |
| Joint Venture | Partnerships with Osaka-based specialty distributors accelerate qualification timelines for Japan's semiconductor precursor market entry. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant managers at aluminum nitrate production facilities, procurement leads at municipal water treatment utilities, distribution channel partners serving chemical manufacturing corridors, and technical R&D directors at specialty compounders were cross-validated against secondary sources including Chinese customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and MEE discharge standard documentation. This triangulation between demand-side consumption patterns and supply-side capacity utilization ensures statistical integrity across volume and value estimations.
Input-output matrices map nitric acid feedstock availability through crystallization capacity to end-use consumption across water treatment, pharmaceutical, electronics, and catalyst applications. Segmentation dimensions modeled include hydrate form specification, end-user industry archetype, functional application, and packaging configuration across the projection horizon. CAGRs were derived from regression analysis of historical procurement cycles and forward-looking regulatory implementation schedules, with specific weighting applied to MEE mandate acceleration timelines and EPA effluent guideline revision phases.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nitric acid price volatility, REACH impurity protocol amendments, and polyaluminum chloride substitution rates in municipal procurement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
United States Iodine Market
Bulk Chemicals
Potassium Sulphate Market
Bulk Chemicals
Pivaloyl Chloride Market
Bulk Chemicals
Cellulose Powder Market
Bulk Chemicals
Lactic Acid Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
Mesifurane Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
Global Vanadium Pentoxide Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Benzyl Chloroformate Market