
 Speciality Pulp and Paper Chemicals Market | 2026-2036
Speciality Pulp and Paper Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Speciality Pulp and Paper Chemicals Market Analytics
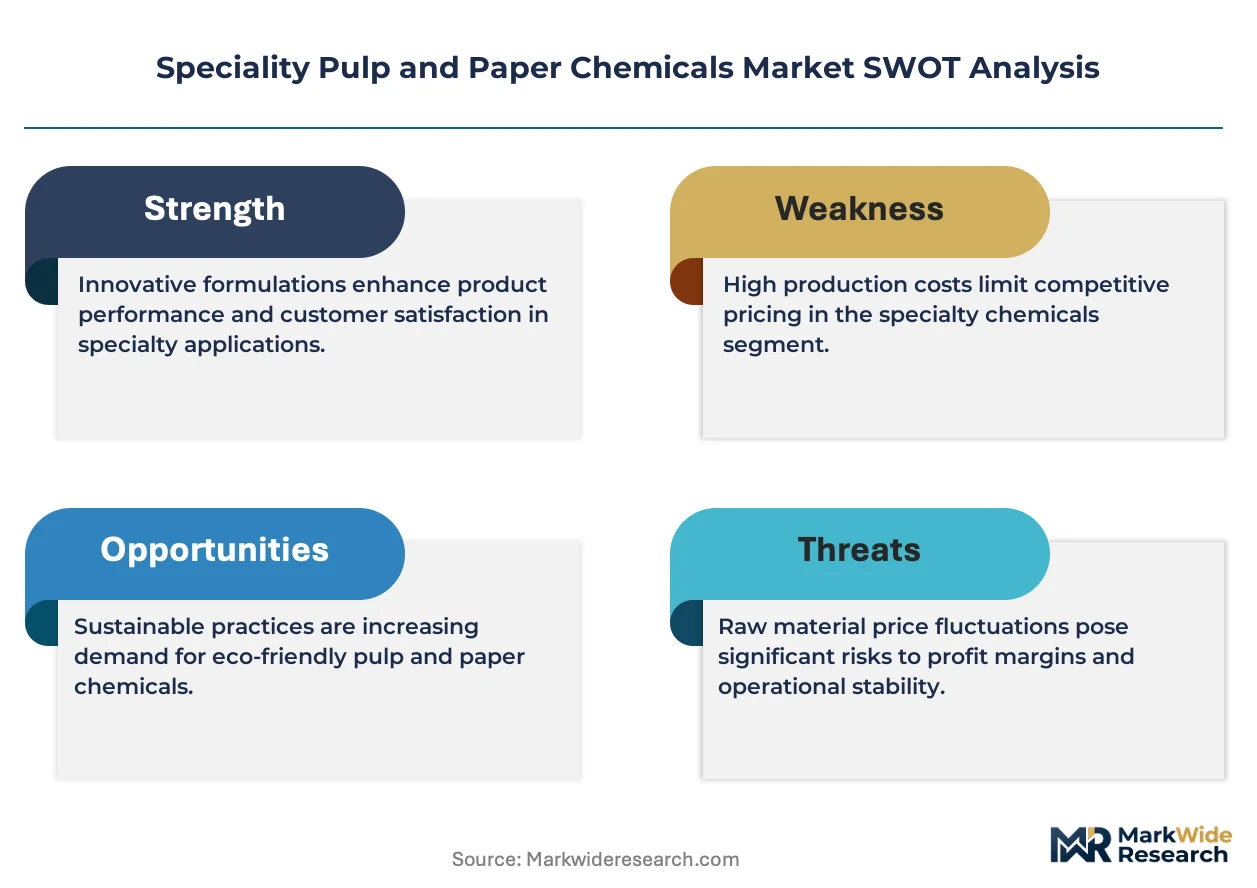
The EU Green Deal is repositioning specialty pulp and paper chemicals toward bio-based and low-chlorine alternatives across European mill networks. Kemira Oyj anchors its position through deep R&D intensity in wet-end chemistry and bleaching optimization. Solenis differentiates via service-led models that integrate chemical supply with process control systems. BASF SE leverages its backward integration into acrylic acid and amine chemistry to sustain margin pools in sizing and coating segments.
Speciality pulp and paper chemicals comprise functional additives, process aids, and finishing agents formulated to modify fiber bonding, surface properties, and optical performance during pulp processing and paper manufacture; these formulations typically operate at dosage rates of 0.1–5.0 kg per tonne of finished paper depending on target functionality. Their primary purpose centers on enabling mills to meet precise end-use specifications for strength, printability, barrier performance, and regulatory compliance without rebuilding capital-intensive machinery. Coating chemicals command the largest value share due to their role in producing high-gloss publication and label grades where kaolin and calcium carbonate binders must integrate with latex and dispersant systems. Bleaching agents represent the fastest-growing product category as mechanical pulp producers in Nordic regions shift from elemental chlorine toward peroxide and ozone sequences under tightening effluent rules. Retention aids concentrate margin attention because cationic polyacrylamide systems allow mills to reduce freshwater intake and capture expensive filler particles that would otherwise exit through white water loops.
EPA effluent limitation guidelines in the United States restrict adsorbable organic halogen discharge from bleached kraft mills, directly shaping chemical procurement toward TCF and ECF bleaching sequences. REACH registration requirements and the EU F-Gas Regulation constrain which fluorinated barrier chemistries may enter European coating formulations, while China's MEE standards on wastewater COD and AOX push domestic mills toward imported specialty chemical packages. Stakeholders must monitor how pending revisions to OECD chemical hazard classifications and country-specific packaging waste directives will redraw permissible chemistries for food-contact paper grades.
Market Dynamics
REACH restrictions on chlorinated chemistries are forcing European mills to dismantle legacy bleaching sequences and rebuild wet-end chemistry stacks around peroxide and ozone alternatives.
Growth Catalysts
- EU Green Deal chemical recovery mandates:Integrated pulp-paper-board clusters in Germany invest in closed-loop systems that recapture process chemicals, pulling demand for advanced retention aids and dispersant packages.
- Food-contact packaging specifications:Specialty barrier coatings for medical and food-grade paper grades require fluorine-free formulations that comply with tightening EU F-Gas Regulation limits.
- Nordic peroxide bleaching transition:Mechanical pulp producers across Sweden and Finland replace elemental chlorine sequences with TCF systems, expanding consumption of hydrogen peroxide stabilizers and chelating agents.
Market Restraints
- Petrochemical feedstock volatility:Acrylic acid and amine precursors for sizing agents fluctuate with crude oil indices, compressing margin pools for coating chemical formulators.
- Fluorinated chemistry substitution timeline:REACH registration barriers and OECD hazard reclassifications delay commercialization of next-generation barrier chemistries for grease-resistant grades.
- White water system complexity:Cationic polyacrylamide retention aids face performance ceilings in high-conductivity loops where dissolved organic content interferes with charge density.
Strategic Opportunities
- Bio-based wet-end chemistry white space:Starch derivatives and cellulose nanofibrils offer renewable alternatives to synthetic dry-strength resins in premium packaging segments.
- Service-integrated chemical supply models:Process control system vendors bundle dosing automation with chemical procurement, capturing mill operating data to optimize dosage rates.
- China MEE wastewater compliance:Domestic mills importing specialty chemical packages to meet COD and AOX discharge standards create openings for Western formulators with proven ECF sequence expertise.
Industry Challenges
- Formulation requalification timelines:Mill certification cycles for food-contact grades under EU Framework Regulation 1935/2004 extend 18-24 months, freezing supplier switches.
- Cross-functional chemistry expertise scarcity:Wet-end optimization requires simultaneous command of colloid chemistry, papermaking physics, and regulatory compliance that few technical specialists possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speciality Pulp and Paper Chemicals Market |
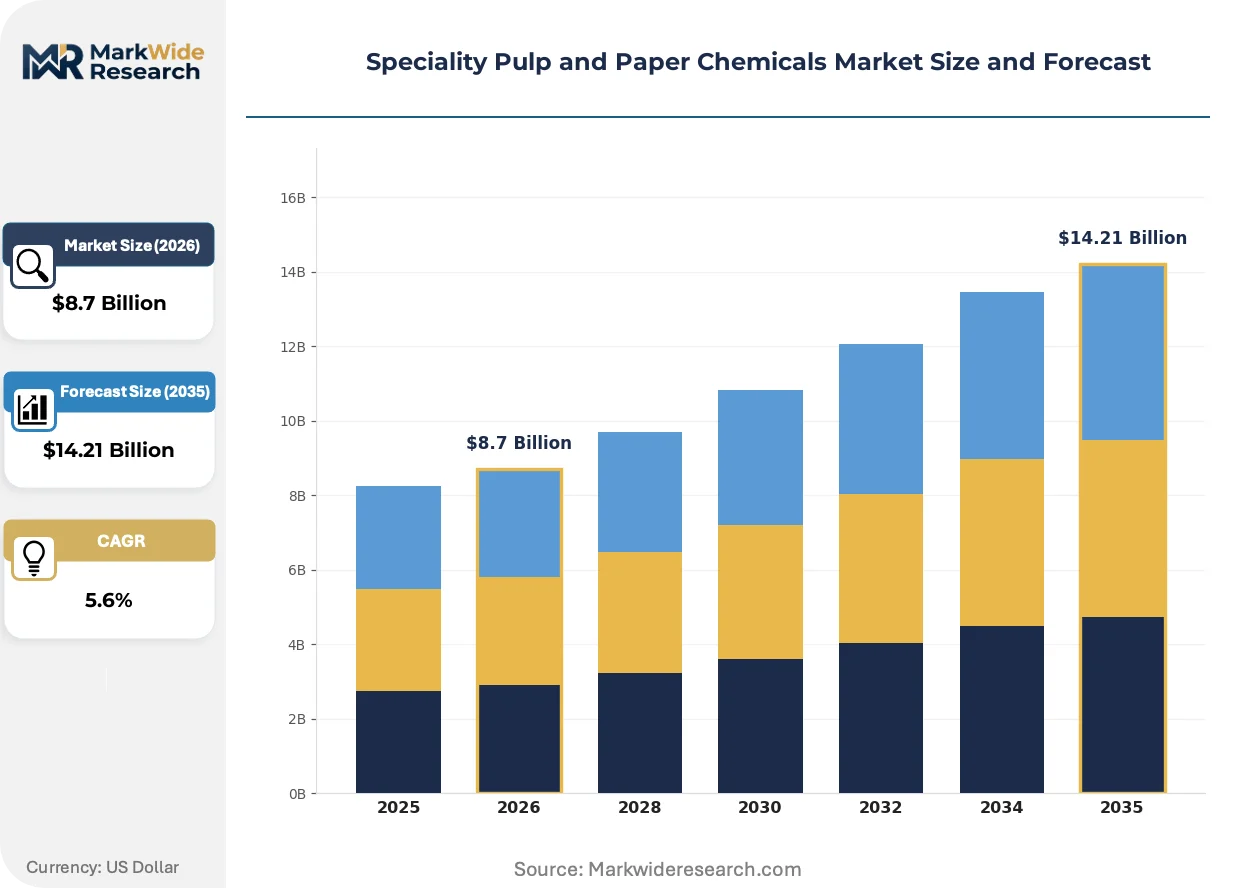
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bleaching Agents, Sizing Agents, Coating Chemicals, Retention Aids Application: Coated Paper, Uncoated Paper, Specialty Paper, Corrugated Packaging End User: Pulp Mills, Paper Manufacturers, Packaging Industry, Printing Industry Functionality: Strength Enhancers, Barrier Solutions, Surface Modifiers, Additives |
| Companies Covered | BASF SE, Ecolab, Solenis, Kemira Oyj, Buckman Laboratories International, Ashland Inc., Nouryon, Dow Chemical Company, SNF Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speciality Pulp and Paper Chemicals Market Evolving Landscape
Digital process control systems are converging with chemical supply contracts, reshaping how mills procure and optimize specialty additives in real-time production environments.
Enzymatic pitch control systems are electrifying machine runnability in recycled fiber lines. Packaging mills running mixed recovered paper grades deploy lipase and esterase formulations to deposit control. This technology is electrifying maintenance schedules and reducing broke generation rates in high-speed corrugating medium machines.
EPA effluent limitation guidelines on adsorbable organic halogen discharge are compressing permissible bleaching chemistries in US kraft mills. The rules explicitly favor TCF and ECF sequences over elemental chlorine. Southern bleached kraft producers respond by retrofitting bleach plants with ozone and peroxide stages, expanding demand for stabilizer chemistries.
Buyers increasingly unbundle chemical supply from equipment vendor packages, creating direct procurement channels with specialty formulators. Mid-size independent mills in the US Southeast and Nordic regions lead this disintermediation, negotiating performance-based contracts tied to specific paper quality metrics rather than tonnage-based supply agreements.
Speciality Pulp and Paper Chemicals Market Segmentation
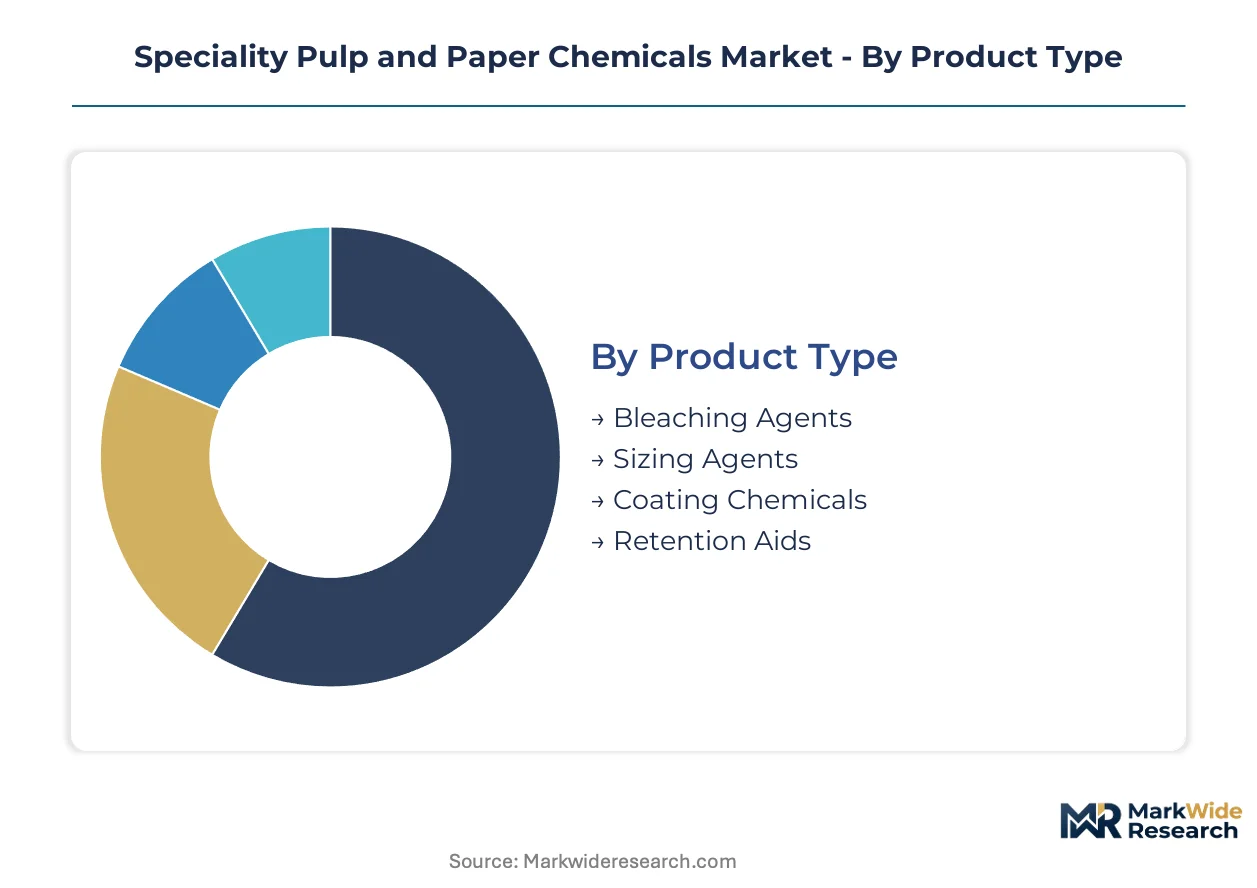
Specialty pulp and paper chemicals serve distinct process stages where dosage precision and formulation compatibility determine mill efficiency. Segmentation reveals how chemical suppliers align R&D portfolios with specific fiber processing and finishing requirements.
Product Type:
Upgrade cycles in European bleaching infrastructure are redrawing procurement patterns across product categories as mills dismantle legacy chlorine-based systems.
- Bleaching Agents:Peroxide, ozone, and chlorine dioxide formulations enable TCF and ECF sequences mandated by EU Green Deal effluent rules. Nordic mechanical pulp producers in Sweden and Finland drive hydrogen peroxide stabilizer consumption as elemental chlorine sequences phase out under tightening AOX discharge limits.
- Coating Chemicals:Latex binders, kaolin dispersants, and calcium carbonate packages command premium value in high-gloss publication and label grades. German integrated pulp-paper-board clusters invest heavily in coating formulations that integrate with closed-loop chemical recovery systems.
- Sizing Agents:Alkyl ketene dimer and alkenyl succinic anhydride chemistries control liquid penetration in printing and packaging grades.
- Retention Aids:Cationic polyacrylamide systems capture filler particles and reduce freshwater intake in white water loops.
Coating chemicals sit at the top of the volume ranking, with bleaching agents climbing the fastest as regulatory deadlines accelerate substitution timelines.
Application:
Cost tier differentiation separates commodity packaging from premium grades where chemical specifications tighten measurably.
- Specialty Paper:Food-contact and medical packaging grades require fluorine-free barrier coatings compliant with EU F-Gas Regulation limits. REACH registration barriers on legacy fluorinated chemistries force reformulation toward bio-based alternatives in German and Nordic mill networks.
- Corrugated Packaging:Recycled fiber lines consume enzymatic pitch control and dry-strength additives to maintain runnability. US Southeast independent mills negotiate performance-based contracts tied to specific burst strength and ring crush metrics rather than tonnage-based supply agreements.
- Coated Paper:Publication grades depend on uniform surface treatment for high-resolution printing.
- Uncoated Paper:Office and communication papers prioritize opacity and printability through internal sizing and filler optimization.
Corrugated packaging dominates shipment volumes, while specialty paper expands most quickly on food-contact certification requirements.
End User:
Customer type determines procurement sophistication, with integrated clusters commanding bundled service models that smaller independents cannot replicate.
- Packaging Industry:Converters running high-speed corrugating medium machines specify enzymatic deposit control and strength chemistries to reduce broke generation. US Southeast and Nordic mid-size independents increasingly unbundle chemical supply from equipment vendor packages, creating direct channels with specialty formulators.
- Pulp Mills:Bleached kraft producers retrofit bleach plants with ozone and peroxide stages under EPA effluent limitation guidelines on adsorbable organic halogen discharge. Southern US mills expand stabilizer consumption as TCF and ECF sequences displace elemental chlorine.
- Paper Manufacturers:Integrated producers balance wet-end chemistry optimization against capital-intensive machinery constraints.
- Printing Industry:Commercial printers demand consistent surface properties through press-ready paper specifications.
Packaging industry buyers represent the largest procurement volume, with pulp mills gaining share fastest on bleaching infrastructure overhaul cycles.
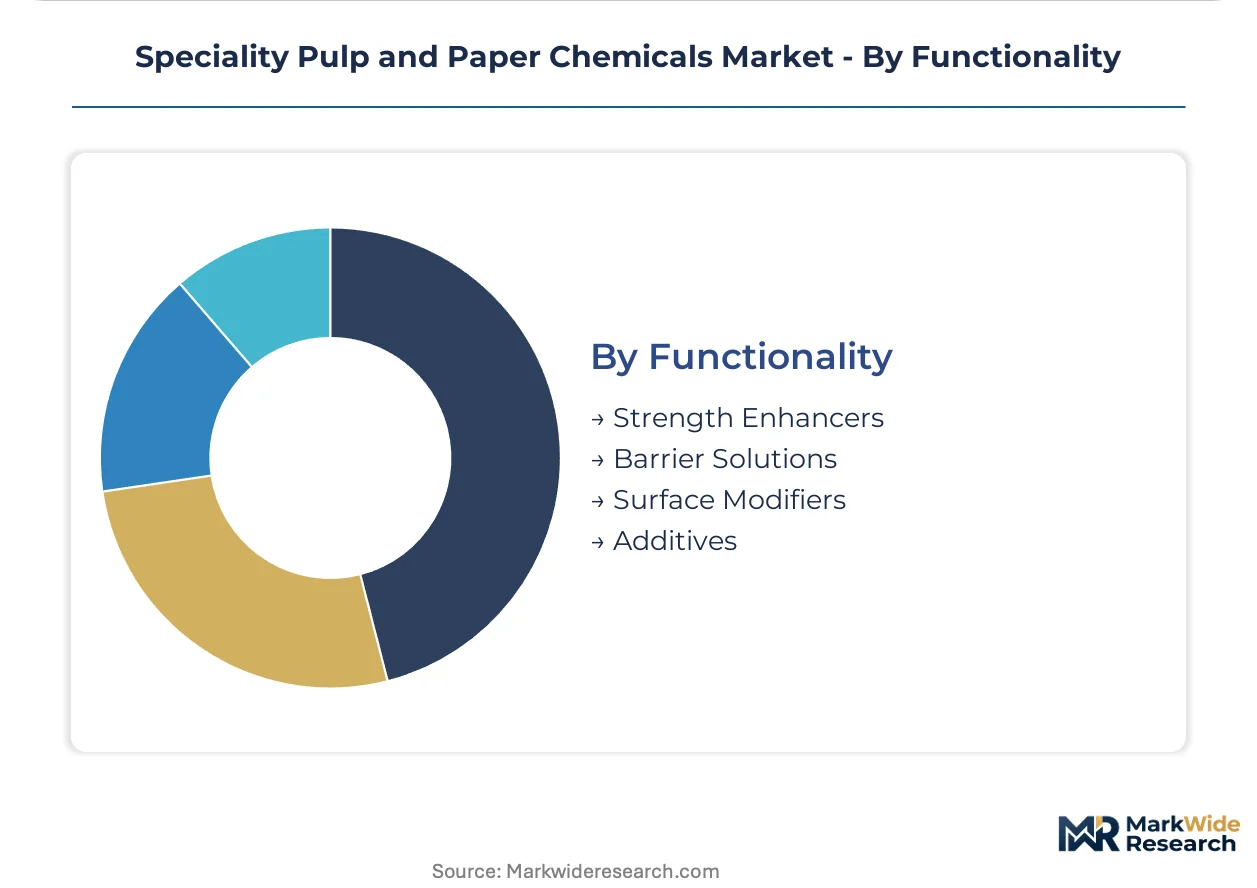
Functionality:
Margin concentration tracks toward chemistries that solve multiple process constraints simultaneously rather than single-attribute additives.
- Barrier Solutions:Grease-resistant and moisture-blocking formulations for food-contact grades face extended requalification timelines under EU Framework Regulation 1935/2004. Mill certification cycles stretching 18-24 months freeze supplier switches and favor incumbents with established compliance dossiers.
- Strength Enhancers:Dry-strength resins and wet-end starch derivatives enable lightweighting in premium packaging segments. Bio-based cellulose nanofibrils offer renewable alternatives to synthetic chemistries as sustainability specifications tighten in European markets.
- Surface Modifiers:Optical brighteners and calendering aids control appearance and print receptivity.
- Additives:Defoamers, biocides, and deposit control agents protect machine runnability.
Barrier solutions command the steepest pricing tiers, with strength enhancers expanding most quickly on lightweighting demands in e-commerce packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The specialty pulp and paper chemicals industry traces its modern scaling to German industrial chemistry clusters of the late 19th century, where integrated paper mills first systematized wet-end additive formulations. Contemporary demand geography reflects this legacy while incorporating new regulatory and sustainability imperatives across diverse national markets.
Germany
Integrated pulp-paper-board clusters in Baden-Württemberg and North Rhine-Westphalia anchor European demand for closed-loop chemical recovery systems. EU Green Deal mandates on circular economy implementation drive mill investment in advanced retention aids and dispersant packages. The Rhine-Ruhr industrial corridor hosts concentrated R&D facilities where formulators collaborate with machinery OEMs on process-integrated chemical delivery.
United States
Southern bleached kraft producers in Georgia and Alabama retrofit bleach plants with ozone and peroxide stages under EPA effluent limitation guidelines restricting adsorbable organic halogen discharge. The US Southeast's independent mid-size mills increasingly unbundle chemical supply from equipment vendor packages, negotiating performance-based contracts tied to burst strength metrics. Appalachian recycled fiber lines consume enzymatic pitch control formulations to maintain corrugating medium runnability.
China
Domestic mills in Shandong and Guangdong provinces import specialty chemical packages to meet MEE wastewater standards on COD and AOX discharge. Yangtze River Delta packaging producers deploy barrier coatings for food-contact grades compliant with evolving national food safety frameworks. State-owned enterprises in the Pearl River Delta region invest in ECF sequence expertise through technology licensing arrangements with Western formulators.
Sweden
Mechanical pulp producers across Värmland and Norrland regions replace elemental chlorine sequences with TCF systems, expanding hydrogen peroxide stabilizer and chelating agent consumption. REACH restrictions on chlorinated chemistries accelerate mill dismantling of legacy bleaching infrastructure. Stockholm-based chemical suppliers coordinate Nordic-wide distribution networks serving integrated forest products companies.
Finland
Export-oriented pulp mills in Kymenlaakso and Central Finland optimize wet-end chemistry for premium packaging grades bound for EU food-contact applications. The country's national pharmaceutical regulator influences migration testing protocols for barrier coatings in medical packaging. Tampere metropolitan area hosts concentrated technical service operations supporting peroxide bleaching transitions across the Baltic region.
Speciality Pulp and Paper Chemicals Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a moderately consolidated structure where integrated chemical majors and specialized papermaking formulators coexist. The vendor base separates into three strategic archetypes: diversified industrial chemical conglomerates with backward integration into precursor synthesis; pure-play pulp and paper specialists delivering process-integrated service models; and regional compounders serving single-mill or single-country accounts. Dominant competitive moves include portfolio diversification into bio-based alternatives and geographic expansion through technical service center establishment in high-growth Asian markets.
Among Nordic-based formulators, Kemira Oyj and Solenis occupy positions exemplifying the specialist archetype through deep wet-end chemistry expertise and service-led customer engagement. BASF SE anchors the diversified conglomerate tier, leveraging captive supply of acrylic acid and amine precursors to sustain formulation margins. These three entities represent distinct strategic postures: integrated upstream control, process optimization services, and hybrid chemical-equipment bundling respectively.
| Leading Market Players |
|---|
| BASF SE |
| Ecolab |
| Solenis |
| Kemira Oyj |
| Buckman Laboratories International |
| Ashland Inc. |
| Nouryon |
| Dow Chemical Company |
| SNF Group |
| Others |
Value Network & Pricing Analysis
Acrylic acid spot indices and amine precursor benchmarks cascade through specialty pulp and paper chemical supply chains, compressing margin pools for coating formulators while concentrating pricing power with backward-integrated conglomerates that command captive precursor supply. German integrated pulp-paper-board clusters leverage closed-loop recovery systems to negotiate volume-based discounts on retention aids, whereas mid-size Nordic independents absorb premium markups on peroxide stabilizers amid petrochemical volatility.
Pricing Analysis
Contract-based long-term offtake arrangements with performance guarantees dominate procurement between integrated mills and major formulators, separating premium-certified food-contact grades from standard industrial chemistries on the basis of REACH compliance depth and EU Framework Regulation 1935/2004 migration testing completeness. Price differentiation tracks certification tier and volume scale, with fluorine-free barrier coatings commanding substantial premia over legacy formulations. Cost compression in standard coating chemistries is intensifying because acrylic acid feedstock volatility transmits directly into alkyl ketene dimer and latex binder production economics. Mid-size independent mills in the US Southeast exhibit highest price sensitivity due to unbundled procurement and absence of captive chemical recovery infrastructure.
Supply Chain Analysis
EU Framework Regulation 1935/2004 certification cycles stretching 18-24 months gate supplier entry and freeze incumbent relationships across food-contact grade supply chains, embedding qualification risk as a structural barrier to sourcing flexibility. Supply concentrates in Germany, Sweden, and the United States, with Nordic mechanical pulp producers and Southern US bleached kraft mills anchoring demand for peroxide stabilizers and ozone-stage chemistries. Raw material dependencies draw from petrochemical feedstocks, kaolin deposits, and bio-based starch derivatives, exposing formulators to crude oil index correlation and agricultural commodity swings. Single-source vulnerability concentrates in cationic polyacrylamide monomer supply, where specialty monomer producers maintain tight oligopoly positions. Distribution runs through direct mill technical service relationships rather than distributor intermediaries, with formulators embedding field chemists at major customer sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialty pulp and paper chemicals market reads as a late-cycle quality story where formulation expertise and regulatory compliance depth increasingly separate viable suppliers from commodity formulators, with food-contact packaging specifications and EU Green Deal mandates pulling procurement toward premium-certified chemistries that command durable margin structures.
For Market Incumbents: Acquire bio-based wet-end chemistry R&D pipelines and peroxide stabilizer formulation libraries to preempt substitution threats from enzymatic deposit control systems and cellulose nanofibril alternatives. Deepen technical service presence in German integrated clusters to defend against disintermediation by independent mills unbundling supply from equipment vendors. Prioritize backward integration into acrylic acid and amine precursor production to insulate margin pools from petrochemical volatility.
For New Entrants and Emerging Players: Capture white space in China MEE wastewater compliance segments where domestic mills import ECF sequence expertise from Western formulators with proven AOX reduction credentials. Target enzymatic pitch control formulations for US Southeast recycled fiber lines running mixed recovered paper grades, where performance-based contracts tied to burst strength metrics create entry paths outside incumbent tonnage-based relationships. Lead with service-integrated chemical supply models bundling dosing automation with procurement to capture mill operating data and optimize dosage rates.
For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play pulp and paper specialists possessing deep wet-end chemistry expertise and established EU Framework Regulation 1935/2004 compliance dossiers that freeze competitor switching. Long-term viability across the analysis window favors formulators with demonstrated peroxide bleaching transition capabilities and fluorine-free barrier coating commercialization track records. Watch pending OECD chemical hazard reclassifications as the inflection signal that will redraw permissible chemistries and trigger reformulation cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Captive acrylic acid and amine supply insulates BASF margin pools from crude oil volatility. |
| Service-Integrated Chemical Supply Models | Solenis bundles dosing automation with procurement to capture German mill operating data. |
| Fluorine-Free Barrier Coating Development | REACH F-Gas compliance enables premium positioning in EU food-contact packaging segments. |
| Technical Service Center Establishment | Kemira anchors Nordic peroxide bleaching transitions through Tampere metropolitan operations. |
| Bio-Based Wet-End Chemistry R&D | Cellulose nanofibril alternatives capture lightweighting demand in European e-commerce packaging. |
Research Methodology
Multiple input streams — primary interviews with mill procurement directors and technical R&D heads, trade data from Cefic and American Chemistry Council reports, and SEC 10-K chemical segment disclosures — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates. Conversations with wet-end chemists at integrated German clusters, independent Nordic mechanical pulp producers, and Southern US bleached kraft operators supplied qualitative calibration on peroxide bleaching transition timelines and fluorine-free barrier coating adoption rates. Secondary validation drew from EU ECHA registration databases, EPA effluent guideline dockets, and China MEE wastewater standard enforcement records.
Historical capacity utilization and chemical dosage rate trajectories were cross-referenced against expert panel inputs on EU Green Deal implementation pacing to anchor growth assumptions across the projection horizon. Segmentation modeling captured product type, application grade, end-user procurement sophistication, and functionality performance tier, with CAGRs derived from slope consistency checks against bleaching infrastructure overhaul cycles and food-contact certification expansion patterns. Industry-specific forecast inputs included Nordic TCF sequence conversion schedules and China domestic mill import dependency ratios for specialty ECF packages.
Underlying measurement precision varies by segment; coating chemicals and bleaching agents carry tighter precision than deposit control additives due to more transparent trade flow reporting and established customs classification. Forecasts reflect assumptions on REACH enforcement intensity, OECD hazard reclassification timing, and petrochemical feedstock correlation persistence that could shift materially with regulatory acceleration or crude oil dislocation. A model refresh is warranted upon material change in EU Framework Regulation 1935/2004 migration testing protocols or China MEE wastewater standard revision implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Duplex Paper and Board Market
Paper Products
Billing Paper Market
Paper Products
Office Printing Papers Market
Paper Products
Printing and Writing Papers Market
Paper Products
Global Paper Chemical Market
Paper Products
Sawn Wood Market
Paper Products
Pulp and Paper Market
Paper Products
Global Security Paper Market
Paper Products
Specialty Paper Market
Paper Products
Thermal Paper Market
Paper Products
Global Electrical Insulation Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Global Paperboard Market
Paper Products
Fluff Pulp Market
Paper Products
Semi Chemical Wood Pulp Market
Paper Products
Latex-Saturated Paper Market