
 Coal Tar Market | 2026-2036
Coal Tar Market Size, Share, and Industry Trends Forecast 2026-2036
Coal Tar Market Analysis
Chinese coking plant expansions is broadening feedstock availability for tar distillers across Asia. Koppers Inc. leverages its integrated carbon materials and chemicals platform to sustain North American supply continuity. Himadri Speciality Chemicals Ltd anchors Indian demand through its specialty pitch and carbon black operations. Mitsubishi Chemical Corporation dominates high-purity carbon precursor segments for lithium-ion battery anodes.
Coal tar is a thick, dark liquid byproduct of high-temperature carbonization of bituminous coal, containing phenols, naphthalene, anthracene, and heterocyclic aromatics with boiling ranges from 200°C to over 400°C; it serves as the primary feedstock for producing binder pitch, creosote preservatives, and carbon black feedstock. Pitch fractions command the deepest value pools due to their irreplaceable role in aluminum smelting anodes and graphite electrode manufacturing. Creosote oil competes in wood preservation against copper-based alternatives, while carbon black from tar distillate leads automotive tire reinforcement applications. Thermal cracking technology is displacing conventional distillation in newer facilities seeking higher naphthalene and light oil yields.
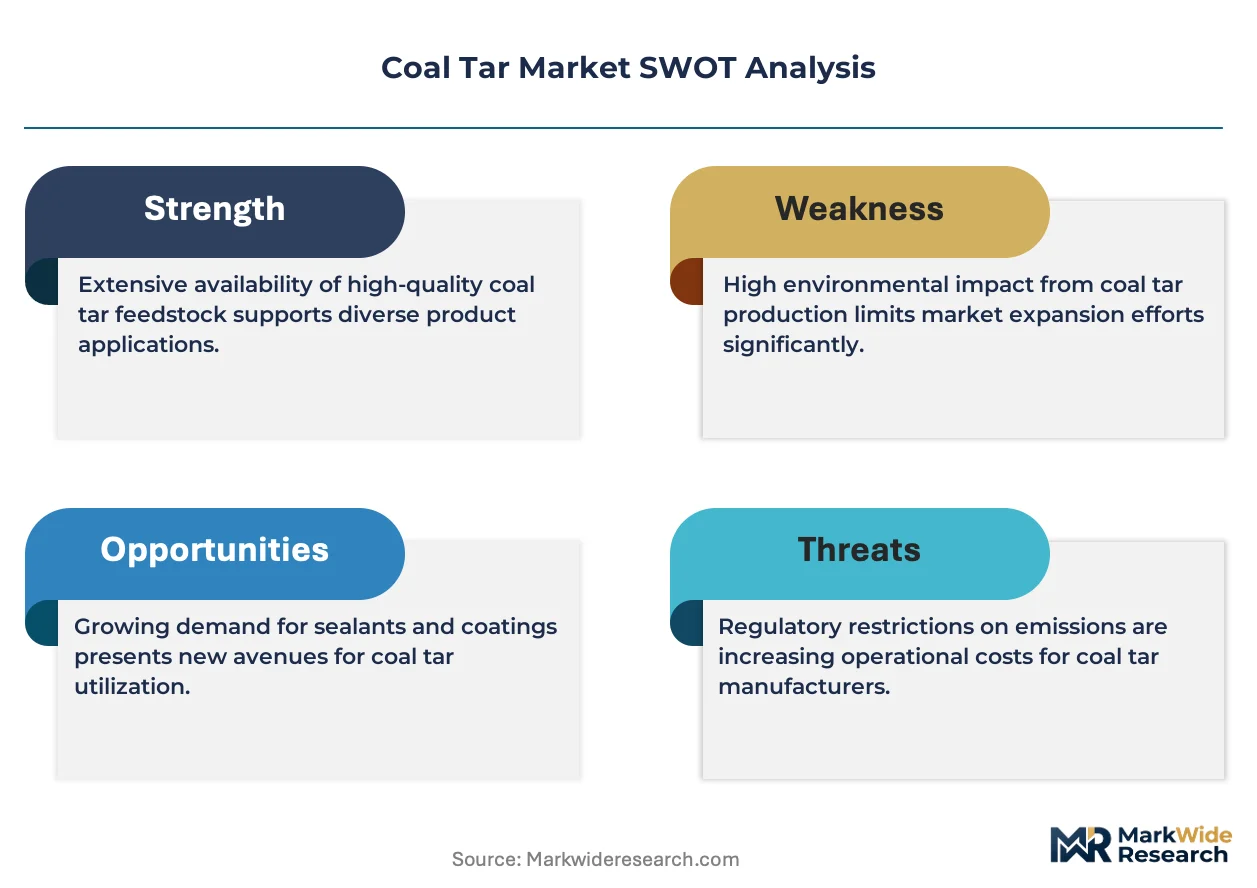
EPA regulations restrict creosote use in residential and aquatic applications, while REACH classifications in Europe impose stringent PAH labeling and handling protocols for coal tar pitch. OSHA workplace exposure limits and BIS quality standards in India further fragment compliance burdens across producer geographies. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate product reformulation costs and access restrictions.
Market Dynamics
Steel production concentration in China and tightening polycyclic aromatic hydrocarbon limits across multiple jurisdictions are compressing feedstock availability while forcing distillers toward higher-refinement processing investments.
Growth Catalysts
- REACH PAH thresholds:European ECHA classifications are accelerating demand for refined pitch grades that meet stricter labeling protocols, pulling capacity toward premium carbon precursor production.
- Aluminum smelter anode specifications:Smelters in the Middle East and India are tightening binder pitch quality requirements, sustaining volume commitments despite feedstock cost pressures.
- Thermal cracking adoption:Newer coking facilities are deploying cracking technology to boost naphthalene and light oil yields from conventional tar streams.
Market Restraints
- Bituminous coal supply concentration:Coking coal availability hinges on Chinese steel sector output cycles, exposing tar distillers to feedstock interruption risks.
- Copper-based wood preservatives:Creosote oil faces substitution pressure from copper azole and micronized copper systems in residential and marine applications.
- EPA aquatic use restrictions:United States environmental rules prohibit creosote in waterfront piling and residential fencing, eliminating traditional demand channels.
Strategic Opportunities
- India specialty pitch demand:Domestic aluminum capacity expansion and graphite electrode manufacturing are creating pull for high-softening-point binder grades.
- Lithium-ion battery anode precursors:Needle coke and mesophase pitch for electric vehicle battery anodes represent emerging high-value applications.
- EU Green Deal carbon border adjustments:Import tariff mechanisms favor locally produced tar derivatives over carbon-intensive imports from less regulated jurisdictions.
Industry Challenges
- Distillation engineering expertise:Fractionation optimization for naphthalene and anthracene recovery requires specialized chemical process skills in short supply.
- Multi-jurisdiction compliance synchronization:Producers must reconcile OSHA exposure limits, BIS quality standards, and REACH labeling into unified operational protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal Tar Market |
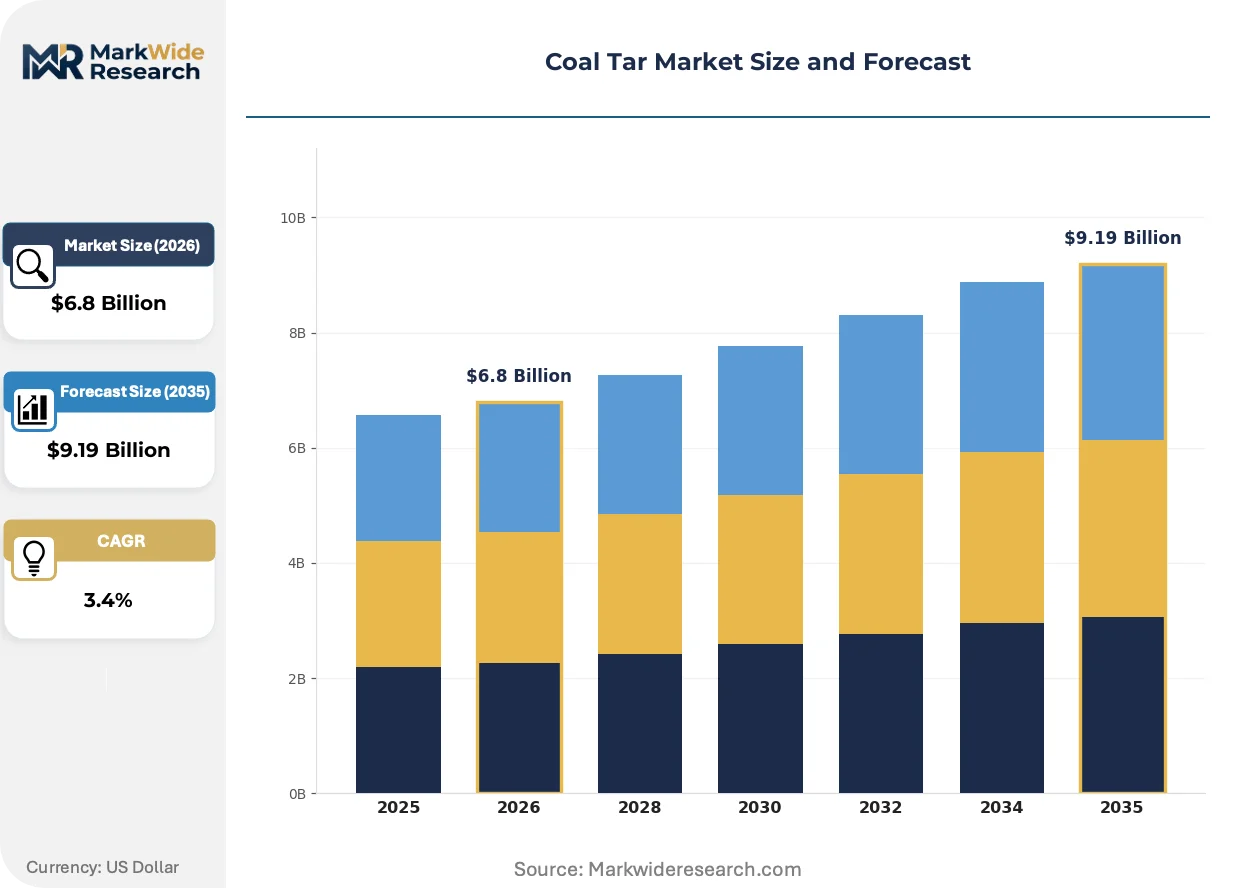
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.19 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pitch, Creosote Oil, Coal Tar Distillate, Carbon Black Application: Pavements, Roofing, Wood Preservation, Adhesives End User: Construction, Automotive, Pharmaceuticals, Chemical Processing Technology: Fractionation, Carbonization, Distillation, Thermal Cracking |
| Companies Covered | Mitsubishi Chemical Corporation, DEZA a.s., Rain Carbon Inc., Epsilon Carbon Pvt. Ltd., Bilbaina de Alquitranes S.A., Koppers Inc., JFE Chemical Corporation, Coopers Creek Chemical Corp., Himadri Speciality Chemicals Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal Tar Market Emerging Trajectories
Tar processing technology is pivoting toward higher-value carbon material outputs as conventional preservative and fuel applications face regulatory compression. Three developments are restructuring competitive positioning.
Advanced thermal cracking systems are converging with conventional atmospheric distillation to maximize light aromatic recovery. Aluminum smelters and carbon black producers are piloting these hybrid configurations in newer Asian facilities. The technology is converging with downstream quality demands by enabling tighter control over pitch softening points and quinoline insoluble content.
REACH authorization requirements for coal tar pitch are forcing reformulation investments across European operations. ECHA's persistent organic pollutant assessments are extending compliance timelines for creosote-containing products. German and Dutch tar distillers are accelerating shift toward electrode binder and specialty carbon precursor grades to escape restricted substance classifications.
Buyer consolidation among aluminum smelters is compressing procurement cycles and tightening specification enforcement. Long-term offtake agreements are replacing spot market purchases in Middle Eastern and Indian smelter supply chains. This concentration is most visible in the Persian Gulf, where integrated aluminum complexes are demanding captive pitch supply arrangements with guaranteed impurity ceilings.
Coal Tar Market Segmentation
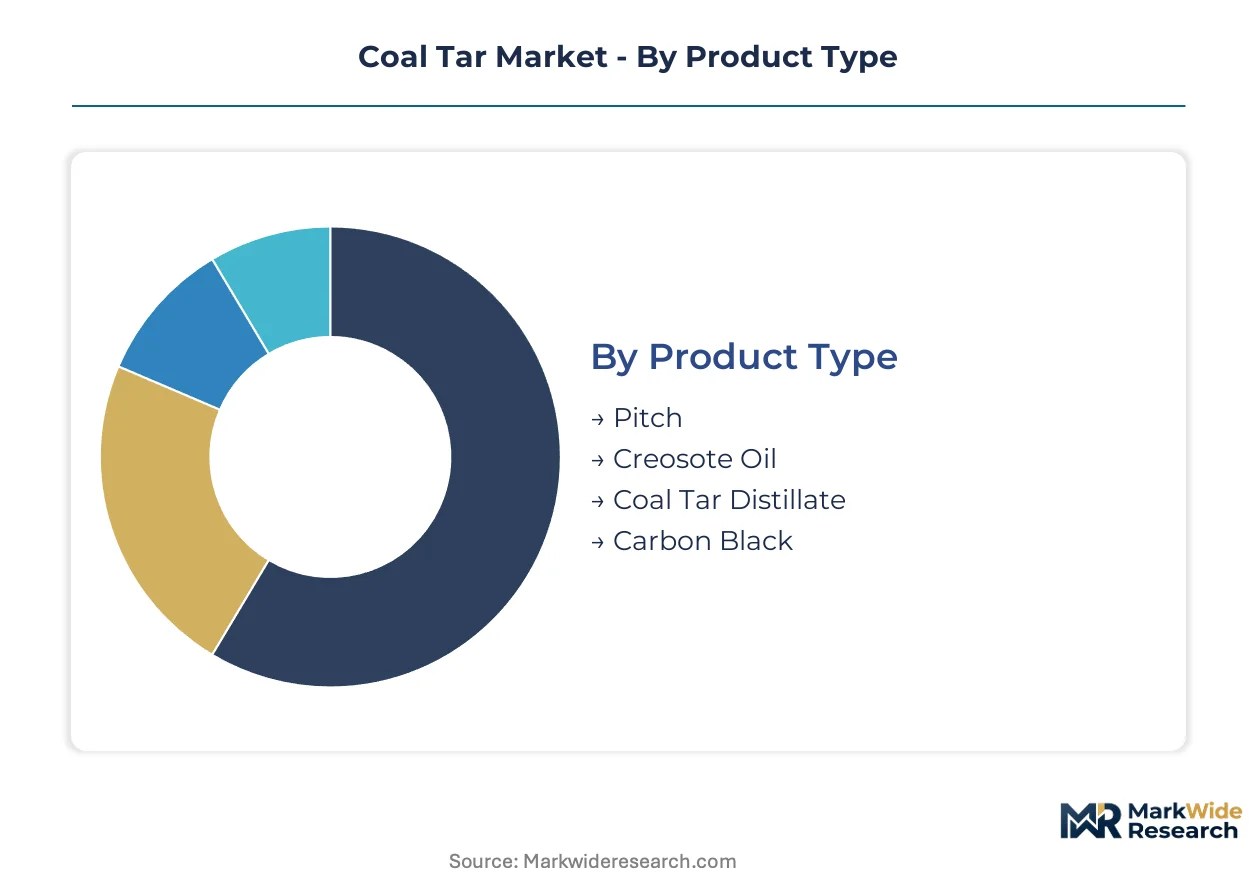
Coal tar derivatives serve divergent value chains with incompatible specification requirements. Product-grade differentiation determines whether output flows into commodity carbon black or premium battery anode precursors.
Product Type:
Upgrade cycles in aluminum smelting and electric vehicle manufacturing are forcing product-tier realignment across tar distillers.
- Pitch:Binder pitch contains condensed aromatic hydrocarbons with softening points from 110°C to 150°C, serving aluminum smelting anodes and graphite electrodes. Indian and Middle Eastern smelters are tightening quinoline insoluble specifications, pulling capacity toward high-purity electrode grades.
- Creosote Oil:A complex mixture of polycyclic aromatic hydrocarbons distilled between 200°C and 400°C, historically dominant in railway tie and marine piling preservation. EPA aquatic use restrictions and copper azole substitution are compressing demand in North American residential applications.
- Coal Tar Distillate:Intermediate fraction yielding naphthalene, anthracene, and heterocyclic bases for dye and pesticide synthesis. Chemical processors in China leverage steel-byproduct availability to sustain downstream aromatic production.
- Carbon Black:Furnace-grade material from tar oil cracking reinforces automotive tires and industrial rubber. Tire manufacturers are shifting toward oil-furnace carbon black for cleaner PAH profiles under REACH protocols.
Pitch sits at the top of the volume ranking, with carbon black climbing the fastest on battery anode precursor demand.
Application:
Cost-tier differentiation separates specification-grade binders from commodity preservative applications.
- Pavements:Coal tar emulsions provide thermoplastic binders for highway seal coats and airport runways. State transportation departments in the United States are specifying polymer-modified tar emulsions for superior rut resistance under heavy axle loads.
- Roofing:Saturated felt and built-up membrane systems rely on coal tar pitch for waterproofing durability. Commercial building codes in Germany and the Netherlands are restricting PAH content in roofing materials under ECHA classification protocols.
- Wood Preservation:Creosote-impregnated timber serves utility poles, railway ties, and marine structures. Copper-based alternatives are capturing residential fencing and playground equipment markets previously served by tar oil treatments.
- Adhesives:Tar-derived resins bind carbon electrodes and refractory materials in high-temperature applications. Specialty adhesive formulators are developing low-PAH tar-modified phenolics for automotive brake lining composites.
Pavements command the largest application volume, while adhesives gain share fastest on electrode manufacturing expansion.
End User:
Customer-type concentration shapes procurement sophistication and contract structure across downstream sectors.
- Construction:Infrastructure contractors consume pavement binders, roofing membranes, and preservative-treated timber. Municipal budget cycles in China and India drive volatile spot purchasing for road maintenance programs.
- Automotive:Tire manufacturers and brake component suppliers specify carbon black and adhesive resins with controlled PAH and ash content. OEM sustainability mandates are pushing tire makers toward tar-derived sustainable carbon black certifications.
- Pharmaceuticals:Naphthalene and creosote derivatives supply antiseptic, disinfectant, and intermediate chemical production. Regulatory scrutiny from FDA and EMA on PAH impurities is constraining pharmaceutical-grade tar sourcing.
- Chemical Processing:Aromatic hydrocarbon refiners extract naphthalene, anthracene, and pyridine bases for dye, pesticide, and plasticizer synthesis. Chinese chemical clusters near steel-producing provinces dominate regional processing capacity.
Construction anchors end-user demand by volume, with automotive expanding most quickly on electric vehicle battery material requirements.
Technology:
Technology maturity curves separate legacy atmospheric units from advanced cracking configurations.
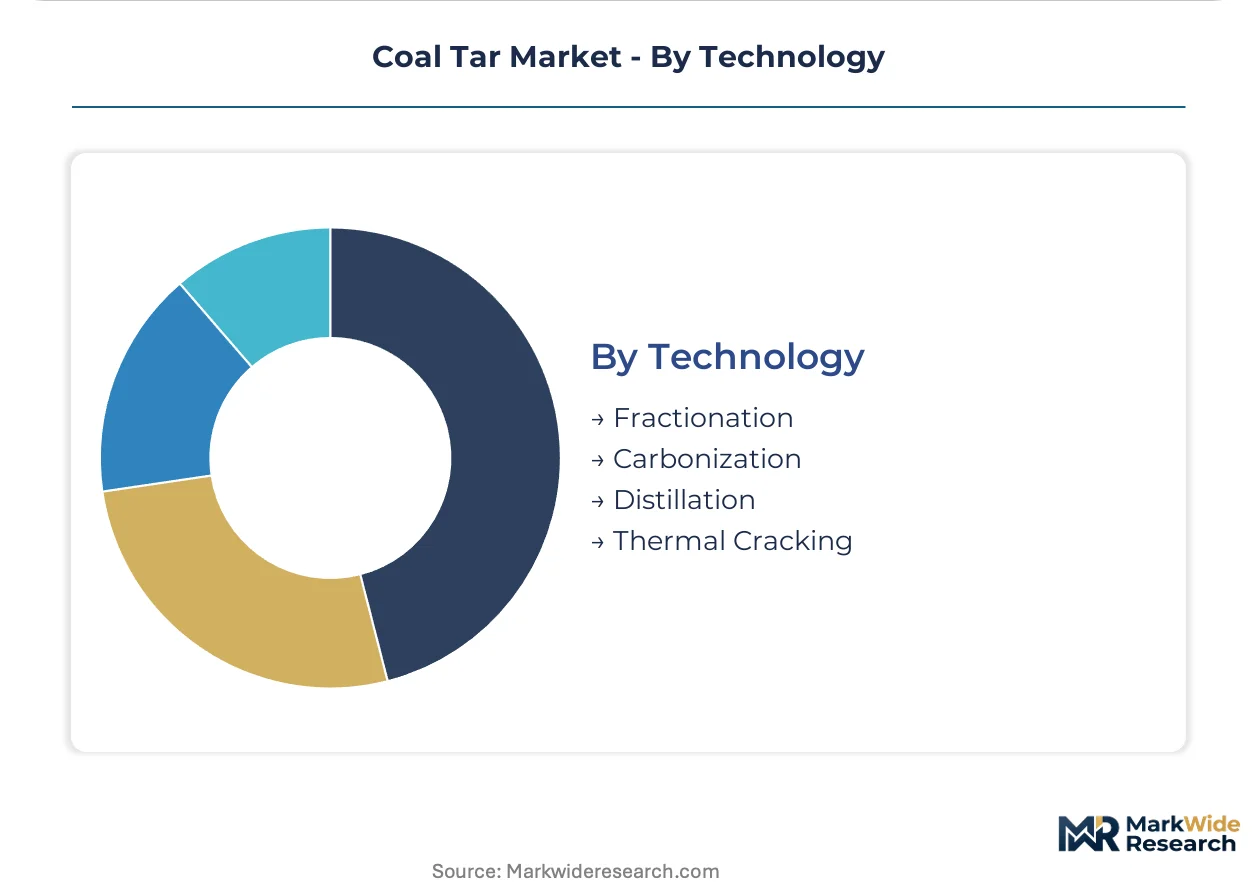
- Fractionation:Atmospheric and vacuum distillation separates tar into oil, pitch, and anthracene fractions based on boiling point. European facilities are retrofitting fractionation trains with improved quinoline insoluble control for electrode binder specifications.
- Carbonization:High-temperature treatment of pitch yields needle coke and mesophase carbon for graphite electrodes. Japanese carbonization technology dominates premium needle coke production for ultra-high-power electric arc furnace electrodes.
- Distillation:Conventional batch and continuous distillation recovers naphthalene and light aromatic oils. Aging distillation assets in Eastern Europe face efficiency disadvantages against newer Chinese integrated coking complexes.
- Thermal Cracking:Elevated-temperature cracking of heavy tar fractions boosts light oil and naphthalene yields. Newer Asian facilities are deploying thermal cracking to maximize high-value aromatic recovery from limited feedstock volumes.
Distillation retains the highest installed base, though thermal cracking shows the steepest expansion trajectory on yield optimization economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redrawing production geography as distillers relocate processing capacity to evade escalating compliance costs in Europe and North America. This arbitrage dynamic favors integrated coking complexes in Asia and the Middle East where environmental enforcement remains less stringent.
China
Steel-byproduct availability from coking plants in Shanxi and Hebei provinces sustains the world's largest tar distillation base. MEE enforcement of dual carbon goals is tightening emissions standards at older facilities. The Yangtze River Delta chemical clusters near Shanghai are absorbing upgraded capacity for battery anode precursor production.
United States
Domestic aluminum smelters in Kentucky and South Carolina sustain demand for high-purity binder pitch despite feedstock cost pressures. EPA aquatic use restrictions have eliminated creosote demand for waterfront piling, forcing distillers toward carbon black and electrode applications. Koppers Inc. maintains integrated operations in Pennsylvania and Arkansas to serve regional carbon materials demand.
India
Domestic aluminum capacity expansion in Odisha and Chhattisgarh is pulling specialty pitch imports and spurring local distillation investments. BIS quality standards for quinoline insoluble content are tightening procurement specifications for smelter anodes. Himadri Speciality Chemicals Ltd anchors processing capacity in West Bengal to serve eastern industrial corridors.
Germany
REACH authorization requirements for coal tar pitch are forcing Rütgers and other distillers toward electrode binder reformulation. ECHA persistent organic pollutant assessments are extending compliance timelines for creosote-containing products. The Ruhr industrial region hosts specialized fractionation capacity serving European carbon black and specialty chemical processors.
Japan
Carbonization technology leadership in Chubu and Kansai regions dominates premium needle coke production for ultra-high-power graphite electrodes. METI industrial decarbonization roadmaps are pressuring tar processors to demonstrate lifecycle emissions reductions. JFE Chemical Corporation leverages integrated steel-chemical operations to sustain high-purity carbon precursor output.
Coal Tar Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue battery anode precursor specialization and thermal cracking yield optimization. The market structures around three player tiers: integrated steel-chemical conglomerates with captive feedstock, independent tar distillers serving commodity carbon black, and technology-licensed specialists in high-purity pitch fractions. Dominant competitive moves include backward integration into coking operations to secure feedstock and strategic partnerships with aluminum smelters for long-term offtake commitments.
Within the integrated conglomerate tier, Mitsubishi Chemical Corporation and JFE Chemical Corporation exemplify steel-chemical platform models that internalize distillation through carbonization expertise. Among independent specialists, Himadri Speciality Chemicals Ltd occupies a position representing Indian specialty pitch capacity expansion. Koppers Inc. anchors North American supply continuity through its integrated carbon materials and chemicals platform.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| DEZA a.s. |
| Rain Carbon Inc. |
| Epsilon Carbon Pvt. Ltd. |
| Bilbaina de Alquitranes S.A. |
| Koppers Inc. |
| JFE Chemical Corporation |
| Coopers Creek Chemical Corp. |
| Himadri Speciality Chemicals Ltd |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap distillers across Eastern Europe and privately-held coking conglomerates in Shanxi province anchor feedstock procurement, enabling pricing discipline that resists spot-market volatility while compressing distributor margins in fragmented downstream channels.
Pricing Analysis
Distributor margin layers in coal tar derivatives compress toward single-digit percentages as direct-to-smelter contracts displace merchant trade. Three-tier pricing structure across electrode-grade pitch, standard binder pitch, and creosote oil fractions reflects quinoline insoluble certification tiers and volume scale commitments. Cost compression in creosote oil is intensifying because copper azole substitution eliminates residential demand channels. Aluminum smelters exhibit lowest price sensitivity due to captive supply arrangements, while municipal road contractors demonstrate highest sensitivity to emulsion binder costs.
Supply Chain Analysis
Freight cost differentials between Baltic Sea ports and inland Chinese coking clusters favor regional processing over intercontinental tar trade. Supply concentrates in China, India, and Germany, with raw material dependencies on bituminous coal coking volumes, metallurgical coke byproduct yields, and naphthalene recovery efficiency. Single-source vulnerability in Chinese steel-byproduct availability exposes distillers to feedstock interruption risks. Distribution runs through integrated steel-chemical platforms and independent merchant distillers serving spot chemical processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ECHA REACH compliance costs in Germany exceed MEE enforcement expenses in Hebei province by multiples, redirecting investment toward Asian carbon precursor capacity.
For Market Incumbents: Extend long-term offtake agreements with Middle Eastern aluminum smelters to lock volume commitments against thermal cracking yield optimization by emerging competitors. Deepen backward integration into coking operations in Shanxi and Hebei provinces to secure feedstock continuity as Chinese steel output cycles tighten. Prioritize quinoline insoluble control investments to meet tightening BIS specifications for Indian smelter procurement. For New Entrants and Emerging Players: Specialty chemical distributors in the Yangtze River Delta offer channel access to battery anode precursor buyers seeking mesophase pitch alternatives to petroleum-based needle coke. Target India's Odisha and Chhattisgarh aluminum corridors where domestic distillation capacity lags smelter expansion. Pursue toll-processing arrangements with existing coking facilities to circumvent capital-intensive distillation asset requirements. For Investors and Strategic Acquirers: Integrated steel-chemical conglomerates are the most active acquirer in this space, seeking carbonization technology capabilities for lithium-ion battery material verticals. Five-to-ten year viability hinges on electric vehicle anode precursor demand sustaining premium pitch margins against regulatory compression in conventional applications. Monitor ECHA persistent organic pollutant assessment timelines as inflection indicators for European asset stranded-risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coking Operations | Captive bituminous coal supply from Shanxi coking plants secures feedstock against Chinese steel sector volatility. |
| Thermal Cracking Technology Deployment | Newer Asian facilities boost naphthalene yields from limited tar volumes through elevated-temperature cracking systems. |
| Long-term Smelter Offtake Agreements | Persian Gulf aluminum complexes demand guaranteed impurity ceilings through captive pitch supply arrangements. |
| Specialty Carbon Precursor Capacity Expansion | Yangtze River Delta clusters absorb upgraded distillation capacity for electric vehicle battery anode production. |
| REACH Compliance Reformulation Investment | German and Dutch distillers shift toward electrode binder grades to escape ECHA restricted substance classifications. |
Methodological Framework
Multiple input streams — executive interviews with tar distiller plant managers, procurement leads at aluminum smelters, and specialty carbon black technical directors; customs and trade flow databases; SEC 10-K filings from integrated chemical producers; and ECHA REACH registration dossiers — were reconciled through bottom-up volume builds and top-down market sizing triangulation.
Data-stream reconciliation across product-grade segmentation, end-use industry classification, and regional production hub analysis shaped the analytical framework over the projection horizon. CAGRs were derived from slope-intercept modeling of historical trade volumes and capacity utilization rates, incorporating metallurgical coke byproduct yield coefficients and aluminum smelter anode consumption intensity as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese steel sector output cycles, ECHA persistent organic pollutant regulatory timelines, and electric vehicle battery chemistry shifts away from graphite anodes. Forecasts reflect documented assumptions about feedstock availability and regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Flame Retardants Chemicals Market
Chemicals
Methanol to Gasoline Market
Chemicals
North America Isopropyl Alcohol Market
Chemicals
Menadione Market
Chemicals
Amyl Nitrite Market
Chemicals
Brazil Methanol Market
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
Iscotrizinol Market
Chemicals
Isooctyl Alcohol Market
Chemicals
Hexachloroethane Market
Chemicals
Welding Chemicals Market
Chemicals
Isopropanolamine Market
Chemicals
Chlorosilane Market
Chemicals
Para Cresol Market
Chemicals
Fluorochemicals Market
Chemicals
Chloroplatinic Acid Market