
 Sodium Aluminum Hydride Market | 2026-2036
Sodium Aluminum Hydride Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Aluminum Hydride Market Analytics
The EU Green Deal is hardening requirements for clean hydrogen supply chains across European industrial clusters. Albemarle Corporation leverages its lithium-hydrogen materials expertise to sustain competitive positioning in energy-dense hydride chemistries. Anhui Wotu Chemical anchors cost-efficient powder production for Asian chemical synthesis buyers. American Elements differentiates through high-purity grades serving North American aerospace and defense contractors.
Sodium aluminum hydride (NaAlH4) is a complex metal hydride with a theoretical hydrogen capacity of 5.6 wt%, synthesized through direct reaction of sodium hydride with aluminum chloride under inert atmosphere. The compound functions primarily as a hydrogen storage medium and strong reducing agent in organic synthesis, releasing hydrogen upon thermal decomposition or catalytic doping with titanium or cerium additives. Powder formulations dominate current commercial supply due to superior surface-area-to-volume ratios enabling faster hydrogen sorption kinetics, while solution segments in tetrahydrofuran or diglyme capture premium margins from pharmaceutical batch reduction processes. Hydrogen storage applications lead volume demand as automotive OEMs evaluate solid-state carriers against compressed gas alternatives, though chemical synthesis retains stable offtake from generic API manufacturers.
The EPA regulates hydrogen storage system safety under its chemical facility standards, while REACH mandates full toxicity profiling for NaAlH4 imports into European Union member states. China's MEE enforces dual carbon compliance on hydrogen project developers, restricting carbon-intensive reduction routes for hydride precursors. Japan's METI subsidizes domestic hydrogen carrier validation through its Green Innovation Fund, directly funding sodium alanate cycle testing. Stakeholders must monitor catalyst cost curves and regional hydrogen hub funding allocations to time capacity commitments effectively.
Market Dynamics
The sodium aluminum hydride market pivots on hydrogen carrier validation cycles, where automotive OEMs weigh solid-state storage against liquid organic hydrogen carriers and compressed gas systems. This technology-screening phase concentrates purchasing decisions among German, Japanese, and Korean vehicle manufacturers with dedicated hydrogen roadmap funding.
Growth Catalysts
- EU Green Deal hydrogen backbone:The framework mandates renewable hydrogen quotas for industrial feedstock substitution, pulling NaAlH4 into European chemical cluster decarbonization roadmaps.
- Japan METI Green Innovation Fund:Direct subsidies for sodium alanate cycle testing accelerate carrier validation timelines and de-risk pilot-scale hydrogen refueling infrastructure.
- Automotive solid-state storage evaluation:Passenger vehicle OEMs benchmark metal hydride gravimetric density against system-level packaging efficiency for fuel cell powertrains.
Market Restraints
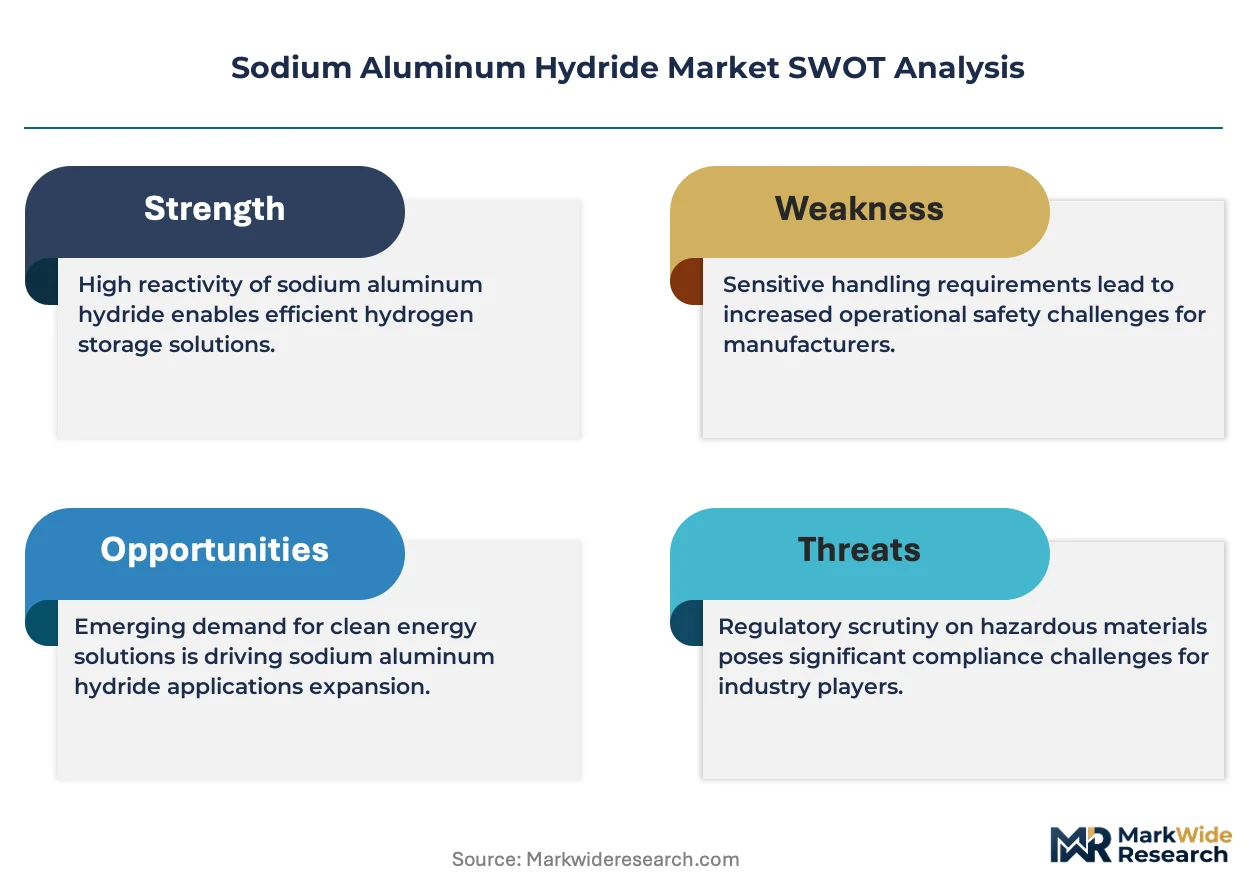
- Titanium catalyst cost volatility:Dopant materials constitute a disproportionate share of reversible hydrogen storage system economics, compressing margins at pilot scale.
- REACH toxicity profiling requirements:ECHA mandates comprehensive substance dossiers for NaAlH4 imports, extending European market entry timelines by twelve to eighteen months.
- Compressed hydrogen infrastructure lock-in:Existing gaseous storage and distribution assets create switching friction for solid-state carrier adoption in established hydrogen hubs.
Strategic Opportunities
- China dual carbon compliance pathways:MEE enforcement creates demand for low-carbon hydride precursors in domestic hydrogen project development.
- Aerospace auxiliary power unit applications:Fuel cell-driven aircraft systems evaluate metal hydrides for weight-critical onboard hydrogen reserves.
- Pharmaceutical batch reduction services:Contract manufacturers in India and Switzerland seek high-purity NaAlH4 solutions for selective organic synthesis.
Industry Challenges
- Pyrophoric handling certification gaps:Workforce training for air-sensitive hydride powder processing lags behind production capacity expansion timelines.
- Reversible cycling durability standards:Absence of harmonized ISO test protocols complicates cross-border equipment qualification and warranty negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Aluminum Hydride Market |
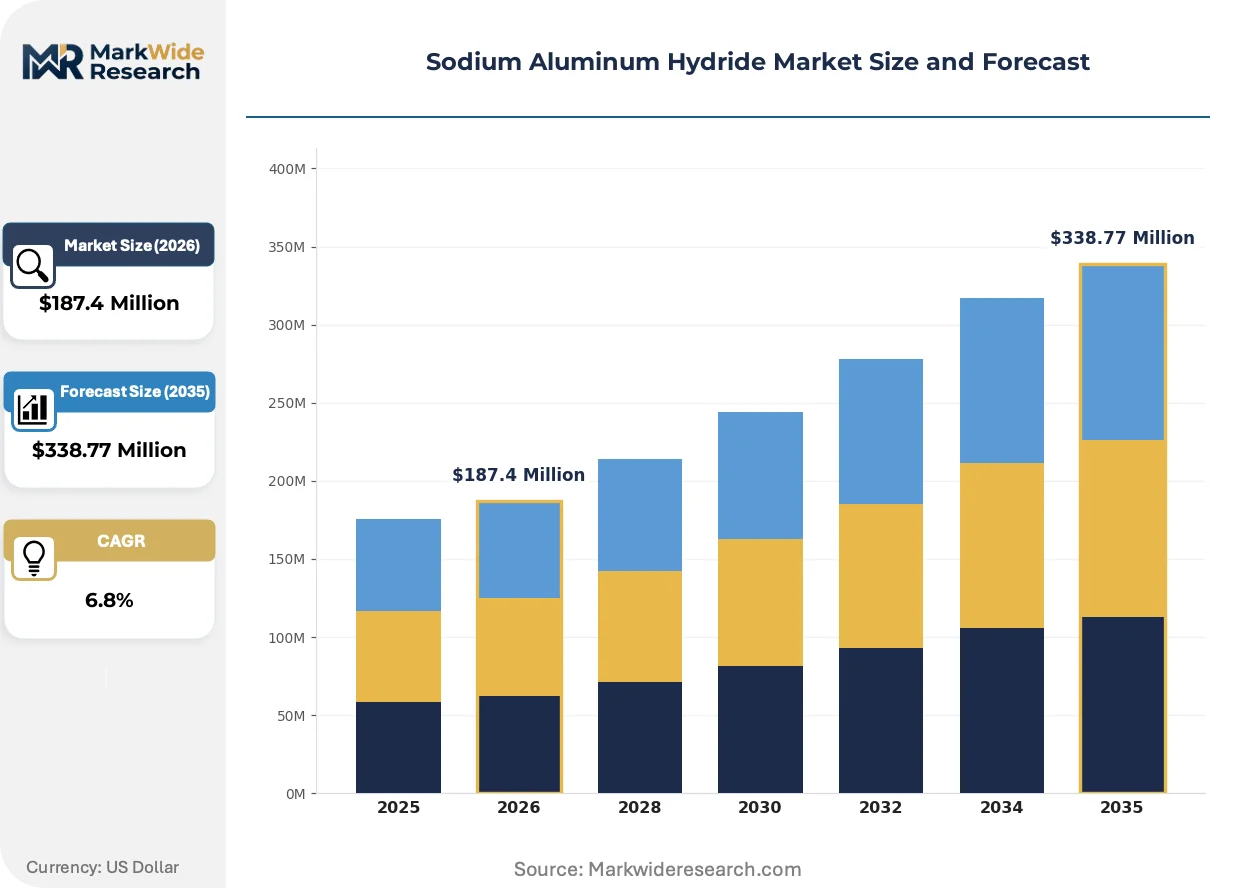
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid, Powder, Granules, Solution Application: Hydrogen Storage, Fuel Cells, Chemical Synthesis, Reducing Agent End User: Aerospace, Pharmaceuticals, Automotive, Electronics Packaging Type: Drums, Bottles, Bags, Totes |
| Companies Covered | Albemarle Corporation, Anhui Wotu Chemical, ShanDong Guobang Pharmaceutical, Dalchem, Tianjin Dipper Fine Chemical, Hebei Keyu, American Elements, North Metal & Chemical Co., Central Drug House, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Aluminum Hydride Market Evolving Landscape
Solid-state hydrogen storage architectures are displacing incumbent compressed gas systems across mobility and stationary power applications. This shift compresses carrier material qualification timelines and rewards suppliers with integrated catalyst-hydride system capabilities.
Titanium-doped sodium alanate formulations are converging with high-surface-area nanostructured aluminum substrates to accelerate hydrogen sorption kinetics. Automotive tier-one suppliers in Germany and Japan pilot these enhanced materials for integrated tank-reactor designs. The convergence is compressing system volume requirements and enabling underbody packaging configurations previously reserved for liquid hydrogen.
REACH authorization requirements for persistent organic pollutants are tightening precursor chemical sourcing standards across European hydride production. ECHA's evolving substance restriction roadmap forces reformulation of residual solvent profiles in tetrahydrofuran-based NaAlH4 solutions. Specialty chemical distributors in the Netherlands and Belgium are consolidating qualified supply base relationships to secure uninterrupted import authorization.
After-sales technical service unbundling is fragmenting traditional chemical distribution relationships in North American aerospace procurement. Prime contractors now source NaAlH4 powder separately from application engineering support, compressing distributor margin structures. This pattern is most visible in California and Washington state defense supply chains, where on-site hydride handling supervision commands separate contracting vehicles.
Sodium Aluminum Hydride Market Segmentation
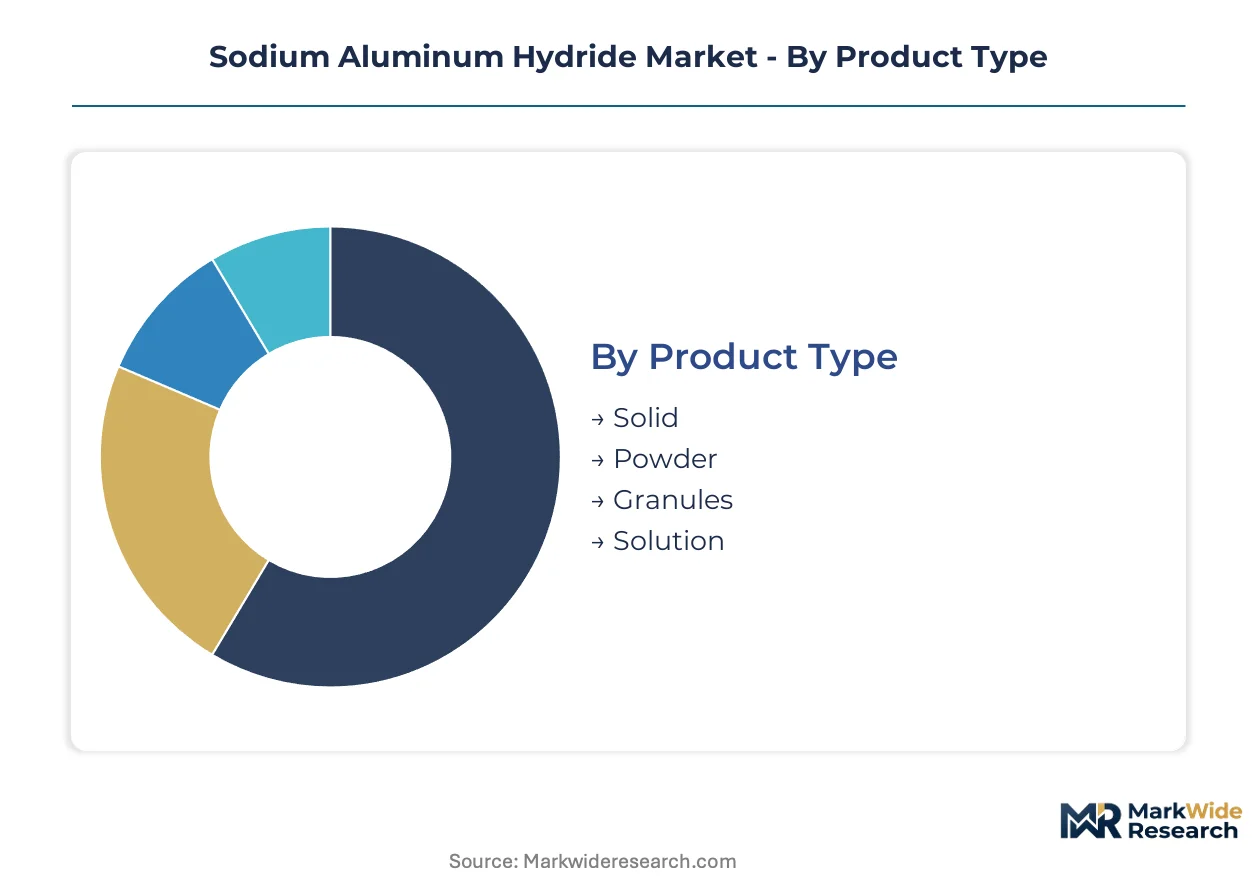
Sodium aluminum hydride supply chains fragment across physical forms, application chemistries, and handling protocols. Each segment carries distinct margin structures and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Physical form dictates reactivity profiles, packaging requirements, and transportation hazard classifications across the value chain.
- Powder:Fine particulate formulations maximize surface-area-to-volume ratios for accelerated hydrogen sorption kinetics. German and Japanese automotive OEMs specify powder grades for integrated tank-reactor designs in fuel cell powertrain development.
- Solution:Tetrahydrofuran or diglyme suspensions serve pharmaceutical batch reduction processes requiring precise stoichiometric control. Swiss and Indian contract manufacturers source solution grades for selective organic synthesis of active pharmaceutical ingredients.
- Solid:Bulk crystalline blocks reduce pyrophoric surface exposure during long-haul transport. Aerospace contractors in Washington state specify solid forms for auxiliary power unit hydrogen reserves.
- Granules:Intermediate particle sizing balances handling safety with reactivity access. Chemical synthesis buyers in Belgium and the Netherlands prefer granules for controlled-rate reduction reactions.
Mature deployment sits with powder formulations in automotive qualification cycles. Newer deployment is concentrated in solution grades for pharmaceutical manufacturing expansion.
Application:
End-use chemistry determines purity thresholds, catalyst integration requirements, and customer technical service intensity.
- Hydrogen Storage:Reversible hydrogen release upon thermal decomposition or titanium-cerium catalytic doping positions NaAlH4 against compressed gas alternatives. METI-subsidized validation programs in Japan accelerate carrier adoption timelines.
- Chemical Synthesis:Strong reducing agent functionality drives stable offtake from generic API manufacturers. REACH-mandated toxicity profiling extends European market entry for synthesis-grade suppliers.
- Fuel Cells:Onboard hydrogen release integration requires system-level packaging efficiency benchmarking. Korean automotive tier-one suppliers pilot solid-state carrier architectures against liquid organic alternatives.
- Reducing Agent:Selective organic transformation applications in fine chemical production demand high-purity grades. California-based aerospace contractors specify reducing agent specifications for defense procurement compliance.
Volume concentration remains in hydrogen storage pilot programs. Margin expansion is climbing the fastest in chemical synthesis contract manufacturing.
End User:
Customer sector shapes certification requirements, order pattern stability, and technical specification stringency.
- Automotive:Passenger vehicle OEMs benchmark gravimetric density against system-level packaging constraints. German manufacturers lead solid-state storage evaluation with dedicated hydrogen roadmap funding.
- Pharmaceuticals:Batch reduction services require high-purity solution grades with residual solvent documentation. Swissmedic-regulated facilities in Switzerland drive premium pricing for certified supply.
- Aerospace:Weight-critical onboard hydrogen reserves for fuel cell-driven aircraft systems favor metal hydride density. FAA and DoD procurement standards govern handling certification requirements.
- Electronics:Specialized deposition and doping applications consume ultra-high-purity powder grades. Japanese electronics material suppliers specify contamination thresholds below pharmaceutical standards.
Procurement scale concentrates in automotive qualification batches. Specification intensity peaks in aerospace defense contracting.
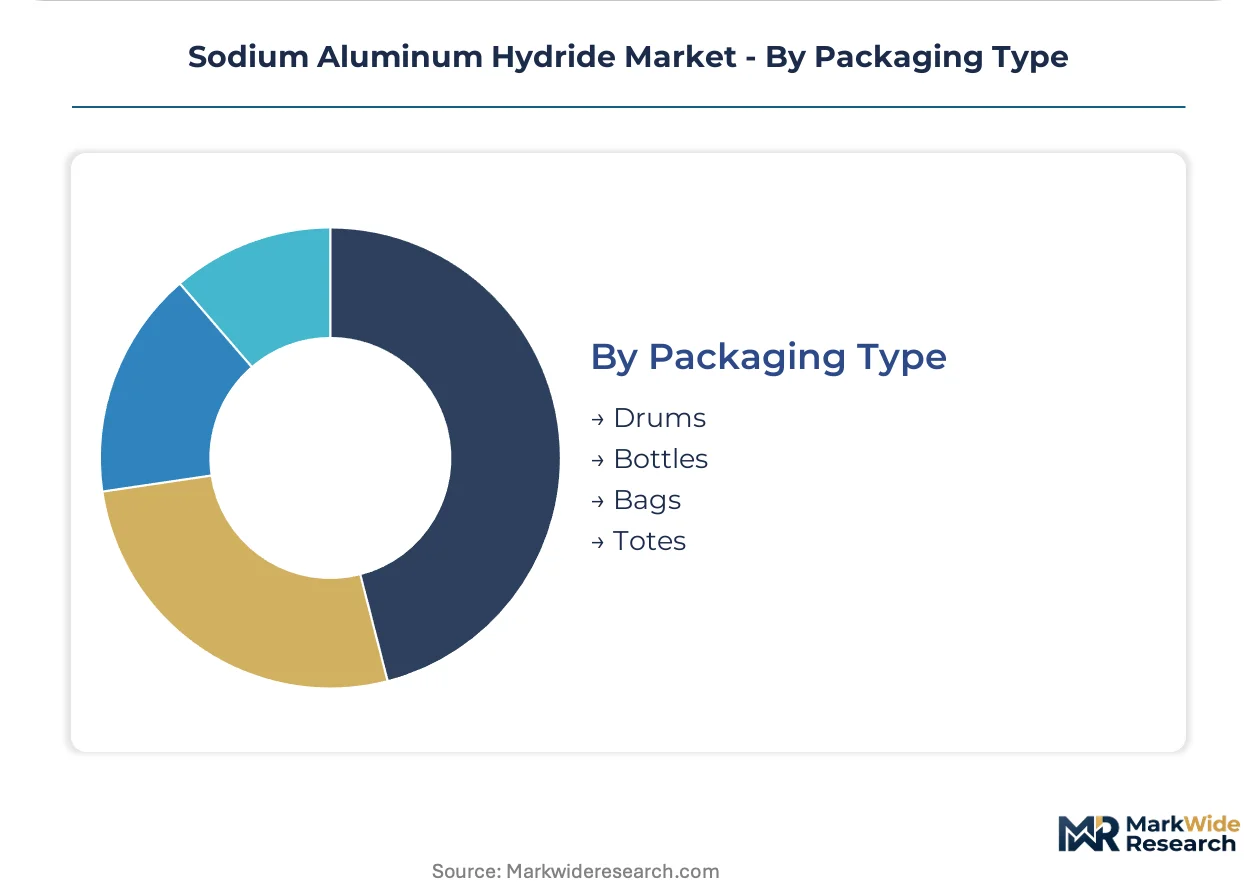
Packaging Type:
Containment configuration aligns with pyrophoric handling protocols, shipment volume economics, and customer inventory systems.
- Drums:Standard steel containment for industrial-scale powder and granule shipments. German chemical clusters specify drum configurations for REACH-compliant import handling.
- Bottles:Amber glass or fluoropolymer containers for solution grades requiring light and moisture exclusion. Pharmaceutical distributors in India mandate bottle packaging for CDSCO-registered facilities.
- Bags:Laminated flexible containment for lower-volume solid block shipments. Aerospace contractors in California prefer bag formats for cleanroom transfer protocols.
- Totes:Intermediate bulk containers for high-volume chemical synthesis customers. Belgian specialty distributors deploy totes for EU Green Deal hydrogen cluster supply.
Standardization dominates drum configurations for industrial buyers. Customization concentrates in bottle formats for pharmaceutical compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial clusters in Germany concentrate hydrogen infrastructure investment and solid-state carrier validation programs for automotive applications.
United States
California hydrogen hubs and Washington state aerospace corridors drive powder-grade procurement for fuel cell development and defense contracting. EPA chemical facility standards govern pyrophoric handling protocols. Houston-Gulf Coast petrochemical clusters evaluate NaAlH4 for refinery decarbonization pilot projects.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg benchmark metal hydride gravimetric density against compressed gas alternatives. EU Green Deal renewable hydrogen quotas pull NaAlH4 into chemical cluster feedstock substitution roadmaps. KBA validation programs coordinate with industrial hydrogen backbone development in North Rhine-Westphalia.
Japan
Kanto region fuel cell vehicle manufacturers pilot integrated tank-reactor designs using titanium-doped sodium alanate formulations. METI Green Innovation Fund subsidizes carrier cycle testing and de-risks hydrogen refueling infrastructure deployment. Nagoya automotive suppliers evaluate solid-state storage against liquid organic hydrogen carriers.
China
Yangtze River Delta hydrogen project developers face MEE dual carbon compliance requirements restricting carbon-intensive hydride precursor reduction routes. Shandong and Jiangsu chemical synthesis buyers source cost-efficient powder grades for pharmaceutical API manufacturing. Beijing-Tianjin-Hebei industrial clusters integrate low-carbon hydride supply into national hydrogen demonstration zones.
Switzerland
Basel pharmaceutical contract manufacturers procure high-purity solution grades for selective organic synthesis of active pharmaceutical ingredients. Swissmedic-regulated facilities mandate residual solvent documentation and certified supply chain traceability. Swiss specialty chemical distributors consolidate REACH-compliant import relationships for European hydrogen cluster supply.
Sodium Aluminum Hydride Market Competitive Landscape
The competitive structure tilts toward specialty chemical producers with integrated catalyst-hydride system capabilities. Market concentration remains moderate with regional specialists commanding geographic niches and multinational material science firms competing on certification breadth. Two strategic archetypes dominate: vertically integrated hydride precursor manufacturers and high-purity solution specialists serving pharmaceutical compliance markets. Capacity expansion and geographic licensing agreements constitute the primary competitive moves as firms position for hydrogen hub funding allocations.
Among North American material science firms, Albemarle Corporation occupies a position exemplifying lithium-hydrogen materials expertise applied to energy-dense hydride chemistries. American Elements represents the high-purity grade archetype serving aerospace and defense procurement channels. Chinese specialty chemical producers including Anhui Wotu Chemical anchor the cost-efficient powder production segment for Asian chemical synthesis buyers. These three archetypes illustrate how competitive positioning fragments across certification intensity, geographic proximity to demand clusters, and integration depth into precursor supply chains.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Anhui Wotu Chemical |
| ShanDong Guobang Pharmaceutical |
| Dalchem |
| Tianjin Dipper Fine Chemical |
| Hebei Keyu |
| American Elements |
| North Metal & Chemical Co. |
| Central Drug House |
| Others |
Value Network & Pricing Analysis
Backward integration into titanium catalyst and sodium hydride precursor production anchors competitive positioning for European and Japanese suppliers, compressing third-party raw material exposure while securing pricing power against volatile dopant cost curves. REACH-mandated toxicity profiling and EPA chemical facility standards create compliance-tiered pricing floors that favor integrated producers with captive regulatory affairs capabilities.
Pricing Analysis
Yield-based pricing tied to hydrogen release efficiency and reversible cycling durability anchors contract structures across automotive qualification programs. Three-tier pricing structure across pharmaceutical-grade solutions, aerospace-certified powders, and industrial synthesis granules reflects certification intensity and residual solvent documentation burdens. Pricing pressure stems from titanium catalyst cost volatility compressing margins at pilot-scale hydrogen storage deployments. Chemical synthesis buyers in India and Belgium exhibit highest price sensitivity due to generic API manufacturing economics, while Swissmedic-regulated pharmaceutical facilities accept premium positioning for certified supply chain traceability.
Supply Chain Analysis
Specialized pyrophoric handling workforce availability in Germany, Japan, and the United States constrains capacity expansion timelines and concentrates qualified production in established chemical clusters. Raw material dependencies center on aluminum chloride feedstocks, sodium hydride precursors, and titanium-cerium dopant materials sourced from constrained specialty chemical suppliers. Single-source vulnerability in high-purity aluminum substrate supply creates qualification bottlenecks for nanostructured hydride formulations. Distribution runs through specialty chemical distributors in the Netherlands and Belgium for European REACH-compliant import, with direct OEM relationships dominating Japanese and German automotive procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH authorization requirements and EPA chemical facility standards erect twelve-to-eighteen-month entry barriers that protect incumbent positioning against unqualified challengers.
For Market Incumbents: Deepen catalyst-hydride system integration capabilities to capture automotive tier-one supplier relationships as solid-state storage validation cycles compress. Defend against liquid organic hydrogen carrier substitution by accelerating reversible cycling durability data packages for KBA and METI qualification programs. Prioritize capacity addition in North Rhine-Westphalia and Kanto region clusters to align with EU Green Deal and Green Innovation Fund funding allocations.
For New Entrants and Emerging Players: Capture pharmaceutical batch reduction service contracts in India and Switzerland where high-purity solution demand outpaces qualified supply. Target CDSCO-registered facilities and Swissmedic-regulated contract manufacturers with certified residual solvent documentation capabilities. Pursue geographic licensing agreements with established specialty chemical distributors to bypass direct REACH authorization timelines.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of vertically integrated hydride precursor manufacturers with captive titanium catalyst supply and established automotive qualification relationships. Long-term viability hinges on hydrogen hub funding durability and solid-state carrier adoption thresholds in passenger vehicle architectures. Watch METI subsidy renewal signals and German KBA validation protocol harmonization as inflection indicators for carrier technology lock-in.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Supply | Captive titanium dopant production insulates margins from raw material volatility affecting pilot-scale deployments. |
| REACH Authorization Investment | Full toxicity dossier completion secures twelve-month first-mover advantage in EU chemical cluster supply. |
| Automotive Qualification Partnership | Integrated tank-reactor design collaboration with Bavarian OEMs locks in volume offtake for powder formulations. |
| Pharmaceutical Solution Certification | Swissmedic-traceable supply commands premium positioning in Basel API manufacturing corridor. |
| Geographic Licensing Agreement | Distribution partnerships with Dutch specialty chemical handlers bypass direct ECHA import authorization barriers. |
Research Methodology
Trade databases, SEC chemical company filings, and ECHA substance registration records formed the secondary backbone, cross-referenced against primary interviews with hydrogen storage system engineers, pharmaceutical contract manufacturing procurement leads, specialty chemical distribution channel managers, and REACH regulatory affairs consultants. Bottom-up and top-down triangulation validated volume estimates across powder, solution, solid, and granule product categories.
Bottom-up modeling anchored demand-side segmentation across hydrogen storage, chemical synthesis, fuel cell, and reducing agent applications, while top-down cross-checks referenced EU Green Deal hydrogen backbone investment disclosures and METI Green Innovation Fund allocation announcements. CAGRs were derived from weighted scenario analysis across automotive qualification timelines, pharmaceutical manufacturing expansion patterns, and aerospace auxiliary power unit development cycles. Forecast inputs incorporated catalyst cost curve trajectories, regional hydrogen hub funding durability, and REACH authorization pipeline progression.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state carrier technology selection decisions by German and Japanese automotive OEMs, titanium supply concentration shifts, and ECHA substance restriction roadmap evolution. Forecasts reflect documented assumptions regarding hydrogen infrastructure deployment pacing and regulatory compliance timeline stability. Material deviation in METI subsidy renewal, KBA validation protocol adoption, or titanium catalyst supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
RDX and HMX Market
Chemicals
Selenium Sulfide Market
Chemicals
Trichlorosilane Market
Chemicals
Chromium Trioxide Market
Chemicals
Spirodiclofen Market
Chemicals
Tin Chemicals Market
Chemicals
Power Plant Chemicals Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Pentanedione Market
Chemicals
Amine Oxide Market
Chemicals
Trimethylamine Market
Chemicals
Dimethyl Phosphate Market
Chemicals
Fine Chemicals Market
Chemicals
Non PVC Plasticizers Market
Chemicals
Metal Finishing Chemicals Market