
 Latin America Drilling Fluids Market | 2026-2036
Latin America Drilling Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Drilling Fluids Market Outlook
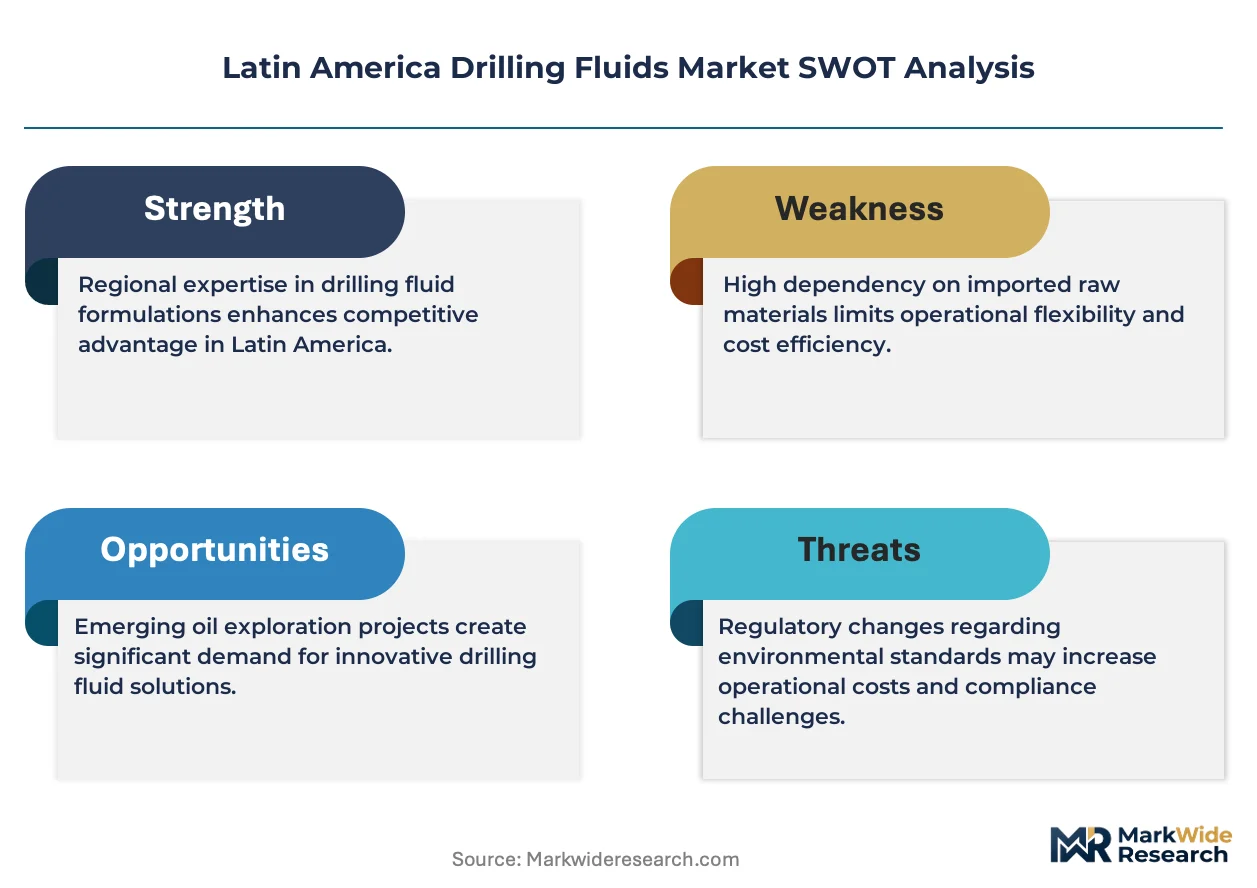
REACH is restructuring the cost-of-entry calculus for drilling fluid suppliers seeking European export certification, forcing reformulation of base fluids and additive packages. Newpark Resources Inc leverages its in-house barite mining operations to secure raw material continuity across the Gulf of Mexico and Andean basins. Halliburton anchors its regional position through integrated well construction services that bundle fluids with directional drilling and logging. CES Energy Solutions Corp differentiates through specialized completion fluid systems tailored for high-pressure, high-temperature reservoirs in Brazil and Mexico.
Latin America drilling fluids are engineered liquid and slurry systems composed of base fluids, weighting agents, viscosifiers, and chemical additives designed to maintain hydrostatic pressure, cool drill bits, transport cuttings, and stabilize wellbore walls during rotary drilling operations. Water-based formulations dominate volume demand due to lower environmental remediation costs and compatibility with Mexico's tightened discharge protocols, though synthetic fluids command premium pricing in Brazil's deepwater pre-salt fields where temperature stability and lubricity justify higher unit costs. Oil-based systems retain structural importance in Argentina's Vaca Muerta shale where water-sensitive formations require invert-emulsion chemistry to prevent clay swelling and wellbore collapse. The end-user base tilts toward drilling contractors and integrated oil companies that self-procure fluids through multi-year framework agreements, while service providers compete for spot market opportunities in exploratory campaigns.
Brazil's National Petroleum Agency (ANP) mandates environmental impact assessments for offshore drilling fluid discharges, shaping product registration requirements and field trial protocols. Mexico's ASEA enforces NOM standards for hydrocarbon exploration waste management, directly influencing water-based fluid adoption rates in onshore and shallow-water concessions. Argentina's Secretariat of Energy promotes local content requirements for Vaca Muerta development, creating procurement preferences for domestically blended fluid systems. Stakeholders must monitor how regulatory divergence across these three jurisdictions affects formulation standardization and inventory pooling strategies.
Market Dynamics
Brazil's pre-salt deepwater expansion is compressing the technology gap between synthetic and water-based formulations, forcing suppliers to engineer hybrid systems that satisfy both ANP environmental mandates and Petrobras' high-pressure operational requirements.
Growth Catalysts
- Pre-salt reservoir complexity:Brazil's ultra-deepwater fields below 2,000 meters require synthetic drilling fluids with thermal stability above 150°C, accelerating formulation R&D investment from integrated service providers.
- ASEA discharge protocols:Mexico's tightened NOM-120-SEMARNAT-2011 amendments for offshore waste management are mandating closed-loop systems that recycle water-based fluids, expanding equipment retrofit demand.
- Vaca Muerta lateral extension:Argentina's shale operators are drilling 3,000-meter laterals through water-sensitive formations, concentrating consumption of oil-based invert emulsion systems that prevent clay swelling.
Market Restraints
- Barite supply concentration:Over 60% of regional weighting agent supply routes through Chinese export quotas, exposing Latin American blenders to freight volatility and customs delays at Veracruz and Santos ports.
- Base oil import dependency:Synthetic fluid manufacturers lack domestic paraffin and olefin production in Brazil, Argentina, and Mexico, forcing dollar-denominated procurement that amplifies working capital pressure during peso or real depreciation cycles.
- REACH export certification:European ECHA registration requirements for bioaccumulative additives create 18-24 month approval timelines, blocking Latin American formulators from Atlantic basin contract opportunities.
Strategic Opportunities
- Colombia's offshore licensing round:ANH's 2024-2025 Caribbean and Pacific deepwater blocks offer first-mover positioning for synthetic fluid suppliers before local environmental rules crystallize.
- Local content incentives:Argentina's Secretariat of Energy procurement preferences for Vaca Muerta create captive demand for domestically blended systems, rewarding joint ventures with regional chemical distributors.
- Modular blending skids:Containerized micro-plants deployed to remote Amazonian or Patagonian drilling camps are reducing logistics costs for exploratory campaigns outside pipeline infrastructure.
Industry Challenges
- Specialized mud engineering talent:Brazil and Mexico each face shortages of 200+ certified drilling fluid engineers capable of formulating for HPHT pre-salt conditions, forcing operators to import personnel at 40% salary premiums.
- Biodegradability certification timelines:OECD 306 seawater biodegradation testing for ANP registration requires 28-day marine exposure studies, delaying product launches by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Drilling Fluids Market |
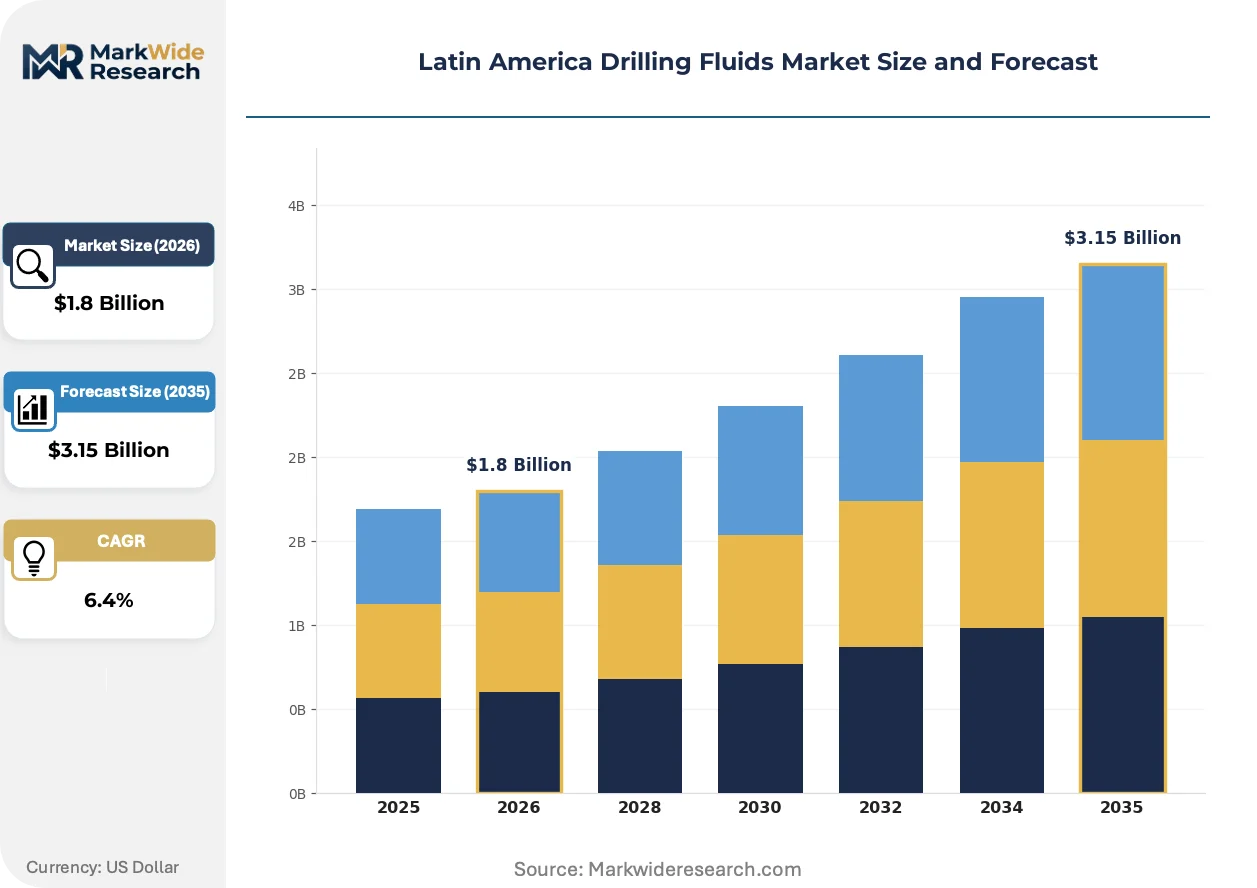
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
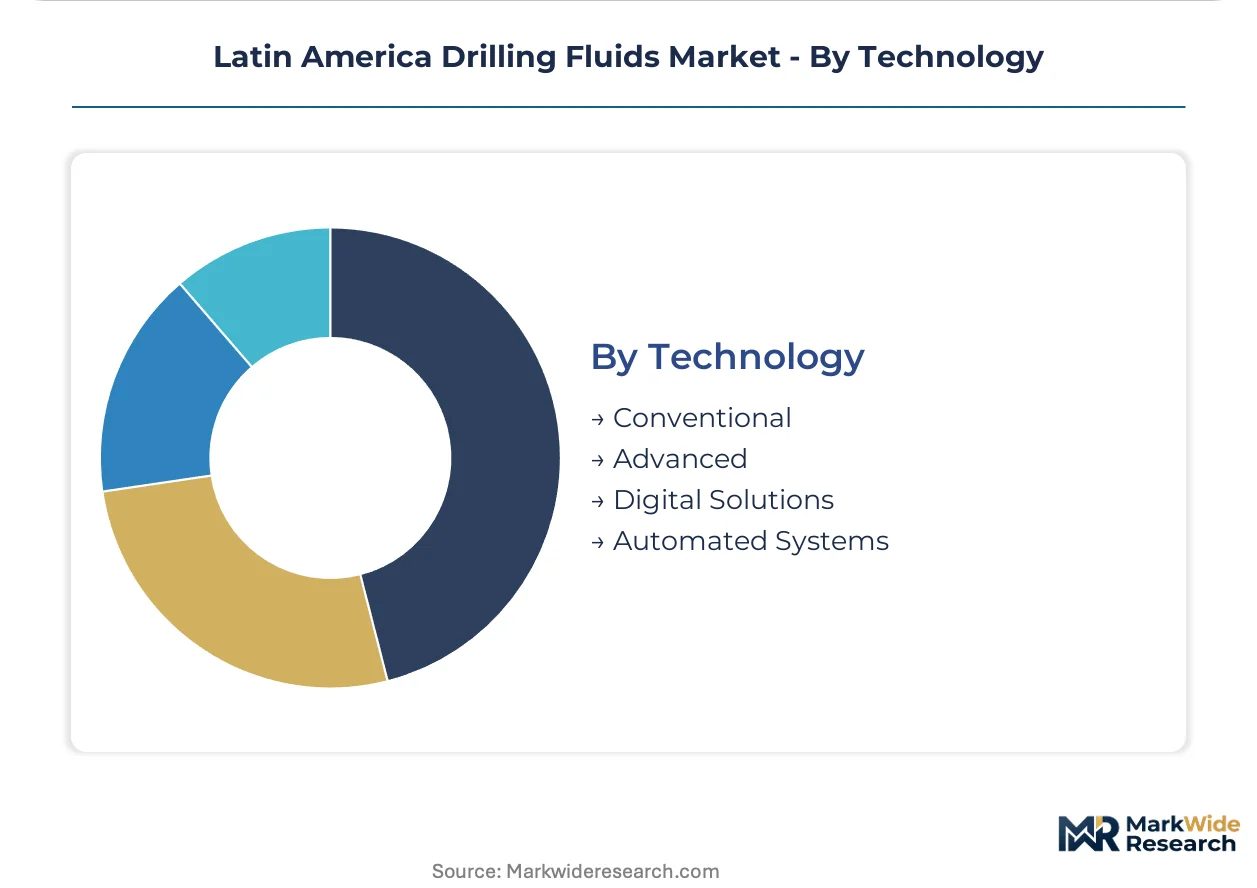
| Segmentation | Product Type: Water-Based, Oil-Based, Synthetic, Emulsified End User: Oil Companies, Drilling Contractors, Service Providers, Mining Firms Application: Offshore Drilling, Onshore Drilling, Geothermal Wells, Horizontal Drilling Technology: Conventional, Advanced, Digital Solutions, Automated Systems |
| Companies Covered | Newpark Resources Inc, CES Energy Solutions Corp, Schlumberger Limited, Weatherford International, Petronas Chemicals Group, Halliburton, Tetra Technologies, NOV Inc, Baker Hughes Company, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Drilling Fluids Market Strategic Shifts
Formulation chemistry is pivoting toward multifunctional additive packages that reduce inventory SKUs while satisfying divergent regulatory thresholds across Brazilian, Mexican, and Argentine jurisdictions.
Nano-particle stabilizers are decentralizing the traditional service-company-dominated fluid engineering model. Independent operators in Vaca Muerta are leasing portable mixing units with pre-loaded nano-silica packages, cutting on-site engineering headcount by half. This technology is decentralizing technical decision-making from major service providers to drilling contractors with in-house competency.
ANP's 2023 Resolution 868 mandates real-time monitoring of drilling fluid discharge volumes and toxicity levels via satellite-linked sensors. Offshore operators must now integrate digital reporting infrastructure with fluid management systems, increasing capital intensity for platform retrofits. Brazil's deepwater segment is responding by consolidating supplier relationships to reduce audit fragmentation.
Integrated oil companies are unbundling fluid procurement from bundled well construction contracts. Petrobras and Pemex are issuing separate tenders for base chemicals, additives, and engineering services, enabling direct negotiation with specialty chemical manufacturers. This pattern is most visible in Brazil's pre-salt cluster where spot-market fluid volumes have doubled since 2022.
Latin America Drilling Fluids Market Segmentation
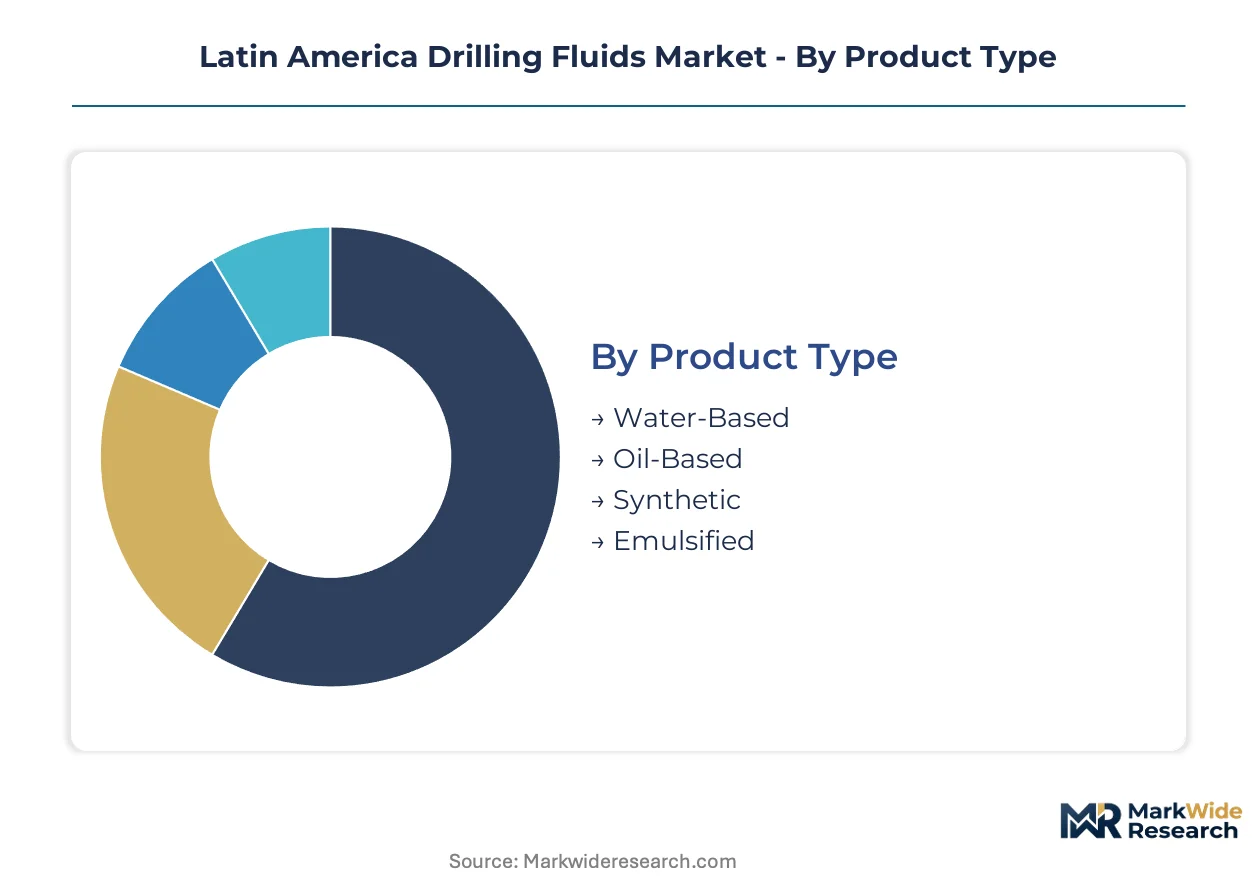
Drilling fluid selection in Latin America hinges on regulatory compatibility with ANP, ASEA, and Secretariat of Energy requirements. Each segment carries distinct certification burdens that shape procurement patterns across Brazilian pre-salt, Mexican shallow-water, and Argentine shale basins.
Product Type:
ANP Resolution 868 and ASEA NOM-120-SEMARNAT-2011 amendments impose divergent biodegradability thresholds that segment suppliers by registration capability.
- Water-Based:Formulations dominated by aqueous base fluids with bentonite or polymer viscosifiers. Mexico's tightened discharge protocols are accelerating closed-loop system adoption in Campeche Bay and Burgos Basin operations, with ASEA compliance now mandatory for offshore concessions.
- Synthetic:Laboratory-engineered base fluids including internal olefins and linear alpha-olefins delivering thermal stability above 150°C. Brazil's pre-salt deepwater fields below 2,000 meters concentrate demand where Petrobras specifications override cost premiums.
- Oil-Based:Diesel or mineral oil continuous-phase systems with calcium chloride brine internal phase. Vaca Muerta's water-sensitive formations in Neuquén Basin require invert-emulsion chemistry to stabilize 3,000-meter laterals.
- Emulsified:Micro-emulsion and nano-emulsion systems bridging water-based environmental profiles with synthetic performance metrics. Colombian Caribbean exploratory blocks are testing hybrid registrations ahead of ANH licensing rounds.
Water-Based sits at the top of the volume ranking, with Synthetic climbing the fastest.
End User:
Procurement authority concentrates with entities capable of multi-year framework agreements and in-house mud engineering competency.
- Oil Companies:Integrated operators including Petrobras and Pemex that self-procure base chemicals and additives through unbundled tenders. These firms direct formulation specifications and retain environmental liability for discharge compliance.
- Drilling Contractors:Firms executing turnkey drilling contracts with fluid costs passed through or fixed. Brazilian pre-salt contractors face 40% salary premiums for imported HPHT-certified mud engineers.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes units bundling fluids with directional drilling and logging services. Spot market participation dominates exploratory campaigns outside pipeline infrastructure.
- Mining Firms:Copper and lithium operators in Chilean Atacama and Argentine Puna adapting oilfield fluid systems for geothermal gradient management in deep exploration boreholes.
Oil Companies command the largest contract values, with Drilling Contractors expanding their technical staffing most aggressively.
Application:
Well architecture and water depth dictate base fluid selection, with environmental jurisdiction layering additional constraints.
- Offshore Drilling:Brazil's pre-salt and Mexico's shallow-water platforms requiring synthetic or premium water-based systems with real-time discharge monitoring mandated by ANP Resolution 868. Satellite-linked toxicity sensors add capital intensity to platform retrofits.
- Onshore Drilling:Argentina's Vaca Muerta and Colombia's Magdalena Valley conventional fields where logistics infrastructure permits bulk chemical delivery and centralized blending operations.
- Geothermal Wells:High-temperature formations in Chilean Andes and Mexican Cerro Prieto demanding thermal stability beyond conventional oil-based specifications.
- Horizontal Drilling:Extended-reach laterals through interbedded shale and carbonate sequences requiring lubricity additives and torque-reduction packages.
Offshore Drilling generates the highest revenue per well, with Onshore Drilling contributing the greatest absolute volume.
Technology:
Capital intensity and data integration requirements segment suppliers by digital infrastructure investment.
- Conventional:Standard mixing and testing protocols with manual density and rheology adjustments. Legacy installations persist in mature onshore fields with stable formation pressures.
- Advanced:Nano-particle stabilizers and multifunctional additive packages reducing inventory SKUs. Vaca Muerta operators lease portable mixing units with pre-loaded nano-silica, cutting on-site engineering headcount.
- Digital Solutions:Cloud-based fluid property tracking and predictive maintenance algorithms. ANP-mandated real-time reporting infrastructure is consolidating supplier relationships to reduce audit fragmentation.
- Automated Systems:Continuous circulation units with robotic chemical dosing and self-adjusting weighting agent addition. Offshore Brazil trials demonstrate 15% reduction in fluid waste volumes.
Conventional retains the widest installed base, with Digital Solutions gaining share fastest among integrated operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mud engineers certified for HPHT pre-salt conditions concentrate in Rio de Janeiro and São Paulo, anchoring Latin America's technical workforce for ultra-deepwater formulation expertise.
Brazil
Petrobras pre-salt fields below 2,000 meters drive synthetic fluid consumption with thermal stability requirements above 150°C. ANP Resolution 868 mandates real-time discharge monitoring via satellite-linked sensors, forcing platform retrofits. Rio de Janeiro's Macaé corridor hosts the densest cluster of fluid engineering contractors serving the Santos Basin.
Mexico
Campeche Bay shallow-water platforms and Burgos Basin onshore drilling accelerate closed-loop water-based system adoption. ASEA enforces NOM-120-SEMARNAT-2011 amendments for offshore waste management, prohibiting untreated discharge. Ciudad del Carmen in Campeche state functions as the primary logistics hub for Gulf of Mexico fluid blending operations.
Argentina
Vaca Muerta shale operators drill 3,000-meter laterals through water-sensitive formations, concentrating demand for oil-based invert emulsion systems. The Secretariat of Energy promotes local content requirements, creating procurement preferences for domestically blended fluids. Neuquén city anchors the regional supply chain for Neuquén Basin drilling campaigns.
Colombia
ANH's 2024-2025 Caribbean and Pacific deepwater licensing rounds attract exploratory investment ahead of crystallized environmental rules. The national hydrocarbons regulator has not yet mandated biodegradability thresholds comparable to ANP or ASEA standards. Barranquilla's port infrastructure supports fluid import logistics for offshore blocks.
Chile
Copper and lithium operators in the Atacama Desert adapt oilfield fluid systems for geothermal gradient management in deep exploration boreholes. The mining sector's non-original equipment demand creates secondary market opportunities for drilling fluid technologies. Antofagasta hosts service company offices supporting both mining and limited petroleum exploration.
Latin America Drilling Fluids Market Competitive Environment
The competitive structure tilts toward integrated service providers with captive formulation capabilities and in-house barite mining operations. Three distinct archetypes occupy the field: global energy service conglomerates bundling fluids with directional drilling, regional specialists focusing on completion fluid systems for HPHT reservoirs, and independent blenders leveraging modular micro-plants for remote exploratory campaigns. Consolidation pressure intensifies through framework agreement unbundling by national oil companies and backward integration into weighting agent supply chains.
Within the integrated service tier, Schlumberger Limited and Halliburton exemplify the bundled well construction model, while Baker Hughes Company occupies a comparable position. Among regional specialists, CES Energy Solutions Corp represents the focused completion fluid archetype. Newpark Resources Inc anchors the upstream-integrated segment through captive barite mining operations. These three groupings reflect the market's segmentation by procurement authority: direct national oil company contracts, drilling contractor pass-through arrangements, and spot-market exploratory opportunities.
| Leading Market Players |
|---|
| Newpark Resources Inc |
| CES Energy Solutions Corp |
| Schlumberger Limited |
| Weatherford International |
| Petronas Chemicals Group |
| Halliburton |
| Tetra Technologies |
| NOV Inc |
| Baker Hughes Company |
| Others |
Value Chain & Pricing Dynamics
Barite export quotas from China cascade through Latin American blending operations into three distinct pricing tiers, with freight volatility at Veracruz and Santos ports compressing margins for independent formulators while integrated service providers absorb shocks through captive mining operations.
Pricing Analysis
The bundled-versus-unbundled service split now defines pricing architecture across the region. Petrobras and Pemex tenders separate base chemicals from engineering services, forcing spot-market competition among specialty additive suppliers. Price differentiation rests on ANP biodegradability certification tier and volume commitment scale, with synthetic fluid premiums widening as real depreciation amplifies dollar-denominated base oil costs. Cost compression in water-based formulations is intensifying because ASEA closed-loop mandates raise equipment retrofit burdens passed through to drilling contractors.
Supply Chain Analysis
Argentina's Secretariat of Energy local-content procurement preferences are reshaping sourcing patterns for Vaca Muerta development, compelling joint ventures with Neuquén Basin chemical distributors. Raw material supply draws from Chinese barite mining, U.S. Gulf Coast paraffin production, and domestic bentonite deposits in Brazil's Minas Gerais state. Single-source vulnerability concentrates in olefin imports for synthetic fluid manufacturers lacking regional cracking capacity. Distribution runs through Rio de Janeiro's Macaé corridor for Santos Basin offshore campaigns and Ciudad del Carmen for Campeche Bay logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ANP Resolution 868 real-time discharge mandates are accelerating platform retrofit demand and consolidating supplier relationships.
For Market Incumbents: Anchor market position through backward integration into weighting agent supply chains and certification pre-positioning for Colombia's ANH licensing rounds. Modular blending skid deployments counter logistics fragmentation in Amazonian exploratory blocks. Defensive consolidation around digital fluid monitoring capabilities offsets unbundling pressure from national oil company procurement reforms. For New Entrants and Emerging Players: Cloud-based fluid property tracking platforms offer the lowest-friction entry vector into Brazil's pre-salt spot market. Colombia's Caribbean deepwater blocks present the most penetrable geography ahead of crystallized environmental rules. Portable nano-silica mixing units leased to Vaca Muerta drilling contractors bypass entrenched service company relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists holding captive completion fluid formulations for HPHT reservoirs. Five-to-ten-year viability favors blenders with domestic barite sourcing and ANP registration portfolios. Watch ANH's adoption of biodegradability thresholds matching Brazilian or Mexican standards as the inflection signal for Colombian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Mining | Newpark Resources' captive supply secures raw material continuity across Gulf of Mexico and Andean basins. |
| Digital Fluid Monitoring Platform | ANP-mandated satellite-linked toxicity sensors consolidate supplier relationships and reduce audit fragmentation. |
| Modular Blending Skid Deployment | Containerized micro-plants cut logistics costs for remote Patagonian and Amazonian exploratory campaigns. |
| Local Content Joint Venture | Argentina's procurement preferences reward domestic blending partnerships in Neuquén Basin supply chains. |
| HPHT Certification Pre-Positioning | CES Energy Solutions' specialized completion fluids target Brazil's pre-salt pressure and temperature specifications. |
Study Parameters
Coverage spans Brazil, Mexico, Argentina, Colombia, and Chile, with primary inputs from each jurisdiction combining interviews with mud engineering directors, procurement leads at drilling contractors, ANP registration specialists, and logistics coordinators at port blending facilities. Secondary validation draws from ANP regulatory filings, ASEA NOM standard amendments, SEC 10-K disclosures from listed service providers, and customs trade data for barite and base oil imports. Bottom-up volume estimates triangulate against top-down expenditure projections from national oil company capital programs.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions include product type, end-user procurement authority, application well architecture, and technology sophistication tier. CAGRs derive from regression analysis against drilling rig counts, well depth trajectories, and regulatory implementation timelines. Industry-specific inputs incorporate Petrobras pre-salt well completion schedules and Vaca Muerta lateral extension drilling patterns.
The model assumes a particular technology adoption path; alternative pathways for nano-particle stabilizer deployment would alter the outlook if independent operator leasing models displace service-company engineering contracts. Forecasts reflect assumptions about ANH regulatory convergence with ANP standards and Chinese export quota continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Smart Well Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
Angola Oil and Gas Upstream Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Egypt Oil and Gas Market
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Asia-Pacific Natural Gas Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Oilfield Drill Bits Sales Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Algeria Oil and Gas Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Oilfield Roller Chain Market