
 Proppant Market | 2026-2036
Proppant Market Size, Share, and Industry Trends Forecast 2026-2036
Proppant Market Analysis
Proppant supply agreements bundled with last-mile logistics and well-site delivery is rebalancing how operators procure fracture media. U.S. Silica Holdings leverages its integrated mine-to-wellbore network across the Upper Midwest to lock in baseload commitments from Permian drillers. Covia Holdings anchors its position through control of Wisconsin frac sand reserves and unit-train rail access to Southwest shale plays. Saint-Gobain Proppants differentiates via ceramic proppant technology leadership for high-closure-stress deep formations.
Proppants are granular materials—typically silica sand, resin-coated substrates, or engineered ceramics—sized between 12/20 and 40/70 mesh that prop open hydraulically induced fractures in hydrocarbon-bearing rock to sustain conductive pathways for oil and gas flow. Manufacturing specifications include sphericity above 0.6, acid solubility below 2%, and crush resistance tested to API RP 19C protocols. Sand dominates volume economics in shallow-to-mid-depth unconventional plays where formation closure stress stays below 8,000 psi, while ceramic proppants command premium positioning in deep Haynesville and DJ Basin wells where crush resistance above 10,000 psi is mandatory. Resin-coated sand occupies a growing intermediate tier as operators seek reduced fines generation and improved flowback performance in multi-cluster plug-and-perf completions.
OSHA silica permissible exposure limits and EPA National Ambient Air Quality Standards are reshaping mining operations, dust control investments, and proppant handling protocols at well pads. State regulators in Texas and New Mexico enforce additional air monitoring requirements for transload facilities near populated areas. Stakeholders must weigh exposure to tightening environmental enforcement against the volume upside from longer laterals and higher proppant intensity per stage.
Market Dynamics
Proppant markets pivot on the tension between EPA silica exposure mandates and operators' push for higher proppant intensity per lateral foot. Regulatory compliance costs now compete directly with downhole performance economics across every major shale basin.
Growth Catalysts
- OSHA Respirable Crystalline Silica Standard:The 2016 rule mandates dust suppression systems that accelerate adoption of resin-coated and ceramic alternatives with reduced airborne fines during handling.
- Permian Basin lateral extension:Average drilled lengths exceeding 15,000 feet consume 50% more proppant per completion than 2019 baselines, concentrating demand pull in West Texas and Southeast New Mexico.
- Multi-cluster plug-and-perf architectures:Higher stage counts per well require engineered proppant blends with tailored crush resistance gradients to maintain conductivity across variable closure stresses.
Market Restraints
- Natural gas feedstock volatility:Resin-coated proppant production depends on methanol and formaldehyde pricing, exposing margins to Henry Hub fluctuations and chemical supply tightness.
- Upper Midwest mine concentration:Wisconsin and Minnesota silica deposits supply 70% of domestic frac sand, creating single-source vulnerability to rail bottlenecks and winter weather disruptions.
- API RP 19C crush testing limitations:Standardized laboratory protocols fail to predict proppant degradation under cyclic loading conditions common in deep Haynesville and Appalachian formations.
Strategic Opportunities
- Argentina Vaca Muerta development:Neuquén Basin unconventional pilot programs offer first-mover positioning for proppant suppliers with logistics partnerships through Bahía Blanca port infrastructure.
- Texas Railroad Commission flaring restrictions:Associated gas capture mandates favor oil-directed drilling with higher proppant loads per barrel of oil equivalent produced.
- Real-time proppant tracking:RFID-embedded mesh systems are integrating with last-mile logistics platforms to reduce well-site inventory mismatches and demurrage charges.
Industry Challenges
- API RP 19D certification backlog:Third-party testing laboratory capacity constraints delay new product qualification timelines by 4-6 months, freezing supplier entry into premium ceramic segments.
- Well-site dust control retrofit costs:Silica handling equipment upgrades at transload facilities require $2-4 million per location, straining mid-tier proppant distributors with limited balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proppant Market |
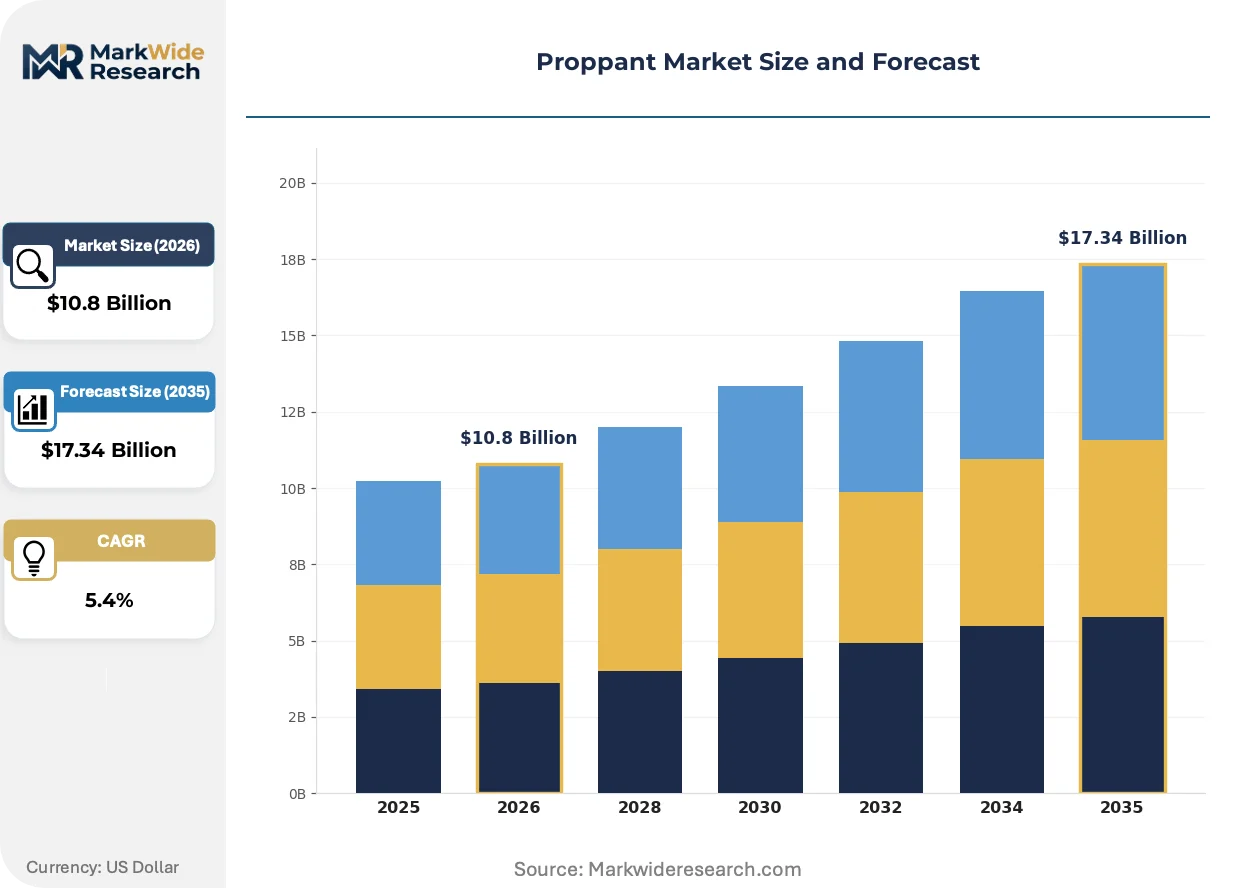
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $17.34 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
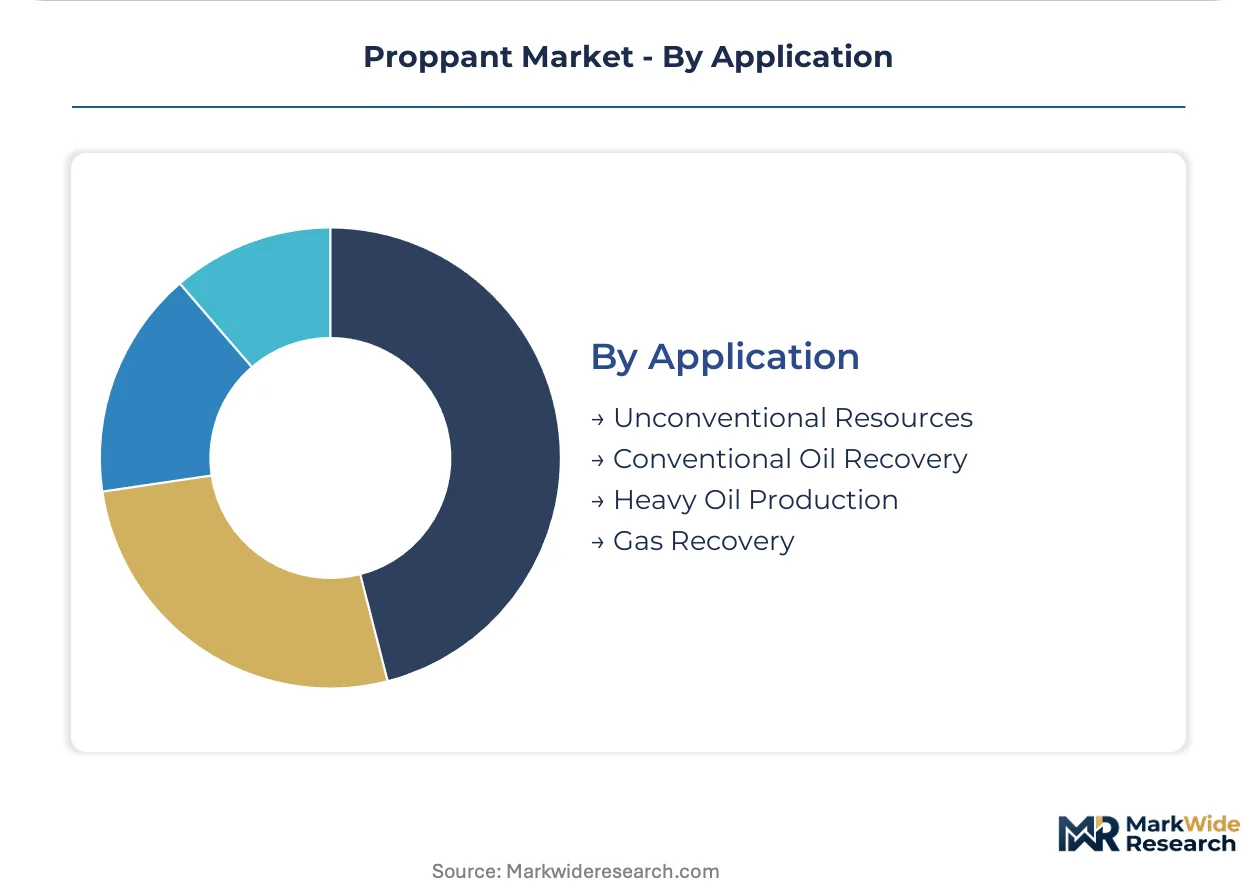
| Segmentation | Product Type: Sand, Resin-Coated Sand, Ceramic Proppants, Biodegradable Proppants End Use Industry: Oil & Gas, Mining, Construction, Industrial Applications Technology: Fracking, Acidizing, Thermal Recovery, Water Flooding Application: Unconventional Resources, Conventional Oil Recovery, Heavy Oil Production, Gas Recovery |
| Companies Covered | CARBO Ceramics Inc., U.S. Silica Holdings Inc., Covia Holdings LLC, Badger Mining Corporation, Hi-Crush Inc., Emerge Energy Services LP, Saint-Gobain Proppants, Atlas Energy Solutions Inc., Hexion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proppant Market Emerging Trajectories
Proppant technology trajectories center on conductivity preservation under extreme closure stress and environmental compliance at the well pad. Three distinct vectors are compressing legacy supply arrangements.
Ultra-lightweight ceramic proppants with specific gravity below 2.65 are integrating nanoscale alumina coatings to reduce embedment in soft shale formations. EOG Resources and Pioneer Natural Resources have shifted 30% of Permian completions to these substrates. The technology is integrating proppant selection with reservoir geomechanics modeling, collapsing the traditional separation between geology and completions engineering.
EPA National Ambient Air Quality Standards for PM2.5 are tightening fugitive dust limits at mining and transload facilities. Industrial operators face Title V permit modifications requiring continuous emissions monitoring systems. Sand suppliers in Chippewa County, Wisconsin are responding with enclosed conveyor systems and real-time silica monitoring to preempt enforcement actions.
Integrated mine-to-wellbore service contracts are displacing spot-market sand purchases. Operators now bundle proppant volume commitments with dedicated rail car fleets and well-site storage silos. This consolidation is most visible in the Delaware Basin, where Diamondback Energy and Coterra Energy have executed five-year take-or-pay agreements locking in delivered costs below indexed WTI correlations.
Proppant Market Segmentation
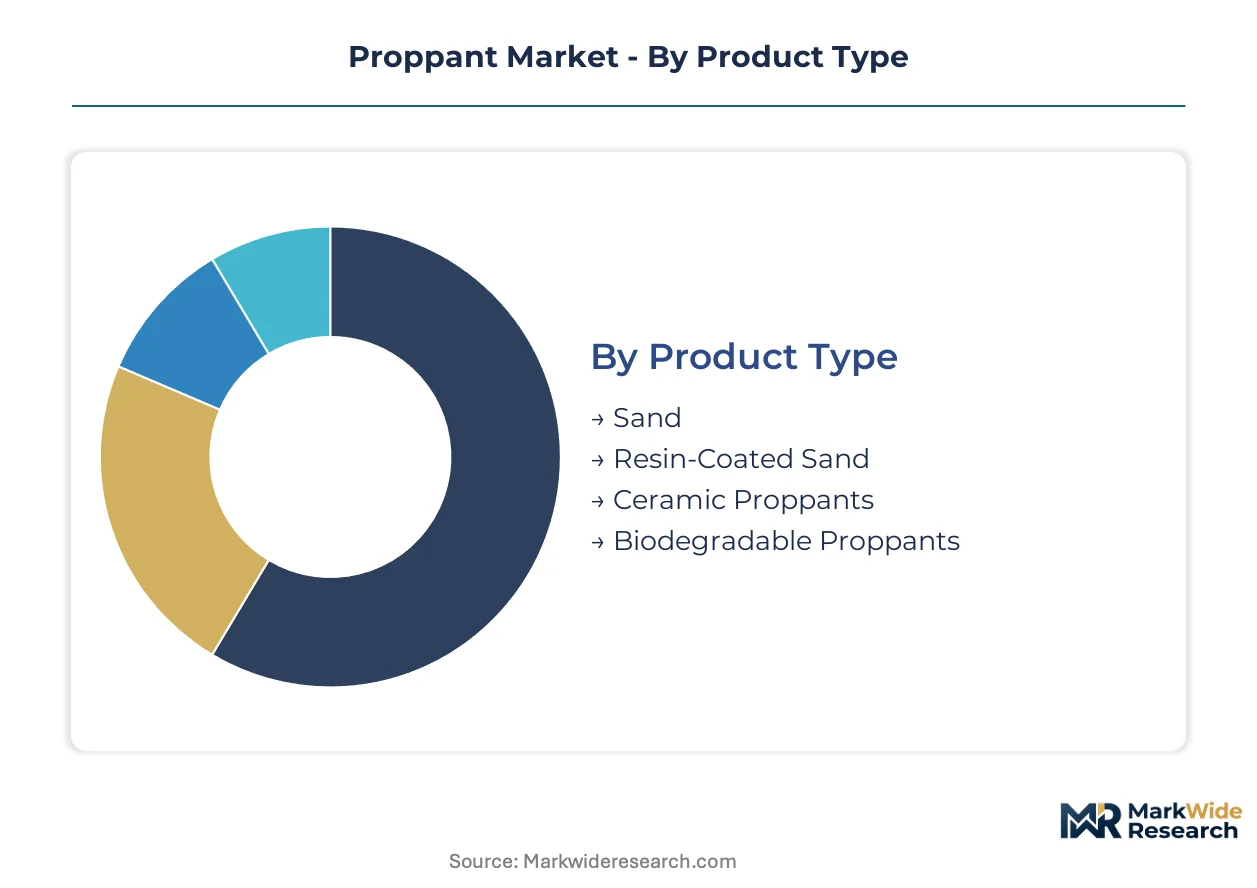
Proppant procurement patterns diverge sharply across product grades and completion technologies. Operators match proppant selection to formation depth, closure stress, and environmental compliance burdens at the well pad.
Product Type:
Supply concentration in Wisconsin and Minnesota silica deposits creates tiered availability across proppant categories, with rail logistics determining effective market reach for each substrate.
- Sand:Raw silica sand graded 12/20 to 40/70 mesh dominates shallow-to-mid-depth unconventional plays where formation closure stress remains below 8,000 psi. Permian Basin operators consume the bulk of domestic sand volumes as lateral lengths extend past 15,000 feet and proppant intensity per stage climbs.
- Resin-Coated Sand:Phenolic or pre-cured resin coatings encapsulate silica grains to reduce fines generation during handling and improve flowback performance in multi-cluster plug-and-perf architectures. Demand is concentrating in EPA-regulated transload facilities where OSHA silica exposure limits favor reduced airborne particulates.
- Ceramic Proppants:Engineered sintered bauxite and intermediate-strength ceramics deliver crush resistance above 10,000 psi for deep Haynesville and DJ Basin wells.
- Biodegradable Proppants:Experimental polymer-based substrates target temporary conductivity applications in environmentally sensitive formations.
Sand absorbs the bulk of installed capacity; biodegradable proppants are expanding most quickly from negligible bases.
End Use Industry:
Cost tier separation between commodity extraction and value-added industrial applications drives divergent specification requirements and procurement contract structures.
- Oil & Gas:Horizontal shale completions account for the dominant proppant consumption globally, with unconventional operators in Texas and New Mexico specifying mesh size, crush resistance, and acid solubility to API RP 19C protocols. Multi-stage fracking in the Delaware Basin consumes 50% more proppant per well than 2019 baselines.
- Mining:Heap leaching and in-situ recovery operations use coarse proppant substrates to maintain permeability in ore-bearing formations.
- Construction:Geotechnical grouting and soil stabilization applications demand consistent grain sphericity above 0.6 for predictable flow characteristics.
- Industrial Applications:Filtration media and foundry casting represent stable ancillary demand outside hydrocarbon extraction cycles.
Oil & Gas commands premium pricing tiers; construction offers volume stability through non-cyclical infrastructure spending.
Technology:
Application maturity determines equipment utilization rates and proppant placement precision across recovery methods.
- Fracking:High-pressure hydraulic fracturing in unconventional shale formations requires engineered proppant blends with tailored crush resistance gradients to preserve conductivity across variable closure stresses.
- Acidizing:Matrix acid stimulation in carbonate reservoirs uses minimal proppant volumes compared to shale completions, focusing instead on etched fracture conductivity.
- Thermal Recovery:Steam-assisted gravity drainage in heavy oil deposits tolerates lower proppant specifications due to reduced mechanical stress on formation media.
- Water Flooding:Secondary recovery in mature conventional fields employs proppant only during initial completion or refracturing campaigns.
Fracking anchors technology-specific demand; thermal recovery is climbing fastest as oil sands development accelerates.
Application:
Resource geology dictates proppant performance requirements and contract duration across extraction categories.
- Unconventional Resources:Tight oil and shale gas formations in the Permian, Eagle Ford, and Bakken require massive proppant loads per lateral foot, with operators bundling volume commitments into five-year take-or-pay agreements.
- Conventional Oil Recovery:Mature sandstone reservoirs with established pressure maintenance need sporadic proppant delivery for workover and refracturing programs.
- Heavy Oil Production:Viscous crude extraction in California and Canada employs specialized proppant chemistries compatible with thermal cycling.
- Gas Recovery:Dry gas plays in the Appalachian Basin prioritize cost-minimized sand over premium ceramics as commodity pricing constrains completion budgets.
Unconventional resources lock in long-term procurement contracts; gas recovery shows the steepest expansion trajectory as LNG export capacity builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midland-Odessa anchors proppant consumption intensity as Permian Basin operators stretch lateral lengths past 15,000 feet. The United States dominates volume economics through shale completion intensity, while Argentina and Saudi Arabia emerge as frontier unconventional plays.
United States
Permian Basin drillers in West Texas and Southeast New Mexico consume half of domestic proppant volumes as lateral extensions drive 50% higher proppant loads per well since 2019. EPA National Ambient Air Quality Standards for PM2.5 tighten fugitive dust limits at Wisconsin mining operations and Texas transload facilities. Chippewa County, Wisconsin supplies 70% of domestic frac sand through enclosed conveyor systems and real-time silica monitoring.
Argentina
Neuquén Basin unconventional pilot programs in Vaca Muerta shale offer first-mover positioning for suppliers with logistics partnerships through Bahía Blanca port infrastructure. The national hydrocarbons regulator enforces local content requirements for imported proppant substrates. Operators in the Loma Campana field test multi-cluster plug-and-perf architectures with engineered proppant blends.
Saudi Arabia
Jafurah Basin unconventional gas development drives ceramic proppant specifications for high-closure-stress deep formations above 10,000 psi. The national oil company mandates domestic proppant manufacturing partnerships under localization programs. Eastern Province industrial zones host sintered bauxite production facilities serving both domestic and Gulf export markets.
Canada
Alberta oil sands thermal recovery operations tolerate lower proppant specifications for steam-assisted gravity drainage wells with reduced mechanical stress. Environment and Climate Change Canada enforces methane capture mandates that favor oil-directed drilling with higher proppant intensity per barrel produced. Calgary-based operators bundle proppant procurement with dedicated rail car fleets for Montney and Duvernay shale plays.
China
Sichuan Basin shale gas development in the Fuling and Weiyuan blocks consumes ceramic proppants for high-pressure deep formations. The Ministry of Ecology and Environment enforces dual carbon goals that restrict silica mining emissions and favor resin-coated alternatives with reduced airborne fines. Yangtze River Delta manufacturing clusters produce intermediate-strength ceramics for domestic unconventional completions.
Proppant Market Vendor Landscape
Capital-heavy mine operators compete with asset-light logistics specialists across tiered supply arrangements. The vendor base clusters around three strategic archetypes: integrated mine-to-wellbore suppliers controlling Wisconsin frac sand reserves, ceramic technology specialists commanding premium positioning in deep formation markets, and regional distributors bundling last-mile delivery with volume commitments. Dominant competitive moves include five-year take-or-pay contract structures and transload facility dust control retrofits.
Among North American integrated suppliers, U.S. Silica Holdings Inc., Covia Holdings LLC, and Hi-Crush Inc. exemplify the mine-to-wellbore archetype through Upper Midwest reserve positions and unit-train rail access to Southwest shale plays. CARBO Ceramics Inc. occupies a position within the engineered ceramics tier for high-closure-stress applications. Saint-Gobain Proppants represents the multinational technology specialist model with sintered bauxite production for deep Haynesville and international unconventional markets.
| Leading Market Players |
|---|
| CARBO Ceramics Inc. |
| U.S. Silica Holdings Inc. |
| Covia Holdings LLC |
| Badger Mining Corporation |
| Hi-Crush Inc. |
| Emerge Energy Services LP |
| Saint-Gobain Proppants |
| Atlas Energy Solutions Inc. |
| Hexion Inc. |
| Others |
Supply Flow & Price Mechanics
EPA National Ambient Air Quality Standards for PM2.5 and OSHA respirable crystalline silica exposure mandates gate qualified supply and premium-tier pricing access, forcing operators to absorb dust control retrofit costs or shift toward resin-coated and ceramic alternatives that command 15-40% markups over raw frac sand.
Pricing Analysis
Conductivity preservation under extreme closure stress anchors value-based pricing, with ceramic proppants commanding premiums tied to crush resistance performance in deep Haynesville and DJ Basin wells. Price differentiation separates API RP 19C-certified ceramics from uncoated sand grades, while volume scale discounts concentrate among Permian operators executing five-year take-or-pay agreements. Cost compression in raw sand tiers is intensifying because rail logistics and silica handling compliance erode delivered margins. Independent exploration and production companies show highest price sensitivity, while majors prioritize performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from major Permian operators mandate multi-supplier qualification across Wisconsin, Minnesota, and Texas sand deposits to mitigate winter weather disruptions and rail bottleneck exposure. Raw material dependencies center on Northern White silica reserves, phenolic resin chemistries, and sintered bauxite feedstocks. Single-source vulnerability concentrates in Chippewa County mining operations supplying 70% of domestic frac sand volume. Distribution runs through unit-train rail networks to West Texas transload facilities, with last-mile well-site delivery increasingly bundled under integrated service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over Wisconsin mine reserves and dedicated rail car fleets determines procurement contract capture. Players are pursuing backward integration into captive silica deposits as the decisive upstream lever.
For Market Incumbents: Lock in five-year take-or-pay agreements with Delaware Basin operators before ceramic substitution accelerates in deep formation segments. Expand enclosed conveyor and real-time silica monitoring capacity at Wisconsin mining operations to preempt EPA enforcement actions that would disqualify spot-market suppliers. Prioritize logistics asset ownership over commodity trading positions. For New Entrants and Emerging Players: Logistics partnerships with regional transload operators in Southeast New Mexico offer the most penetrable entry path for sand distributors lacking mine reserves. Target Vaca Muerta development in Argentina through Bahía Blanca port infrastructure relationships, where local content requirements favor foreign suppliers with established logistics networks. Lead with RFID-embedded proppant tracking as a differentiated service layer. For Investors and Strategic Acquirers: API RP 19D certification backlog duration is the leading indicator that ceramic testing laboratory capacity constraints will persist, freezing premium segment entry and sustaining incumbent pricing power. Five-to-ten year viability favors integrated mine-to-wellbore suppliers with rail-advantaged reserve positions. Monitor OSHA silica enforcement intensity in Texas transload corridors as the inflection signal for accelerated resin-coated substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Reserves | Wisconsin mine ownership secures baseload supply commitments from Permian drillers amid tightening silica regulations. |
| Long-term Supply Agreement Structuring | Five-year take-or-pay contracts with Diamondback Energy and Coterra Energy lock in delivered cost below WTI correlations. |
| Green Manufacturing Transition | Enclosed conveyor systems and real-time PM2.5 monitoring at Chippewa County operations preempt EPA Title V permit modifications. |
| Joint Venture for International Expansion | Bahía Blanca port logistics partnerships position first-mover suppliers for Neuquén Basin unconventional development. |
| Technology Licensing for Ceramic Coatings | Nanoscale alumina coating patents from Saint-Gobain Proppants enable ultra-lightweight ceramic conductivity preservation in soft shale. |
Methodological Framework
SEC 10-K filings, EIA drilling productivity reports, and EPA enforcement action databases formed the secondary backbone for supply concentration and regulatory trajectory assessment. Primary interviews with mine operations managers, Permian Basin procurement leads at E&P operators, rail logistics coordinators, and ceramic proppant R&D directors validated capacity utilization and pricing structure assumptions. Bottom-up and top-down triangulation reconciled proppant intensity per well data against basin-level completion forecasts.
Bottom-up modeling built from individual well proppant load specifications across Permian, Eagle Ford, and Bakken formations, while top-down analysis tracked rail car fleet deployments and transload facility throughput. Segmentation dimensions included product type, formation depth tier, closure stress category, and logistics integration level. CAGRs were derived from regression analysis linking lateral length extension trajectories to proppant consumption coefficients. Forecast inputs incorporated OSHA silica enforcement probability weights and ceramic substitution elasticity in deep formation plays.
Caveats apply where EPA National Ambient Air Quality Standard revisions or state-level silica exposure limit tightening could materially shift the outlook toward accelerated resin-coated and ceramic adoption. Deviation in Permian Basin drilling activity or rail logistics capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
Global Fracking Fluids and Chemicals Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
Egypt Oil and Gas Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
Oil and Gas Automation and Instrumentation Market
Oil & Gas
Drilling Bits Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
Crude Oil Desalter and Electrostatic Dehydrator Market
Oil & Gas
Europe Oilfield Chemicals Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market