
 LNG Bunkering Market | 2026-2036
LNG Bunkering Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Bunkering Market Analysis
Container shipping consolidation among top-ten liner operators is pivoting LNG bunkering procurement toward long-term offtake contracts with dedicated suppliers. Shell plc leverages its integrated LNG production and marine fuel distribution network to anchor terminal-based delivery positions in major hub ports. TotalEnergies SE sustains competitive coverage through floating storage and regasification assets that extend bunkering reach beyond fixed infrastructure. Korea Gas Corporation specializes in cryogenic handling systems that differentiate its service for new-build LNG-fueled vessel programs.
LNG bunkering denotes the transfer of liquefied natural gas, stored at minus 162 degrees Celsius in vacuum-insulated tanks, to marine vessels for propulsion or auxiliary power generation. The process requires cryogenic pumps, vapor return systems, and custody transfer metering to maintain fuel integrity and safety during loading operations. Ship-to-ship delivery dominates operational flexibility for large cargo vessels requiring volumes that exceed truck-to-ship capacity, while port-based infrastructure anchors fixed demand from ferry routes with predictable schedules. Retrofit services command premium margins as existing vessel owners adapt tonnage to dual-fuel configurations without new-build capital outlay.
The International Maritime Organization enforces sulfur content limits through MARPOL Annex VI, compelling vessel operators to adopt LNG as compliant fuel or install exhaust scrubbers. The EU Green Deal and F-Gas Regulation shape infrastructure investment standards for European port operators developing land-based bunkering systems. Classification societies including Lloyd's Register and DNV publish guidelines for cryogenic fuel containment and bunkering procedures that determine vessel certification and insurance eligibility. Stakeholders must monitor regulatory alignment between flag-state requirements and port-state control regimes to anticipate compliance cost structures and infrastructure deployment timelines.
Market Dynamics
Container shipping lines are consolidating procurement power around dedicated LNG offtake contracts, compressing spot-market liquidity and forcing terminal operators to secure long-term supply commitments before infrastructure deployment. This buyer-side concentration is reshaping capital allocation across the bunkering value chain.
Growth Catalysts
- MARPOL Annex VI sulfur caps:The International Maritime Organization's fuel sulfur limits compel vessel operators to adopt LNG or install exhaust scrubbers, creating structural demand pull for compliant bunkering infrastructure.
- Ship-to-ship delivery systems:Cryogenic transfer technology enables large cargo vessels to receive fuel volumes exceeding truck-to-ship capacity, unlocking operational flexibility for deep-sea container routes.
- EU Green Deal port investment:European port operators access capital for land-based bunkering systems under unified decarbonization frameworks, accelerating fixed infrastructure deployment.
Market Restraints
- Cryogenic storage capex intensity:Vacuum-insulated tank systems and vapor return infrastructure require substantial upfront investment, limiting terminal development to well-capitalized port authorities.
- Supply concentration in Qatar and Australia:LNG production geography concentrates feedstock availability, exposing bunkering operators to shipping cost volatility and contract renegotiation risk.
- Bio-LNG substitution pressure:Renewable synthetic methane variants compete for sustainability-minded fleet operators seeking lifecycle emissions reductions beyond conventional LNG.
Strategic Opportunities
- Retrofit service expansion:Existing vessel owners seek dual-fuel conversions without new-build capital outlay, creating premium-margin service demand for cryogenic system integrators.
- Ferry route electrification corridors:Predictable short-haul schedules in the Baltic and Mediterranean enable dedicated bunkering contracts with volume certainty.
- ISO 20570 bunkering standardization:Emerging international protocols for cryogenic fuel transfer procedures reduce insurance friction and accelerate vessel certification timelines.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in minus 162 degrees Celsius handling systems remains concentrated among legacy LNG liquefaction project veterans, constraining service expansion.
- Flag-state certification misalignment:Vessel operators face fragmented approval processes across Lloyd's Register, DNV, and national maritime authorities, extending compliance timelines.
- Legacy diesel infrastructure stranded asset risk:Port authorities must manage write-downs on conventional bunkering assets while financing parallel LNG systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Bunkering Market |
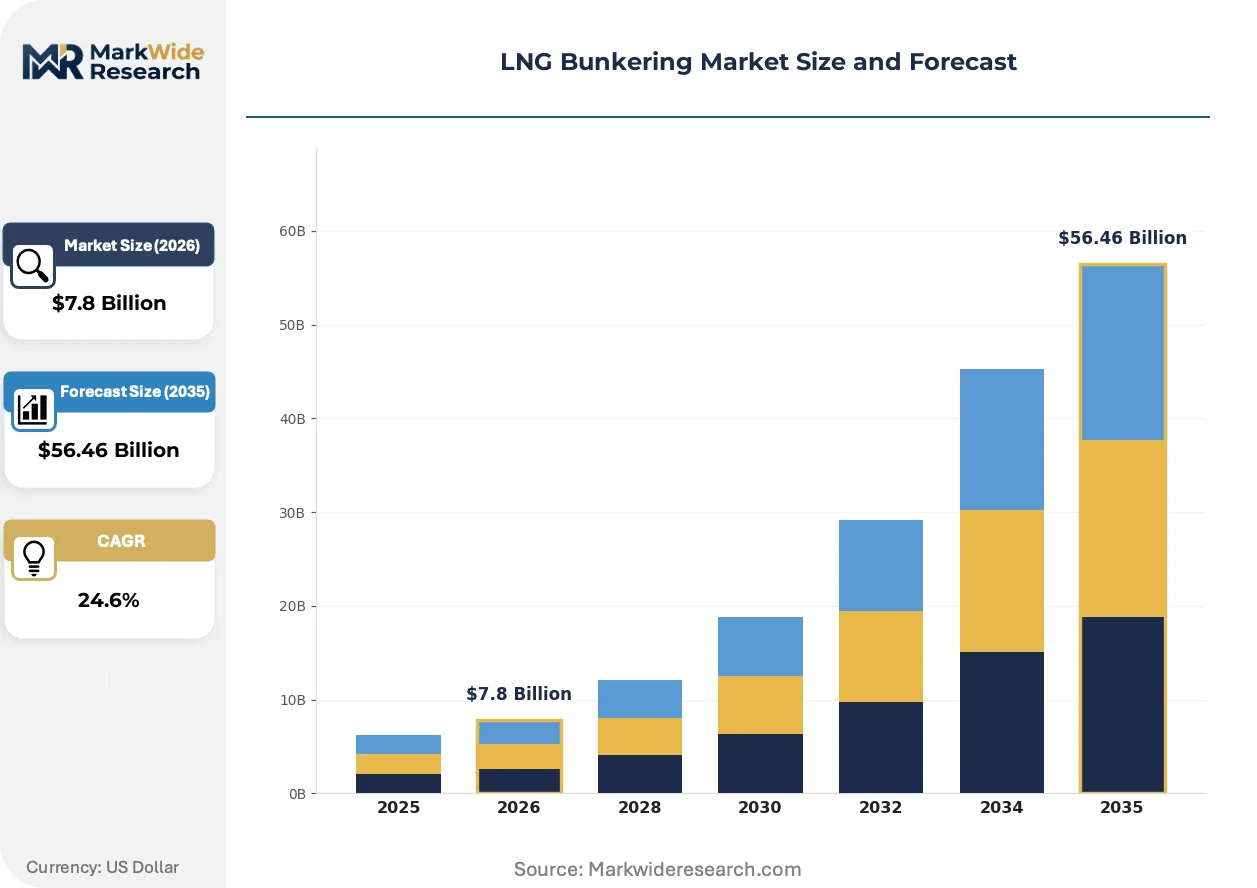
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $56.46 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Port-Based, Ship-to-Ship, Truck-to-Ship, Terminal-based Service Type: New Build, Retrofit, Maintenance, Consultancy End User: Cargo Vessels, Ferries, Fishing Boats, Offshore Support Vessels Infrastructure Type: Land-Based, Floating Storage, Barge Systems, Regasification Terminals |
| Companies Covered | Shell plc, TotalEnergies SE, Gazprom Neft, ENGIE SA, Korea Gas Corporation, ENN Energy Holdings, Harvey Gulf International Marine, Gasum Oy, Eagle LNG Partners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Bunkering Market Emerging Trajectories
Digital custody transfer systems and automated vapor recovery are compressing bunkering cycle times while cryogenic pump efficiency gains reduce boil-off losses. These advances are enabling new operational models that challenge traditional terminal-based delivery economics.
Submerged cryogenic pump technology is rewriting fuel transfer economics by eliminating deck-mounted equipment and reducing vessel alongside time. Large container lines including MSC and CMA CGM are specifying these systems for new-build dual-fuel tonnage. The technology is compressing port call duration and enabling higher-frequency bunkering without berth congestion.
The EU F-Gas Regulation is tightening containment system standards for European port infrastructure, mandating enhanced vapor recovery and leak detection protocols. Terminal operators in Rotterdam and Antwerp are retrofitting existing facilities to meet phased compliance deadlines. Container shipping lines with EU-dedicated fleets are prioritizing certified terminals, creating competitive segmentation in hub port rankings.
Charter-party fuel clauses are evolving to split LNG price risk between shipowners and cargo interests, displacing traditional bunker adjustment factor mechanisms. This contractual innovation is most visible in Asia-Europe trades where long-term volume commitments anchor infrastructure investment. Freight forwarders and cargo owners are gaining direct exposure to LNG price volatility, reshaping hedging demand across marine fuel derivatives markets.
LNG Bunkering Market Segmentation
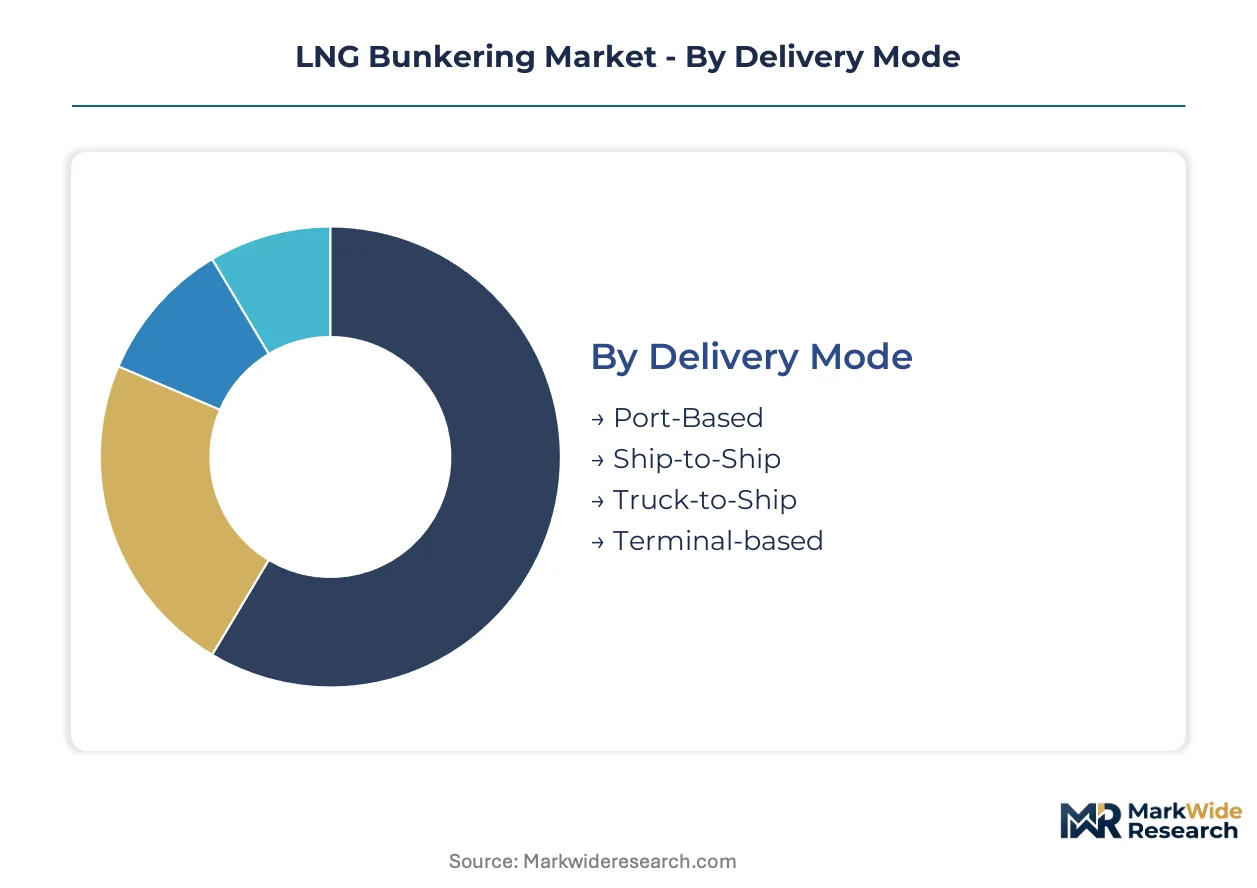
LNG bunkering segmentation reveals how fuel delivery economics fragment across vessel types, infrastructure configurations, and service models. Each axis carries distinct capital intensity profiles and regulatory exposure that shape supplier positioning.
Delivery Mode:
Cryogenic transfer technology defines operational flexibility and volume scalability across maritime supply chains.
- Ship-to-Ship:Cryogenic transfer between specialized bunkering vessels and receiving ships enables fuel volumes exceeding 1,000 cubic meters per operation. Deep-sea container lines operating Asia-Europe routes concentrate procurement here, driven by berth congestion avoidance and minimal port call duration extension.
- Port-Based:Fixed terminal infrastructure with vacuum-insulated storage tanks and vapor return systems anchors predictable demand from scheduled ferry services. Baltic Sea operators prioritize these installations for route electrification corridors under EU Green Deal frameworks.
- Truck-to-Ship:Road-mobile cryogenic tanker delivery suits smaller vessels and remote port calls lacking dedicated infrastructure. Fishing fleets and offshore support vessels in dispersed geographies rely on this modality.
- Terminal-based:Integrated liquefaction or regasification facilities with dedicated marine loading arms serve high-throughput hub ports. Singapore and Rotterdam authorities anchor investment concentration here.
Mature deployment sits with Port-Based systems. Newer deployment is concentrated in Ship-to-Ship configurations.
Service Type:
Capital deployment timing separates service demand between vessel construction cycles and operational retrofit windows.
- New Build:Dual-fuel engine specification and cryogenic tank integration during original construction commands premium engineering margins. Korean shipyards anchor global capacity for LNG-fueled container vessel programs.
- Retrofit:Conversion of existing diesel tonnage to dual-fuel capability involves engine modification, fuel gas supply system installation, and tank retrofit. Container lines seeking IMO 2020 compliance without fleet replacement drive fastest expansion here.
- Maintenance:Cryogenic pump overhaul, vapor recovery system calibration, and insulation integrity testing sustain operational safety margins.
- Consultancy:Regulatory pathway navigation, flag-state certification preparation, and bunkering procedure documentation support first-time LNG adopters.
Retrofit services are climbing the fastest as existing fleet owners defer new-build capital commitments.
End User:
Vessel operational profiles determine fuel volume predictability and bunkering infrastructure requirements.
- Cargo Vessels:Container ships, bulk carriers, and tankers with predictable route structures anchor long-term offtake contracting. Top-ten liner operators consolidate procurement power through dedicated supply agreements.
- Ferries:Short-haul passenger and vehicle services with fixed schedules enable dedicated terminal investment and volume certainty. Mediterranean and Baltic routes concentrate deployment under EU decarbonization mandates.
- Fishing Boats:Smaller vessels with dispersed port calls and irregular fueling patterns rely on truck-to-ship delivery flexibility.
- Offshore Support Vessels:Platform supply and anchor handling operations in remote basins require mobile bunkering solutions and cryogenic storage durability.
Cargo Vessels dominate contract value. Ferries represent the steepest infrastructure deployment trajectory.
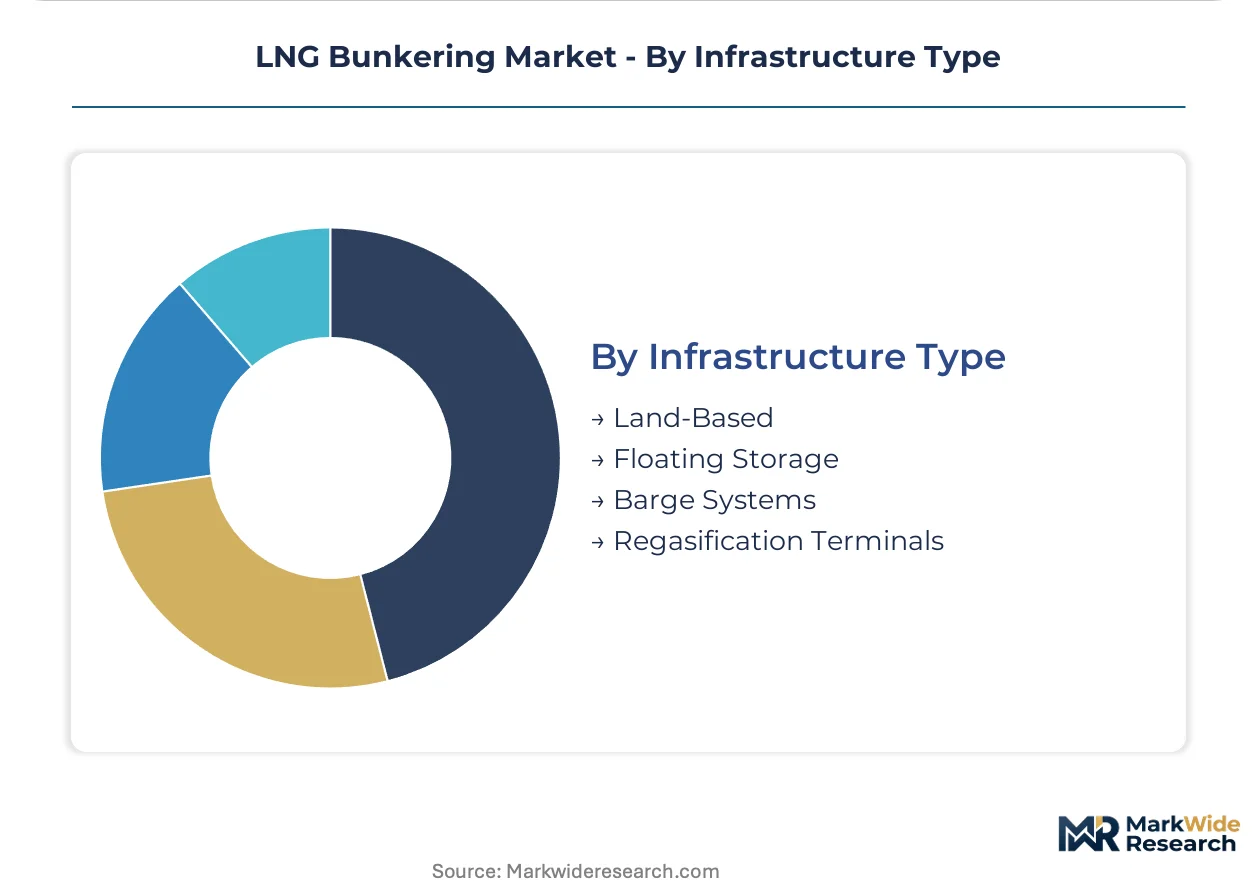
Infrastructure Type:
Physical asset configuration determines feedstock access, storage duration, and regulatory compliance scope.
- Land-Based:Fixed shoreside tanks with permanent cryogenic pumps and custody transfer metering anchor hub port economics. EU F-Gas Regulation mandates enhanced vapor recovery for European installations.
- Floating Storage:Moored LNG carriers or specialized vessels provide buffer capacity without permanent land commitment. Singapore and Middle Eastern ports deploy these for demand volatility absorption.
- Barge Systems:Self-propelled or towed flat-deck units with modular tankage extend bunkering reach to secondary ports. River and coastal operations in China leverage this configuration.
- Regasification Terminals:Import facilities with marine loading capability dual-purpose feedstock supply and bunkering distribution. Qatar and Australia export geography shapes availability.
Land-Based systems hold established certification pathways. Floating Storage is gaining share fastest in emerging hub development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container shipping lines concentrate procurement power in ports where ship-to-ship infrastructure anchors Asia-Europe trade lanes. Demand clusters around Singapore, Rotterdam, and Shanghai as dedicated LNG offtake contracts reshape terminal investment timing.
Singapore
Asia-Europe container routes drive bunkering volume through the Port of Singapore Authority's liquefaction and marine loading investments. The Maritime and Port Authority of Singapore mandates LNG-ready terminal standards under its Green Port Programme. Jurong Island anchors integrated supply chains where Shell plc and TotalEnergies SE hold dedicated storage positions.
Netherlands
EU Green Deal frameworks accelerate Rotterdam's land-based terminal deployment for Baltic and Mediterranean ferry corridors. The EU F-Gas Regulation enforces enhanced vapor recovery standards that reshape infrastructure certification timelines. The Port of Rotterdam Authority coordinates with Gasunie on cryogenic storage expansion along the Maasvlakte industrial zone.
South Korea
Korean shipyards dominate new-build dual-fuel container vessel output, pulling bunkering service demand toward Ulsan and Busan clusters. The Ministry of Trade, Industry and Energy channels public capital into cryogenic handling systems through national hydrogen-LNG convergence programs. Korea Gas Corporation specializes in minus 162 degrees Celsius infrastructure that differentiates its terminal offerings.
United States
Gulf Coast export geography positions Houston and Corpus Christi for Atlantic basin bunkering distribution to container and cruise fleets. The Federal Energy Regulatory Commission governs LNG export terminal siting that dual-purposes feedstock supply and marine fuel loading. Eagle LNG Partners anchors Jones Act-compliant small-scale distribution along the Florida coast and Caribbean routes.
Qatar
Ras Laffan Industrial City's liquefaction capacity feeds bunkering demand through regasification terminals with marine loading capability. The Qatar Energy regulatory framework prioritizes long-term supply contracting that matches container line procurement consolidation. Qatari production geography exposes European and Asian bunkering operators to shipping cost volatility on term cargo.
LNG Bunkering Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue floating storage and mobile bunkering configurations that bypass fixed infrastructure commitments. The market structures around three archetypes: integrated oil majors with captive LNG production, national gas utilities leveraging cryogenic expertise, and specialized marine fuel distributors with Jones Act or regional licensing positions. Consolidation pressure intensifies as container lines consolidate procurement into dedicated offtake agreements. Competitive moves center on terminal concession securing and ship-to-ship vessel fleet expansion.
Within the integrated major tier, Shell plc and TotalEnergies SE exemplify players combining upstream liquefaction control with marine distribution networks. Korea Gas Corporation represents the national utility archetype, translating domestic cryogenic handling experience into bunkering service differentiation. Among specialized distributors, Eagle LNG Partners occupies a position focused on small-scale Atlantic basin logistics. These anchors illustrate how supplier positioning fragments across production integration, infrastructure control, and regional licensing vectors.
| Leading Market Players |
|---|
| Shell plc |
| TotalEnergies SE |
| Gazprom Neft |
| ENGIE SA |
| Korea Gas Corporation |
| ENN Energy Holdings |
| Harvey Gulf International Marine |
| Gasum Oy |
| Eagle LNG Partners |
| Others |
Supply Flow & Price Mechanics
Container shipping lines consolidating procurement into dedicated LNG offtake contracts are forcing terminal operators to secure multi-year supply commitments before infrastructure deployment, compressing spot-market liquidity and anchoring pricing power with integrated producers who control liquefaction assets.
Pricing Analysis
High-volume ship-to-ship delivery commands premium margins against truck-to-ship and port-based alternatives. Three-tier pricing structure across premium, standard, and economy levels separates certified EU F-Gas terminals from legacy installations and remote mobile operations. Cost compression in the standard tier is intensifying as Qatar and Australian feedstock shipping volatility feeds into contract renegotiations. Cargo vessel operators with consolidated procurement power exhibit lowest price sensitivity, while fishing fleets and offshore support vessels in dispersed geographies face acute cost pressure.
Supply Chain Analysis
Dual-sourcing qualification requirements from major container lines are compelling bunkering operators to maintain feedstock relationships across Qatar, Australia, and the United States Gulf Coast. Cryogenic storage tanks, vapor return systems, and specialized ship-to-ship transfer vessels draw from steel fabrication in South Korea and China plus cryogenic pump engineering concentrated in Europe. Single-source vulnerability on Qatari term cargo exposes Asian and European operators to shipping cost spikes. Distribution runs through integrated oil majors with captive liquefaction, national gas utilities with cryogenic expertise, and specialized marine fuel distributors holding regional licensing positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MARPOL Annex VI sulfur enforcement creates a compliance moat where certified terminal operators capture stranded demand from scrubber-adverse fleets, raising barriers for uncertified entrants.
For Market Incumbents: Lock in long-term offtake contracts with top-ten container lines before rival terminals achieve EU F-Gas certification. Expand ship-to-ship vessel fleets in Singapore and Rotterdam to defend against floating storage entrants bypassing fixed infrastructure commitments. Bio-LNG substitution pressure demands backward integration into renewable synthetic methane supply chains to preserve premium positioning. For New Entrants and Emerging Players: Digital custody transfer platforms offering automated vapor recovery and real-time custody metering present a channel route to bypass incumbent terminal concessions. Target truck-to-ship service gaps in Southeast Asian and African secondary ports where dispersed fishing and offshore support vessel demand lacks dedicated infrastructure. Partner with classification societies on ISO 20570 bunkering standardization to accelerate vessel certification timelines. For Investors and Strategic Acquirers: Re-rating potential sits with national gas utilities possessing cryogenic handling expertise given EU Green Deal port investment acceleration. Five-to-ten year viability favors operators with integrated liquefaction access and marine distribution networks over pure-play terminal developers. Watch for charter-party fuel clause evolution splitting LNG price risk between shipowners and cargo interests as the signal for derivatives market depth sufficient to support infrastructure scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Ship-to-Ship Vessel Fleet Expansion | MSC and CMA CGM specifications for submerged cryogenic pumps compress port call duration. |
| EU F-Gas Terminal Certification | Rotterdam and Antwerp retrofits create competitive segmentation in hub port rankings. |
| Dual-Fuel Retrofit Service Scaling | Existing vessel owners seeking IMO 2020 compliance without new-build capital drive premium margins. |
| Long-Term Offtake Contracting | Shell and TotalEnergies anchor dedicated storage positions through procurement consolidation. |
| Bio-LNG Supply Chain Integration | Renewable synthetic methane variants compete for sustainability-minded fleet operators. |
Methodological Framework
Independent corroboration across terminal operators, ship-to-ship vessel engineers, and container line procurement executives underwrites the qualitative findings. Primary interviews with cryogenic system integrators, port authority infrastructure planners, and classification society surveyors combined with secondary validation from Lloyd's Register guidelines, DNV certification protocols, and EU F-Gas Regulation filings. Customs data on LNG cargo movements, SEC filings from integrated oil majors, and IEA marine fuel reports anchor quantitative inputs. Bottom-up vessel deployment tracking and top-down infrastructure investment flows triangulate market sizing.
Rate-of-change decomposition separates volume growth from price evolution across delivery mode, service type, end user, and infrastructure type segmentation. Delivery mode splits between ship-to-ship, port-based, truck-to-ship, and terminal-based configurations. Service type captures new-build, retrofit, maintenance, and consultancy demand. Infrastructure type distinguishes land-based, floating storage, barge systems, and regasification terminals. CAGRs derive from vessel orderbook analysis, terminal concession timelines, and regulatory compliance deadlines. Cryogenic engineering talent availability and flag-state certification alignment pace constrain supply-side expansion.
The model holds under sustained MARPOL Annex VI enforcement and EU Green Deal funding continuity; deviation in IMO regulatory stringency or Qatari supply contract renegotiation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
Reservoir Analysis Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
Middle East and Africa Pipeline Maintenance Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Distributed Fiber Optic Sensor in Oil & Gas Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Middle-East and Africa Frac Stack Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Proppant Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Frac Tree Market