
 Desalter Market | 2026-2036
Desalter Market Size, Share, and Industry Trends Forecast 2026-2036
Desalter Market Outlook
EU Green Deal wastewater discharge rules and EPA effluent limitation guidelines for oil and gas extraction is consolidating procurement standards across offshore and onshore operations. Schlumberger leverages its integrated project delivery model to anchor long-term service contracts in the Middle East and North Sea. Baker Hughes competes through advanced electrostatic coalescer designs that cut chemical injection rates. Alfa Laval specializes in compact, skid-mounted desalter packages suited for offshore platform retrofits where space constraints dominate.
A desalter removes dissolved salts and residual water from crude oil or treats saline water sources through phase separation, electrostatic coalescence, or membrane-based rejection, typically operating at pressures between 50 and 150 psi and temperatures of 100–160°F to optimize water-oil separation efficiency. Horizontal desalters dominate upstream oilfield installations due to superior residence time and handling of high-water-cut crudes, while compact desalters are gaining share in offshore brownfield upgrades where deck load limits apply. Reverse osmosis technology leads the non-thermal segment for seawater desalination applications, though multi-effect distillation retains preference where waste heat from power generation is available.
EPA effluent guidelines under the Clean Water Act, EU REACH chemical restrictions on demulsifier formulations, and Saudi Arabia's Saline Water Conversion Corporation standards collectively shape equipment specifications, chemical compatibility requirements, and market access conditions for suppliers. The International Maritime Organization's ballast water management conventions are extending desalter-adjacent treatment demand into vessel-based crude transport. Stakeholders must monitor how national oil companies integrate carbon-intensity benchmarks into desalter procurement criteria.
Market Dynamics
Electrocoalescer miniaturization is compressing equipment footprints across offshore platforms while Middle Eastern national oil companies consolidate procurement around integrated water treatment packages that bundle desalination with produced-water handling.
Growth Catalysts
- EPA effluent limitation guidelines:Tighter discharge standards for oil and gas extraction operations in the United States mandate upgraded water treatment infrastructure at both greenfield and brownfield sites.
- Horizontal desalter technology:Superior residence time characteristics enable efficient processing of high-water-cut crudes, driving replacement demand across mature oilfields in Saudi Arabia and Iraq.
- Offshore platform retrofits:Deck load constraints on aging North Sea and Gulf of Mexico installations accelerate procurement of compact, skid-mounted desalter packages.
Market Restraints
- Specialized alloy supply concentration:Duplex stainless steel and super-duplex material sourcing clusters in Nordic and Japanese metallurgical suppliers, exposing fabricators to price volatility and extended lead times.
- Multi-effect distillation thermal inertia:Large-scale MED plants require substantial waste heat integration with adjacent power generation, limiting deployment flexibility where co-located infrastructure is absent.
- EU REACH chemical restrictions:Demulsifier formulation constraints raise chemical procurement costs and complicate compatibility testing for electrostatic coalescer systems operating in European waters.
Strategic Opportunities
- Floating production storage and offloading vessels:FPSO newbuild programs in Brazil and West Africa create demand for modular desalter systems that can be containerized and crane-lifted onto converted hulls.
- Saudi Saline Water Conversion Corporation standards:National water security procurement frameworks favor vendors offering combined seawater desalination and produced-water treatment capabilities.
- Electrocoalescer-membrane hybrid architectures:Convergence of electrostatic separation with reverse osmosis pretreatment enables single-vessel processing of highly emulsified feedstocks previously requiring multi-stage trains.
Industry Challenges
- Electrostatic coalescer electrode calibration:Field technicians skilled in high-voltage field optimization across variable crude compositions remain scarce, extending commissioning timelines for complex installations.
- Legacy vessel integration:Retrofitting horizontal desalters into existing tank farms with fixed piping geometries demands custom nozzle configurations and structural reinforcement engineering.
- IMO ballast water management certification:Vessel-based crude carriers must demonstrate treatment efficacy against invasive species protocols, adding compliance layers to desalter-adjacent system design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desalter Market |
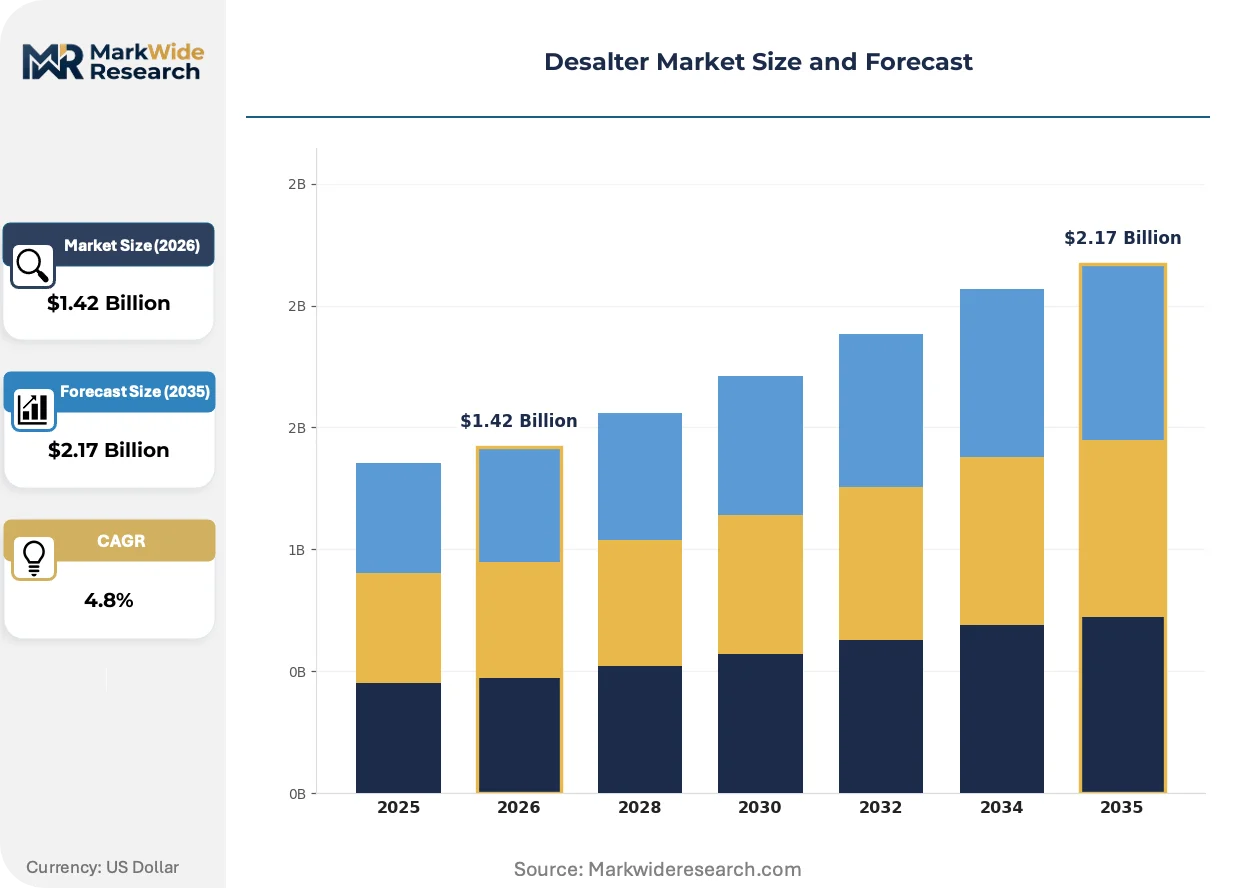
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Vertical Desalters, Horizontal Desalters, Compact Desalters, Large-Scale Desalters Technology: Reverse Osmosis, Electrodialysis, Multi-Effect Distillation, Vacuum Distillation End User: Oil & Gas Industry, Power Generation, Municipal Water Supply, Agricultural Sector Application: Seawater Desalination, Brackish Water Treatment, Wastewater Recycling, Industrial Process Water |
| Companies Covered | Schlumberger, Halliburton, Alfa Laval, Frames Group, Veolia Water Technologies, Baker Hughes, Honeywell, Canadian Petroleum Processing Equipment Inc., EN-FAB Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desalter Market Strategic Shifts
Equipment miniaturization, regulatory convergence on chemical discharge, and procurement consolidation around lifecycle service contracts are compressing traditional vendor boundaries between desalter OEMs and water treatment service providers.
Electrocoalescer technology is overtaking conventional gravity settling in offshore brownfield upgrades. These systems apply high-voltage electric fields to accelerate water droplet coalescence, cutting residence time requirements by half. North Sea operators facing platform weight restrictions are retrofitting compact electrostatic units into existing vessel footprints, enabling capacity expansion without structural deck modifications. This shift is overtaking the historical dominance of large-diameter horizontal separators in space-constrained environments.
EU Green Deal wastewater discharge rules are harmonizing effluent standards across member state oil and gas operations. The framework mandates numeric limits on oil-in-water content that exceed legacy national permits, forcing operators in the Netherlands, Norway, and UK continental shelf to upgrade treatment trains. Offshore platform clusters in the Danish and Norwegian sectors are responding by procuring integrated electrostatic-membrane packages that guarantee compliance across variable feed conditions.
Lifecycle service contracting is displacing equipment-only procurement in Middle Eastern upstream operations. Saudi Aramco and ADNOC are bundling desalter supply with ten-year chemical management and performance guarantees, transferring operational risk to vendors. This model concentrates vendor selection around integrated service capabilities rather than capital cost minimization, favoring firms with regional chemical logistics networks and local technical staffing.
Desalter Market Segmentation
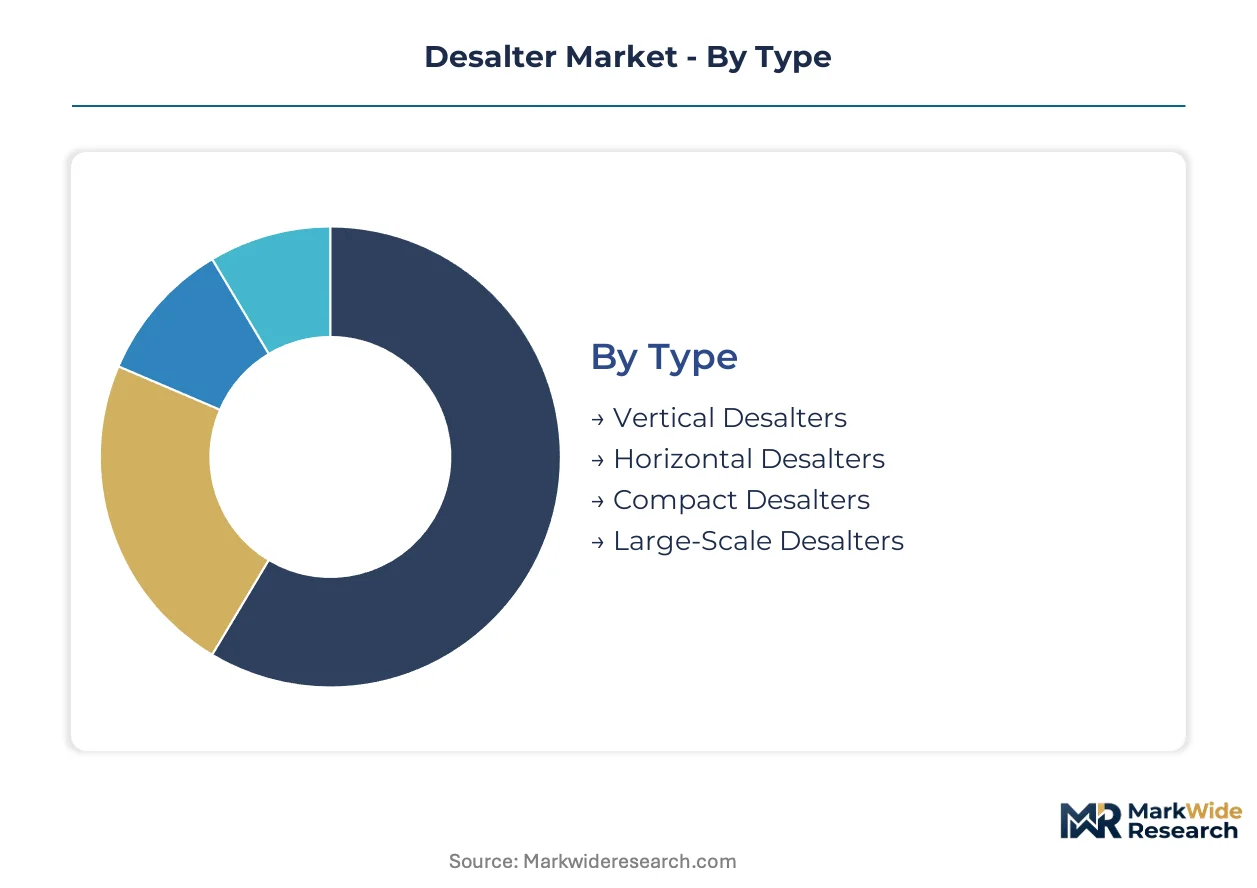
Desalter procurement patterns diverge sharply across vessel geometry, separation technology, and end-use chemistry. Understanding these splits reveals where capital deployment concentrates and which specifications command premium pricing.
Type:
Capital intensity peaks with large-scale field installations requiring extensive civil works and alloy fabrication, while compact units minimize upfront outlay through modular skidding.
- Horizontal Desalters:These cylindrical vessels orient the oil-water interface horizontally to maximize residence time and separation efficiency. Demand concentrates in Saudi Arabia and Iraq where high-water-cut crude processing requires extended settling periods. National oil companies specify these for greenfield upstream expansions despite higher steel tonnage requirements.
- Compact Desalters:Skid-mounted electrostatic units compress separation into vertically stacked configurations. North Sea platform retrofits drive procurement where deck load limits prohibit additional structural reinforcement. Operators in the UK and Norwegian sectors prioritize these for brownfield capacity additions.
- Vertical Desalters:Traditional upright vessels suit onshore tank farms with available footprint. Lower fabrication complexity reduces lead times for standard crude processing.
- Large-Scale Desalters:Field-erected systems exceeding 20-meter diameter serve integrated water treatment hubs. Saudi Saline Water Conversion Corporation procurement frameworks favor these for combined desalination and produced-water handling.
Most installed capacity flows through Horizontal Desalters. Expansion is steepest in Compact Desalters.
Technology:
Energy intensity and thermal integration requirements separate these approaches, with membrane-based methods dominating where electricity costs undercut thermal fuel inputs.
- Reverse Osmosis:Semi-permeable membranes reject dissolved salts under high pressure without phase change. Municipal water supply in Saudi Arabia and UAE deploys this for seawater desalination where grid power availability exceeds waste heat access. Membrane replacement schedules and energy recovery device performance define lifecycle economics.
- Multi-Effect Distillation:Successive evaporation stages concentrate brine using waste heat from adjacent power generation. Kuwait and Qatar favor this technology where cogeneration infrastructure already exists. Thermal inertia limits deployment flexibility but yields superior water quality for boiler feed applications.
- Electrodialysis:Ion-selective membranes and direct current remove salts from brackish sources. Agricultural sector adoption in Israel and Spain targets irrigation water with moderate salinity.
- Vacuum Distillation:Reduced-pressure boiling enables low-temperature separation for heat-sensitive industrial process water. Niche applications in pharmaceutical and food processing sectors.
Reverse Osmosis commands the greatest installed base. Electrodialysis is gaining share fastest in agricultural water reuse.
End User:
Operational risk tolerance and chemical compatibility requirements shape procurement specifications across these verticals.
- Oil & Gas Industry:Upstream producers require desalters that handle variable crude compositions and aggressive corrosive species. Saudi Aramco and ADNOC bundle equipment with long-term chemical management contracts. Produced-water reinjection regulations in Texas and Alberta mandate treatment depth that favors electrostatic coalescence.
- Municipal Water Supply:Public utilities prioritize operational simplicity and energy efficiency over separation speed. Saudi Arabia's national water security strategies concentrate procurement of large-scale seawater desalination.
- Power Generation:Boiler feedwater specifications drive ultrapure output requirements. Combined cycle plants in the UAE integrate MED for waste heat utilization.
- Agricultural Sector:Irrigation water quality standards are less stringent than industrial applications. Israel's drip irrigation infrastructure demands consistent salinity reduction.
Oil & Gas Industry accounts for the dominant share of equipment value. Municipal Water Supply is expanding most quickly in water-stressed Gulf states.
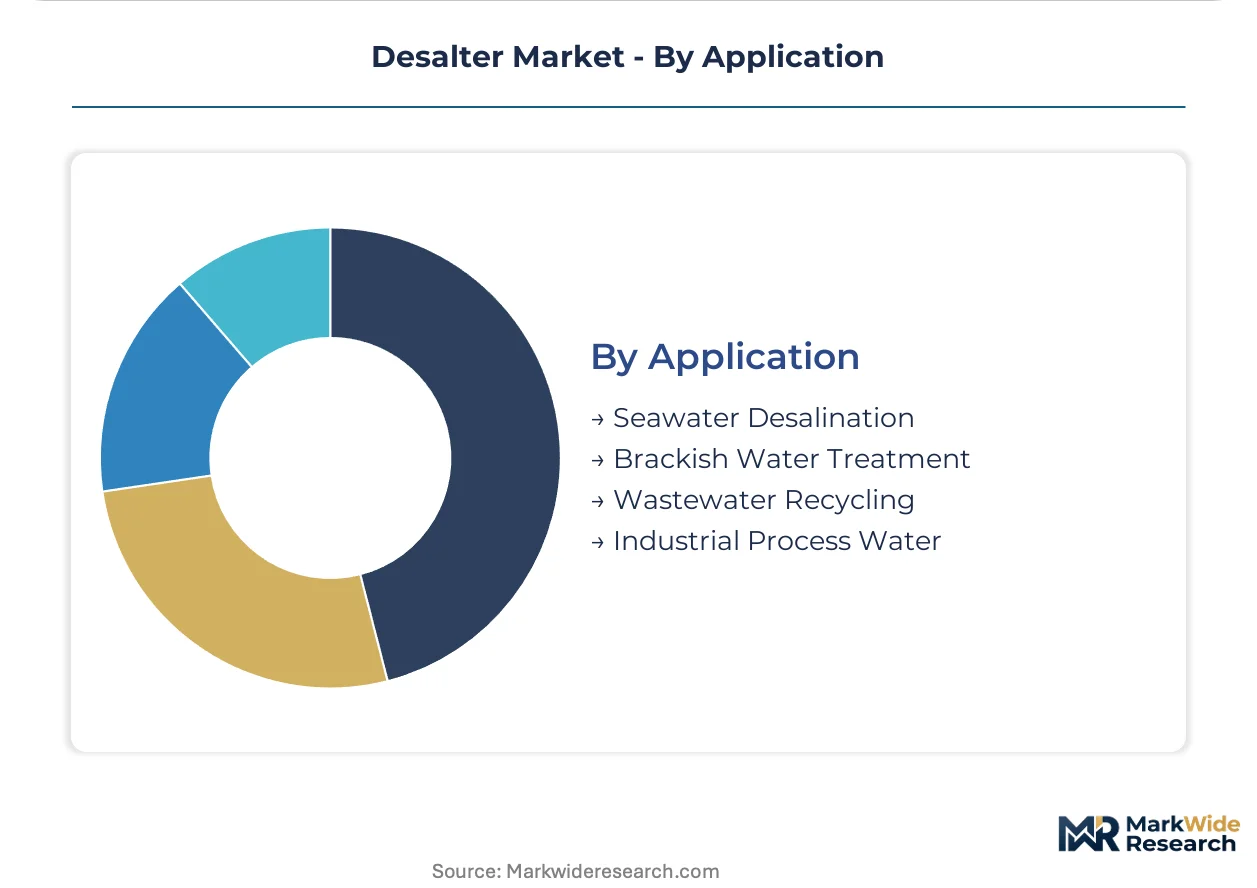
Application:
Feedstock salinity and contaminant profiles determine technology selection and pretreatment complexity.
- Seawater Desalination:High total dissolved solids and biofouling potential require extensive pretreatment trains. Saudi Arabia's Red Sea and Arabian Gulf coastlines concentrate demand for large-capacity installations.
- Industrial Process Water:Manufacturing facilities require consistent chemistry for cooling and boiler systems. Petrochemical complexes in Texas and Louisiana specify integrated treatment packages.
- Brackish Water Treatment:Moderate salinity sources in inland aquifers suit lower-energy electrodialysis. Agricultural users in California's Central Valley deploy these for irrigation supply.
- Wastewater Recycling:Oilfield produced water and municipal effluent reuse demand robust contaminant rejection. Texas Railroad Commission discharge rules tighten treatment requirements.
Seawater Desalination carries the largest cumulative investment. Wastewater Recycling is climbing the fastest as produced-water volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The desalter industry traces its modern scaling to the 1950s American Southwest, where Texas oilfield operators pioneered electrostatic coalescence for high-salinity crude processing before technology transfer anchored Middle Eastern upstream infrastructure.
Saudi Arabia
Saline Water Conversion Corporation procurement frameworks and Aramco upstream expansion drive dual demand for seawater desalination and produced-water treatment. SFDA chemical compatibility standards shape demulsifier formulation requirements for electrostatic systems. The Eastern Province concentrates large-scale field-erected installations serving Ghawar and Safaniya oilfields.
United States
Permian Basin water-cut escalation and Gulf of Mexico platform aging create parallel demand for high-capacity horizontal units and compact retrofits. EPA effluent limitation guidelines under the Clean Water Act mandate treatment depth upgrades across Texas and Louisiana. Houston anchors fabrication clusters supplying electrostatic coalescer packages for domestic and export markets.
Norway
North Sea platform weight restrictions and decommissioning timelines accelerate compact electrostatic unit procurement. EU Green Deal wastewater discharge rules harmonize effluent standards exceeding legacy national permits. Stavanger and Bergen clusters specialize in skid-mounted systems for brownfield capacity additions without structural deck modifications.
United Arab Emirates
ADNOC bundled service contracts and national water security strategies concentrate procurement of integrated treatment packages. MOHAP chemical registration requirements affect demulsifier supply chains for offshore operations. Abu Dhabi and Dubai serve as procurement hubs linking desalination capacity expansion with upstream produced-water handling.
Brazil
Pre-salt development and FPSO newbuild programs generate demand for containerized, crane-liftable desalter modules. ANVISA industrial water quality standards influence boiler feedwater specifications for offshore power generation. Rio de Janeiro and São Paulo fabrication yards supply modular systems for deepwater field developments.
Desalter Market Competitive Environment
Premium-margin players sit above commodity-margin players across service integration depth, with lifecycle contracting and chemical management bundling separating tier-one vendors from equipment-only suppliers. The vendor base concentrates around integrated oilfield service conglomerates, specialized water treatment OEMs, and regional fabrication shops serving brownfield retrofit demand. Three archetypes dominate: full-service providers anchoring national oil company frameworks, technology specialists licensing electrostatic designs, and modular fabricators targeting offshore space constraints. Competitive moves center on ten-year performance guarantee contracts and electrocoalescer-membrane hybrid system development.
Within the integrated service tier, Schlumberger and Halliburton exemplify vendors bundling equipment supply with chemical logistics and field operations. Baker Hughes occupies a position bridging electrostatic technology specialization with global service scale. Among pure-play water treatment specialists, Alfa Laval represents the compact modular archetype targeting offshore platform constraints, while Veolia Water Technologies anchors the municipal-industrial crossover segment. These five entities collectively illustrate the competitive spectrum from upstream oilfield integration through utility-scale desalination.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Alfa Laval |
| Frames Group |
| Veolia Water Technologies |
| Baker Hughes |
| Honeywell |
| Canadian Petroleum Processing Equipment Inc. |
| EN-FAB Inc. |
| Others |
Value Chain & Pricing Dynamics
Middle Eastern national oil company procurement consolidation around ten-year lifecycle service contracts anchors pricing power with integrated vendors bundling equipment, chemicals, and performance guarantees. This buyer concentration rewards regional service scale over capital-cost minimization, compressing margins for equipment-only suppliers while elevating premium capture for firms with captive chemical logistics networks.
Pricing Analysis
Project-based contracting with performance-guarantee escalations dominates upstream oilfield procurement, with pricing stratifying across integrated service bundles, standalone equipment sales, and aftermarket chemical supply tiers. Price differentiation rests on electrostatic coalescer efficiency ratings and SFDA chemical compatibility certifications. Cost compression in standard horizontal vessel fabrication intensifies as Chinese and Indian fabricators enter Middle Eastern supply chains. Municipal water utilities exhibit highest price sensitivity due to budget-cycle constraints, while FPSO operators accept premium positioning for modular, crane-liftable configurations.
Supply Chain Analysis
Single-source vulnerability sits with Nordic and Japanese metallurgical suppliers controlling duplex and super-duplex stainless steel production for corrosion-resistant vessel fabrication. Raw material procurement draws from nickel ore concentrates in Indonesia and the Philippines, with molybdenum alloying elements sourced from Chile and Peru. Tariff exposure on specialty steel imports into Saudi Arabia and the United States elevates landed costs for fabricators without long-term offtake agreements. Distribution runs through Houston, Stavanger, and Dubai as regional stocking hubs serving offshore platform retrofit demand and greenfield upstream expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The desalter market represents a late-cycle quality story as procurement shifts from equipment-only transactions toward integrated water treatment packages demanding decade-long performance accountability. This specification elevation favors vendors with regional chemical logistics infrastructure and localized technical staffing capabilities.
For Market Incumbents: Extend lifecycle service contracting depth by anchoring ten-year chemical management agreements with Saudi Aramco and ADNOC procurement frameworks. Counter electrocoalescer-membrane hybrid system entrants by securing exclusive alloy supply contracts with Japanese metallurgical suppliers. Prioritize certification investment under EU REACH and SFDA demulsifier formulation standards to maintain access to premium-tier European and Middle Eastern tenders. For New Entrants and Emerging Players: Electrocoalescer miniaturization for North Sea platform retrofits offers a technology-first wedge into an underserved brownfield segment where deck load constraints exclude incumbent horizontal vessel suppliers. Target Norwegian and UK continental shelf operators with containerized, skid-mounted units requiring no structural reinforcement. Pursue go-to-market partnerships with Stavanger-based engineering procurement contractors possessing established relationships with Equinor and Aker BP maintenance divisions. For Investors and Strategic Acquirers: Integrated oilfield service conglomerates are the most active acquirer in this space, seeking to deepen water treatment capabilities within existing national oil company relationships. Long-term viability across the analysis window hinges on chemical logistics regionalization rather than equipment manufacturing scale. Monitor Saudi Saline Water Conversion Corporation procurement framework amendments as the critical signal for integrated versus standalone system preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Electrocoalescer-Membrane Hybrid Development | Converges separation technologies for single-vessel processing of emulsified feedstocks at Saudi Aramco facilities. |
| Regional Chemical Logistics Expansion | Establishes localized demulsifier blending capabilities under SFDA and EU REACH compliance frameworks. |
| Compact Skid-Mounted System Certification | Enables North Sea platform retrofits without structural deck modifications under Norwegian Petroleum Safety Authority guidelines. |
| Long-Term Service Contract Anchoring | Locks in ten-year revenue visibility with ADNOC bundled procurement frameworks transferring operational risk. |
| Specialty Alloy Supply Agreement | Secures duplex stainless steel allocation from Japanese suppliers amid extended lead time volatility. |
Study Parameters
Coverage spans Saudi Arabia, the United States, Norway, the United Arab Emirates, and Brazil, with primary inputs from each market cluster. The research combines structured interviews with desalter OEM technical directors, national oil company procurement managers, EPC contractor water treatment specialists, and aftermarket chemical supply coordinators with secondary validation from SEC filings, customs trade databases, EPA effluent guideline dockets, and EU Green Deal implementation reports. Bottom-up project pipeline enumeration triangulates against top-down national water security strategy assessments.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts across the projection horizon. The analytical framework models desalter demand by vessel geometry, separation technology, end-use vertical, and application chemistry, with additional dimensioning by regulatory compliance tier. CAGRs derive from installed base replacement cycles, greenfield upstream capacity announcements, and produced-water volume projections. Industry-specific inputs include Saudi Aramco master gas system expansion timelines and Permian Basin water-cut escalation curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Middle Eastern national oil company procurement framework revisions, EU REACH chemical restriction amendments, and specialty steel supply concentration disruptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Pipeline Integrity Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Downhole Drilling Tools Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Europe Completion Equipment and Services Market
Oil & Gas
Crude Oil Desalter Market
Oil & Gas
Italy Oil and Gas Market
Oil & Gas
Asia-Pacific Well Intervention Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
Mexico Oil and Gas Market
Oil & Gas
FTIR Oil Condition Monitoring Market
Oil & Gas
Intelligent Well Completion Market