
 Global Oil Line Corrosion Inhibitors Market | 2026-2036
Global Oil Line Corrosion Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oil Line Corrosion Inhibitors Market Foresight
North American specialty chemical producers is shifting capacity toward filming inhibitor formulations for high-sour gas transmission lines. BASF SE leverages its Ludwigshafen integrated site to sustain captive supply of organic phosphate intermediates. Baker Hughes anchors its position through field-service bundling with chemical injection hardware. Nalco Champion differentiates via digital monitoring platforms tied to continuous dosing contracts.
Oil line corrosion inhibitors comprise surface-active chemical formulations—typically amines, organic phosphates, or filming polymers—designed to adsorb onto steel substrates in hydrocarbon transport infrastructure, forming protective barriers against electrochemical degradation at operating temperatures between 40°C and 150°C. Cathodic inhibitor demand dominates pipeline protection applications where oxygen scavenging governs internal corrosion rates, while filming inhibitors capture margin pools in offshore rig deployments requiring persistent saline resistance. Midstream operators represent the fastest-growing end user industry as gathering network expansion in unconventional basins multiplies injection point requirements.
The US EPA regulates discharge of spent inhibitor chemistries under NPDES permits, while REACH in Europe mandates substitution assessments for solvent-refined products containing hazardous aromatic fractions. OSHA process safety management standards influence formulation handling protocols at US refining facilities. Stakeholders must monitor evolving MEE guidelines in China and dual carbon compliance timelines that could restrict conventional amine production pathways.
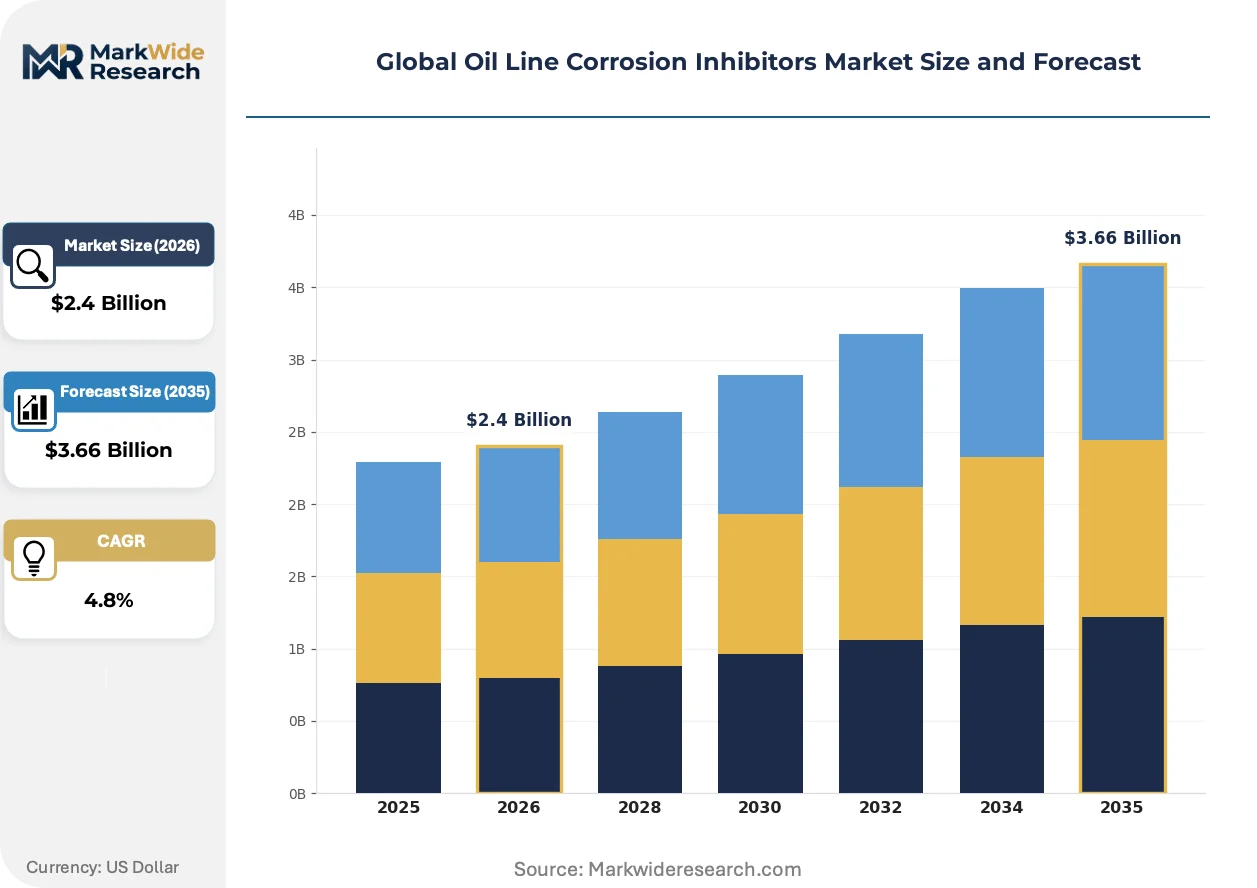
Market Dynamics
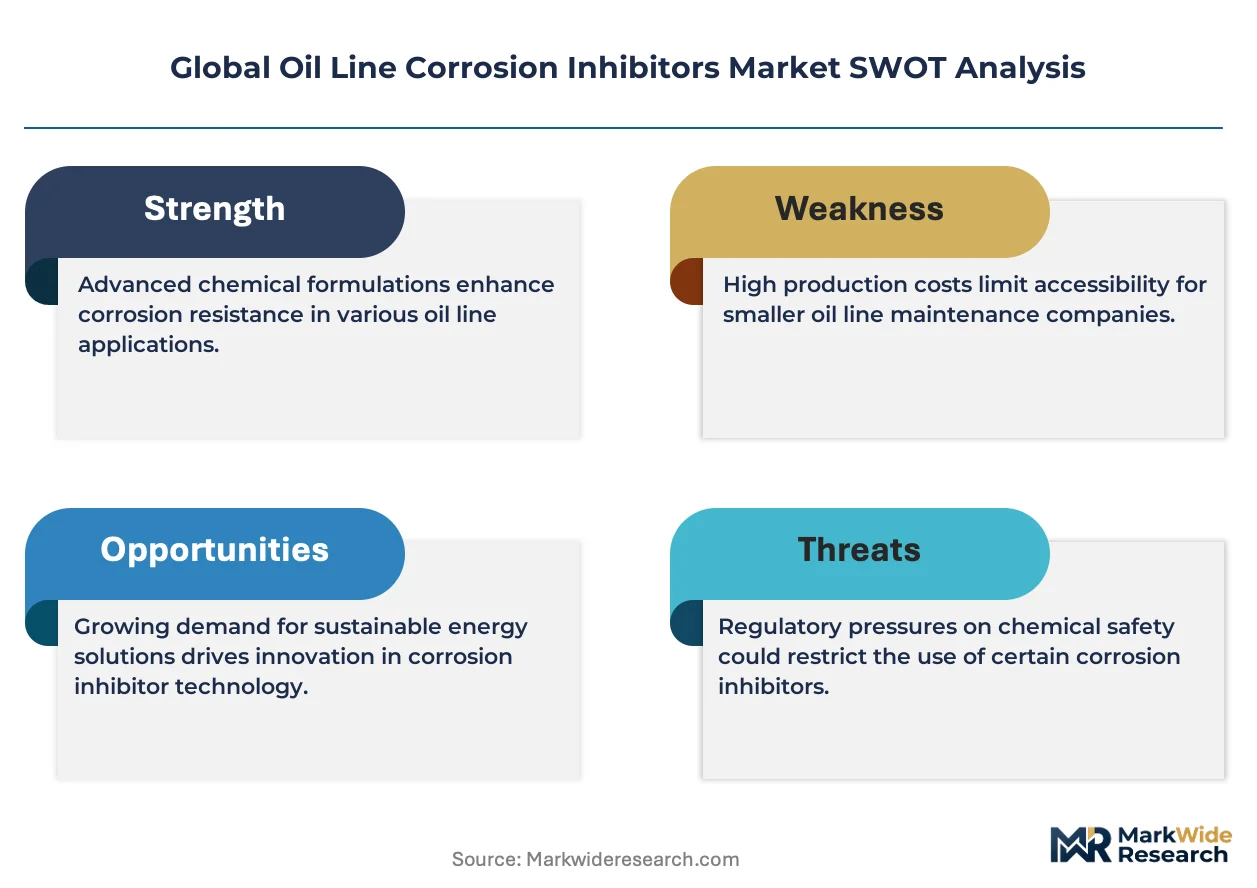
The US EPA and EU REACH frameworks are compressing permissible discharge limits for amine-based chemistries, forcing midstream operators toward continuous dosing systems and reformulated organic phosphate alternatives.
Growth Catalysts
- Offshore rig expansion:Gulf of Mexico and North Sea operators deploy persistent saline-resistant filming inhibitors for subsea infrastructure protection.
- REACH substitution mandates:European operators accelerate hazardous aromatic fraction phase-outs, opening formulation upgrade cycles.
- Unconventional basin gathering networks:US shale operators multiply injection point requirements across Permian and Bakken developments.
Market Restraints
- Ethylene oxide feedstock volatility:Amine precursor costs fluctuate with petrochemical cracking economics, squeezing blender margins.
- Ludwigshafen supply concentration:Captive organic phosphate intermediate production anchors with BASF SE, creating single-source exposure.
- High-sour gas technical ceiling:Filming inhibitors face performance degradation above 120°C in hydrogen sulfide-rich transmission lines.
Strategic Opportunities
- Middle Eastern offshore concessions:Saudi Aramco and ADNOC tender packages specify digital monitoring integration for chemical injection contracts.
- Digital-physical convergence:IoT sensor networks paired with predictive analytics enable real-time inhibitor dosing optimization.
- China MEE discharge guidelines:Tightening effluent standards for oilfield chemicals create import substitution openings for compliant formulators.
Industry Challenges
- Electrochemical corrosion modeling expertise:Field engineers with combined materials science and data analytics capabilities remain scarce across service company hiring pipelines.
- Legacy SCADA integration:Continuous dosing platforms require costly retrofitting of 1990s-era pipeline control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oil Line Corrosion Inhibitors Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filming Inhibitors, Cathodic Inhibitors, Solvent-Refined Products, Amines, Organic Phosphates Application: Pipeline Protection, Refinery Systems, Storage Tanks, Drilling Equipment, Transport Lines, Offshore Rigs End User Industry: Exploration & Production Companies, Midstream Operators, Refining Facilities, Petrochemical Plants, Chemical Processing Units Deployment Mode: Chemical Injection, Mixer Addition, Batch Treatment, Continuous Dosing, Manual Application |
| Companies Covered | BASF SE, Nalco Champion, Baker Hughes, Akzo Nobel N.V., Dow Inc., Schlumberger, Ecolab Inc., Lubrizol Corporation, Halliburton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oil Line Corrosion Inhibitors Market Shifts & Advancements
Formulation chemistry, regulatory compliance architecture, and service delivery models are converging to reshape competitive positioning in pipeline protection.
Polymeric filming inhibitors are integrating quaternary ammonium compounds with fluorinated surfactants to achieve sub-monolayer coverage at lower dosage rates. Offshore rig operators in the Norwegian continental shelf adopt these systems for extended subsea tieback applications. The technology is integrating real-time electrochemical impedance spectroscopy feedback loops, compressing traditional batch-treatment cycles into continuous injection protocols.
REACH authorization requirements for solvent-refined aromatic extracts are forcing European blenders toward bio-based carrier fluid development. Industrial consequence includes reformulation R&D budget reallocation exceeding 15% of annual chemical spend for major pipeline operators. Midstream assets crossing EU member states face the most acute compliance timeline pressure, with substitution assessments due ahead of 2027 sunset dates.
Performance-based chemical management contracts are displacing traditional volume-purchase agreements across US shale basins. Midstream gatherers now tie service provider compensation to corrosion rate reduction metrics rather than gallons delivered. The Permian Delaware sub-basin exhibits the fastest contract structure conversion, with operators bundling hardware, chemicals, and digital monitoring under single-vendor accountability frameworks.
Global Oil Line Corrosion Inhibitors Market Segmentation
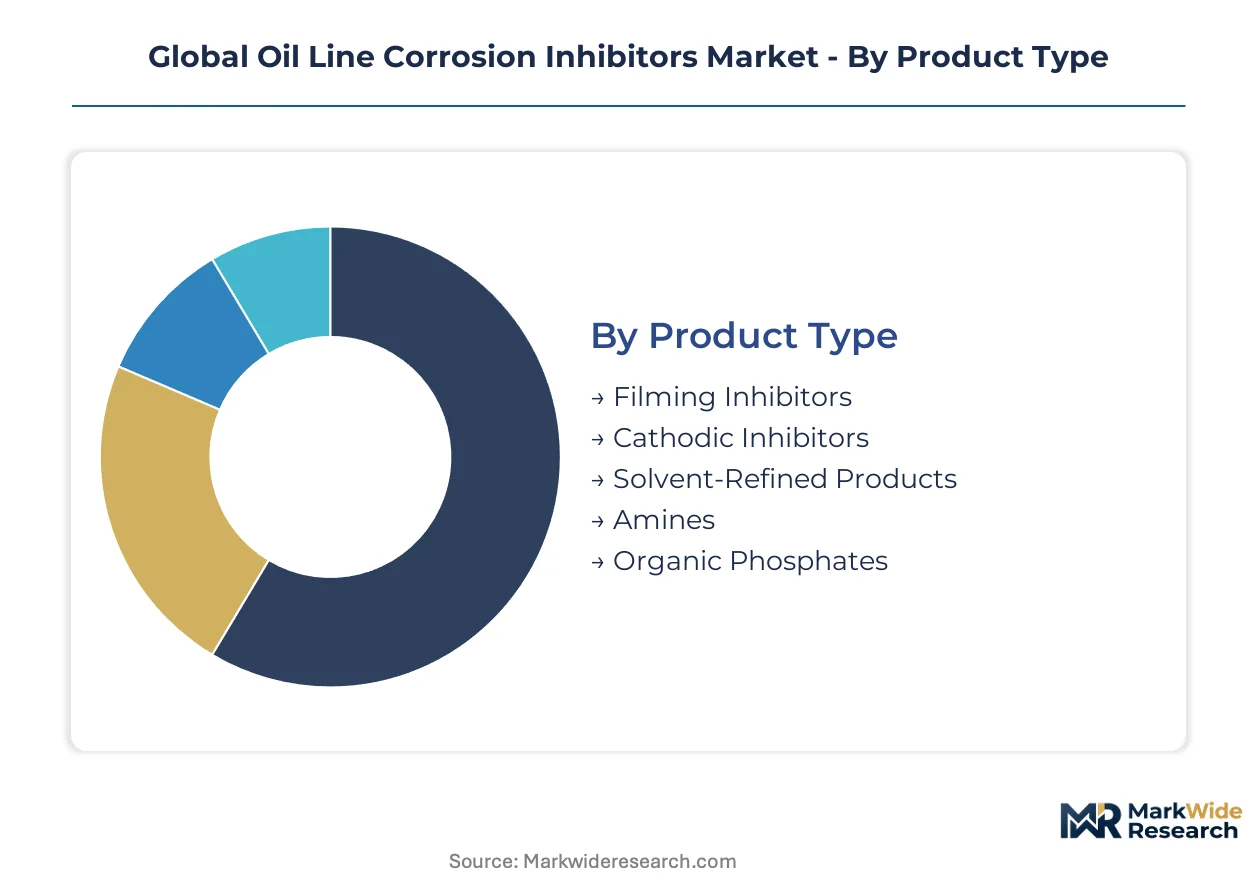
Corrosion inhibitor procurement diverges sharply across product chemistries and deployment contexts. Regulatory frameworks from EPA, REACH, and MEE impose distinct compliance burdens on each segment category, reshaping supplier qualification requirements and end-user specification protocols.
Product Type:
REACH authorization timelines and EPA NPDES discharge permits create tiered certification obligations across inhibitor chemistries, with filming formulations facing the most stringent substance evaluation protocols.
- Filming Inhibitors:Polymeric formulations incorporating quaternary ammonium compounds and fluorinated surfactants form sub-monolayer protective barriers on steel substrates. Norwegian continental shelf operators specify these systems for subsea tieback infrastructure where saline persistence exceeds 150°C operating thresholds.
- Cathodic Inhibitors:Oxygen-scavenging chemistries dominate internal corrosion control in oxygen-rich transmission environments. US shale basins concentrate demand as gathering network expansion multiplies injection point requirements across Permian and Bakken developments.
- Solvent-Refined Products:REACH sunset assessments for hazardous aromatic fractions accelerate phase-out timelines across EU member states.
- Amines:Ethylene oxide feedstock volatility compresses blender margins while EPA discharge limits tighten under NPDES permit renewals.
- Organic Phosphates:BASF SE's Ludwigshafen site anchors captive intermediate supply, creating single-source concentration risk for formulators dependent on phosphonate precursors.
Leading the category by volume: Cathodic Inhibitors. Growing fastest: Filming Inhibitors.
Application:
Deployment environment dictates formulation selection, with subsea infrastructure commanding premium specifications and terrestrial pipelines optimizing for cost-effective batch protocols.
- Pipeline Protection:Internal corrosion control in hydrocarbon transmission networks represents the foundational application segment, spanning gathering lines through trunk systems.
- Refinery Systems:High-temperature processing units require thermally stable chemistries resistant to catalytic degradation above 120°C.
- Storage Tanks:Bottom-water corrosion mitigation drives demand for vapor-phase inhibitors in floating roof and fixed-roof configurations.
- Drilling Equipment:Drill pipe and casing protection during completion operations utilizes temporary corrosion inhibitors with rapid film formation kinetics.
- Transport Lines:Rail and marine loading systems face intermittent wet-dry cycling that accelerates localized pitting without persistent inhibitor films.
- Offshore Rigs:Gulf of Mexico and North Sea platforms deploy continuous dosing systems for subsea infrastructure, with Saudi Aramco and ADNOC tender packages now mandating digital monitoring integration.
Pipeline Protection commands the largest installed base. Offshore Rigs exhibit the steepest expansion trajectory as deepwater concessions proliferate.
End User Industry:
Procurement sophistication varies across the value chain, with midstream operators driving performance-based contracting models that displace traditional volume-purchase structures.
- Exploration & Production Companies:Upstream operators prioritize temporary protection during drilling and completion phases, favoring rapid-deployment chemistries over persistent film technologies.
- Midstream Operators:Gathering network owners in US shale basins pioneered outcome-based chemical management contracts tying supplier compensation to corrosion rate reduction metrics rather than gallons delivered.
- Refining Facilities:OSHA process safety management standards govern formulation handling protocols, with integrated sites demanding bulk delivery infrastructure compatibility.
- Petrochemical Plants:Olefin and aromatics producers require inhibitors compatible with polymerization catalyst systems and sensitive to trace contamination thresholds.
- Chemical Processing Units:Specialty chemical manufacturers specify food-grade or pharmaceutical-grade inhibitor variants for process streams with downstream product contact risks.
Midstream Operators anchor category revenue. Refining Facilities are gaining share fastest as FCC unit revamps expand treatment capacity.
Deployment Mode:
Capital intensity and labor requirements stratify adoption patterns, with automated systems capturing offshore applications and manual protocols persisting in remote terrestrial assets.
- Chemical Injection:Pump-skid systems deliver precise dosage control at pipeline injection points, forming the backbone of continuous protection programs.
- Mixer Addition:Tank blending operations suit batch treatment scenarios with predictable throughput and residence time characteristics.
- Batch Treatment:Periodic slug dosing remains economical for low-throughput gathering lines where continuous system capital cannot be justified.
- Continuous Dosing:Real-time electrochemical impedance spectroscopy feedback loops compress traditional batch cycles into persistent injection protocols, with IoT sensor networks enabling predictive optimization.
- Manual Application:Remote locations without SCADA infrastructure depend on field technician rounds for inhibitor drum deployment and monitoring.
Chemical Injection holds the dominant installed base. Continuous Dosing is climbing the fastest as digital-physical convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene oxide availability along the US Gulf Coast anchors formulation capacity for amine-based chemistries. BASF SE's Ludwigshafen complex supplies organic phosphate intermediates to European blenders. Middle Eastern offshore concessions in Saudi Arabia and the UAE drive specification upgrades for subsea applications.
United States
Permian and Bakken shale operators multiply injection point requirements across gathering networks. EPA NPDES permit renewals tighten discharge limits for spent amine chemistries. Houston anchors specialty chemical production, with midstream operators pioneering performance-based contracts that tie supplier compensation to corrosion rate metrics.
Norway
North Sea subsea tieback infrastructure demands filming inhibitors with saline persistence above 150°C operating thresholds. REACH authorization requirements accelerate hazardous aromatic fraction phase-outs across the continental shelf. Stavanger clusters offshore service providers integrating digital monitoring platforms with continuous dosing hardware.
China
MEE effluent guidelines for oilfield chemicals create import substitution openings for compliant formulators. Dual carbon compliance timelines restrict conventional amine production pathways in coastal provinces. Sichuan-Chongqing shale basins expand gathering network infrastructure, multiplying cathodic inhibitor procurement volumes.
Saudi Arabia
ADNOC and Saudi Aramco tender packages specify digital monitoring integration for offshore chemical injection contracts. The country's national environmental regulator tightens discharge standards for spent inhibitor chemistries in Arabian Gulf operations. Dhahran anchors integrated oilfield service clusters bundling hardware, chemicals, and predictive analytics.
Germany
REACH sunset assessments for solvent-refined aromatic extracts force blenders toward bio-based carrier fluid development. ECHA substitution mandates require reformulation R&D budget reallocation exceeding 15% of annual chemical spend for pipeline operators. Ludwigshafen's integrated site sustains captive organic phosphate intermediate supply, creating single-source concentration exposure for European formulators.
Global Oil Line Corrosion Inhibitors Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and field-service bundling. The vendor base stratifies into three tiers: integrated petrochemical conglomerates with captive intermediate supply, oilfield service companies bundling chemicals with injection hardware, and specialty chemical pure-plays focused on compliant formulations. Strategic moves concentrate on backward integration into organic phosphate precursors and partnerships for IoT-enabled dosing platforms.
Within the integrated chemical tier, BASF SE and Dow Inc. occupy positions anchored by Ludwigshafen and US Gulf Coast manufacturing footprints. Among oilfield service providers, Baker Hughes and Schlumberger exemplify the hardware-chemical bundling archetype. Nalco Champion sits within the digital-physical convergence segment, representing predictive analytics integration with continuous dosing contracts.
| Leading Market Players |
|---|
| BASF SE |
| Nalco Champion |
| Baker Hughes |
| Akzo Nobel N.V. |
| Dow Inc. |
| Schlumberger |
| Ecolab Inc. |
| Lubrizol Corporation |
| Halliburton |
| Others |
Supply & Pricing Matrix
REACH substitution mandates for hazardous aromatic fractions are forcing European blenders toward bio-based carrier fluid development, compelling supply chain reconfiguration and compressing margin structures for solvent-refined product tiers. EPA NPDES permit renewals in the US simultaneously tighten discharge limits, redirecting procurement budgets toward continuous dosing hardware bundles that capture pricing premiums through service integration.
Pricing Analysis
Service-bundling with chemical injection hardware and digital monitoring platforms commands 15-25% pricing premiums over unbundled volume-purchase contracts in offshore rig applications. Three-tier pricing structure separates premium filming inhibitors with fluorinated surfactants from standard amine-based formulations and economy-grade cathodic chemistries. Pricing pressure stems from ethylene oxide feedstock volatility squeezing blender margins, with midstream operators in US shale basins exhibiting highest price sensitivity due to outcome-based contract adoption, while Norwegian continental shelf operators show lowest sensitivity given subsea specification requirements.
Supply Chain Analysis
Direct-to-refinery channels handle bulk formulation demand, while field-service bundling flows through oilfield service company networks. Geographic supply concentrates in Germany through BASF SE's Ludwigshafen complex, the US Gulf Coast ethylene oxide corridor, and Chinese coastal provinces for amine intermediates. Raw material dependencies include ethylene oxide for amine precursors, phosphonate intermediates for organic phosphates, and fluorinated surfactants for filming formulations. Single-source vulnerability around Ludwigshafen phosphonate supply creates concentration risk for European formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is transitioning from batch-treatment chemistries toward continuous dosing systems integrated with IoT sensor networks, with real-time electrochemical impedance spectroscopy displacing legacy manual monitoring protocols.
For Market Incumbents: Hedge against REACH authorization sunset timelines by accelerating bio-based carrier fluid R&D and securing captive phosphonate precursor supply through backward integration or long-term offtake agreements. Defensive consolidation through digital-physical service bundling protects margin pools as hardware-chemical integration becomes standard in Middle Eastern tender specifications. For New Entrants and Emerging Players: Launch via digital monitoring platform partnerships targeting China's Sichuan-Chongqing shale basins where MEE discharge guidelines create import substitution openings for compliant formulators. White-space concentration exists in mid-tier filming inhibitors for high-sour gas transmission lines above 120°C where technical performance ceilings exclude incumbent formulations. For Investors and Strategic Acquirers: The window for entry favors specialty chemical pure-plays with REACH-compliant formulation libraries and IoT-enabled dosing platform partnerships. Long-term viability hinges on regulatory compliance architecture rather than commodity volume scale. Signal to watch: ADNOC and Saudi Aramco tender packages mandating predictive analytics integration as inflection toward outcome-based contracting.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Phosphate Intermediates | BASF SE's Ludwigshafen concentration creates acquisition premium for captive phosphonate supply security. |
| Digital-Physical Convergence Partnership | IoT sensor networks paired with predictive analytics enable real-time dosing optimization in offshore contracts. |
| Bio-Based Carrier Fluid Development | REACH sunset assessments force reformulation R&D reallocation exceeding 15% of annual chemical spend. |
| Continuous Dosing Hardware Bundling | Midstream operators in Permian Delaware sub-basin convert fastest to single-vendor accountability frameworks. |
| Regulatory Compliance Certification Investment | EPA NPDES permit renewals and MEE guidelines create qualification barriers for non-compliant formulators. |
Research Methodology
Trade databases, ECHA substitution assessment filings, and SEC 10-K disclosures from specialty chemical producers formed the secondary backbone. Primary interviews with midstream procurement directors, offshore field service engineers, refinery chemical treatment managers, and regulatory compliance officers combined with customs data and ACC industry reports. Bottom-up volume modeling across product chemistries triangulated against top-down market sizing from petrochemical consumption patterns.
Historical trendline analysis of formulation chemistry adoption rates informed projection frameworks across the analysis window. Segmentation dimensions modeled include inhibitor chemistry type, deployment mode, application environment, and end-user procurement sophistication. CAGRs derived from ethylene oxide capacity expansion timelines, offshore rig deployment schedules, and regulatory compliance phase-in dates. Forecast inputs incorporated REACH authorization sunset timelines and shale basin gathering network expansion trajectories.
The model assumes a particular technology adoption path; alternative pathways for electrochemical impedance spectroscopy integration would alter the outlook. Forecasts reflect base-case assumptions regarding regulatory enforcement consistency and feedstock cost stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Middle-East and Africa Frac Stack Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
Frac Stack Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
Europe Oilfield Chemicals Market
Oil & Gas
Global Oil and Chemical Spill Kits Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Qatar Oilfield Chemicals Market