
 Clean Label Fruit and Vegetable Powder Market | 2026-2036
Clean Label Fruit and Vegetable Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Label Fruit and Vegetable Powder Market Analytics
Single-serve pouch configurations is shifting how beverage and supplement brands trial clean label powders, reducing bulk purchase risk for smaller health and wellness brands. Döhler Group leverages its European botanical extraction network to supply fruit concentrates that convert into clean label powders. FutureCeuticals anchors its position through intensive agronomic R&D, controlling cultivar selection from farm to finished extract. ARONA GmbH specializes in gentle drying technologies that preserve polyphenol activity for premium cosmetic applications.
Clean label fruit and vegetable powders consist of minimally processed, dehydrated plant tissues retaining native phytochemical profiles without synthetic carriers, produced via spray-drying, freeze-drying, or refractance window evaporation below thermal degradation thresholds. These powders serve primarily as natural colorants, flavor modulators, and nutritional fortificants in formulated consumer goods. Fruit powders occupy the largest volume share due to widespread use in smoothie bases and infant nutrition, while organic powders command premium positioning as supply chain transparency becomes a purchasing criterion. Blends represent the fastest-expanding configuration as manufacturers seek synergistic polyphenol combinations that simplify formulation workflows for food manufacturers.
The FDA enforces strict identity standards under 21 CFR for fruit and vegetable ingredients used in dietary supplements, while the USDA Organic seal governs certification thresholds for organic powder claims in the United States. EFSA's novel food assessments and EU Green Deal sustainability disclosure requirements create dual compliance burdens for exporters targeting European food manufacturers. Stakeholders must monitor evolving enzyme-assisted extraction patents and carbon footprint labeling mandates to secure preferential positioning in procurement decisions.
Market Dynamics
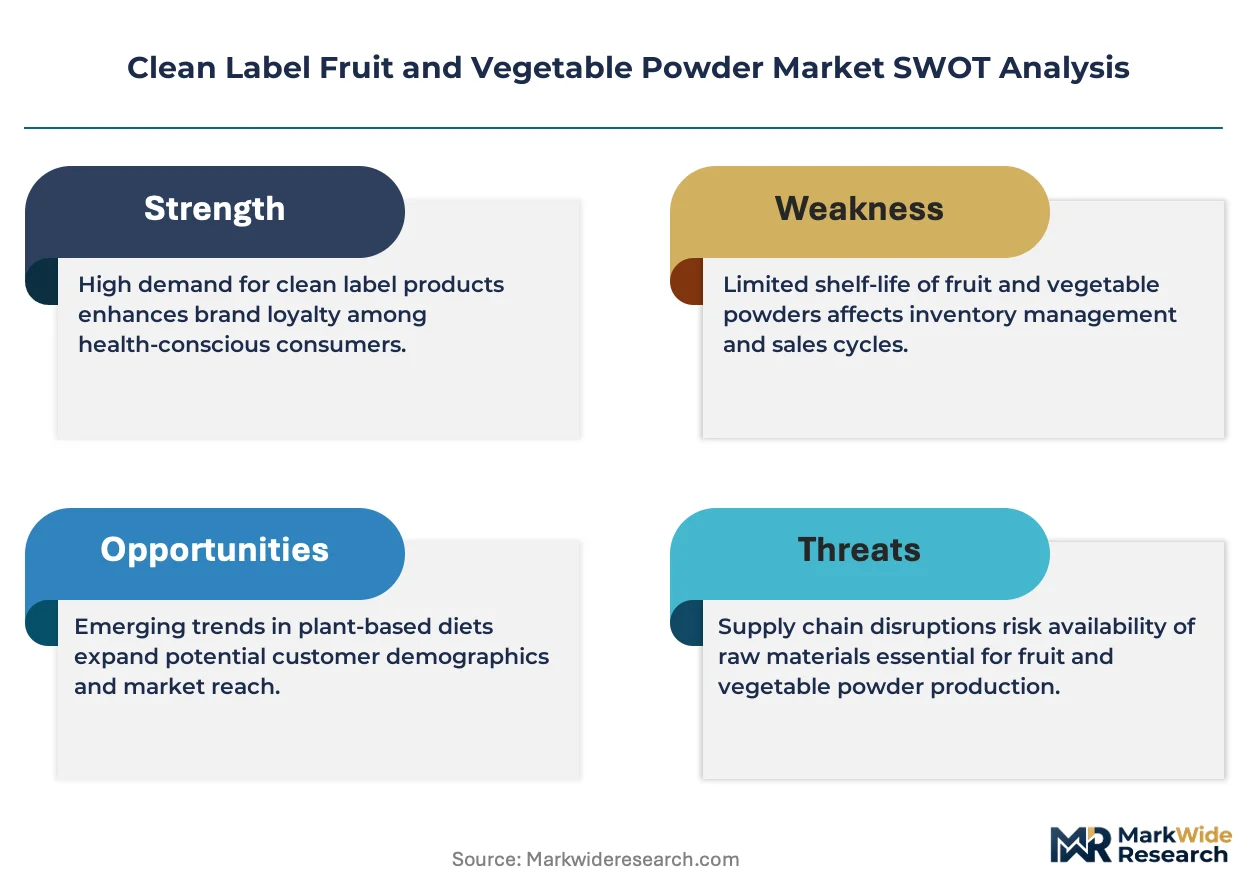
The EU Green Deal's Farm to Fork strategy compresses disclosure timelines for synthetic additives, forcing reformulation cycles that favor minimally processed fruit and vegetable powders over certified colorants.
Growth Catalysts
- EU Green Deal disclosure mandates:Tightening additive transparency rules under Farm to Fork accelerate manufacturer migration toward single-ingredient powders that require minimal label declarations.
- Beverage natural colorant demand:Soft drink and functional beverage producers replace synthetic dyes with beet and carrot powders to meet clean label positioning without reformulation complexity.
- Freeze-drying technology diffusion:Capital equipment cost curves flatten as Chinese and Indian equipment suppliers enter the market, expanding access to polyphenol-preserving drying methods for mid-tier processors.
Market Restraints
- Organic raw material cost volatility:Certified organic fruit feedstock prices fluctuate with weather-induced harvest variability, compressing margin predictability for powder processors locked into long-term supply contracts.
- Concentrated extraction technology suppliers:Gentle drying equipment and enzyme-assisted extraction systems source from a narrow German-Swiss vendor base, creating single-source risk for capacity expansion.
- EFSA novel food assessment timelines:Extended safety evaluation periods for new fruit-vegetable hybrid powders delay product launches by 18-36 months, freezing R&D returns.
Strategic Opportunities
- Infant nutrition fortification:Powder blends delivering synergistic polyphenol combinations capture formulation simplification demand from manufacturers seeking single-ingredient solutions for pediatric products.
- Cosmetic active ingredient migration:Premium skincare brands adopt polyphenol-rich vegetable powders as natural antioxidant alternatives to synthetic preservatives, opening margin-dense channels outside food applications.
- Carbon footprint labeling tailwinds:EU Green Deal sustainability disclosure requirements create procurement preference for powders with farm-to-finished-product traceability, rewarding vertically controlled supply chains.
Industry Challenges
- Enzyme-assisted extraction patent thickets:Dense intellectual property landscapes around cell-wall disruption methods force licensing negotiations or costly workarounds for processors developing proprietary extraction protocols.
- USDA Organic certification timeline compression:Three-year transition periods for conventional orchards seeking organic powder feedstock status strain supply planning for brands targeting premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Label Fruit and Vegetable Powder Market |
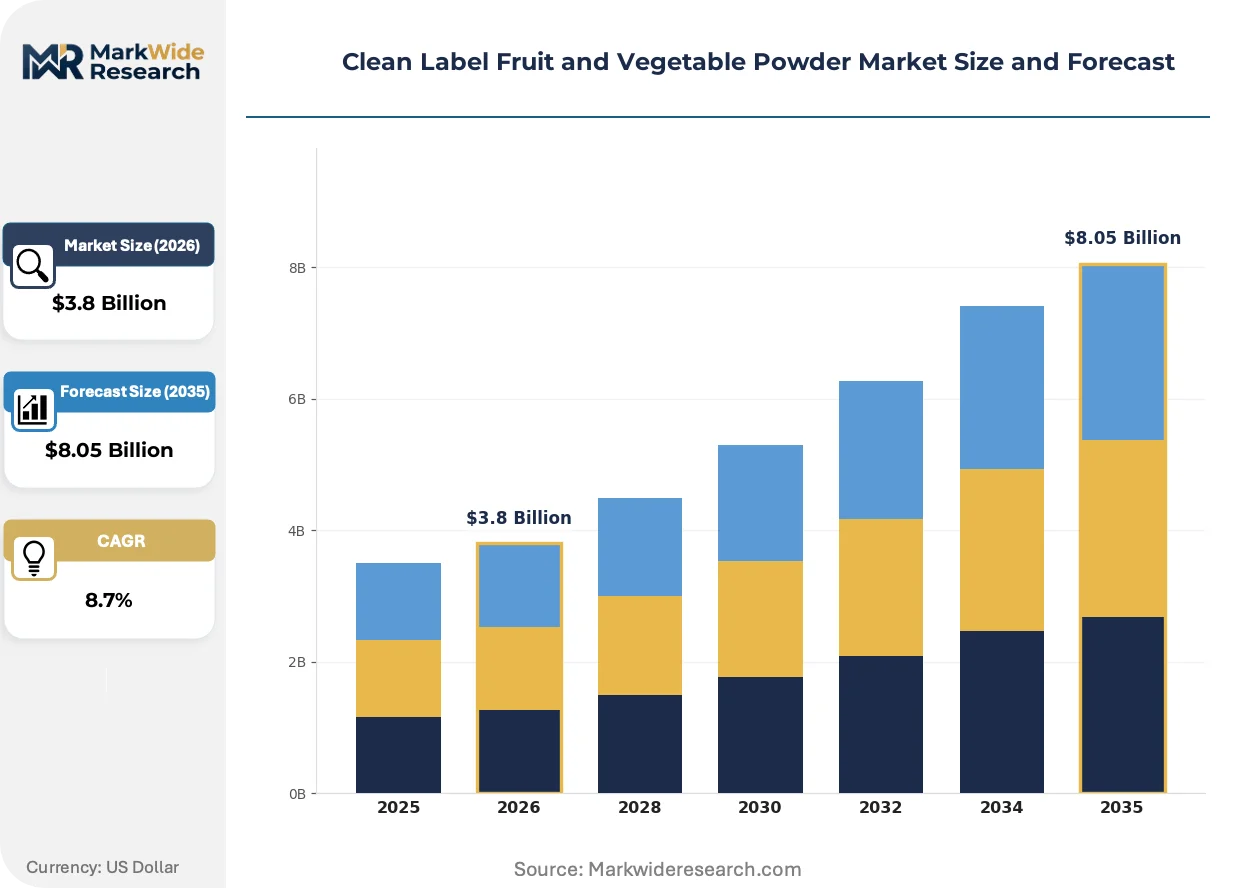
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Powders, Vegetable Powders, Blends, Organic Powders Application: Food & Beverages, Dietary Supplements, Nutraceuticals, Cosmetic Products End User: Food Manufacturers, Beverage Companies, Health & Wellness Brands, Cosmetic Manufacturers Packaging Type: Plastic Bags, Glass Containers, Pouches, Bulk Packaging |
| Companies Covered | General Mills, ARONA GmbH, Döhler Group, FutureCeuticals, The Green Labs LLC, Batory Foods, Herbafood Ingredients GmbH, Green Rootz, Milne MicroDried, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Label Fruit and Vegetable Powder Market Evolving Landscape
Refractance window evaporation advances alongside enzyme-assisted extraction are compressing the performance gap between premium freeze-dried and conventional spray-dried powders.
Refractance window drying employs infrared energy transfer across thin liquid films to dehydrate fruit purees below thermal degradation thresholds. Mid-tier beverage manufacturers adopt this technology at accelerating rates to access color stability previously reserved for freeze-dried alternatives. The method is unifying quality tiers across price-sensitive and premium powder categories, eliminating the historical trade-off between cost and polyphenol retention.
CSRD sustainability reporting mandates now require granular supply chain emissions disclosure from EU-listed food manufacturers. This regulatory pressure cascades downstream to powder suppliers, who must document cultivation inputs, processing energy, and transport carbon. Organic certification bodies in Germany and France respond by integrating carbon accounting modules into existing audit protocols, creating dual-compliance efficiency for exporters.
Single-serve pouch configurations displace bulk drum purchasing among emerging health and wellness brands seeking formulation flexibility without inventory risk. Direct-to-manufacturer sampling programs replace traditional distributor-led trials, compressing the supplier qualification cycle from quarters to weeks. This channel restructuring concentrates in North American and German markets where smaller brand proliferation outpaces established beverage conglomerate procurement scale.
Clean Label Fruit and Vegetable Powder Market Segmentation
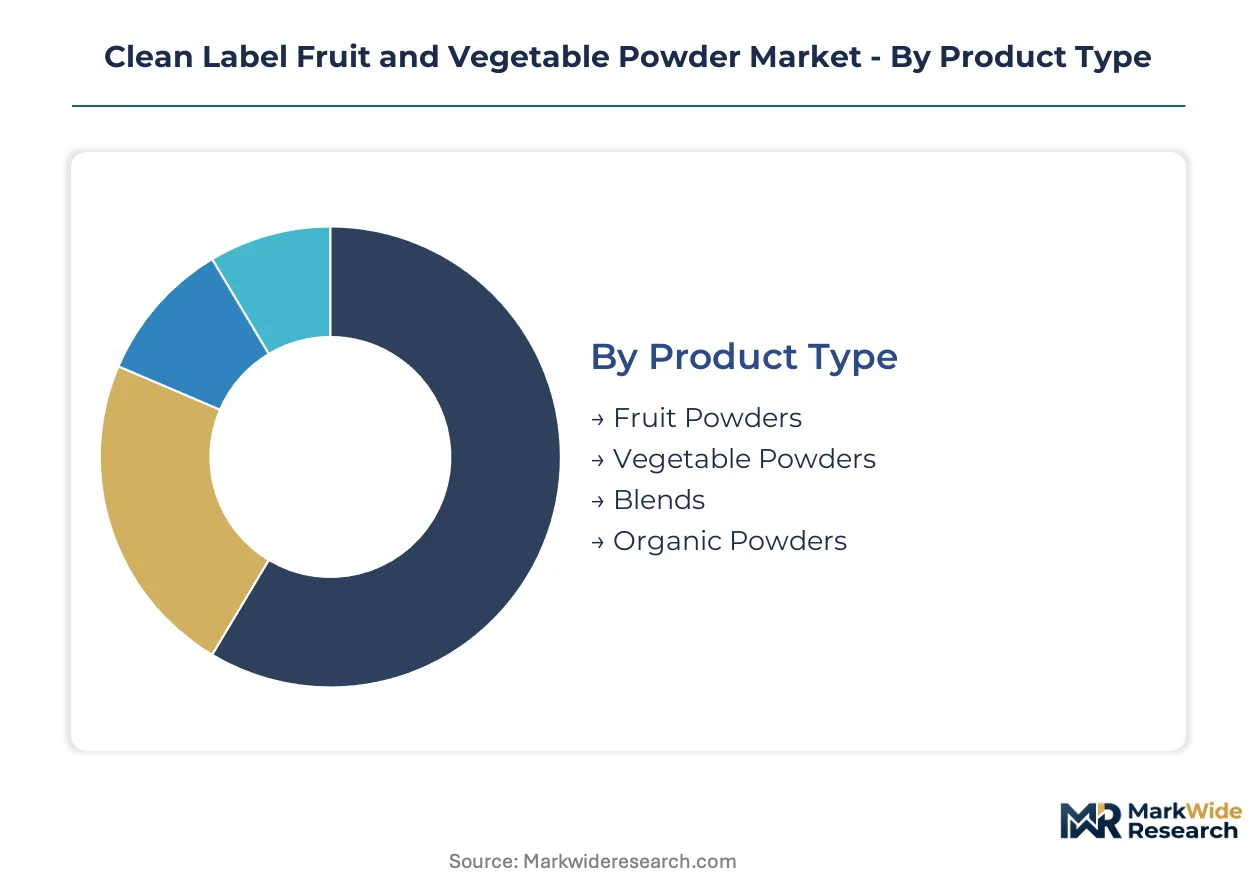
Clean label powder procurement decisions pivot on functional specifications that determine regulatory compliance thresholds and formulation integration complexity. Manufacturers segment demand across four intersecting axes that govern pricing premiums and supply chain qualification timelines.
Product Type:
Spray-drying versus freeze-drying specifications create the primary technical stratification, with polyphenol retention rates and color stability dictating end-use suitability.
- Fruit Powders:Dehydrated apple, berry, and citrus tissues retain native anthocyanin profiles for natural colorant applications. Beverage manufacturers in Germany source these for clean label reformulations replacing synthetic dyes under EU Green Deal disclosure mandates.
- Blends:Synergistic combinations of multiple fruit and vegetable sources deliver simplified single-ingredient solutions for fortification. Health and wellness brands trial these through single-serve pouch configurations to reduce formulation risk.
- Vegetable Powders:Carrot, beet, and spinach-derived powders provide earth-tone colorants and umami modulation for savory applications.
- Organic Powders:Certified organic feedstock commands premium positioning as supply chain transparency becomes a purchasing criterion for EU-listed food manufacturers.
Fruit Powders lead on scale; Blends lead on momentum.
Application:
Regulatory jurisdiction determines formulation complexity, with dietary supplements facing stricter identity standards than conventional food applications.
- Food & Beverages:Natural colorant and flavor enhancement applications dominate volume, with soft drink producers migrating from certified colorants to beet and carrot powders. EFSA novel food assessments create compliance burdens for new hybrid formulations entering European markets.
- Dietary Supplements:Capsule and tablet applications require precise phytochemical standardization under FDA 21 CFR identity standards. USDA Organic certification timelines strain supply planning for brands targeting premium positioning.
- Nutraceuticals:Functional food applications emphasize bioactive compound retention through gentle drying technologies.
- Cosmetic Products:Polyphenol-rich vegetable powders serve as natural antioxidant alternatives to synthetic preservatives in premium skincare formulations.
Food & Beverages commands current volume; Cosmetic Products exhibits the steepest expansion trajectory.
End User:
Procurement scale and technical sophistication separate multinational formulators from emerging specialty brands.
- Beverage Companies:Large-scale natural colorant demand drives contract volumes for beet and carrot powder supply. These buyers negotiate long-term supply agreements that expose processors to organic raw material cost volatility.
- Food Manufacturers:Diverse application requirements across bakery, dairy, and savory categories create fragmented specification demands.
- Health & Wellness Brands:Smaller order quantities favor single-serve pouch configurations and direct-to-manufacturer sampling programs that compress supplier qualification cycles.
- Cosmetic Manufacturers:Premium positioning requirements emphasize polyphenol activity preservation for antioxidant claims.
Beverage Companies anchor procurement volume; Health & Wellness Brands are gaining share fastest.
Packaging Type:
Inventory risk tolerance and formulation flexibility requirements shape container selection across customer tiers.
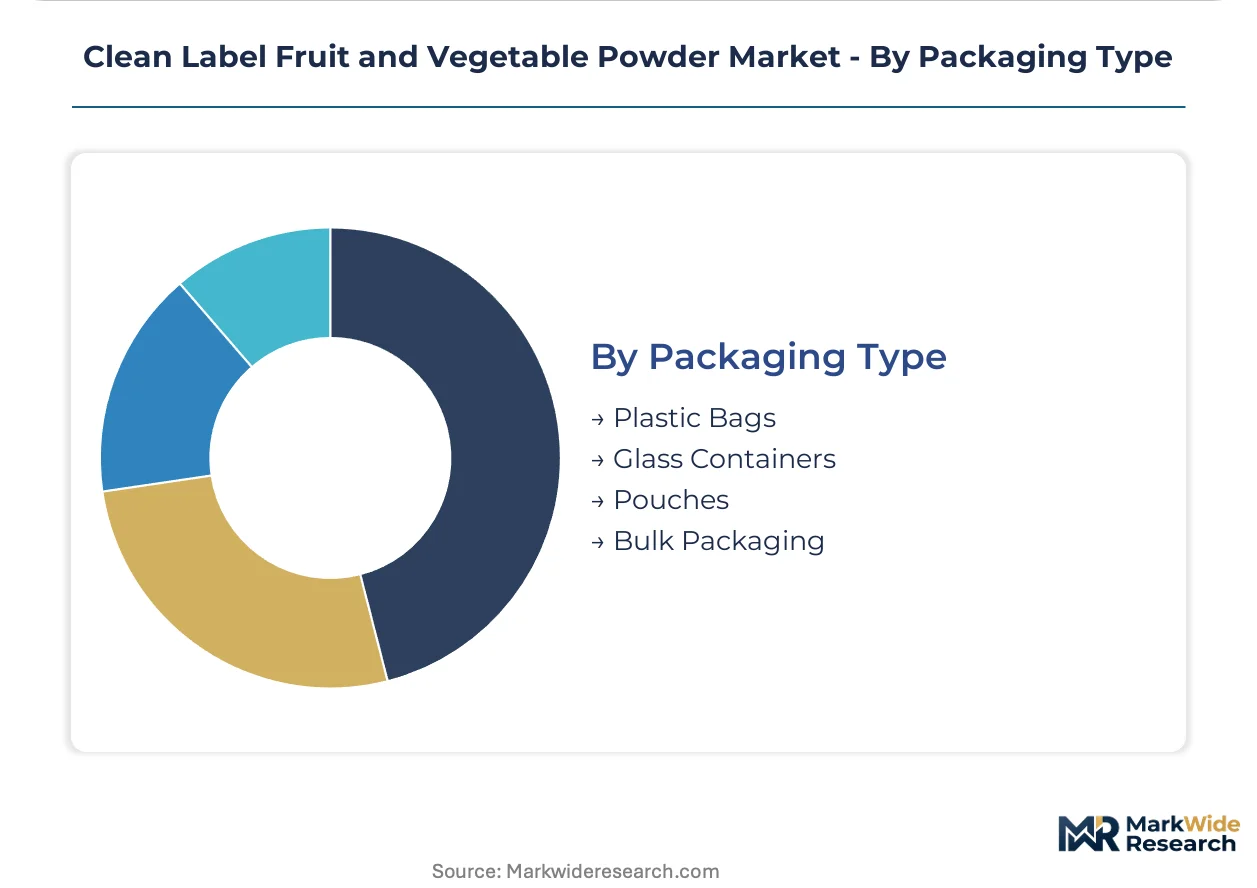
- Pouches:Single-serve configurations reduce bulk purchase risk for emerging health and wellness brands testing clean label positioning. Direct sampling programs replace traditional distributor-led trials in North American markets.
- Bulk Packaging:Drum and tote quantities serve multinational food manufacturers with stable demand forecasts and established formulation pipelines.
- Plastic Bags:Intermediate volumes balance cost efficiency with handling convenience for mid-tier processors.
- Glass Containers:Premium positioning for high-value cosmetic and nutraceutical applications requiring barrier protection.
Bulk Packaging dominates contract value; Pouches climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean label fruit and vegetable powder production originated in European botanical extraction facilities during the 1990s, with German processors pioneering gentle drying technologies for polyphenol preservation. The industry has since diffused across North American contract manufacturing networks and Asian ingredient processing clusters.
Germany
Beverage manufacturers in Bavaria and Baden-Württemberg drive demand for beet and carrot powders as natural colorant replacements under EU Green Deal Farm to Fork disclosure mandates. EFSA novel food assessment requirements create compliance bottlenecks for hybrid powder launches entering European markets. The Düsseldorf-Cologne corridor hosts concentrated extraction technology vendors supplying gentle drying equipment to mid-tier processors.
United States
Health and wellness brands in California and the Pacific Northwest trial single-serve pouch configurations to reduce formulation risk without bulk inventory commitments. FDA 21 CFR identity standards govern dietary supplement applications, while USDA Organic certification timelines strain supply planning for brands targeting premium positioning. Chicago-area food manufacturers anchor contract volumes for natural colorant migration in beverage reformulations.
India
Freeze-drying equipment cost curves flatten as domestic machinery suppliers enter the market, expanding access to polyphenol-preserving methods for mid-tier processors in Maharashtra and Gujarat. FSSAI labeling regulations tighten disclosure requirements for synthetic additive alternatives in processed foods. The Bangalore-Chennai corridor concentrates spray-drying capacity serving export markets for fruit powder concentrates.
China
Domestic equipment manufacturers in Jiangsu and Zhejiang provinces compress capital costs for refractance window drying systems, enabling quality tier unification across price-sensitive powder categories. SAMR food safety standards govern additive disclosure thresholds in formulated consumer goods. The Yangtze River Delta clusters contract processors supplying organic powder feedstock to European importers.
Brazil
Organic fruit feedstock cultivation concentrates in São Paulo and Minas Gerais states, though weather-induced harvest variability creates margin compression for powder processors locked into long-term supply contracts. ANVISA regulatory timelines for novel ingredient approvals delay product launches in functional food categories. The Campinas region hosts extraction facilities serving South American nutraceutical manufacturers.
Clean Label Fruit and Vegetable Powder Market Competitive Landscape
Premium-margin players sit above commodity-margin players across polyphenol retention specifications and supply chain traceability depth. The vendor base stratifies into three tiers: multinational ingredient conglomerates with captive agricultural networks, mid-scale processors specializing in gentle drying technologies, and regional traders sourcing commodity spray-dried powders. Strategic archetypes include vertically integrated botanical extractors, equipment-technology licensors, and private-label contract manufacturers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with processors securing long-term organic feedstock agreements and licensing enzyme-assisted extraction patents.
Among European-based specialists, ARONA GmbH and Döhler Group occupy positions within the premium-tier extraction segment, while FutureCeuticals exemplifies the agronomic R&D archetype controlling cultivar selection from farm to finished extract. These three companies anchor distinct strategic positions: ARONA GmbH represents gentle drying technology specialization, Döhler Group exemplifies European botanical network leverage, and FutureCeuticals sits within the intensive agronomic control tier. Each occupies a definable competitive space without overlapping core capabilities.
| Leading Market Players |
|---|
| General Mills |
| ARONA GmbH |
| Döhler Group |
| FutureCeuticals |
| The Green Labs LLC |
| Batory Foods |
| Herbafood Ingredients GmbH |
| Green Rootz |
| Milne MicroDried |
| Others |
Value Network & Pricing Analysis
Premium-mid-economy pricing differentiation across freeze-dried, refractance window, and spray-dried tiers creates divergent margin structures that map directly onto supply chain depth. Organic certification ladders in Germany and the United States enforce multi-year feedstock conversion timelines that concentrate pricing power with vertically controlled cultivar suppliers while compressing spot-market processors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts, with polyphenol retention rates and USDA Organic certification status as the primary price differentiation drivers. Cost compression in economy-tier spray-dried powders intensifies as Chinese equipment manufacturers flatten capital cost curves for mid-tier processors. Beverage conglomerates locked into long-term supply agreements exhibit lowest price sensitivity, while emerging health and wellness brands trialing single-serve pouches drive hardest bargain on unit economics.
Supply Chain Analysis
EU Green Deal domestic-content mandates for sustainability disclosure are reshaping sourcing patterns across European food manufacturers. Feedstock cultivation concentrates in Brazil, India, and select EU member states, while gentle drying equipment draws from a narrow German-Swiss vendor base. Single-source vulnerability in enzyme-assisted extraction systems creates bottleneck risk for capacity expansion. Distribution runs through direct-to-manufacturer channels for emerging brands and bulk contract logistics for multinational formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU Green Deal compliance costs and Indian equipment cost curves positions mid-tier processors for margin expansion. Regulatory divergence between EFSA novel food timelines and FDA 21 CFR identity standards creates formulation outsourcing opportunities.
For Market Incumbents: Extend backward integration into organic orchards to secure three-year certification timelines before USDA Organic demand spikes. Lock exclusive enzyme-assisted extraction licenses to neutralize patent thicket threats from emerging competitors. Capacity addition in Maharashtra and Gujarat captures flattening freeze-drying equipment cost curves. For New Entrants and Emerging Players: Enter via cosmetic active ingredient channels where polyphenol-rich vegetable powders command premium positioning outside saturated food applications. White-space concentrates in infant nutrition fortification blends and carbon-footprint-labeled supply chains serving EU-listed manufacturers. Go-to-market leverage refractance window drying as quality-tier unification narrative against established freeze-dried incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where gentle drying technology specialization overlaps with narrow German-Swiss equipment vendor dependencies. Long-term viability favors agronomic R&D archetypes controlling cultivar selection from farm to finished extract. Acquisition target archetype: mid-scale processors with captive organic feedstock agreements and documented carbon accounting protocols. Signal to watch: EFSA novel food assessment timeline compression for hybrid powder approvals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feedstock | Captive supply of certified orchards secures three-year USDA Organic conversion timelines ahead of demand spikes. |
| Enzyme-Assisted Extraction Patent Licensing | Exclusive cell-wall disruption licenses neutralize intellectual property thickets threatening proprietary protocol development. |
| Refractance Window Drying Scale-Up | Quality-tier unification narrative challenges freeze-dried premium positioning at mid-tier price points. |
| Carbon Footprint Labeling Certification | CSRD-aligned traceability documentation unlocks procurement preference from EU-listed food manufacturers. |
| Single-Serve Pouch Channel Expansion | Direct sampling programs compress supplier qualification cycles from quarters to weeks for emerging brands. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extraction technology vendors, procurement leads at beverage manufacturers, organic certification auditors, and agronomic R&D directors with secondary validation. FDA 21 CFR filings, USDA Organic certification databases, EFSA novel food registers, and EU Green Deal sustainability disclosure protocols anchored supply-side intelligence. Customs records from Germany, the United States, and India tracked cross-border powder flows. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level outputs.
Segment-weighting across product type, application, end user, and packaging dimensions structured the analytical framework across the analysis window. Fruit powders, blends, vegetable powders, and organic certification tiers received distinct growth assumptions based on polyphenol retention specifications and regulatory compliance burdens. Beverage natural colorant demand, infant nutrition fortification trends, and cosmetic active ingredient migration supplied industry-specific forecast inputs. CAGRs derived from historical trajectory analysis and elasticity-adjusted projection modeling.
Inputs from extraction technology vendors and organic certification bodies were available through the study window; gaps in proprietary agronomic R&D yield data introduce uncertainty bands around cultivar-specific polyphenol retention estimates. Forecasts reflect documented assumptions regarding EU Green Deal implementation pace and freeze-drying equipment cost curve trajectories. Weather-induced harvest variability in Brazil and extended EFSA novel food timelines represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Pickle Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
Global Maqui Berries Market
Fruits and Vegetables
Banana Puree Market
Fruits and Vegetables
Asia Pacific Lime Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market
Fruits and Vegetables
Fresh Peaches Market
Fruits and Vegetables
GCC Fruits and Vegetables Market
Fruits and Vegetables
Fruit Pulp Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Apple Concentrate Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Lycopene Market