
 Asia Pacific Lime Market | 2026-2036
Asia Pacific Lime Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Lime Market Outlook
Modular supply arrangements for quicklime and hydrated lime is shifting procurement patterns across the Asia Pacific region. Graymont Asia Pacific leverages its integrated quarry-to-delivery network across Southeast Asian markets. Chememan Plc anchors its position through specialized dolomitic lime production for metallurgical clients. Sibelco Australia competes on high-purity calcium carbonate grades serving food processing and chemical applications.
Asia Pacific lime encompasses calcium oxide (quicklime) and calcium hydroxide (hydrated lime) produced through calcination of limestone at temperatures exceeding 900°C, yielding products with 90-96% CaO content for industrial fluxing, soil stabilization, and effluent neutralization. Quicklime dominates volume flows into construction and metallurgical applications where slaking reactivity and particle size distribution determine pricing tiers. Hydrated lime commands premium positioning in environmental and water treatment segments due to superior handling safety and controlled reactivity profiles. Dolomitic lime occupies a specialized niche in steel desulfurization across integrated mills in China and India.
China's SAMR enforces GB standards for chemical-grade lime purity, while India's BIS mandates IS 1514 specifications for construction applications, and Australia's state-level EPA frameworks govern air emissions from calcination facilities. These regulatory layers elevate compliance costs for smaller kiln operators and favor producers with captive limestone reserves and emission control investments. Stakeholders must monitor evolving carbon intensity benchmarks across Chinese provincial jurisdictions and Indian state pollution control mandates to anticipate supply consolidation patterns.
Market Dynamics
China's dual carbon goals and India's tightening BIS certification are forcing calcination facilities across the Asia Pacific to reconfigure kiln operations and emission controls, consolidating supply around producers with captive limestone reserves and advanced scrubbing infrastructure.
Growth Catalysts
- Steel desulfurization demand:Integrated mills in China and India consume dolomitic lime for molten metal treatment. This metallurgical application commands premium pricing and locks in multi-year offtake contracts.
- IS 1514 specifications:India's BIS mandates for construction-grade lime are disqualifying unorganized kiln operators. Certified producers gain pricing power in western cement belt procurement.
- Eastern China industrial corridors:Clustered steel and chemical manufacturing in Jiangsu and Shandong provinces concentrates quicklime demand within 200-kilometer radii of calcination hubs.
Market Restraints
- Natural gas and coal price volatility:Fuel costs represent 35-45% of quicklime production expenses. Smaller rotary kiln operators in Vietnam and Indonesia lack hedging mechanisms against energy input swings.
- Limestone reserve concentration:High-calcium deposits suitable for chemical-grade lime concentrate in Guangxi, Vietnam's northern provinces, and select Queensland formations. New entrants face decade-long quarry permitting timelines.
- Slag and synthetic flux substitution:Steelmakers in Japan and South Korea increasingly blend blast furnace slag with lime for fluxing applications, compressing unit consumption per ton of crude steel.
Strategic Opportunities
- Philippines infrastructure buildout:The government's Build Better More program targets 194 billion pesos in road and bridge construction through 2028. Hydrated lime for soil stabilization remains underpenetrated relative to ASEAN peers.
- Carbon capture integration:Post-combustion capture systems at calcination facilities can monetize CO2 for urea or methanol synthesis. China's MEE provincial pilots offer emission credit offsets for early adopters.
- Direct-to-mixer distribution:Ready-mix concrete producers in Australia's eastern states are bypassing traditional merchant distributors for bulk hydrated lime deliveries synchronized to batch plant schedules.
Industry Challenges
- Kiln operator skill scarcity:Precise temperature control for 90%+ CaO content requires experienced burners. Australia's aging workforce and Vietnam's rural-urban migration strain technical recruitment pipelines.
- Baghouse and scrubber capex cycles:China's GB standard upgrades and India's state pollution control mandates require 15-25 million yuan investments per facility. Smaller operators defer compliance and risk forced closures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Lime Market |
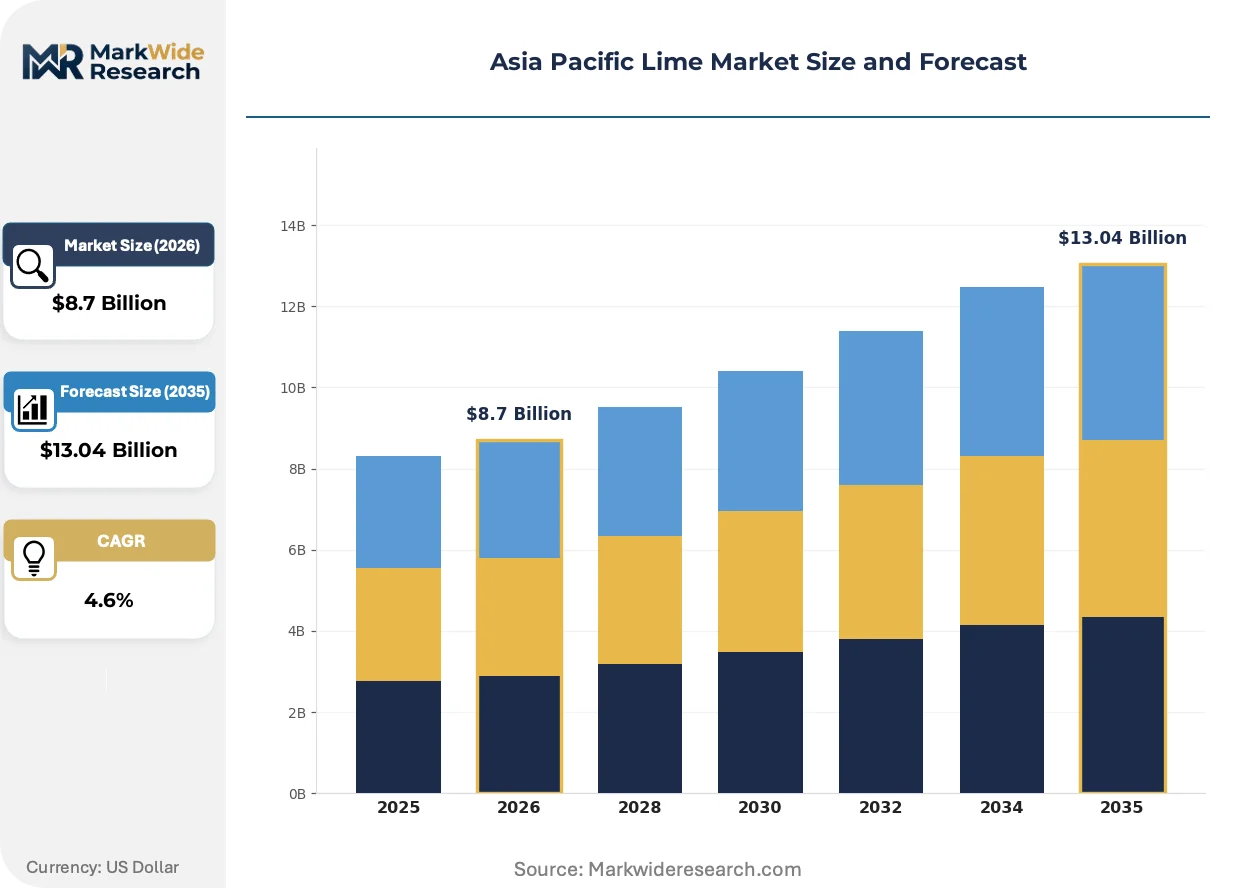
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quicklime, Hydrated Lime, Dolomitic Lime, Calcium Carbonate Application: Construction, Environmental, Chemical, Metallurgical End User: Manufacturing, Agriculture, Water Treatment, Food Processing Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | India Lime Producer Association, China National Fruit Marketing Corp, Thai Lime Exporters Association, Chememan Plc, Vietnam Fruit and Vegetable Export Corp, Australian Lime Export Co, Philippine Citrus Growers Association, Graymont Asia Pacific, Sibelco Australia, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Lime Market Strategic Shifts
Calcination technology and emission control systems are converging to reshape competitive economics across Asia Pacific lime production, with digital kiln monitoring and carbon intensity benchmarking emerging as decisive differentiators.
Advanced process control systems using real-time temperature sensors and predictive algorithms are optimizing fuel efficiency in rotary and vertical shaft kilns. Steelmakers and chemical processors in China and India are specifying suppliers with digitized quality traceability. This capability is integrating into procurement scoring matrices alongside traditional CaO content and reactivity metrics.
China's MEE is rolling out provincial carbon intensity benchmarks for non-metallic mineral manufacturing, with Jiangsu and Hebei piloting emissions trading integration. Facilities exceeding baseline intensities must purchase allowances or face production quotas. Quicklime exporters serving EU-bound supply chains are accelerating measurement system investments to preempt CBAM border adjustments.
Long-term offtake agreements are displacing spot market purchases among Australia's construction aggregates sector and India's cement producers. Buyers are consolidating vendor panels to three to five certified suppliers per region, trading price flexibility for supply security and technical service access. This concentration is most visible in Victoria's infrastructure procurement and Maharashtra's ready-mix concrete supply chains.
Asia Pacific Lime Market Segmentation
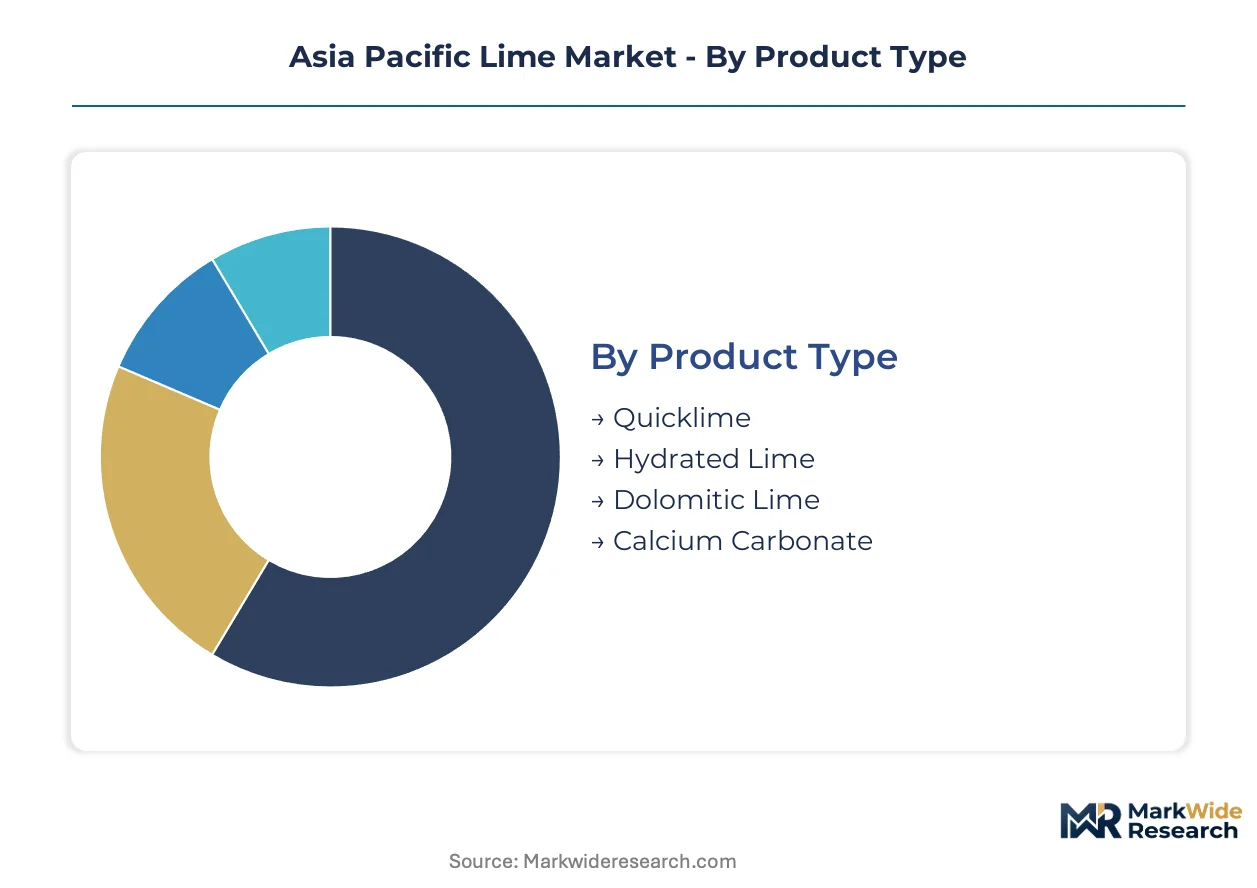
Calcination technology upgrades and emission control retrofits are reshaping how lime products compete across specification tiers. Procurement patterns in Asia Pacific increasingly favor suppliers with certified purity grades and integrated logistics networks over merchant traders.
Product Type:
Replacement cycles for rotary and vertical shaft kilns favor producers with captive limestone reserves and advanced scrubbing infrastructure, locking in supply concentration around integrated operators.
- Quicklime:Calcium oxide produced at 900-1200°C yields 90-96% CaO content for metallurgical fluxing and soil stabilization. Steelmakers in Jiangsu and Shandong provinces specify reactivity and particle size distribution in procurement contracts.
- Hydrated Lime:Controlled slaking of quicklime produces calcium hydroxide with superior handling safety for water treatment and effluent neutralization. Municipal utilities in Australia's eastern states specify this grade for pH control applications.
- Dolomitic Lime:High-magnesium variant commands premium positioning in steel desulfurization across integrated mills in India and China.
- Calcium Carbonate:High-purity precipitated grades serve food processing and pharmaceutical applications with stringent SAMR and BIS certification requirements.
Volume placements concentrate in Quicklime; the faster expansion belongs to Hydrated Lime.
Application:
Cost tier differentiation separates commodity fluxing grades from certified chemical and food-grade specifications with 40-60% price premiums.
- Construction:IS 1514 certified lime for mortar and soil stabilization dominates procurement in India's western cement belt. Maharashtra and Gujarat ready-mix producers specify certified suppliers for infrastructure projects.
- Environmental:Flue gas desulfurization and wastewater neutralization drive hydrated lime consumption. China's MEE provincial pilots create compliance-driven demand spikes in industrial corridors.
- Chemical:Reagent-grade calcium oxide serves caustic soda and calcium carbide production with GB standard purity mandates.
- Metallurgical:Integrated steel mills consume dolomitic lime for molten metal treatment with multi-year offtake contracts locking in supply security.
Construction commands the largest volume share; Environmental applications are climbing the fastest on regulatory compliance mandates.
End User:
Customer type segmentation reveals diverging procurement sophistication between industrial processors and fragmented agricultural buyers.
- Manufacturing:Steel, cement, and chemical processors specify CaO content, reactivity, and delivery reliability in consolidated vendor panels. Eastern China's industrial clusters concentrate demand within 200-kilometer radii of calcination hubs.
- Water Treatment:Municipal utilities and industrial effluent plants favor bulk hydrated lime with automated dosing systems. Australia's EPA frameworks govern specification compliance.
- Agriculture:Soil pH correction and livestock sanitation drive scattered demand across Vietnam's Mekong Delta and Indonesia's Java corridor with price-sensitive spot purchasing.
- Food Processing:Precipitated calcium carbonate for anticaking and fortification requires FSSAI and SAMR food-grade certification with limited qualified supplier pools.
Manufacturing absorbs the heaviest volume flows; Water Treatment is gaining share fastest on infrastructure buildout and tightening discharge standards.
Distribution Channel:
Supply concentration in captive quarry networks favors direct sales relationships over merchant distribution for volume accounts.
- Direct Sales:Long-term offtake agreements with steelmakers, cement producers, and chemical processors displace spot market purchases. Victoria's infrastructure procurement and Maharashtra's ready-mix chains consolidate around three to five certified suppliers per region.
- Distributors:Regional merchants serve fragmented construction and agricultural demand with bagged product and technical service support.
- Wholesalers:Bulk handling intermediaries bridge calcination hubs to remote construction sites in the Philippines and Indonesia with limited logistics infrastructure.
- Online Retail:E-commerce platforms capture small-lot agricultural and specialty chemical buyers with price transparency and specification documentation.
Direct Sales lock in the steepest volume concentration; Distributors retain relevance in geographically fragmented demand pockets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate calcination capacity within 150 kilometers of Shanghai's port infrastructure. Vietnam's northern border provinces leverage cross-border limestone deposits to serve Guangxi industrial demand. India's western cement belt anchors construction-grade lime consumption.
China
Jiangsu and Shandong provinces host integrated steel mills consuming dolomitic lime for desulfurization. SAMR enforces GB standards for chemical-grade purity, disqualifying smaller kiln operators. The Yangtze River Delta industrial corridor concentrates quicklime demand within tight logistics radii around calcination hubs.
India
Maharashtra and Gujarat ready-mix producers specify IS 1514 certified lime for infrastructure procurement. BIS mandates tighten product standards, consolidating supply around organized producers with captive reserves. The western cement belt channels volume through long-term offtake agreements with certified suppliers.
Vietnam
Northern provinces exploit high-calcium limestone formations for chemical-grade lime exports. State-level quarry permitting timelines stretch to decade-long horizons for new entrants. Border-adjacent calcination facilities serve cross-border demand from Guangxi manufacturing clusters.
Australia
Queensland's high-purity calcium carbonate deposits support food processing and chemical applications. State EPA frameworks govern air emissions from calcination facilities, elevating compliance investments. Eastern states infrastructure procurement consolidates around bulk hydrated lime deliveries synchronized to batch plant schedules.
Philippines
The Build Better More program channels 194 billion pesos into road and bridge construction through 2028. Municipal procurement frameworks favor certified construction materials for public works. Hydrated lime for soil stabilization remains underpenetrated relative to ASEAN infrastructure buildout benchmarks.
Asia Pacific Lime Market Competitive Environment
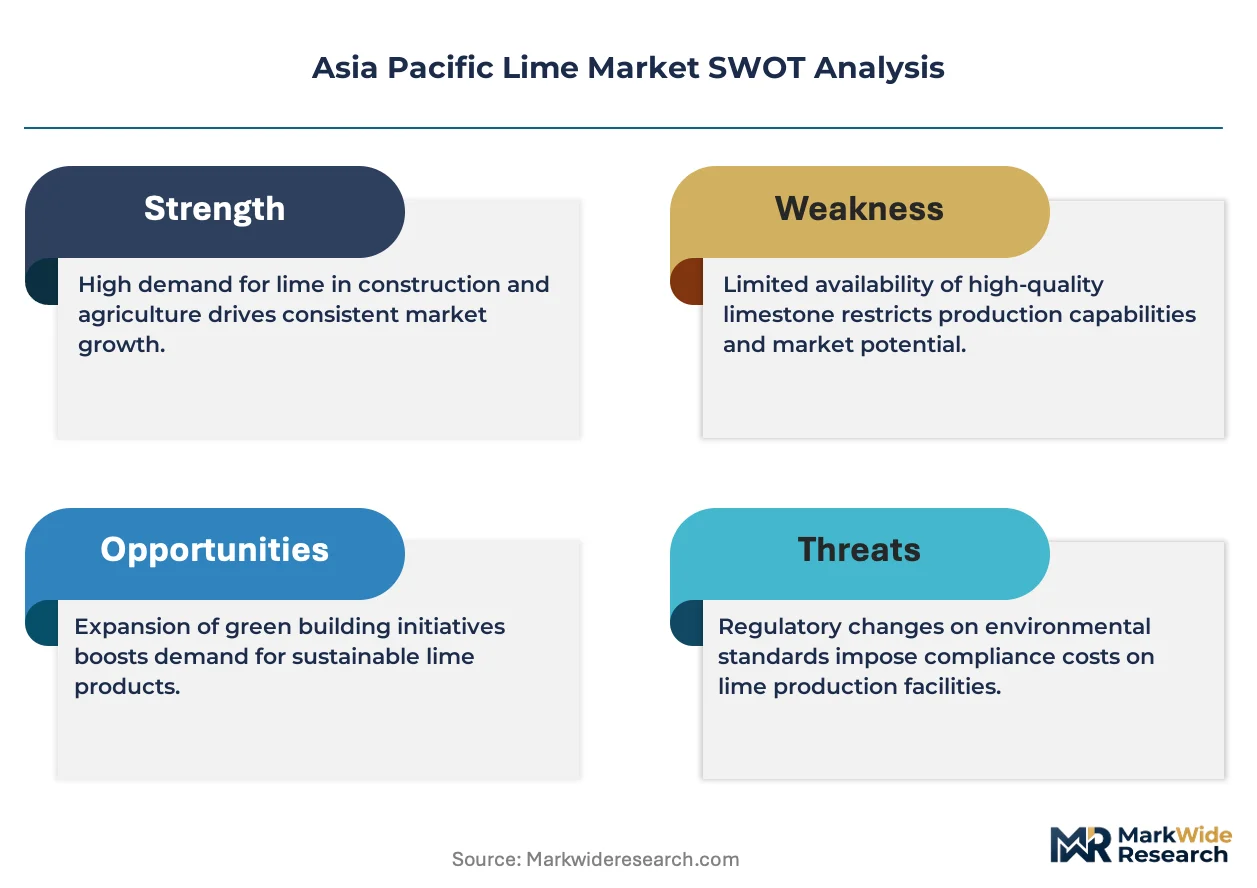
Diversified conglomerates compete with focused pure-play specialists across calcination technology tiers. Supply concentrates around producers with captive limestone reserves and emission control infrastructure. Three archetypes dominate: integrated quarry-to-delivery networks, metallurgical specialists with dolomitic lime capacity, and high-purity carbonate processors serving food-grade applications. Competitive moves center on kiln modernization cycles and direct sales relationships displacing merchant distribution.
Among Asia Pacific-based operators, Graymont Asia Pacific, Chememan Plc, and Sibelco Australia occupy distinct positioning within this structure. Graymont exemplifies the integrated network archetype spanning Southeast Asian markets. Chememan anchors the metallurgical specialization vector through dolomitic lime production. Sibelco represents the high-purity carbonate tier serving stringent certification requirements. Each sits within procurement scoring matrices that weight digitized quality traceability alongside traditional purity metrics.
| Leading Market Players |
|---|
| India Lime Producer Association |
| China National Fruit Marketing Corp |
| Thai Lime Exporters Association |
| Chememan Plc |
| Vietnam Fruit and Vegetable Export Corp |
| Australian Lime Export Co |
| Philippine Citrus Growers Association |
| Graymont Asia Pacific |
| Sibelco Australia |
| Others |
Value Chain & Pricing Dynamics
Coal and natural gas feedstock costs flow through calcination economics to stratify pricing across quicklime purity grades, with fuel expenses representing 35-45 percent of production outlays and forcing tiered contract structures that reward integrated kiln operators with captive limestone reserves.
Pricing Analysis
Margin tightening in standard-grade quicklime reflects energy input volatility and BIS certification compliance burdens. Three-tier pricing structure across premium chemical-grade, certified construction-grade, and unorganized kiln output dominates procurement matrices. Price differentiation hinges on SAMR GB standard purity and IS 1514 certification level. Cost compression accelerates as smaller rotary kiln operators in Vietnam and Indonesia lack hedging mechanisms. Agricultural buyers in Indonesia's Java corridor exhibit highest price sensitivity; metallurgical steelmakers in Jiangsu province show lowest sensitivity due to multi-year offtake contract lock-ins.
Supply Chain Analysis
Limestone reserve quality rests on high-calcium deposits concentrated in Guangxi, Vietnam's northern provinces, and select Queensland formations. Quicklime production draws from metallurgical coal, natural gas, and specialized refractory linings as critical inputs. Single-source vulnerability emerges from decade-long quarry permitting timelines blocking new entrant supply. Distribution runs through direct sales relationships with steelmakers and cement producers displacing traditional merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as emission control investments and captive quarry access separate viable producers from forced closures.
For Market Incumbents: Lock in multi-year offtake contracts with integrated steel mills in Jiangsu and Shandong provinces before carbon intensity benchmarks tighten. Deepen upstream control over high-calcium limestone reserves in Vietnam's northern border provinces to secure feedstock against decade-long permitting delays. Invest in digitized kiln monitoring systems to meet procurement scoring matrices that now weight quality traceability alongside traditional CaO content metrics. Defend against slag substitution threats in Japan and South Korea by embedding technical service teams within steelmaker R&D facilities. For New Entrants and Emerging Players: Carbon capture integration technology offers a regulatory-compliant entry wedge into China's MEE provincial pilot markets. Target hydrated lime for soil stabilization in the Philippines Build Better More program, where penetration lags ASEAN infrastructure benchmarks. Pursue direct-to-mixer distribution partnerships with ready-mix concrete producers in Australia's eastern states, bypassing entrenched merchant distributors. Anchor initial capacity in border-adjacent Vietnamese provinces to serve cross-border Guangxi manufacturing demand with lower logistics radii than inland Chinese competitors. For Investors and Strategic Acquirers: Distressed-cycle entries favor organized producers with IS 1514 certification and captive reserves in India's western cement belt as BIS mandates force unorganized kiln closures. Frame five-to-ten year viability around emission control infrastructure rather than raw capacity tonnage. Watch for MEE carbon intensity benchmark rollout pace across Chinese provincial jurisdictions as the inflection indicator for supply consolidation velocity. Prioritize targets with existing scrubber investments over greenfield kiln permits facing extended approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Reserves | Captive quarry access in Vietnam's northern provinces eliminates decade-long permitting risk for Chinese cross-border supply. |
| Carbon Capture Retrofit Installation | Post-combustion systems at Jiangsu calcination facilities monetize CO2 for urea synthesis under MEE emission credit pilots. |
| Long-term Metallurgical Offtake Agreement | Multi-year contracts with Shandong steel mills lock in premium dolomitic lime pricing against slag substitution trends. |
| Direct-to-Mixer Distribution Network | Bulk hydrated lime deliveries synchronized to Victoria batch plant schedules displace traditional merchant intermediaries. |
| IS 1514 Certification Investment | BIS compliance enables pricing power in Maharashtra and Gujarat ready-mix procurement as unorganized operators exit. |
Study Parameters
Document review covered customs and trade flow databases, BIS certification registries, and MEE provincial emission pilot disclosures, complemented by interviews with rotary kiln plant managers, steelmaker procurement leads, cement producer technical directors, and state pollution control board officials. Secondary validation drew from SAMR GB standard filings, Australian state EPA enforcement records, and India Lime Producer Association capacity surveys. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates across the analysis window.
Cross-referencing historical production data against panel input from calcination technology suppliers and limestone quarry operators shaped the analytical framework. Segmentation dimensions spanned product type tier, end-use industry concentration, regional regulatory cluster, and distribution channel structure. CAGRs were derived through regression analysis of historical shipment volumes and elasticity-adjusted demand drivers. Industry-specific forecast inputs included steel desulfurization intensity ratios and infrastructure project pipeline tracking for Philippines Build Better More program commitments.
Several conditions sit outside the modeled scope, including abrupt fuel price shocks beyond historical volatility bands, forced kiln closures from unanticipated regulatory enforcement waves, and breakthrough slag substitution technologies that compress lime unit consumption per ton of crude steel. Forecasts reflect documented assumptions and risk-weighted scenario weightings. A small set of named triggers warrants ongoing watch: MEE carbon intensity benchmark expansion pace, BIS certification audit enforcement rigor, and Philippines municipal procurement framework implementation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Dragon Fruit Market
Fruits and Vegetables
Bamboo Shoots Market
Fruits and Vegetables
Noni Fruit Powder Market
Fruits and Vegetables
Avocado Puree Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
Qatar Fruits and Vegetables Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
Fermented Cucumber Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Goji Berries Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Japan Frozen Fruit Puree Market
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market