
 Freeze-Dried Fruit Powder Market | 2026-2036
Freeze-Dried Fruit Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze-Dried Fruit Powder Market Analysis
China is reconfiguring capacity for freeze-dried tropical fruit processing through state-backed agricultural modernization zones. Van Drunen Farms leverages backward integration into raw fruit sourcing across Midwestern US growing regions. European Freeze Dry Limited anchors its position through pharmaceutical-grade cleanroom drying infrastructure. Paradise Fruits Solutions GmbH & Co. KG differentiates via precision particle-size engineering for beverage solubility requirements.
Freeze-dried fruit powder consists of fresh fruit pulp subjected to sublimation dehydration at temperatures below minus forty degrees Celsius, yielding a shelf-stable matrix retaining over ninety percent of original vitamin C and polyphenol content. The material serves as a natural colorant, flavor carrier, and nutrient fortificant across formulated food systems. Berry powder occupies the dominant revenue position within product type segmentation due to concentrated anthocyanin demand from supplement and cosmetics formulators. Single serve packaging within the packaging type dimension is expanding fastest among direct-to-consumer wellness brands seeking portion-controlled convenience formats.
FDA GRAS self-determination protocols govern ingredient safety for US food and beverage applications, while EFSA health claim substantiation requirements constrain marketing language for European dietary supplement positioning. China's NMPA and GB standards for food additives create additional compliance layers for imported fruit powder entering functional food channels. Stakeholders must monitor evolving dual carbon goals from China's MEE and their projected impact on energy-intensive lyophilization operations.
Market Dynamics
Energy-intensive lyophilization operations face mounting pressure from China's dual carbon goals under MEE oversight, forcing processors to relocate capacity toward renewable-powered zones or absorb carbon-offset costs that reshape regional competitiveness.
Growth Catalysts
- Clean-label ingredient mandates:EFSA's evolving guidance on health claims drives supplement formulators toward berry powders with substantiated polyphenol content, accelerating procurement from validated suppliers.
- Pharmaceutical-grade infrastructure expansion:Cleanroom drying capabilities at European processors unlock medical nutrition and clinical food applications previously blocked by contamination risk.
- Midwest raw fruit sourcing clusters:Backward integration into Michigan and Washington apple, cherry, and blueberry orchards secures varietal traceability for organic certification requirements.
Market Restraints
- Energy cost volatility:Natural gas and electricity price spikes in Germany directly compress margins at Hamburg corridor processors dependent on continuous sublimation cycles.
- Input concentration risk:Tropical fruit pulp supply chains cluster in Southeast Asian export zones vulnerable to monsoon disruption and port congestion.
- Substitution pressure from spray-dried alternatives:Lower-cost maltodextrin carriers capture beverage fortification contracts where heat-sensitive nutrient retention is deprioritized.
Strategic Opportunities
- Underpenetrated pet nutrition channels:Freeze-dried fruit inclusions for premium dog and cat food formulations remain below ten percent penetration in North American specialty retail.
- EU Green Deal agricultural transition incentives:CAP subsidies for sustainable processing infrastructure support retrofitting of legacy drying facilities in Poland and Romania.
- Precision particle-size engineering convergence:Integration of laser diffraction quality control with modified atmosphere packaging extends solubility performance claims into ready-to-drink protein beverages.
Industry Challenges
- Novel Food authorization timelines:EU Regulation 2015/2283 safety dossier requirements delay market entry for exotic tropical powders by eighteen to thirty-six months.
- Lyophilization technician scarcity:Specialized vacuum system maintenance and sublimation cycle optimization skills concentrate at legacy pharmaceutical equipment operators.
- Cross-border GB standard harmonization:China's NMPA food additive reclassifications create compliance friction for imported powders entering functional food channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze-Dried Fruit Powder Market |
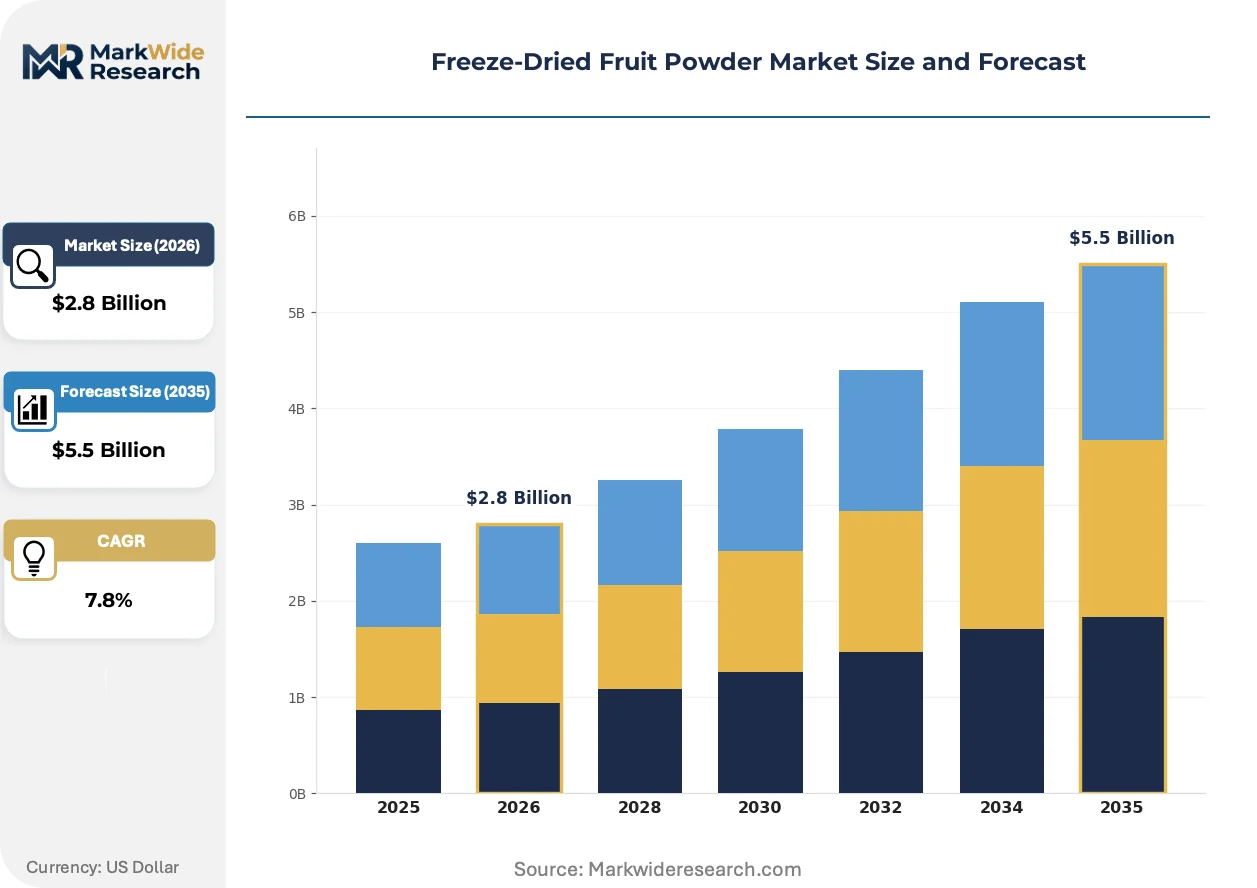
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Berry Powder, Citrus Powder, Tropical Powder, Stone Fruit Powder End Use Industry: Food & Beverage, Cosmetics, Dietary Supplements, Bakery Products Packaging Type: Bulk Packaging, Retail Packs, Single Serve, Pouches Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Kanegrade Limited, Van Drunen Farms, European Freeze Dry Limited, Aarkay Food Products Ltd., Paradise Fruits Solutions GmbH & Co. KG, Döhler Group SE, Milne MicroDried, Saipro Biotech Pvt. Ltd., Thrive Freeze Dry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze-Dried Fruit Powder Market Emerging Trajectories
Digital twin modeling of sublimation kinetics and blockchain-enabled orchard-to-powder traceability systems are compressing quality assurance cycles and reconfiguring buyer-supplier contracting structures across formulated food networks.
Controlled-atmosphere microwave-assisted freeze-drying (CA-MFD) is virtualizing traditional batch lyophilization timelines by reducing primary drying duration from twenty-four hours to under eight hours while preserving cellular structure integrity. Nutraceutical contract manufacturers in Germany and the Netherlands are piloting CA-MFD units for high-anthocyanin berry matrices where thermal degradation tolerance is minimal. This acceleration is virtualizing capital efficiency benchmarks and compressing minimum viable scale thresholds for regional processors.
EFSA's 2023 updated guidance on Article 13.1 health claims substantiation now requires randomized controlled trial data for antioxidant-related marketing statements, elevating documentation burdens for berry powder positioning. The regulation forces reformulation toward standardized polyphenol extracts or investment in clinical study infrastructure. Dietary supplement brands targeting German and French pharmacy channels face the steepest compliance ramps and are consolidating supplier relationships toward dossier-complete processors.
Direct-to-consumer wellness brands are unbundling bulk ingredient procurement from co-manufacturing relationships, establishing captive freeze-drying capacity or exclusive offtake agreements with single-origin orchards. This disintermediation bypasses traditional ingredient distributors and concentrates volume commitments among vertically integrated processors. The pattern is most visible in California and Colorado, where venture-backed start-ups market traceable single-variety powders through subscription channels.
Freeze-Dried Fruit Powder Market Segmentation
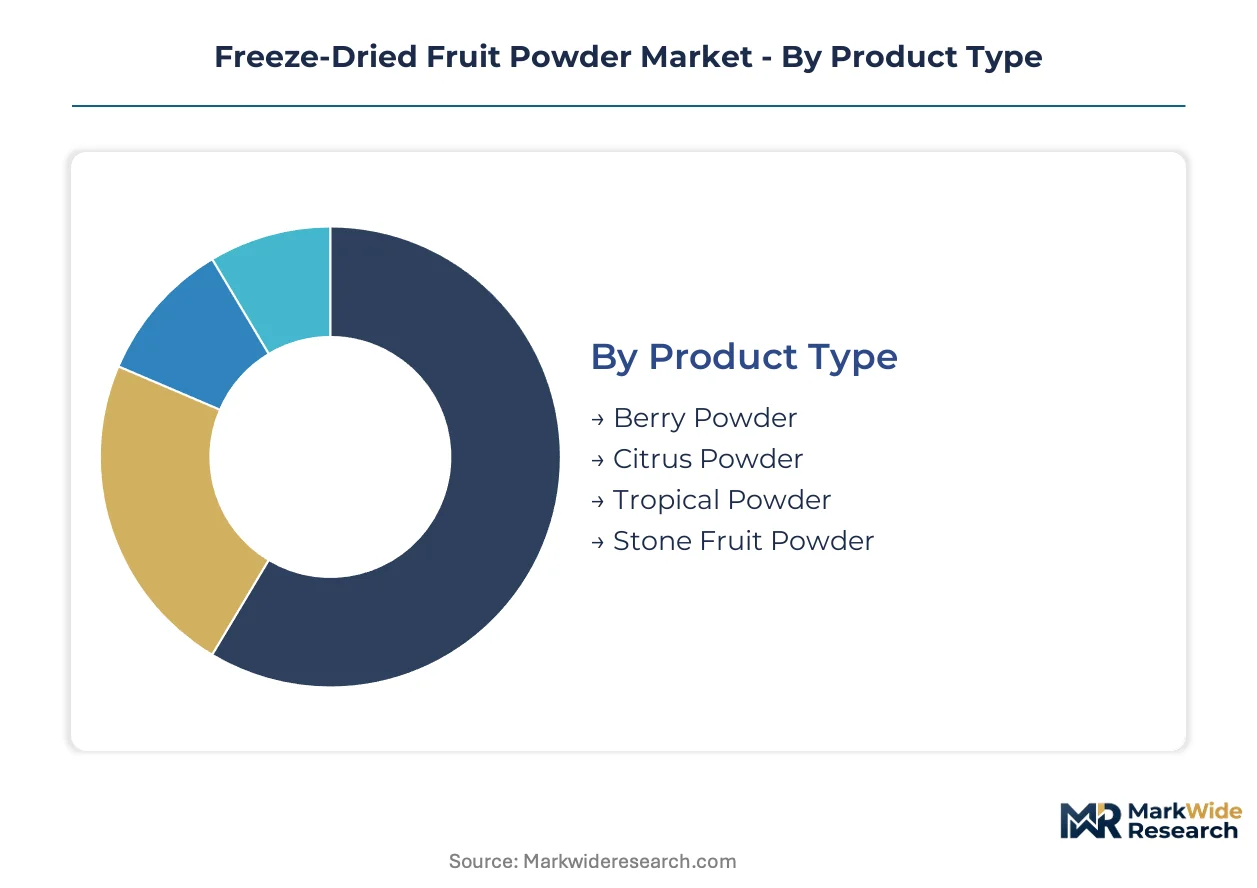
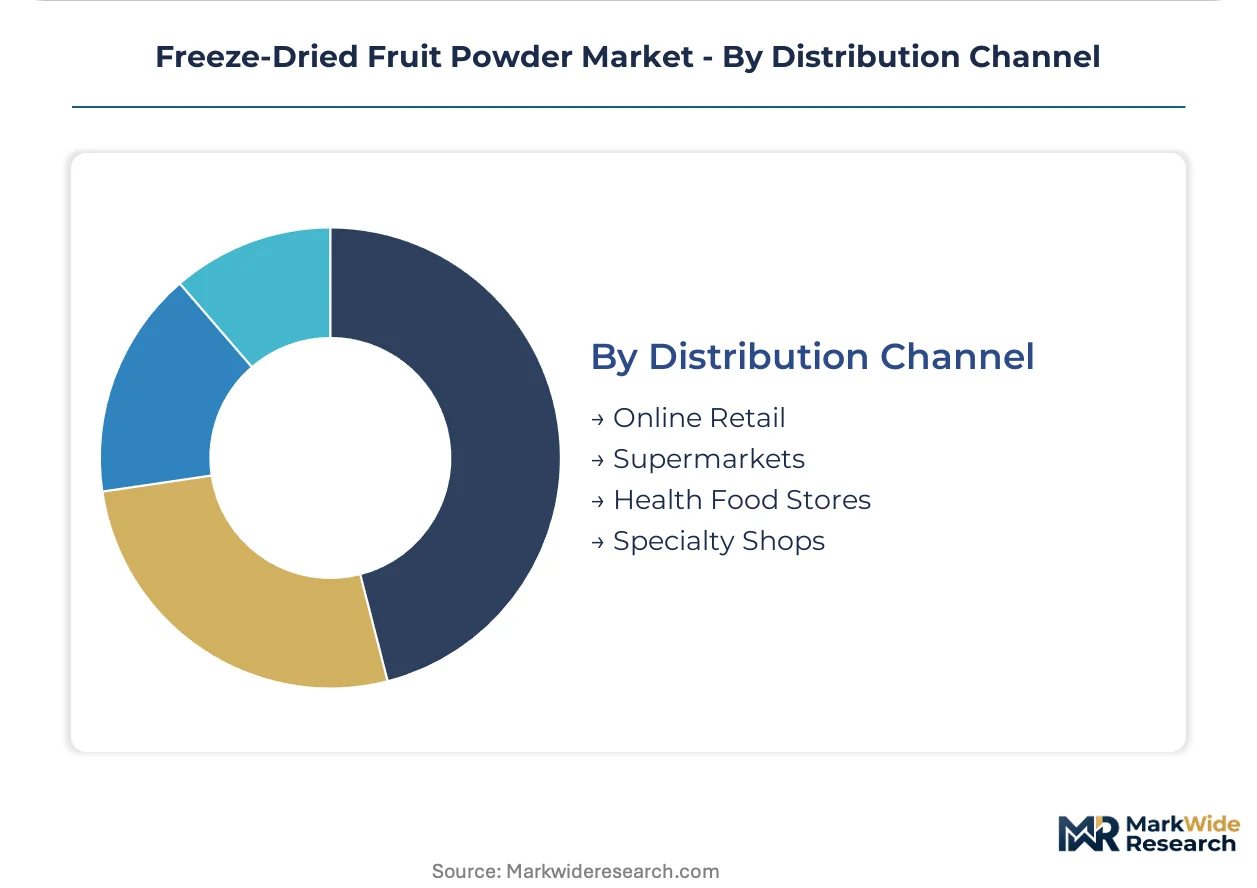
Freeze-dried fruit powder markets fragment across four distinct dimensions that determine pricing power and margin capture. Product type and end-use alignment dictate lyophilization cycle specifications, while packaging and channel choices separate commodity bulk sales from premium direct-to-consumer positioning.
Product Type:
Mature berry applications coexist with emerging tropical formats as formulators balance substantiated health claims against supply chain risk.
- Berry Powder:Anthocyanin-rich matrices from blueberry, raspberry, and elderberry sources retain polyphenol stability through controlled sublimation. Demand concentrates in German and French dietary supplement channels where EFSA health claim substantiation requirements favor documented antioxidant content.
- Tropical Powder:Mango, pineapple, and dragon fruit variants deliver vibrant colorant properties for beverage fortification. Procurement is accelerating among US clean-label brands seeking to bypass synthetic additive scrutiny, though Southeast Asian pulp supply concentration creates monsoon vulnerability.
- Citrus Powder:Freeze-dried orange and lemon powders preserve volatile terpene profiles for flavor carrier applications. European processors in Spain and Italy dominate capacity for organic-certified citrus matrices.
- Stone Fruit Powder:Cherry and peach variants serve natural sweetening functions in reduced-sugar bakery formulations. Michigan and Washington orchard clusters supply North American organic certification requirements.
Berry powder retains volume leadership; tropical powder holds the steepest expansion curve.
End Use Industry:
Application maturity spreads from established food manufacturing through nascent clinical nutrition channels requiring pharmaceutical-grade infrastructure.
- Food & Beverage:Natural colorant and flavor carrier applications in ready-to-drink smoothies and protein beverages demand precision particle-size engineering for solubility performance. German beverage formulators specify sub-100-micron distributions to prevent sedimentation.
- Dietary Supplements:Capsule and tablet manufacturers prioritize standardized polyphenol content for EFSA Article 13.1 compliance. Cleanroom drying capabilities unlock medical nutrition positioning previously blocked by contamination risk.
- Cosmetics:Anthocyanin-rich berry powders serve active ingredient roles in antioxidant skincare formulations. French and Korean beauty brands specify organic-certified sources for clean beauty marketing.
- Bakery Products:Natural colorant substitution for synthetic dyes drives procurement in premium European and North American artisan channels. Moisture sensitivity requires modified atmosphere packaging for shelf stability.
Food & beverage commands the largest volume commitment; dietary supplements generate the highest margin capture per kilogram.
Packaging Type:
Format selection tracks customer scale, with industrial buyers favoring unbranded bulk and wellness brands investing in portion-controlled convenience.
- Bulk Packaging:25-kilogram fiber drums with nitrogen flushing serve contract manufacturers and industrial bakeries. Hamburg corridor processors dominate European bulk supply through integrated logistics.
- Single Serve:Pre-measured sachets address direct-to-consumer wellness brands seeking subscription channel differentiation. California and Colorado venture-backed start-ups specify single-origin traceability for premium positioning.
- Retail Packs:100-300 gram canisters target health food store distribution. German pharmacy channels require child-resistant closures for supplement-adjacent positioning.
- Pouches:Flexible stand-up bags with resealable zippers balance cost efficiency with shelf presence. Polish and Romanian processors leverage CAP subsidy support for sustainable packaging retrofits.
Bulk packaging anchors industrial procurement volume; single serve formats are climbing the fastest among wellness brand channels.
Distribution Channel:
Channel fragmentation reflects divergent customer acquisition economics between digital-native brands and legacy retail gatekeepers.
- Online Retail:Direct-to-consumer platforms enable traceability storytelling and subscription revenue models. US wellness brands bypass traditional ingredient distributors through captive freeze-drying capacity or exclusive orchard offtake agreements.
- Supermarkets:Mass retail placement requires scale certification and promotional slotting fees. Berry powder SKUs concentrate in German REWE and EDEKA organic private label lines.
- Health Food Stores:Independent retailers prioritize organic certification and local sourcing narratives. Colorado and California specialty retail supports premium single-variety positioning.
- Specialty Shops:Gourmet food boutiques and cosmetic apothecaries stock limited SKUs with experiential merchandising. French pharmacy channels demand EFSA dossier completeness for antioxidant marketing claims.
Supermarkets maintain the broadest geographic footprint; online retail is gaining share fastest through disintermediation of traditional distribution layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freeze-dried fruit powder capacity clusters around established agricultural processing corridors where cold-chain logistics and lyophilization infrastructure intersect. Regulatory divergence across major markets is fragmenting approval pathways and reshaping procurement geography.
United States
Midwestern orchard clusters in Michigan and Washington supply organic-certified berry and stone fruit feedstock to domestic processors. FDA GRAS self-determination protocols govern ingredient safety for food and beverage applications. Van Drunen Farms leverages backward integration into these growing regions to secure varietal traceability.
Germany
Dietary supplement manufacturers in Hamburg and Frankfurt logistics corridors drive concentrated anthocyanin demand from berry powders. EFSA health claim substantiation requirements under Article 13.1 constrain marketing language for antioxidant positioning. European Freeze Dry Limited anchors operations through pharmaceutical-grade cleanroom drying infrastructure.
China
State-backed agricultural modernization zones are reconfiguring capacity for tropical fruit processing to serve domestic functional food channels. NMPA and GB standards for food additives create compliance layers for imported powders. Dual carbon goals under MEE oversight are pressuring energy-intensive lyophilization operations toward renewable-powered zones.
India
Saipro Biotech Pvt. Ltd. and domestic processors source tropical fruit pulp from Southeast Asian supply chains vulnerable to monsoon disruption. FSSAI food safety standards govern additive classifications for nutraceutical applications. Processing capacity concentrates around Mumbai-Pune and Bengaluru corridors serving export markets.
United Kingdom
EFSA-aligned regulatory frameworks post-Brexit maintain health claim documentation burdens for berry powder positioning. Kanegrade Limited and European processors serve formulated food manufacturers seeking clean-label ingredient alternatives. Logistics integration with Rotterdam and Hamburg corridors sustains bulk supply efficiency.
Freeze-Dried Fruit Powder Market Vendor Landscape
Vertically integrated processors and specialized contract manufacturers split the market between captive supply security and flexible tolling services. The vendor base concentrates around three strategic archetypes: orchard-backward integrators securing organic certification, pharmaceutical-grade infrastructure operators unlocking medical nutrition channels, and precision-engineering specialists serving beverage solubility requirements. Competitive moves center on exclusive offtake agreements with single-origin orchards and retrofitting legacy facilities with controlled-atmosphere microwave-assisted freeze-drying units.
Within the orchard-integrated tier, Van Drunen Farms exemplifies backward control over Midwestern growing regions. Among European infrastructure specialists, European Freeze Dry Limited occupies a position defined by cleanroom drying capabilities. Paradise Fruits Solutions GmbH & Co. KG represents the precision-engineering archetype through particle-size engineering for beverage applications. These three anchors illustrate divergent paths to margin capture across supplement, clinical nutrition, and beverage fortification channels.
| Leading Market Players |
|---|
| Kanegrade Limited |
| Van Drunen Farms |
| European Freeze Dry Limited |
| Aarkay Food Products Ltd. |
| Paradise Fruits Solutions GmbH & Co. KG |
| Döhler Group SE |
| Milne MicroDried |
| Saipro Biotech Pvt. Ltd. |
| Thrive Freeze Dry |
| Others |
Supply Flow & Price Mechanics
Hamburg corridor processors anchor European lyophilization capacity, with their energy cost exposure directly transmitting into downstream berry powder pricing power across German and French dietary supplement channels. Cleanroom certification tiers and organic traceability requirements stratify procurement costs, while Southeast Asian tropical pulp concentration creates divergent risk premiums between berry and tropical formats.
Pricing Analysis
EFSA Article 13.1 health claim substantiation dictates the pricing tier structure for European berry powder positioning, separating dossier-complete pharmaceutical-grade suppliers from commodity bulk operators. Three-tier pricing structure across premium certified-organic, standard food-grade, and economy conventional tiers reflects documentation burden and cleanroom infrastructure investment. Cost compression in standard tiers is intensifying because natural gas price volatility erodes continuous sublimation margins at Hamburg processors. Contract manufacturers exhibit highest price sensitivity, while direct-to-consumer wellness brands absorb premium positioning for traceability storytelling.
Supply Chain Analysis
Midwestern US orchard clusters, Southeast Asian tropical pulp zones, and Mediterranean citrus belts feed freeze-dried fruit powder production across three distinct input streams. Raw material dependencies center on blueberry and cherry varietals from Michigan and Washington, mango and dragon fruit pulp from Thailand and Vietnam, and orange matrices from Spain and Italy. Single-source vulnerability concentrates in Southeast Asian monsoon corridors, where port congestion disrupts tropical powder feedstock. Distribution runs through Hamburg and Rotterdam logistics hubs for European bulk, with direct-to-consumer channels bypassing traditional ingredient distributors through captive freeze-drying capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeze-dried fruit powder markets are cycling through a capacity rationalization phase as energy cost pressures force consolidation among legacy processors. China's dual carbon goals under MEE oversight are accelerating this restructuring by penalizing carbon-intensive lyophilization operations.
For Market Incumbents: Pre-empt margin erosion by retrofitting legacy facilities with controlled-atmosphere microwave-assisted freeze-drying units that compress cycle timelines from twenty-four hours to under eight hours. Secure exclusive offtake agreements with single-origin orchards in Michigan and Washington to defend organic certification traceability against emerging contract manufacturers. Channel control through pharmaceutical-grade cleanroom infrastructure represents the critical lever for medical nutrition positioning. For New Entrants and Emerging Players: Pet nutrition inclusions for premium dog and cat food formulations in North American specialty retail represent the most penetrable entry point, with penetration below ten percent creating first-mover advantages. CAP subsidy-supported retrofitting opportunities in Poland and Romania offer infrastructure cost advantages for European market entry. Direct-to-consumer subscription channels enable bypass of traditional ingredient distributor gatekeepers through traceability storytelling. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because orchard-backward integrated processors with pharmaceutical-grade cleanroom capabilities will capture disproportionate margin expansion as EFSA documentation burdens intensify. Acquisition targets should prioritize Midwestern US operators with organic certification infrastructure and established German logistics corridor relationships. The signal to watch is CA-MFD unit adoption rates among European processors, which compress capital efficiency thresholds and accelerate minimum viable scale requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Microwave-Assisted Freeze-Drying Adoption | CA-MFD unit deployment by German nutraceutical contract manufacturers virtualizes capital efficiency benchmarks for high-anthocyanin berry matrices. |
| Exclusive Single-Origin Orchard Offtake Agreements | Captive supply relationships with Michigan and Washington growers secure varietal traceability for organic certification requirements. |
| Pharmaceutical-Grade Cleanroom Infrastructure Expansion | Cleanroom drying capabilities at European processors unlock medical nutrition and clinical food applications previously blocked by contamination risk. |
| Direct-to-Consumer Channel Disintermediation | Venture-backed wellness brands in California and Colorado bypass traditional ingredient distributors through captive freeze-drying capacity. |
| CAP Subsidy-Supported Sustainable Retrofitting | EU Green Deal agricultural transition incentives support legacy drying facility modernization in Poland and Romania. |
Methodological Framework
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in documented operational reality. Lyophilization equipment operators, dietary supplement formulators, organic certification auditors, and logistics corridor managers provided ground-level perspective on capacity constraints and procurement patterns. FDA GRAS determination databases, EFSA Novel Food authorization records, EU CAP subsidy disbursement reports, and China NMPA food additive classifications supplied secondary validation. Bottom-up facility capacity modeling and top-down end-use demand estimation triangulate volume outputs.
Calibration against historical lyophilization capacity utilization and energy cost trajectories shapes the projection framework across the analysis window. Product type segmentation by berry, tropical, citrus, and stone fruit matrices; end-use industry splits across food and beverage, dietary supplements, cosmetics, and bakery products; and packaging format differentiation between bulk and single serve all feed into demand modeling. CAGRs derive from segment-specific growth assumptions tied to clean-label ingredient procurement trends and EFSA health claim substantiation evolution. Energy cost volatility and Southeast Asian supply disruption probability weight scenario outputs.
Practitioners should monitor MEE dual carbon enforcement intensity and EFSA Article 13.1 guidance updates for early signals of forecast revision. Projections reflect assumptions about lyophilization technology adoption rates and regulatory documentation burden trajectories. Cross-checking against customs trade data for freeze-dried fruit powder import volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
Fruit Pulp Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
Cucumber and Gherkins Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Global Fruit Pomace Market
Fruits and Vegetables
Europe Frozen Fruits and Vegetables Market
Fruits and Vegetables
Mango Puree Market
Fruits and Vegetables
GCC Fruits and Vegetables Market
Fruits and Vegetables
Rosehip Market
Fruits and Vegetables
Annatto Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
Mulberry Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Infused Dried Fruits Market