
 Fruit Pulp Market | 2026-2036
Fruit Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Pulp Market Intelligence
India is fragmenting as new aseptic processing capacity comes online in Maharashtra and Gujarat. Doehler Group leverages its European extraction technology to sustain premium positioning in concentrated fruit preparations. Keventer Group anchors South Asian supply through integrated mango and guava sourcing networks. SunOpta Inc. competes in North American organic segments with non-GMO certification and clean-label formulations.
Fruit pulp comprises mechanically processed fruit flesh with retained fiber, soluble solids, and natural sugars, typically standardized to 10-32°Brix depending on end-use application. Manufacturers employ hot-break or cold-break enzymatic processes to control viscosity and preserve organoleptic properties for downstream formulation. The beverage end-use segment leads volume absorption, with concentrated pulp commanding the largest share of industrial procurement due to freight and storage efficiencies. Frozen pulp exhibits the fastest structural expansion, driven by smoothie chains and specialty dairy applications requiring extended shelf stability without chemical preservatives.
FDA enforcement of juice HACCP rules and the EU's MDR-aligned food contact material standards shape product safety benchmarks for export-oriented processors. India's FSSAI mandates quantitative ingredient declarations that push brands toward single-origin pulp sourcing to simplify compliance. BIS certification for aseptically packed fruit products creates tiered market access barriers between organized and unorganized suppliers. Stakeholders must monitor evolving cold-chain infrastructure investments and regulatory harmonization pressures between major importing blocs to calibrate capacity allocation decisions.
Market Dynamics
Cold-chain infrastructure upgrades and the EU F-Gas Regulation are compressing frozen pulp logistics economics while aseptic processing capacity expansion in India fragments regional supply concentration.
Growth Catalysts
- Clean-label beverage formulation:Food and beverage manufacturers accelerate concentrated pulp procurement to replace artificial additives in juice, smoothie, and dairy applications.
- F-Gas Regulation compliance:The EU's phasedown of hydrofluorocarbon refrigerants forces cold-chain operators to upgrade freezing and transport equipment, improving frozen pulp shelf stability.
- Aseptic processing technology:Hot-break and cold-break enzymatic systems enable processors to standardize viscosity and preserve organoleptic properties for industrial buyers.
Market Restraints
- Input cost volatility:Fresh fruit procurement faces climate-driven yield fluctuation, squeezing margin predictability for pulp processors dependent on mango, guava, and tropical varietals.
- Supply concentration risk:Organized suppliers in Maharashtra and Gujarat control premium aseptic capacity, creating tiered access barriers for smaller beverage formulators.
- Regulatory friction:India's FSSAI quantitative ingredient declaration mandates complicate multi-origin pulp blending, forcing single-origin sourcing that limits formulation flexibility.
Strategic Opportunities
- Underpenetrated organic segments:North American clean-label demand outpaces certified organic pulp supply, creating white space for non-GMO verified processors.
- Smoothie chain channel expansion:Frozen pulp adoption accelerates in quick-service beverage outlets requiring extended shelf stability without chemical preservatives.
- PLI scheme alignment:India's production-linked incentive framework for food processing subsidizes aseptic line investments, attracting integrated dairy and juice processors.
Industry Challenges
- Capex intensity for cold-chain compliance:EU F-Gas retrofit requirements and FDA juice HACCP enforcement demand simultaneous equipment upgrades, straining mid-tier processor balance sheets.
- Certification timeline compression:BIS aseptic packing approval and organic certification cycles create working capital gaps between capacity commissioning and market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Pulp Market |
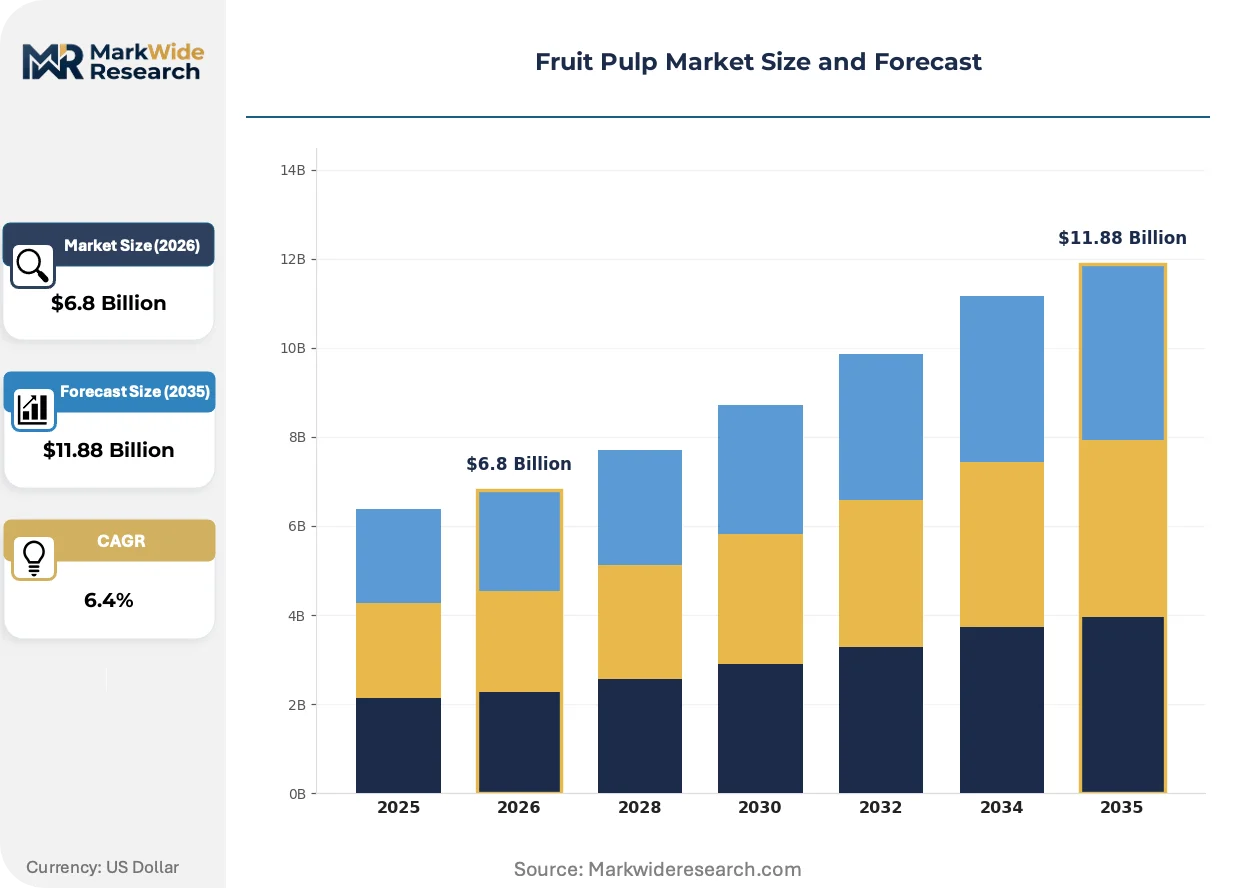
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Pulp, Puree, Frozen Pulp, Dried Pulp End Use: Beverages, Bakery, Dairy, Confectionery Packaging Type: Glass Jar, Plastic Container, Tetra Pack, Pouch Distribution Channel: Supermarket, Online Retail, Specialty Store, Wholesale |
| Companies Covered | Doehler Group, Keventer Group, PepsiCo Inc., SunOpta Inc., Iprona The Fruit Company, Conagra Brands Inc., SVZ International B.V., Allanasons Private Limited, AGRANA Beteiligungs-AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Pulp Market Strategic Shifts & Innovations
Digital traceability systems and enzymatic process control are compressing quality assurance cycles while regulatory alignment pressures reshape export-oriented processor strategies.
Aseptic bulk storage and remote temperature monitoring is virtualizing traditional frozen pulp inventory management. Large beverage formulators deploy IoT-enabled cold-chain sensors to track °Brix stability and enzymatic activity across multi-modal shipments. This virtualization enables just-in-time pulp procurement that reduces working capital requirements and waste from temperature excursions.
The EU F-Gas Regulation mandates refrigerant phase-down schedules that reshape frozen logistics economics. Cold-chain operators must retrofit transport refrigeration units with lower-GWP alternatives, increasing fleet capital costs. Indian exporters targeting EU markets face compressed compliance timelines as member states accelerate national implementation ahead of 2030 targets.
Specialty dairy processors now specify single-origin pulp with full farm-to-facility traceability to satisfy clean-label positioning. This specification displaces commodity blended concentrates in premium yogurt and ice cream formulations. The shift is most visible in European and North American organic dairy segments where ingredient storytelling commands shelf price premiums.
Fruit Pulp Market Segmentation
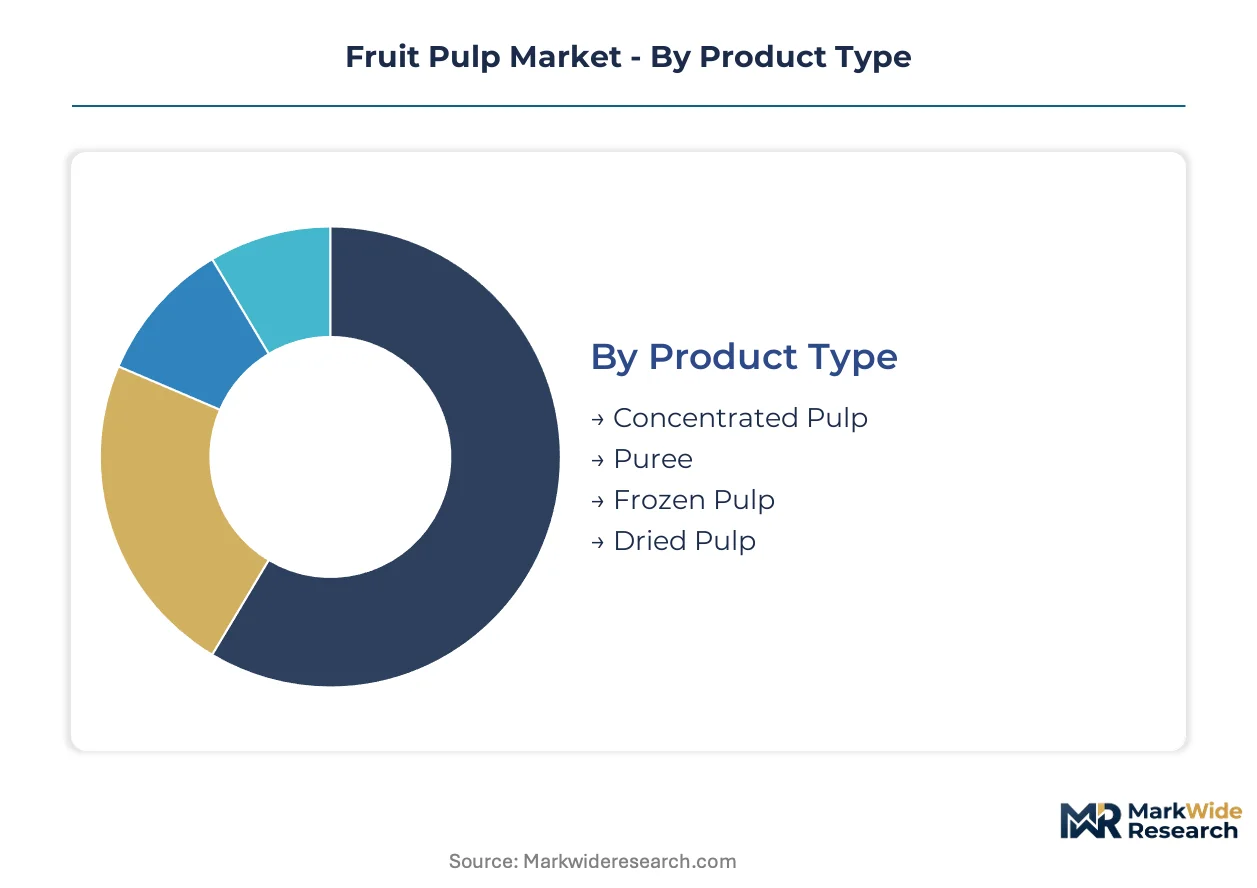
Fruit pulp segmentation reflects divergent processing economics and cold-chain requirements across industrial and retail channels. Buyers select product formats based on shelf stability needs, formulation viscosity specifications, and distribution infrastructure availability.
Product Type:
Cost tier differentiation separates commodity concentrates from premium frozen formats requiring specialized logistics investment.
- Concentrated Pulp:Mechanical reduction to 28-32°Brix soluble solids delivers freight efficiency for long-haul industrial procurement. Beverage manufacturers in India and Brazil prioritize this format for large-scale juice and nectar production where water removal cuts transport expenditure.
- Frozen Pulp:Blast-frozen at -18°C immediately after enzymatic processing to arrest enzymatic browning and preserve volatile aromatic compounds. Smoothie chains and specialty dairy processors in North American urban markets absorb volume growth as EU F-Gas Regulation upgrades improve cold-chain reliability.
- Puree:Coarse-textured preparation retaining higher fiber content for bakery and infant food applications requiring mouthfeel differentiation.
- Dried Pulp:Low-moisture powder format serving confectionery and nutritional bar segments with ambient distribution constraints.
Concentrated pulp holds installed capacity. Frozen pulp is rotating up the share rankings.
End Use:
Application requirements dictate viscosity specifications, acidity tolerance, and packaging sterilization protocols.
- Beverages:Juice, nectar, and smoothie formulations consume standardized 10-15°Brix pulp with controlled pH for thermal stability. Clean-label procurement from Indian and Thai processors is displacing artificial flavor systems in European retail channels.
- Dairy:Yogurt, ice cream, and flavored milk applications demand single-origin pulp with full farm-to-facility traceability for premium positioning. European organic dairy segments specify aseptic puree to avoid post-pasteurization contamination.
- Bakery:Fillings and fruit bases require higher brix concentrates to manage moisture migration in laminated dough systems.
- Confectionery:Jellies, jams, and fruit centers utilize low-water-activity preparations compatible with extended ambient shelf life.
Beverage applications anchor volume absorption. Dairy is climbing the fastest as traceability premiums expand addressable pricing.
Packaging Type:
Customer type and channel destination determine barrier properties, sterilization compatibility, and unit economics.
- Tetra Pack:Aseptic carton systems enable ambient distribution of liquid concentrates to foodservice and industrial buyers. Indian processors leverage this format for export compliance with EU food contact material standards.
- Pouch:Flexible laminate structures reduce material cost for retail puree and single-serve frozen portions. Online retail channels in North American metro markets favor this lightweight format for last-mile delivery efficiency.
- Glass Jar:Premium retail positioning for organic and specialty pulp with visual clarity requirements.
- Plastic Container:Frozen pulp standard with resealability for foodservice portion control.
Tetra Pack dominates industrial procurement. Pouch formats are expanding most quickly in direct-to-consumer channels.
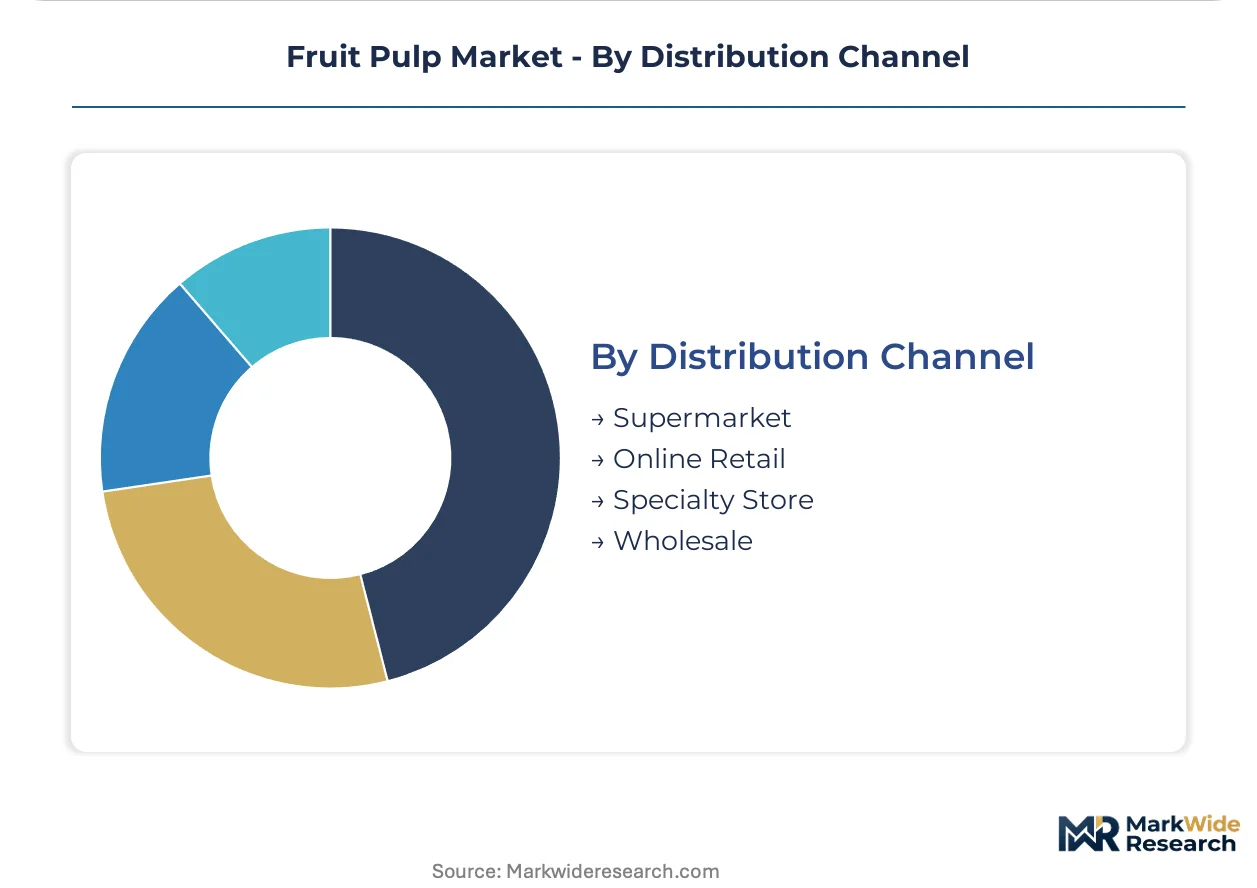
Distribution Channel:
Volume scale and margin structure separate bulk wholesale from high-touch specialty retail.
- Wholesale:Tanker and drum shipments of aseptic concentrate to beverage and dairy processors achieve maximum freight efficiency. Maharashtra and Gujarat processing clusters in India serve this channel through integrated port access.
- Supermarket:Branded retail pulp in jar and pouch formats targets home baking and smoothie preparation. Clean-label certification requirements from FSSAI and FDA juice HACCP rules shape supplier qualification.
- Specialty Store:Organic and single-origin SKUs with full provenance documentation command shelf price premiums in European and North American urban markets.
- Online Retail:Frozen pulp subscription and direct shipment models emerging in cold-chain-mature metro corridors.
Wholesale channels absorb production scale. Online retail is gaining share fastest as last-mile frozen logistics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing capacity clusters in Maharashtra and Gujarat anchor supply-side concentration for export-oriented aseptic pulp. Demand fragmentation across beverage, dairy, and smoothie channels pulls procurement toward regional cold-chain hubs.
India
Domestic dairy processors and juice formulators drive concentrated pulp absorption for clean-label product lines. The FSSAI mandates quantitative ingredient declarations that simplify compliance through single-origin sourcing. Maharashtra and Gujarat processing corridors expand aseptic capacity under PLI scheme subsidies, fragmenting regional supply concentration.
United States
Smoothie chains and organic dairy segments accelerate frozen pulp procurement for extended-shelf-stability formulations. FDA juice HACCP enforcement shapes safety benchmarks for import qualification. California and Florida distribution hubs deploy IoT-enabled cold-chain monitoring to track °Brix stability across multi-modal shipments.
Germany
Beverage manufacturers prioritize concentrated preparations for freight efficiency in large-scale nectar production. The EU F-Gas Regulation forces cold-chain operators to retrofit transport refrigeration with lower-GWP alternatives, compressing frozen logistics economics. Hamburg and Rotterdam corridor access supports integrated port-to-processor supply scheduling.
Brazil
Tropical fruit processors standardize hot-break enzymatic systems for viscosity-controlled mango and guava concentrates. ANVISA alignment with international food contact standards shapes export-oriented safety protocols. São Paulo state clusters concentrate mechanical reduction capacity for 28-32°Brix industrial procurement.
Thailand
Pineapple and tropical varietal processors serve ASEAN beverage manufacturers with aseptic puree formats. National food safety regulators enforce microbial load standards compatible with EU and US import requirements. Bangkok and Chonburi industrial zones anchor blast-freezing infrastructure for aromatic compound preservation.
Fruit Pulp Market Key Industry Players
Vertically integrated processors and specialized extraction technology providers split the market between scale-driven commodity supply and premium concentrated preparations. The vendor base organizes around three archetypes: European technology-led ingredient houses, South Asian integrated sourcing networks, and North American certified-organic specialists. Dominant competitive moves include aseptic line capacity expansion and cold-chain infrastructure partnerships.
Among European technology-led houses, Doehhler Group exemplifies premium positioning through advanced extraction systems. Keventer Group anchors South Asian supply integration through captive mango and guava sourcing networks. SunOpta Inc. occupies the North American organic segment with non-GMO verification credentials.
| Leading Market Players |
|---|
| Doehler Group |
| Keventer Group |
| PepsiCo Inc. |
| SunOpta Inc. |
| Iprona The Fruit Company |
| Conagra Brands Inc. |
| SVZ International B.V. |
| Allanasons Private Limited |
| AGRANA Beteiligungs-AG |
| Others |
Cost & Logistics Intelligence
Overcapacity in Maharashtra and Gujarat aseptic processing corridors compresses margin recovery for commodity concentrate suppliers while forcing premium-tier processors toward single-origin certification investments. This utilization imbalance simultaneously erodes pricing power at the bulk industrial tier and reinforces premium capture for traceable pulp formats.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across frozen pulp logistics, retrofitting costs for lower-GWP refrigerants stratifying supplier economics. Three-tier pricing structure across premium, standard, and economy levels separates single-origin organic puree from multi-origin concentrates and commodity blended preparations. Cost compression in standard-tier concentrates is intensifying because Indian PLI-subsidized capacity additions accelerate supply expansion. Beverage manufacturers in Brazil and India exhibit highest price sensitivity, while European organic dairy processors absorb premium differentials for full farm-to-facility traceability.
Supply Chain Analysis
Maharashtra and Gujarat processing clusters hold dominant aseptic capacity, with Thai pineapple processors and Brazilian mango specialists anchoring tropical varietal supply. Fresh fruit procurement draws from seasonal mango harvests in Maharashtra, guava orchards in Uttar Pradesh, and pineapple plantations in Chonburi province. Single-source vulnerability concentrates in EU-bound frozen pulp shipments dependent on retrofitted cold-chain fleets. Distribution runs through integrated port-to-processor scheduling at Mumbai, Hamburg, and São Paulo corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic flavor systems and artificial colorants pose persistent substitution threats that clean-label pulp suppliers must outmaneuver through traceability premiums and formulation performance.
For Market Incumbents: Pre-empt margin erosion in commodity concentrates by securing captive mango and guava sourcing networks before PLI-subsidized entrants fragment procurement access. Invest in BIS aseptic packing certification to maintain tiered market access barriers against unorganized suppliers. Synthetic flavor substitution in mass-market beverages remains the primary threat; defend through clean-label formulation partnerships with beverage formulators. For New Entrants and Emerging Players: North American certified organic pulp supply gaps offer white-space entry with non-GMO verification as the qualification threshold. Target smoothie chain direct procurement channels requiring frozen pulp with extended shelf stability specifications. Lead with single-origin storytelling and IoT-enabled cold-chain transparency as the go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aseptic line investments as EU F-Gas compliance and BIS certification timelines compress working capital cycles. Five-to-ten year viability favors processors with integrated sourcing networks and multi-regulatory export qualifications. Acquisition target archetype: mid-tier Indian processors with PLI-aligned capacity expansion and dormant EU export certifications. Monitor FSSAI quantitative ingredient declaration enforcement intensity as inflection indicator for single-origin premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Processing Capacity Expansion | PLI scheme subsidies in Maharashtra and Gujarat accelerate organized supplier fragmentation. |
| Backward Integration into Orchard Networks | Keventer Group and Doehler Group secure captive mango and guava sourcing for traceability premiums. |
| Cold-Chain Infrastructure Partnership | F-Gas Regulation retrofit requirements force fleet upgrades for EU-bound frozen pulp reliability. |
| Organic Certification Investment | SunOpta Inc. leverages non-GMO verification to capture North American clean-label demand gaps. |
| Direct-to-Smoothie-Chain Distribution | Frozen pulp subscription models bypass wholesale tier compression in cold-chain-mature metro corridors. |
Research Approach
The analysis maps concentrated pulp, frozen pulp, puree, and dried pulp sub-sectors, each validated through procurement managers at beverage formulators, dairy processors, and smoothie chain operators. Primary interviews with cold-chain logistics directors and aseptic packaging engineers combined with secondary validation from FSSAI enforcement circulars, EU F-Gas implementation schedules, FDA juice HACCP guidance documents, and Indian PLI scheme disbursement records. Bottom-up capacity utilization assessments and top-down demand absorption models triangulate volume estimates.
Assumptions held fixed include regulatory enforcement timelines for F-Gas phase-down and FSSAI quantitative declaration mandates, while fresh fruit yield volatility and cold-chain retrofit adoption rates were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type viscosity specifications, end-use application requirements, packaging sterilization protocols, and distribution channel infrastructure availability. CAGRs derive from installed capacity expansion schedules cross-referenced against per-capita beverage consumption elasticity estimates and smoothie chain outlet growth trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by PLI-subsidized domestic processors or synthetic flavor formulators would shift outcomes beyond projected ranges. Quarterly review of FSSAI enforcement intensity, EU F-Gas retrofit completion rates, and organic certification backlog durations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Citrus Pulp Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Venezuela Fruits and Vegetable Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Acai Berry Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Brazil Fruits and Vegetables Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Europe Dried Mushroom Market
Fruits and Vegetables
Date Fruit Market
Fruits and Vegetables
Organic Bananas Market
Fruits and Vegetables
Turkish Figs Market