
 Global Pickle Market | 2026-2036
Global Pickle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pickle Market Outlook
Premium artisan-grade specification tiers is collapsing the gap between commodity bulk pickles and small-batch fermented products. The Kraft Heinz Company leverages its refrigerated distribution network to sustain shelf-stable dominance in North American retail. Mt. Olive Pickle Company anchors regional brand loyalty through heritage recipes and localized flavor profiles. ADF Foods Ltd specializes in ethnic Indian pickle exports, navigating complex phytosanitary requirements across destination markets.
Pickles are vegetables or fruits preserved through brine fermentation or vinegar acidification, typically achieving pH below 4.6 for shelf stability and food safety. The primary commercial purpose spans condiment applications, ingredient supply to food manufacturers, and direct retail consumption across temperature-stable and refrigerated formats. Dill pickles and gherkins occupy the largest volume share in mature Western markets where per-capita consumption remains high. Online retailers represent the fastest-expanding sales channel as direct-to-consumer fermentation brands bypass traditional grocery slotting fees. Glass jar packaging retains premium positioning despite higher logistics costs, while pouch formats gain traction in foodservice bulk procurement.
FDA acidified food regulations govern manufacturing standards in the United States, mandating scheduled process filings for all shelf-stable pickle products. EFSA and national EU regulators enforce strict additive labeling under the EU Green Deal's sustainable food framework, pushing manufacturers toward natural fermentation preservatives. India's FSSAI codifies regional pickle standards that both protect domestic heritage production and create export certification pathways. Stakeholders must monitor evolving sodium-reduction mandates and carbon-labeling requirements that will reshape formulation priorities and geographic sourcing decisions.
Market Dynamics
Fermentation-process standardization and clean-label acidification protocols are compressing batch-to-batch variability, forcing legacy manufacturers to retrofit production lines while craft entrants scale through co-packing networks.
Growth Catalysts
- EU Green Deal additive restrictions:EFSA enforcement of natural preservation mandates is accelerating vinegar-to-lacto-fermentation conversion across shelf-stable product lines.
- Foodservice cocktail applications:Bars in the United States and Germany are incorporating brine into craft cocktails, creating incremental volume for artisan pickle producers.
- India's FSSAI export certification:Codified regional standards are opening phytosanitary pathways for mango and lime pickle varieties into Middle Eastern retail channels.
Market Restraints
- Cucumber input volatility:Weather-driven crop yield fluctuations in Michigan and Karnataka compress margin predictability for brined cucumber processors.
- Glass jar logistics costs:Freight weight premiums on glass packaging constrain price competitiveness against pouch-format competitors in bulk foodservice procurement.
- FDA acidified food filing burdens:Scheduled process documentation requirements create compliance friction for small-batch fermentation startups entering interstate commerce.
Strategic Opportunities
- Vietnam retail underpenetration:Modern trade expansion in Ho Chi Minh City and Hanoi creates first-mover positioning for refrigerated pickle brands.
- Carbon-labeling differentiation:EU Green Deal carbon accounting frameworks reward low-fermentation-energy producers with shelf-placement advantages.
- Direct-to-consumer subscription models:Online channels bypass grocery slotting fees, enabling fermentation brands to capture full margin on recurring shipments.
Industry Challenges
- Microbiological quality control talent:Shortage of fermentation scientists capable of managing mixed-culture consistency at commercial scale.
- Legacy ERP integration:Batch-tracking software for pH monitoring and lot genealogy requires capital expenditure incompatible with artisan producer cash flows.
- Phytosanitary certification timelines:Multi-month export approval processes delay revenue recognition for India-based specialty pickle exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pickle Market |
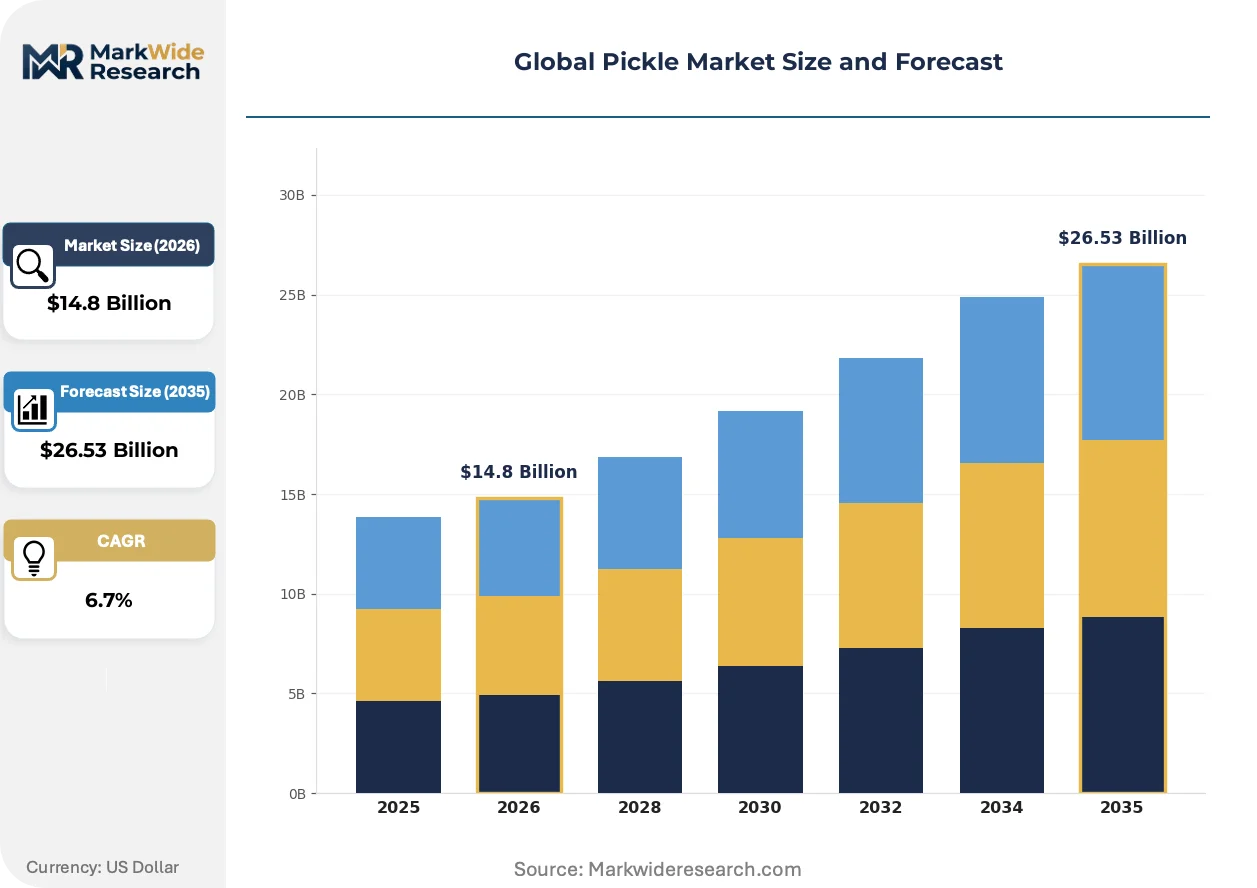
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gherkins, Dill Pickles, Sweet Pickles, Bread & Butter Pickles Packaging Type: Glass Jars, Plastic Containers, Pouches, Cans Sales Channel: Supermarkets, Online Retailers, Specialty Stores, Convenience Stores Form: Slices, Whole, Chunks, Relishes |
| Companies Covered | The Kraft Heinz Company, Conagra Brands Inc, Mt. Olive Pickle Company, ADF Foods Ltd, Del Monte Foods, Nilon’s Enterprises Pvt. Ltd., Mothers Recipe, Orkla ASA, Reitzel S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pickle Market Strategic Shifts
Clean-label preservation and packaging format experimentation are redrawing competitive boundaries between refrigerated premium tiers and shelf-stable mass-market positioning.
Pulse-electric field pasteurization is miniaturizing thermal processing footprints for small-batch producers. Regional craft brands in Oregon and Bavaria are adopting these systems to achieve FDA-compliant shelf stability without flavor degradation from heat. The technology is compressing capital barriers between artisan and industrial scale, enabling fermentation specialists to retain equity while expanding distribution.
EFSA's evolving stance on benzoate and sorbate preservatives under the EU Green Deal is forcing reformulation toward cultured vinegar and celery juice concentrates. Manufacturers serving German and French retail face reformulation costs and shelf-life compression. The segment most affected is long-cut dill varieties, where processors are accelerating natural fermentation timelines to maintain 18-month dating.
Buyer concentration among meal-kit aggregators is consolidating procurement volume previously fragmented across independent specialty retailers. HelloFresh and Blue Apron specifications now drive brine salinity and crunch retention standards for supplier qualification. This pattern is most visible in California and New York, where direct-to-consumer fermentation brands are redesigning packaging formats to survive last-mile logistics.
Global Pickle Market Segmentation
Pickle manufacturers navigate divergent margin structures across product formats and distribution channels. Each segmentation dimension carries distinct substitution pressures from adjacent condiment categories and alternative preservation technologies.
Product Type:
Gherkins face intensifying substitution from cocktail onions and olives in European foodservice, while sweet pickle variants confront ketchup and chutney encroachment in retail condiment aisles.
- Gherkins:Small, firm cucumbers preserved in brine or vinegar, typically harvested at 2-4 centimeters diameter. German and French foodservice operators specify these for charcuterie and appetizer applications, though olive bars in US grocery delis are capturing parallel occasion spending.
- Dill Pickles:Fermented or vinegar-preserved cucumbers seasoned with dill weed and garlic. North American sandwich chains and quick-service restaurants specify these as standard accompaniments, with refrigerated fresh-pack variants displacing shelf-stable alternatives in premium positioning.
- Sweet Pickles:Cucumber slices or chips cured in sugar-vinegar brine. These retain loyalty in Midwest US households and Southern barbecue traditions, though mango chutney imports are eroding share in British Commonwealth markets.
- Bread & Butter Pickles:Sweet-tangy cross-cut chips popular in US regional cooking. These occupy niche placement in sandwich builds and potato salad formulations, constrained by limited export recognition outside North American diaspora communities.
Dill pickles anchor the volume base while gherkins gain share at the steepest rate through European cocktail culture expansion.
Packaging Type:
Cost-to-weight ratios and breakage risk create divergent channel economics, with foodservice bulk procurement favoring lighter formats and retail premiumization sustaining heavier containers.
- Glass Jars:Transparent vessels enabling visual quality assessment and heritage brand signaling. German and US specialty retailers mandate these for organic and fermented product lines, though freight density penalties constrain e-commerce viability.
- Plastic Containers:Polyethylene terephthalate or polypropylene vessels reducing shipping weight and shatter risk. These dominate US mass-market retail and school foodservice contracts, facing regulatory pressure from EU single-use plastic directives.
- Pouches:Flexible laminated films enabling hot-fill or retort processing. Australian and UK foodservice distributors specify these for back-of-house dispensing, with portion-control formats gaining traction in airline catering procurement.
- Cans:Metal containers for retort-sterilized sliced and relish products. These retain viability in Indian institutional feeding and US military supply chains, though consumer perception lags behind jarred alternatives.
Glass jars retain the premium positioning while pouches expand most quickly through foodservice channel conversion.
Sales Channel:
Customer acquisition economics and slotting fee structures fragment go-to-market strategies, with direct channels offering margin recovery but demanding logistics investment.
- Supermarkets:Conventional and hypermarket formats controlling majority retail volume. These extract listing fees and promotional allowances that compress net margins for fermentation startups entering US and UK grocery retail.
- Online Retailers:E-commerce platforms and direct-to-consumer subscription services. Indian urban consumers and US coastal metro buyers drive growth here, bypassing traditional distribution markups.
- Specialty Stores:Gourmet food retailers and ethnic grocers curating artisan and import selections. These command higher retail prices for small-batch Indian mango pickles and Eastern European fermented varieties.
- Convenience Stores:Small-format urban and highway locations prioritizing grab-and-go accessibility. Single-serve pouch placement in Japanese konbini and US c-store chains targets impulse and travel occasion purchasing.
Supermarkets anchor the volume base while online retailers gain share at the steepest rate through subscription model adoption.
Form:
Processing intensity and yield recovery rates determine cost structures, with whole formats preserving input value and processed forms enabling byproduct utilization.
- Slices:Cross-cut chips for sandwich stacking and burger applications. US quick-service restaurant specifications drive volume here, with thickness and diameter tolerances tightly controlled.
- Whole:Intact cucumbers for spearing and charcuterie presentation. These command highest per-unit prices in German, Polish, and Russian retail, where size grading and crunch retention determine quality tiers.
- Chunks:Irregular pieces and end cuts for salad and relish manufacturing. Food manufacturers in UK and Netherlands specify these for ingredient supply, absorbing processing trim that would otherwise downgrade to waste.
- Relishes:Finely chopped vegetable blends with sweet or savory seasoning profiles. These compete with sauerkraut and chow-chow in US hot dog and sausage applications, with regional配方 variations limiting national brand consolidation.
Whole pickles anchor the volume base while relishes gain share at the steepest rate through condiment diversification in food manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are reshaping pickle trade flows, with India emerging as a net specialty exporter while the United States and Germany balance domestic production against premium import demand from artisan producers.
United States
Foodservice cocktail applications and refrigerated fresh-pack preferences drive demand in coastal metro markets. FDA acidified food regulations mandate scheduled process filings for interstate shelf-stable distribution. Michigan's cucumber-growing regions supply raw material to Midwest processing clusters, though weather volatility compresses margin predictability for brined processors.
Germany
Charcuterie culture and cocktail bar expansion sustain gherkin consumption in Berlin and Munich foodservice channels. EFSA enforcement of EU Green Deal additive restrictions accelerates vinegar-to-lacto-fermentation conversion across retail product lines. Bavarian craft producers adopt pulse-electric field pasteurization to achieve shelf stability without thermal degradation.
India
Regional mango and lime pickle varieties command premium positioning in Middle Eastern export channels. FSSAI codification of heritage standards creates phytosanitary certification pathways for specialty exporters. Gujarat and Andhra Pradesh processing clusters navigate multi-month approval timelines to access UAE and Saudi retail distribution.
United Kingdom
Sweet pickle loyalty in Midlands and Northern households confronts mango chutney import competition from Commonwealth trade routes. EFSA labeling requirements under EU Green Deal frameworks push reformulation toward natural fermentation preservatives. London specialty retailers curate small-batch Indian and Eastern European fermented varieties for premium positioning.
Vietnam
Modern trade expansion in Ho Chi Minh City and Hanoi creates first-mover positioning for refrigerated pickle brands entering underpenetrated retail. National food safety standards align with ASEAN harmonization protocols for cross-border distribution. Da Nang and Can Tho processing zones supply domestic foodservice while testing export-ready formulations for regional markets.
Global Pickle Market Competitive Environment
Listed leaders compete with private specialists across fermentation-process capabilities and refrigerated distribution infrastructure. The vendor base stratifies into three tiers: multinational packaged-food conglomerates with shelf-stable dominance, regional heritage brands with localized flavor loyalty, and direct-to-consumer fermentation startups scaling through subscription channels. Strategic moves concentrate on co-packing network expansion and clean-label reformulation to meet EU additive restrictions.
Within the multinational tier, The Kraft Heinz Company and Conagra Brands Inc exemplify scale-driven shelf-stable positioning across North American retail. Mt. Olive Pickle Company anchors regional heritage loyalty through North Carolina-based production and localized recipe portfolios. ADF Foods Ltd occupies the ethnic export-specialist archetype, navigating FSSAI certification pathways for Indian pickle varieties into Middle Eastern channels.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Conagra Brands Inc |
| Mt. Olive Pickle Company |
| ADF Foods Ltd |
| Del Monte Foods |
| Nilon's Enterprises Pvt. Ltd. |
| Mothers Recipe |
| Orkla ASA |
| Reitzel S.A. |
| Others |
Value Chain & Pricing Dynamics
FDA acidified food regulations gate both supply qualification and price differentiation simultaneously, mandating scheduled process filings that small-batch fermentation startups cannot afford while enabling incumbent shelf-stable producers to command premium positioning through compliance infrastructure. Glass jar freight density penalties and cucumber input volatility from Michigan and Karnataka compress margin predictability across all tiers, forcing manufacturers to arbitrage between heritage packaging aesthetics and pouch-format foodservice economics.
Pricing Analysis
Industrial OEM buyers anchor pricing stratification across premium artisan, standard refrigerated, and economy shelf-stable tiers. Price differentiation hinges on fermentation certification tier and glass versus pouch packaging format, with carbon-labeling premiums under EU Green Deal frameworks widening spreads between natural lacto-fermented and vinegar-acidified alternatives. Pricing pressure stems from meal-kit aggregator procurement consolidation, with HelloFresh and Blue Apron specifications standardizing brine salinity and crunch retention thresholds. Contract foodservice operators exhibit highest price sensitivity, while specialty retailers in London and New York tolerate freight premiums for heritage jarred formats.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and Red Sea routing disruptions inflate inbound logistics costs for Indian mango pickle exporters targeting Middle Eastern retail. Supply concentrates in India, the United States, and Germany, with Gujarat and Andhra Pradesh processing clusters, Michigan cucumber-growing regions, and Bavarian craft producers anchoring respective regional networks. Raw material dependencies rest on cucumber cultivar consistency, sea salt sourcing, and dill weed supply from specific terroirs. Single-source vulnerability concentrates in Michigan's weather-exposed crop yields. Distribution runs through refrigerated trucking networks for fresh-pack variants and ambient containerized freight for shelf-stable retort formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Olive bars and cocktail onion substitution in European foodservice, alongside mango chutney encroachment in British Commonwealth retail, compress incumbent pickle positioning. Incumbents must navigate these adjacent condiment threats while defending fermentation-process differentiation.
For Market Incumbents: Consolidate co-packing network control in Vietnam and India to capture modern trade expansion while retrofitting legacy production lines for pulse-electric field pasteurization compliance. Vertical integration into cucumber cultivar development in Karnataka and Michigan reduces weather-driven input volatility. EFSA additive restriction timelines threaten shelf-life dating on long-cut dill varieties; accelerate natural fermentation timeline investments to maintain 18-month retail positioning against cultured vinegar substitutes. For New Entrants and Emerging Players: FSSAI export certification fast-tracks open phytosanitary pathways for regional Indian pickle varieties into UAE and Saudi retail, bypassing multi-month approval bottlenecks that constrain established exporters. Target Vietnam's underpenetrated refrigerated pickle segment in Ho Chi Minh City and Hanoi hypermarkets, where first-mover positioning precedes multinational refrigerated distribution buildout. Direct-to-consumer subscription models bypass grocery slotting fees and capture full margin on recurring shipments to US coastal metro buyers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fermentation startups scaling through subscription channels before refrigerated distribution infrastructure requirements force capital-intensive expansion. Long-term viability across the analysis window hinges on clean-label preservation technology ownership and carbon-accounting certification capabilities. Acquisition targets should demonstrate pulse-electric field pasteurization deployment or established FSSAI export pathways. Watch EU Green Deal carbon-labeling implementation velocity as inflection indicator for shelf-placement advantage shifts toward low-fermentation-energy producers.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EFSA benzoate restrictions under EU Green Deal force vinegar-to-lacto-fermentation conversion across German and French retail lines. |
| Pulse-Electric Field Pasteurization Deployment | Oregon and Bavarian craft producers achieve FDA shelf stability without thermal flavor degradation, compressing artisan-industrial scale barriers. |
| Direct-to-Consumer Channel Launch | Subscription models bypass US grocery slotting fees and enable fermentation brands to capture full margin on recurring shipments. |
| Co-Packing Network Expansion | Artisan producers scale distribution without capital-intensive production assets through FDA-compliant partner facilities. |
| Carbon-Labeling Certification Program | EU Green Deal carbon accounting frameworks reward low-fermentation-energy producers with retail shelf-placement advantages. |
Study Parameters
Desk research of FSSAI codification documents, FDA acidified food regulation filings, and EU Green Deal additive restriction frameworks preceded structured interviews with fermentation scientists, foodservice procurement directors at US sandwich chains, specialty retail category buyers in London and New York, and logistics planners at Indian export processing clusters. Secondary validation drew from customs trade data on pickle export flows, Nielsen retail audit data on condiment aisle placement, and SEC filings from multinational packaged-food conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across product type, packaging format, and sales channel dimensions.
Variance decomposition separated volume growth drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type (gherkins, dill pickles, sweet pickles, bread and butter variants), packaging format (glass jars, plastic containers, pouches, cans), sales channel (supermarkets, online retailers, specialty stores, convenience stores), and regional regulatory cluster (FDA-governed, EFSA-enforced, FSSAI-codified). CAGRs derived from trend extrapolation of per-capita consumption patterns, channel shift elasticity, and premium tier penetration curves. Forecast inputs incorporated cucumber crop yield volatility indices and carbon-labeling adoption velocity assumptions.
Underlying assumptions cover sustained EU Green Deal enforcement trajectories, stable phytosanitary certification timelines for Indian exporters, and continued meal-kit aggregator procurement consolidation, with deviation risk concentrated in weather-driven Michigan and Karnataka crop failures, Red Sea logistics disruption persistence, and EFSA preservative stance hardening beyond current celery juice concentrate allowances. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
Fresh Pumpkin Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
North Africa Table Olives Market
Fruits and Vegetables
Dry Beans Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Olive Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Banana Puree Market
Fruits and Vegetables
Asia-Pacific Sweet Potatoes Market
Fruits and Vegetables
Fermented Cucumber Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market