
 Uruguay Fruits and Vegetables Market | 2026-2036
Uruguay Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Uruguay Fruits and Vegetables Market Analytics
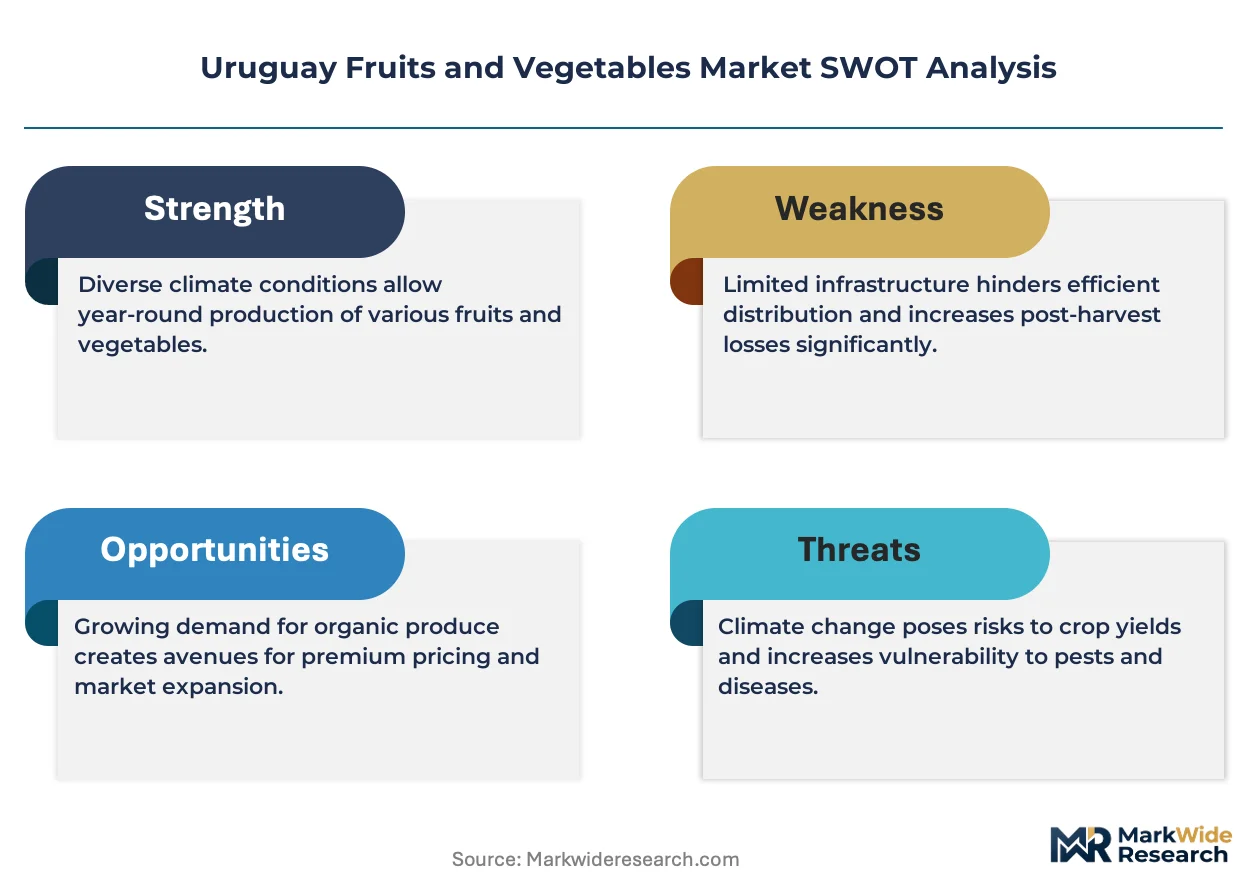
Plastic packaging is rebalancing toward biodegradable alternatives across Uruguay's produce supply chain, cutting unit costs for premium-grade exports. BROCOS S.A. leverages cold-chain infrastructure to dominate apple distribution in the Montevideo metro corridor. BELEM S.A. anchors tomato supply through controlled-environment agriculture near Canelones. SILCOM S.A. specializes in citrus logistics, extending reach into Brazilian border markets.
Uruguay fruits and vegetables encompass fresh and minimally processed horticultural products grown across temperate and subtropical climatic zones, with harvest cycles spanning September through April for temperate varieties and year-round production for greenhouse tomatoes. The sector serves domestic consumption, food service procurement, industrial processing, and cross-border trade, with phytosanitary certification determining market access. Tomatoes and oranges capture the dominant volume share through retail and wholesale channels, while exporter-facing segments command premium pricing due to MERCOSUR compliance overhead. Online distribution remains nascent but grows fastest among urban households in Montevideo, though farmers' markets sustain margin pools through direct producer pricing.
Uruguay's national food safety regulator and the Ministry of Livestock, Agriculture and Fisheries enforce phytosanitary protocols that shape export eligibility, particularly for Brazilian and Argentine buyers. MERCOSUR technical standards further constrain varietal approval and pesticide residue thresholds, filtering which producers access formal trade channels. Stakeholders must monitor evolving biodegradable packaging mandates and water-use regulations in the Canelones growing belt to preserve competitive positioning.
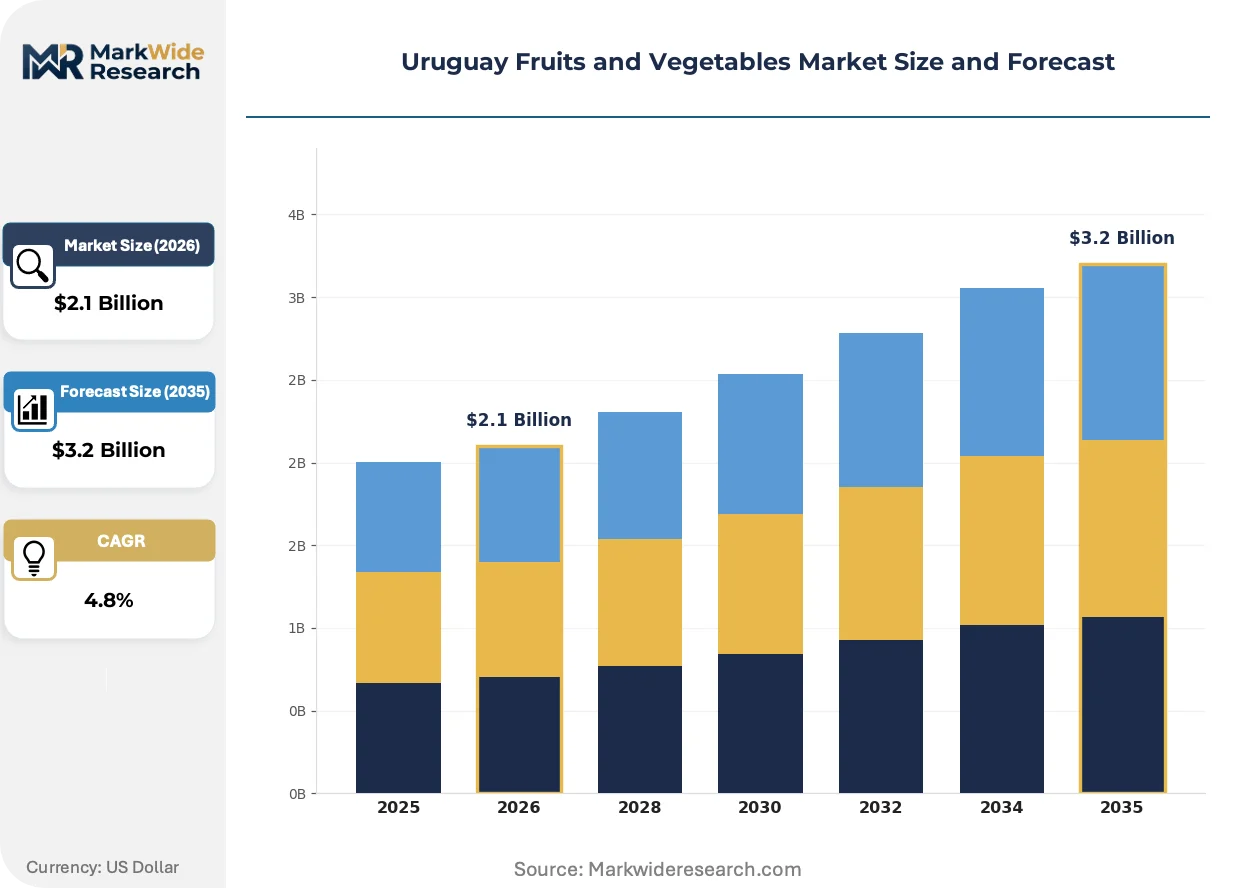
Market Dynamics
Biodegradable packaging mandates from Uruguay's national food safety regulator are compressing margins for conventional plastic suppliers while redirecting procurement budgets toward certified compostable alternatives across the Colonia and Canelones corridors.
Growth Catalysts
- MERCOSUR phytosanitary alignment:Harmonized certification standards slash border inspection delays for Uruguayan exporters shipping to Brazilian and Argentine food processors.
- Cold-chain infrastructure expansion:Refrigerated logistics networks connecting Montevideo port to interior growing regions reduce post-harvest loss rates for temperature-sensitive citrus varieties.
- Tourism-driven food service procurement:Restaurants in Punta del Este and Montevideo's Ciudad Vieja district are doubling fresh produce orders as international visitor arrivals rebound.
Market Restraints
- Input cost volatility:Fertilizer and agricultural chemical prices fluctuate with global commodity markets, squeezing margins for Canelones greenhouse operators.
- Supply concentration risk:Three logistics providers control overland refrigerated transport from interior growing belts to Montevideo export terminals.
- Water access limitations:Irrigation quotas in the Santa Lucía river basin restrict expansion of controlled-environment tomato production during drought cycles.
Strategic Opportunities
- Underpenetrated Brazilian border markets:Rivera and Artigas departments offer direct overland access to Rio Grande do Sul food retailers seeking MERCOSUR-certified citrus.
- Online grocery channel emergence:Montevideo urban households under age 35 are adopting smartphone-based produce ordering faster than national retail averages.
- Biodegradable packaging regulatory tailwind:Pending municipal waste ordinances in Montevideo and Maldonado will mandate compostable containers for all retail produce by 2027.
Industry Challenges
- Phytosanitary certification timeline compression:Exporter-facing growers must complete MERCOSUR residue testing and documentation within shrinking pre-shipment windows.
- Specialized cold-chain technician scarcity:Refrigeration mechanics with horticultural handling credentials command premium wages in the Montevideo metro corridor.
- Legacy market infrastructure retrofit costs:Traditional wholesale terminals in Montevideo's Mercado Modelo require expensive temperature-controlled loading dock upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uruguay Fruits and Vegetables Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tomatoes, Apples, Carrots, Oranges Distribution Channel: Retail, Wholesale, Online, Farmers' Markets End User: Households, Restaurants, Food Processors, Exporters Packaging Type: Bags, Boxes, Crates, Bulk |
| Companies Covered | BROCOS S.A., BELEM S.A., SILCOM S.A., Domingo Moizo, Envista Farms, Guarino, Kaltur Importaciones, UPEFRUY, Uruguay Fruits, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uruguay Fruits and Vegetables Market Evolving Landscape
Sensor-enabled logistics and shifting buyer preferences are restructuring how Uruguayan produce reaches end consumers. Three developments dominate the current transformation window.
Blockchain-based traceability platforms are decentralizing supply chain verification. Montevideo-based export consortiums are piloting distributed ledger systems that let Brazilian supermarkets query individual batch pesticide records in real time. This transparency infrastructure is decentralizing quality assurance away from centralized laboratory testing toward farm-level data capture.
Uruguay's national food safety regulator is tightening biodegradable packaging mandates ahead of municipal waste reforms. Industrial composting facilities in Canelones and San José departments lack capacity to process projected volumes of certified packaging waste. Exporter-facing processors are responding by consolidating procurement through pre-approved biodegradable suppliers with established composting partnerships.
Direct-to-restaurant procurement platforms are bypassing traditional wholesale layers. Punta del Este resort kitchens and Montevideo boutique hotels now source specialty tomatoes and leafy greens through app-based ordering systems connecting them to Canelones greenhouse operators. This channel compression is most visible in Montevideo's Pocitos and Carrasco neighborhoods where chef-operated establishments cluster.
Uruguay Fruits and Vegetables Market Segmentation
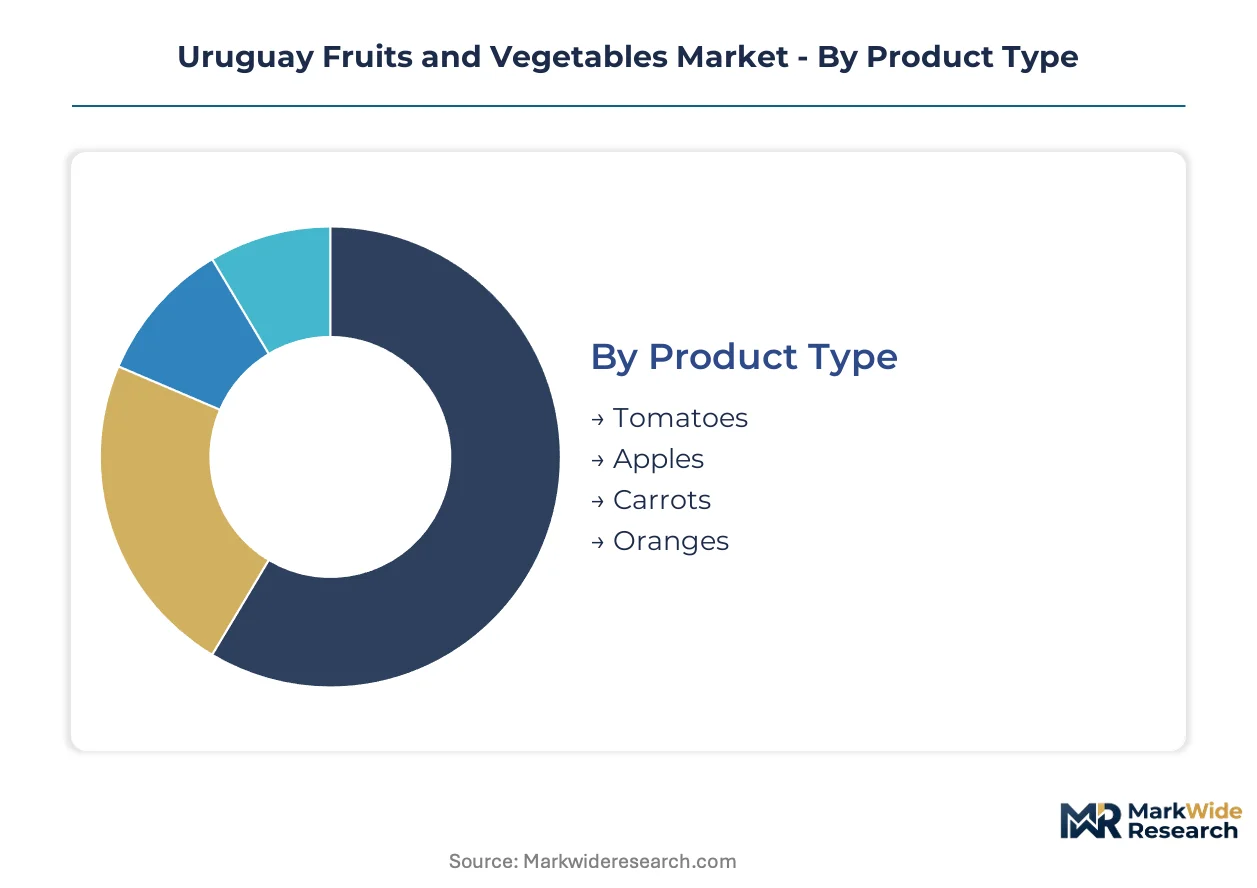
Segmentation in Uruguay's horticultural sector reveals how phytosanitary requirements, cold-chain reach, and buyer sophistication split procurement flows. Each dimension channels capital toward compliance-heavy export corridors or cost-sensitive domestic wholesale.
Product Type:
Supply concentration clusters around temperature-tolerant varieties with established MERCOSUR certification pathways, while greenhouse-intensive crops face water quota constraints.
- Tomatoes:Year-round greenhouse production in Canelones dominates volume, with controlled-environment agriculture commanding premium pricing from Montevideo restaurants. Punta del Este resort kitchens source vine-ripened specialty varieties through direct-to-chef platforms, bypassing traditional wholesale markups.
- Apples:Cold-chain infrastructure from interior orchards to Montevideo port enables quality retention for Brazilian border markets. BROCOS S.A. controls distribution through refrigerated consolidation points, locking in exporter-facing food processors.
- Carrots:Temperate harvest cycles in September through April supply domestic processing and fresh retail.
- Oranges:Citrus logistics networks extend into Rio Grande do Sul retail channels via Rivera department overland routes.
Tomatoes absorb the bulk of installed capacity; apples are expanding most quickly through cold-chain infrastructure buildout.
Distribution Channel:
Channel selection hinges on buyer technical requirements and traceability needs, with formal retail and export procurement demanding residue documentation absent from informal trade.
- Retail:Supermarket chains in Montevideo and Maldonado enforce biodegradable packaging mandates ahead of municipal ordinances. Pre-approved compostable suppliers consolidate procurement relationships as regulatory deadlines approach.
- Wholesale:Mercado Modelo in Montevideo handles volume aggregation for interior growing belts, though legacy loading docks require expensive temperature-controlled retrofits to serve citrus exporters.
- Online:Smartphone-based ordering gains traction among Montevideo households under age 35, outpacing national retail adoption rates.
- Farmers' Markets:Direct producer pricing sustains margin pools for smallholders in Ciudad Vieja and Pocitos neighborhoods.
Wholesale channels retain the greatest throughput volume; online distribution shows the steepest expansion trajectory among urban demographics.
End User:
End-user segmentation splits between price-sensitive domestic consumption and compliance-heavy export-facing segments with diverging certification timelines.
- Households:Urban Montevideo consumers drive biodegradable packaging adoption through supermarket preference shifts.
- Restaurants:Tourism rebound in Punta del Este and Ciudad Vieja doubles fresh produce orders, with chef-operated establishments sourcing through app-based platforms connecting directly to Canelones greenhouse operators.
- Food Processors:Colonia and Canelones corridor processors demand MERCOSUR-aligned phytosanitary documentation for Brazilian and Argentine buyers.
- Exporters:Shrinking pre-shipment windows for residue testing and documentation compress operational timelines for grower-exporter relationships.
Food processors absorb the bulk of certified supply; restaurants are gaining share fastest through channel compression and direct procurement platforms.
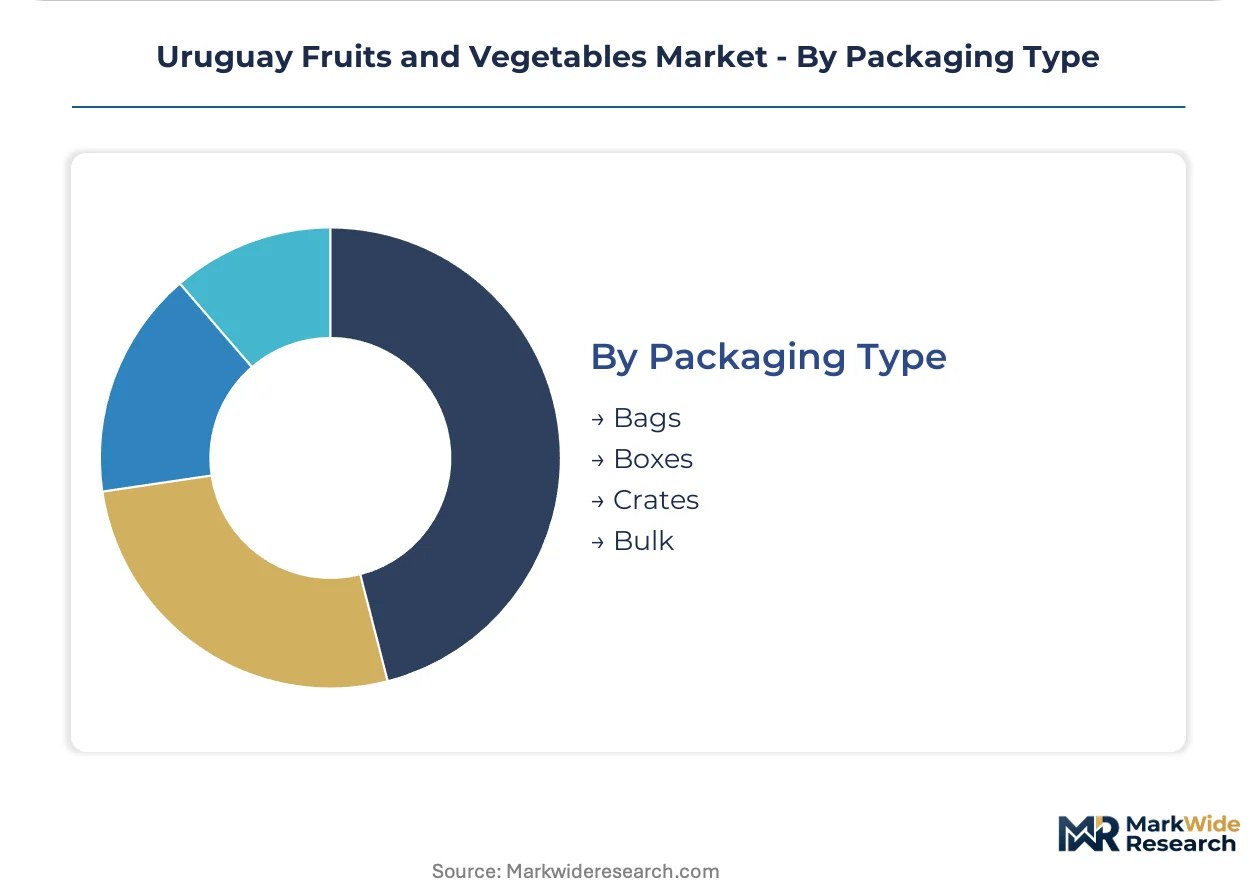
Packaging Type:
Packaging selection tracks regulatory pressure and composting infrastructure availability across Canelones and San José departments.
- Bags:Biodegradable alternatives displace conventional plastic as unit costs compress for premium-grade exports.
- Boxes:Standardized corrugated containers dominate retail supermarket flows with pre-printed traceability codes.
- Crates:Returnable plastic and wooden systems serve wholesale terminal consolidation in Mercado Modelo.
- Bulk:Unpackaged shipments concentrate in processor-facing procurement from interior growing belts.
Boxes retain the greatest installed base; bags are climbing the fastest on regulatory tailwinds and municipal waste reform deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Canelones Department free trade zone incentives concentrate greenhouse infrastructure investment and cold-chain logistics development across Uruguay's central agricultural corridor.
Montevideo Metro Corridor
Urban restaurant procurement and supermarket distribution dominate demand in Montevideo's Pocitos and Ciudad Vieja districts. The national food safety regulator enforces biodegradable packaging mandates ahead of municipal waste ordinances. Cold-chain consolidation points near Mercado Modelo handle temperature-sensitive citrus flows for Brazilian export channels.
Canelones Department
Controlled-environment agriculture clusters around greenhouse tomato production serving direct-to-chef platforms. Water-use quotas from the Santa Lucía river basin authority constrain expansion during drought cycles. BELEM S.A. anchors supply through hydroponic operations near the department's industrial parks.
Colonia Department
Exporter-facing food processors demand MERCOSUR-aligned phytosanitary documentation for Argentine buyers. The Ministry of Livestock, Agriculture and Fisheries operates residue testing facilities at the Colonia port corridor. Apple cold-chain infrastructure from interior orchards terminates at refrigerated consolidation points.
Maldonado Department
Tourism rebound in Punta del Este drives resort kitchen procurement of specialty produce varieties. Pending municipal waste ordinances will mandate compostable retail containers by 2027. Farmers' markets in coastal neighborhoods sustain direct producer pricing for smallholder margins.
Artigas and Rivera Departments
Overland routes into Rio Grande do Sul offer underpenetrated access to Brazilian food retailers seeking MERCOSUR-certified citrus. SILCOM S.A. extends logistics reach through border-adjacent distribution nodes. Phytosanitary alignment with Brazilian federal agriculture ministry standards filters eligible export volumes.
Uruguay Fruits and Vegetables Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cold-chain logistics providers commanding premium positioning in export-facing corridors while greenhouse operators capture restaurant-direct margins. The vendor base concentrates around three archetypes: integrated logistics-cum-distribution platforms, controlled-environment agricultural specialists, and cross-border trade facilitators. M&A activity targets refrigerated transport capacity, while strategic partnerships consolidate biodegradable packaging procurement ahead of regulatory deadlines.
Among Uruguayan S.A.-structured operators, BROCOS S.A., BELEM S.A., and SILCOM S.A. exemplify the three dominant competitive archetypes. BROCOS S.A. represents the integrated logistics platform model through Montevideo metro cold-chain dominance. BELEM S.A. anchors the controlled-environment specialist tier with Canelones greenhouse concentration. SILCOM S.A. occupies the cross-border facilitator position through Brazilian border market extension. These three structures collectively demonstrate how phytosanitary compliance capability and refrigerated infrastructure ownership determine competitive positioning in MERCOSUR-aligned produce trade.
| Leading Market Players |
|---|
| BROCOS S.A. |
| BELEM S.A. |
| SILCOM S.A. |
| Domingo Moizo |
| Envista Farms |
| Guarino |
| Kaltur Importaciones |
| UPEFRUY |
| Uruguay Fruits |
| Others |
Value Network & Pricing Analysis
Cold-chain infrastructure expansion across Uruguay's interior-to-port corridors is simultaneously compressing post-harvest loss rates and redistributing margin capture toward logistics-integrated distributors. This capital-intensive transition favors operators with refrigerated consolidation assets while squeezing conventional wholesale intermediaries unable to absorb retrofit costs.
Pricing Analysis
Volume-heavy wholesale channels trade at thinner spreads than direct-to-restaurant procurement, where app-based platforms connecting Canelones greenhouse operators to Punta del Este resort kitchens capture premium markups. MERCOSUR phytosanitary certification tiers separate export-facing growers from domestic-only suppliers, with residue documentation overhead pricing smaller operators out of Brazilian border markets. Cost compression in conventional plastic packaging is intensifying because biodegradable mandates redirect procurement budgets toward certified compostable alternatives. Food processors in the Colonia corridor exhibit lowest price sensitivity due to pass-through mechanisms with Argentine buyers, while Montevideo supermarket chains face margin pressure from municipal waste ordinance deadlines.
Supply Chain Analysis
MERCOSUR phytosanitary alignment functions as the primary qualification gate, filtering which Uruguayan growers access formal export channels to Brazil and Argentina. Supply concentrates in Canelones greenhouse belts for tomatoes, interior orchards for apples, and Rivera department citrus zones for cross-border flows. The sector draws from fertilizer imports subject to global commodity volatility, refrigerated transport capacity constrained to three dominant providers, and water allocations from the Santa Lucía river basin authority. Single-source vulnerability in overland refrigerated logistics from interior growing belts to Montevideo export terminals creates congestion risk during peak harvest windows. Distribution runs through Mercado Modelo wholesale terminals for domestic aggregation, direct-to-chef platforms for restaurant bypass, and SILCOM S.A.-operated border nodes for Brazilian retail penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-based traceability platforms are displacing centralized laboratory verification as the dominant supply chain technology, replacing legacy batch-testing documentation with farm-level data capture accessible to Brazilian supermarket buyers in real time.
For Market Incumbents: Acquire refrigerated transport capacity and cold-chain consolidation assets to defend against margin compression from biodegradable packaging mandates and input cost volatility. BELEM S.A.'s hydroponic integration model demonstrates how backward control over water-efficient production technology insulates against Santa Lucía basin quota restrictions. Certification investment in MERCOSUR residue testing infrastructure preserves export eligibility as pre-shipment windows shrink. For New Entrants and Emerging Players: Sensor-enabled logistics platforms offer a technology-first wedge into the fragmented wholesale layer, where legacy Mercado Modelo infrastructure lacks temperature-controlled loading dock modernization. The underpenetrated Brazilian border markets via Rivera and Artigas departments present the most accessible white-space target, with Rio Grande do Sul food retailers actively seeking MERCOSUR-certified citrus suppliers. A go-to-market angle anchored in real-time traceability data capture addresses Brazilian supermarket procurement committees demanding batch-level pesticide transparency. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated logistics platforms seeking cold-chain density and cross-border trade facilitation capabilities. Long-term viability across the analysis window hinges on water-use efficiency and composting infrastructure partnerships as regulatory deadlines approach. The signal to watch is municipal waste ordinance implementation pace in Montevideo and Maldonado, which will force packaging procurement consolidation toward pre-approved biodegradable suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Refrigerated consolidation points near Mercado Modelo reduce citrus spoilage rates for Brazilian export channels. |
| Biodegradable Packaging Procurement Consolidation | Pre-approved compostable supplier relationships secure compliance ahead of 2027 municipal waste mandates in Montevideo. |
| Direct-to-Restaurant Platform Development | App-based ordering systems bypass wholesale markups and capture margin from Punta del Este resort kitchen procurement. |
| MERCOSUR Certification Infrastructure Investment | In-house residue testing capabilities compress pre-shipment documentation timelines for Argentine and Brazilian buyers. |
| Water-Efficient Production Technology Adoption | Hydroponic and controlled-environment systems insulate Canelones greenhouse operators against Santa Lucía basin irrigation quotas. |
Research Methodology
Multi-period observation of cold-chain infrastructure buildout, biodegradable packaging procurement shifts, and MERCOSUR certification timeline compression anchored the trend analysis, supplemented by interviews with greenhouse operations managers at Canelones controlled-environment facilities, procurement leads at Montevideo supermarket chains, logistics coordinators at refrigerated transport providers, regulatory affairs officers at the national food safety regulator, and restaurant executive chefs in Punta del Este and Ciudad Vieja districts. Secondary validation drew from MERCOSUR technical standard publications, Uruguay Ministry of Livestock Agriculture and Fisheries phytosanitary bulletins, municipal waste ordinance drafts from Montevideo and Maldonado, and customs trade data for citrus and apple cross-border flows. Bottom-up grower-exporter relationship mapping and top-down sector revenue aggregation were triangulated to produce volume and value estimates.
Segment-weighting across product type, distribution channel, end user, and packaging format dimensions shaped the analytical framework, with additional modeling of phytosanitary certification tier as an industry-specific segmentation layer. CAGRs were derived from trend extrapolation of infrastructure deployment rates, regulatory deadline impacts, and tourism recovery trajectories across the projection horizon. Forecast inputs incorporated water quota allocation scenarios from the Santa Lucía river basin authority, cold-chain technician wage inflation in the Montevideo metro corridor, and Brazilian retail demand elasticity for MERCOSUR-certified citrus.
Several conditions sit outside the modeled scope, including extreme drought cycles beyond historical Santa Lucía basin variance, MERCOSUR trade agreement suspension or renegotiation, and disruptive substitution from Argentine or Brazilian domestic production. Forecasts reflect assumptions about regulatory implementation timelines, infrastructure investment continuity, and cross-border phytosanitary alignment stability. A model refresh is warranted upon material change in municipal waste ordinance enforcement pace or Brazilian federal agriculture ministry import protocol adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Apple Concentrate Market
Fruits and Vegetables
Tropical Fruit Puree Market
Fruits and Vegetables
Raisins Market
Fruits and Vegetables
Dates Market
Fruits and Vegetables
Gold Kiwifruit Market
Fruits and Vegetables
Morocco Fruits and Vegetables Market
Fruits and Vegetables
Chile Fruits and Vegetables Market
Fruits and Vegetables
Dry Beans Market
Fruits and Vegetables
Global Orange Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Asia Pacific Lime Market
Fruits and Vegetables
Lycopene Market
Fruits and Vegetables
Ackee Market