
 Global Maqui Berries Market | 2026-2036
Global Maqui Berries Market Size, Share, and Industry Trends Forecast 2026-2036
Global Maqui Berries Market Outlook
The EU Green Deal is rebalancing sourcing priorities across the superfood ingredient chain, pushing buyers toward traceable, low-carbon harvest networks. Navitas Organics leverages certified organic partnerships in southern Chile to secure freeze-dried supply. Terrasoul Superfoods anchors its procurement through direct farmer alliances that bypass conventional commodity brokers. SouthAm Freeze Dry dominates processing capacity near the source, converting fresh maqui into shelf-stable formats for export.
Maqui berries are small, dark-purple Aristotelia chilensis fruits native to Chilean and Argentinian Patagonia, containing anthocyanin concentrations that exceed most commercial berries and serve as natural colorants and antioxidant feedstocks for functional food systems. Organic maqui commands premium positioning in nutraceutical channels where clean-label certification drives purchase decisions, while freeze-dried formats retain higher bioactive integrity than powdered alternatives and capture the fastest-growing share among supplement manufacturers. The food and beverage segment leads volume absorption as beverage innovators incorporate maqui for natural purple pigmentation and polyphenol content.
EMA guidelines on novel food safety assessments govern European market entry for maqui extracts, while FDA GRAS self-affirmation pathways shape US commercialization timelines for new ingredient introductions. Chile's agricultural regulator, SAG, enforces wild harvest quotas that directly constrain raw material availability and influence seasonal pricing. Stakeholders must monitor whether Chile expands cultivation permits or tightens wild-collection limits, as this policy trajectory will determine supply elasticity against rising nutraceutical demand.
Market Dynamics
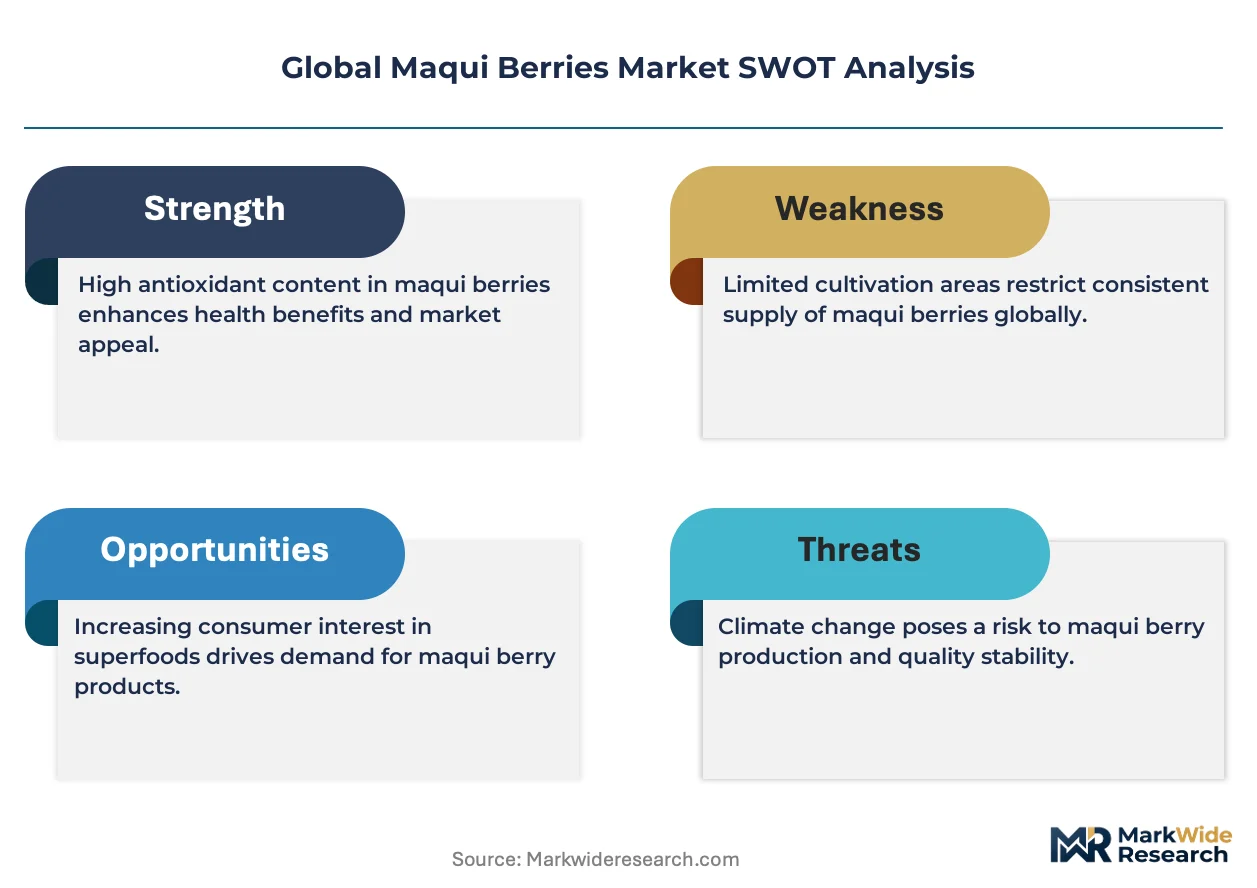
Wild harvest quotas enforced by Chile's SAG are tightening raw material availability just as nutraceutical formulators expand anthocyanin procurement, creating a structural squeeze that favors processors with captive supply arrangements and organic certification pipelines.
Growth Catalysts
- EU Novel Food approvals:EFSA safety assessments for maqui berry extracts are clearing pathways for European nutraceutical launches, accelerating ingredient adoption by supplement manufacturers seeking antioxidant positioning.
- Clean-label beverage innovation:Natural purple pigmentation demand from functional drink developers is pulling freeze-dried maqui into formulation pipelines as synthetic colorant replacement.
- Los Lagos harvest clusters:Concentrated wild collection and early cultivation development in this Chilean region is creating supply scale sufficient to anchor international processor commitments.
Market Restraints
- Input cost volatility:Wild harvest labor intensity and seasonal weather variation in Patagonia generate raw material price instability that compresses processor margins.
- Supply concentration risk:Dependence on Chile's Los Lagos region for the majority of global raw material creates geographic vulnerability to climate events and regulatory quota changes.
- Regulatory friction:EMA novel food safety assessment timelines extend European commercialization lead times by months compared to FDA GRAS self-affirmation pathways in the United States.
Strategic Opportunities
- Underpenetrated cultivation expansion:Argentina's Neuquén and Río Negro provinces offer untapped Aristotelia chilensis growing territory with potential to diversify supply beyond Chilean concentration.
- Emerging cosmetic applications:Anthocyanin-rich extracts are gaining traction in dermal care formulations targeting oxidative stress protection, opening adjacent demand channels beyond food and supplements.
- EU Green Deal procurement standards:Traceability and low-carbon harvest requirements are favoring certified organic suppliers with direct farmer alliances, creating competitive differentiation for compliant processors.
Industry Challenges
- Technical drying expertise gap:Freeze-drying capacity sufficient to preserve anthocyanin bioactivity remains concentrated among limited processors, constraining quality-grade supply expansion.
- Certification timeline compression:Organic and wild-collection certification audits for new harvest areas require multi-year validation cycles that lag behind demand acceleration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Maqui Berries Market |
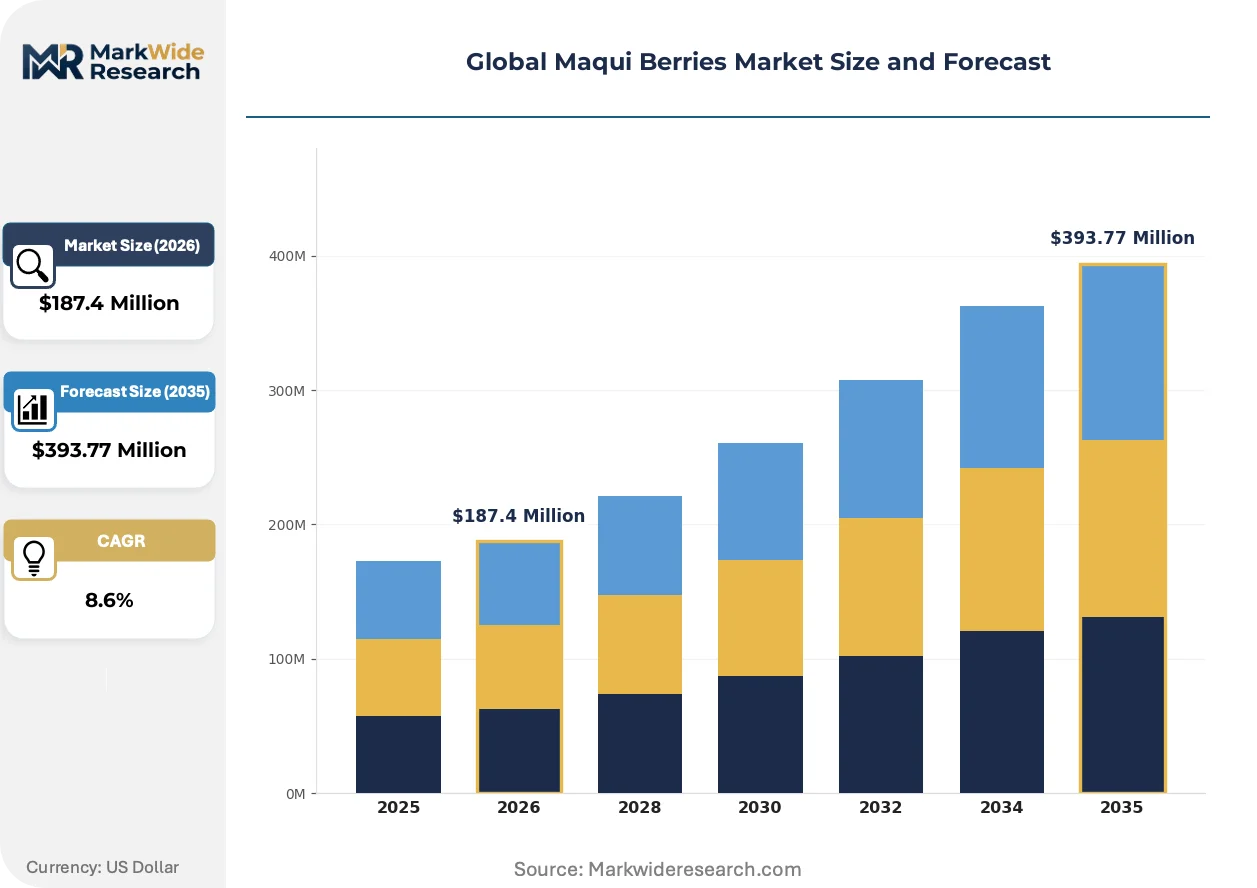
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Freeze-Dried, Powdered End User: Food & Beverage, Supplements, Cosmetics, Nutraceuticals Sales Channel: Online, Retail, Wholesale, Direct Sales Packaging Type: Bulk, Jars, Pouches, Sachets |
| Companies Covered | Navitas Organics, Terrasoul Superfoods, SouthAm Freeze Dry, Maqui New Life, HP Ingredients, Bayas del Sur, Sunfood Superfoods, NOW Foods, NP Nutra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Maqui Berries Market Strategic Shifts
Processing technology advancement and procurement model restructuring are redrawing competitive boundaries in maqui berry value capture, with bioactive preservation and supply chain transparency emerging as decisive differentiators.
Freeze-drying technology is consolidating quality-tier supply by preserving delphinidin and cyanidin glycoside concentrations that spray-drying degrades. Premium supplement manufacturers are specifying freeze-dried material in procurement contracts, compressing price premiums toward processors with installed lyophilization capacity near Chilean source regions. This technology shift is consolidating market position among South American processors with capital-intensive drying infrastructure.
REACH registration requirements for berry extract imports into the European Union are tightening contaminant and residue documentation standards. ECHA compliance obligations now extend to wild harvest pesticide screening and heavy metal testing protocols that smaller exporters cannot satisfy. Nutraceutical distributors serving EU markets are responding by consolidating supplier relationships toward integrated processors with in-house analytical laboratories.
Direct farmer alliance models are displacing conventional commodity broker networks as the preferred procurement architecture. Formulators seeking clean-label certification are bypassing spot-market purchasing in favor of multi-year supply agreements with traceable harvest cooperatives. This behavioral shift is most visible among North American organic brands that now require lot-level geographic provenance documentation as a standard procurement condition.
Global Maqui Berries Market Segmentation
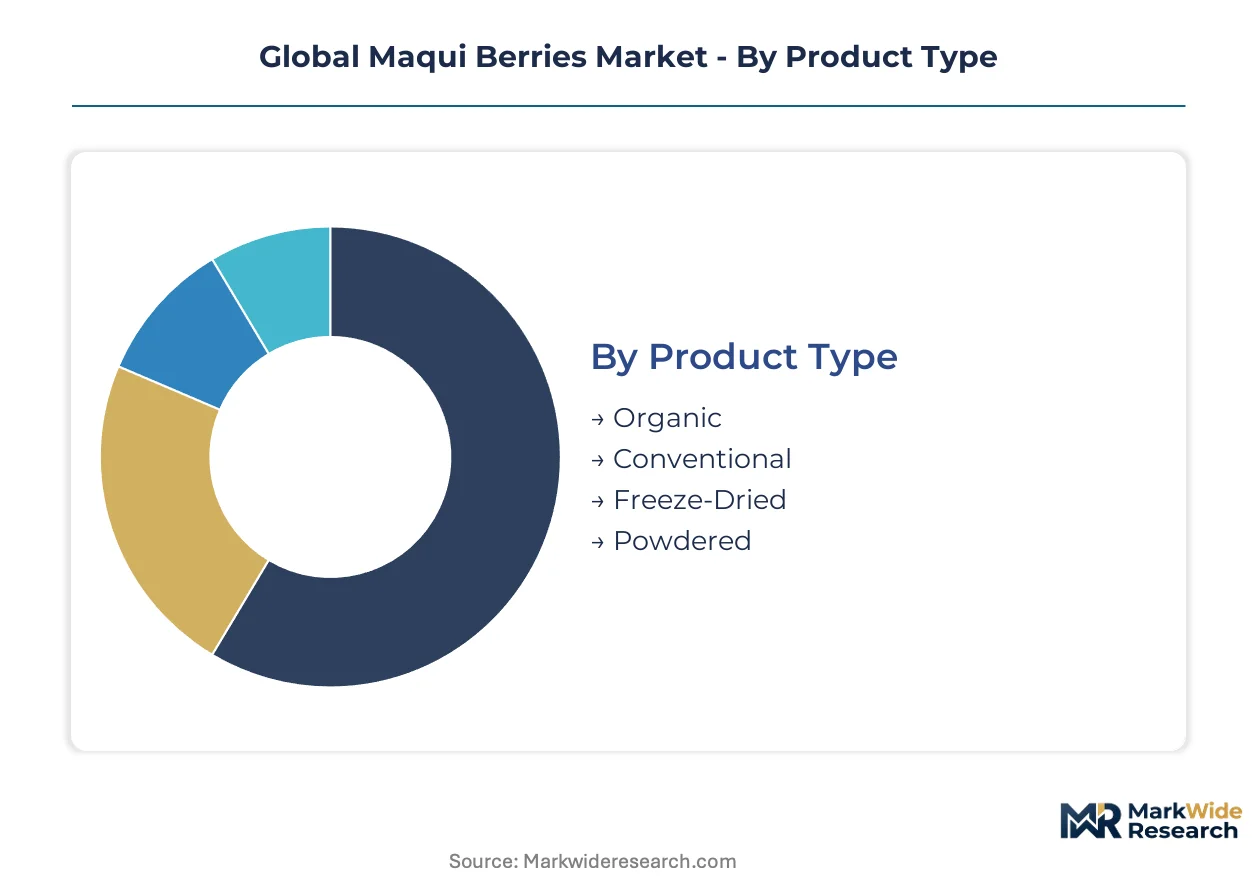
Segmentation in the maqui berries market reveals how procurement priorities split between bioactive preservation requirements and certification premiums. Understanding these divides exposes where margin concentrates and which supply configurations command pricing power across functional food, supplement, and cosmetic channels.
Product Type:
Freeze-dried formats operate as standalone premium inputs requiring specialized lyophilization infrastructure, while powdered alternatives embed more flexibly into mass-market formulations with lower capital barriers.
- Freeze-Dried:Lyophilization preserves delphinidin and cyanidin glycoside integrity at concentrations spray-drying degrades. Supplement manufacturers in North America specify freeze-dried material in procurement contracts, compressing premiums toward South American processors with installed capacity near Chilean source regions.
- Organic:Clean-label certification drives purchase decisions in nutraceutical channels where EU Green Deal procurement standards favor traceable, low-carbon harvest networks. Organic maqui commands positioning premiums through certified partnerships in southern Chile.
- Conventional:Standard harvest material serves cost-sensitive beverage applications where natural purple pigmentation matters more than bioactive concentration thresholds.
- Powdered:Spray-dried formats sacrifice anthocyanin retention for production scalability, embedding into commodity-grade functional food systems with price-driven formulation constraints.
Freeze-dried leads volumes today; organic certification is gaining share fastest across premium supplement channels.
End User:
Application splits reflect divergent technical specifications — beverage formulators prioritize color stability while nutraceutical buyers demand validated bioactive content per serving.
- Supplements:Capsule and tablet manufacturers require standardized anthocyanin assays with batch-level documentation. EFSA safety assessments for maqui berry extracts are clearing pathways for European launches, accelerating adoption by manufacturers seeking antioxidant positioning.
- Food & Beverage:Functional drink developers incorporate maqui for natural purple pigmentation as synthetic colorant replacement. Clean-label beverage innovation pulls freeze-dried supply into formulation pipelines at scale.
- Nutraceuticals:Functional food systems target polyphenol content claims with ingredient doses calibrated to EFSA health claim thresholds.
- Cosmetics:Anthocyanin-rich extracts gain traction in dermal care formulations targeting oxidative stress protection, opening adjacent demand beyond ingestible applications.
Food & Beverage leads volumes today; cosmetics is expanding most quickly as topical antioxidant positioning proliferates.
Sales Channel:
Channel structure maps directly onto buyer sophistication — direct alliances serve traceability requirements while wholesale handles commodity volume aggregation.
- Direct Sales:Multi-year supply agreements with traceable harvest cooperatives displace spot-market purchasing among North American organic brands requiring lot-level geographic provenance documentation.
- Wholesale:Conventional commodity broker networks aggregate conventional-grade material for price-sensitive beverage manufacturers without certification requirements.
- Online:E-commerce platforms serve small-batch supplement brands and direct-to-consumer freeze-dried products with shorter lead times.
- Retail:Brick-and-mortar health food channels stock packaged finished goods rather than bulk ingredients, capturing end-consumer premiums.
Wholesale leads volumes today; direct sales is climbing the fastest as clean-label procurement standards harden.
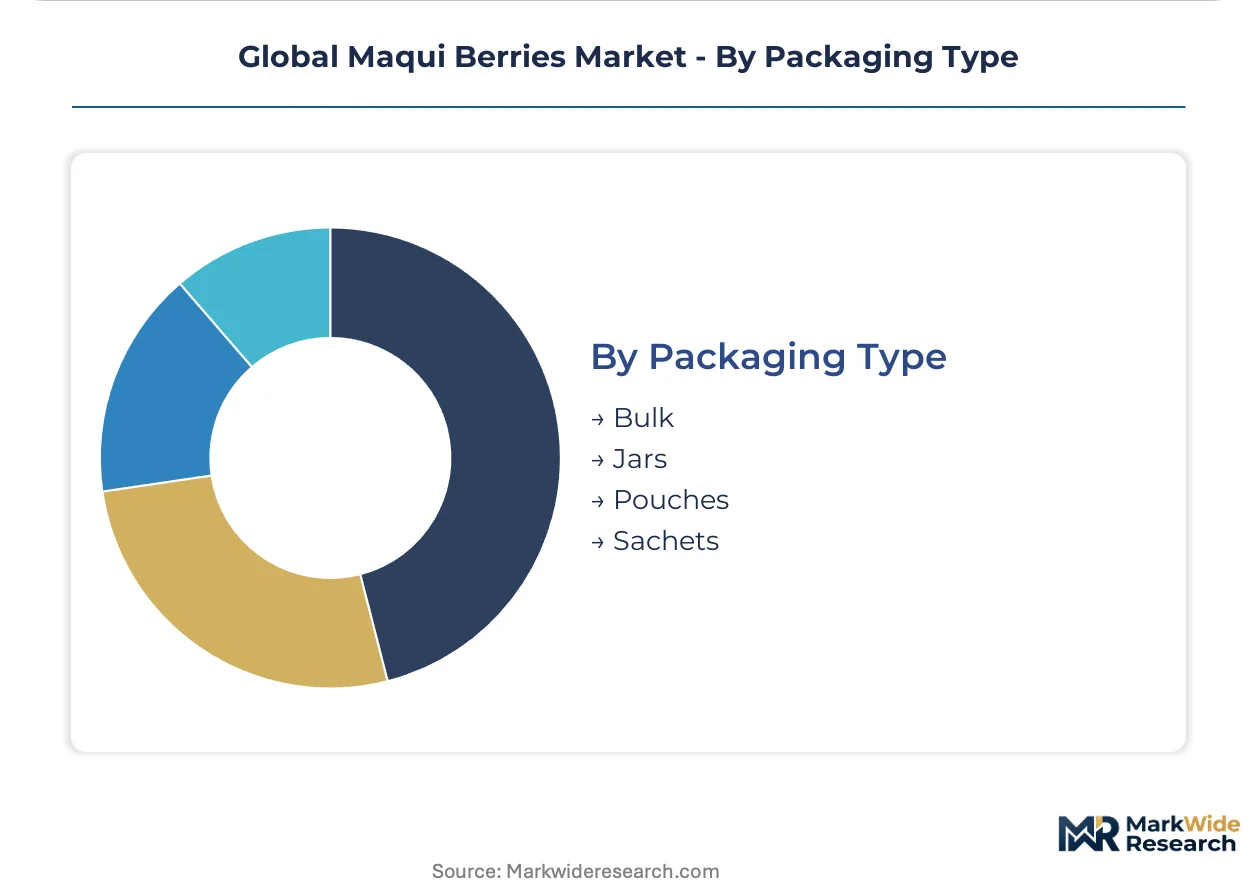
Packaging Type:
Packaging configuration signals supply chain position — bulk serves processor inputs while unitized formats target finished goods distribution.
- Bulk:Industrial-scale shipments supply freeze-drying processors and contract manufacturers with raw material for downstream conversion into shelf-stable formats.
- Pouches:Flexible packaging serves single-serve supplement powders and beverage additive sachets with moisture barrier requirements.
- Jars:Rigid containers target premium freeze-dried retail products where visual product integrity supports shelf presence.
- Sachets:Portion-controlled units embed into functional drink stick packs and travel-size cosmetic sample programs.
Bulk leads volumes today; pouches is gaining share fastest as single-serve functional beverage formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maqui berry commercialization traces its roots to Chilean Patagonia, where indigenous Mapuche communities first harvested Aristotelia chilensis for traditional use before international nutraceutical markets discovered its anthocyanin density in the early 2000s.
Chile
SAG wild harvest quotas constrain raw material flows just as nutraceutical formulators expand procurement. The country's national agricultural regulator enforces seasonal collection limits that directly influence international pricing. Los Lagos region clusters dominate supply, with Puerto Montt and surrounding provinces hosting freeze-drying infrastructure that converts fresh harvest into export-grade formats.
United States
FDA GRAS self-affirmation pathways accelerate ingredient commercialization timelines relative to European alternatives. Supplement manufacturers specify freeze-dried maqui in procurement contracts, pulling premium supply toward North American distributors. California-based organic brands require lot-level geographic provenance documentation as standard sourcing conditions.
Germany
EMA novel food safety assessments govern market entry for maqui extracts, extending lead times for European launches. ECHA REACH registration requirements tighten contaminant documentation standards that smaller exporters cannot satisfy. Hamburg and Frankfurt nutraceutical distributors consolidate supplier relationships toward integrated processors with in-house analytical laboratories.
Argentina
Neuquén and Río Negro provinces offer untapped Aristotelia chilensis growing territory with potential to diversify supply beyond Chilean concentration. The country's national agricultural regulator has yet to impose equivalent wild harvest restrictions, creating regulatory arbitrage opportunities. Early cultivation development in northern Patagonia is attracting processor investment from cross-border Chilean operators.
France
ANSM oversight of novel food ingredients aligns with broader EMA frameworks, though national implementation adds procedural layers. Cosmetic formulators in Paris and Lyon are testing anthocyanin-rich extracts for dermal care applications targeting oxidative stress protection. Provence-based natural ingredient distributors are building direct farmer alliances to satisfy EU Green Deal traceability requirements.
Global Maqui Berries Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification and processing technology dimensions. The vendor base separates into three functional tiers: integrated processors with captive lyophilization capacity near Chilean sources, organic-certified traders with direct farmer alliances, and commodity brokers aggregating conventional-grade material for price-sensitive beverage manufacturers. Strategic moves concentrate on backward integration into harvest networks and multi-year supply agreement structures that lock in traceability documentation.
Within the integrated processor tier, SouthAm Freeze Dry exemplifies capital-intensive drying infrastructure positioned near raw material origins. Among North American organic distributors, Navitas Organics and Terrasoul Superfoods occupy positions that emphasize certified partnerships and clean-label procurement standards. These three anchors represent divergent competitive vectors: processing scale, certification depth, and direct alliance architecture.
| Leading Market Players |
|---|
| Navitas Organics |
| Terrasoul Superfoods |
| SouthAm Freeze Dry |
| Maqui New Life |
| HP Ingredients |
| Bayas del Sur |
| Sunfood Superfoods |
| NOW Foods |
| NP Nutra |
| Others |
Value Chain & Pricing Dynamics
Freeze-dried versus powdered grade bifurcation splits the maqui berry market into parallel pricing universes, with lyophilization capacity scarcity anchoring premium tiers near Chilean source regions while spray-dried commodity flows trade through spot-market channels. This divergence concentrates pricing power among South American processors with installed lyophilization infrastructure, compressing margins for traders dependent on conventional drying networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and bioactive retention variance. Premium freeze-dried material commands positioning premiums through organic certification and validated anthocyanin assays, while standard powdered grades compete on color stability for beverage applications. Pricing pressure stems from SAG wild harvest quota tightening, which constrains raw material flows and intensifies cost compression in conventional tiers. Nutraceutical manufacturers exhibit lowest price sensitivity, prioritizing batch-level documentation over per-kilogram economics.
Supply Chain Analysis
Freight cost differentials between Patagonian harvest zones and North American processing hubs favor lyophilization investment near source regions rather than bulk frozen shipment. Supply concentrates in Chile's Los Lagos region and emerging cultivation clusters in Argentina's Neuquén province, with raw material dependencies on seasonal wild collection labor and freeze-drying equipment capacity. Single-source vulnerability to SAG regulatory quota changes creates structural supply chain risk. Distribution runs through direct farmer alliances for certified organic tiers and conventional commodity brokers for mass-market beverage supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Novel Food approval milestones unlock European nutraceutical demand and accelerate ingredient adoption timelines.
For Market Incumbents: Deepen captive lyophilization capacity in southern Chile to defend margin position against Argentine cultivation expansion. Secure multi-year supply agreements with Mapuche harvest cooperatives before SAG quota tightening accelerates. Certification investment in EU Organic and USDA Organic tiers represents the critical defensive lever against commodity-grade price erosion. For New Entrants and Emerging Players: E-commerce direct-to-consumer channels offer the most penetrable entry vector for small-batch freeze-dried retail products with geographic provenance storytelling. Target cosmetic formulators in France and Germany with anthocyanin-rich extract samples for dermal care applications. White-space exists in Argentina's unregulated wild harvest zones before national agricultural regulators impose equivalent quota restrictions. For Investors and Strategic Acquirers: Consolidation pressure builds where freeze-drying technical expertise concentrates among limited processor pools with validated ECHA REACH documentation capabilities. Long-term viability favors integrated operators with backward control over harvest networks and in-house analytical laboratories. Monitor SAG cultivation permit expansion decisions as the decisive inflection signal for supply elasticity against rising nutraceutical demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Harvest Networks | Captive supply arrangements insulate processors from SAG quota volatility and seasonal price spikes. |
| EU Novel Food Safety Assessment Completion | EMA clearance unlocks European supplement manufacturer procurement pipelines and accelerates adoption. |
| Freeze-Drying Capacity Expansion | Lyophilization infrastructure near Chilean sources preserves bioactive integrity and commands premium positioning. |
| Direct Farmer Alliance Structuring | Multi-year agreements with traceable cooperatives satisfy EU Green Deal traceability requirements for organic brands. |
| Cosmetic Application Development | Anthocyanin-rich extract positioning in dermal care opens adjacent revenue channels beyond ingestible markets. |
Study Parameters
Direct dialogue with freeze-drying processors, organic certification auditors, nutraceutical procurement managers, and Mapuche harvest cooperative leaders grounded this analysis in operational reality. Secondary validation drew from SAG wild harvest quota publications, EFSA novel food safety assessments, ECHA REACH registration databases, and Chilean agricultural export statistics. Bottom-up volume estimates from processor capacity utilization triangulated against top-down demand projections from supplement manufacturer procurement surveys.
Bottom-up modeling segmented the market by product format, certification tier, end-use application, and sales channel across the projection horizon. CAGRs derived from historical price trajectory analysis and forward-looking procurement contract volumes. Forecast inputs incorporated SAG regulatory policy scenarios, EU Green Deal procurement standard adoption curves, and freeze-drying technology diffusion rates among Argentine processors.
The model assumes a particular technology adoption path; alternative pathways for spray-drying quality improvement would alter the outlook for premium tier pricing power. Forecasts reflect documented assumptions regarding SAG quota stability and EMA assessment timeline consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Asia Pacific Lime Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Avocado Puree Market
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Global Not from Concentrate (NFC) Puree Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
China Table Grapes Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Global Hass Avocado Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Cyanidin Market
Fruits and Vegetables
Sweet Cherry Powder Market