
 Asia Pacific Orange Market | 2026-2036
Asia Pacific Orange Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Orange Market Outlook
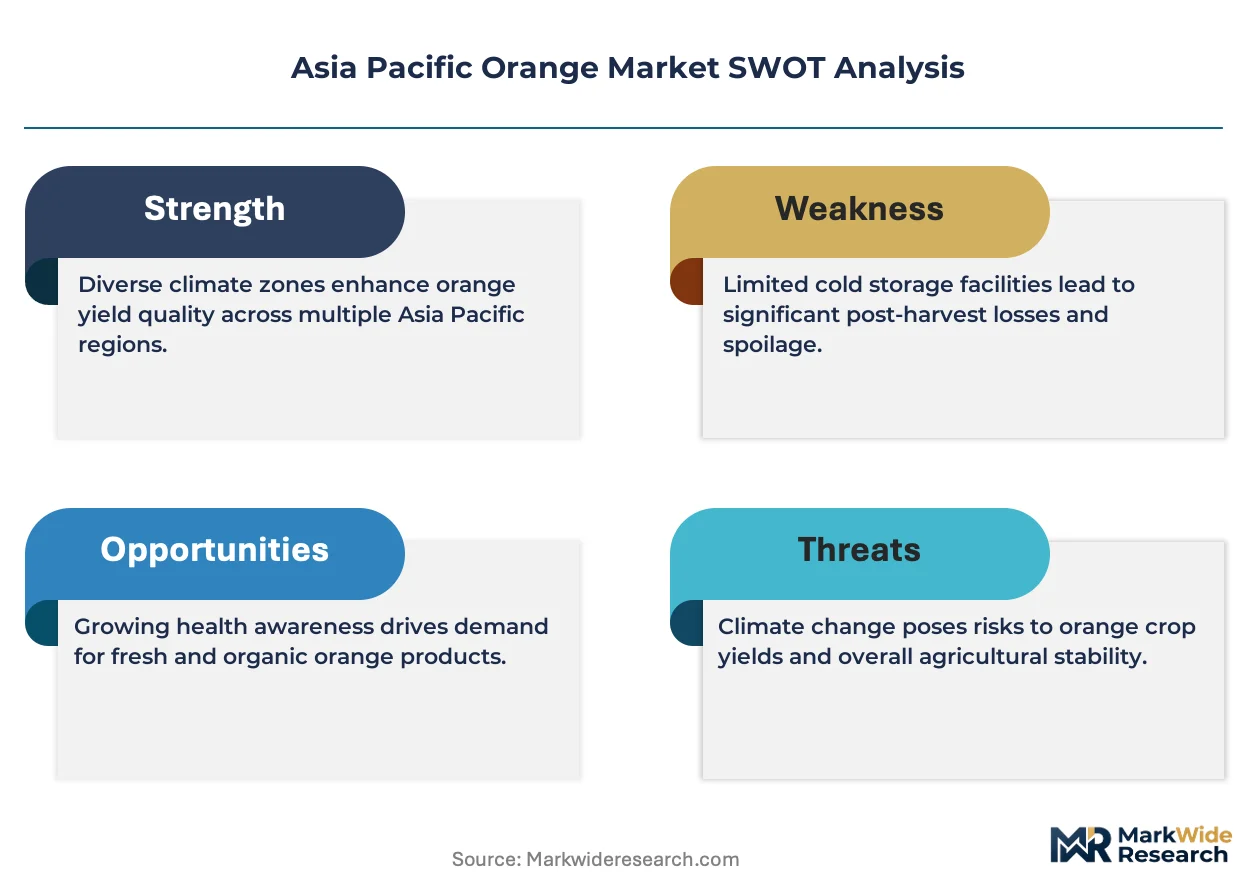
Harvest labor availability is reorganizing supply patterns across the Asia Pacific orange value chain as seasonal worker shortages in China's Jiangxi and Hunan provinces force mechanization investments. China Citrus Group leverages its integrated cold-chain infrastructure to sustain year-round distribution dominance. Yantai North Andre Juice Co. Ltd. anchors the juicing segment through captive orchard contracts in Shandong. Zain Natural Agro India Pvt. Ltd. specializes in organic-certified fresh exports to Middle Eastern buyers.
Oranges are citrus fruits of the species Citrus sinensis, typically containing 10-13% total soluble solids and 0.8-1.2% citric acid by weight, harvested for direct consumption, juice extraction, and peel-derived essential oil recovery. Fresh oranges occupy the largest revenue pool across the region, though orange concentrate commands premium margins from industrial beverage producers seeking consistent brix levels. Juicing oranges represent the fastest-expanding product type as food service chains and packaged juice manufacturers scale procurement. Online retail channels are gaining traction for premium fresh varieties, while bulk packaging dominates industrial transactions.
India's FSSAI, China's SAMR, and Vietnam's Ministry of Agriculture and Rural Development enforce divergent pesticide residue and labeling standards that fragment compliance costs for cross-border suppliers. The EU Green Deal's deforestation regulation, applied to Asian exports reaching European ports, indirectly reshapes orchard traceability requirements across the region. Stakeholders must monitor evolving phytosanitary protocols and decide between regional specialization versus multi-country certification investments.
Market Dynamics
Harvest labor scarcity in China's Jiangxi and Hunan provinces is forcing mechanization investments that compress seasonal production windows and reshape procurement calendars across the Asia Pacific orange value chain.
Growth Catalysts
- FSSAI residue standard tightening:India's food safety regulator is mandating lower pesticide thresholds, compelling orchard-level compliance upgrades that qualify domestic suppliers for premium export channels.
- Mekong Delta processing corridor expansion:Vietnam's concentrated juice infrastructure is attracting cross-border fruit flows from Cambodia and Laos, consolidating regional juicing orange aggregation.
- Dual carbon goals implementation:China's national decarbonization framework is accelerating cold-chain electrification, reducing post-harvest spoilage in transit from Shandong and Sichuan growing belts.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings in Indonesian and Philippine growing regions compress farmer margins and deter replanting investments.
- Supply concentration risk:China's dominance in mandarin and sweet orange varietal propagation creates genetic bottleneck vulnerability for regional orchard renewal programs.
- EU Green Deal deforestation regulation:European port-of-entry traceability requirements impose documentation burdens on Vietnamese and Thai exporters lacking geospatial orchard mapping.
Strategic Opportunities
- Underpenetrated Bangladesh market:Dhaka and Chittagong retail networks show minimal cold-chain orange penetration, offering first-mover advantage for Indian exporters with FSSAI-compliant logistics.
- Emerging HORECA channel:Southeast Asian hotel and restaurant chains are scaling fresh-squeeze juice programs, creating dedicated varietal demand outside commodity concentrate circuits.
- Organic certification arbitrage:Middle Eastern buyer preference for India-origin organic oranges allows Zain Natural Agro and similar operators to command tiered premiums above conventional export grades.
Industry Challenges
- Mechanical harvesting skill gaps:China's citrus belt lacks trained operators for shake-and-catch equipment, slowing automation deployment despite labor shortages.
- Multi-jurisdiction certification timelines:Exporters serving both China's SAMR and India's FSSAI must maintain parallel residue testing protocols, duplicating laboratory validation costs.
- Legacy orchard replanting cycles:Vietnam's aging Mekong Delta tree stock requires phased replacement that disrupts multi-year processor supply agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Orange Market |
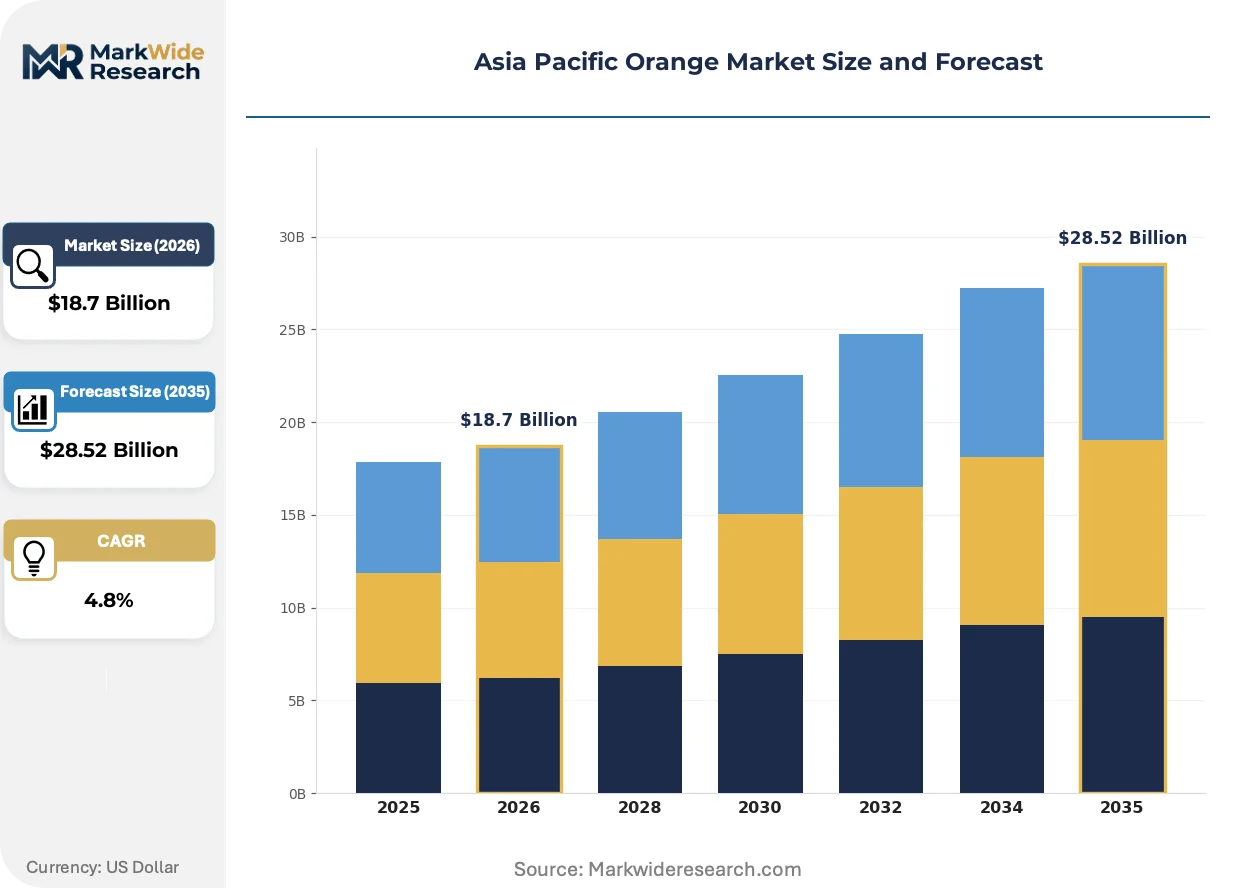
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Oranges, Juicing Oranges, Dried Oranges, Orange Concentrate Distribution Channel: Online Retail, Supermarkets, Local Markets, wholesalers End User: Households, Food Service, Industrial Use, Beverage Producers Packaging Type: Cartons, Plastic Bags, Bulk Packaging, Mesh Bags |
| Companies Covered | China Citrus Group, Yantai North Andre Juice Co. Ltd., Zain Natural Agro India Pvt. Ltd., Paradise Juice Pvt. Ltd., Sunrise Fruits Company SL, Pacific Coast Fruit Products Ltd., Del Monte Fresh Produce, Indian River Fruit Co., Hyatt Fruit Co., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Orange Market Strategic Shifts
Spectral sorting and blockchain traceability are converging to transform quality assurance and supply chain transparency across Asia Pacific orange distribution networks.
Near-infrared spectroscopy deployed at packhouse intake is bifurcating fruit streams into juice-grade and fresh-market categories with precision that manual grading cannot match. Yantai North Andre and similar processors are adopting inline brix measurement to enforce contract specifications at orchard gate. This compression of quality variance is enabling just-in-time concentrate production that minimizes storage carry costs.
China's SAMR and Vietnam's Ministry of Agriculture and Rural Development are mandating blockchain-based origin documentation for citrus exports transiting to European destinations. The regulatory friction is accelerating vendor investment in distributed ledger infrastructure that satisfies EU Green Deal traceability audits. Smallholder cooperatives in Jiangxi face exclusion from export channels without third-party verification integration.
Food service chains across Southeast Asia are unbundling procurement from traditional wholesale markets, establishing direct varietal contracts with Shandong and Sichuan orchard operators. This disintermediation collapses margin layers for legacy traders in Bangkok and Ho Chi Minh City distribution hubs. Premium fresh varieties now move through temperature-controlled e-commerce channels that bypass wet-market intermediaries entirely.
Asia Pacific Orange Market Segmentation
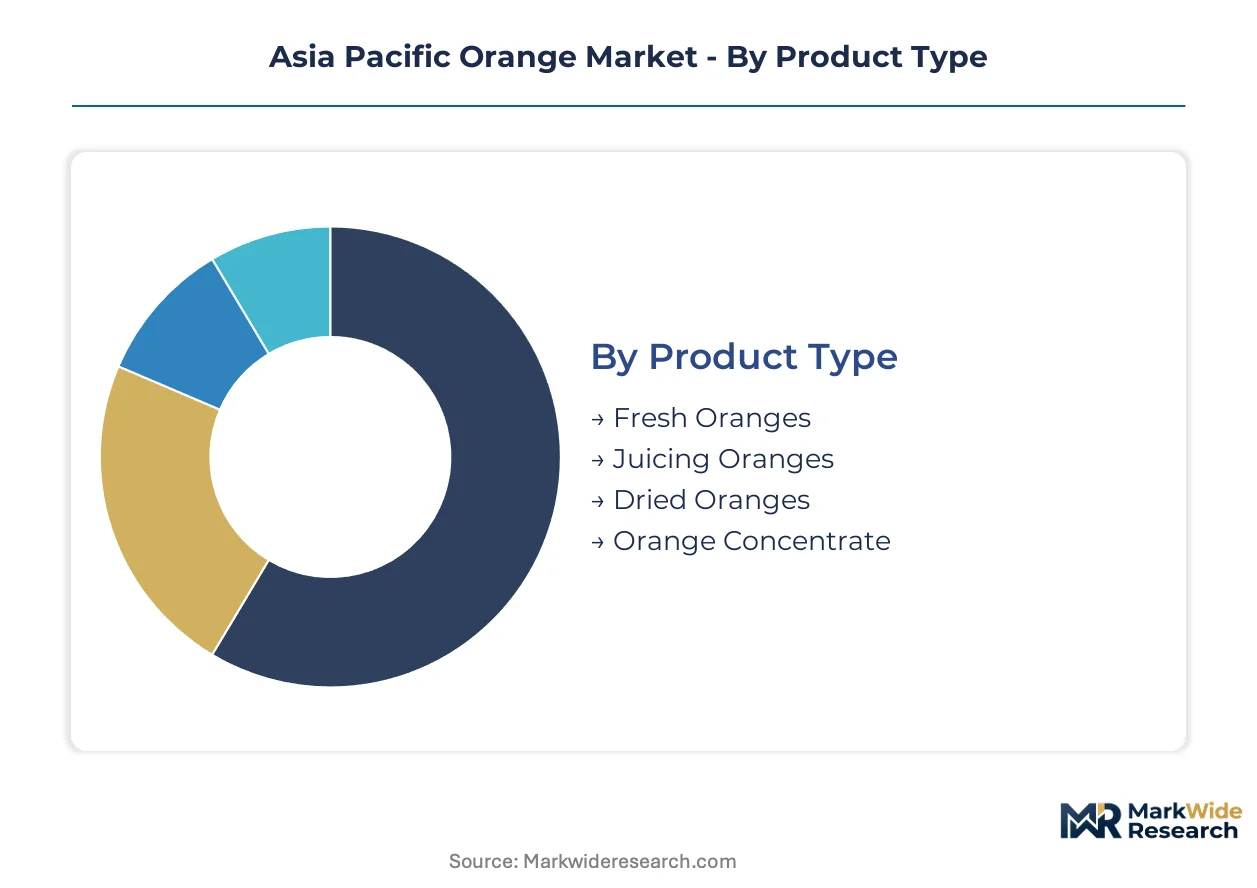
Segmentation in the Asia Pacific orange market reveals divergent margin structures and compliance requirements across product types and channels. Fresh and juicing oranges command distinct logistics investments, while distribution channel choice determines access to FSSAI-compliant versus conventional supply tiers.
Product Type:
Domestic consumption concentrates in fresh and dried segments across India and China's interior provinces, while juicing oranges and concentrate flow toward Vietnam's Mekong Delta processing corridor and export-oriented beverage manufacturers.
- Fresh Oranges:Harvested at 10-13% total soluble solids for direct consumption, these varieties dominate supermarket and local market channels across China's Jiangxi and Hunan growing belts. India's urban households drive premium-grade procurement through organized retail networks in Mumbai and Delhi.
- Juicing Oranges:Selected for higher juice yield and consistent acidity profiles, these varieties anchor industrial procurement from Vietnam's processing corridor and Thailand's central plains. Beverage producers in Southeast Asia are expanding captive orchard contracts to secure brix-standardized supply.
- Dried Oranges:Dehydrated slices and peel segments serve snack manufacturers and traditional medicine processors across China's Sichuan and Yunnan provinces.
- Orange Concentrate:Frozen and aseptic concentrates move through bulk industrial channels to multinational beverage bottlers requiring year-round formulation consistency.
Fresh oranges hold the largest share; momentum sits with juicing oranges as food service chains scale fresh-squeeze programs.
Distribution Channel:
Channel selection determines cold-chain investment intensity and regulatory exposure, with online retail requiring SAMR traceability compliance while local markets operate under lighter documentation burdens.
- Online Retail:Temperature-controlled e-commerce platforms bypass traditional wholesale layers, delivering premium fresh varieties directly to urban consumers in Shanghai, Bangalore, and Jakarta with blockchain-verified origin documentation.
- Supermarkets:Organized retail chains enforce FSSAI and SAMR residue standards at procurement gate, consolidating supplier bases toward certified orchard operators with integrated packhouse infrastructure.
- Local Markets:Wet-market intermediaries in Bangkok, Ho Chi Minh City, and Manila handle conventional-grade fruit with minimal cold-chain investment, serving price-sensitive household segments.
- Wholesalers:Legacy traders aggregate mixed-grade volumes for redistribution to smaller retailers and food service operators across secondary cities.
Supermarkets capture the steepest margin expansion; online retail is climbing the fastest as last-mile cold-chain infrastructure electrifies under China's dual carbon framework.
End User:
End-user segmentation maps directly to product form requirements, with households consuming whole fresh fruit while industrial processors demand standardized concentrate specifications.
- Households:Urban consumers across India's metropolitan corridors and China's tier-one cities drive premium fresh orange demand through organized retail and e-commerce channels.
- Food Service:Hotel and restaurant chains in Southeast Asia are unbundling procurement from wholesale markets, establishing direct varietal contracts with Shandong and Sichuan orchard operators for fresh-squeeze juice programs.
- Industrial Use:Flavor extraction and essential oil recovery operations concentrate in China's Jiangxi province, utilizing peel waste from fresh processing streams.
- Beverage Producers:Multinational and regional bottlers in Vietnam, Thailand, and Indonesia procure concentrate and NFC juice under long-term supply agreements with Mekong Delta processors.
Households absorb the greatest volume; beverage producers are expanding most quickly as Southeast Asian packaged juice consumption accelerates.
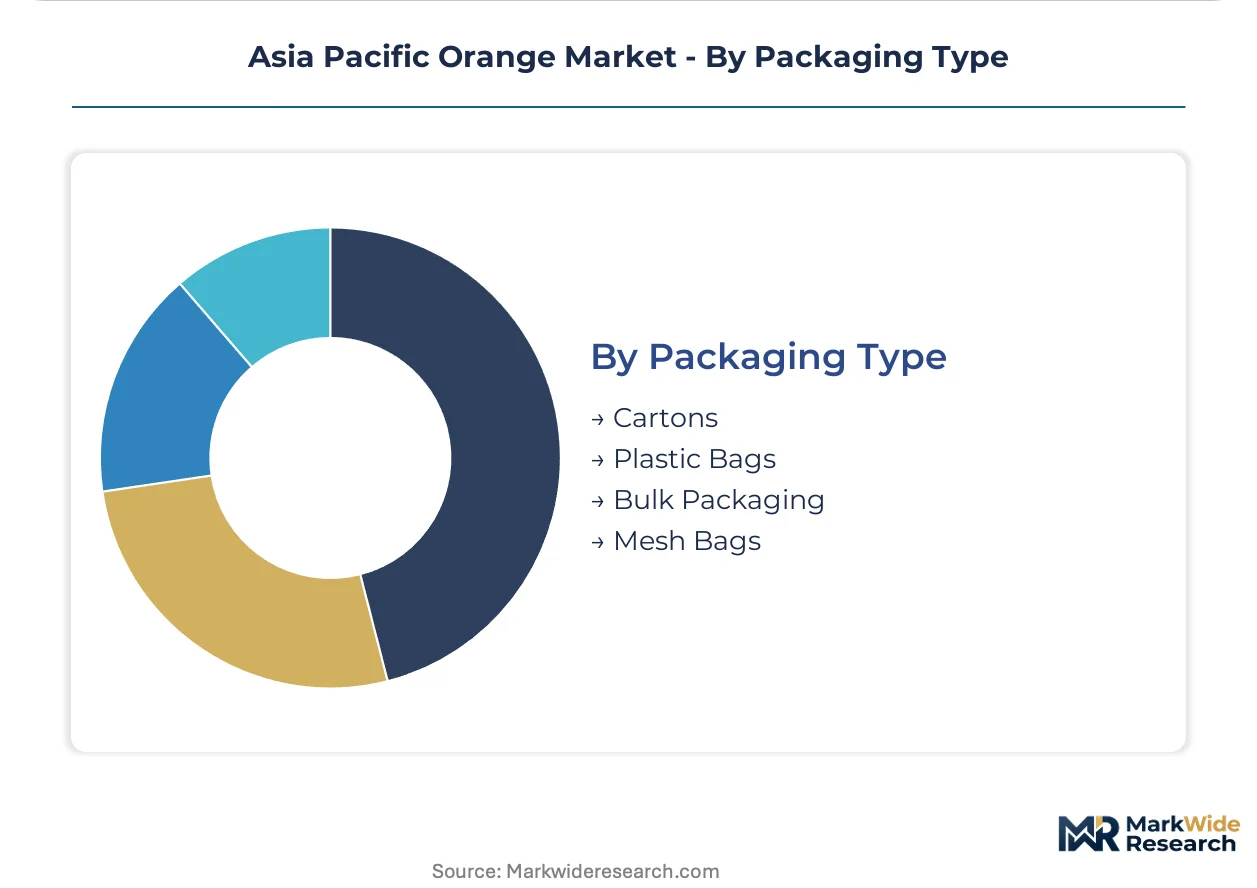
Packaging Type:
Packaging selection reflects channel and end-user requirements, with export-oriented segments demanding traceability-compatible formats while domestic bulk flows minimize unit costs.
- Cartons:Corrugated containers with ventilation apertures dominate supermarket and online retail channels, enabling brand differentiation and shelf-ready presentation for premium fresh varieties.
- Plastic Bags:Polyethylene film packaging serves conventional-grade local market distribution across Indonesian and Philippine growing regions with lower unit economics.
- Bulk Packaging:Bin containers and tote bags move juicing oranges from orchard to processor gate across Vietnam's Mekong Delta corridor, minimizing handling costs in concentrate supply chains.
- Mesh Bags:Net packaging for consumer-count units dominates traditional retail channels in India's secondary cities and China's county-level markets.
Bulk packaging commands the greatest tonnage; cartons are gaining share fastest as organized retail penetration deepens across Southeast Asian urban centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR traceability mandates and China's dual carbon framework are electrifying cold-chain corridors from Shandong to Sichuan, while FSSAI residue tightening across India reconfigures export qualification pathways toward Middle Eastern and Bangladeshi destinations.
China
Jiangxi and Hunan provinces face acute harvest labor scarcity that accelerates shake-and-catch mechanization trials. SAMR blockchain documentation requirements for EU-bound exports are excluding smallholder cooperatives lacking third-party verification. Yantai North Andre Juice Co. Ltd. anchors the juicing segment through captive orchard contracts across Shandong's processing belt.
India
FSSAI's tightened pesticide residue thresholds are compelling orchard-level compliance investments that qualify domestic suppliers for premium export channels. Zain Natural Agro India Pvt. Ltd. specializes in organic-certified fresh exports to Middle Eastern buyers commanding tiered premiums. The underpenetrated Dhaka and Chittagong retail networks offer first-mover advantage for FSSAI-compliant logistics operators.
Vietnam
The Mekong Delta processing corridor is attracting cross-border fruit flows from Cambodia and Laos, consolidating regional juicing orange aggregation. The Ministry of Agriculture and Rural Development enforces divergent phytosanitary standards that fragment compliance costs for multi-country suppliers. Aging tree stock across the Delta requires phased replacement that disrupts multi-year processor supply agreements.
Thailand
Central plains juicing varieties anchor industrial procurement for Southeast Asian beverage producers scaling packaged juice consumption. Input cost volatility across fertilizer and fuel compresses farmer margins and deters replanting investments in peripheral growing regions. Bangkok wholesale intermediaries face margin compression as food service chains establish direct varietal contracts with upstream orchard operators.
Indonesia
Conventional-grade local market distribution dominates with minimal cold-chain investment serving price-sensitive household segments. The national food safety regulator enforces residue documentation that lags FSSAI and SAMR stringency, creating dual-track export qualification complexity. Polyethylene film packaging serves lower-unit-economics distribution across Javanese growing regions.
Asia Pacific Orange Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that fragments across organic certification, regional processing, and varietal propagation niches. The upper tier commands captive orchard networks and electrified cold-chain infrastructure that sustains year-round distribution dominance. Strategic archetypes include integrated processors with backward orchard control, organic-certified export specialists, and multinational fresh produce traders. Competitive moves concentrate on direct contracting with food service chains and blockchain traceability investments that satisfy EU Green Deal audit requirements.
Within the integrated processor tier, China Citrus Group leverages its cold-chain infrastructure to sustain distribution dominance across the region's largest volume pool. Yantai North Andre Juice Co. Ltd. exemplifies the captive-orchard archetype through varietal contracts that enforce brix specifications at gate. Zain Natural Agro India Pvt. Ltd. occupies the organic-certified export specialist position, commanding tiered premiums above conventional grades through Middle Eastern buyer relationships.
| Leading Market Players |
|---|
| China Citrus Group |
| Yantai North Andre Juice Co. Ltd. |
| Zain Natural Agro India Pvt. Ltd. |
| Paradise Juice Pvt. Ltd. |
| Sunrise Fruits Company SL |
| Pacific Coast Fruit Products Ltd. |
| Del Monte Fresh Produce |
| Indian River Fruit Co. |
| Hyatt Fruit Co. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Mekong Delta processors and Vietnamese beverage bottlers lock in supply access while fixing price visibility across volatile harvest cycles. These arrangements compress spot market liquidity and concentrate bargaining power with integrated operators holding captive orchard networks.
Pricing Analysis
Price spreads between China's Shandong processing belt and Vietnam's Mekong Delta corridor reflect divergent labor and cold-chain electrification costs. Three-tier pricing structure across premium organic, FSSAI-compliant standard, and conventional local-market grades separates certified export tiers from commodity flows. Cost compression in conventional segments intensifies as fertilizer volatility runs through Indonesian and Philippine growing regions. Household buyers in India's organized retail channels show lowest price sensitivity, while wet-market intermediaries in Bangkok and Ho Chi Minh City operate on thinnest margins.
Supply Chain Analysis
Inventory carry periods extend from harvest peaks through China's dual carbon framework electrification rollout, compressing lead times for EU-bound exports requiring blockchain traceability documentation. Supply concentrates in China's Jiangxi and Hunan provinces, Vietnam's Mekong Delta, and India's Maharashtra and Punjab belts. Production rests on fertilizer inputs, agricultural labor availability, and cold-chain equipment. Single-source vulnerability sits with China's dominance in mandarin varietal propagation. Distribution runs through integrated processor networks for industrial concentrate flows and fragmented wholesale layers for conventional fresh fruit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern Asia Pacific orange value chains as blockchain traceability infrastructure creates interoperability standards between SAMR, FSSAI, and EU Green Deal compliance systems. Ecosystem control points have shifted toward data-verified origin documentation.
For Market Incumbents: Shield integrated cold-chain investments by accelerating captive orchard consolidation in Shandong and Sichuan before mechanization trials in Jiangxi mature. Prioritize FSSAI certification overlays for Indian export corridors to capture Bangladesh first-mover premiums. Defensive positioning against spectral sorting technology adoption by Mekong Delta processors requires inline brix measurement deployment at orchard gate. For New Entrants and Emerging Players: Lead with organic certification arbitrage into Middle Eastern buyer networks where Zain Natural Agro has established tiered premium benchmarks. Target Dhaka and Chittagong retail networks with FSSAI-compliant logistics partnerships. Go-to-market execution should bypass legacy Bangkok wholesale intermediaries through direct food service chain contracting for fresh-squeeze juice programs. For Investors and Strategic Acquirers: Orchard operators with integrated packhouse infrastructure and multi-jurisdiction residue testing capabilities represent the most defensible acquisition profile. Long-term viability hinges on electrified cold-chain density and blockchain traceability integration. Watch for EU Green Deal audit failure rates at Vietnamese export terminals as inflection indicator for compliance cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Orchard Contracting | Yantai North Andre's Shandong belt consolidation enforces brix specifications at processor gate. |
| Blockchain Traceability Deployment | SAMR and Vietnam's Ministry of Agriculture mandates exclude smallholder cooperatives lacking third-party verification. |
| Spectral Sorting Adoption | Near-infrared packhouse intake bifurcates juice-grade and fresh-market streams with precision manual grading cannot match. |
| Organic Certification Investment | Middle Eastern buyer preference for India-origin organic allows tiered premiums above conventional export grades. |
| Direct Food Service Contracting | Southeast Asian hotel and restaurant chains unbundle procurement from Bangkok wholesale intermediaries entirely. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with orchard operators, packhouse managers, beverage procurement leads, and cold-chain logistics specialists; and secondary validation through FSSAI residue standard filings, SAMR traceability directives, Vietnam Ministry of Agriculture phytosanitary protocols, and EU Green Deal deforestation regulation documentation. Bottom-up volume modeling across product type, distribution channel, end user, and packaging segments triangulated against top-down trade flow analysis.
Across the analysis window, forecasts derived from segmented adoption curves for mechanization, organic certification penetration, and cold-chain electrification under China's dual carbon framework. Modeled dimensions included fresh versus juicing orange varietal splits, online retail channel expansion rates, and FSSAI-compliant versus conventional supply tier qualification pathways. Growth rate outputs anchored in harvest labor availability trajectories and processor capacity utilization patterns.
The analysis sits within stated boundaries; outcomes outside sustained regulatory tightening by India's FSSAI or accelerated EU Green Deal enforcement would require recalibration. Forecasts reflect assumptions around mechanization deployment timelines and blockchain infrastructure investment rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Red Berries Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
Bamboo Shoots Market
Fruits and Vegetables
Mulberry Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
Global Fresh Fruits and Vegetables Market
Fruits and Vegetables
Aegle Marmelos Market
Fruits and Vegetables
Middle East and Africa Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Global Fruit Pomace Market
Fruits and Vegetables
Tropical Fruit Puree Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Olive Market