
 Fresh Peaches Market | 2026-2036
Fresh Peaches Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Peaches Market Foresight
Precision-controlled atmosphere storage and cold-chain logistics is reshaping how fresh peaches move from orchard to retail shelf, extending viable shipping windows and opening distant markets. Costa Group leverages integrated farm-to-pack operations across Australian growing regions to sustain year-round supply consistency. Dalian Yidu Group anchors northern China's export pipeline through port-adjacent processing facilities. Fresh Del Monte Produce competes via vertically controlled Latin American sourcing networks that feed North American retail contracts.
Fresh peaches are stone fruits of Prunus persica, harvested at firm-mature stage with soluble solids typically exceeding 10 degrees Brix and flesh texture ranging from melting to non-melting depending on cultivar; their primary commercial purpose centers on direct fresh consumption, with secondary processing into juices, purees, and frozen products. Yellow peach varieties dominate volume trade due to shipping durability and broad consumer recognition, while white peach demand accelerates in premium Asian markets where sugar-acid balance commands price premiums. Distribution through supermarkets captures the largest value pool, though online grocery channels show the fastest structural expansion as last-mile refrigeration infrastructure matures.
USDA grading standards and FDA Food Safety Modernization Act requirements shape product specifications for peaches entering the United States, mandating traceability protocols and microbial testing thresholds that filter supplier eligibility. China's SAMR enforces national food safety standards GB 2762 and GB 2763, regulating heavy metal limits and maximum residue levels that directly determine which orchards qualify for domestic retail placement. Stakeholders must monitor evolving phytosanitary barriers and carbon-accounting requirements that increasingly determine market access eligibility across major import jurisdictions.
Market Dynamics
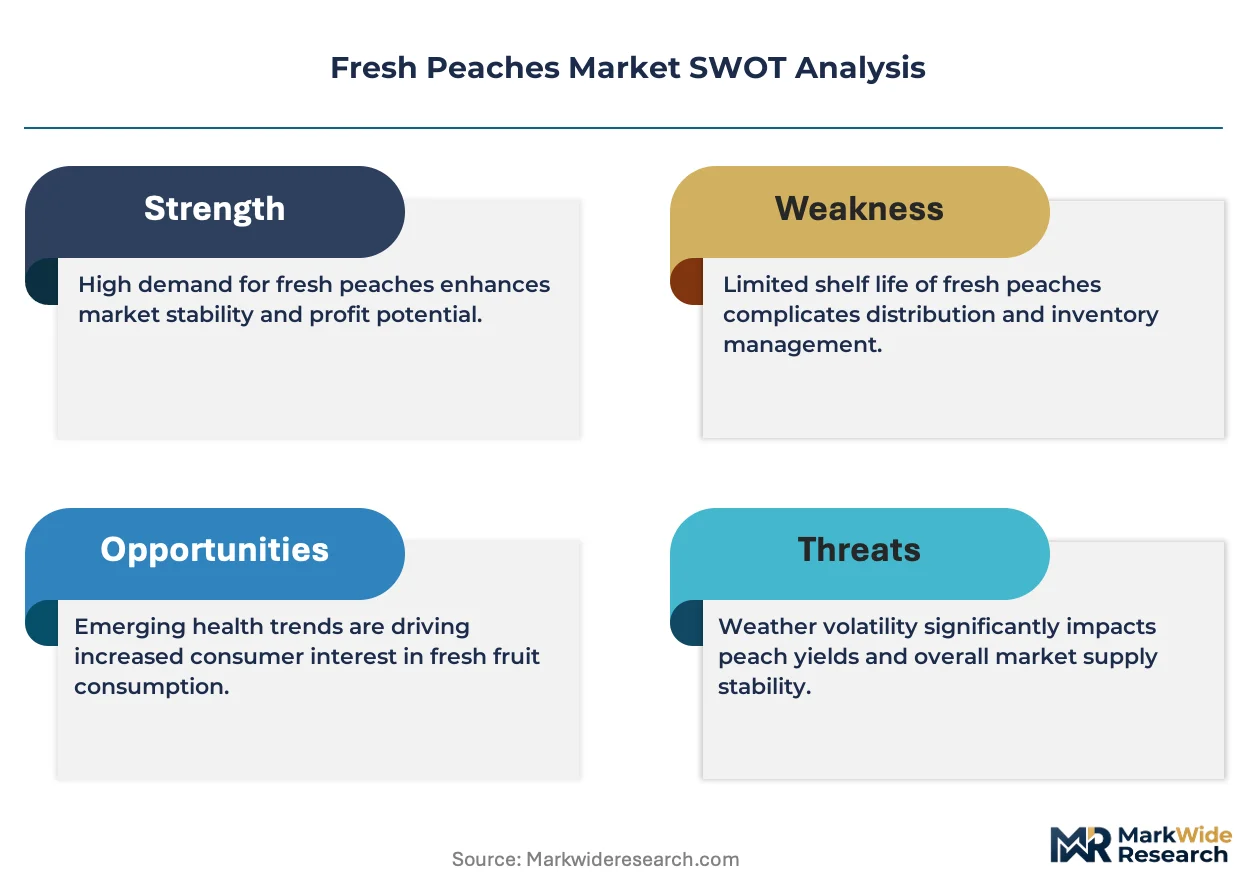
Supermarket retail chains are aggressively expanding fresh produce sections to capture shifting consumer preferences toward health-forward, minimally processed foods, while the EU Green Deal's Farm to Fork strategy tightens pesticide residue thresholds and forces orchard operators toward integrated pest management systems.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory pesticide reduction targets are accelerating adoption of biological control agents and precision monitoring systems across European orchards.
- Controlled Atmosphere Storage:Port-adjacent processing facilities in northern China are extending viable shipping windows and opening distant export markets previously unreachable for fresh stone fruit.
- Shandong and Hebei Provinces:Climate-advantageous growing corridors in these Chinese provinces concentrate production capacity that feeds both domestic retail and international export channels.
Market Restraints
- Input Cost Volatility:Labor-intensive hand-picking requirements and seasonal wage fluctuations in major producing regions compress margin structures for orchard operators.
- Phytosanitary Barriers:China's SAMR enforcement of GB 2762 heavy metal limits and GB 2763 maximum residue levels filters supplier eligibility and blocks market access for non-compliant orchards.
- Perishability Constraint:Narrow harvest-to-retail windows limit distribution radius and force reliance on expensive cold-chain infrastructure that smaller operators cannot finance.
Strategic Opportunities
- Online Grocery Channels:Last-mile refrigeration infrastructure maturation in urban China and North America is creating direct-to-consumer pathways that bypass traditional wholesale markups.
- White Peach Premiumization:Sugar-acid balance preferences in Japanese and South Korean markets command price premiums that justify specialized cultivar development and protected cultivation investments.
- Carbon Accounting Integration:Emerging import jurisdiction requirements for supply chain emissions disclosure favor operators with existing farm-level energy and transport monitoring systems.
Industry Challenges
- Integrated Pest Management Expertise Gap:Orchard workforce transition from chemical-dependent to biological control methods requires retraining programs that current agricultural extension services inadequately deliver.
- Traceability System Integration:FDA Food Safety Modernization Act traceability protocols demand hardware and software investments that fragment across incompatible state-level reporting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Peaches Market |
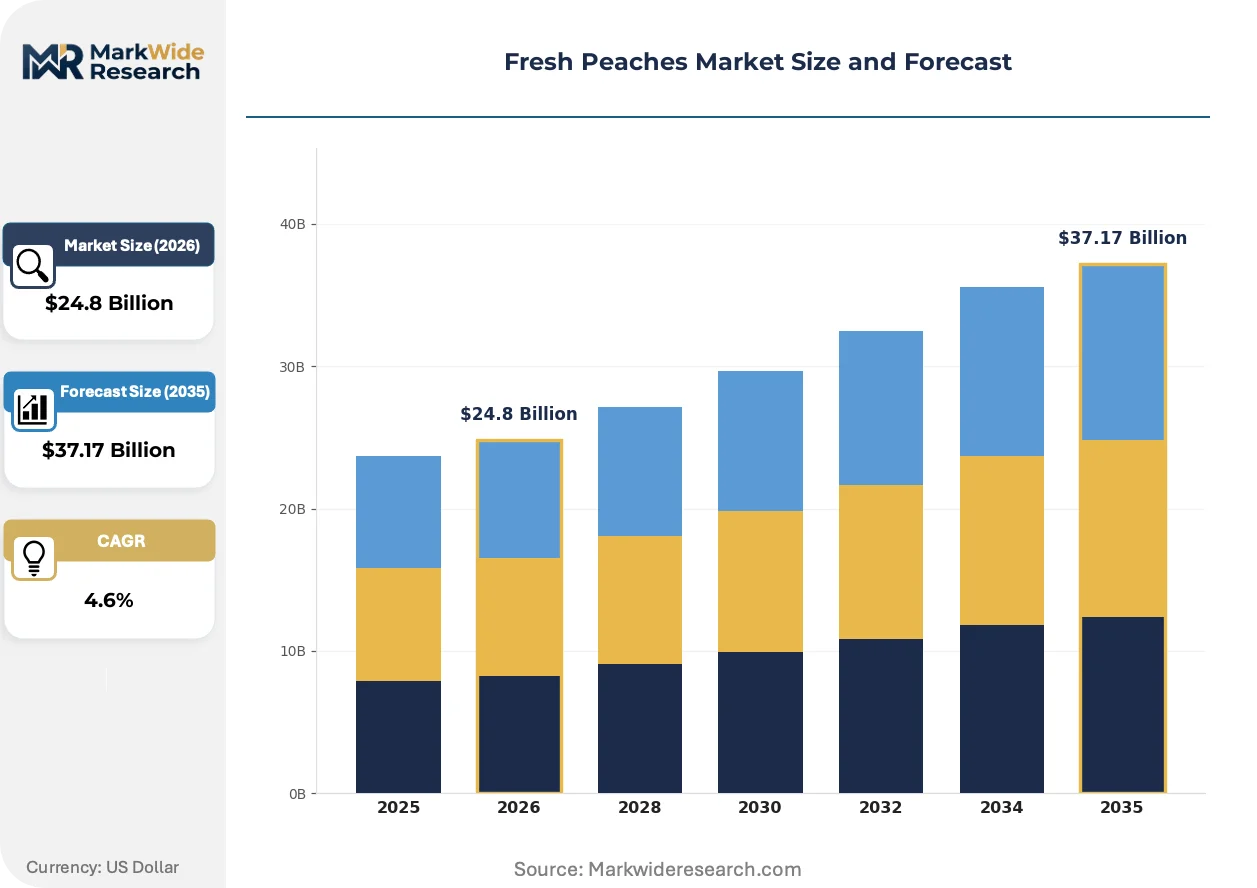
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Variety: Yellow Peaches, White Peaches, Donut Peaches, Clingstone, Freestone Ripeness Level: Unripe, Mid-Ripe, Fully Ripe, Overripe Packaging Type: Plastic Clamshell, Cardboard Box, Mesh Bags, Bulk Bins Distribution Channel: Supermarkets, Farmers Markets, Online Grocery, Specialty Stores |
| Companies Covered | AgroSuper, Camanchaca, Costa Group, Fresh Del Monte Produce, Hortifrut, Robinson Fresh, Dalian Yidu Group, Hebei Jinzhou Fruit Group, Shandong Zhongnan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Peaches Market Shifts & Advancements
Precision agriculture and post-harvest technologies are actively compressing spoilage rates and extending market radius for fresh peaches, while regulatory frameworks on both sides of the Pacific reshape competitive eligibility criteria.
Hyperspectral imaging systems deployed in packhouse sorting lines are hybridizing quality assessment protocols by detecting internal bruising and sugar content non-destructively. Large retail chains in Australia and California are adopting these systems at accelerating pace to reduce rejection rates at distribution centers. The technology is hybridizing procurement relationships by enabling outcome-based pricing contracts tied to measured Brix levels rather than visual grade alone.
China's SAMR has tightened enforcement timelines for GB 2763 maximum residue limit compliance, forcing export-oriented orchards to accelerate pesticide record-keeping digitization. The industrial consequence is a bifurcation between operators with certified integrated pest management systems and those facing exclusion from premium retail placement. Shandong province orchards serving Japanese import markets are most affected and are responding by contracting third-party laboratory pre-shipment testing.
Direct-to-restaurant procurement contracts are displacing traditional wholesale auction systems in Mediterranean producing regions. Chef-driven varietal selection programs in Barcelona and Milan are contracting specific harvest windows and post-harvest ripening protocols. This pattern is most visible in Spain's Lleida growing cluster, where fixed-price seasonal agreements now cover thirty percent of yellow peach volume.
Fresh Peaches Market Segmentation
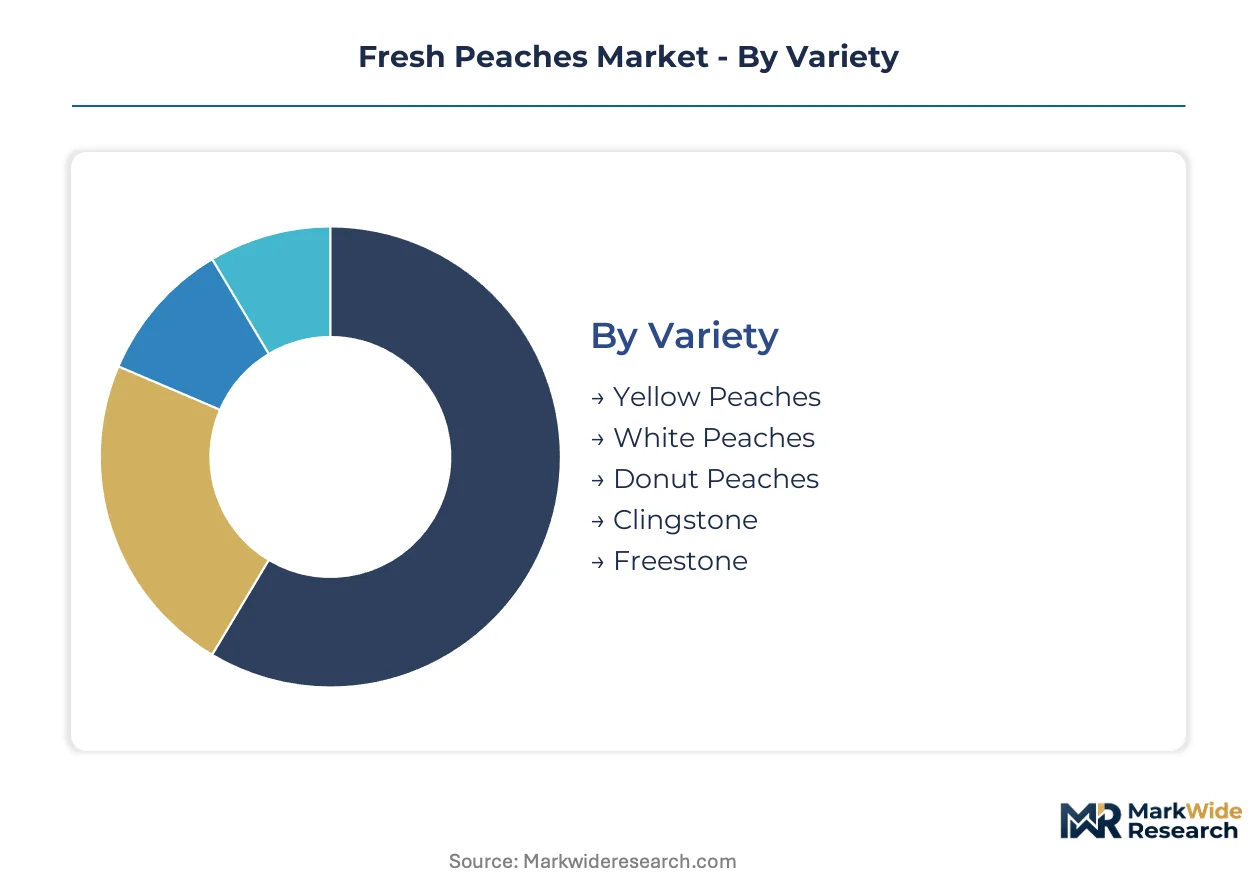
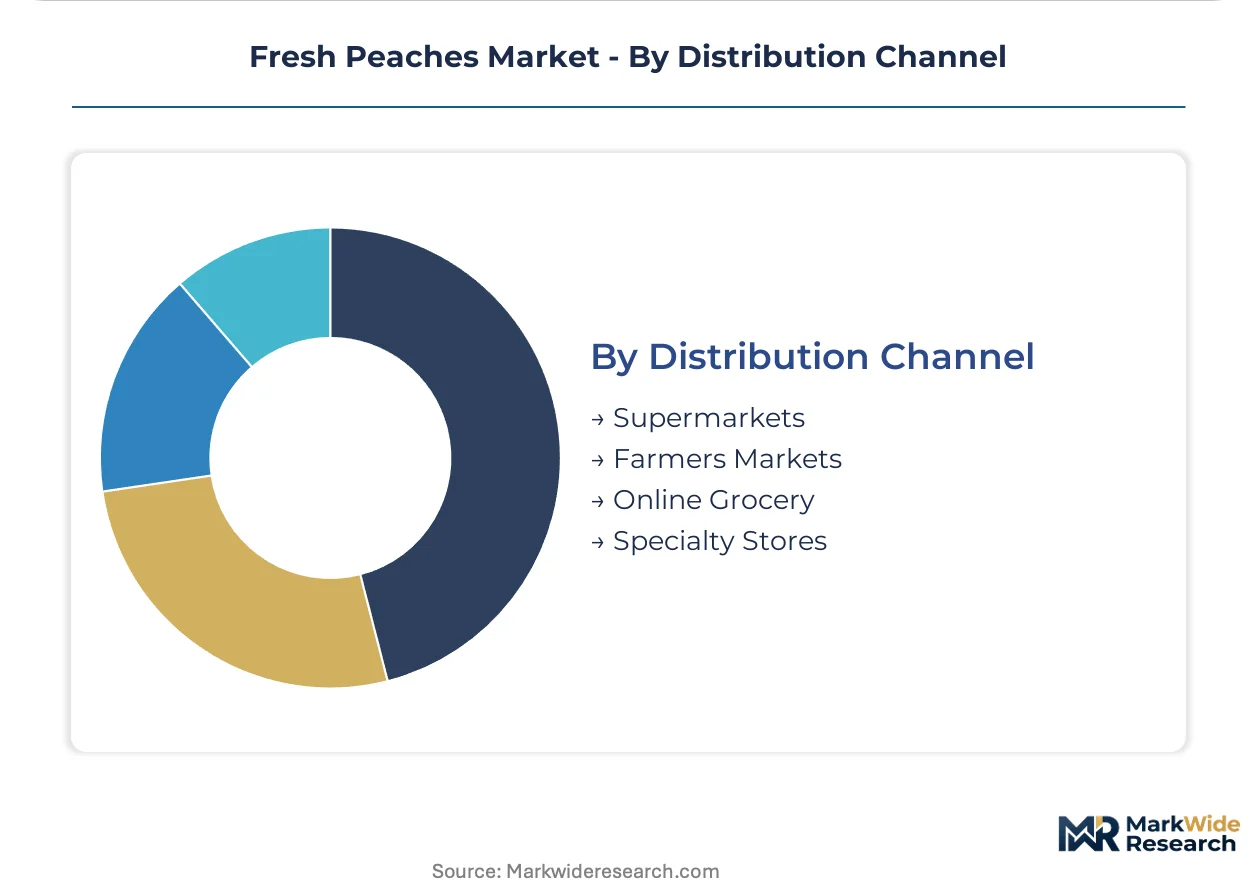
Fresh peach segmentation reveals how shelf-life constraints and handling requirements stratify commercial value across the supply chain. Variety and ripeness classifications determine cold-chain intensity, while packaging and channel choices reflect the trade-off between protection cost and retail price realization.
Variety:
Yellow peach cultivars turn inventory fastest with broad retail acceptance, while specialty varieties rotate slowly through premium channels with higher margin capture per unit.
- Yellow Peaches:Firm flesh and higher acid content withstand mechanical harvesting and extended transit. Supermarket chains in the United States and Australia specify these cultivars for year-round program contracts due to predictable storage behavior.
- White Peaches:Lower acid and higher sugar profiles demand gentler handling and accelerated retail turnover. Japanese and South Korean import buyers pay premiums for specific Brix thresholds, justifying air-freight logistics from Shandong province orchards.
- Donut Peaches:Flattened shape creates packing inefficiencies that limit scale economics. Niche placement in North American specialty retailers and direct-to-consumer subscription boxes.
- Clingstone:Flesh adheres to pit, complicating fresh consumption but suiting processing channels. Declining fresh-market share as freestone alternatives improve shipping durability.
- Freestone:Clean pit separation enables efficient slicing for foodservice and ready-to-eat retail formats. Dominant in European supermarket peach programs.
Yellow Peaches anchors the volume base while White Peaches gains share at the steepest rate.
Ripeness Level:
Harvest timing decisions cascade through margin structures, with earlier picks sacrificing flavor for logistics flexibility and later picks capturing price premiums in proximal markets.
- Unripe:Firm fruit harvested at physiological maturity tolerates longest supply chains. Export-oriented orchards in Hebei province target this specification for seafreight to European markets.
- Mid-Ripe:Partial softening begins, narrowing distribution radius to regional truck routes. Preferred by supermarket distribution centers with 5-7 day turnover targets.
- Fully Ripe:Peak eating quality demands same-day or next-day retail placement. Farmers markets and restaurant procurement contracts specify this stage with premium pricing.
- Overripe:Processing diversion grade for juice and puree manufacture. Orchards with on-site freezing capacity capture value that would otherwise be lost to spoilage.
Unripe fruit dominates export tonnage while Fully Ripe commands the highest per-kilogram returns in domestic premium channels.
Packaging Type:
Protection investment correlates inversely with handling velocity, creating four distinct cost tiers that filter operator participation by capital availability.
- Plastic Clamshell:Rigid protection with retail-ready presentation supports automated checkout systems. Required by major North American supermarket chains for stone fruit categories.
- Cardboard Box:Standard export format with ventilation engineering for controlled-atmosphere containers. Shandong port facilities specialize in custom box specifications for Japanese importers.
- Mesh Bags:Low-cost option for high-turnover domestic retail with minimal handling stages. Common in Chinese wet markets and European discount grocery formats.
- Bulk Bins:Foodservice and processing channel format eliminating retail packaging cost. Requires immediate downstream cold-chain transfer to prevent compression damage.
Cardboard Box configurations move the greatest export volume while Plastic Clamshell expands most quickly in automated retail environments.
Distribution Channel:
Channel selection determines price realization speed and traceability burden, with digital intermediaries compressing traditional wholesale markups.
- Supermarkets:Centralized procurement with strict quality protocols and year-round volume commitments. EU Green Deal pesticide documentation requirements filter supplier eligibility.
- Farmers Markets:Direct producer-consumer contact with minimal packaging and maximum ripeness. Seasonal concentration in Mediterranean growing regions with strong culinary tourism.
- Online Grocery:Last-mile refrigeration infrastructure enables direct-to-door delivery of ripe fruit. Urban China and North American metro areas show steepest adoption curves.
- Specialty Stores:Curated varietal selection with origin storytelling and premium positioning. Japanese depachika food halls and organic retailers in California.
Supermarkets capture the largest revenue pool while Online Grocery climbs the fastest as cold-chain infrastructure matures in major metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket procurement managers in China, the United States, and Germany drive the largest volume commitments, while Japanese specialty retailers and Australian foodservice distributors anchor premium-tier demand with strict cultivar specifications.
China
Shandong and Hebei provinces concentrate export-oriented production serving Japanese and South Korean import markets. SAMR enforcement of GB 2763 maximum residue limits accelerates pesticide record-keeping digitization across orchard operations. Dalian port-adjacent processing facilities extend cold-chain reach to European markets previously inaccessible to Chinese stone fruit exporters.
United States
California Central Valley growers supply year-round supermarket programs through controlled-atmosphere storage investments. FDA Food Safety Modernization Act traceability protocols filter supplier eligibility for retail placement. Georgia and South Carolina orchards capture eastern seaboard demand with shortened logistics windows during peak summer harvest.
Spain
Lleida growing cluster orchards displace traditional wholesale auctions with fixed-price restaurant procurement contracts. EU Green Deal Farm to Fork pesticide reduction targets force integrated pest management adoption. Barcelona and Milan chef-driven varietal selection programs now cover thirty percent of regional yellow peach volume through direct contracting.
Australia
Costa Group leverages integrated farm-to-pack operations across multiple growing regions to sustain year-round supply consistency. TGA-equivalent state-level food safety frameworks govern export eligibility to Asian markets. Goulburn Valley and Swan Hill production zones feed domestic supermarket chains and Southeast Asian air-freight channels.
Chile
Counter-seasonal harvest windows position Chilean orchards as critical suppliers to North American winter markets. Phytosanitary protocols under USDA APHIS agreements determine cultivar eligibility for US entry. Central Valley packing cooperatives consolidate smallholder output to meet minimum volume thresholds for supermarket direct contracts.
Fresh Peaches Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base stratifies between vertically integrated orchard-to-retail operators and regional packing cooperatives serving wholesale channels. Three archetypes dominate: integrated agribusiness conglomerates with multi-continent sourcing networks, national champions anchored in climate-advantaged growing regions, and cooperative associations consolidating smallholder output. Competitive moves center on cold-chain infrastructure expansion and cultivar development partnerships with research institutions.
Among integrated agribusiness operators, Costa Group and Fresh Del Monte Produce exemplify the multi-continent sourcing model that underpins year-round retail contract fulfillment. Dalian Yidu Group anchors the Chinese export pipeline through northern port-adjacent processing investments. Regional specialists including Hebei Jinzhou Fruit Group and Shandong Zhongnan Group occupy positions within domestic supply chains where geographic proximity to demand centers substitutes for vertical integration depth.
| Leading Market Players |
|---|
| AgroSuper |
| Camanchaca |
| Costa Group |
| Fresh Del Monte Produce |
| Hortifrut |
| Robinson Fresh |
| Dalian Yidu Group |
| Hebei Jinzhou Fruit Group |
| Shandong Zhongnan Group |
| Others |
Supply & Pricing Matrix
Phytosanitary barrier volatility between China and key import markets determines both tier spreads between air-freight white peaches and seafreight yellow peaches and the geographic shape of cold-chain infrastructure investment. Operators must price in pre-shipment laboratory testing costs and reject-rate risk while configuring supply chains around port-adjacent processing nodes that qualify for multiple jurisdiction entry.
Pricing Analysis
Cost-plus contracts with agricultural input indexation dominate supermarket procurement programs, locking in margin protection against fertilizer and fuel swings. Three-tier pricing structure across premium, standard, and economy levels separates Japanese air-freight white peach contracts from European seafreight yellow peach volumes and domestic wet-market mesh-bag sales. Cost compression in the standard tier is intensifying because Hebei province labor rates are converging with Shandong levels during peak harvest windows. Foodservice buyers in Barcelona and Milan show least price sensitivity, while European discount grocery chains drive hardest volume negotiations.
Supply Chain Analysis
Tariff exposure between China and Japan dominates supply chain risk calculus for Shandong export orchards serving premium Asian markets. Production gravity centers on China, Spain, and Chile, with the latter two anchoring counter-seasonal supply to Northern Hemisphere winter demand. Cold-chain equipment and controlled-atmosphere container capacity constitute critical input dependencies that constrain smaller operators. Distribution runs through supermarket centralized procurement systems in developed markets, while direct-to-restaurant contracting displaces wholesale auctions in Mediterranean clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of integrated pest management expertise with digitized pesticide record-keeping capability is filtering supplier eligibility across EU and Chinese regulatory frameworks. Orchard operators lacking certified IPM systems face exclusion from premium retail placement regardless of fruit quality.
For Market Incumbents: Build cultivar development moats through exclusive partnerships with agricultural research institutions in climate-advantaged growing regions. Consolidate position by acquiring controlled-atmosphere storage capacity in port-proximate locations to extend shipping windows for export markets. Counter the threat of SAMR enforcement acceleration by pre-certifying integrated pest management systems ahead of competitor compliance timelines. For New Entrants and Emerging Players: Pursue white peach premiumization in Japanese and South Korean import channels where sugar-acid balance specifications command price premiums that justify specialized cultivation investments. Target online grocery direct-to-consumer pathways in urban China where last-mile refrigeration infrastructure maturation is compressing traditional wholesale markups. Enter through varietal differentiation contracts with chef-driven procurement programs in Barcelona and Milan that displace auction systems. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors operators with existing farm-level energy monitoring systems capable of meeting emerging carbon-accounting disclosure requirements. Long-term viability over the next decade rests on backward integration into cold-chain infrastructure rather than commodity cultivation exposure. Watch EU Green Deal pesticide reduction target acceleration as the inflection signal that will bifurcate certified IPM operators from excluded legacy orchards.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Pest Management Certification | SAMR GB 2763 compliance locks in Chinese retail placement eligibility against non-certified competitors. |
| Controlled-Atmosphere Storage Expansion | Dalian port-adjacent facilities extend European market access previously unreachable for Chinese stone fruit. |
| Chef-Driven Varietal Contracting | Barcelona and Milan restaurant procurement now covers thirty percent of Lleida cluster yellow peach volume. |
| Carbon Accounting System Integration | Farm-level energy monitoring meets emerging import jurisdiction supply chain emissions disclosure requirements. |
| Direct-to-Consumer Channel Development | Online grocery platforms bypass wholesale markups in urban China and North American metropolitan markets. |
Research Methodology
Initial hypotheses were tested against primary input from orchard operations managers, supermarket produce category buyers, cold-chain logistics coordinators, and export packing facility directors and refined through secondary validation. Orchard pesticide application records, SAMR GB 2763 enforcement bulletins, EU Green Deal Farm to Fork strategy documents, and FDA Food Safety Modernization Act traceability guidance supplied triangulation anchors. Bottom-up cultivation area and yield estimates were cross-checked against top-down import customs data and retail scanner volumes.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeled across variety type, ripeness specification, packaging format, and distribution channel dimensions. CAGRs were derived from trend extrapolation of historical trade flows adjusted for regulatory enforcement intensity and infrastructure buildout schedules. Hyperspectral imaging adoption curves and integrated pest management certification penetration rates served as technology and compliance input variables.
Macroeconomic conditions sit as an overlay; deviation in fuel costs, ocean freight rates, or agricultural labor availability would shift the trajectory of export competitiveness for distant markets. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and cold-chain infrastructure deployment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
Global Fruit Pomace Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
Sudachi Market
Fruits and Vegetables
Dried Berries Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
Egypt Fruits and Vegetables Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
Mulberry Market
Fruits and Vegetables
Europe Freeze-Dried Fruits and Vegetable Market
Fruits and Vegetables
Yellow Oyster Mushroom Market
Fruits and Vegetables
Global Shiitake Mushroom Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
Oman Fruits and Vegetables Market