
 Apple Concentrate Market | 2026-2036
Apple Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Apple Concentrate Market Analysis
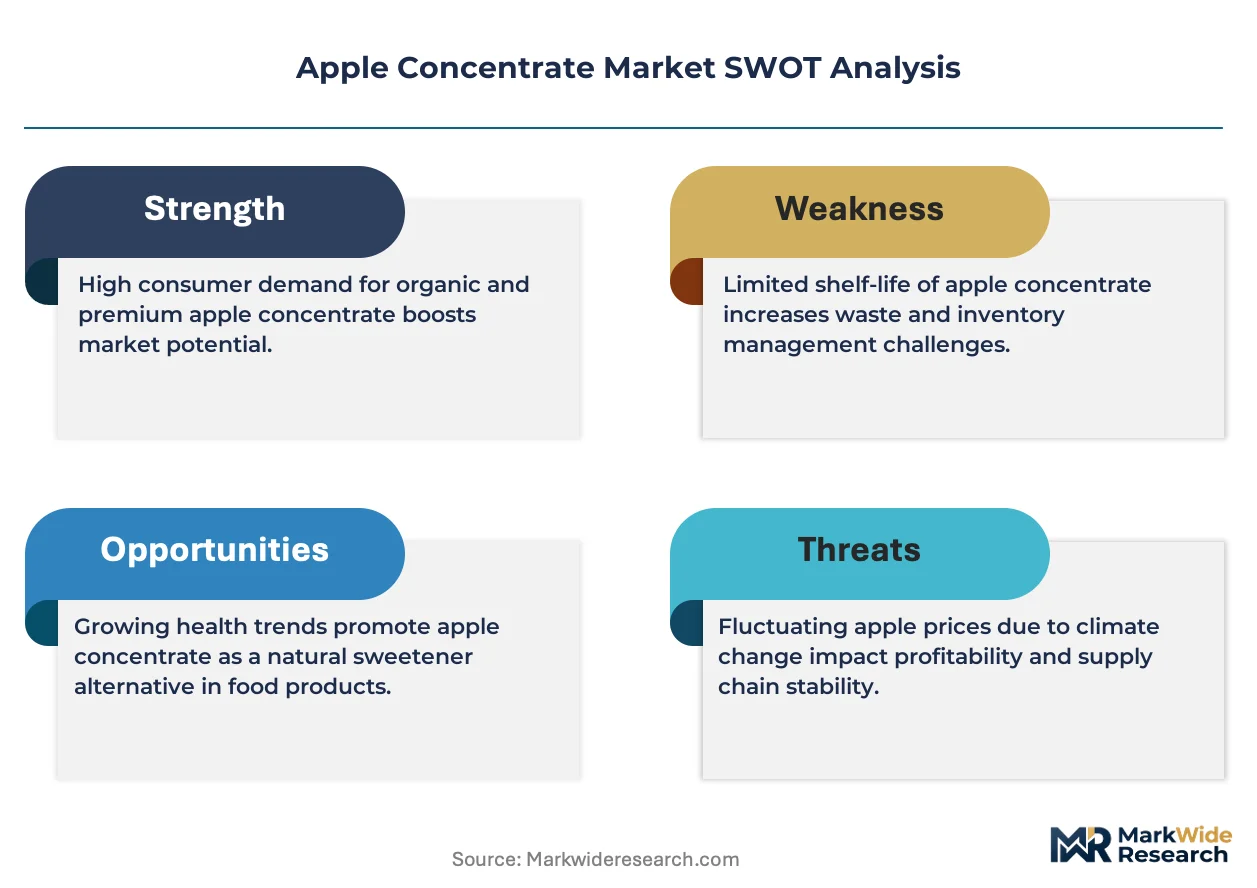
The gap between premium organic apple concentrate and commodity-grade conventional supply is realigning procurement strategies across European and North American beverage supply chains. Döhler leverages its integrated flavor systems portfolio to anchor long-term contracts with multinational drink brands. Tree Top Inc. sustains its position through backward integration into Pacific Northwest orchard operations and controlled-atmosphere storage infrastructure. Agrana Juice GmbH competes on geographic density, operating processing facilities proximate to Austrian and Hungarian growing regions.
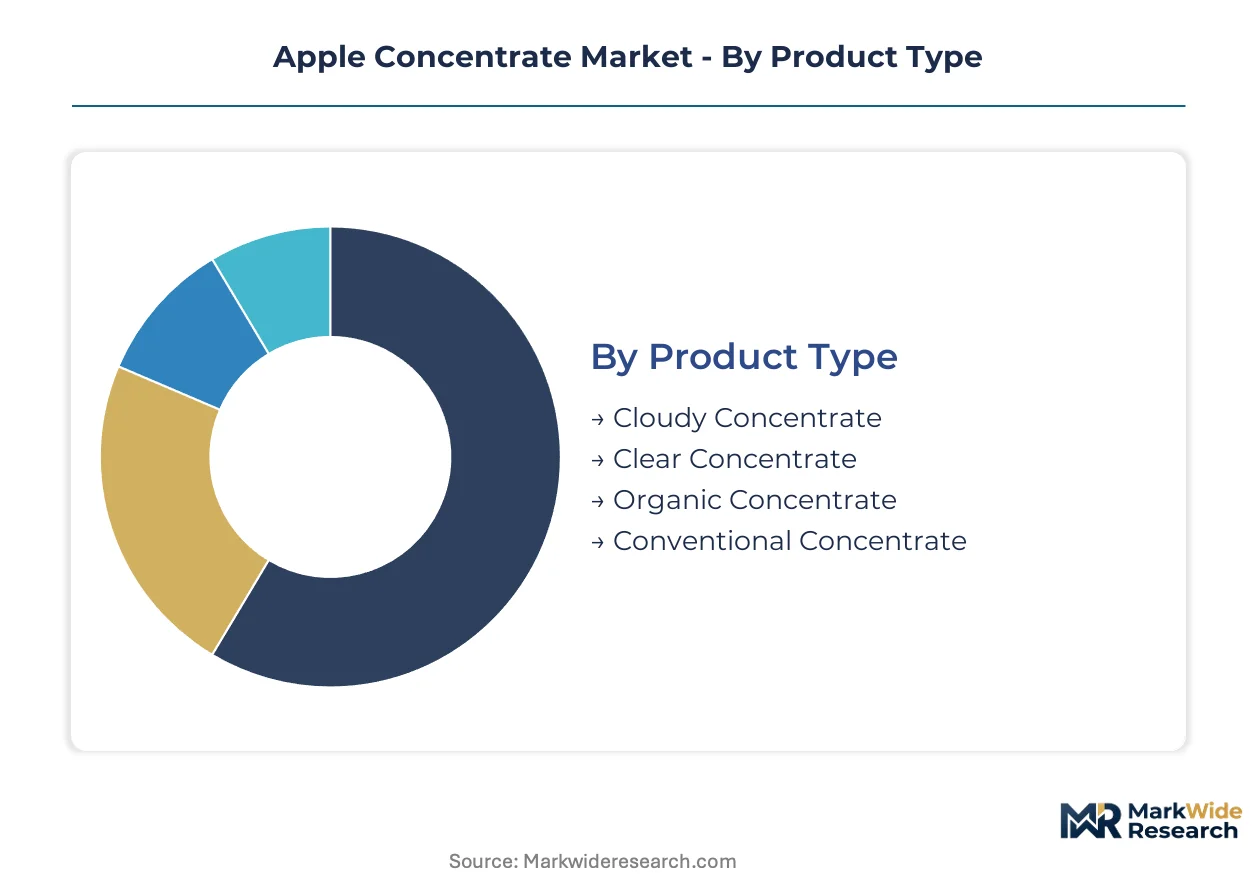
Apple concentrate is the partially dehydrated liquid extract produced by evaporating water from pressed apple juice to approximately 70-72 degrees Brix soluble solids, yielding a viscous, shelf-stable intermediate used for reconstitution into beverages, confectionery fillings, and sauce bases. Cloudy concentrate retains pectin and starch particulates preferred in premium juice applications where mouthfeel differentiation commands price premiums, while clear concentrate dominates high-volume carbonated soft drink formulations where clarity and color stability are functional requirements. The organic concentrate segment within product type classifications draws tightening procurement competition as beverage brands reformulate clean-label portfolios, whereas conventional concentrate maintains volume leadership through cost structures aligned with private-label retail positioning.
The FDA governs apple concentrate under 21 CFR standards for juice safety and Hazard Analysis Critical Control Point protocols, while the EU Green Deal and REACH frameworks impose escalating due diligence on agricultural chemical residues entering European processing channels. Organic certification bodies including USDA National Organic Program and EU organic regulations create dual-track compliance costs that filter supplier participation and reshape margin distribution between certified and conventional handlers. Stakeholders must monitor evolving pesticide maximum residue limits and carbon border adjustment mechanisms that threaten to reroute trade flows from established supply origins.
Market Dynamics
EU Green Deal sustainability mandates are compressing pesticide residue thresholds for imported fruit derivatives, forcing beverage manufacturers to requalify their concentrate sourcing networks and recalibrate formulation specifications around certified organic supply lines.
Growth Catalysts
- Clean-label beverage reformulation:Major drink brands are stripping artificial flavors from their portfolios, creating pull-through demand for natural apple concentrate as a flavor carrier and colorant in carbonated and still beverages.
- REACH chemical due diligence escalation:European processors now face mandatory disclosure requirements for agricultural chemical residues, advantaging suppliers with integrated organic certification and traceable orchard partnerships.
- German bottling cluster expansion:Central European processing capacity for organic concentrate formulations is concentrating demand in Germany, drawing supply chain investment toward Rhine-Main logistics corridors.
Market Restraints
- Apple input cost volatility:Fresh apple prices fluctuate with Pacific Northwest and Polish growing season weather, compressing margins for processors without captive orchard supply or long-term purchase agreements.
- Organic certification dual-track compliance:USDA National Organic Program and EU organic regulations impose parallel audit and documentation burdens that filter supplier participation and elevate administrative overhead.
- White grape juice concentrate substitution:Cost-sensitive beverage formulators in private-label retail channels are substituting apple with white grape concentrate where flavor profile permits, capping price elasticity in commodity-grade segments.
Strategic Opportunities
- Carbonated soft drink natural flavoring:Clear concentrate specifications are penetrating high-volume CSD formulations as brands eliminate synthetic additives, opening volume contracts previously served by artificial flavor systems.
- Confectionery and sauce base diversification:Viscous concentrate intermediates are displacing corn syrup and artificial flavoring in premium confectionery fillings and prepared sauce applications.
- Cloudy concentrate mouthfeel differentiation:Pectin-retaining cloudy variants command price premiums in premium juice applications where texture and visual opacity signal authenticity to discerning consumers.
Industry Challenges
- Hazard Analysis Critical Control Point protocol complexity:FDA 21 CFR juice safety mandates require continuous monitoring and documentation across evaporation and aseptic filling operations, elevating technical staffing requirements.
- Controlled-atmosphere storage capex intensity:Seasonal apple harvest concentration demands substantial investment in oxygen-regulated warehousing to maintain raw material quality across processing campaigns.
- Carbon border adjustment mechanism uncertainty:Emerging EU trade instruments threaten to reroute established supply flows from non-EU origins, complicating long-term contract negotiations and logistics planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apple Concentrate Market |
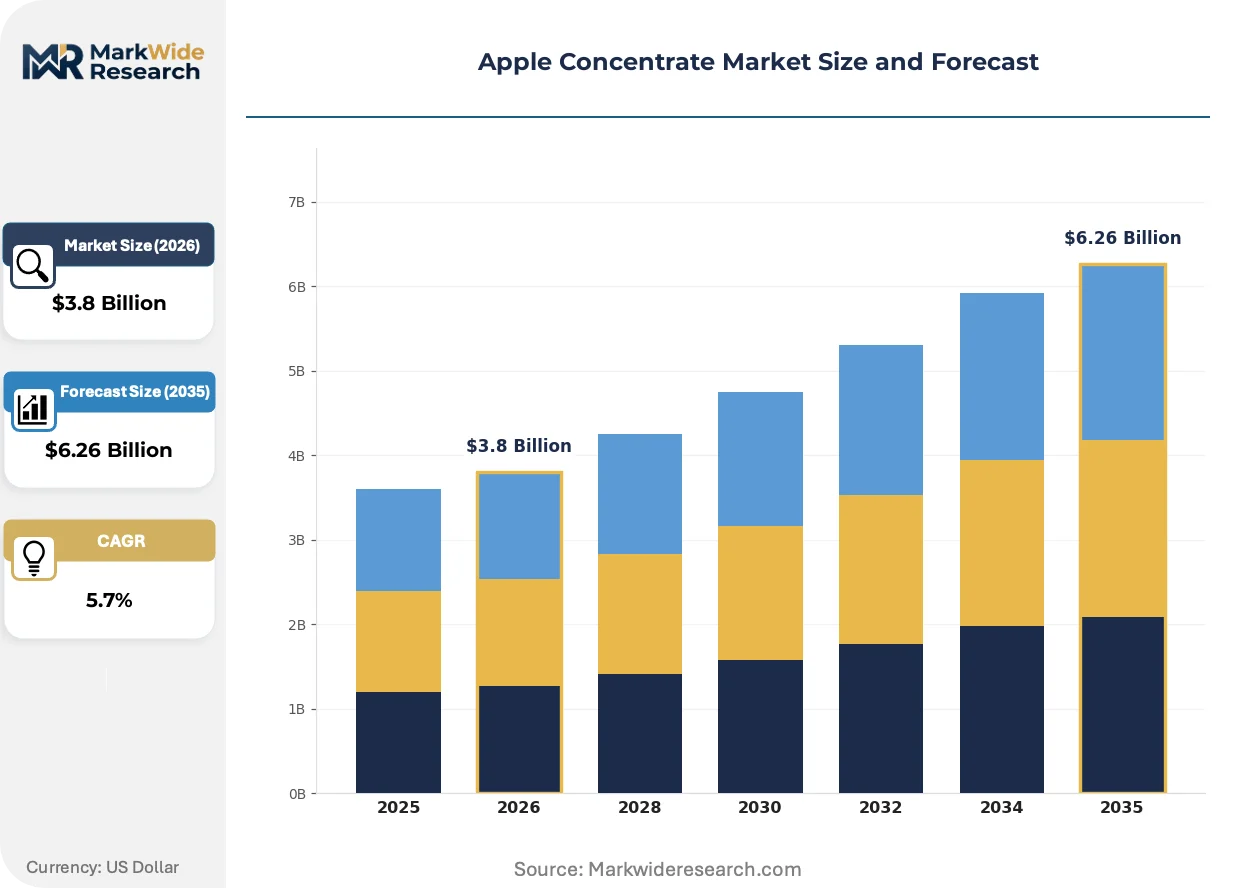
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloudy Concentrate, Clear Concentrate, Organic Concentrate, Conventional Concentrate End User: Food & Beverage Industry, Cosmetics, Pharmaceuticals, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Packaging Type: Glass Bottles, Plastic Containers, Tetra Paks, Drums |
| Companies Covered | Tree Top Inc., Agrana Juice GmbH, Döhler, Welch Foods Inc., Ingredion Incorporated, Hermann Pfanner Getranke GmbH, Lemon Concentrate, Austrian Juice, Süddeutsche Zuckerrübenverwertungs-Genossenschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apple Concentrate Market Emerging Trajectories
Processing technology and regulatory disclosure requirements are reshaping how apple concentrate is manufactured, certified, and procured across beverage and food manufacturing channels.
Membrane filtration systems for pectin and starch separation are converging with precision evaporation controls to enable real-time Brix adjustment during concentrate production. Mid-sized processors in Austria and Hungary are adopting these integrated lines to switch between cloudy and clear specifications on single production campaigns. This flexibility is converging with contract manufacturing demand from brands seeking SKU proliferation without dedicated capital investment.
EU Green Deal Farm-to-Fork strategy mandates are tightening maximum residue limits for pesticides in imported fruit derivatives entering European processing channels. Processors must now demonstrate supply chain due diligence through documented orchard partnerships and third-party testing protocols. Organic concentrate handlers with established certification infrastructure are capturing disproportionate contract flow as conventional suppliers face requalification delays.
Beverage brand technical buyers are consolidating supplier relationships around integrated flavor system providers capable of delivering concentrate alongside complementary natural extracts and colorants. Long-term partnership models are displacing spot-market purchasing for premium formulations. This concentration is most visible in German and Austrian bottling corridors where multinational drink brands have co-located technical development facilities with concentrate suppliers.
Apple Concentrate Market Segmentation
Apple concentrate procurement patterns diverge sharply across product specifications, end-use applications, and channel structures. Understanding these fault lines reveals where margin pools concentrate and which supply configurations command sustainable pricing power.
Product Type:
Buyers differentiate primarily by clarity requirements and certification status, with formulation constraints dictating concentrate selection.
- Cloudy Concentrate:Retains pectin and starch particulates that deliver opacity and mouthfeel differentiation. Premium juice brands in Germany and Austria specify cloudy variants where visual authenticity signals quality to discerning consumers.
- Clear Concentrate:Membrane-filtered to remove suspended solids, yielding transparent, color-stable intermediates. High-volume carbonated soft drink manufacturers across European bottling corridors specify clear concentrate for formulations where clarity and shelf stability are non-negotiable.
- Organic Concentrate:USDA National Organic Program and EU organic regulations impose dual-track compliance costs that filter supplier participation.
- Conventional Concentrate:Cost structures aligned with private-label retail positioning maintain volume leadership through established procurement networks.
Conventional concentrate leads volumes today; organic concentrate is gaining share fastest.
End User:
Application-specific formulation requirements create divergent demand profiles across processing industries.
- Food & Beverage Industry:Beverage manufacturers strip artificial flavors from portfolios, creating pull-through demand for natural apple concentrate as flavor carrier and colorant in carbonated and still beverages.
- Cosmetics:Natural fruit extracts displace synthetic compounds in premium skincare formulations.
- Pharmaceuticals:Excipient applications require documented purity grades and traceable supply chains.
- Nutraceuticals:Functional food manufacturers incorporate concentrate into supplement matrices where polyphenol content supports health positioning.
Food and beverage dominates procurement volumes; nutraceuticals demonstrate the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects buyer scale, technical requirements, and inventory velocity needs.
- Online Retail:E-commerce platforms serve small-batch food manufacturers and regional beverage startups seeking flexible order quantities without long-term contract commitments.
- Supermarkets:Private-label retail channels drive commodity-grade concentrate volumes through established procurement relationships with major processors.
- Specialty Stores:Gourmet and organic food retailers source certified organic concentrate for premium product lines.
- Direct Sales:Multinational beverage brands negotiate long-term partnership models with integrated flavor system providers, displacing spot-market purchasing for premium formulations.
Direct sales anchor value capture; online retail is expanding most quickly among emerging brands.
Packaging Type:
Packaging economics and shelf stability requirements shape procurement decisions across supply chain configurations.
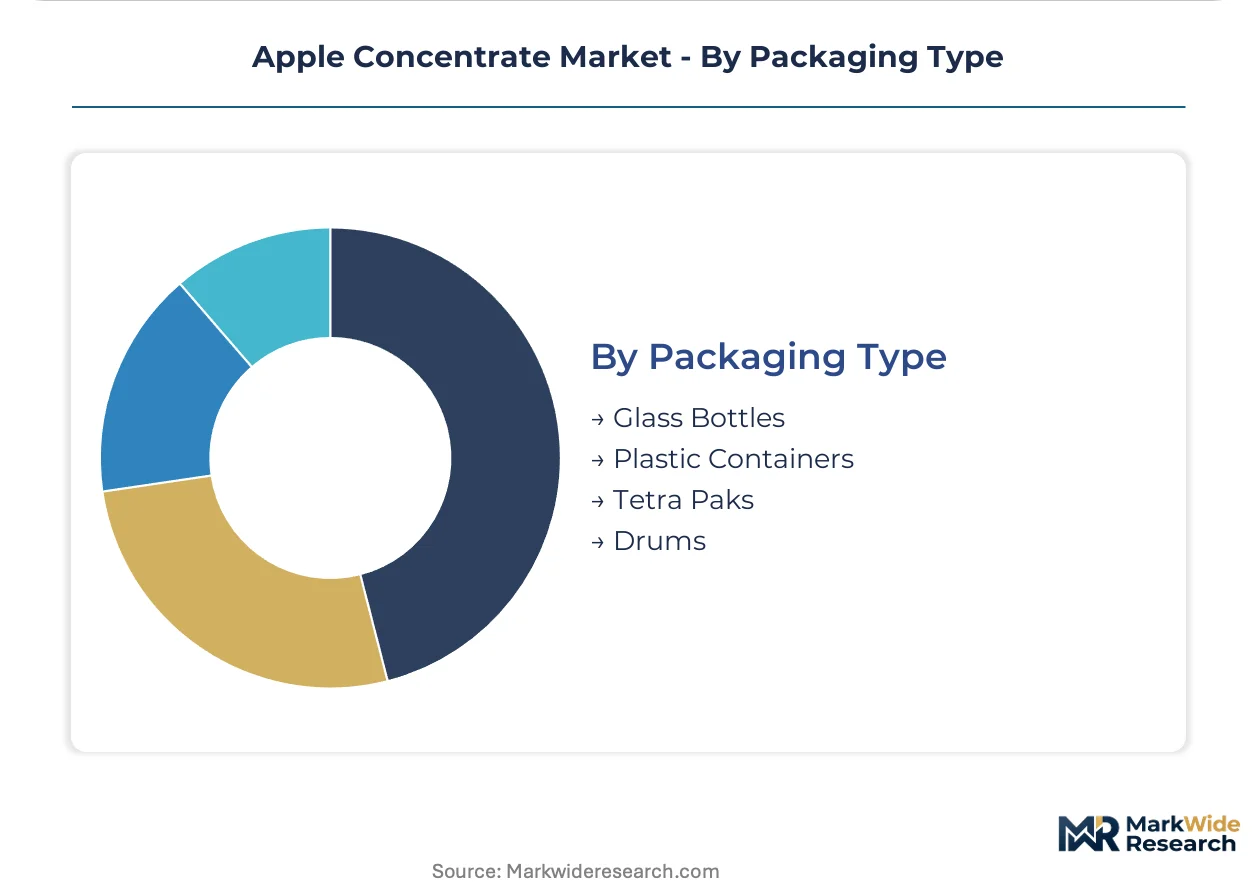
- Glass Bottles:Premium positioning and chemical inertness support high-value organic concentrate segments where contamination risk must be minimized.
- Plastic Containers:Cost efficiency and logistics flexibility dominate high-volume conventional concentrate movements.
- Tetra Paks:Aseptic packaging technology extends shelf life for international shipments from Pacific Northwest and Polish processing origins.
- Drums:Industrial-scale bulk packaging serves food manufacturers with dedicated reconstitution and blending facilities.
Drums command the largest volume share; Tetra Paks are climbing the fastest in export-oriented supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing expertise concentrates in Central European orchard belts and Pacific Northwest growing regions, with technical talent clustering around integrated juice extraction and concentrate evaporation facilities. Regional procurement patterns diverge sharply between organic-certified supply corridors and conventional volume channels.
Germany
Organic concentrate demand from beverage reformulation programs pulls supply through Rhine-Main logistics corridors. EU Green Deal Farm-to-Fork mandates tighten residue thresholds for imported fruit derivatives entering processing facilities near Frankfurt and Mainz. Bavarian bottling clusters expand contract manufacturing capacity for multinational drink brands seeking integrated flavor system partnerships.
United States
Pacific Northwest orchard operations anchor North American supply through controlled-atmosphere storage infrastructure in Washington State. FDA 21 CFR juice safety protocols and Hazard Analysis Critical Control Point mandates govern evaporation and aseptic filling operations across processing plants. Yakima Valley concentrate facilities leverage backward integration into captive apple supply to manage input cost volatility.
Austria
Geographic density of processing facilities proximate to Hungarian and domestic growing regions supports just-in-time concentrate production for Central European beverage manufacturers. EU organic regulations and REACH chemical due diligence requirements filter supplier participation through documented orchard partnerships. Lower Austria processing corridors capture disproportionate contract flow from German bottling clusters seeking certified organic supply lines.
Poland
Fresh apple price fluctuations from growing season weather compress margins for processors without long-term purchase agreements or captive orchard supply. National agricultural quality standards intersect with EU pesticide residue limits for fruit derivatives entering European processing channels. Mazovia and Greater Poland regions concentrate evaporator capacity serving private-label retail channels across the continent.
China
Domestic beverage manufacturers strip artificial flavors from portfolios, creating pull-through demand for natural concentrate as flavor carrier in carbonated formulations. National food safety standards and GB quality benchmarks govern juice processing and concentrate production for internal consumption and export. Shandong Province processing clusters expand evaporation capacity to serve reformulation programs across Asian beverage markets.
Apple Concentrate Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a market structure that fragments between integrated orchard-processor operations and contract manufacturing specialists. Tiered competitive positioning separates handlers with captive supply from those dependent on spot-market apple procurement. Three archetypes dominate: backward-integrated orchard operators, geographic-density regional processors, and integrated flavor system providers. Competitive intensity concentrates on long-term contract anchoring and organic certification infrastructure rather than price alone.
Within the integrated flavor system tier, Döhler exemplifies the partnership-model approach with multinational beverage brands. Tree Top Inc. occupies a position representing Pacific Northwest backward integration into orchard operations and storage infrastructure. Agrana Juice GmbH anchors the geographic-density archetype through Austrian and Hungarian processing proximity to growing regions. These three patterns illustrate how procurement consolidation around technical development co-location and certified supply chains is reshaping vendor selection criteria.
| Leading Market Players |
|---|
| Tree Top Inc. |
| Agrana Juice GmbH |
| Döhler |
| Welch Foods Inc. |
| Ingredion Incorporated |
| Hermann Pfanner Getranke GmbH |
| Lemon Concentrate |
| Austrian Juice |
| Süddeutsche Zuckerrübenverwertungs-Genossenschaft |
| Others |
Supply Flow & Price Mechanics
Multinational beverage brand procurement offices concentrate contract negotiations around integrated flavor system providers, anchoring premium pricing to long-term partnership models that bundle concentrate supply with technical development co-location. This buyer concentration elevates contract-based long-term offtake as the dominant pricing structure, while spot-market purchasing persists only in commodity-grade conventional segments serving private-label retail channels.
Pricing Analysis
Service bundling separates integrated flavor system contracts from unbundled commodity concentrate transactions. Three-tier pricing structure across premium organic, standard conventional, and economy private-label levels reflects certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from white grape juice concentrate substitution in cost-sensitive formulations. Private-label retail channels exhibit highest price sensitivity, while multinational beverage brands demonstrate lowest sensitivity due to reformulation-driven quality requirements.
Supply Chain Analysis
Dual-sourcing mandates from EU beverage manufacturers require qualified organic concentrate suppliers in both Austria-Hungary corridor and Pacific Northwest growing regions. Raw material dependencies center on fresh apple supply from Washington State, Polish growing regions, and Shandong Province processing clusters. Single-source vulnerability concentrates in controlled-atmosphere storage infrastructure for seasonal harvest management. Distribution runs through Rhine-Main logistics corridors serving German bottling clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in organic certification infrastructure as EU Green Deal residue thresholds filter conventional supplier participation and concentrate premium-tier contract flow among certified handlers.
For Market Incumbents: Cement long-term anchoring through backward integration into captive orchard supply in Pacific Northwest and Austrian growing regions. White grape juice substitution threat demands defensive certification investment to maintain premium positioning against alternative natural flavor carriers. For New Entrants and Emerging Players: Membrane filtration technology for real-time Brix adjustment offers entry wedge into contract manufacturing demand from brands seeking SKU proliferation without dedicated capital investment. Target mid-sized Austrian and Hungarian processors as most penetrable geography. Lead with flexible production line capabilities as go-to-market angle. For Investors and Strategic Acquirers: Integrated beverage conglomerates are the most active acquirer in this space, pursuing flavor system consolidation to secure concentrate supply alongside complementary natural extracts. Long-term viability hinges on carbon border adjustment mechanism resolution and organic certification infrastructure scalability. Watch EU pesticide maximum residue limit enforcement intensity as inflection signal for trade flow rerouting.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Operations | Tree Top's Yakima Valley captive supply model reduces input cost volatility exposure. |
| Organic Certification Infrastructure Investment | Agrana's documented Hungarian orchard partnerships capture disproportionate EU contract flow. |
| Integrated Flavor System Partnership | Döhler's technical co-location with German bottling clusters displaces spot-market purchasing. |
| Membrane Filtration Technology Adoption | Austrian processors switch between cloudy and clear specifications on single production campaigns. |
| Rhine-Main Logistics Corridor Expansion | Central European processing capacity concentrates demand drawing supply chain investment. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured concentrate procurement managers at multinational beverage brands, technical directors at integrated flavor system providers, orchard operations managers in Washington State and Austrian growing regions, and regulatory compliance officers navigating EU Green Deal Farm-to-Fork mandates. Secondary validation drew from FDA 21 CFR juice safety filings, EU REACH chemical disclosure databases, USDA National Organic Program certification records, and customs trade data for apple concentrate movements. Bottom-up concentrate production estimates triangulated against top-down beverage formulation demand projections.
Segment-weighting across product type, end-use application, and distribution channel dimensions shaped volume and value outputs across the projection horizon. Cloudy versus clear concentrate specifications, organic versus conventional certification status, and direct sales versus retail channel structures formed core segmentation layers. CAGRs derived from historical price trajectory analysis and procurement pattern elasticity modeling. Forecast inputs incorporated EU pesticide maximum residue limit enforcement schedules and carbonated soft drink reformulation program timelines.
The model holds under stable EU Green Deal implementation pace and Pacific Northwest growing season weather norms; deviation in carbon border adjustment mechanism activation or Polish apple harvest volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Spain Table Grape Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Fresh Peaches Market
Fruits and Vegetables
Global Dehydrated Onion Flakes Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
Global Fresh Fruits and Vegetables Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Passion Fruit Extract Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
Dragon Fruit Market
Fruits and Vegetables
Rosehip Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Banana Puree Market