
 Plums and Sloes Market | 2026-2036
Plums and Sloes Market Size, Share, and Industry Trends Forecast 2026-2036
Plums and Sloes Market Analytics
Buyer concentration among large-scale food manufacturers is hardening as processors negotiate multi-year supply agreements for dried plum and prune ingredients. Sun-Maid Growers of California leverages its cooperative structure to sustain volume commitments with institutional buyers. Dole Food Company anchors its position through backward integration into Central American plum cultivation. Blue Diamond Growers competes by extending its orchard management expertise into stone fruit diversification.
Plums and sloes comprise stone fruit species within the genus Prunus, characterized by a single hard endocarp surrounding a seed and flesh with soluble sugar content typically ranging from 10-20% at commercial harvest. The primary commercial purpose centers on fresh consumption, dehydration into prunes, and extraction for juice concentrates and purees. Fresh plums dominate value capture in North American retail channels where premium varietal branding commands shelf price separation. Dried plums sustain margin pools through industrial bakery and snack bar formulations where moisture retention and fiber content drive ingredient specification. Plum juice occupies a narrower but defensible niche in functional beverage portfolios targeting digestive health positioning.
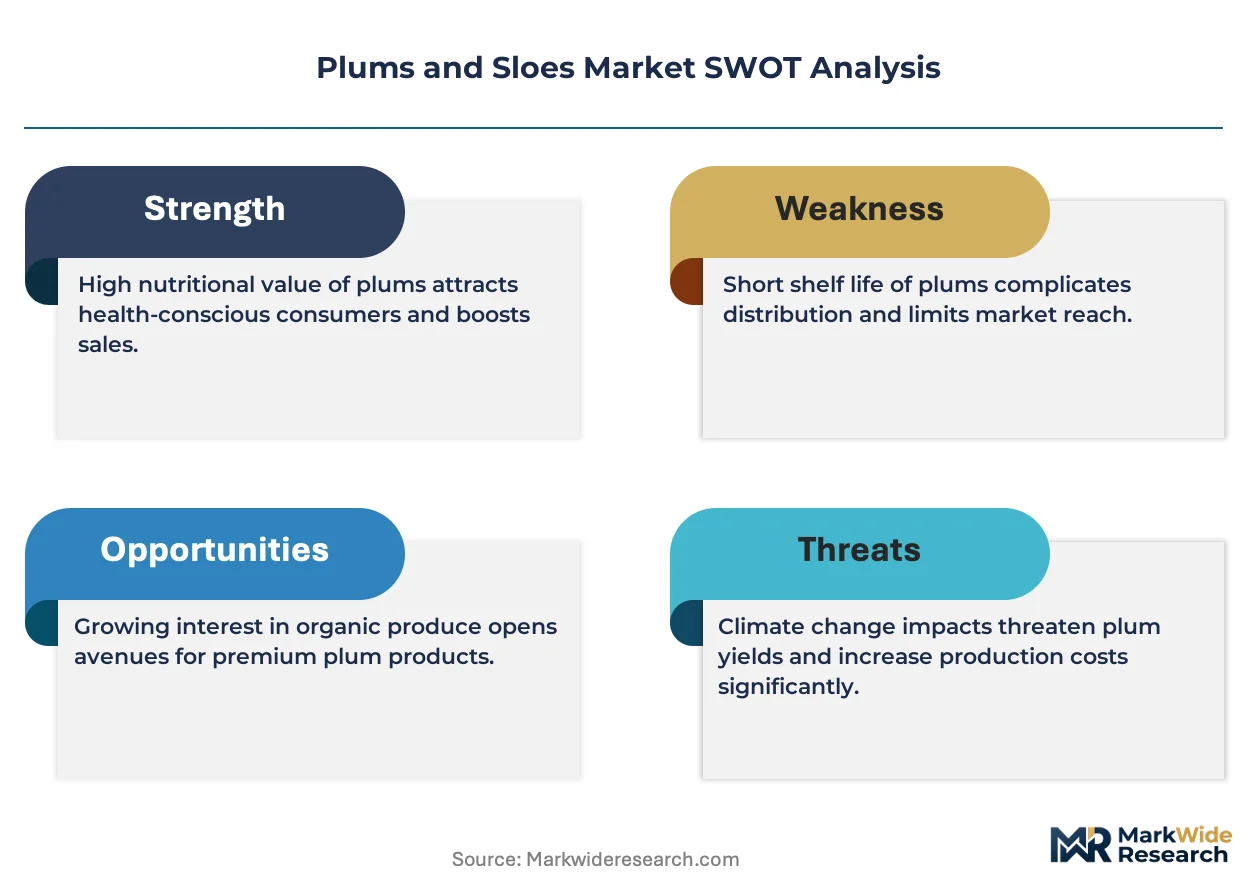
USDA grading standards and FDA food safety rules govern interstate commerce and import tolerances for stone fruit products in the United States. EFSA maximum residue limits and EU organic certification requirements shape market access for Mediterranean and South American exporters serving European processors. Stakeholders must monitor evolving pesticide approval withdrawals and water usage restrictions in California's Central Valley, where irrigation scarcity threatens orchard productivity and supply continuity.
Market Dynamics
Food industry procurement consolidation is compressing supplier margins and forcing processors into multi-year volume commitments with penalty clauses for shortfall. Large manufacturers now demand backward integration proof and residue testing documentation before contract award.
Growth Catalysts
- EFSA MRL tightening:Stricter pesticide residue limits for stone fruit imports are accelerating orchard certification upgrades across Mediterranean suppliers.
- Functional food demand:German consumers are driving antioxidant-rich dried plum formulations into bakery and snack bar portfolios.
- Dehydration technology:Advanced low-temperature drying processes are preserving polyphenol content and extending shelf stability for industrial ingredients.
Market Restraints
- Input cost volatility:Irrigation water scarcity in California's Central Valley is threatening orchard productivity and supply continuity.
- Supply concentration risk:California and Chile dominate prune processing capacity, creating geographic vulnerability to climate events.
- Regulatory friction:EU organic certification requirements impose multi-year conversion timelines that lock out conventional growers.
Strategic Opportunities
- Underpenetrated geography:China's domestic prune consumption remains below per-capita levels seen in Western Europe, offering expansion potential.
- Emerging application:Plum-derived prebiotic fibers are entering digestive health supplements targeting microbiome formulations.
- Technology convergence:Blockchain traceability combined with satellite irrigation monitoring is enabling premium pricing for verified sustainable orchards.
Industry Challenges
- Skill gap in orchard management:Experienced pruners and irrigation specialists are aging out of California's Central Valley workforce faster than training programs replace them.
- Capex intensity for compliance:Residue testing laboratories and cold chain upgrades require capital deployment that smaller cooperatives struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plums and Sloes Market |
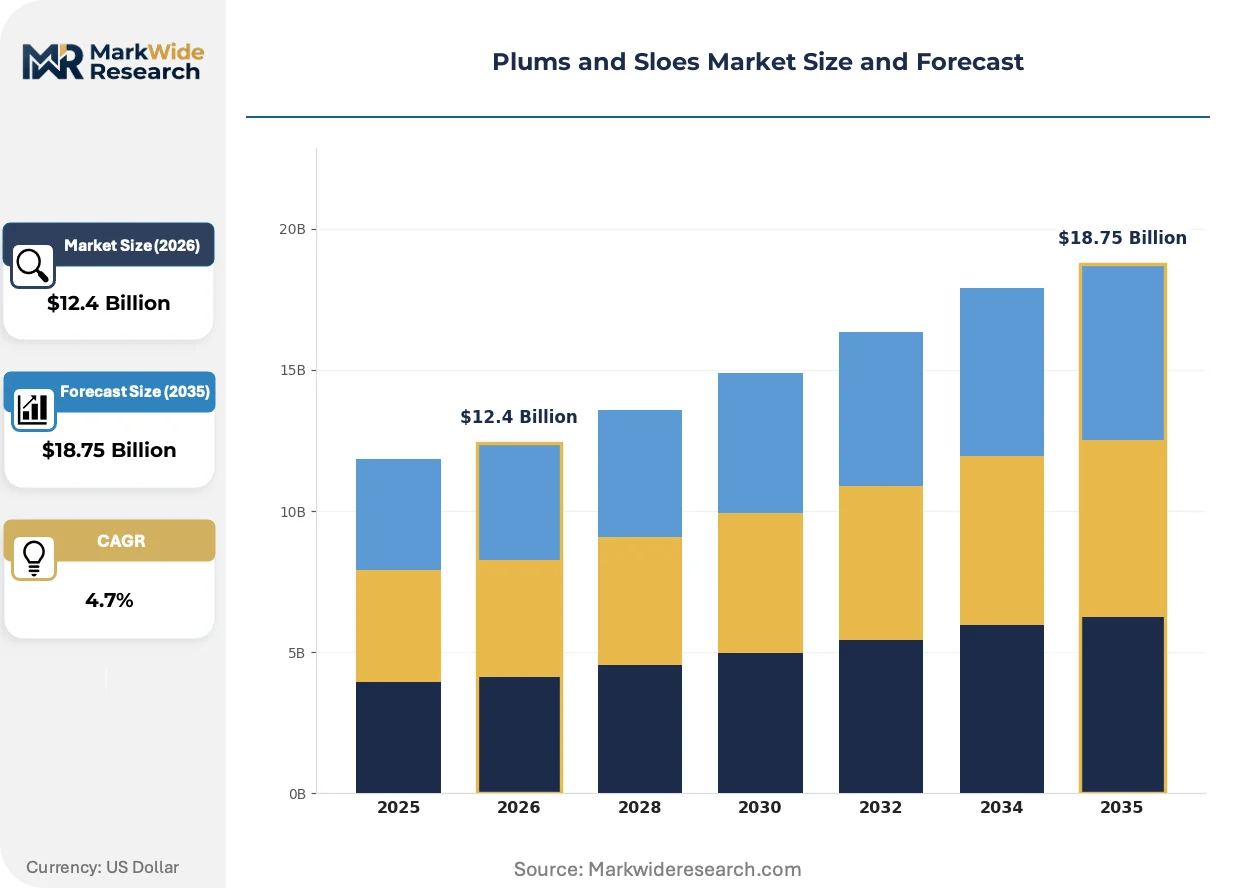
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Plums, Dried Plums, Plum Juice, Plum Jam End Use: Food Industry, Beverage Industry, Culinary Use, Confectionery Distribution Channel: Online Retail, Supermarkets, Grocery Stores, Farmers Markets Packaging Type: Bulk Packaging, Retail Packaging, Glass Jars, Pouches |
| Companies Covered | Sun-Maid Growers of California, Fresh Del Monte Produce, Dole Food Company, Sunkist Growers, Driscoll's, Blue Diamond Growers, Pandol Brothers, Grimmway Farms, California Dried Plum Board, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plums and Sloes Market Evolving Landscape
Processing technology and procurement protocols are converging to reshape how plum ingredients move from orchard to formulation. Quality verification systems and supply chain transparency tools are becoming competitive differentiators.
Controlled-atmosphere storage technology is extending fresh plum marketing windows by 6-8 weeks beyond traditional limits. Retail chains in Germany and France are adopting these systems to reduce shrinkage and maintain varietal consistency. This capability is modularizing regional sourcing strategies by reducing dependency on staggered harvest geographies.
EFSA's evolving maximum residue limits for stone fruit are forcing exporters to adopt integrated pest management protocols. Mediterranean suppliers must now document spray calendars and buffer zones to maintain market access. Dried plum processors serving EU industrial buyers are absorbing compliance costs and passing selective premiums to certified orchard partners.
Ingredient specification contracts are displacing spot market purchasing among North American bakery and snack manufacturers. Procurement teams now require multi-year supply guarantees with fixed-price escalators and third-party audit rights. This pattern is most visible in contract negotiations between California cooperatives and multinational food conglomerates seeking digestive health positioning for their fiber-enriched product lines.
Plums and Sloes Market Segmentation
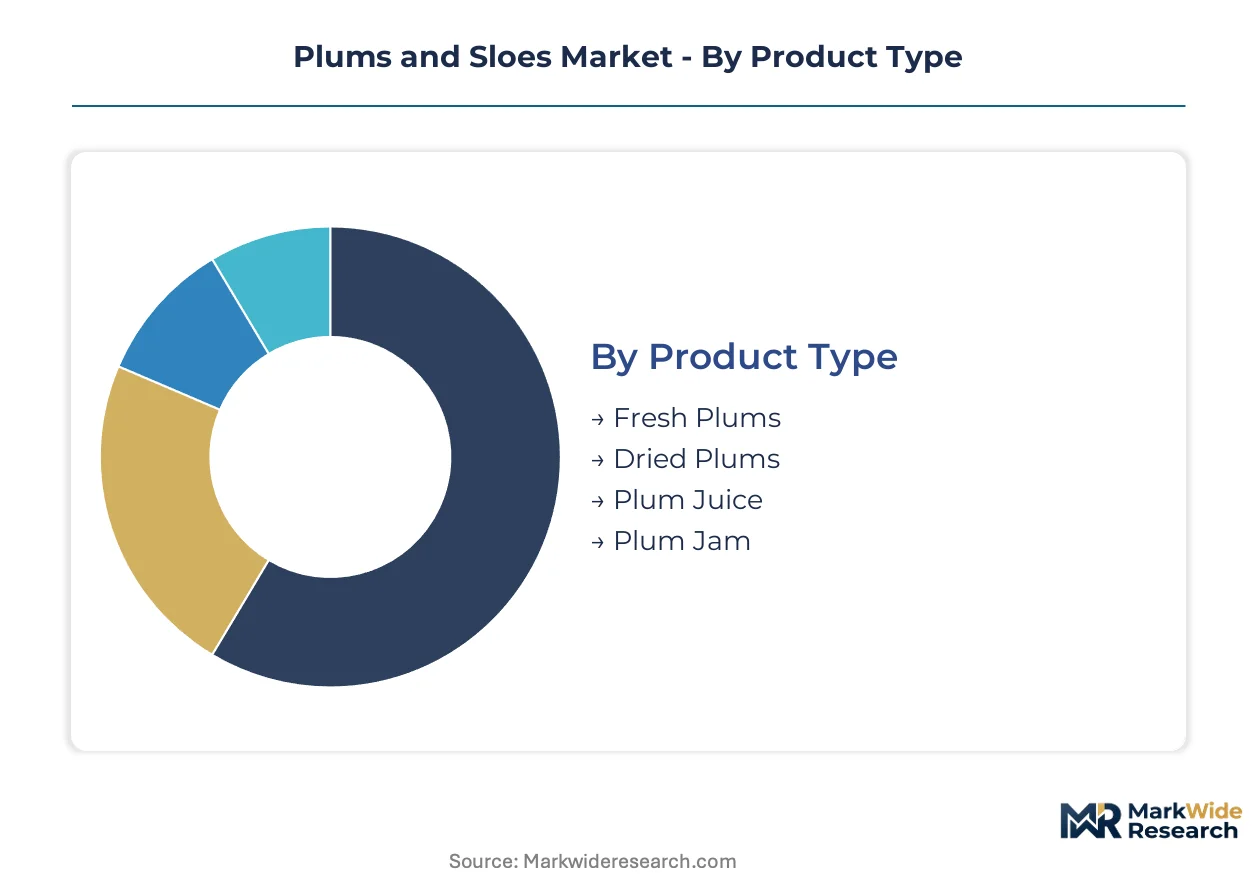
Plums and sloes flow through distinct commercial pathways where certification requirements, moisture specifications, and shelf stability demands reshape procurement patterns. Each segment carries unique regulatory burdens and margin structures that determine supplier viability.
Product Type:
EFSA maximum residue limits apply differentially across fresh versus processed forms, with dried plums facing the strictest pesticide documentation requirements and plum juice concentrated under beverage-grade HACCP protocols.
- Fresh Plums:Harvested at 10-20% soluble sugar content with firm flesh suitable for controlled-atmosphere storage extension. German retail chains demand varietal consistency and 6-8 week marketing windows, driving adoption of CA technology by French and Spanish exporters.
- Dried Plums:Low-temperature dehydration preserves polyphenol content for functional food positioning. Industrial bakery and snack bar manufacturers in Germany specify moisture retention and fiber content, locking suppliers into multi-year volume commitments with residue testing documentation.
- Plum Juice:Concentrated and pureed forms occupy narrow functional beverage niches targeting digestive health.
- Plum Jam:Traditional preservation with high sugar content serves retail and foodservice channels.
Leading the category by volume: Dried Plums. Growing fastest: Fresh Plums.
End Use:
Ingredient specification intensity varies sharply across customer types, with food manufacturers imposing the most rigorous backward integration proof and audit rights.
- Food Industry:Bakery, snack bar, and cereal manufacturers specify fiber content and moisture parameters. California cooperatives negotiate fixed-price escalators with penalty clauses for volume shortfall, absorbing EFSA compliance costs into contract premiums.
- Beverage Industry:Functional drink portfolios target digestive health positioning with plum-derived prebiotic fibers. Formulators require microbiome-specific documentation and third-party polyphenol verification.
- Culinary Use:Restaurants and foodservice operators source for sauce and compote applications.
- Confectionery:Chocolate and candy manufacturers use plum pieces and purees for flavor layering.
Dominant by procurement value: Food Industry. Expanding most quickly: Beverage Industry.
Distribution Channel:
Channel selection determines cold chain investment requirements and traceability system complexity, with direct-to-consumer platforms demanding the most granular batch documentation.
- Supermarkets:Controlled-atmosphere storage adoption by German and French chains reduces shrinkage and enables varietal consistency. These retailers now require blockchain traceability for premium stone fruit SKUs.
- Online Retail:Direct-to-consumer platforms for dried plum and functional ingredient sales. Packaging must withstand last-mile logistics while maintaining shelf stability claims.
- Grocery Stores:Traditional independent and small-chain retail with localized sourcing preferences.
- Farmers Markets:Direct producer sales with minimal processing and organic certification emphasis.
Highest throughput: Supermarkets. Steepest expansion trajectory: Online Retail.
Packaging Type:
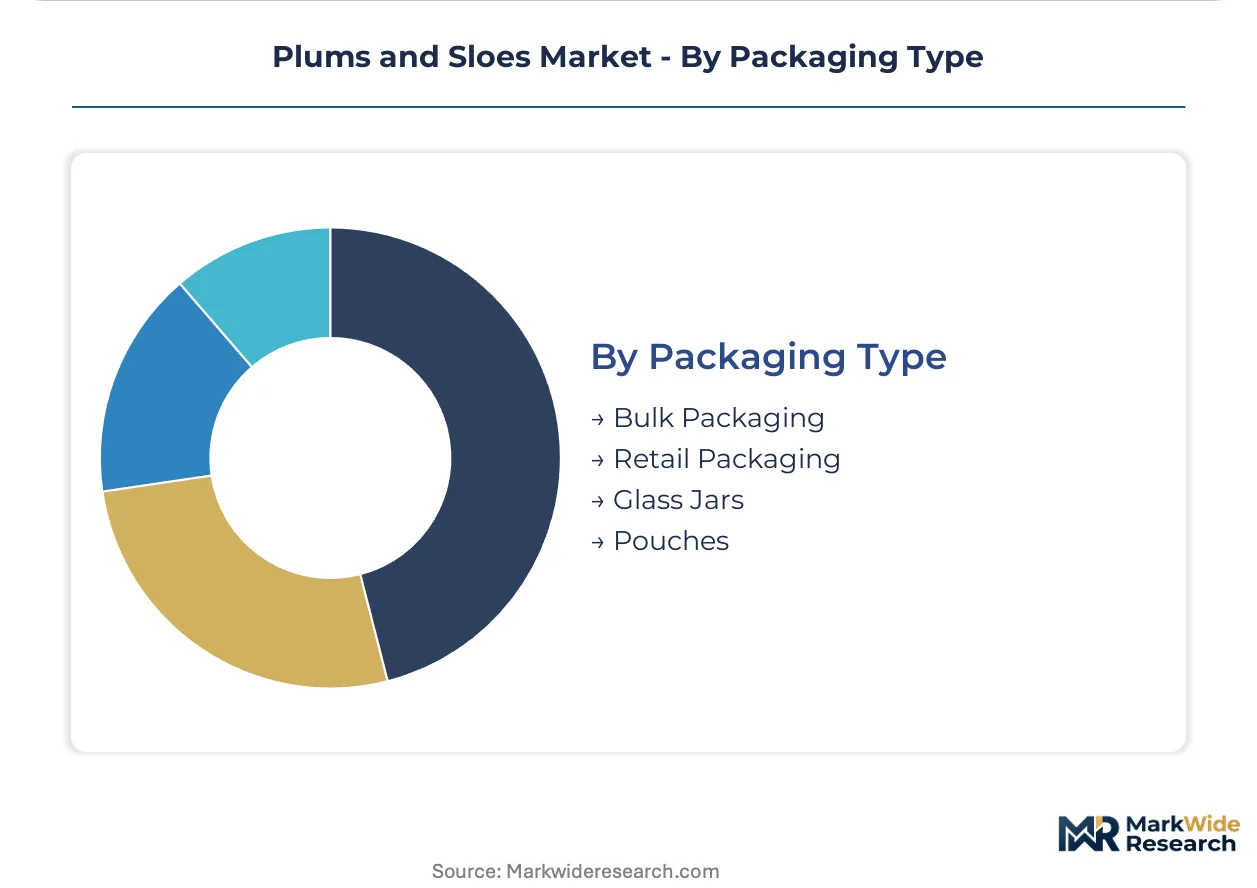
Packaging economics align with customer scale, with bulk formats serving industrial processors and retail formats absorbing compliance documentation costs.
- Bulk Packaging:Industrial totes and drums for bakery and beverage manufacturers. Residue testing documentation travels with each lot, satisfying EFSA audit requirements for EU-bound shipments.
- Retail Packaging:Consumer-facing formats with nutritional and origin labeling. German functional food positioning demands antioxidant content callouts and organic certification logos.
- Glass Jars:Traditional preservation format for jams and premium juices.
- Pouches:Flexible formats for snack and dried fruit applications.
Largest volume flow: Bulk Packaging. Gaining share fastest: Retail Packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional food demand concentrates in Germany where antioxidant-rich dried plum formulations command premium positioning. California's Central Valley anchors prune processing capacity while Chile diversifies Southern Hemisphere supply. Mediterranean exporters face EFSA compliance pressure.
United States
Industrial bakery and snack bar manufacturers specify fiber content and moisture parameters from California cooperatives. FDA food safety rules govern interstate commerce while USDA grading standards shape contract negotiations. The Central Valley faces irrigation scarcity threatening orchard productivity and supply continuity.
Germany
Retail chains adopt controlled-atmosphere storage to extend fresh plum marketing windows by 6-8 weeks. EFSA maximum residue limits tighten pesticide documentation requirements for Mediterranean suppliers. Supermarkets in Berlin and Munich now require blockchain traceability for premium stone fruit SKUs.
Chile
Counter-seasonal harvest timing fills Northern Hemisphere supply gaps for dried plum processors. The national agricultural service enforces export certification protocols aligned with EU organic requirements. Central Valley orchards around Santiago expand dehydration capacity to serve North American industrial buyers.
France
Fresh consumption dominates value capture through premium varietal branding in Paris and Lyon retail channels. ANSM monitors food contact material safety for packaging applications. Southwestern growing regions around Agen sustain traditional prune production with protected designation status.
Spain
Mediterranean suppliers upgrade integrated pest management protocols to maintain EU market access. The Ministry of Agriculture enforces spray calendar documentation and buffer zone requirements. Murcia and Valencia clusters invest in residue testing laboratories to satisfy EFSA audit demands.
Plums and Sloes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue functional ingredient specialization and sustainability certification. California cooperatives and Central American integrated growers dominate volume contracts with multi-year penalty structures. Three archetypes prevail: backward-integrated plantation operators, cooperative marketing associations, and diversified nut-and-stone-fruit processors. Competitive moves center on orchard technology licensing and cold chain infrastructure partnerships.
Among cooperative marketing structures, Sun-Maid Growers of California and Sunkist Growers exemplify volume-aggregation models that sustain institutional buyer relationships. Dole Food Company occupies a position representing backward-integrated plantation operators with Central American cultivation assets. Blue Diamond Growers sits within the diversified processor archetype, extending orchard management expertise across stone fruit categories.
| Leading Market Players |
|---|
| Sun-Maid Growers of California |
| Fresh Del Monte Produce |
| Dole Food Company |
| Sunkist Growers |
| Driscoll's |
| Blue Diamond Growers |
| Pandol Brothers |
| Grimmway Farms |
| California Dried Plum Board |
| Others |
Value Network & Pricing Analysis
Multi-year procurement contracts with penalty clauses for volume shortfall are forcing California cooperatives and Chilean processors into fixed-price escalators that absorb EFSA compliance costs. This buyer-driven specification intensity compresses supplier margins while rewarding orchard partners with residue testing documentation and backward integration proof.
Pricing Analysis
Volume contracts for industrial dried plum ingredients capture margin pools through fiber content and moisture specifications, while fresh plum retail commands shelf price separation via varietal branding. Three-tier pricing structure across premium organic, standard certified, and economy conventional levels reflects EFSA documentation burden and blockchain traceability investment. Pricing pressure stems from irrigation scarcity in California's Central Valley that threatens supply continuity and elevates input cost volatility. Food manufacturers exhibit lowest price sensitivity due to digestive health positioning premiums, whereas commodity traders in spot markets face acute margin compression.
Supply Chain Analysis
Experienced pruners and irrigation specialists aging out of California's Central Valley workforce faster than training programs replace them constrains orchard productivity expansion. Supply concentrates in California, Chile, and Mediterranean Spain, with dehydration capacity anchored in the Central Valley and Santiago clusters. Raw material flows draw from stone fruit orchards, sulfur dioxide for preservation, and cold chain infrastructure for fresh distribution. Single-source vulnerability to climate events in these geographic clusters elevates supply interruption risk. Distribution runs through cooperative marketing associations to industrial bakery and snack manufacturers, with residue testing documentation traveling with each bulk lot.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California irrigation scarcity and EFSA compliance timelines create a supply-constrained structure that sustains pricing power for certified orchard operators with documented integrated pest management protocols.
For Market Incumbents: Hedge geographic concentration risk by diversifying dehydration partnerships into Chilean Central Valley expansions and Murcia cluster upgrades. Lock multi-year volume commitments with German retail chains demanding blockchain traceability before competitor capacity comes online. Absorb residue testing laboratory capex through cooperative structures that pass selective premiums to certified partners. For New Entrants and Emerging Players: Enter via plum-derived prebiotic fiber specialization for digestive health supplement formulators seeking microbiome-specific documentation. China's domestic prune consumption gap offers the most penetrable geography, with per-capita levels trailing Western Europe significantly. Pursue sustainability certification convergence with satellite irrigation monitoring to capture premium pricing for verified orchards. For Investors and Strategic Acquirers: The window for entry favors backward-integrated Mediterranean operators with EFSA-aligned spray calendar documentation and buffer zone compliance. Long-term viability hinges on water rights security and organic conversion timeline completion. Watch California groundwater adjudication proceedings as the inflection signal for supply continuity reassessment.| Strategic Initiative | Industry Significance |
|---|---|
| Orchard Certification Upgrade | Integrated pest management documentation satisfies EFSA maximum residue limits for EU market access. |
| Dehydration Capacity Expansion | Low-temperature polyphenol preservation technology extends shelf stability for industrial ingredient contracts. |
| Blockchain Traceability Deployment | German supermarket chains now mandate batch-level documentation for premium stone fruit SKUs. |
| Cooperative Structure Consolidation | Volume aggregation models sustain institutional buyer relationships with penalty-clause contract terms. |
| Prebiotic Fiber Extraction Investment | Microbiome formulation demand opens functional supplement applications beyond traditional food channels. |
Research Methodology
USDA crop production reports, EFSA pesticide residue monitoring data, and FDA food safety compliance records formed the secondary backbone for supply-side quantification. Primary interviews with cooperative marketing directors, industrial bakery procurement managers, dehydration technology specialists, and German retail category buyers validated input cost structures and contract term evolution. Bottom-up orchard yield modeling and top-down import flow analysis were triangulated against customs documentation and cold chain logistics assessments.
Bottom-up volume builds aggregated individual orchard productivity across California, Chile, and Mediterranean growing regions, while top-down demand validation tracked procurement contract awards by multinational food manufacturers. Segmentation modeling spanned product type, end-use application, distribution channel, and packaging format dimensions across the projection horizon. CAGRs were derived from price-volume elasticity analysis and substitution coefficient estimation for dried plum ingredients in fiber-enriched formulations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under groundwater adjudication acceleration or EFSA maximum residue limit expansion to additional active ingredients. Material deviation in California irrigation allocation rulings or EU organic certification conversion timeline compression warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fruit Punnet Market
Fruits and Vegetables
South America Olive Market
Fruits and Vegetables
Date Fruit Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Dried Figs Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Morocco Fruits and Vegetables Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Asia-Pacific Sweet Potatoes Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
Colombia Fruits and Vegetables Market
Fruits and Vegetables
Raisins Market
Fruits and Vegetables
Fava Beans Market