
 Dried Apple Peel Market | 2026-2036
Dried Apple Peel Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Apple Peel Market Analytics
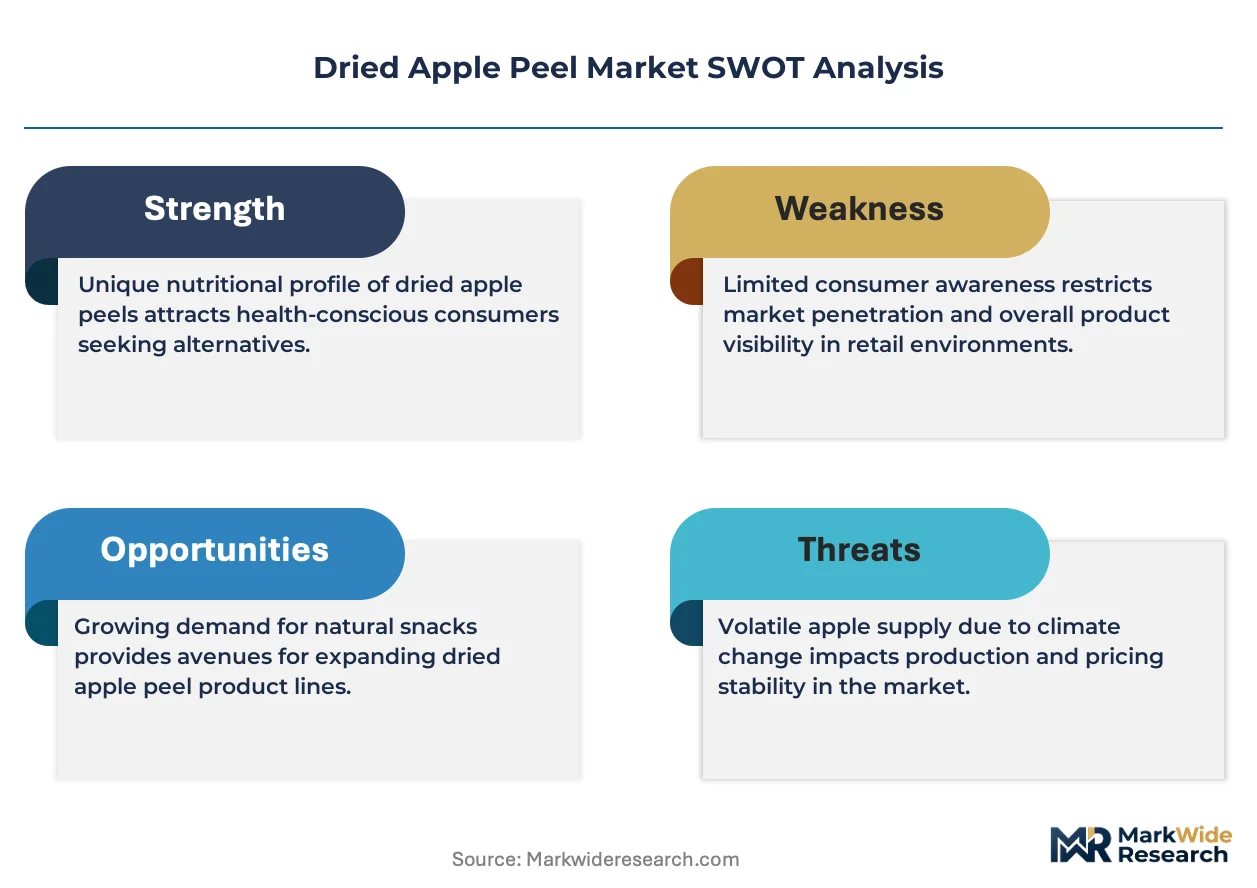
EU Green Deal circular-economy mandates for food waste valorization are pivoting European apple processors toward peel recovery systems. Agrana Beteiligungs-AG leverages its vertically integrated fruit ingredient network across Austria and Hungary to secure raw peel supply. Döhler GmbH anchors its position through beverage-industry formulation partnerships that specify standardized polyphenol content. Herbafood Ingredients GmbH specializes in pectin and fiber extraction, competing on technical specification breadth rather than commodity volume.
Dried apple peel consists of the outer pericarp and flavedo layers separated from fresh apples, then dehydrated to moisture levels below 10 percent to preserve bioactive compounds including quercetin glycosides and ursolic acid. The material functions primarily as a functional food ingredient, natural antioxidant source, and fiber additive across human and animal nutrition applications. Organic product type commands premium positioning through certified supply chains, while powdered form leads growth in beverage and supplement formulations where solubility and dosing precision matter. Food and Beverage end use dominates current offtake, though Nutraceuticals represents the fastest-expanding demand pool as polyphenol standardization protocols mature.
FDA GRAS self-affirmation pathways govern U.S. incorporation into food matrices, while EFSA novel food consultations shape European market access timelines for concentrated peel extracts. BIS food safety standards and FSSAI ingredient labeling rules in India create compliance thresholds for imported dried peel products entering South Asian markets. Stakeholders must monitor evolving polyphenol content disclosure requirements across jurisdictions to anticipate reformulation obligations and procurement specification shifts.
Market Dynamics
EU Green Deal circular economy mandates are redirecting apple processing residues from waste streams toward polyphenol extraction infrastructure, compressing supply timelines and concentrating procurement around certified peel recovery facilities.
Growth Catalysts
- EFSA novel food consultations:Standardized approval pathways for concentrated peel extracts accelerate nutraceutical market entry timelines.
- Polyphenol standardization protocols:Mature analytical methods enable precise dosing in functional beverage formulations, expanding addressable applications.
- Germany's Lake Constance cluster:Dense fruit processing infrastructure provides captive raw material supply for regional extraction facilities.
Market Restraints
- Fresh apple price volatility:Weather-driven crop fluctuations in major producing regions compress processor margins during low-yield cycles.
- Moisture specification rigidity:Sub-10% dehydration thresholds require energy-intensive thermal processing, limiting geographic deployment options.
- Quercetin glycoside degradation:Temperature-sensitive bioactive compounds impose narrow processing windows that constrain throughput scalability.
Strategic Opportunities
- India's FSSAI ingredient pathway:Emerging regulatory clarity for imported dried peel products opens South Asian nutraceutical formulation markets.
- Precision fermentation convergence:Hybrid extraction-biomanufacturing approaches enable standardized polyphenol production independent of agricultural cycles.
- Direct-to-supplement-brand distribution:Bypassing traditional ingredient distributors captures margin in high-growth personalized nutrition channels.
Industry Challenges
- Polyphenol quantification expertise:Scarce analytical chemistry talent delays batch certification timelines for export-bound products.
- Legacy dryer retrofit requirements:Converting conventional fruit dehydration lines to peel-specific low-temperature systems demands capital commitments without guaranteed offtake.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Apple Peel Market |
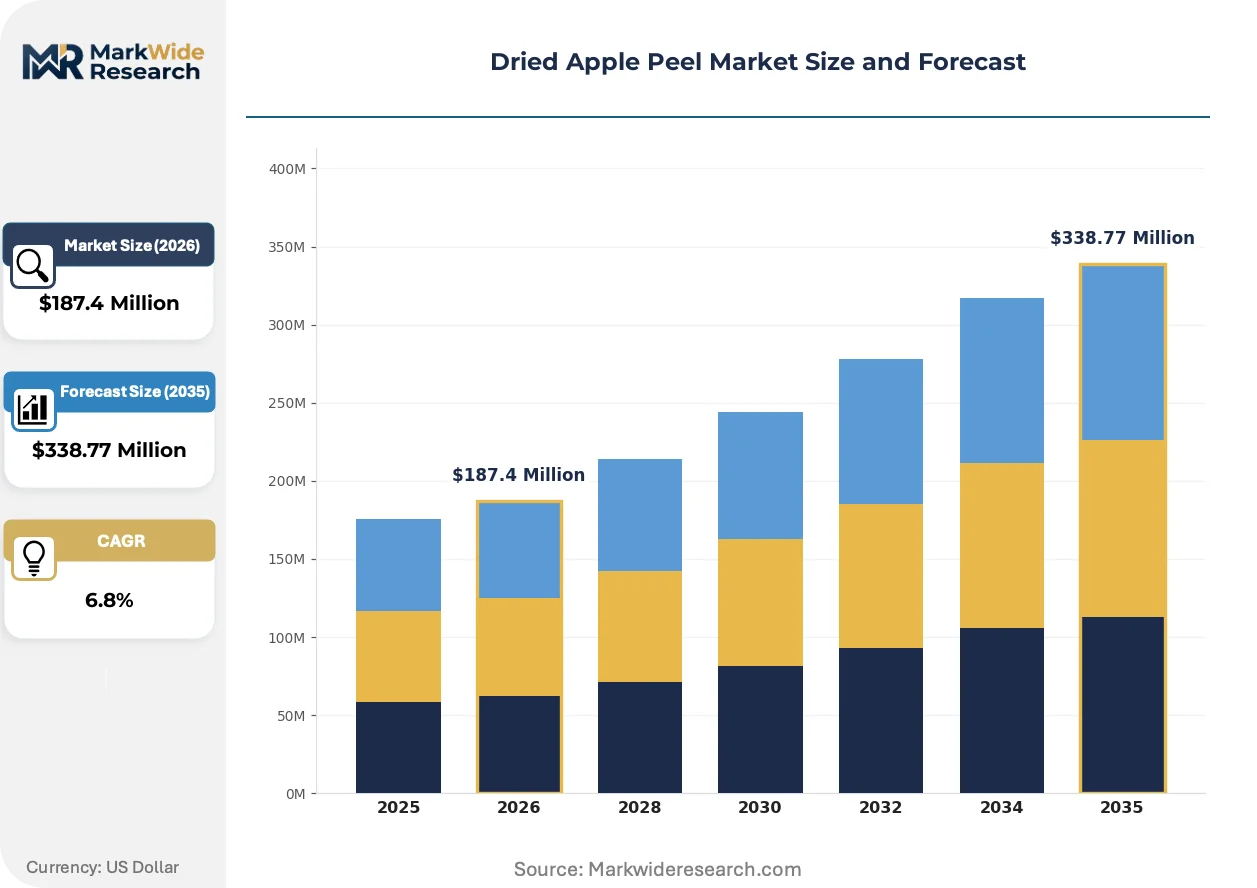
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Powdered, Whole End Use Industry: Food & Beverage, Cosmetics, Nutraceuticals, Animal Feed Packaging Type: Bags, Boxes, Bulk Containers, Pouches Sales Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Agrana Beteiligungs-AG, Döhler GmbH, Herbafood Ingredients GmbH, TreeSweet Products, Tree Top, Made in Nature, Brothers All Natural, Bergin Fruit and Nut Company, Traina Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Apple Peel Market Evolving Landscape
Near-infrared spectroscopy deployment is compressing quality control cycles while regulatory disclosure requirements tighten across major import jurisdictions, forcing simultaneous investment in analytical infrastructure and compliance systems.
Hyperspectral imaging is automating real-time polyphenol content assessment during dehydration. Nutraceutical contract manufacturers are adopting these systems at pilot scale to reduce batch rejection rates. The technology is automating specification compliance that previously required offline laboratory testing, shrinking release timelines from days to hours.
EU Green Deal food waste valorization targets are mandating peel recovery percentages for processors above defined volume thresholds. Member state enforcement timelines vary, creating staggered compliance deadlines across the trading bloc. Concentrated extract categories face the tightest reporting requirements, pushing processors toward integrated recovery systems rather than third-party sourcing.
Formulation houses are consolidating supplier relationships around vertically integrated peel processors capable of certifying ursolic acid content by lot. This specification-driven consolidation displaces commodity spot purchasing in premium supplement channels. Germany and Austria exhibit the most advanced buyer concentration, with Hamburg-area beverage developers leading long-term contracting adoption.
Dried Apple Peel Market Segmentation
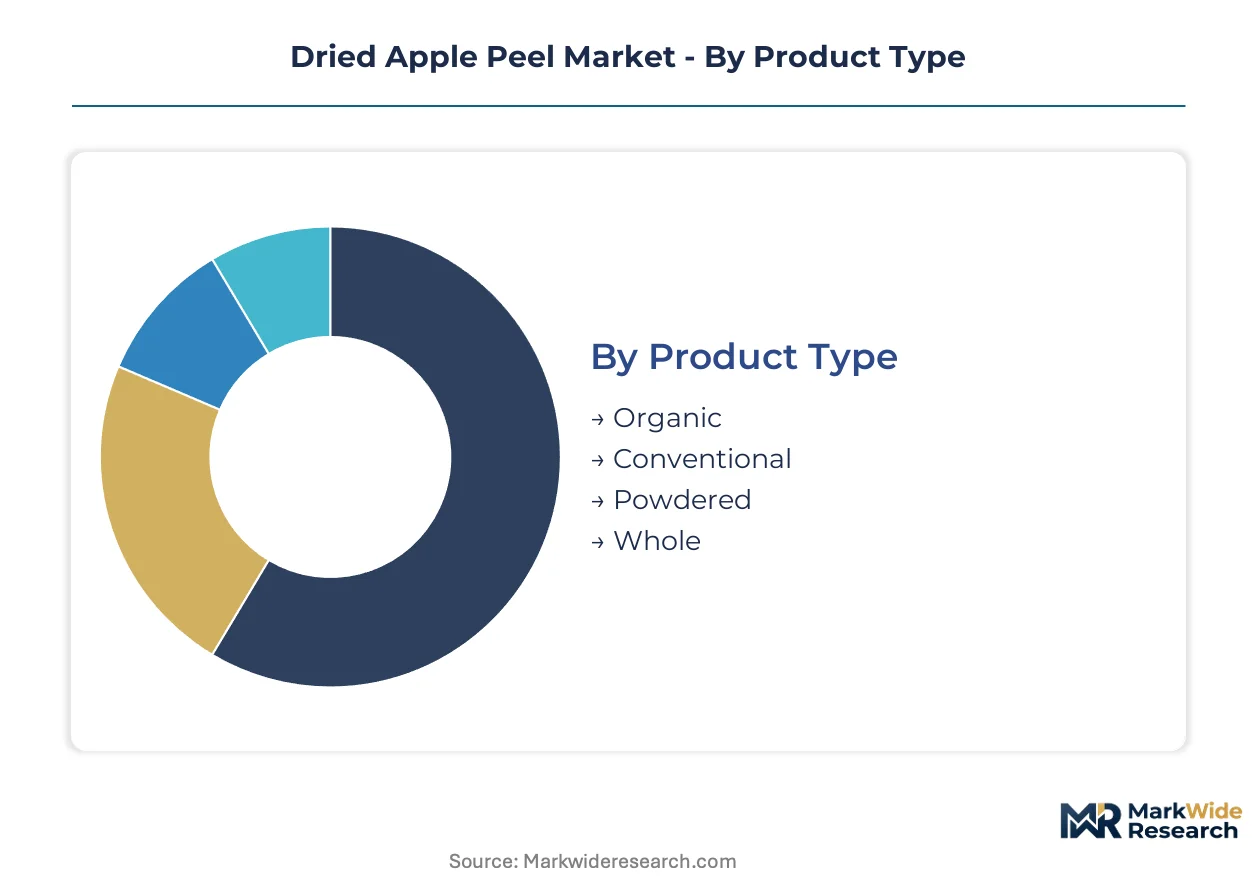
Dried apple peel segmentation reflects divergent capital requirements across processing tiers. Certified organic lines demand dedicated equipment segregation, while conventional operations achieve scale through shared infrastructure.
Product Type:
Capital intensity peaks in certified organic dehydration, where equipment segregation and audit trails multiply fixed costs versus conventional processing.
- Organic:Certified supply chains require dedicated dryer lines and contamination protocols that double per-unit capital intensity. German nutraceutical formulators in Hamburg specify organic grades for premium polyphenol extracts, with EU Green Deal waste valorization mandates tightening traceability requirements.
- Powdered:Milling and particle-size classification equipment adds processing stages that elevate technical specification capabilities. Beverage manufacturers around Lake Constance favor powdered form for solubility and precise dosing in functional drink formulations.
- Conventional:Shared processing lines with other dried fruit categories spread capital burden across higher volumes.
- Whole:Minimal processing preserves structural fiber integrity for animal nutrition applications requiring chewable formats.
Most installed capacity flows through Conventional. Expansion is steepest in Powdered.
End Use Industry:
Application economics vary sharply, with human-grade nutraceutical processing commanding equipment standards that animal feed operations bypass entirely.
- Nutraceuticals:Polyphenol standardization protocols require near-infrared spectroscopy and batch certification infrastructure that elevates technical barriers. Austrian extraction facilities serving supplement brands are consolidating procurement around vertically integrated peel processors capable of certifying ursolic acid content by lot.
- Food & Beverage:Current volume concentration sits in beverage formulations where polyphenol content claims face tightening EFSA disclosure requirements. Germany's ingredient technology corridor drives specification adoption across the EU.
- Cosmetics:Antioxidant positioning in topical formulations demands cosmetic-grade purity certification that extends processing timelines.
- Animal Feed:Fiber content specifications dominate procurement, with lower bioactive retention thresholds acceptable for livestock nutrition.
Food & Beverage absorbs the largest current volume. Nutraceuticals is gaining share fastest.
Packaging Type:
Packaging selection tracks customer scale and handling automation, with bulk formats minimizing unit costs for ingredient manufacturers while retail-ready formats capture downstream margin.
- Bulk Containers:Tote systems and fiber drums dominate nutraceutical contract manufacturing intake, with automated conveying equipment amortized across high-throughput facilities.
- Pouches:Stand-up formats with reseal features serve specialty supplement brands requiring consumer-facing presentation without repackaging investment.
- Bags:Multi-wall paper constructions balance moisture protection with sustainability positioning for mid-scale food processors.
- Boxes:Corrugated retail cases target club store and food service distribution requiring pallet-ready unitization.
Bulk Containers handle the majority of ingredient-grade movement. Pouches is expanding most quickly.
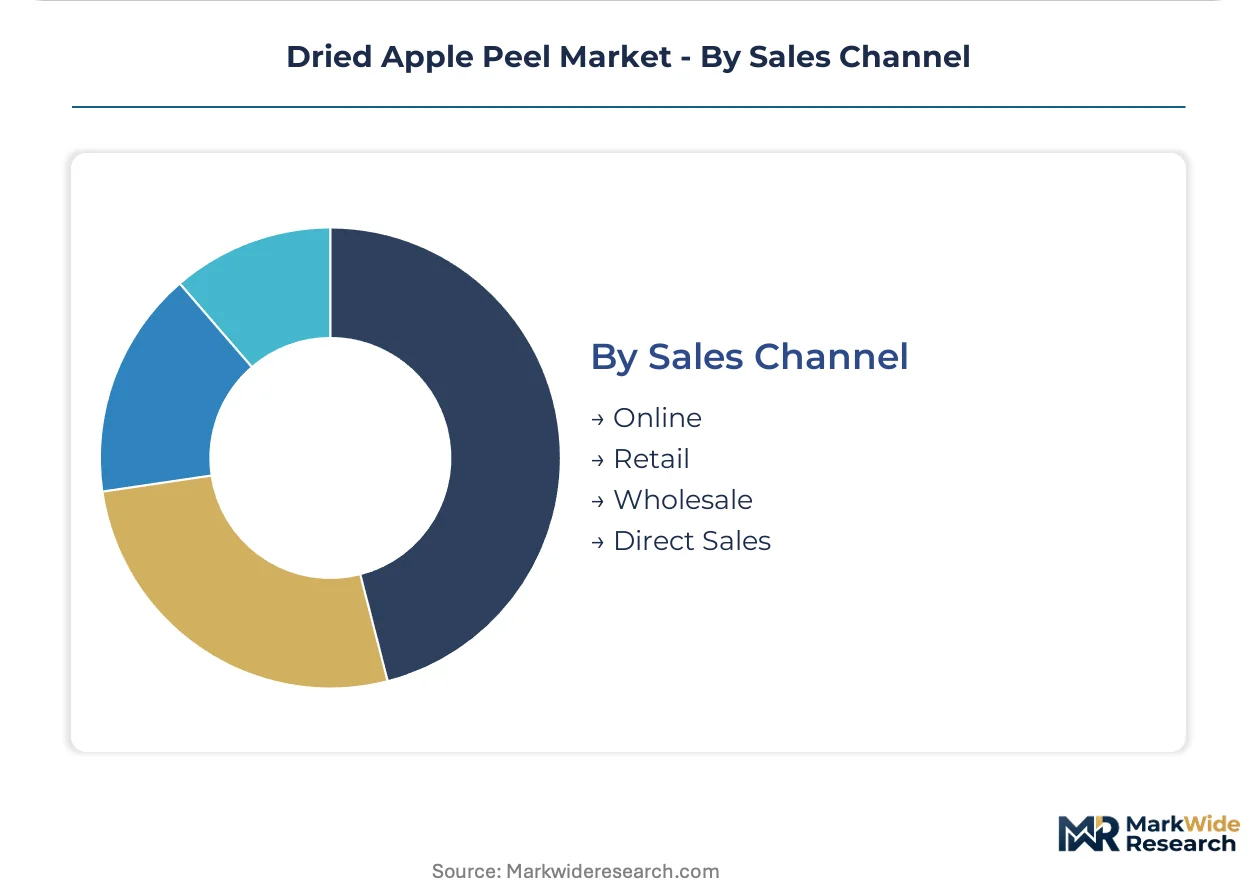
Sales Channel:
Channel economics reflect customer acquisition cost tradeoffs, with direct relationships capturing margin in specification-heavy segments while distributors aggregate fragmented demand.
- Wholesale:Ingredient distributors aggregate demand from regional food processors, extending geographic reach without dedicated sales infrastructure.
- Direct Sales:Long-term contracting with beverage and supplement developers enables specification co-development and captive offtake arrangements. Hamburg-area formulators are consolidating supplier relationships around processors with certified analytical capabilities.
- Online:Digital platforms serve small-batch cosmetic and specialty food producers requiring sample quantities and rapid turnaround.
- Retail:Limited to consumer-packaged formats through natural product channels, with minimal current penetration in mainstream grocery.
Wholesale channels move the highest absolute volume. Direct Sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial apple peel valorization originated in Central European fruit processing clusters during the early 2000s, when Austrian and German processors first deployed industrial-scale pectin recovery systems. This technical lineage established quality benchmarks that now govern procurement specifications across import markets.
Germany
Lake Constance fruit processors supply captive raw material to regional extraction facilities, while Hamburg beverage formulators drive polyphenol standardization adoption. EFSA novel food consultations shape approval timelines for concentrated extracts entering German nutraceutical channels. The Hamburg ingredient technology corridor concentrates procurement relationships around vertically integrated peel processors with certified analytical capabilities.
Austria
Agrana Beteiligungs-AG leverages vertically integrated fruit ingredient networks to secure raw peel supply across Austria and Hungary. EU Green Deal circular economy mandates redirect processing residues toward higher-value ingredient streams, compressing supply timelines. The country's extraction facilities serve supplement brands consolidating procurement around processors certifying ursolic acid content by lot.
United States
FDA GRAS self-affirmation pathways govern incorporation into food matrices, with California and Washington state processors driving organic certification adoption. Fresh apple price volatility from Pacific Northwest weather cycles compresses processor margins during low-yield periods. The Pacific Northwest apple-growing region supplies raw material to regional dehydration facilities serving domestic nutraceutical contract manufacturers.
India
BIS food safety standards and FSSAI ingredient labeling rules create compliance thresholds for imported dried peel products entering South Asian markets. FSSAI's emerging regulatory clarity for imported dried peel products opens nutraceutical formulation channels. Maharashtra and Gujarat processing hubs are developing import handling infrastructure for ingredient-grade material targeting domestic supplement manufacturers.
China
GB standards govern food ingredient safety specifications, with Shandong and Shaanxi provinces hosting apple processing clusters exploring peel recovery system deployment. SAMR oversight shapes market access requirements for concentrated bioactive extracts. The Shandong Peninsula fruit processing belt is piloting near-infrared spectroscopy systems for real-time polyphenol content assessment during dehydration operations.
Dried Apple Peel Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and analytical-capability dimensions. The vendor base stratifies into three tiers: vertically integrated fruit processors with captive raw material supply, specialized extraction houses competing on technical specification breadth, and commodity dehydrators serving animal nutrition applications. Strategic archetypes include polyphenol-standardization specialists, organic-certified supply chain operators, and regional fruit processing conglomerates extending into ingredient valorization. Dominant competitive moves encompass backward integration into apple orchard operations and long-term contracting with beverage formulators for specification co-development.
Within the integrated-processor tier, Agrana Beteiligungs-AG represents the vertically integrated conglomerate archetype spanning Austria and Hungary. Döhler GmbH anchors the formulation-partnership model through its German GmbH structure. Herbafood Ingredients GmbH exemplifies the technical-specialist position, competing on specification breadth rather than commodity volume. These three players collectively illustrate how European fruit processing heritage translates into ingredient-grade positioning.
| Leading Market Players |
|---|
| Agrana Beteiligungs-AG |
| Döhler GmbH |
| Herbafood Ingredients GmbH |
| TreeSweet Products |
| Tree Top |
| Made in Nature |
| Brothers All Natural |
| Bergin Fruit and Nut Company |
| Traina Foods |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between organic and conventional dried apple peel segments manifests in divergent pricing power and sourcing configurations. Organic certification commands dedicated dryer lines and audit trails that double per-unit capital intensity, while conventional operations achieve scale through shared infrastructure with other dried fruit categories.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic grades from conventional powder and whole-form commodity supply. Price differentiation hinges on polyphenol standardization capability and EU organic certification status, with Hamburg-area beverage formulators least sensitive to price and animal feed buyers most reactive to cost fluctuations. Pricing pressure stems from fresh apple price volatility in Pacific Northwest growing regions compressing processor margins during low-yield cycles.
Supply Chain Analysis
EU Green Deal circular economy mandates for domestic food waste valorization are reshaping sourcing patterns toward captive peel recovery systems within member state processing facilities. Supply concentrates in Germany, Austria, and Hungary, with raw material flows drawing from Lake Constance fruit clusters and Hungarian orchard networks. Single-source vulnerability sits with weather-dependent fresh apple harvests in these concentrated regions. Distribution runs through bulk tote systems to nutraceutical contract manufacturers and direct long-term contracting with beverage formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU regulatory premium capture and South Asian cost-positioned import handling, with FSSAI pathway clarity in India creating a compliance-cost differential against European novel food consultation timelines.
For Market Incumbents: Cement polyphenol standardization leadership through near-infrared spectroscopy deployment at Austrian extraction facilities, defending against precision fermentation substitutes by locking Hamburg beverage developers into specification co-development contracts. Backward integration into Hungarian orchard operations secures captive raw material supply against weather-driven price spikes.
For New Entrants and Emerging Players: Specialty cosmetic formulators in South Asia represent an underserved buyer archetype with lower certification barriers than pharmaceutical-grade channels. White-space opportunity sits in India's Maharashtra and Gujarat processing hubs developing import handling infrastructure, with FSSAI regulatory clarity enabling direct-to-supplement-brand distribution bypassing traditional ingredient distributors.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated peel processors certifying ursolic acid content by lot, given consolidation pressure from nutraceutical contract manufacturers. Long-term viability over a multi-year horizon favors extraction facilities with demonstrated EFSA novel food consultation navigation. Watch for precision fermentation convergence announcements as an inflection indicator threatening agricultural-cycle dependency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Operations | Captive supply of Hungarian and Austrian apple varieties reduces weather-driven raw material cost volatility. |
| Near-Infrared Spectroscopy Deployment | Real-time polyphenol assessment at Shandong and Lake Constance facilities compresses batch certification timelines. |
| EFSA Novel Food Consultation Navigation | Standardized approval pathways accelerate German nutraceutical market entry for concentrated extract categories. |
| Direct-to-Supplement-Brand Distribution | Bypassing ingredient distributors captures margin in India's emerging personalized nutrition channels. |
| Precision Fermentation Partnership | Hybrid biomanufacturing approaches enable standardized polyphenol production independent of agricultural harvest cycles. |
Research Methodology
Multiple input streams — primary interviews with fruit processing executives, nutraceutical formulation leads, and regulatory affairs specialists; secondary validation through EFSA consultation databases, FSSAI labeling directives, and EU Green Deal implementation trackers; customs and trade flow records — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning product type, end-use industry, packaging format, and regional regulatory cluster. CAGRs were derived from modeled annual progression rates validated against historical growth patterns. Forecast inputs incorporated polyphenol standardization protocol maturation timelines and EU member state enforcement schedules for waste valorization mandates.
Underlying measurement precision varies by segment; certified organic and nutraceutical-grade categories carry tighter precision than commodity animal feed supply. Forecasts reflect documented assumptions regarding regulatory pathway durations and fresh apple yield stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Banana Puree Market
Fruits and Vegetables
Fresh Pumpkin Market
Fruits and Vegetables
Europe Blueberry Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Cavendish Banana Market
Fruits and Vegetables
Camellia Oil Market
Fruits and Vegetables
Fresh Figs Market
Fruits and Vegetables
Aegle Marmelos Market
Fruits and Vegetables
Fava Beans Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
US Vegetable Puree Market
Fruits and Vegetables
Canned Fruits and Vegetables Market
Fruits and Vegetables
Red Berries Market
Fruits and Vegetables
Global Fruit Concentrate Puree Market
Fruits and Vegetables
Europe Orange Market