
 Lycopene Market | 2026-2036
Lycopene Market Size, Share, and Industry Trends Forecast 2026-2036
Lycopene Market Outlook
Direct procurement between tomato processing cooperatives and extract manufacturers is narrowing as branded ingredient suppliers consolidate backward into cultivation. BASF SE leverages its integrated carotenoid production network across multiple continents to secure raw material streams. Lycored anchors its position through proprietary tomato strain development and controlled-environment agriculture in Israel and California. DSM competes by extending its fermentation-derived lycopene platform, which bypasses seasonal agricultural constraints entirely.
Lycopene is a C40 tetraterpenoid hydrocarbon with eleven conjugated double bonds, typically extracted from ripe tomatoes via solvent or supercritical CO2 methods to yield 5-10% standardized oleoresins for industrial use. Its primary commercial purpose centers on antioxidant delivery in human nutrition and topical formulations where singlet oxygen quenching provides functional value. Natural-source lycopene from tomato extraction leads in pharmaceutical-grade applications where purity certification commands premium positioning, while synthetic variants occupy cost-sensitive food coloration segments. Powder formulations dominate dietary supplement manufacturing due to blending compatibility, though liquid suspensions are gaining traction in beverage fortification where dispersion stability determines adoption.
FDA New Dietary Ingredient notifications and EFSA health claim assessments shape market access for novel lycopene delivery formats, with both agencies scrutinizing bioavailability substantiation. ISO 22000 and FSSC 22000 certifications function as baseline qualifiers for ingredient supply contracts with multinational food manufacturers. REACH registration requirements in Europe constrain synthetic lycopene import volumes from non-compliant producers. Stakeholders must monitor evolving clinical trial data on prostate and cardiovascular endpoints, as positive outcomes would trigger reformulation mandates across preventive nutrition portfolios.
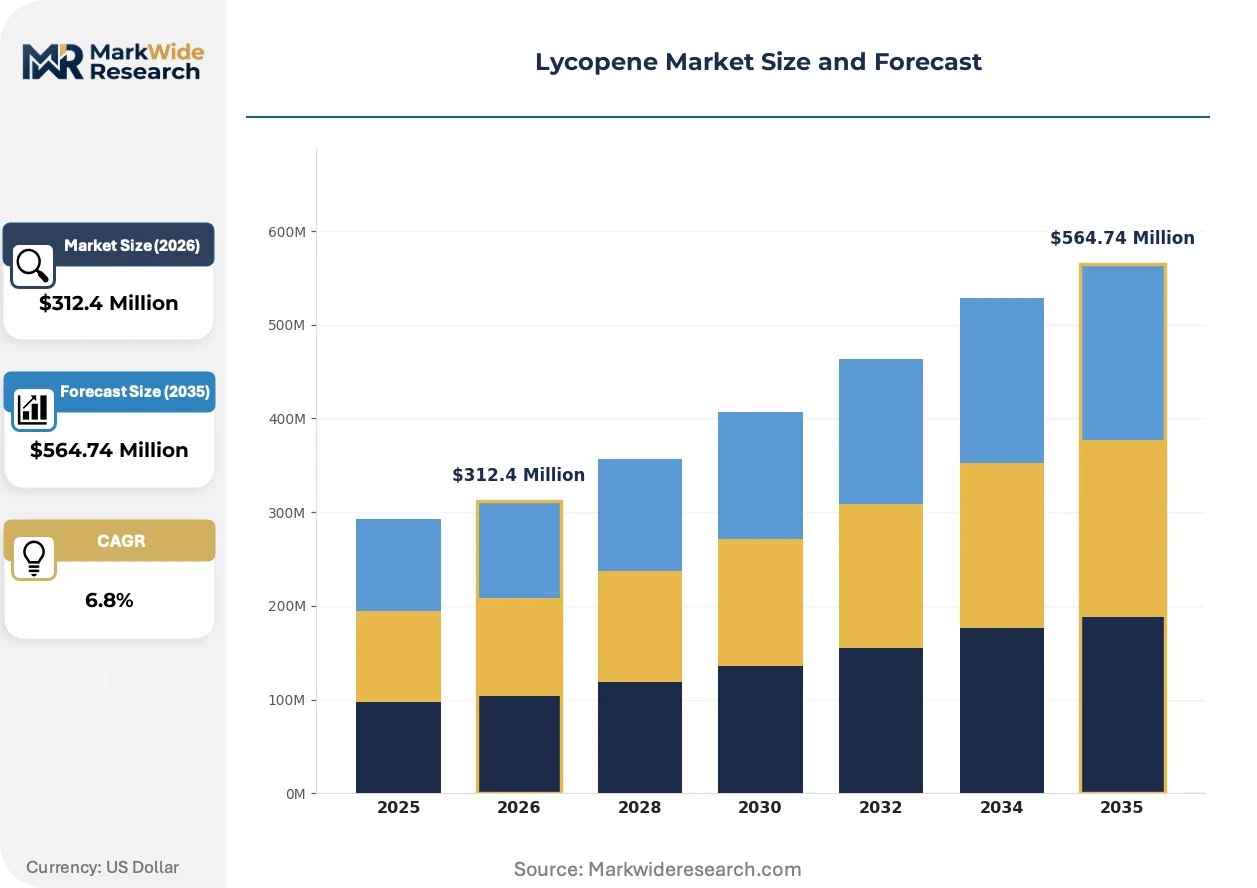
Market Dynamics
The lycopene market is restructuring around bioavailability substantiation requirements, with regulatory agencies demanding clinical validation for novel delivery formats and manufacturers consolidating cultivation-to-extraction control to secure compliant raw material streams.
Growth Catalysts
- FDA New Dietary Ingredient notifications:Compliance frameworks now reward early movers with cleared status, creating preferential access for supplement manufacturers investing in pre-market notification dossiers.
- Preventive health portfolios:Clinical nutrition formulators in the United States are expanding lycopene inclusion in antioxidant stacks targeting cardiovascular and prostate endpoints.
- Fermentation-derived production:Microbial biosynthesis platforms bypass seasonal agricultural constraints, enabling year-round supply continuity for pharmaceutical-grade specifications.
Market Restraints
- Tomato crop volatility:Concentrated cultivation in Mediterranean and Californian growing regions exposes extractors to climate-driven yield fluctuations and input cost spikes.
- REACH registration barriers:European chemical compliance requirements constrain synthetic lycopene import volumes from non-registered producers, limiting supply source diversification.
- Synthetic-natural price compression:Petrochemical-derived carotenoids undercut natural-source pricing in food coloration segments where purity certification carries no premium.
Strategic Opportunities
- Beverage fortification channels:Liquid suspension formats with enhanced dispersion stability are penetrating functional drink portfolios where powder incompatibility previously blocked adoption.
- EFSA health claim assessments:Positive cardiovascular or prostate outcome rulings would trigger mandatory reformulation across European preventive nutrition categories.
- Controlled-environment agriculture:Proprietary tomato strain development in Israel and California enables phytochemical standardization impossible in open-field cultivation.
Industry Challenges
- ISO 22000 certification timelines:Multinational food manufacturers require baseline food safety management credentials that strain smaller extractors' quality infrastructure investments.
- Singlet oxygen quenching assay standardization:Inconsistent analytical methods across laboratories complicate bioequivalence demonstrations for novel delivery technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lycopene Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Organic, Non-Organic Application: Food & Beverage, Cosmetics, Pharmaceuticals, Dietary Supplements Source: Tomato, Watermelon, Pink Grapefruit, Guava Form: Powder, Liquid, Gel, Capsule |
| Companies Covered | BASF SE, DSM, Lycored, Jamieson Laboratories, Wellgreen Technology Co., Ltd., Divi's Laboratories, Archer-Daniels-Midland Company, San-Ei Gen F.F.I., Inc., GNC Holdings, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lycopene Market Strategic Shifts
Extraction technology and delivery format innovation are compressing the boundary between pharmaceutical-grade purity and food-grade cost structures, while regulatory scrutiny of bioavailability claims intensifies competitive differentiation requirements.
Supercritical CO2 extraction is migrating from premium pharmaceutical applications toward mid-tier dietary supplement manufacturing as equipment costs decline and throughput scales. Contract manufacturers in the United States are retrofitting solvent-based facilities to accommodate this non-thermal method. The technology is migrating from niche high-purity segments into broader antioxidant formulation markets by eliminating residual solvent concerns that previously restricted natural-source positioning.
EFSA health claim substantiation protocols are tightening evidentiary standards for antioxidant mechanisms, forcing reformulators to commission human intervention trials rather than rely on in vitro singlet oxygen quenching data. This regulatory shift elevates capital requirements for market access. European supplement manufacturers are responding by consolidating procurement with extractors possessing established clinical trial portfolios.
Direct contracting between tomato processing cooperatives and branded ingredient suppliers is displacing traditional spot-market purchasing in North American supply chains. Large supplement manufacturers now negotiate multi-year cultivation agreements specifying lycopene content and pesticide residue limits. This pattern is most visible in California's Central Valley processing clusters, where backward integration into proprietary variety development secures supply predictability.
Lycopene Market Segmentation
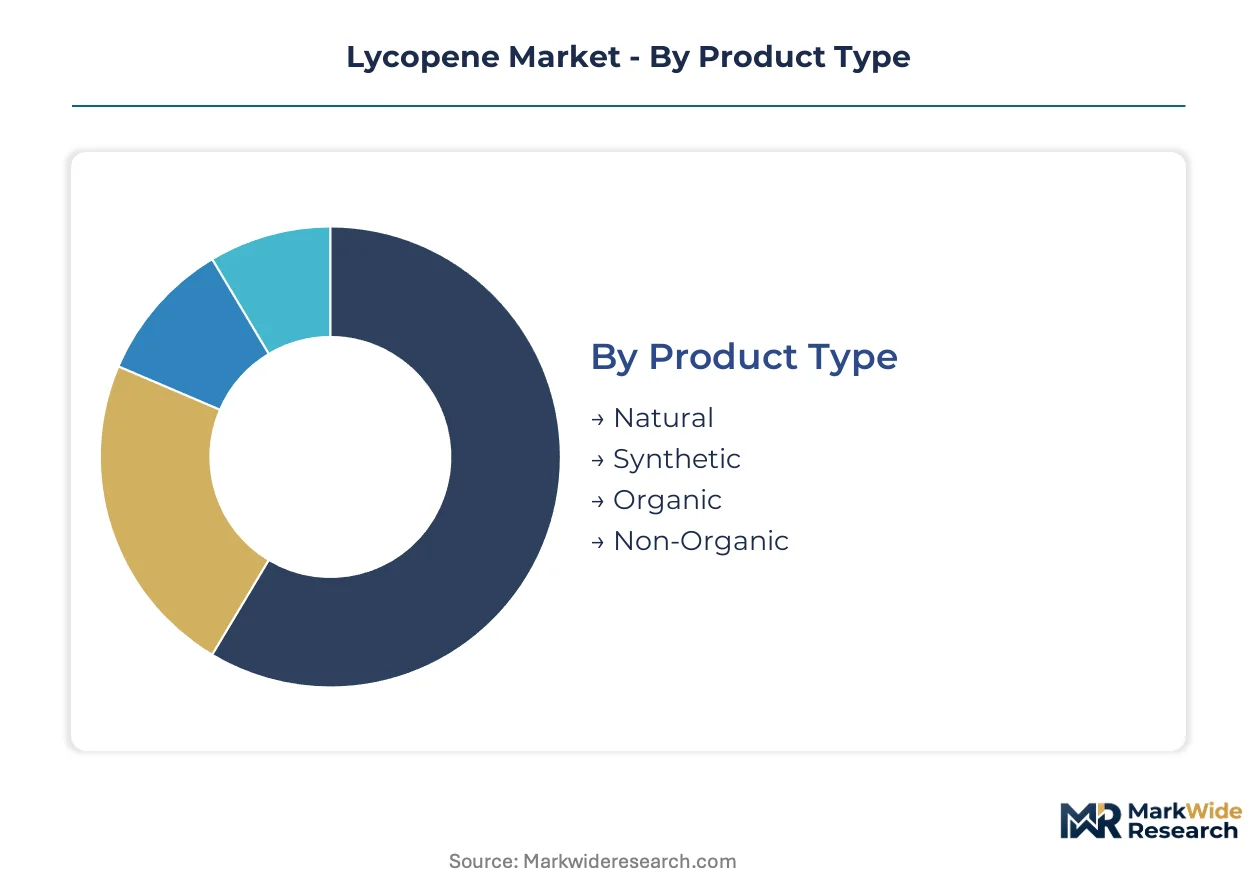
Lycopene market segmentation reveals divergent supply chain requirements across extraction methods and end-use specifications. Product origin and delivery format determine regulatory compliance pathways, pricing tiers, and procurement relationships between extractors and formulators.
Product Type:
Mature extraction technologies dominate natural-source supply while fermentation platforms are emerging as viable alternatives to agricultural dependency.
- Natural:Solvent and supercritical CO2 extraction from tomato oleoresins yields 5-10% standardized concentrates for pharmaceutical-grade applications. United States clinical nutrition manufacturers specify natural-source lycopene for preventive health portfolios where purity certification commands premium positioning.
- Synthetic:Petrochemical-derived carotenoids produced via chemical synthesis occupy cost-sensitive food coloration segments. REACH registration requirements in Europe constrain import volumes from non-compliant producers, limiting supply source diversification for European food manufacturers.
- Organic:Certified organic extraction relies on pesticide-free tomato cultivation and processing under USDA National Organic Program or EU organic standards. Supply concentrates in California's Central Valley and Israeli controlled-environment agriculture facilities.
- Non-Organic:Conventional cultivation without organic certification serves mass-market dietary supplement and food coloration applications where cost minimization outweighs certification premiums.
Natural lycopene handles the majority of throughput in pharmaceutical and premium supplement channels; synthetic is gaining share fastest in emerging economy food manufacturing.
Application:
Customer type determines specification intensity, with pharmaceutical buyers imposing the most stringent purity and documentation requirements.
- Food & Beverage:Beverage fortification channels are absorbing liquid suspension formats with enhanced dispersion stability. FDA color additive regulations govern synthetic lycopene use in conventional foods.
- Cosmetics:Topical formulations leverage singlet oxygen quenching for antioxidant delivery in skincare. ISO 22716 GMP certification functions as a baseline qualifier for ingredient supply contracts with multinational personal care manufacturers.
- Pharmaceuticals:Human drug applications require USP or EP monograph compliance with full impurity profiling and stability data. EMA quality guidelines shape specification requirements for European pharmaceutical procurement.
- Dietary Supplements:Powder formulations dominate manufacturing due to blending compatibility in tablet and capsule production. FDA New Dietary Ingredient notifications create compliance barriers for novel delivery formats entering the United States market.
Dietary Supplements handles the majority of volume throughput; Pharmaceuticals is expanding most quickly on specification intensity and margin contribution.
Source:
Geographic concentration of cultivation creates supply vulnerability that extraction technology and alternative sourcing are beginning to address.
- Tomato:Solanum lycopersicum remains the dominant commercial source, with processing cooperatives in California, Spain, and Italy supplying concentrated oleoresins. Lycored and BASF SE maintain backward integration into proprietary strain development.
- Watermelon:Citrullus lanatus offers higher natural lycopene concentration per fresh weight than tomato, though commercial extraction infrastructure remains limited. Israeli and Chinese processors are piloting scale-up operations.
- Pink Grapefruit:Citrus paradisi provides a secondary botanical source with distinct carotenoid profiles including beta-carotene co-extraction. Florida and Texas cultivation supplies North American cosmetic formulators.
- Guava:Psidium guajava concentrates lycopene in pink-fleshed varieties, with India and Mexico emerging as cultivation centers for regional extractors serving Asian and Latin American markets.
Tomato handles the majority of global extraction throughput; Watermelon is climbing the fastest on bioavailability research interest and cultivation yield potential.
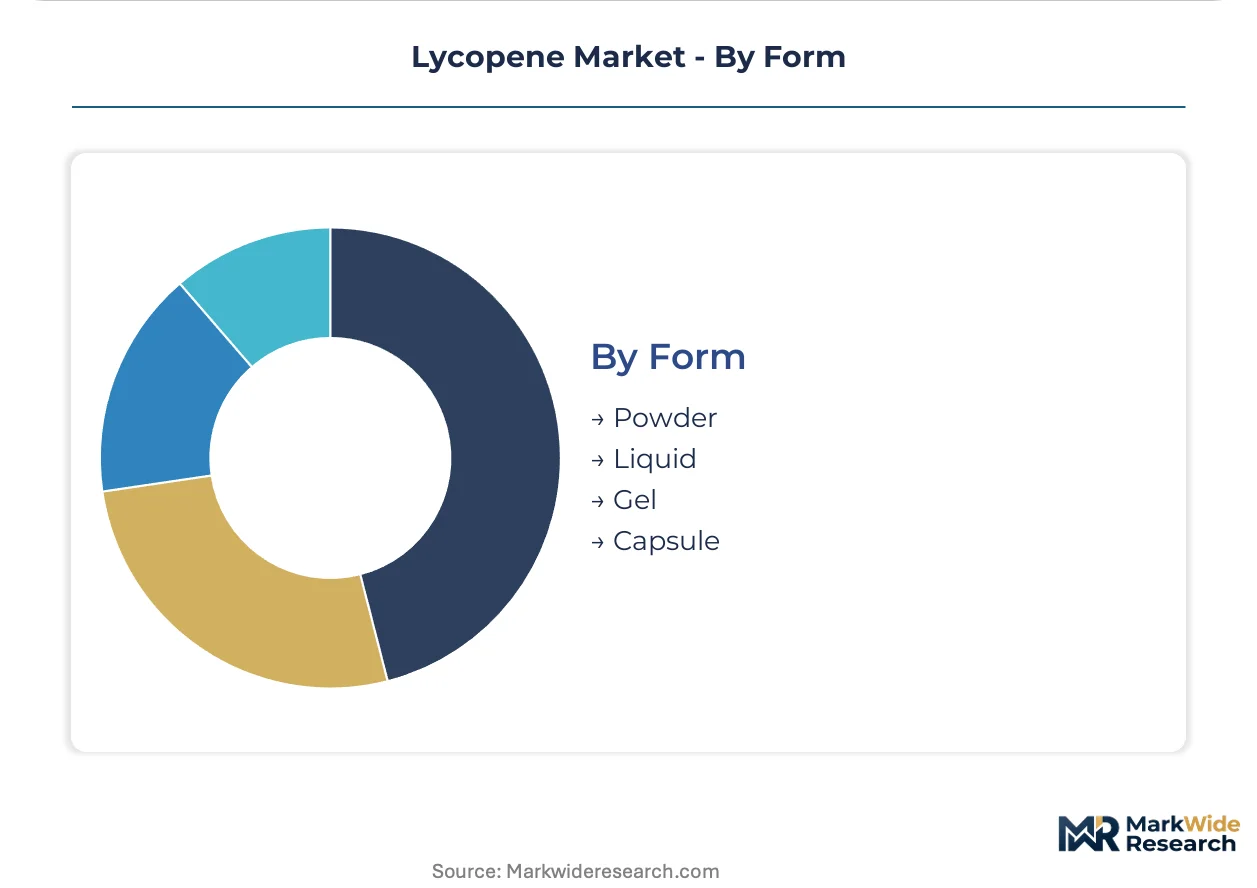
Form:
Manufacturing compatibility and end-use dispersion requirements are driving format innovation, particularly in liquid delivery systems.
- Powder:Spray-dried and microencapsulated formats dominate dietary supplement manufacturing for blending into tablet matrices and hard-shell capsules. Powder incompatibility previously blocked adoption in beverage applications.
- Liquid:Oil-based suspensions and emulsions are penetrating functional drink portfolios where dispersion stability determines adoption. Supercritical CO2 extraction yields cleaner liquid concentrates for premium positioning.
- Gel:Hydrogel and organogel matrices enable controlled-release formulations in topical and oral delivery. Cosmetic manufacturers in South Korea and Japan specify gel formats for skincare serum applications.
- Capsule:Pre-filled softgel and hardshell presentations reduce manufacturing complexity for small-scale supplement brands. United States contract manufacturers offer capsule filling as a value-added service.
Powder handles the majority of manufacturing throughput; Liquid is gaining share fastest on beverage fortification expansion and dispersion technology improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites European lycopene import flows, while California's Central Valley irrigation networks anchor North American tomato processing capacity. These physical assets determine where extraction facilities cluster and which regulatory jurisdictions govern trade.
United States
Clinical nutrition manufacturers in the United States drive bulk procurement of natural-source extracts for preventive health portfolios. FDA New Dietary Ingredient notifications shape compliance pathways for novel delivery formats entering supplement channels. California's Central Valley processing clusters concentrate backward integration into proprietary tomato variety development, securing supply predictability through multi-year cultivation agreements.
Germany
German pharmaceutical formulators specify USP-grade lycopene for cardiovascular endpoint trials, creating specification intensity unmatched in other European markets. REACH registration requirements constrain synthetic lycopene import volumes from non-compliant producers, limiting supply source diversification. The Rhine-Ruhr industrial corridor hosts carotenoid refinement facilities serving EMA-regulated drug applications.
China
Chinese ingredient suppliers are scaling fermentation-derived lycopene platforms to bypass seasonal agricultural constraints entirely. SAMR food additive regulations govern synthetic carotenoid use in domestic food manufacturing. Shandong Peninsula processing zones concentrate contract extraction capacity serving both domestic supplement brands and export markets.
Israel
Israeli controlled-environment agriculture facilities enable phytochemical standardization impossible in open-field cultivation, commanding premium positioning in pharmaceutical-grade channels. The country's national pharmaceutical regulator aligns with EMA quality guidelines for European market access. Negev Desert greenhouse complexes anchor proprietary tomato strain development programs supplying global extractors.
India
Indian dietary supplement manufacturers are expanding lycopene inclusion in antioxidant formulations targeting domestic preventive health demand. FSSAI food safety standards shape ingredient import requirements for multinational brands entering the market. Gujarat and Maharashtra processing hubs concentrate solvent-extraction capacity serving regional cosmetic and nutraceutical formulators.
Lycopene Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in extraction and strain development. The lycopene market structures around three tiers: multinational chemical conglomerates with integrated carotenoid networks, dedicated natural extract specialists with captive cultivation assets, and regional contract manufacturers serving formulation houses. Strategic moves concentrate on backward integration into proprietary agriculture and fermentation platform licensing to bypass climate-driven supply volatility.
Within the integrated chemical tier, BASF SE and DSM exemplify platform breadth spanning multiple continents and production modalities. Lycored occupies a distinct position as a cultivation-anchored specialist with controlled-environment agriculture assets in Israel and California. These three entities represent the dominant competitive archetypes: petrochemical-integrated diversification, microbial biosynthesis bypass, and proprietary botanical extraction with vertical cultivation control.
| Leading Market Players |
|---|
| BASF SE |
| DSM |
| Lycored |
| Jamieson Laboratories |
| Wellgreen Technology Co., Ltd. |
| Divi's Laboratories |
| Archer-Daniels-Midland Company |
| San-Ei Gen F.F.I., Inc. |
| GNC Holdings, LLC |
| Others |
Value Chain & Pricing Dynamics
California's Central Valley processing clusters concentrate solvent and supercritical CO2 extraction capacity, translating irrigation-dependent tomato yields into downstream pricing power for pharmaceutical-grade lycopene suppliers. Multi-year cultivation agreements between cooperatives and branded ingredient suppliers now lock in volume commitments that insulate premium tiers from spot-market volatility in conventional food coloration segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies lycopene procurement by certification grade and volume scale. Pharmaceutical buyers absorbing USP-grade specifications face the least price sensitivity, while mass-market food coloration manufacturers drive cost compression through synthetic alternatives. Pricing pressure stems from fermentation-derived platforms achieving cost parity with agricultural extraction in mid-tier dietary supplement channels.
Supply Chain Analysis
Contract manufacturing concentration in California, Israel, and China's Shandong Peninsula holds extraction capacity for global lycopene supply. Raw material flows draw from tomato oleoresins, microbial fermentation feedstocks, and petrochemical precursors. Single-source vulnerability concentrates in Mediterranean climate-dependent cultivation zones. Distribution runs through branded ingredient suppliers negotiating direct procurement with downstream formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-derived lycopene platforms are disrupting agricultural supply dependencies, with FDA New Dietary Ingredient notifications creating regulatory moats that favor early movers in novel delivery formats.
For Market Incumbents: Pre-empt synthetic-natural price compression by deepening backward integration into proprietary tomato strain development and controlled-environment agriculture. Secure multi-year cultivation agreements specifying lycopene content and pesticide residue limits. Invest in ISO 22000 and FSSC 22000 certification infrastructure to maintain baseline qualifications for multinational food manufacturer contracts. For New Entrants and Emerging Players: Establish a beachhead in beverage fortification channels where liquid suspension formats with enhanced dispersion stability remain underpenetrated. Target functional drink portfolios in Asia-Pacific markets where powder incompatibility previously blocked adoption. Commission human intervention trials for EFSA health claim substantiation rather than relying on in vitro singlet oxygen quenching data. For Investors and Strategic Acquirers: Carve-out targets emerge from chemical conglomerates divesting non-core carotenoid assets amid portfolio rationalization. Long-term viability hinges on bioavailability substantiation capabilities and regulatory clearance dossiers. Monitor clinical trial readouts on prostate and cardiovascular endpoints as mandatory reformulation triggers across preventive nutrition portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Cultivation | Lycored's controlled-environment agriculture in Israel and California secures phytochemical standardization impossible in open-field tomato farming. |
| Fermentation Platform Licensing | DSM's microbial biosynthesis bypasses seasonal agricultural constraints, enabling year-round pharmaceutical-grade supply continuity. |
| Supercritical CO2 Capacity Expansion | Contract manufacturers in the United States retrofit solvent-based facilities to eliminate residual solvent concerns in premium supplement positioning. |
| EFSA Health Claim Investment | European supplement manufacturers consolidate procurement with extractors possessing established clinical trial portfolios for antioxidant mechanism validation. |
| Multi-Year Cultivation Agreements | Direct contracting between California Central Valley cooperatives and branded ingredient suppliers displaces spot-market purchasing volatility. |
Study Parameters
Cross-validation between primary interviews with extraction facility managers, dietary supplement formulators, regulatory affairs specialists, and pharmaceutical procurement officers anchors the qualitative findings. Secondary validation draws from FDA New Dietary Ingredient notification databases, EFSA health claim assessments, customs and trade flow records, and SEC filings of publicly traded ingredient suppliers. Bottom-up volume estimates from cultivation acreage and extraction throughput triangulate against top-down market sizing from end-use consumption patterns.
Calibration against historical price series and capacity utilization rates informs the projection framework across the analysis window. Segmentation dimensions include extraction method, purity grade tier, delivery format, end-use application, and regional regulatory cluster. CAGRs derive from slope analysis of normalized growth trajectories, with fermentation technology adoption curves and EFSA ruling timelines as industry-specific forecast inputs.
Stress conditions across tomato crop yields, REACH registration compliance costs, and synthetic-natural price spreads were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on technology diffusion rates and regulatory clearance timelines. Quarterly review of clinical trial enrollment data and cultivation contract announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
Goji Berries Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Apple Concentrate Market
Fruits and Vegetables
Fruit Punnet Market
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
Dried Berries Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
Middle East and Africa Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
China Table Grapes Market
Fruits and Vegetables
South America Olive Market
Fruits and Vegetables
North America Olive Market
Fruits and Vegetables
Qatar Fruits and Vegetables Market