
 Banana Puree Market | 2026-2036
Banana Puree Market Size, Share, and Industry Trends Forecast 2026-2036
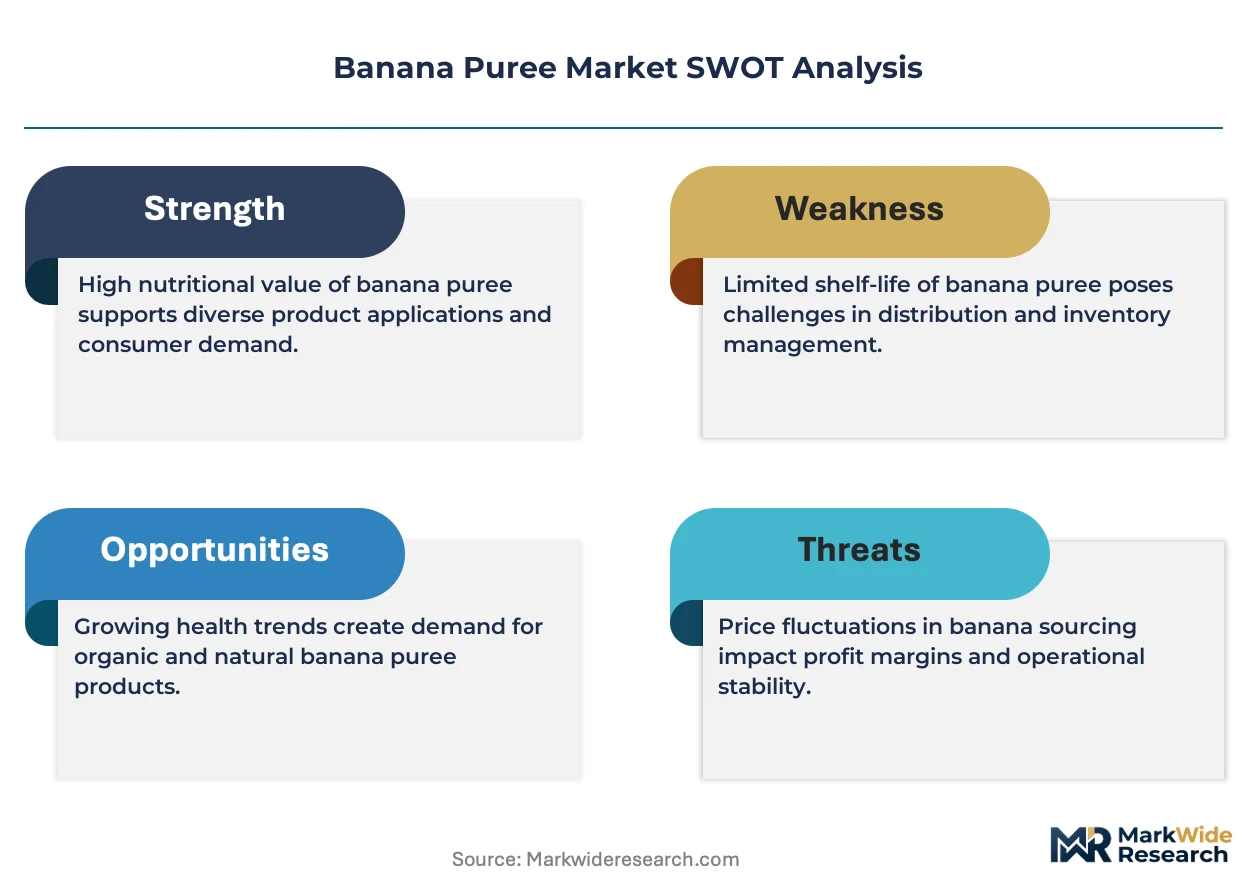
Banana Puree Market Analysis
Apple puree is pivoting toward premium baby food formulations as banana puree captures cost-sensitive segments in emerging economies. Döhler GmbH leverages its European fruit ingredient network to sustain contract supply for multinational food processors. Nestlé S.A. anchors its infant nutrition portfolio with banana-derived formulations across Latin American and African markets. Kiril Mischeff specializes in aseptic banana puree for industrial bakery applications, competing on processing consistency and bulk logistics.
Banana puree consists of mechanically processed Musa acuminata fruit flesh, typically standardized to 18-22°Brix soluble solids and pH below 4.6 for thermal stability and microbial safety. The product serves as a natural sweetener, fat replacer, and texture modifier across infant nutrition, bakery, and beverage manufacturing segments. Organic banana puree commands premium positioning in European and North American retail channels, while conventional puree dominates food-service and industrial procurement volumes. Frozen puree retains superior flavor volatiles for smoothie and ice cream applications, whereas dried formats reduce freight costs for export-oriented supply chains.
The FDA enforces juice and puree safety standards under 21 CFR 120, mandating hazard analysis and preventive controls for domestic and imported banana processing facilities. EFSA's evolving pesticide residue benchmarks and the EU Green Deal's Farm-to-Fork sustainability targets are reshaping cultivation and processing compliance costs for European-bound exports. India's FSSAI and BIS standards govern domestic quality parameters, while the PLI scheme for food processing incentivizes capacity expansion in banana-growing states. Stakeholders must monitor regulatory divergence between organic certification equivalence agreements and emerging carbon-border adjustment mechanisms affecting tropical fruit ingredient trade.
Market Dynamics
The EU Green Deal's Farm-to-Fork targets and EFSA's tightening pesticide residue benchmarks are forcing banana puree processors to requalify supplier networks and absorb compliance cost escalations across European export channels.
Growth Catalysts
- Clean-label infant nutrition:Formulators are replacing synthetic sweeteners and stabilizers with banana puree in jarred baby food, driven by parent demand for recognizable ingredient decks.
- India PLI scheme for food processing:Government incentives are accelerating cold chain investments and aseptic processing capacity in banana-growing states, expanding export-ready supply.
- Carbon-border adjustment preparation:EU-bound suppliers are investing in lifecycle tracking and low-emission logistics to preempt compliance requirements on tropical fruit ingredient imports.
Market Restraints
- Cavendish monoculture vulnerability:Panama disease TR4 spread across Latin American plantations threatens concentrated supply bases with no resistant commercial replacement variety available.
- Freight cost volatility:Reefer container rates on Asia-Europe and Latin America-North America lanes swing unpredictably, compressing margins on frozen and aseptic puree exports.
- Heavy-metal threshold tightening:The EU's updated contaminants regulation for processed fruit products is disqualifying legacy suppliers unable to meet reduced cadmium and lead limits.
Strategic Opportunities
- West African processing investment:Ghana and Cameroon offer tariff-advantaged banana supply into EU markets with underdeveloped local puree conversion capacity.
- Plantain puree diversification:Starch-forward Musa paradisiaca variants address savory applications and gluten-free bakery segments that Cavendish puree cannot serve.
- Direct-to-manufacturer digital platforms:B2B marketplaces are disintermediating traditional import brokers, letting mid-size processors contract directly with beverage and bakery formulators.
Industry Challenges
- Aseptic engineering talent scarcity:Operating continuous-flow sterilization systems requires specialized technicians that banana-growing regions lack, forcing reliance on expatriate staffing.
- Organic certification timeline compression:Three-year conversion periods and fragmented certifier equivalence between EU, USDA, and Indian NPOP standards delay premium market access.
- Legacy ERP integration with traceability platforms:Blockchain and farm-to-fork tracking systems require costly middleware to connect with established processor inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banana Puree Market |
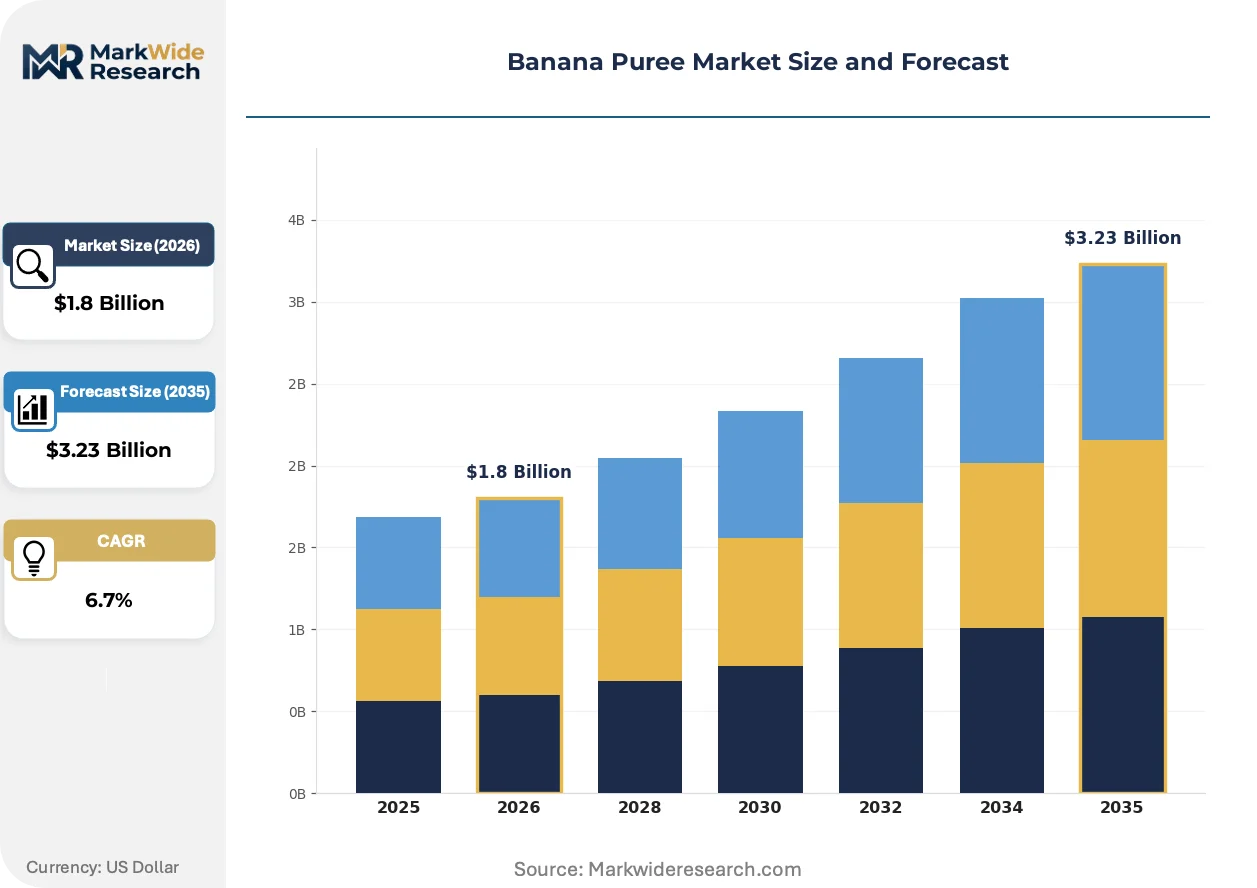
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Frozen, Dried End User: Food Processing, Bakery, Baby Food, Smoothies Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Packaging Type: Tubs, Pouches, Jars, Cartons |
| Companies Covered | Tree Top Inc., Nestlé S.A., The Kraft Heinz Company, Döhler GmbH, Kiril Mischeff, Ariza B.V., Antigua Processors S.A., Hiltfields Ltd., Shimla Hills Offerings Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banana Puree Market Emerging Trajectories
Processing technology and supply chain transparency tools are converging to reshape how banana puree is produced, verified, and procured across food manufacturing segments.
High-pressure processing (HPP) is integrating into banana puree lines to retain heat-sensitive flavor volatiles and vitamin content that conventional thermal sterilization degrades. Premium smoothie and infant nutrition brands are specifying HPP-treated puree for clean-label positioning, compressing the quality gap between frozen and shelf-stable formats.
EFSA's evolving pesticide residue benchmarks and the EU Green Deal's Farm-to-Fork sustainability targets are mandating farm-level digital traceability and reduced chemical input protocols. Processors serving European markets must now document cultivation practices through integrated farm management software, with organic and conversion-grade supply commanding preferential contract terms.
Ingredient buyers are consolidating procurement around fewer, larger suppliers capable of delivering multi-origin supply with unified certification and documentation standards. This concentration is displacing fragmented spot-market purchasing in North American and European bakery and beverage manufacturing, favoring processors with integrated sourcing across Latin America, Africa, and Asia-Pacific origins.
Banana Puree Market Segmentation
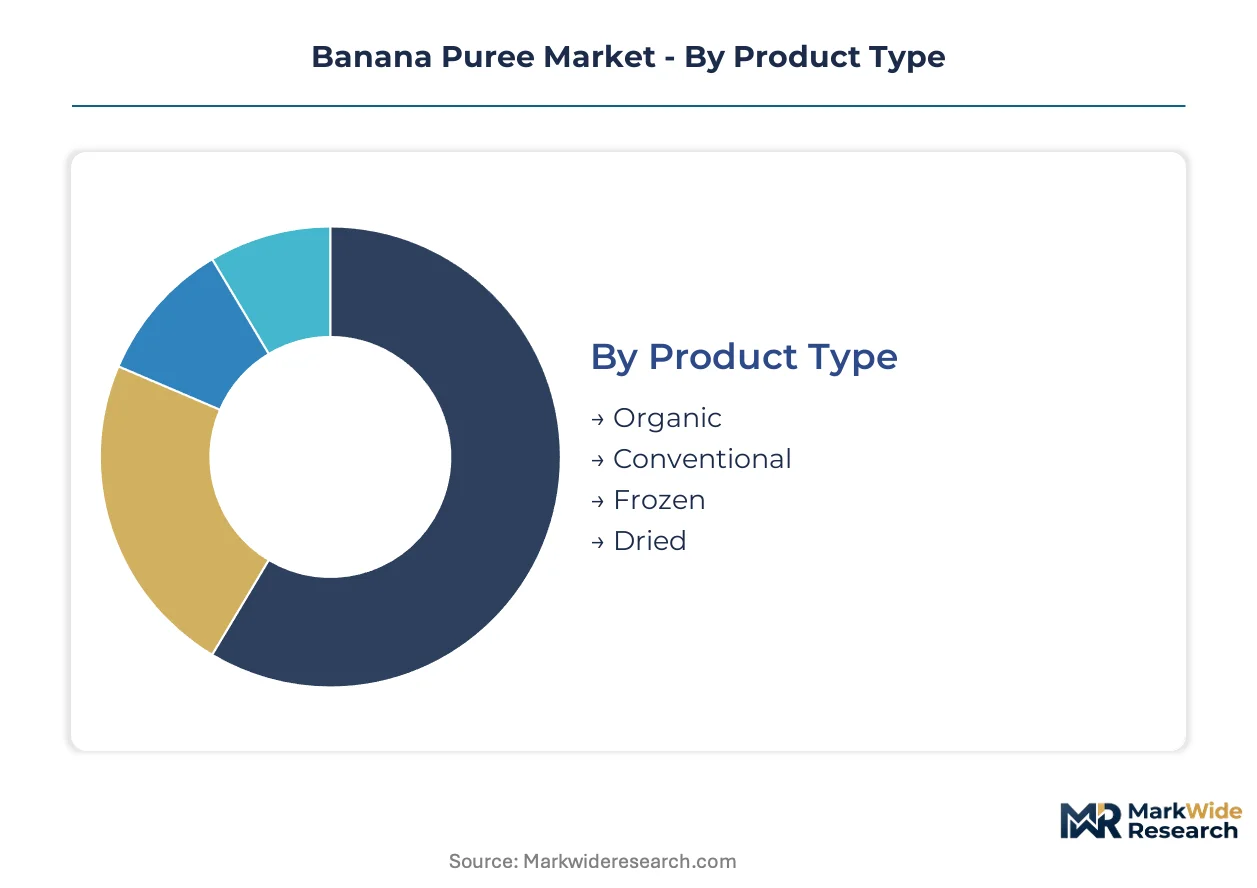
Banana puree procurement decisions hinge on certification grade, thermal processing requirements, and end-use application constraints. Manufacturers segment supply across organic-conventional divides and frozen-dried formats to match formulation needs with cost targets and shelf-life specifications.
Product Type:
Buyers select product type based on certification premiums versus functional performance tradeoffs in their target channels.
- Organic:Cultivated without synthetic pesticides and certified under USDA, EU, or Indian NPOP standards. European infant nutrition brands and North American clean-label manufacturers absorb 25-40% cost premiums to secure supply. Conversion timelines and fragmented certifier equivalence create procurement bottlenecks for new entrants.
- Conventional:Standard Cavendish-derived puree dominates industrial food-service procurement and cost-sensitive bakery applications. Indian domestic consumption and Latin American export volumes concentrate here, with EFSA's tightening residue benchmarks forcing supplier requalification across European-bound shipments.
- Frozen:Retains volatile flavor compounds and vitamin content through blast-freezing at -18°C. Premium smoothie chains and ice cream manufacturers specify frozen puree for sensory fidelity.
- Dried:Reduced moisture content cuts freight costs for export supply chains serving remote manufacturing locations. Reconstitution ratios vary by spray-dry versus drum-dry processing methods.
Volume sits with Conventional; growth tilts toward Organic.
End User:
Application-specific formulation requirements drive puree specification differences in Brix levels, pH stability, and microbial load tolerances.
- Food Processing:Industrial manufacturers of sauces, fillings, and prepared desserts source aseptic puree in bulk totes for continuous production lines. HPP-treated variants command premiums for heat-sensitive applications.
- Bakery:Banana puree replaces fat and sugar in gluten-free and reduced-calorie formulations. Kiril Mischeff and similar suppliers compete on processing consistency for industrial-scale contracts.
- Baby Food:Clean-label jarred formulations displace synthetic additives. Nestlé S.A. anchors procurement across Latin American and African manufacturing facilities.
- Smoothies:Frozen puree dominates for texture and flavor retention. Juice bar chains and retail ready-to-drink manufacturers specify single-origin supply for traceability marketing.
Procurement scale peaks with Food Processing; expansion accelerates fastest in Baby Food.
Distribution Channel:
Channel selection reflects buyer scale, certification documentation requirements, and cold chain infrastructure availability.
- Online Retail:Direct-to-consumer platforms serve small-batch artisan manufacturers and specialty food startups. Digital procurement bypasses traditional import broker margins.
- Supermarkets:Retail-packaged puree in pouches and jars reaches household consumers. Private-label expansion by European and North American grocery chains concentrates volume.
- Specialty Stores:Organic and fair-trade certified products target premium positioning. Health food retailers and boutique grocers curate origin-specific supply.
- Direct Sales:Large food processors contract directly with puree manufacturers for multi-year supply agreements. Integrated sourcing across Latin America, Africa, and Asia-Pacific origins satisfies consolidation trends.
Transaction volume concentrates in Direct Sales; channel expansion runs strongest through Online Retail.
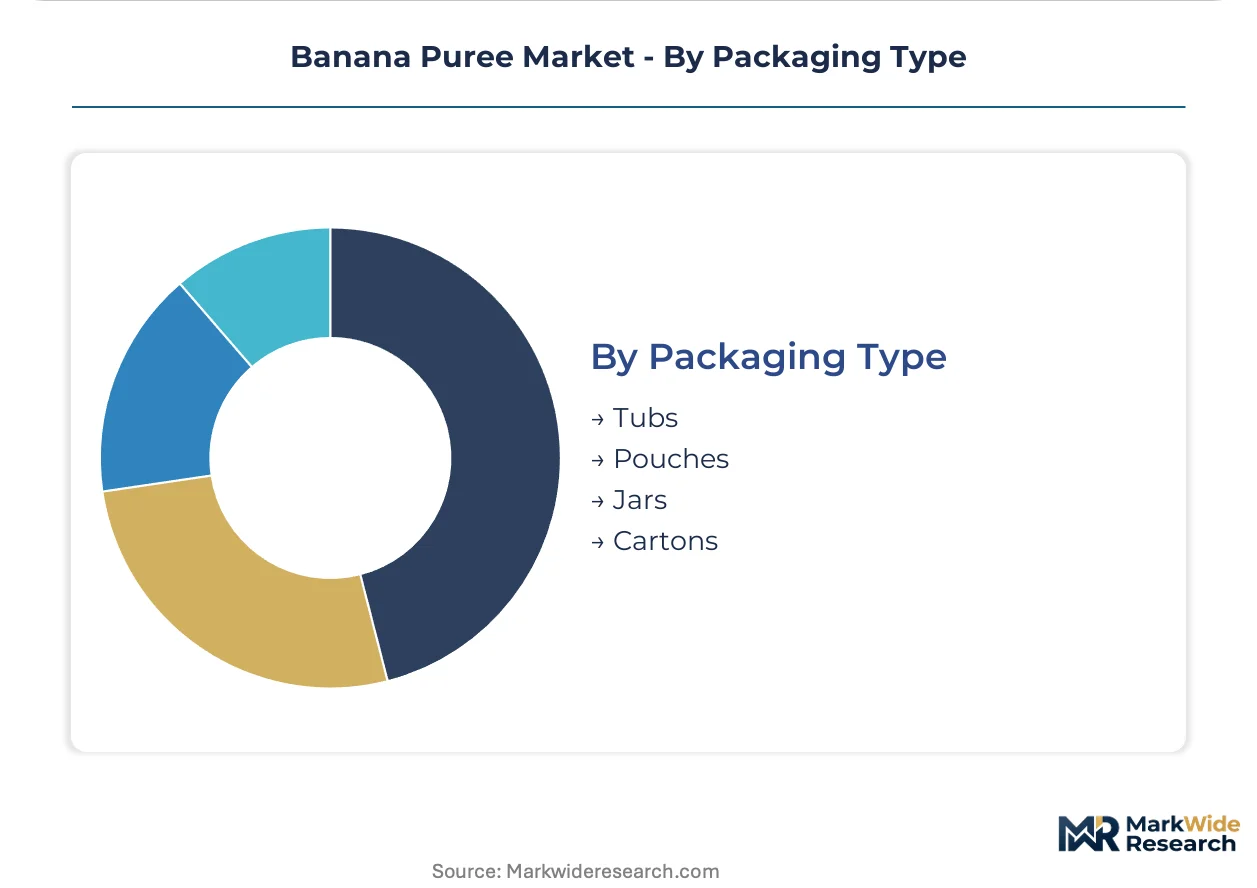
Packaging Type:
Packaging selection balances shelf stability, portion control, and sustainability positioning against unit economics.
- Tubs:Rigid plastic containers serve food-service bulk requirements and industrial ingredient handling. Reclosability supports multi-use applications in commercial kitchens.
- Pouches:Flexible packaging reduces freight cube and material weight. Stand-up pouches with spouts dominate retail baby food and smoothie segments.
- Jars:Glass packaging supports premium organic positioning and thermal processing compatibility. European retail channels favor jarred formats for perceived quality.
- Cartons:Aseptic brick packs extend shelf life without refrigeration. Beverage manufacturers and institutional food service specify cartons for ambient distribution.
Shipment volume clusters around Tubs; sustainability-driven substitution favors Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the fastest demand expansion as infant nutrition brands and export-oriented processors scale procurement from domestic Cavendish supply chains. Cold chain investments in Maharashtra and Karnataka are converting fresh fruit losses into aseptic puree capacity for European and Middle Eastern buyers.
India
Maharashtra and Tamil Nadu processors supply Nestlé S.A. and domestic baby food brands with conventional and organic grades. FSSAI quality standards and the PLI scheme for food processing subsidize aseptic line installations. Cold chain infrastructure in Nashik and Jalgaon is reducing post-harvest losses while expanding export-ready puree volumes.
United States
Tree Top Inc. and beverage manufacturers drive procurement of frozen puree for smoothie chains and private-label retail. FDA enforcement of 21 CFR 120 mandates hazard analysis for imported banana processing facilities. Pacific Northwest ingredient distributors are consolidating supply relationships with Latin American processors to secure multi-origin coverage.
Germany
Döhler GmbH anchors European contract supply for multinational bakery and confectionery manufacturers. EFSA pesticide residue benchmarks and EU Green Deal Farm-to-Fork targets are forcing supplier requalification and farm-level digital traceability investments. Hamburg and Rotterdam port logistics clusters handle bulk aseptic imports for redistribution across continental processing facilities.
Ecuador
Antigua Processors S.A. and regional exporters supply conventional puree to North American industrial buyers. Panama disease TR4 spread threatens plantation yields in El Oro and Los Ríos provinces. The national agricultural regulator enforces phytosanitary certification for export-bound processed fruit shipments.
United Kingdom
Kiril Mischeff and Hiltfields Ltd. serve industrial bakery and food-service procurement with aseptic and frozen formats. Post-Brexit divergence from EU contaminants regulations creates parallel compliance tracks for European versus domestic-bound production. Midlands distribution hubs manage bulk totes for continuous manufacturing lines.
Banana Puree Market Vendor Landscape
Capacity expansion dominates the current landscape as processors in India and Latin America install aseptic lines to capture EU and North American contract demand. The vendor base clusters around three tiers: multinational ingredient conglomerates with integrated fruit networks, regional specialists with single-origin expertise, and emerging Indian processors leveraging PLI subsidies. Strategic archetypes include certification-integrated suppliers capable of organic-equivalent documentation and logistics-heavy operators controlling cold chain assets. Portfolio diversification into plantain and specialty Musa variants represents a secondary competitive vector alongside geographic expansion into West African sourcing.
Among European-based ingredient conglomerates, Döhler GmbH and Kiril Mischeff occupy positions spanning industrial bakery and beverage supply. Nestlé S.A. exemplifies downstream vertical integration, anchoring infant nutrition procurement through captive formulation demand across Latin American and African manufacturing footprints. Indian specialists including Shimla Hills Offerings Pvt. Ltd. represent the emerging capacity tier, converting domestic banana abundance into export-oriented aseptic processing with PLI scheme support.
| Leading Market Players |
|---|
| Tree Top Inc. |
| Nestlé S.A. |
| The Kraft Heinz Company |
| Döhler GmbH |
| Kiril Mischeff |
| Ariza B.V. |
| Antigua Processors S.A. |
| Hiltfields Ltd. |
| Shimla Hills Offerings Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap processors in India and Latin America anchor supply discipline through generational capital structures that resist short-term margin compression, enabling patient investment in aseptic capacity while sustaining contract pricing power against multinational buyers. Their ownership patterns concentrate procurement leverage with Nestlé S.A. and Döhler GmbH, forcing spot-market purchasers to absorb freight volatility or exit.
Pricing Analysis
Volume sits with conventional aseptic totes for industrial food processors; margins concentrate in organic-certified grades for European infant nutrition brands. Three-tier pricing structure across premium, standard, and economy levels separates USDA/EU organic equivalence from conversion-grade and conventional supply. Cost compression in frozen formats is intensifying because reefer container rates on Asia-Europe lanes swing unpredictably. Private-label bakery manufacturers exhibit highest price sensitivity; clean-label baby food brands absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
Aseptic engineering talent scarcity in Maharashtra, Tamil Nadu, and Ecuador forces reliance on expatriate technicians for continuous-flow sterilization commissioning. Cavendish fruit supply draws from Ecuador, India, and Costa Rica, with processing capacity expanding fastest in Nashik and Jalgaon cold chain clusters. Phytosanitary certification requirements from the national agricultural regulator in Ecuador create single-source vulnerability for North American industrial buyers. Distribution runs through Hamburg and Rotterdam port logistics clusters for European redistribution, with Pacific Northwest distributors consolidating Latin American multi-origin coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic processing capacity bottlenecks in banana-growing regions prop pricing discipline by constraining export-ready supply expansion despite PLI scheme subsidies. Qualified supplier pools remain shallow relative to contract demand from infant nutrition manufacturers.
For Market Incumbents: Deploy certification investment as the primary lever to lock in multi-year supply agreements with European buyers facing EFSA residue benchmark tightening. Backward integration into cold chain assets in Karnataka and Maharashtra defends margin position against freight volatility. Capture plantain puree diversification opportunities in West Africa before specialty Musa variants commoditize. For New Entrants and Emerging Players: Direct-to-manufacturer digital platforms offer the fastest path to bypass traditional import broker margins and contract with mid-size beverage formulators. West African processing investment in Ghana and Cameroon presents the most penetrable white space, given tariff-advantaged EU access and underdeveloped local conversion capacity. Lead with HPP-treated premium positioning for smoothie chain procurement specifications. For Investors and Strategic Acquirers: Distressed-cycle entries favor Indian PLI-subsidized processors with installed aseptic lines and FSSAI compliance infrastructure in Maharashtra. Long-term viability hinges on securing organic certification equivalence across USDA, EU, and Indian NPOP standards within a five-to-ten year window. Watch Panama disease TR4 spread velocity across Latin American plantations as the critical inflection signal for supply base restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | PLI-subsidized aseptic line installations in Nashik and Jalgaon convert fresh fruit losses into export-ready volumes for EU buyers. |
| Backward Integration | Cold chain asset control in Karnataka reduces post-harvest spoilage and secures Nestlé S.A. contract supply continuity. |
| Certification Investment | Three-year organic conversion timelines and NPOP-EU equivalence documentation unlock premium positioning in German retail channels. |
| Joint Venture | West African processing partnerships in Ghana leverage tariff advantages into EU markets with underdeveloped local puree capacity. |
| Geographic Expansion | Cameroon and Ecuador multi-origin sourcing satisfies Döhler GmbH consolidation requirements for unified documentation standards. |
Methodological Framework
Trade databases, FSSAI quality filings, and EFSA pesticide residue reports formed the secondary backbone, cross-referenced with SEC disclosures from Nestlé S.A. and The Kraft Heinz Company. Primary interviews with aseptic processing engineers, infant nutrition procurement leads at multinational food manufacturers, cold chain logistics operators in Maharashtra, and organic certification auditors in India validated demand assumptions. Bottom-up volume modeling triangulated against top-down ingredient spending patterns across bakery, beverage, and baby food manufacturing segments.
Historical trendline analysis tracked Brix-standardized puree volumes and certification-grade mix shifts across the projection horizon. Segmentation dimensions modeled include organic-conventional grade tier, frozen-aseptic-dried thermal processing format, end-use application constraint, and regional production hub regulatory cluster. CAGRs derived from fitted growth curves adjusted for Panama disease TR4 supply risk and EU Green Deal Farm-to-Fork compliance cost escalations. Forecast inputs incorporated PLI scheme disbursement timelines and reefer container rate volatility indices.
Caveats apply where Panama disease TR4 plantation abandonment, EU cadmium threshold disqualification waves, or India cold chain infrastructure delays could materially shift the outlook. Forecasts embed assumptions around certification equivalence agreement stability and freight rate normalization patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
North America Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Dried Berries Market
Fruits and Vegetables
Cavendish Banana Market
Fruits and Vegetables
Farro Market
Fruits and Vegetables
Annatto Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
Red Berries Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Organic Bananas Market
Fruits and Vegetables
Global Fruit Concentrate Puree Market