
 Global Resist Processing Equipment Market | 2026-2036
Global Resist Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Resist Processing Equipment Market Intelligence
The EU's Restriction of Hazardous Substances (RoHS) directive is hardening material selection criteria for semiconductor fabrication equipment. This shift favors suppliers with strong R&D in compliant materials. Tokyo Electron Limited leverages its extensive portfolio to serve high-volume foundries, while Lam Research Corporation specializes in advanced plasma etch systems. SCREEN Holdings Co., Ltd. focuses on precision coating and developing tools for specific lithography steps.
Resist processing equipment encompasses systems designed to apply, bake, and develop photosensitive resist layers onto substrates. These systems are critical for patterning circuits on silicon wafers, often supporting 300mm wafer sizes. Spin coaters dominate the product landscape due to their ability to create highly uniform films. The photolithography technology segment, essential for semiconductor manufacturing, continues to represent the core application driving equipment design and innovation.
Regulatory frameworks from bodies like the US EPA, China's MEE, and Japan's METI govern the use of solvents and chemicals. These regulations directly impact equipment design by setting standards for waste management and emissions control. Consequently, manufacturers must innovate towards more efficient and environmentally benign processing technologies. The key decision for foundries is balancing capital expenditure on new, compliant equipment against retrofitting existing production lines.
Market Dynamics
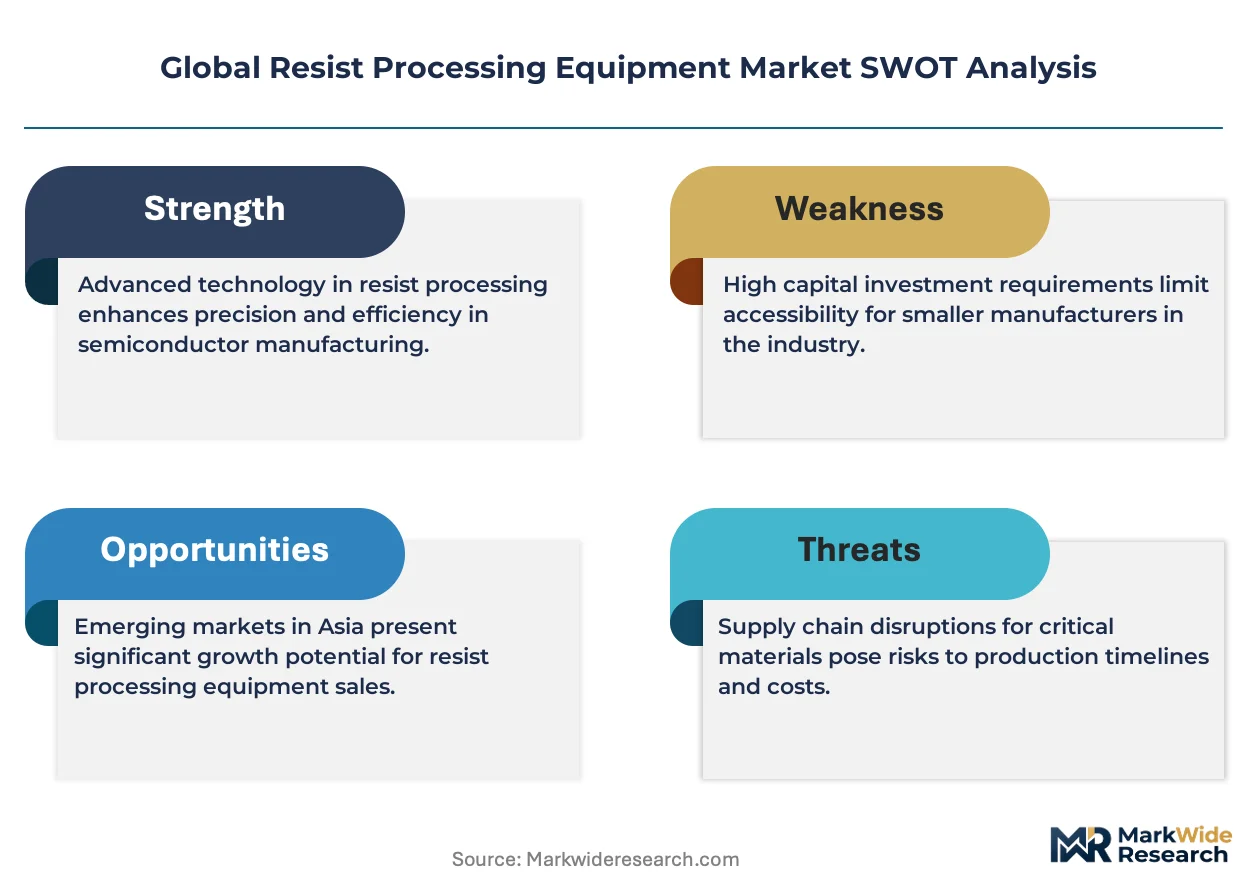
The central tension shaping the resist processing equipment market is the conflict between the semiconductor industry's push for sub-5nm process nodes and the simultaneous tightening of global environmental regulations. This dynamic forces equipment innovation on two fronts: achieving unprecedented atomic-level precision and accommodating a new generation of environmentally compliant photoresists and solvents.
Growth Catalysts
- Advanced Packaging Technologies:The adoption of Fan-Out Wafer-Level Packaging (FOWLP) and 2.5D/3D IC stacking creates demand for resist processing tools capable of handling thicker films and non-planar wafer topologies with high uniformity.
- Geopolitical Semiconductor Initiatives:Government-led programs like the US CHIPS Act and the European Chips Act are stimulating new foundry construction in North America and Europe, directly driving new capital equipment orders for complete lithography cells.
- Material Compliance Mandates:The EU's RoHS directive, along with similar regulations, compels equipment redesign to ensure compatibility with lead-free components and new, less hazardous process chemicals, favoring suppliers with strong materials science R&D.
Market Restraints
- High Capital Expenditure:The immense cost of developing and acquiring equipment compatible with 300mm wafers and Extreme Ultraviolet (EUV) lithography creates a significant financial barrier for smaller foundries and new market entrants.
- Spin Coating Limitations:Conventional spin coating technology faces physical limits in achieving defect-free, uniform resist layers on wafers with complex topographies and high-aspect-ratio features, challenging next-generation device manufacturing.
- Supply Chain Concentration:Critical subsystems, including advanced optical lenses, precision robotics, and specialized fluid delivery systems, are sourced from a limited number of suppliers, creating vulnerability to geopolitical disruptions and supply bottlenecks.
Strategic Opportunities
- Alternative Deposition Methods:There is a growing opportunity for tools based on spray coating or inkjet printing technologies, particularly for MEMS, compound semiconductors, and display applications where non-planar substrates are common.
- Emerging Semiconductor Ecosystems:Supplying resist processing equipment to nascent semiconductor manufacturing hubs in countries like India, which are supported by government incentives such as the PLI scheme, offers a new geographic growth vector.
- Equipment Retrofitting and Upgrades:Offering certified upgrade packages to bring existing equipment fleets into compliance with new chemical handling rules from bodies like China's MEE provides a valuable service-based revenue stream.
Industry Challenges
- Process Integration Complexity:Ensuring seamless data communication and physical handoffs between resist processing tools and adjacent lithography scanners and etchers, often from different vendors, remains a significant operational hurdle for fab engineers.
- Skilled Talent Scarcity:A global shortage of experienced process and equipment engineers capable of installing, calibrating, and maintaining these highly sophisticated systems can delay production ramps and limit fab efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Resist Processing Equipment Market |
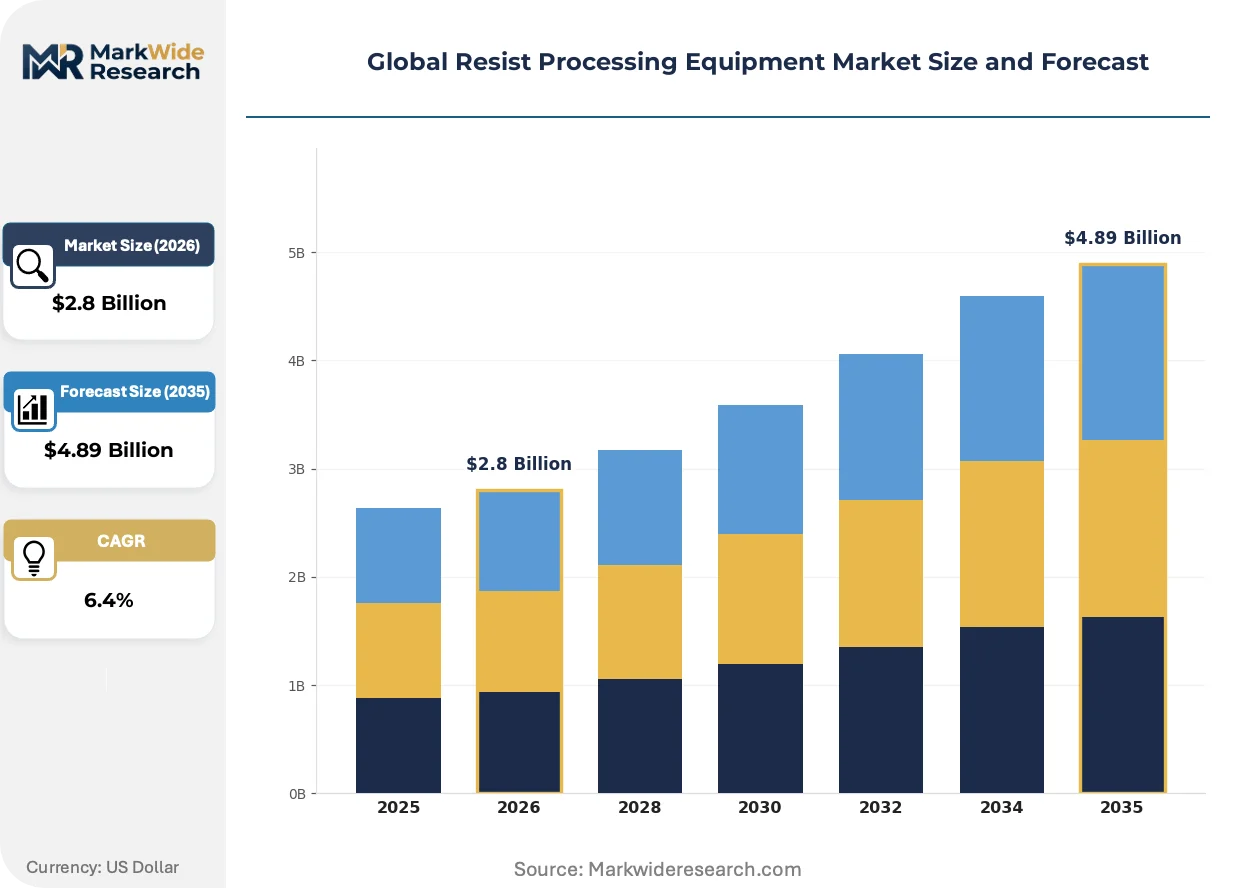
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spin Coaters, Spray Coaters, Dip Coaters, Vapor Deposition Systems, Plasma Etchers Technology: Photolithography, Electron Beam Lithography, Nanoimprint Lithography, X-ray Lithography, Interference Lithography Application: Semiconductor Manufacturing, MEMS Fabrication, Optical Devices, Solar Cell Production, Printed Circuit Board Assembly End User: Chip Foundries, Electronic Component Manufacturers, Research Laboratories, Contract Fabricators |
| Companies Covered | Tokyo Electron Limited, SCREEN Holdings Co., Ltd., ASML Holding, Lam Research Corporation, Applied Materials, Inc., EV Group, Screen Semiconductor Solutions Co Ltd, KLA Corporation, Panasonic Smart Factory Solutions Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Resist Processing Equipment Market Strategic Shifts & Innovations
Technological evolution in this market is defined by the dual pursuit of atomic-scale patterning precision and greater process sustainability. Equipment designs must now deliver flawless performance with a shrinking environmental footprint, responding to both manufacturing and regulatory pressures.
Directed Self-Assembly (DSA) provides a complementary patterning method to traditional photolithography for creating dense, regular features. Leading-edge logic and memory fabs are adopting DSA to mitigate stochastic defects and improve pattern fidelity at critical layers. As a materials-driven process, DSA is overtaking certain multi-patterning lithography steps due to its potential to reduce complexity and cost for future device generations.
Regulations from the US EPA targeting Per- and Polyfluoroalkyl Substances (PFAS) are creating new design constraints for equipment manufacturers. This action compels validation of system compatibility with a new generation of PFAS-free photoresists, developers, and surfactants. Coater and developer modules are most affected, necessitating material changes and process recalibration to ensure performance is not compromised by the alternative chemistries.
Foundries are shifting their purchasing criteria beyond initial capital cost to a total-solution evaluation that includes process development and yield optimization support. This behavioral change disrupts the traditional hardware-centric sales model, favoring vendors who can act as integrated process partners. This demand-side shift is most prominent in Taiwan and South Korea, where leading fabs compete on the speed and success of new technology node introductions.
Global Resist Processing Equipment Market Segmentation
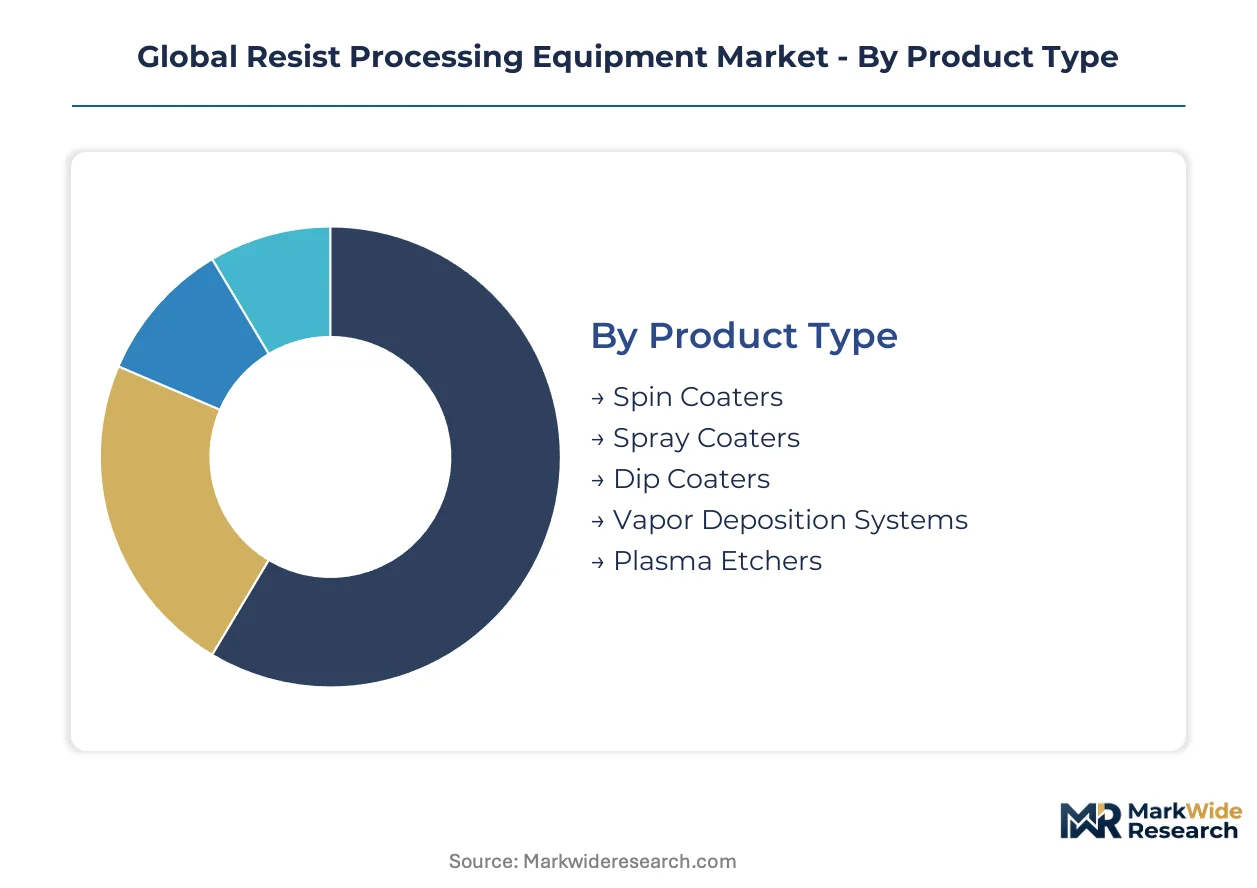
Segmentation of the global resist processing equipment market provides a granular view of diverse technological requirements and end-user demands. Understanding these distinctions is critical for manufacturers to tailor product development and market strategies. Equipment specifications vary significantly based on the precision, throughput, and material compatibility needed for different applications.
Product Type:
The capital-intensive nature of semiconductor manufacturing dictates that certain resist processing equipment types command substantial upfront investment due to their complexity and precision requirements.
- Spin Coaters:These systems apply a thin, highly uniform layer of photoresist onto a substrate by spinning the wafer at high speeds. They are fundamental for creating precise patterns on 300mm silicon wafers in high-volume photolithography processes.
- Plasma Etchers:Advanced plasma etch systems utilize reactive gases and electromagnetic fields to selectively remove material from a wafer, defining circuit features with atomic-level precision. Demand is pronounced in leading-edge foundries pushing sub-5nm process nodes and complex 3D structures.
- Spray Coaters:These tools deposit resist onto non-planar substrates or wafers with high-aspect-ratio features, finding utility in MEMS fabrication and advanced packaging.
- Vapor Deposition Systems:These systems apply resist films through vapor phase processes, offering excellent uniformity for specialized applications requiring ultrathin or conformal coatings.
- Dip Coaters:Dip coating offers a cost-effective method for applying resist layers, particularly for larger substrates or specific optical and display applications.
Spin Coaters absorb the bulk of installed capacity; Spray Coaters are expanding most quickly.
Technology:
The application focus of resist processing technologies drives innovation, with each method optimized for specific resolution, throughput, and cost profiles in circuit patterning.
- Photolithography:This foundational technology uses light to transfer circuit patterns from a photomask onto a resist-coated wafer, essential for nearly all semiconductor device manufacturing. Innovation in photolithography, including Extreme Ultraviolet (EUV), continues to define the industry's patterning capabilities.
- Electron Beam Lithography:Offering extremely high resolution down to a few nanometers, electron beam lithography directly writes patterns onto resist, primarily used for photomask creation and advanced research and development. This technology facilitates the creation of intricate designs for next-generation devices.
- Nanoimprint Lithography:This technology replicates patterns by physically pressing a mold into a resist layer, offering a potentially cost-effective method for high-volume patterning of fine features.
- X-ray Lithography:Utilizing X-rays for patterning, this technology provides high resolution and aspect ratios, suitable for specialized applications requiring very fine features.
- Interference Lithography:This method creates periodic structures by interfering two or more coherent light beams, useful for manufacturing gratings and other repetitive patterns.
Photolithography remains the foundational technology, while Nanoimprint Lithography is gaining traction for specific high-volume applications.
Application:
Volume demand across various industries dictates the scale and specialization of resist processing equipment, with semiconductor manufacturing representing the largest segment.
- Semiconductor Manufacturing:This segment encompasses the patterning of integrated circuits on silicon wafers for logic, memory, and power devices, representing the largest and most technologically demanding application. Advanced lithography tools are critical for achieving the high precision required for modern chip designs.
- MEMS Fabrication:Micro-Electro-Mechanical Systems (MEMS) require specialized resist processing for complex 3D structures, non-planar surfaces, and thicker resist layers. This application segment is expanding with the proliferation of sensors and actuators in consumer electronics and automotive systems.
- Optical Devices:Resist processing equipment is used in the fabrication of optical components like waveguides, diffractive optical elements, and micro-lenses. Precision coating and patterning are essential for optical performance.
- Solar Cell Production:This application involves patterning for photovoltaic cells, often requiring large-area processing capabilities for high-volume manufacturing. Resist layers define electrodes and other cell structures.
- Printed Circuit Board Assembly:Resist processing is integral to defining conductive traces and insulating layers on printed circuit boards, supporting the assembly of electronic systems.
Semiconductor Manufacturing represents the largest end-use category, with MEMS Fabrication driving specialized equipment demand.
End User:
The scale and operational models of end-users dictate their procurement strategies, ranging from high-volume foundries to specialized research facilities.
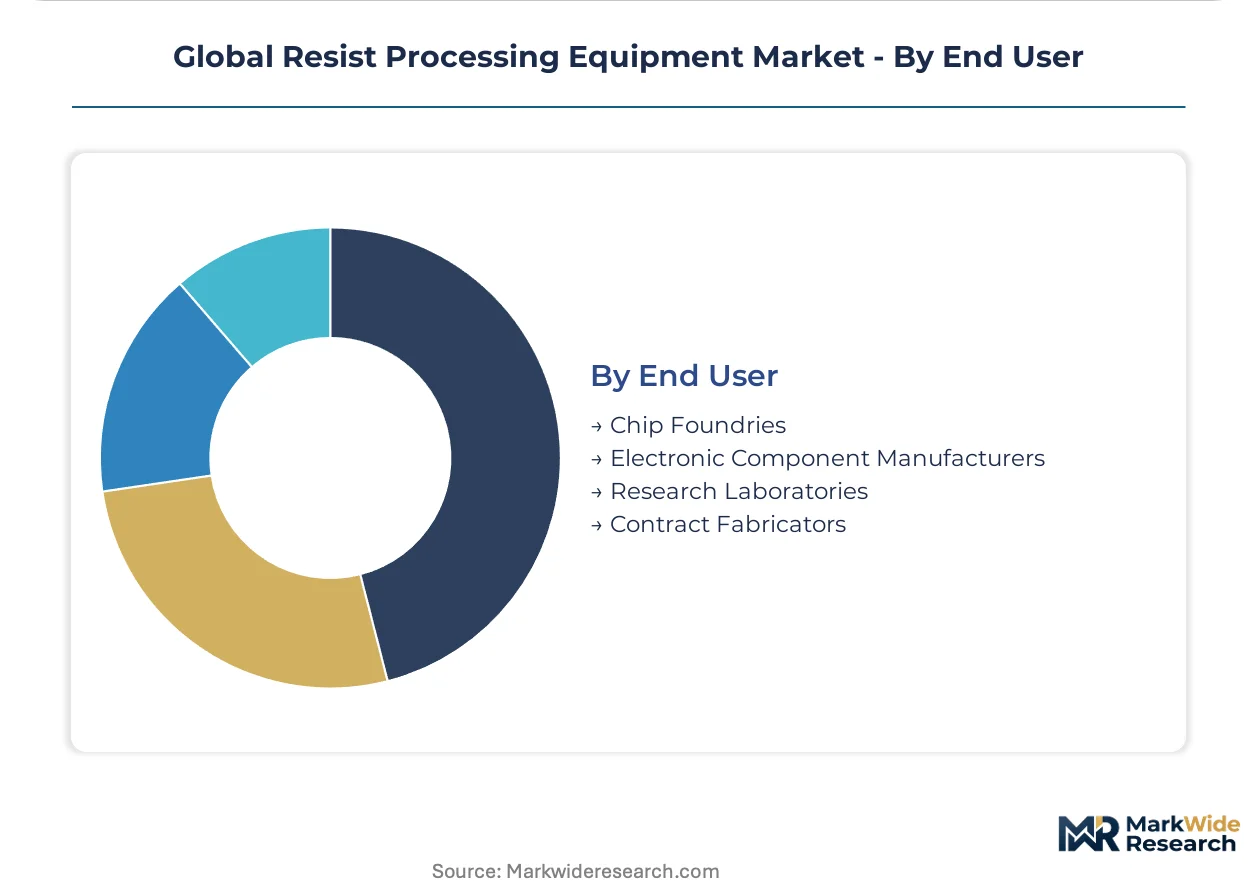
- Chip Foundries:These are high-volume manufacturers of integrated circuits for fabless design companies, demanding the most advanced and high-throughput resist processing systems. New fab construction in Taiwan and South Korea drives substantial capital equipment orders.
- Electronic Component Manufacturers:This category includes diverse companies producing a wide array of electronic components beyond just integrated circuits, requiring resist processing tools for their specific product lines. Their needs vary significantly based on product complexity and volume.
- Research Laboratories:Academic and corporate research institutions utilize resist processing equipment for prototyping new devices, materials science studies, and small-scale experimental fabrication. These users often prioritize flexibility and precision over high throughput.
- Contract Fabricators:These firms offer specialized manufacturing services to clients, often handling niche products or providing overflow capacity, requiring versatile resist processing capabilities.
Chip Foundries represent the largest purchasers of advanced systems, while Research Laboratories drive demand for versatile, lower-volume equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park in Taiwan anchors significant demand for advanced resist processing equipment. This hub drives innovation in semiconductor manufacturing, attracting substantial capital investment. Foundries here continuously upgrade facilities to maintain technological leadership and meet global chip demand.
Taiwan
Taiwanese foundries demand advanced lithography tools for sub-5nm process nodes. Government initiatives, including local versions of "CHIPS Act" support, stimulate new fab construction. The Hsinchu Science Park, a key industrial cluster, focuses on high-volume production and R&D for leading-edge chips.
South Korea
South Korean manufacturers prioritize high-throughput resist processing systems for memory and logic devices. The national government actively promotes semiconductor self-sufficiency through substantial R&D funding. Gyeonggi Province, home to major fabs, sees continuous investment in next-generation fabrication capabilities.
United States
US-based fabs require robust resist processing equipment for both advanced logic and specialized applications. The US CHIPS Act provides significant incentives for domestic semiconductor manufacturing expansion. Arizona, with new foundry projects, is rapidly expanding its capacity for advanced wafer production.
Germany
German R&D centers and specialized foundries seek precision resist processing tools for optics and advanced materials. The EU's RoHS directive influences material choices in equipment design, pushing for compliant solutions. Dresden, a prominent microelectronics cluster, focuses on developing and integrating advanced lithography solutions.
Global Resist Processing Equipment Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology sophistication and R&D investment. The resist processing equipment market exhibits a tiered structure, with a few dominant players offering comprehensive solutions. Integrated solutions providers and specialized technology innovators form the primary strategic archetypes. Capacity expansion and strategic partnerships define competitive moves within this sector, aimed at securing supply chains and broadening market reach.
Within the integrated solutions segment, Tokyo Electron Limited and Lam Research Corporation exemplify global leadership, offering broad portfolios. Tokyo Electron Limited, a Japanese multinational, occupies a position as a comprehensive equipment supplier for high-volume foundries. Lam Research Corporation, a US-based firm, anchors the market for advanced plasma etch systems, critical for sub-5nm nodes. SCREEN Holdings Co., Ltd., also a Japanese entity, sits within the specialized segment, focusing on precision coating and developing tools for specific lithography steps. These companies represent the high-end of the market, driven by continuous innovation.
| Leading Market Players |
|---|
| Tokyo Electron Limited |
| SCREEN Holdings Co., Ltd. |
| ASML Holding |
| Lam Research Corporation |
| Applied Materials, Inc. |
| EV Group |
| Screen Semiconductor Solutions Co Ltd |
| KLA Corporation |
| Panasonic Smart Factory Solutions Co., Ltd. |
| Others |
Cost & Logistics Intelligence
The transition to sub-5nm process nodes simultaneously reshapes equipment cost economics and concentrates the supply of advanced components for resist processing.
Pricing Analysis
Value-based pricing anchors resist processing equipment sales to critical performance metrics like yield and throughput. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by sub-5nm capability and comprehensive after-sales support. Pricing softness stems from the high capital expenditure burden for foundries, which must balance new equipment purchases against retrofitting existing lines. Leading-edge fabs in Taiwan and South Korea exhibit lower price sensitivity due to their focus on rapid technology node introduction.
Supply Chain Analysis
Stringent certification and qualification processes gate the supply chain for resist processing equipment. Supply concentrates in Japan and the United States, which host key manufacturers of advanced optical lenses, precision robotics, and specialized fluid delivery systems. The market depends on a limited number of suppliers for critical subsystems, creating single-source vulnerability to geopolitical disruptions. Downstream distribution runs through direct sales channels to high-volume chip foundries and specialized distributors for smaller research laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The resist processing equipment market operates as a cost-of-compliance story. The EU's RoHS directive creates a barrier-to-entry moat for compliant equipment suppliers, driving innovation.
For Market Incumbents: Anchor R&D investments into next-generation compliant materials and PFAS-free chemistries. Secure supply of critical subsystems through long-term contracts to mitigate geopolitical disruptions and single-source vulnerability. This protects market share against emerging entrants offering niche compliant solutions. Expand after-sales service and process development support to strengthen relationships with leading foundries.
For New Entrants and Emerging Players: The US EPA's regulations targeting Per- and Polyfluoroalkyl Substances (PFAS) in North America open a window for novel chemical and equipment suppliers. Target MEMS fabrication and optical devices with alternative deposition methods like spray coating or inkjet printing. A go-to-market strategy focusing on specialized solutions for non-planar substrates offers a viable entry point. Offer certified upgrade packages for existing equipment fleets to meet new chemical handling rules.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized technology innovators given the continuous demand for atomic-level precision and environmental compliance. Long-term viability is driven by the semiconductor industry's relentless pursuit of smaller process nodes. Target acquisition profiles include companies with proprietary PFAS-free process technology or expertise in alternative deposition methods. A signal to watch is the adoption rates of alternative deposition methods in emerging semiconductor manufacturing hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Key Regions | Meeting demand from new foundry construction in North America and Europe stabilizes global supply. |
| R&D in PFAS-Free Chemistries | Ensuring equipment compatibility with new environmental regulations reduces compliance risks for manufacturers. |
| Strategic Partnerships for Subsystems | Securing supply of advanced optical lenses and precision robotics mitigates supply chain concentration risks. |
| Equipment Retrofitting Services | Offering upgrades for existing production lines creates a valuable service-based revenue stream for suppliers. |
| Entry into Emerging Ecosystems | Supplying equipment to nascent semiconductor hubs like India diversifies geographic revenue streams. |
Research Approach
Independent corroboration across industry reports, company disclosures, and academic papers underwrites the qualitative findings. Primary interviews were conducted with fab engineers, R&D directors, procurement managers, and regulatory compliance officers. This primary research was triangulated with secondary data from SEC filings, patent databases, and trade association reports, employing both bottom-up and top-down validation.
The forecast window was anchored to historical reference periods, establishing a baseline for projected market trajectories across the modeling period. Segmentation dimensions modeled include product type, technology, application, end-user, and geographic region. Compound annual growth rates were derived from historical trends, projected growth drivers, and expert consensus. Key forecast inputs included semiconductor capital expenditure cycles and evolving regulatory mandates.
The model assumes a particular technology adoption path; alternative pathways for Directed Self-Assembly would alter the outlook. Forecasts reflect assumptions concerning global economic stability and continued semiconductor investment. A model refresh is warranted upon material change in geopolitical semiconductor initiatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
Wafer CMP Machine Market
Semiconductor Equipment
Global Semiconductor Back-End Equipment Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Molecular Beam Epitaxy System Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
Chip Mounter Market
Semiconductor Equipment
High Current Ion Implanter Market
Semiconductor Equipment
Semiconductor Bonding Equipment Market
Semiconductor Equipment
Solar Module Production Equipment Market
Semiconductor Equipment
Sputtering Equipment Cathode Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
Global Wafer Cleaning Equipment Market