
 Battery Holders Market | 2026-2036
Battery Holders Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Holders Market Analysis
Medical device demand is broadening the end-use vertical mix for battery holders as portable diagnostic and patient monitoring equipment proliferates in clinical and home-care settings. Keystone Electronics specializes in precision contact designs for critical-care applications where vibration resistance matters. TE Connectivity dominates high-reliability interconnect portfolios that span automotive, aerospace, and medical verticals. Bourns differentiates through magnetic and circuit protection integration adjacent to holder assemblies.
A battery holder is a mechanical enclosure designed to secure one or more electrochemical cells, incorporating spring-loaded or pressure contacts to maintain electrical continuity, with specifications typically covering retention force, contact resistance below 10 milliohms, and temperature ratings from -40°C to 85°C for industrial grades. Its primary purpose is to enable safe, replaceable power sourcing in equipment where permanent cell integration is impractical. Safety Holders command premium positioning due to integrated short-circuit prevention and flame-retardant material requirements in medical and transportation applications. Plastic remains the dominant material segment for cost-sensitive consumer electronics, though Metal holders sustain share in automotive underhood environments where thermal cycling tolerance proves essential. Multi-Bay Holders represent the fastest-growing configuration as IoT gateways and industrial edge devices consolidate multiple cell formats.
ISO 9001 quality management and IEC 62133 safety standards for portable sealed cells shape baseline design requirements for holder manufacturers serving international OEMs. The EU Battery Regulation and REACH chemical restrictions are forcing material composition audits across European supply chains, particularly for cadmium and lead content in metal contacts. In the United States, FDA device classification rules for powered medical equipment indirectly dictate holder reliability documentation. Stakeholders must monitor evolving cell form factor standards, as the transition from cylindrical to pouch and prismatic lithium configurations threatens mechanical holder relevance in several high-growth device categories.
Market Dynamics
The EU Battery Regulation's material traceability mandates are forcing a supply-chain reconfiguration across battery holder manufacturing, as recyclability requirements and restricted substance audits propagate from cell producers to enclosure suppliers serving European OEMs.
Growth Catalysts
- Portable Medical Equipment:Diagnostic device manufacturers in Germany and Switzerland are expanding orders for vibration-resistant holders designed for patient-monitoring applications in ambulatory settings.
- REACH Chemical Audits:The European Chemicals Agency's expanded substance restrictions are accelerating replacement of cadmium-plated contacts with nickel-tin alternatives in metal holder production.
- Industrial IoT Consolidation:Edge computing deployments are standardizing on multi-bay configurations that accommodate heterogeneous cell formats within single enclosure designs.
Market Restraints
- Contact Material Volatility:Nickel and copper price swings compress margins for metal holder producers serving automotive underhood applications where thermal cycling tolerance is non-negotiable.
- Pouch Cell Substitution:Prismatic and pouch lithium configurations in consumer electronics are displacing cylindrical cell holders in smartphones and tablets, eroding a historically high-volume segment.
- Certification Timeline Friction:IEC 62133 testing protocols for portable sealed cells extend holder qualification cycles, delaying new product introductions for medical device OEMs.
Strategic Opportunities
- Home Healthcare Expansion:Remote patient monitoring device deployments in Japan and South Korea are creating demand for safety-rated holders with integrated short-circuit prevention for lithium primary cells.
- Magnetic Protection Convergence:Circuit protection integration adjacent to holder assemblies offers margin expansion for suppliers capable of combining EMI suppression with mechanical retention functions.
- Battery Passports:The EU Battery Regulation's digital traceability requirements are opening service revenue streams for holder manufacturers capable of embedding QR-coded material provenance data.
Industry Challenges
- Precision Contact Engineering Talent:The scarcity of specialists capable of designing sub-10 milliohm contact resistance geometries for critical-care applications constrains expansion in medical-grade product lines.
- Legacy Equipment Integration:Industrial automation retrofits require holders compatible with decades-old enclosure footprints, forcing manufacturers to maintain obsolete tooling for diminished-volume SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Holders Market |
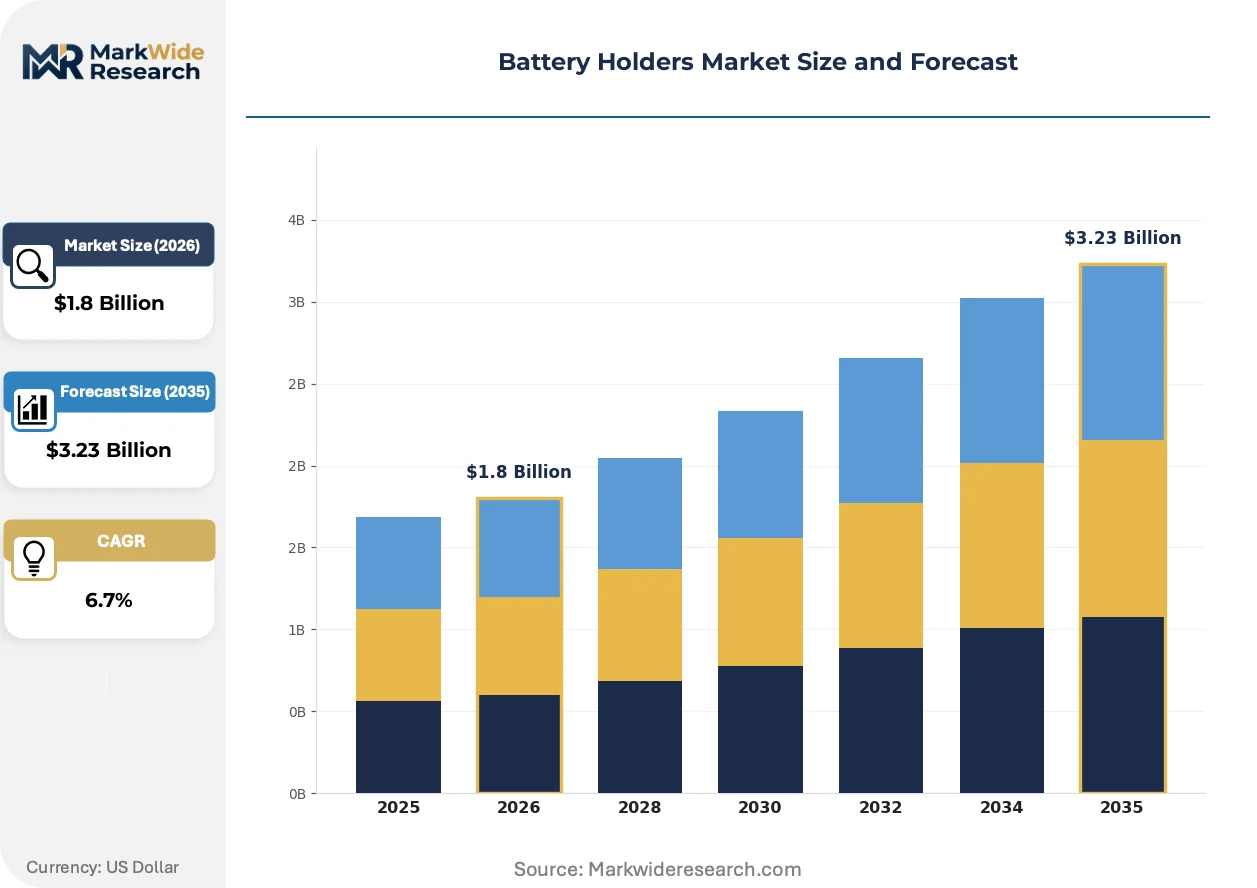
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Holders, Adjustable Holders, Multi-Bay Holders, Safety Holders Material: Plastic, Metal, Rubber, Composite End User: Consumer Electronics, Automotive, Industrial Equipment, Medical Devices Installation Type: Surface Mount, Panel Mount, Through-Hole, Embedded |
| Companies Covered | Keystone Electronics, Renata, Bourns, KYOCERA AVX, TE Connectivity, Bulgin, Newton Instrument Co., Storage Battery Systems, EnviroGuard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Holders Market Emerging Trajectories
Active materials substitution and digital traceability mandates are restructuring competitive requirements for battery holder suppliers, compressing the viable design space between safety certification burdens and cell format obsolescence risks.
Additive manufacturing of flame-retardant polymer composites is decentralizing holder prototyping and low-volume production. Medical device startups in Massachusetts and Bavaria are adopting printed nylon-12 enclosures with embedded contact springs for diagnostic equipment validation cycles. This distributed fabrication model is compressing lead times from twelve weeks to seventy-two hours for sub-thousand-unit orders.
REACH restrictions on persistent organic pollutants are tightening acceptable material portfolios for European-bound products. The European Chemicals Agency's 2024 candidate list expansion has forced reformulation of polycarbonate blends used in consumer electronics holders. German automotive suppliers are responding with accelerated qualification of polyetherimide alternatives capable of withstanding 150°C underhood temperatures.
Buyer consolidation among contract manufacturers is concentrating procurement leverage in electronics assembly. Foxconn and Jabil are standardizing holder specifications across multiple OEM programs, displacing custom designs with catalog alternatives. This specification compression is most visible in Taiwan and Shenzhen, where volume aggregation is eroding margins for specialty holder producers unable to meet consolidated technical requirements.
Battery Holders Market Segmentation
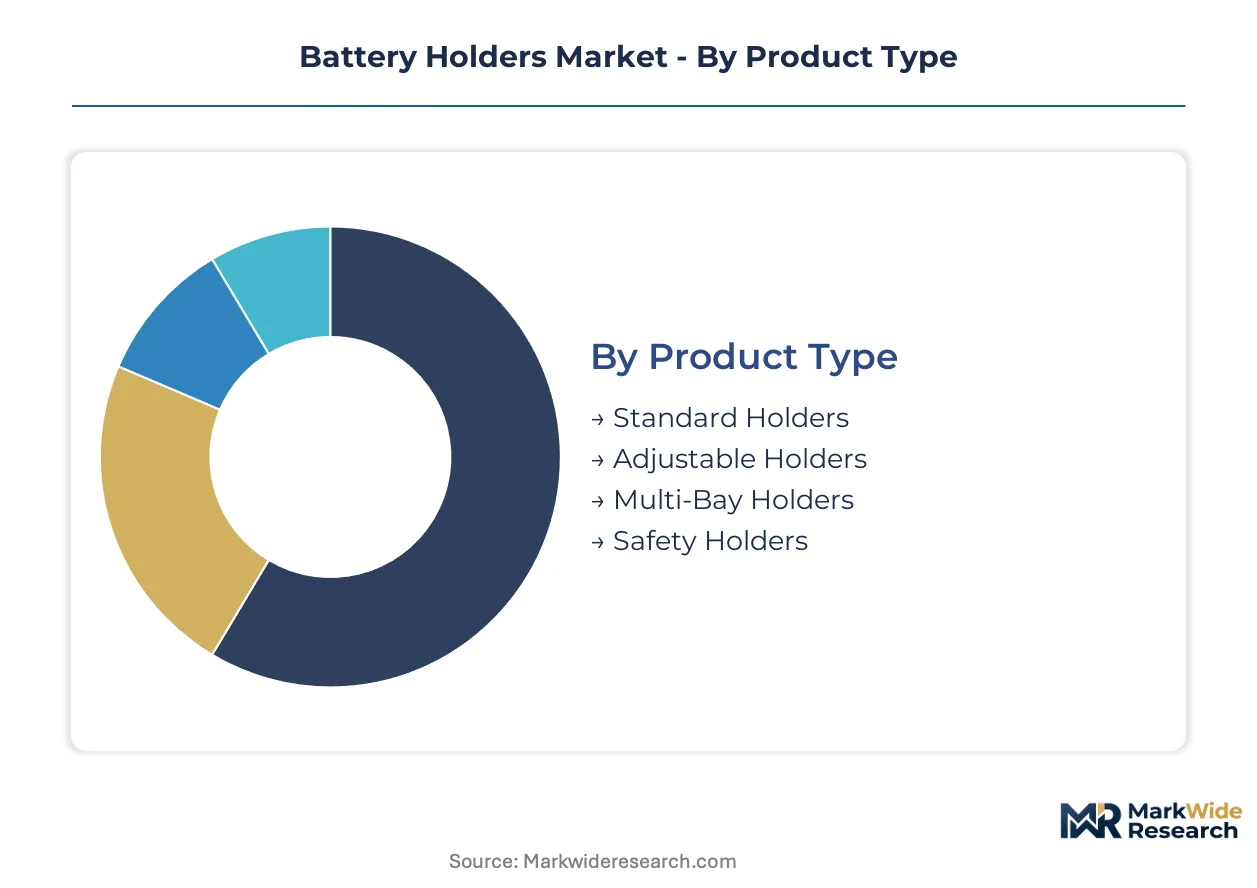
Battery holder segmentation reflects divergent buyer priorities across safety certification tiers, thermal performance requirements, and cell format compatibility. Procurement patterns in medical and automotive verticals increasingly favor specialized configurations over commoditized alternatives.
Product Type:
Buyers select configurations based on cell interchangeability needs and safety compliance burdens specific to end-use environments.
- Safety Holders:Integrated short-circuit prevention and flame-retardant enclosures meet IEC 62133 requirements for patient-monitoring equipment in German clinical settings. Medical device OEMs pay premiums for vibration-resistant contact geometries that maintain continuity during ambulatory transport.
- Multi-Bay Holders:Heterogeneous cell accommodation within single enclosures supports IoT gateway consolidation in industrial edge deployments. Demand concentrates in Japan and South Korea where factory automation retrofits require backward-compatible footprint designs.
- Standard Holders:Cost-optimized designs serve high-volume consumer electronics replacement markets with minimal certification overhead.
- Adjustable Holders:Spring-loaded contact mechanisms accommodate multiple cylindrical cell diameters for prototyping and low-volume equipment builds.
Safety Holders lead on scale through medical premiumization; Multi-Bay Holders lead on momentum through industrial IoT expansion.
Material:
Material selection hinges on thermal cycling exposure, with automotive underhood specifications demanding metal resilience that consumer electronics plastic cannot match.
- Metal:Nickel-plated copper alloys withstand temperature swings from -40°C to 150°C in automotive engine compartments. REACH-mandated cadmium elimination has accelerated tin-nickel plating adoption across European supplier networks.
- Plastic:Polycarbonate and polyetherimide blends dominate cost-sensitive portable electronics. ECHA's 2024 candidate list expansion has forced reformulation of legacy polycarbonate grades for EU-bound products.
- Composite:Flame-retardant polymer-fiber hybrids bridge weight and thermal performance for aerospace power distribution units.
- Rubber:Vibration-damping gaskets and seals supplement primary retention structures in heavy machinery applications.
Plastic leads on scale through electronics volume; Metal leads on momentum through automotive thermal specification tightening.
End User:
End-use verticals impose distinct reliability documentation requirements that fragment procurement specifications across buyer categories.
- Medical Devices:FDA device classification rules for powered diagnostic equipment mandate traceable contact resistance documentation below 10 milliohms. Portable monitoring equipment proliferation in home-care settings is expanding safety-rated holder procurement from German manufacturers.
- Automotive:Underhood thermal cycling tolerance and vibration resistance specifications sustain metal holder demand despite pouch cell encroachment elsewhere. German automotive electronics clusters drive premium contact engineering requirements.
- Industrial Equipment:Legacy enclosure compatibility constraints force manufacturers to maintain obsolete tooling for automation retrofit markets.
- Consumer Electronics:Prismatic and pouch lithium configurations are displacing cylindrical holders in smartphones and tablets, eroding historically high-volume segments.
Automotive leads on scale through metal content value; Medical Devices leads on momentum through home-care monitoring expansion.
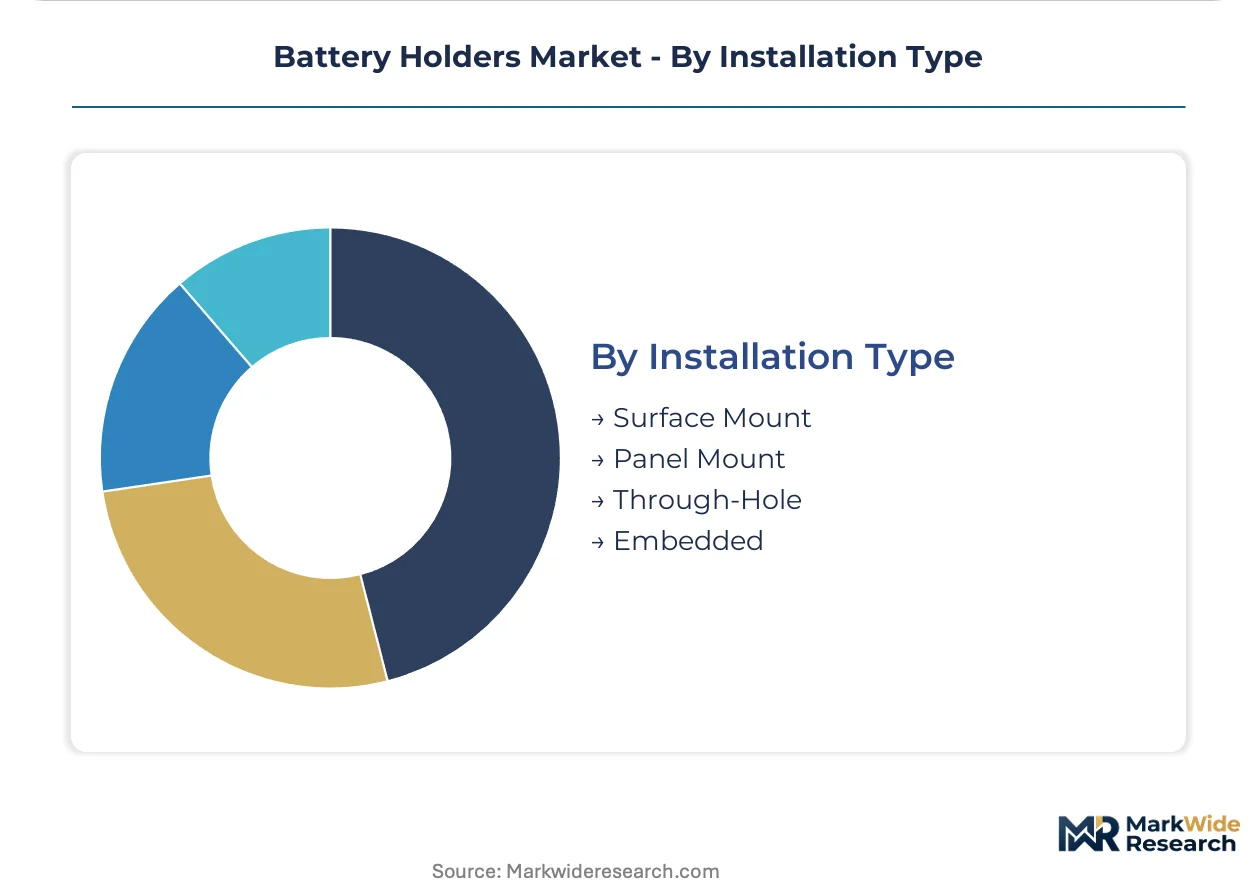
Installation Type:
Mounting method selection reflects equipment lifecycle expectations and field service accessibility requirements.
- Panel Mount:Front-accessible retention enables rapid cell replacement in medical carts and industrial control stations without equipment disassembly. Swiss diagnostic equipment manufacturers specify snap-fit panel configurations for clinical environments.
- Surface Mount:Low-profile designs suit space-constrained portable electronics where PCB integration density matters.
- Through-Hole:Mechanical stability for high-vibration environments in transportation and heavy machinery applications.
- Embedded:Permanent enclosure integration for sealed consumer devices with non-replaceable cell strategies.
Panel Mount leads on scale through serviceability premiums; Surface Mount leads on momentum through miniaturization trends in portable electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive electronics clusters anchor procurement specifications for thermal-tolerant metal holders serving underhood environments. Medical device manufacturers in Switzerland and Japan are expanding safety-rated orders for portable diagnostic equipment. Contract manufacturers in Taiwan and Shenzhen are consolidating procurement leverage across multiple OEM programs.
United States
FDA device classification rules for powered medical equipment mandate traceable contact resistance documentation below 10 milliohms for diagnostic applications. The EPA's evolving chemical substance restrictions influence material selection for holders bound for clinical environments. Massachusetts hosts diagnostic equipment startups adopting additive manufacturing for rapid holder prototyping cycles.
Germany
Industrial automation and automotive electronics clusters drive premium holder specifications requiring vibration resistance and thermal cycling tolerance. The EU Battery Regulation's material traceability mandates force recyclability audits across enclosure supply chains serving European OEMs. Bavaria concentrates procurement activity for patient-monitoring equipment in ambulatory settings.
Japan
Remote patient monitoring device deployments create demand for safety-rated holders with integrated short-circuit prevention for lithium primary cells. METI standards for industrial equipment reliability shape baseline design requirements for factory automation retrofits. The Kanto region concentrates IoT gateway manufacturing consolidating multiple cell formats within single enclosure designs.
South Korea
Factory automation retrofits require backward-compatible footprint designs for multi-bay holder configurations accommodating heterogeneous cell formats. MFDS medical device regulations parallel FDA requirements for traceable documentation in diagnostic equipment. Seoul-based electronics assemblers are standardizing holder specifications across consolidated OEM programs.
China
Consumer electronics manufacturing volumes sustain cost-optimized plastic holder production despite pouch cell displacement in smartphones. GB standards for portable sealed cells and MIIT industrial policies shape baseline certification requirements. Shenzhen contract manufacturers are aggregating procurement specifications across multiple OEM programs, compressing margins for specialty producers.
Battery Holders Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers respond to medical device premiumization and automotive thermal specification tightening. The vendor base organizes into three tiers: precision contact specialists serving critical-care applications, diversified interconnect suppliers spanning multiple verticals, and commoditized fabricators competing on cost for consumer electronics. Strategic archetypes include safety-certified medical specialists, thermal-tolerant automotive suppliers, and multi-bay configuration providers for industrial IoT. Portfolio diversification and geographic expansion represent the dominant competitive moves as manufacturers seek to offset pouch cell substitution in consumer segments.
Among diversified interconnect suppliers, TE Connectivity and KYOCERA AVX exemplify scale-driven positions spanning automotive, aerospace, and medical verticals. Keystone Electronics occupies a specialist tier focused on precision contact designs where vibration resistance commands premium positioning. Bourns sits within the circuit protection convergence archetype, integrating magnetic and suppression functions adjacent to mechanical retention assemblies.
| Leading Market Players |
|---|
| Keystone Electronics |
| Renata |
| Bourns |
| KYOCERA AVX |
| TE Connectivity |
| Bulgin |
| Newton Instrument Co. |
| Storage Battery Systems |
| EnviroGuard |
| Others |
Supply Flow & Price Mechanics
Nickel and copper contact alloys flow from mining concentrates through German automotive electronics clusters into three distinct pricing tiers downstream. Contract manufacturers in Taiwan and Shenzhen compress margins by aggregating procurement specifications across multiple OEM programs, forcing specialty holder producers to absorb raw material volatility or surrender volume.
Pricing Analysis
Distributor markups separate safety-certified medical holders from catalog-standard alternatives in procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden differentiation, with IEC 62133-compliant safety holders commanding substantial premiums over consumer-grade plastic variants. Cost compression in standard holders intensifies because Foxconn and Jabil consolidate specifications across programs. Medical device OEMs exhibit lowest price sensitivity due to FDA documentation requirements and liability exposure, while consumer electronics assemblers drive aggressive unit-cost negotiations.
Supply Chain Analysis
Freight costs from Chinese plastic injection molding centers to European medical device manufacturers have reshored some prototyping capacity to Bavaria and Massachusetts. Supply concentrates in China for polycarbonate enclosures, Germany for precision metal contacts, and Japan for high-reliability spring mechanisms. Raw material flows draw from Chilean copper concentrates, Indonesian nickel laterites, and Saudi petrochemical feedstocks for polymer grades. Single-source vulnerability concentrates in cadmium-free plating chemistry transitions mandated by REACH. Distribution runs through contract manufacturer hubs in Shenzhen and Taipei before final assembly integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The battery holders market functions as a stable compounder where medical device premiumization and automotive thermal specification tightening generate steady replacement demand regardless of consumer electronics cyclicality.
For Market Incumbents: Cement medical-grade certification portfolios against pouch cell substitution threats in consumer segments. Expand precision contact engineering capacity in Germany to capture automotive underhood thermal cycling specifications. Vertical integration into flame-retardant polymer compounding insulates margin from ECHA candidate list volatility. For New Entrants and Emerging Players: EU Battery Regulation material traceability mandates in Germany open a window for digital passport-enabled holder suppliers. Target home healthcare monitoring device deployments in Japan and South Korea where safety-rated lithium primary cell holders remain underpenetrated. Pursue additive manufacturing partnerships with Massachusetts diagnostic startups for rapid prototyping service revenue. For Investors and Strategic Acquirers: Consolidation pressure builds where contract manufacturer procurement leverage erodes specialty producer margins. The five-to-ten year viability window favors precision contact specialists with medical FDA documentation capabilities over commoditized plastic fabricators. Watch for IEC 62133 testing protocol revisions as inflection indicators for qualification timeline friction.| Strategic Initiative | Industry Significance |
|---|---|
| Medical Safety Certification Investment | IEC 62133 compliance unlocks premium positioning in German patient-monitoring equipment procurement. |
| Automotive Thermal Specification Expansion | 150°C polyetherimide qualifications capture German underhood electronics cluster demand. |
| Digital Battery Passport Integration | QR-coded material provenance meets EU Battery Regulation traceability mandates for European OEMs. |
| Additive Manufacturing Prototyping Service | Printed nylon-12 enclosures compress Massachusetts diagnostic equipment validation cycles from weeks to days. |
| REACH-Compliant Contact Plating Transition | Tin-nickel alternatives replace cadmium-plated contacts across European supplier networks. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured holder procurement managers at German automotive electronics clusters, biomedical engineers at Swiss diagnostic equipment manufacturers, and supply chain directors at Taiwan contract manufacturers. Secondary validation drew from IEC 62133 testing documentation, ECHA substance restriction databases, FDA device classification filings, and automotive OEM technical procurement specifications. Bottom-up cell format demand modeling triangulated against top-down electronics assembly value chain estimates.
Historical reference periods anchored volume and value projections across the modeling period. Segmentation dimensions included product type hierarchy, material thermal grade, end-use vertical certification tier, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to medical device expansion rates and industrial IoT gateway deployment trajectories. Forecast inputs incorporated REACH candidate list reformulation timelines and pouch cell substitution elasticity in consumer electronics.
Revisions become necessary when EU Battery Regulation enforcement intensity shifts, nickel-copper price volatility exceeds historical bands, or additive manufacturing adoption accelerates beyond prototyping into volume production. Forecasts reflect documented assumptions about medical device premiumization sustainability and automotive thermal specification tightening continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
Microspeaker Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
China Crystal Oscillator Market
Electronic Components
China Data Converter Market
Electronic Components
Electrolytic Capacitor Market
Electronic Components
Global Smartphone Cover Glass Market
Electronic Components
Conductive Polymer Capacitor Market
Electronic Components
Automation Component Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
Timing Relay Market
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
Display Port Adapters Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Blockchain in Electronic Component Market