
 United States MLCC Market | 2026-2036
United States MLCC Market Size, Share, and Industry Trends Forecast 2026-2036
United States MLCC Market Insights
Premium automotive-grade MLCC pricing is decoupling from commodity consumer electronics tiers as qualification requirements diverge. Murata Manufacturing Co., Ltd. leverages its vertical integration into ceramic powder production to sustain margin control on high-reliability automotive parts. Samsung Electro-Mechanics Co., Ltd. anchors its US position through dedicated capacity serving domestic EV manufacturers. Kyocera AVX Components Corporation differentiates via specialty high-voltage designs for electrified powertrains.
Multilayer ceramic capacitors consist of alternating layers of ceramic dielectric and metal electrodes fired into monolithic blocks, with Class 2 dielectrics such as X7R and X5R delivering volumetric efficiency above 100 µF/cm³ for DC-link buffering and decoupling applications. The automotive end-user segment commands the highest qualification barriers and longest product lifecycles, concentrating margin pools with suppliers holding AEC-Q200 and PPAP Level 3 certifications. Multilayer product types dominate unit volumes, while 0201 form factors face constrained capacity as equipment transitions favor 0402 and smaller case sizes for miniaturized telecom modules.
The National Highway Traffic Safety Administration enforces functional safety standards that cascade into MLCC reliability requirements for braking and steering systems, while the EPA's tightened fuel economy rules push electrification architectures demanding higher capacitor counts per vehicle. The CHIPS and Science Act directs domestic supply chain investments that reshape procurement patterns for US-based OEMs and Tier 1 integrators. Stakeholders must monitor how NHTSA autonomous vehicle guidance evolves dielectric robustness specifications and whether domestic foundry buildouts alter regional demand concentration for precision form factors.
Market Dynamics
The CHIPS and Science Act is rewiring domestic MLCC procurement patterns by conditioning federal semiconductor incentives on North American component sourcing, forcing automotive OEMs to qualify new supplier footprints ahead of 2027 contract renewals.
Growth Catalysts
- NHTSA functional safety mandates:Braking and steering system electrification requires AEC-Q200 qualified MLCCs with extended temperature ratings, expanding specification sheets across Detroit Three supply chains.
- Texas-Michigan battery corridor:Gigafactory investments in these states are clustering demand for high-voltage DC-link capacitors within 500-mile radii of final assembly plants.
- Silicon carbide inverter adoption:Wide-bandgap power electronics operate at higher switching frequencies, multiplying ceramic capacitor counts per traction inverter by three to five times versus silicon IGBT designs.
Market Restraints
- Barium titanate supply concentration:Domestic ceramic powder production remains insufficient for automotive-grade dielectric demand, creating import dependency on Japanese and Korean material suppliers.
- 0201 form factor equipment obsolescence:Depreciation schedules for legacy pick-and-place lines constrain capacity expansion for the smallest case sizes demanded by telecom module integrators.
- EPA fuel economy compliance costs:Tier 3 emissions standards divert R&D budgets from passive component qualification toward powertrain electrification, compressing MLCC development cycles.
Strategic Opportunities
- CHIPS Act domestic content bonuses:Tier 1 suppliers capturing 25% value-add thresholds in US-based production qualify for advanced manufacturing tax credits through 2032.
- Autonomous vehicle sensor fusion:LiDAR and camera module miniaturization is creating specification windows for ultra-small case sizes with automotive reliability ratings.
- Grid-scale energy storage:Utility battery inverters represent an underpenetrated demand vertical requiring high-voltage MLCCs with extended life ratings beyond automotive cycles.
Industry Challenges
- AEC-Q200 qualification timelines:Eighteen to twenty-four month PPAP Level 3 cycles mismatch EV platform launch schedules, forcing parallel qualification paths that strain engineering resources.
- Cleanroom capex intensity:Class 1000 fabrication environments for automotive-grade dielectrics require $400-600 million per greenfield line, restricting expansion to balance-sheet-strong incumbents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States MLCC Market |
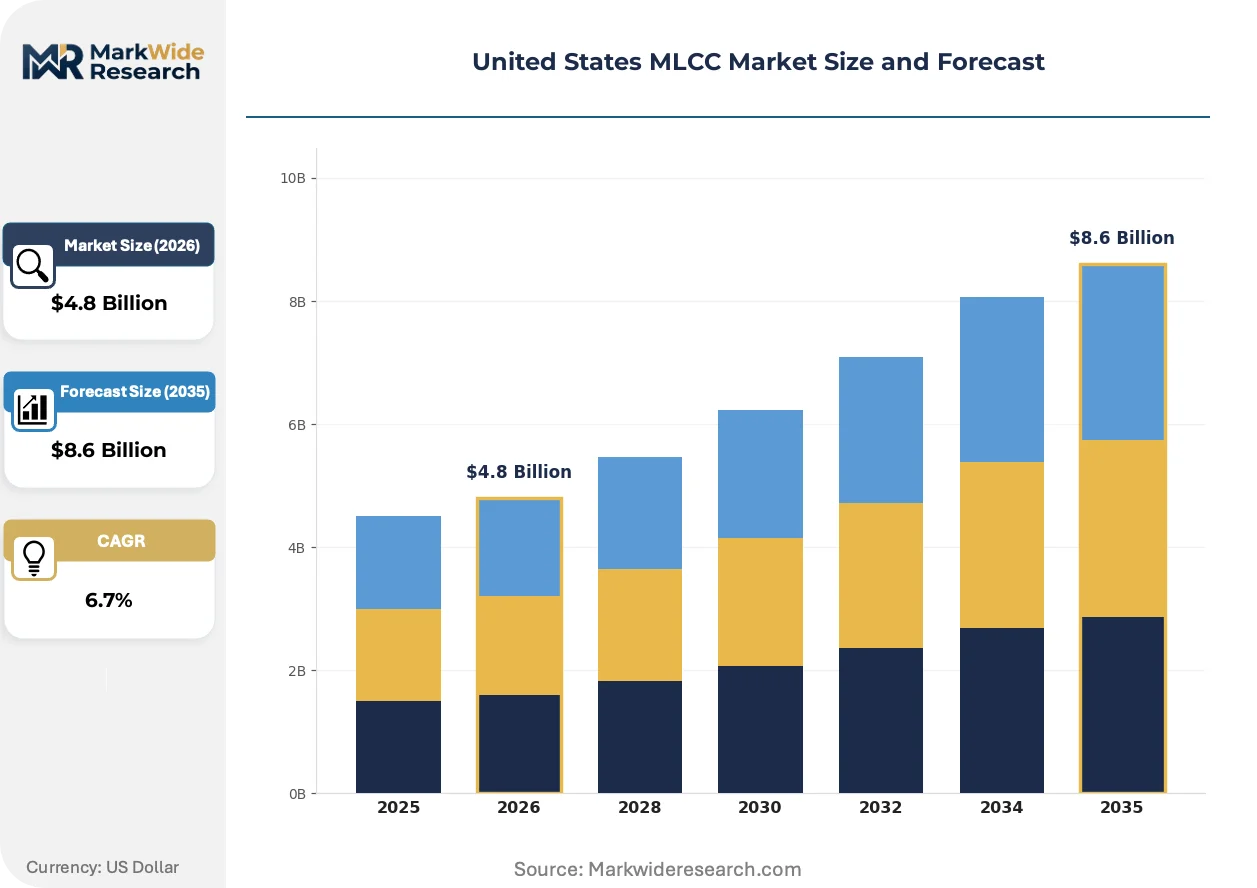
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multilayer, Monolayer, Ceramic, Tantalum End User: Consumer Electronics, Automotive, Industrial, Telecommunications Application: Power Supply, Signal Coupling, DC-DC Conversion, EMI Filtering Form Factor: 0805, 0603, 0402, 0201 |
| Companies Covered | Murata Manufacturing Co., Ltd., Samsung Electro-Mechanics Co., Ltd., Kyocera AVX Components Corporation, TDK Corporation, Yageo Corporation, Taiyo Yuden Co., Ltd., Vishay Intertechnology Inc., Walsin Technology Corporation, Nippon Chemi-Con Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States MLCC Market Trends and Innovations
Electrification architectures are fragmenting MLCC specification requirements across voltage ratings, temperature grades, and form factors simultaneously, compressing the viable product portfolio for undifferentiated suppliers.
Base-metal electrode technology is consolidating market share in automotive DC-link applications by replacing silver-palladium systems with nickel or copper electrodes that withstand reducing atmospheres during sintering. Ford and General Motors have accelerated BEM qualification timelines from thirty-six to eighteen months. This transition is consolidating procurement authority with suppliers possessing captive ceramic powder and electrode co-firing expertise.
The CHIPS and Science Act's domestic content provisions are cascading into MLCC sourcing requirements through NHTSA-EPA coordinated rulemaking on critical mineral traceability. Tier 1 integrators must now document smelter and refiner origins for tantalum, tin, tungsten, and gold used in termination plating. Michigan-based battery manufacturers are responding by pre-qualifying suppliers with North American powder processing capabilities.
Consolidated procurement desks at domestic EV OEMs are unbundling capacitor sourcing from legacy passive component distributors, establishing direct vendor-managed inventory agreements with qualified manufacturers. This disintermediation compresses lead times from sixteen weeks to four weeks for high-runner specifications. The practice is most visible in Texas, where Tesla and Rivian have established supplier parks with synchronized sequencing to assembly lines.
United States MLCC Market Segmentation
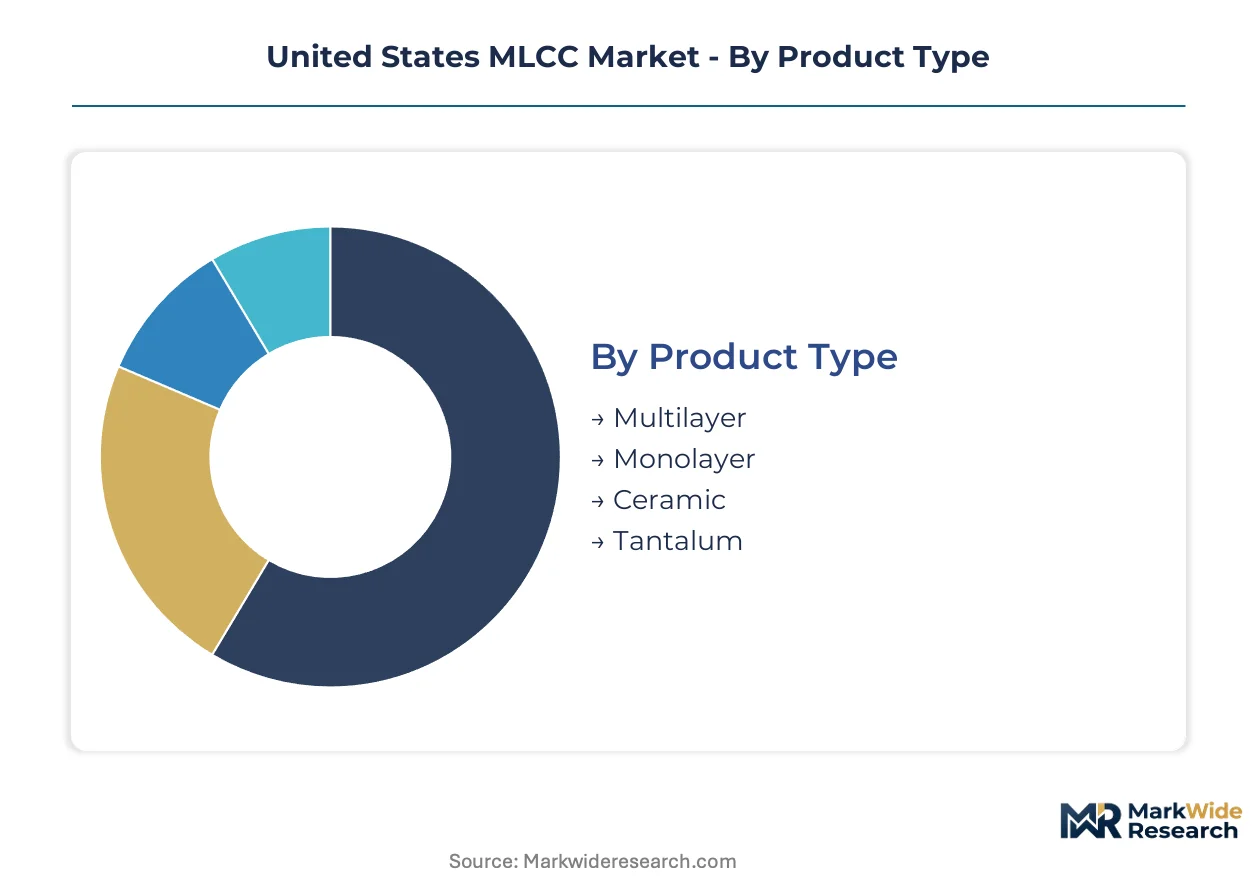
MLCC procurement in the United States fragments across four distinct segmentation axes, each governing different competitive dynamics. Product type determines manufacturing scale economies, while end-user qualification barriers create divergent margin pools across automotive and consumer tiers.
Product Type:
Buyers differentiate primarily by volumetric efficiency requirements and monolithic integration levels.
- Multilayer:Alternating ceramic dielectric and metal electrode layers deliver capacitance densities above 100 µF/cm³. DC-link buffering in Michigan-based EV battery plants consumes the highest-specification X7R and X5R dielectric grades, with CHIPS Act domestic content rules pushing procurement toward North American-qualified suppliers.
- Ceramic:Barium titanate-based formulations dominate automotive-grade reliability tiers. Texas gigafactory corridors cluster demand for high-voltage designs with AEC-Q200 temperature ratings, though domestic powder production shortfalls sustain import dependency on Japanese material suppliers.
- Monolayer:Single-layer constructions serve cost-sensitive filtering applications with reduced volumetric efficiency. Industrial motor drives in Ohio and Pennsylvania represent stable replacement demand.
- Tantalum:Polymer and manganese dioxide cathode systems address niche high-reliability military and medical segments. NHTSA critical mineral traceability requirements complicate sourcing for termination plating.
Multilayer leads volumes today; ceramic is gaining share fastest.
End User:
Qualification intensity and product lifecycle duration separate margin pools across buyer categories.
- Automotive:AEC-Q200 and PPAP Level 3 certifications mandate 18-24 month qualification cycles. Ford and General Motors have compressed base-metal electrode approval timelines, consolidating procurement with suppliers holding captive ceramic powder capabilities.
- Consumer Electronics:High-volume, short-lifecycle demand from smartphone and laptop OEMs prioritizes cost over reliability. 0201 and 0402 form factors dominate, though legacy pick-and-place equipment obsolescence constrains capacity expansion.
- Industrial:Factory automation and motor drive applications require extended temperature ratings with moderate qualification burdens. Midwest manufacturing corridors sustain steady replacement cycles.
- Telecommunications:5G base station and optical module miniaturization drives demand for precision form factors. FCC equipment authorization rules cascade into component traceability requirements.
Automotive commands the steepest expansion trajectory; consumer electronics retains absolute volume leadership.
Application:
Voltage handling and frequency response requirements dictate dielectric selection and electrode metallurgy.
- Power Supply:Input filtering and bulk capacitance in AC-DC converters require high-voltage X1/Y2 safety-rated ceramics. Data center buildouts in Virginia and Oregon sustain demand for 105°C-rated designs.
- DC-DC Conversion:Silicon carbide inverter adoption multiplies ceramic capacitor counts three to five times versus silicon IGBT architectures. Wide-bandgap switching frequencies demand low-ESR X7R formulations.
- Signal Coupling:High-frequency data path isolation in automotive Ethernet and PCIe interfaces favors C0G/NP0 temperature-stable dielectrics. Autonomous vehicle sensor fusion modules create specification windows for ultra-small case sizes.
- EMI Filtering:Common-mode choke integration and ferrite bead pairing address conducted emissions compliance. EPA Tier 3 emissions standards divert R&D budgets toward active filtering, compressing passive component development cycles.
DC-DC conversion is expanding most quickly; power supply maintains installed base dominance.
Form Factor:
Miniaturization limits and pick-and-place equipment economics govern capacity allocation.
- 0402:The migration target for telecom module miniaturization, with equipment transition investments favoring this case size over legacy 0201 lines. Rivian and Tesla supplier parks in Texas specify 0402 for synchronized sequencing compatibility.
- 0603:Industrial and automotive applications with moderate density requirements. General Motors DC-link designs specify 0603 for thermal management headroom in underhood environments.
- 0805:Legacy industrial equipment and cost-optimized consumer designs. Stable replacement demand from Midwest manufacturing facilities.
- 0201:The smallest standard case size faces constrained capacity as depreciation schedules for legacy pick-and-place equipment discourage expansion. Smartphone OEMs face allocation pressure for high-runner specifications.
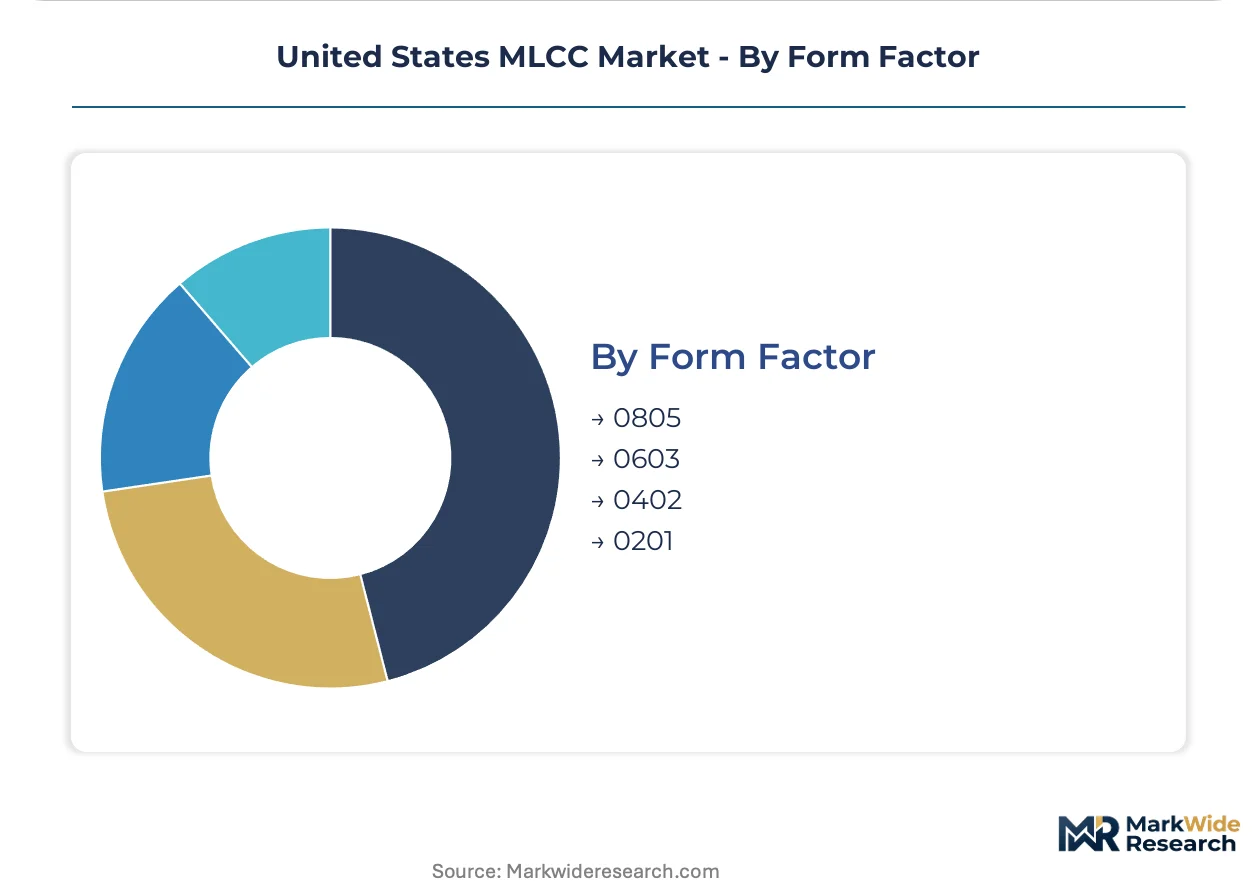
0402 leads forward capacity investments; 0603 retains the broadest application footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive electrification pace trails the United States, while Japan maintains tighter supplier integration with domestic OEMs. Regional demand patterns reflect distinct regulatory frameworks and industrial clustering strategies.
Michigan
Ford and General Motors battery plant investments drive AEC-Q200 qualified MLCC procurement for DC-link applications. The CHIPS Act domestic content provisions condition federal incentives on North American component sourcing. Detroit's supplier parks concentrate high-voltage capacitor demand within 500-mile radii of final assembly.
Texas
Tesla and Rivian gigafactory corridors cluster demand for silicon carbide inverter-compatible capacitors. NHTSA functional safety mandates cascade into extended temperature rating requirements for braking systems. Austin and Dallas-Fort Worth supplier parks synchronize vendor-managed inventory with assembly line sequencing.
California
Autonomous vehicle sensor fusion modules create specification windows for ultra-small automotive-rated form factors. EPA fuel economy rules push electrification architectures requiring higher capacitor counts per vehicle. Silicon Valley LiDAR manufacturers pre-qualify suppliers with captive ceramic powder capabilities.
Ohio
Industrial motor drive replacement cycles sustain steady demand for 0603 and 0805 form factors with moderate qualification burdens. OSHA workplace safety standards influence factory automation component traceability. Cleveland and Cincinnati manufacturing corridors maintain legacy equipment service requirements.
Southeast
Battery assembly investments in Georgia and South Carolina expand DC-link buffering demand for X7R dielectric grades. The IRA clean vehicle tax credits reshape procurement patterns for qualifying domestic content. Atlanta logistics hubs coordinate regional distribution for Tier 1 integrators.
United States MLCC Market Competitive Landscape
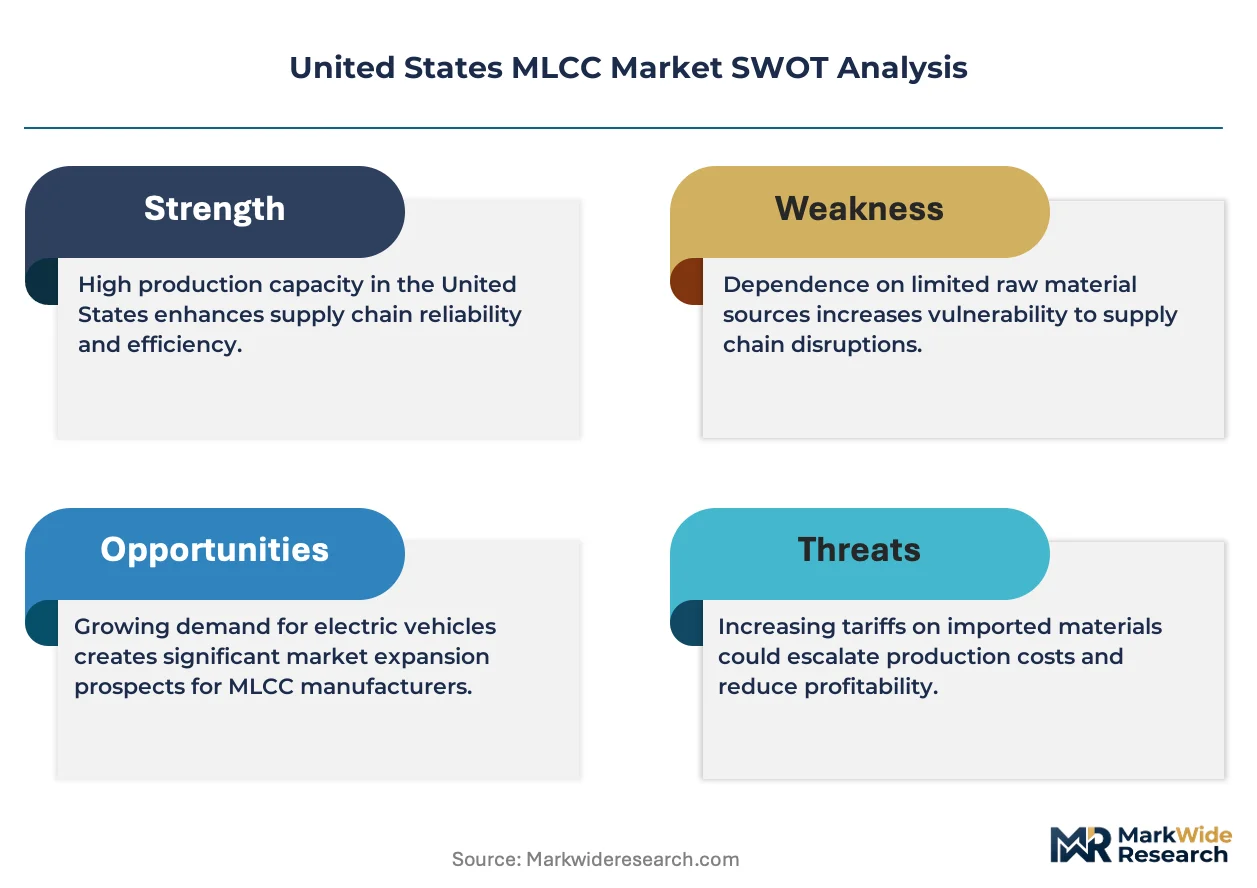
Top-tier vendors anchor premium automotive-grade supply, while commodity consumer electronics tiers concentrate with scale-driven fabricators. Japanese and Korean manufacturers dominate high-reliability qualification pools through captive ceramic powder production. Strategic archetypes separate into backward-integrated material specialists, dedicated automotive capacity operators, and diversified passive component conglomerates. Competitive moves center on AEC-Q200 certification acceleration and domestic production line qualification ahead of 2027 contract renewals.
Within the premium-tier vector, Murata Manufacturing Co., Ltd. and Samsung Electro-Mechanics Co., Ltd. occupy positions reflecting distinct geographic supply strategies. Kyocera AVX Components Corporation exemplifies the specialty high-voltage design archetype for electrified powertrain applications. These three anchors represent contrasting approaches to margin defense: backward integration into ceramic powder production, dedicated regional capacity serving domestic EV manufacturers, and differentiated technical specifications for wide-bandgap power electronics.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| Samsung Electro-Mechanics Co., Ltd. |
| Kyocera AVX Components Corporation |
| TDK Corporation |
| Yageo Corporation |
| Taiyo Yuden Co., Ltd. |
| Vishay Intertechnology Inc. |
| Walsin Technology Corporation |
| Nippon Chemi-Con Corporation |
| Others |
Pricing and Supply Chain Analysis
Barium titanate ceramic powder costs cascade through three distinct pricing tiers as Japanese and Korean material suppliers feed domestic formulation plants serving automotive OEMs. The CHIPS Act domestic content thresholds compress margins on imported dielectric grades while rewarding North American-qualified suppliers with advanced manufacturing tax credits.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for commodity consumer electronics grades, forcing a three-tier pricing structure across premium, standard, and economy levels. AEC-Q200 certification and PPAP Level 3 documentation drive premium tier pricing for Michigan-based EV battery plants, while smartphone OEMs exhibit highest price sensitivity for 0201 and 0402 form factors. Cost compression in standard tiers intensifies as equipment depreciation schedules favor 0402 over legacy 0201 pick-and-place lines.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and Korean ceramic powder suppliers, where barium titanate formulation expertise concentrates among Murata, TDK, and Samsung Electro-Mechanics captive operations. Raw material dependencies span high-purity barium carbonate, titanium dioxide, and rare earth dopants for temperature-stable dielectrics. Tariff exposure on Chinese-sourced termination plating metals compounds NHTSA critical mineral traceability requirements. Distribution runs through direct vendor-managed inventory agreements at Texas and Michigan supplier parks, disintermediating legacy passive component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States MLCC market functions as a regulatory compounder where NHTSA functional safety mandates and CHIPS Act domestic content rules jointly reshape procurement authority toward qualified manufacturers.
For Market Incumbents: Anchor AEC-Q200 certification acceleration ahead of 2027 contract renewals by compressing base-metal electrode qualification timelines from thirty-six to eighteen months. Prioritize captive ceramic powder capabilities to defend margin pools against emerging Korean challengers expanding US footprint. Channel control through direct supplier park agreements at Tesla and Rivian facilities in Texas locks out distributor intermediaries. For New Entrants and Emerging Players: Silicon carbide inverter-compatible high-voltage designs offer technology-first wedge into underpenetrated grid-scale energy storage applications requiring extended life ratings beyond automotive cycles. Target utility battery inverter OEMs in Virginia and Oregon with X7R dielectric grades rated for 105°C continuous operation. Go-to-market angle centers on NHTSA-EPA coordinated critical mineral traceability documentation that incumbent distributors struggle to assemble. For Investors and Strategic Acquirers: Consolidation pressure builds where balance-sheet-strong incumbents possess Class 1000 cleanroom fabrication assets that mid-cap specialists cannot replicate without $400-600 million per greenfield line. Long-term viability favors backward-integrated material specialists with captive barium titanate production and electrode co-firing expertise. Acquisition target archetype: North American-qualified suppliers with AEC-Q200 portfolios and CHIPS Act domestic content compliance infrastructure. Signal to watch: EPA Tier 3 emissions standard revisions that divert OEM R&D budgets toward active filtering, compressing passive component supplier development cycles.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Certification Acceleration | Ford and General Motors compressed timelines reward qualified suppliers with 2027 contract lock-in. |
| Base-Metal Electrode Transition | Nickel and copper electrode systems displace silver-palladium, consolidating procurement with co-firing experts. |
| Supplier Park Direct Agreements | Tesla and Rivian in Texas bypass distributors, cutting lead times from sixteen weeks to four. |
| Critical Mineral Traceability Infrastructure | NHTSA-EPA coordinated rulemaking forces documentation of smelter origins for tantalum and tin plating. |
| Grid-Scale Energy Storage Qualification | Utility battery inverters in Virginia and Oregon represent untapped demand for extended-life high-voltage designs. |
Research Methodology
Direct dialogue with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and ceramic powder formulation specialists grounded qualitative findings in operational reality. Secondary validation drew from NHTSA regulatory filings, EPA emissions compliance databases, SEC 10-K disclosures from listed passive component manufacturers, and vehicle production data from Michigan and Texas automotive clusters. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Bottom-up unit economics segmented by dielectric grade, form factor, voltage rating, and end-user qualification tier fed into value aggregation. Top-down validation cross-referenced CHIPS Act incentive disbursement patterns with announced battery plant capacities in Michigan, Texas, Georgia, and South Carolina. CAGRs derived from installation base growth in silicon carbide inverters and autonomous vehicle sensor fusion modules, calibrated against historical automotive electronics content trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NHTSA autonomous vehicle guidance evolution and domestic foundry buildout timelines for precision form factors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Intel Motherboards Market
Electronic Components
Timing Relay Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
Blockchain in Electronic Component Market
Electronic Components
Electronic Shelf Label Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Touch Screen Controllers Market
Electronic Components
Wireless Charging Stand Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Acoustic Diaphragm Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Electric Vehicle (EV) Electronic Components Market
Electronic Components
Global Smartphone Cover Glass Market
Electronic Components
Global Tantalum Capacitors Market
Electronic Components
Dual Relay Board Market