
 Coaxial Attenuators Market | 2026-2036
Coaxial Attenuators Market Size, Share, and Industry Trends Forecast 2026-2036
Coaxial Attenuators Market Outlook
MIL-PRF-39030 qualification is collapsing the supplier base for mission-critical coaxial attenuators, leaving only certified manufacturers in contention for defense and aerospace contracts. Narda-Miteq leverages its vertical integration across RF component fabrication to sustain pricing power in high-reliability segments. Mini-Circuits anchors volume production for commercial test equipment, while Keysight Technologies competes through captive demand from its own instrumentation portfolio.
Coaxial attenuators are passive RF devices that reduce signal amplitude by a specified decibel value across defined impedance, typically 50 ohms, using resistive film or chip-based elements deposited on ceramic or beryllium oxide substrates; they protect sensitive receiver stages, enable power-level calibration, and isolate mismatched loads in transmission systems. Fixed attenuators dominate unit shipments in telecommunications infrastructure, while programmable attenuators command premium positioning in automated test environments where rapid reconfiguration replaces manual substitution. The 6 GHz to 18 GHz frequency band captures outsized margin pools as 5G mid-band and satellite ground terminal deployments intensify.
FCC Part 15 emissions rules and MIL-STD-202 environmental stress standards govern product certification for US-sold attenuators, with RoHS and REACH restricting hazardous substance content in European-bound supply. The EU AI Act and CSRD reporting frameworks are beginning to ripple into RF component procurement as system integrators document supply chain provenance. Stakeholders must monitor how satellite constellation launches and Open RAN disaggregation reshape volume and specification requirements for precision attenuation.
Market Dynamics
MIL-PRF-39030 qualification requirements are compressing the supplier base for mission-critical coaxial attenuators, forcing procurement officers toward certified manufacturers and reshaping competitive positioning across defense and aerospace verticals.
Growth Catalysts
- 5G Mid-Band Infrastructure:Deployment of 3.5 GHz to 6 GHz base stations across the United States is generating volume demand for precision fixed attenuators in macro cell installations.
- REACH Compliance Deadlines:European material restrictions are accelerating substrate transitions from beryllium oxide to aluminum nitride, creating upgrade cycles in installed telecom infrastructure.
- Satellite Ground Terminal Proliferation:Low-earth orbit constellation buildouts in California and Texas are concentrating procurement for 6-18 GHz programmable attenuators.
Market Restraints
- Beryllium Oxide Supply Concentration:Ceramic substrate fabrication concentrates among a handful of North American specialty materials suppliers, exposing attenuator manufacturers to input bottlenecks.
- MIL-STD-202 Certification Burden:Environmental stress testing timelines extend 18-24 months for new attenuator designs, freezing smaller competitors out of defense procurement.
- Solid-State Power Amplifier Substitution:GaN and GaAs amplifier architectures with integrated gain control are displacing discrete attenuator modules in some radar applications.
Strategic Opportunities
- Open RAN Disaggregation:Interface standardization is creating entry points for attenuator specialists into radio unit supply chains previously dominated by integrated OEMs.
- EU AI Act Supply Chain Documentation:Provenance reporting mandates are rewarding manufacturers with transparent material sourcing and captive ceramic production.
- India Telecom Infrastructure:BharatNet phase-3 rural broadband expansion represents underpenetrated volume demand for cost-optimized fixed attenuator families.
Industry Challenges
- Thin-Film Resistive Deposition Expertise:Qualified process engineers for precision resistor patterning on ceramic substrates remain scarce, constraining capacity expansion.
- Legacy Test Equipment Integration:Automated calibration systems in existing manufacturing lines require costly retrofitting to accommodate programmable attenuator interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coaxial Attenuators Market |
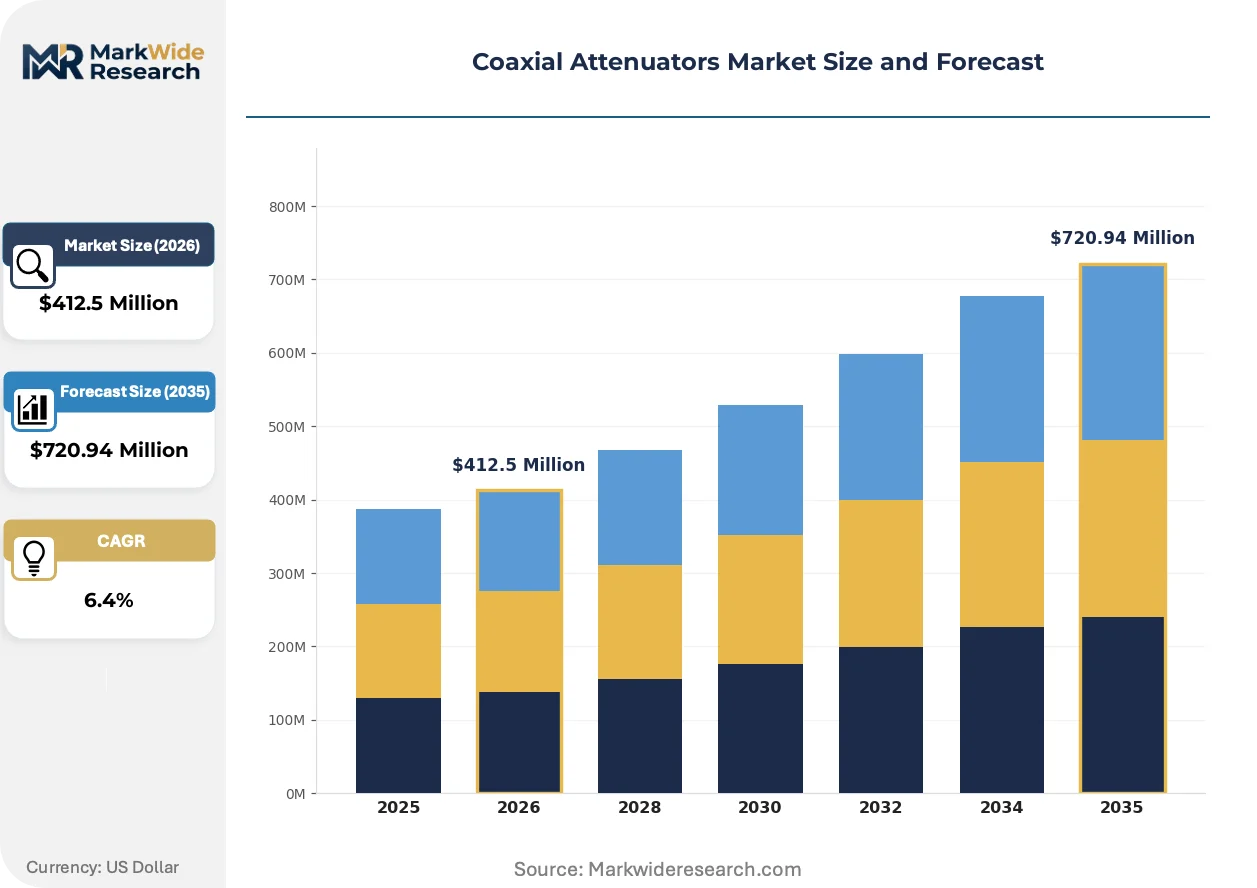
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Attenuators, Variable Attenuators, Programmable Attenuators, Load Resistors Frequency Range: DC to 1 GHz, 1 GHz to 6 GHz, 6 GHz to 18 GHz, 18 GHz to 40 GHz Connector Type: SMA, N-Type, BNC, TNC Application: Telecommunications, Broadcasting, Testing, Instrumentation |
| Companies Covered | Narda-Miteq, Mini-Circuits, Infinite Electronics, Hirose Electric, Amphenol, Huber+Suhner, SV Microwave, Keysight Technologies, Radiall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coaxial Attenuators Market Strategic Shifts
RF component architectures are fragmenting as system designers trade integration for flexibility, creating openings for specialized attenuator suppliers in disaggregated signal chains.
Silicon-on-insulator switch matrices is decomposing traditional relay-based programmable attenuator architectures. 5G base station OEMs in South Korea are adopting these solid-state alternatives for rapid beam-steering calibration. The shift is compressing mechanical attenuator margins while expanding addressable market for semiconductor-based solutions.
EU CSRD reporting frameworks are mandating lifecycle carbon documentation for electronic components sold into European infrastructure. Attenuator manufacturers must now trace ceramic sintering energy consumption and precious metal content through tier-three suppliers. Defense integrators with EU satellite ground stations are screening procurement lists for CSRD-compliant component sources.
Buyer consolidation among test equipment lessors is compressing replacement cycles for precision attenuators. Keysight and Rohde & Schwarz calibration service networks now specify multi-year attenuator performance guarantees, shifting risk onto component suppliers. This pattern concentrates most visibly in US aerospace clusters where captive metrology labs dominate instrument sourcing.
Coaxial Attenuators Market Segmentation
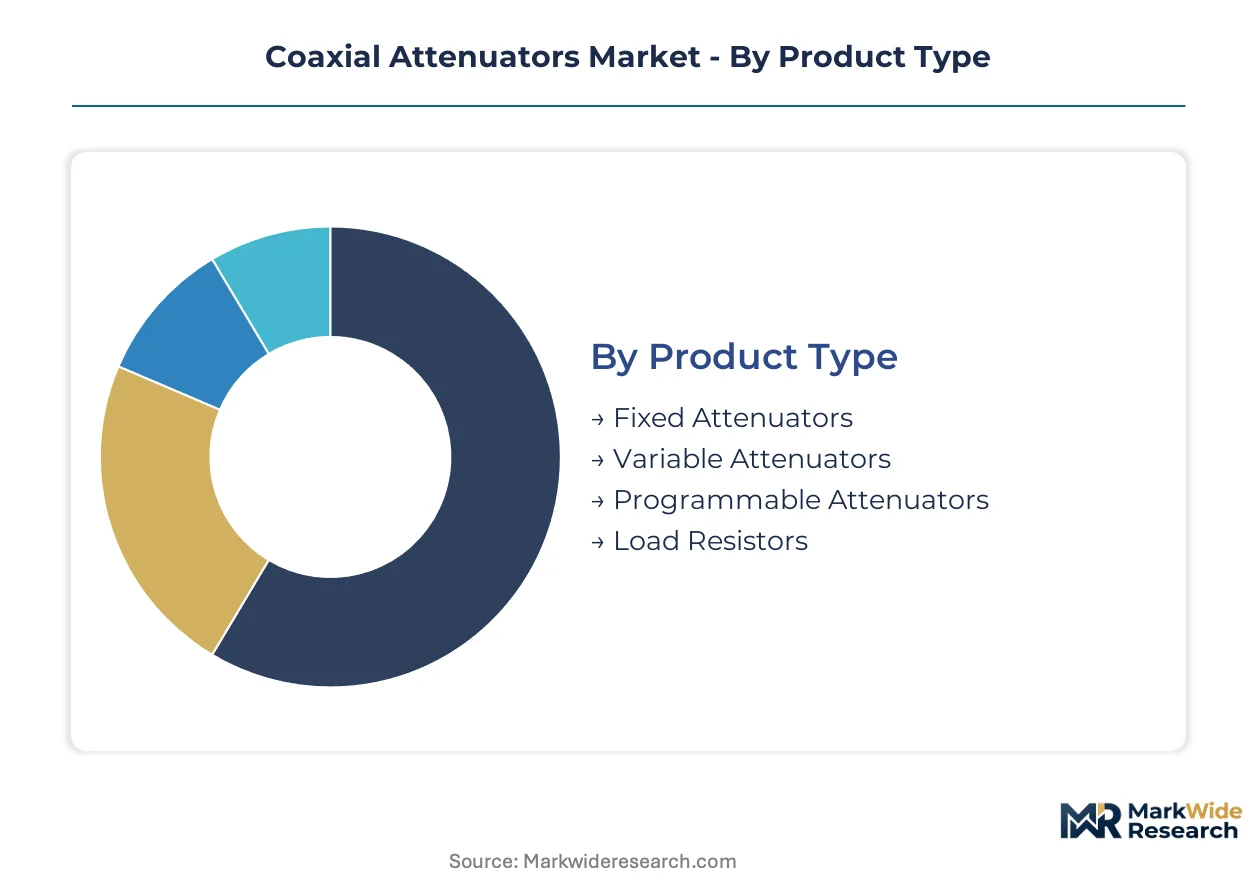
Segmentation in coaxial attenuators reveals how procurement channels fragment across defense certification requirements, commercial volume economics, and precision calibration standards. Channel strategy must align with whether buyers prioritize MIL-PRF-39030 traceability, cost-optimized telecommunications scale, or programmable flexibility for automated test environments.
Product Type:
Fixed attenuators flow through high-volume distribution channels serving telecommunications infrastructure, while programmable variants route through specialized RF component distributors and direct OEM relationships.
- Fixed Attenuators:Resistive film elements deposited on ceramic substrates deliver predetermined attenuation values in compact surface-mount or connectorized packages. Demand concentrates in United States 5G macro cell deployments where California and Texas base station buildouts require precision power-leveling components. REACH-driven substrate transitions from beryllium oxide to aluminum nitride are accelerating replacement cycles in European-bound supply chains.
- Programmable Attenuators:Solid-state PIN diode or MEMS switch matrices enable rapid electronic adjustment of attenuation levels under digital control. Satellite ground terminal procurement in California aerospace clusters favors these units for automated calibration sequences in low-earth orbit communication systems. Solid-state architectures are displacing electromechanical alternatives in beam-steering applications.
- Variable Attenuators:Manual or motorized adjustment mechanisms allow continuous attenuation tuning across specified ranges.
- Load Resistors:Termination devices absorb RF power to prevent signal reflection at unused ports.
By volume, Fixed Attenuators leads. By growth pace, Programmable Attenuators is ahead.
Frequency Range:
Cost tier stratification runs inverse to frequency, with DC-to-6 GHz segments competing on price and 18+ GHz bands commanding premium positioning through specialized foundry relationships.
- 6 GHz to 18 GHz:Mid-band coverage spans 5G n77/n78 deployments and satellite downlink frequencies with demanding linearity specifications. Defense electronics procurement in Texas anchors demand for qualified attenuators in radar front-end and electronic warfare subsystems. FCC Part 15 emissions certification complexity limits supplier participation.
- 18 GHz to 40 GHz:Millimeter-wave precision requires thin-film resistive deposition on ultra-low-loss ceramic substrates with sub-micron patterning accuracy. 5G mmWave base station testing in South Korea and United States R&D facilities drives calibration-grade demand. Environmental stress screening per MIL-STD-202 extends qualification timelines.
- DC to 1 GHz:Established designs serve legacy broadcast and industrial RF applications with mature cost structures.
- 1 GHz to 6 GHz:Cellular and Wi-Fi infrastructure bands dominate commercial volume shipments.
By revenue contribution, 6 GHz to 18 GHz leads. By expansion trajectory, 18 GHz to 40 GHz climbs the fastest.
Connector Type:
Application maturity determines connector selection, with instrumentation favoring precision interfaces and telecommunications prioritizing rapid-deployment compatibility.
- SMA:Subminiature threaded interface dominates precision test equipment and laboratory environments through 18 GHz with reliable repeatability. United States aerospace clusters in California specify SMA for satellite payload integration where size constraints and electrical performance converge. RoHS compliance mandates affect plating chemistry selections.
- N-Type:Rugged threaded design handles higher power levels in base station and broadcast transmitter applications. Texas telecommunications infrastructure deployment favors N-Type for outdoor macro cell installations where environmental sealing and mechanical durability outweigh size penalties.
- BNC:Bayonet coupling enables quick-connect functionality in video and lower-frequency RF systems.
- TNC:Threaded variant of BNC improves vibration resistance in mobile and aerospace platforms.
By installation base, N-Type leads. By specification density in new designs, SMA is ahead.
Application:
Customer type fragmentation separates defense-aerospace procurement with rigid qualification requirements from commercial segments where cost and availability dominate.
- Telecommunications:Base station power leveling, distributed antenna systems, and fiber-to-the-antenna links consume attenuators in million-unit annual volumes. BharatNet rural broadband expansion in India represents underpenetrated demand for cost-optimized fixed attenuator families. Open RAN disaggregation is creating procurement entry points for specialized suppliers.
- Testing:Automated calibration systems and vector network analyzer accessories require programmable attenuators with guaranteed repeatability across temperature cycles. Keysight and Rohde & Schwarz service networks in United States metropolitan areas now specify multi-year performance guarantees.
- Broadcasting:Transmitter power control and studio signal distribution employ fixed attenuators with emphasis on thermal stability.
- Instrumentation:Portable and rack-mounted RF measurement equipment integrates attenuators as built-in ranging elements.
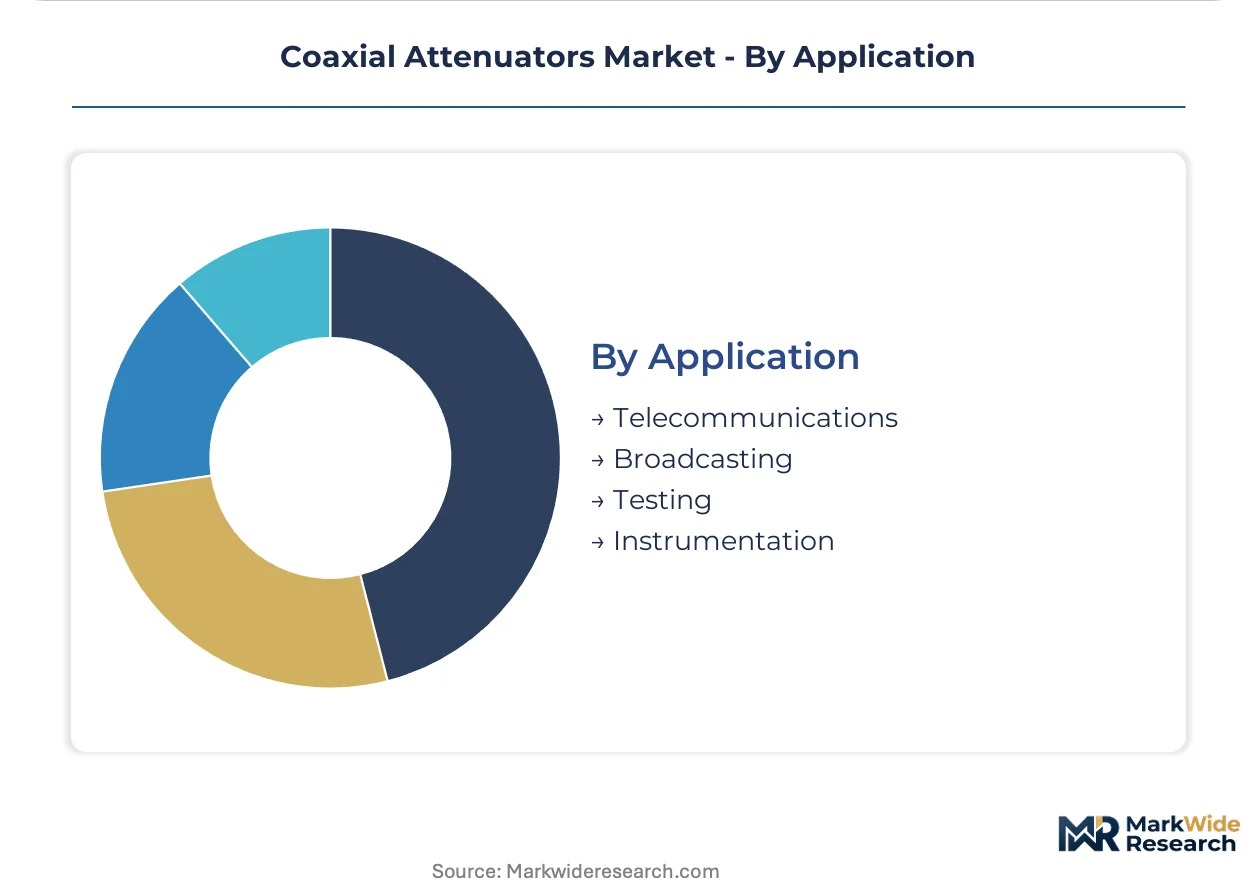
By unit volume, Telecommunications leads. By margin structure, Testing is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement incentives and telecommunications infrastructure subsidies are concentrating coaxial attenuator demand in aerospace clusters and 5G deployment corridors across multiple economies.
United States
MIL-PRF-39030 qualification requirements and FCC Part 15 emissions rules govern defense and commercial procurement respectively. California aerospace clusters around Los Angeles and San Diego anchor satellite payload integration demand, while Texas telecommunications infrastructure deployment favors ruggedized N-Type connectors for outdoor macro cells.
Germany
Industrial automation and automotive radar testing sustain precision attenuator demand in measurement applications. REACH compliance deadlines from ECHA accelerate substrate material transitions in European-bound supply chains, with Baden-Württemberg hosting RF component distribution hubs serving continental test equipment markets.
China
MIIT 5G base station deployment targets and dual carbon goals reshape domestic procurement priorities. Yangtze River Delta manufacturing corridors concentrate ceramic substrate fabrication capacity, while Beijing-Tianjin-Hebei R&D clusters drive millimeter-wave attenuator development for domestic instrumentation.
South Korea
METI-coordinated 5G mmWave testing programs and semiconductor foundry expansion sustain calibration-grade attenuator demand. Seoul Capital Area hosts automated test equipment lessors specifying multi-year performance guarantees, while Busan-Ulsan corridors supply connectorized assemblies for export markets.
India
BharatNet phase-3 rural broadband expansion and PLI scheme incentives for telecom equipment manufacturing create volume opportunities. Karnataka and Tamil Nadu electronics manufacturing clusters absorb cost-optimized fixed attenuator families for domestic base station assembly.
Coaxial Attenuators Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, with public companies leveraging capital access for qualification investments and family-owned entities dominating niche ceramic fabrication. The supplier base compresses around MIL-PRF-39030 traceability requirements, leaving certified incumbents to capture defense-aerospace premiums while commercial volumes fragment among scale operators. Three archetypes dominate: vertically integrated substrate-to-assembly manufacturers, fabless design houses with captive test equipment demand, and regional distributors with local calibration service networks. Consolidation proceeds through qualification-burdened acquisition of smaller certified players and strategic partnerships between ceramic suppliers and attenuator assemblers.
Among US-based defense-qualified fabricators, Narda-Miteq occupies a position exemplifying vertical integration across RF component production, while Mini-Circuits represents the volume-driven commercial tier with distribution-heavy market presence. Keysight Technologies anchors the captive-demand archetype through its instrumentation portfolio creating internal attenuator consumption.
| Leading Market Players |
|---|
| Narda-Miteq |
| Mini-Circuits |
| Infinite Electronics |
| Hirose Electric |
| Amphenol |
| Huber+Suhner |
| SV Microwave |
| Keysight Technologies |
| Radiall |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for beryllium oxide and aluminum nitride substrates lock in both supply access and price visibility for defense-qualified attenuator manufacturers, insulating MIL-PRF-39030 certified suppliers from spot-market volatility while compressing margins for non-certified competitors excluded from aerospace procurement channels.
Pricing Analysis
Certification level (MIL-PRF-39030 vs. commercial-grade) creates the primary spread between premium and economy tiers, with qualified defense-aerospace attenuators commanding substantial premiums over telecommunications volume products. Three-tier pricing structure separates mission-critical qualified units from standard commercial test equipment components and cost-optimized fixed attenuators for infrastructure. Cost compression in the commercial tier is intensifying because Open RAN disaggregation invites price competition from new substrate-to-assembly specialists. Telecommunications OEMs exhibit highest price sensitivity, while defense integrators prioritize traceability and qualification pedigree over unit cost.
Supply Chain Analysis
Port congestion on trans-Pacific lanes and container availability constraints at Long Beach and Los Angeles are elevating inbound logistics costs for ceramic substrate shipments from East Asian fabrication centers. Ceramic substrate supply concentrates in the United States, Japan, and China, with beryllium oxide drawing from a handful of North American specialty materials suppliers. Aluminum nitride powder and precious metal thick-film pastes constitute critical input dependencies. Single-source vulnerability around beryllium oxide extraction exposes qualified manufacturers to input bottlenecks. Distribution runs through specialized RF component distributors and direct OEM relationships for programmable variants, while fixed attenuators flow through high-volume electronics distribution serving telecommunications infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
5G mid-band infrastructure deployment and satellite constellation proliferation are disrupting traditional RF component procurement patterns, creating asymmetric opportunities across certification tiers and frequency bands.
For Market Incumbents: Consolidate around MIL-PRF-39030 qualification barriers by acquiring smaller certified players facing 18-24 month environmental stress testing timelines, while deepening backward integration into ceramic substrate fabrication to secure beryllium oxide and aluminum nitride supply against single-source concentration risk. GaN and GaAs amplifier architectures with integrated gain control threaten discrete attenuator modules in radar applications, demanding R&D investment in programmable solid-state alternatives. For New Entrants and Emerging Players: Calibration service networks for automated test equipment represent a service-layer gap where incumbents under-serve, with Keysight and Rohde & Schwarz multi-year performance guarantees shifting risk onto component suppliers and creating white-space for independent service specialists. India BharatNet phase-3 rural broadband expansion offers the most penetrable geography for cost-optimized fixed attenuator families. Open RAN interface standardization enables direct radio unit supply chain entry previously blocked by integrated OEMs. For Investors and Strategic Acquirers: Family-owned ceramic fabrication specialists with captive sintering capacity and transparent material sourcing documentation represent the priority acquisition archetype, as EU CSRD provenance mandates and EU AI Act supply chain reporting reward manufacturers with tier-three supplier traceability. Long-term viability hinges on positioning for satellite ground terminal proliferation and Open RAN disaggregation over a multi-year horizon. The signal to monitor is silicon-on-insulator switch matrix adoption rates in South Korean 5G base station OEMs, as this substitution trajectory indicates displacement risk for mechanical programmable architectures.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-PRF-39030 Certification Investment | Qualification barriers collapse supplier base, concentrating defense-aerospace premiums among certified incumbents. |
| Backward Integration into Ceramic Substrates | Captive aluminum nitride production insulates against REACH-driven beryllium oxide transitions and supply concentration. |
| Solid-State Programmable Attenuator Development | PIN diode and MEMS architectures capture beam-steering calibration demand displacing electromechanical alternatives. |
| India Distribution Partnership | BharatNet phase-3 rural broadband creates volume outlet for cost-optimized fixed attenuator families. |
| CSRD-Compliant Supply Chain Documentation | Lifecycle carbon tracing and tier-three provenance screening secure procurement eligibility for EU satellite ground stations. |
Study Parameters
Operator-level perspectives from RF component procurement officers at defense integrators, telecommunications infrastructure OEMs, automated test equipment lessors, and satellite ground terminal manufacturers anchored the qualitative base, supplemented by regulatory affairs specialists at ECHA and FCC, and ceramic substrate fabrication engineers. Primary interview insights combined with secondary validation from MIIT 5G deployment disclosures, ECHA REACH substance restriction updates, FCC Part 15 emissions filings, and SEC 10-K filings from listed RF component manufacturers. Bottom-up volume modeling across product type, frequency band, and application segments triangulated against top-down infrastructure investment forecasts.
Sensitivity analysis around substrate material transition timelines, satellite constellation launch cadence, and Open RAN adoption rates tested forecast robustness across the projection horizon. Segmentation dimensions modeled include product architecture (fixed, programmable, variable), frequency range (DC-6 GHz, 6-18 GHz, 18-40 GHz), connector interface (SMA, N-Type, BNC, TNC), and end-use application (telecommunications, testing, broadcasting, instrumentation). CAGRs derived from polynomial trend fitting of historical shipment data adjusted for technology substitution effects and regulatory-driven replacement cycles. Millimeter-wave test equipment calibration demand and defense electronics procurement patterns served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FCC emissions certification, ECHA REACH compliance deadlines, and MIIT 5G infrastructure targets; material policy shifts would require re-modeling. Technology substitution risk from solid-state amplifier integration and supply disruption from beryllium oxide sourcing constraints represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Frequency Control and Timing Devices Market
Electronic Components
US Supercapacitor Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
Safety Relay Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Europe PCB Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Coaxial Coupler Market
Electronic Components
Industrial Relays Market
Electronic Components
Microspeaker Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Blockchain in Electronic Component Market
Electronic Components
Crystal Oscillators Market
Electronic Components
Capacitive Stylus Pen Market
Electronic Components
Radiation Hardened Electronics Market