
 Blockchain in Electronic Component Market | 2026-2036
Blockchain in Electronic Component Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain in Electronic Component Market Outlook
Market Context
The gap between premium authenticated components and commodity unverified parts is shifting as blockchain verification becomes a procurement gate. NVIDIA Corporation leverages its GPU architecture to anchor high-performance blockchain validation nodes for semiconductor traceability. Samsung Electronics sustains manufacturing-scale integration by embedding ledger verification into its foundry-to-assembly workflows. IBM competes through enterprise-grade platforms that connect tier-three suppliers to OEM audit systems.
Technical Foundation and Segment Structure
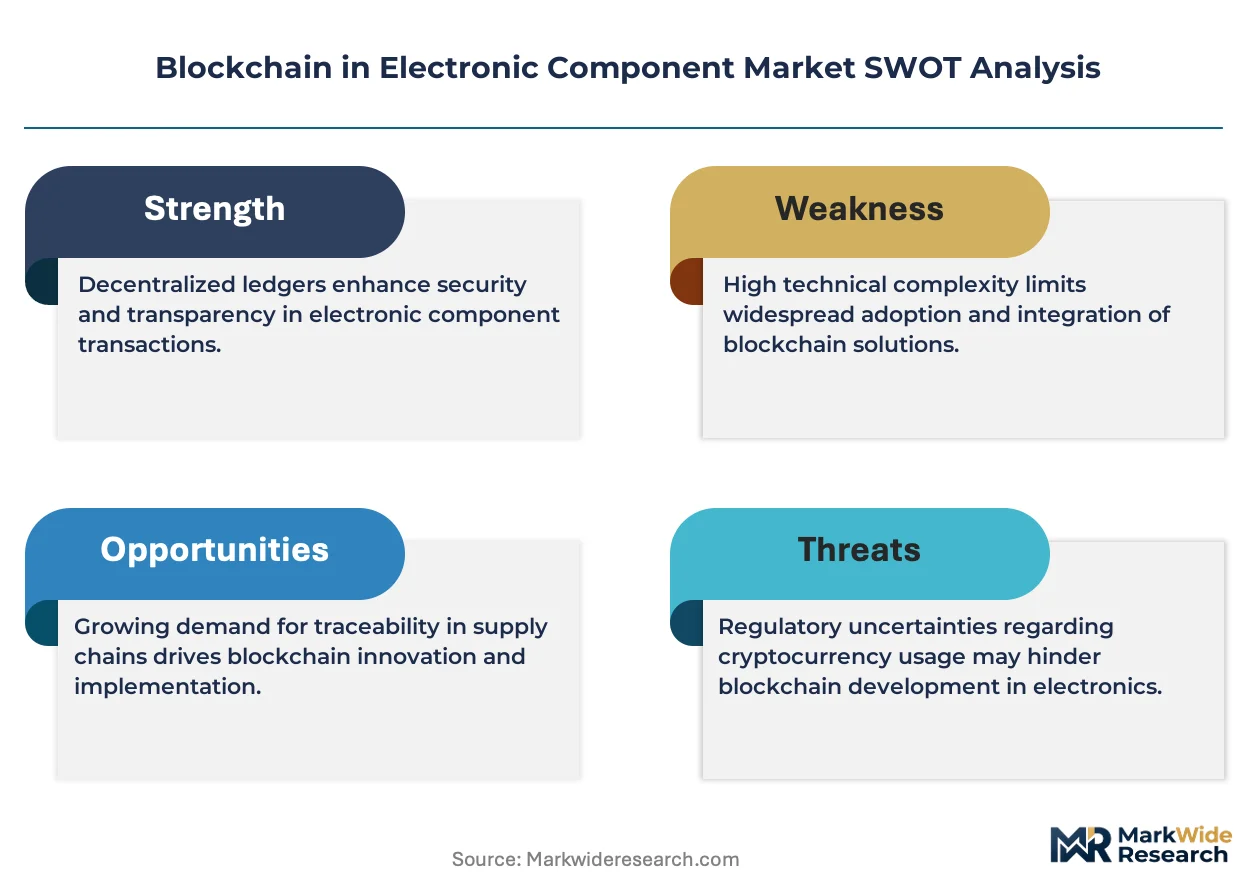
Blockchain in electronic components denotes distributed ledger systems that cryptographically record component origin, test parameters, custody transfers, and compliance certificates across multi-tier supply chains, typically operating with SHA-256 hashing and consensus mechanisms to ensure tamper-evident records. Smart Contracts and Private Blockchain configurations lead current deployments because manufacturers require permissioned access with automated enforcement of procurement rules. Supply Chain Management applications capture the deepest margin pools as aerospace, automotive, and medical device buyers mandate end-to-end traceability for liability reduction.
Regulatory Environment and Outlook
The EU Green Deal's digital product passport requirements and REACH substance tracking obligations are reshaping compliance architectures for component suppliers serving European manufacturers. FDA device traceability rules and SEC climate disclosure mandates in the United States add parallel pressure for immutable chain-of-custody records. Stakeholders must decide whether to build captive ledger infrastructure or subscribe to multi-enterprise platforms before procurement specifications harden around verified traceability tiers.
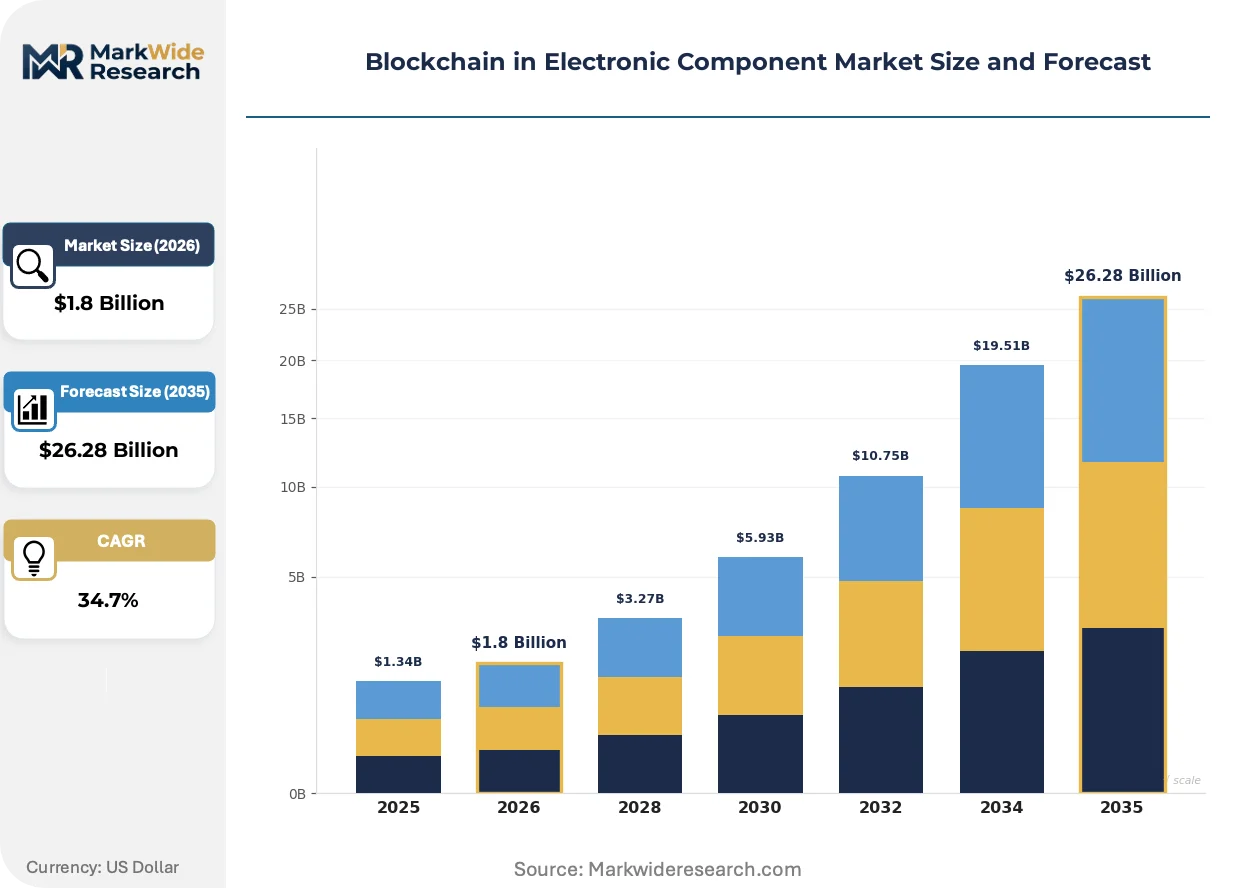
Market Dynamics
Blockchain verification is consolidating as a procurement gate between authenticated and commodity component tiers, with EU Green Deal mandates forcing supply chain reconfiguration before digital product passport deadlines harden.
Growth Catalysts
- EU Green Deal mandates:Digital product passport requirements under REACH substance tracking obligations are compelling tier-three suppliers to adopt immutable ledger systems for component provenance documentation.
- Aerospace traceability demands:Defense contractors now specify blockchain-verified chain-of-custody records for mission-critical semiconductors, reducing liability exposure through cryptographic audit trails.
- Smart contract automation:Permissioned ledger configurations with automated procurement rule enforcement are compressing supplier onboarding cycles and reducing manual compliance verification costs.
Market Restraints
- Foundry-to-ledger integration costs:Embedding SHA-256 hashing and consensus mechanisms into existing semiconductor manufacturing execution systems requires substantial capital redeployment at mature fabrication facilities.
- Supplier concentration in East Asian foundries:Taiwan and South Korea-based semiconductor manufacturers control critical wafer supply, creating geopolitical friction for Western OEMs seeking ledger-verified component sourcing.
- Interoperability limitations:Competing private blockchain protocols lack standardized data exchange formats, fragmenting multi-enterprise platform adoption across tiered supply networks.
Strategic Opportunities
- India's electronics manufacturing clusters:PLI scheme incentives for semiconductor assembly and testing are creating greenfield opportunities for native blockchain infrastructure deployment without legacy system retrofit burdens.
- Medical device traceability convergence:FDA device traceability rules intersecting with SEC climate disclosure mandates are opening unified ledger platforms that serve dual compliance architectures for US-based manufacturers.
- AI-ledger hybrid verification:Machine learning anomaly detection layered atop distributed consensus mechanisms is emerging as a differentiated offering for high-reliability component authentication.
Industry Challenges
- Distributed systems engineering scarcity:Cryptographic protocol design expertise remains concentrated among specialized consultancies, constraining manufacturer ability to build captive ledger infrastructure.
- Multi-tier data standardization:Harmonizing test parameter formats, custody transfer protocols, and compliance certificate schemas across OEM, tier-one, and tier-two supplier systems requires prolonged negotiation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain in Electronic Component Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Contracts, Public Ledger, Private Blockchain, Consortium Blockchain Application: Supply Chain Management, Secure Transactions, Digital Identity, Asset Management End User: Manufacturers, Retailers, Distributors, Supply Chain Managers Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud |
| Companies Covered | NVIDIA Corporation, Samsung Electronics, Canaan, IBM, Oracle, AWS, Huawei, Accenture, Chronicled, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain in Electronic Component Market Strategic Shifts
Permissioned blockchain architectures are actively displacing public ledger approaches as manufacturers prioritize data sovereignty and automated enforcement of procurement specifications over decentralized transparency.
Zero-knowledge proof implementations are consolidating around semiconductor authentication use cases, enabling component origin verification without exposing proprietary supplier pricing or yield data. Medical device manufacturers in Germany's industrial corridor around Munich and Stuttgart are piloting these cryptographic methods for FDA-aligned traceability. The structural consequence is compressing audit preparation timelines from months to days while maintaining regulatory defensibility.
REACH substance tracking obligations under the EU Green Deal are mandating immutable chain-of-custody records for electronic components containing conflict minerals or restricted substances. Automotive OEMs serving European assembly plants must now connect tier-three smelter certifications directly to finished vehicle compliance documentation. Battery-electric vehicle manufacturers are responding fastest, integrating ledger nodes into their cell supplier qualification workflows ahead of 2027 enforcement thresholds.
Buyer concentration among aerospace and defense prime contractors is forcing component distributors to unbundle traceability verification from physical logistics services. Tier-one distributors now offer standalone blockchain attestation subscriptions to smaller EMS providers lacking direct OEM relationships. This pattern is most visible in Southern California's defense electronics cluster, where Northrop Grumman and Raytheon procurement specifications are reshaping regional distributor capability investments.
Blockchain in Electronic Component Market Segmentation
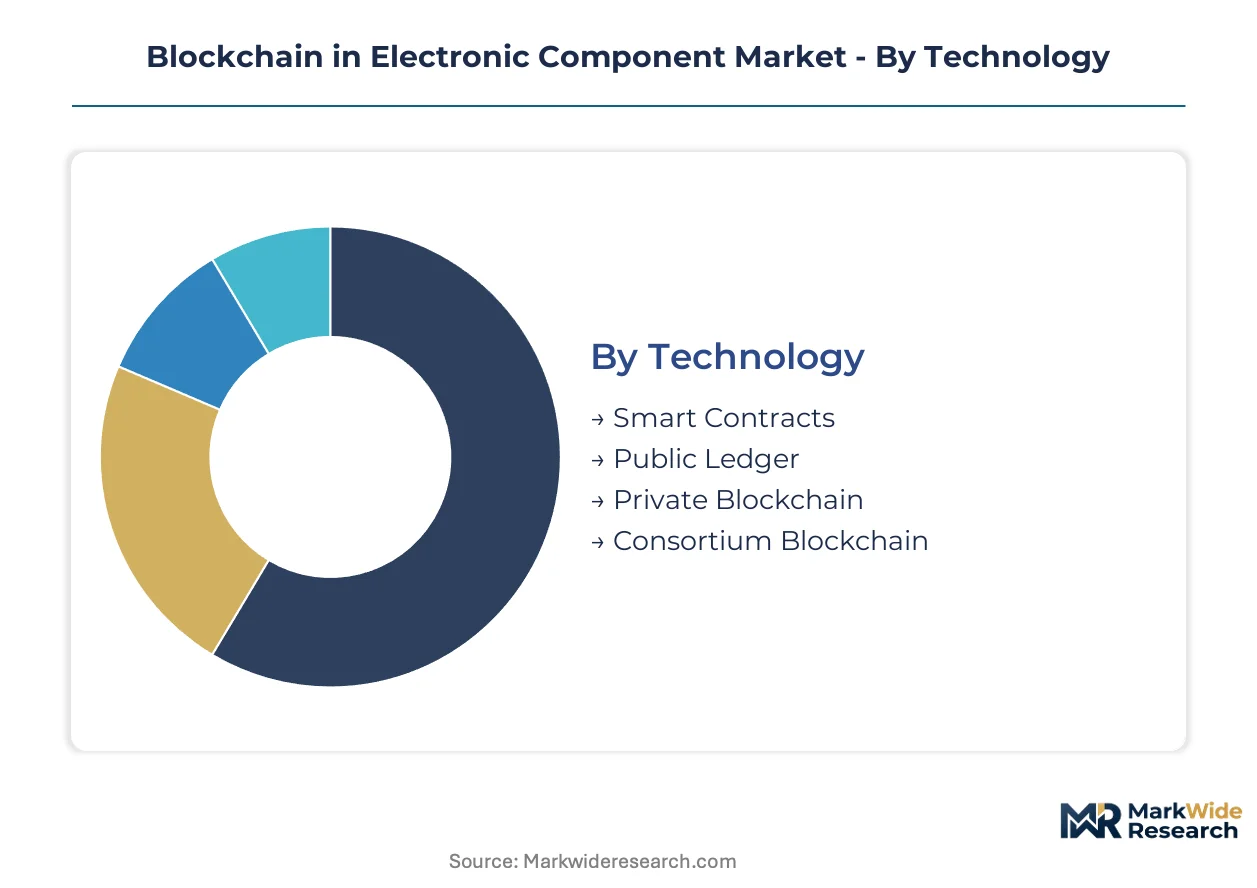
Segmentation in blockchain-enabled electronic components reveals how procurement specifications harden around specific technical configurations. Buyers now select ledger architectures based on regulatory exposure and supply chain tier depth rather than generic technology preferences.
Technology:
Volume deployments favor permissioned configurations, while premium implementations invest in cryptographic sophistication for multi-party verification.
- Smart Contracts:Self-executing code modules automate procurement rule enforcement across supplier tiers. Aerospace primes in Germany's industrial corridor specify these for REACH-compliant component qualification, compressing audit cycles from months to days.
- Private Blockchain:Permissioned ledger architectures restrict node participation to vetted supply chain members. Medical device manufacturers serving FDA-regulated markets favor these for data sovereignty, isolating proprietary yield data from competitors while maintaining immutable audit trails.
- Public Ledger:Open participation models suit commodity component verification where transparency outweighs confidentiality needs.
- Consortium Blockchain:Multi-enterprise governance structures balance decentralization with controlled access for tiered supplier networks.
Today's leader: Private Blockchain. Tomorrow's challenger: Smart Contracts.
Application:
Functional deployment patterns track directly to liability exposure and regulatory mandate intensity across end-use sectors.
- Supply Chain Management:Distributed ledger systems cryptographically record component origin, test parameters, and custody transfers across multi-tier networks. Battery-electric vehicle manufacturers integrate these nodes into cell supplier workflows ahead of EU Green Deal enforcement thresholds.
- Secure Transactions:Cryptographic settlement layers protect high-value component exchanges between geographically dispersed trading partners.
- Digital Identity:Decentralized credentialing systems authenticate component provenance without exposing supplier pricing structures.
- Asset Management:Tokenized representation of physical inventory enables fractional ownership and collateralization of component stockpiles.
Supply Chain Management commands current procurement budgets. Secure Transactions is climbing the fastest as financial settlement layers merge with physical logistics.
End User:
Organizational role determines ledger access requirements and automation depth.
- Manufacturers:OEMs and EMS providers anchor ledger infrastructure investments, embedding SHA-256 hashing into manufacturing execution systems for immutable production records.
- Supply Chain Managers:Specialized coordinators orchestrate multi-enterprise platform subscriptions for tier-two and tier-three supplier onboarding.
- Distributors:Physical logistics providers unbundle traceability verification as standalone attestation services for smaller EMS providers lacking direct OEM relationships.
- Retailers:End-market sellers access verified component documentation through distributor-mediated platform subscriptions.
Manufacturers dominate infrastructure ownership. Supply Chain Managers are gaining share fastest as intermediation specialization deepens.
Deployment:
Hosting architecture selection reflects data residency requirements and integration complexity with legacy manufacturing systems.
- On-Premises:Captive server installations serve defense contractors with air-gapped security requirements for mission-critical semiconductor traceability.
- Cloud-Based:Third-party hosted nodes reduce capital deployment for mid-tier suppliers entering blockchain verification without dedicated IT infrastructure.
- Hybrid:Split architectures isolate sensitive cryptographic operations on-premises while leveraging cloud scalability for non-critical data processing.
- Multi-Cloud:Redundant hosting across independent providers ensures continuity for aerospace programs requiring guaranteed ledger availability.
Cloud-Based deployments lead adoption velocity. Hybrid configurations represent the steepest expansion trajectory as sovereignty requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cryptographic protocol engineers concentrate in Germany's industrial corridor, anchoring European blockchain verification development for semiconductor supply chains.
United States
Aerospace prime contractors in Southern California's defense electronics cluster mandate blockchain-verified chain-of-custody records for mission-critical semiconductors. FDA device traceability rules and SEC climate disclosure mandates compel medical device and industrial manufacturers to adopt immutable ledger systems. Northrop Grumman and Raytheon procurement specifications are reshaping regional distributor capability investments around cryptographic audit trails.
Germany
Automotive OEMs and medical device manufacturers in the Munich-Stuttgart industrial corridor drive demand for zero-knowledge proof implementations enabling component origin verification. EU Green Deal digital product passport requirements under REACH substance tracking obligations accelerate ledger adoption ahead of enforcement thresholds. Battery-electric vehicle manufacturers integrate blockchain nodes into cell supplier qualification workflows throughout Bavaria and Baden-Württemberg.
China
Domestic semiconductor assembly and testing facilities in the Yangtze River Delta and Pearl River Delta regions expand ledger infrastructure for export compliance. MIIT standards for industrial blockchain applications guide state-backed pilot programs in major manufacturing hubs. Shenzhen and Shanghai-based electronics manufacturers embed distributed ledger verification into foundry-to-assembly workflows for European-bound component shipments.
South Korea
Memory and foundry giants in the Seoul Capital Area and Busan-Ulsan region sustain manufacturing-scale blockchain integration for global OEM audit compliance. Samsung Electronics anchors domestic ledger infrastructure development, embedding SHA-256 hashing into semiconductor production execution systems. Government-backed initiatives in Daejeon-Sejong support cryptographic protocol research for supply chain traceability applications.
India
PLI scheme incentives for semiconductor assembly and testing create greenfield opportunities for native blockchain infrastructure in Karnataka and Tamil Nadu electronics manufacturing clusters. Bangalore and Chennai-based EMS providers deploy cloud-hosted ledger nodes without legacy system retrofit burdens. The country's central bank and DGFT guidelines on digital documentation accelerate permissioned ledger adoption for export-oriented component verification.
Blockchain in Electronic Component Market Competitive Environment
Capital-heavy semiconductor foundries compete with asset-light enterprise software providers for blockchain infrastructure dominance in electronic component verification. The vendor base stratifies across three tiers: GPU and chip manufacturers anchoring high-performance validation nodes, cloud and IT services firms hosting multi-enterprise platforms, and specialized blockchain consultancies delivering cryptographic protocol design. Dominant competitive moves include strategic partnerships connecting tier-three suppliers to OEM audit systems and technology licensing agreements embedding ledger verification into manufacturing execution systems.
Within the GPU-centric validation tier, NVIDIA Corporation represents high-performance blockchain node architecture for semiconductor traceability applications. Samsung Electronics exemplifies manufacturing-scale integration, embedding ledger verification into captive foundry-to-assembly workflows. IBM occupies a position among enterprise-grade platform providers, offering multi-enterprise connectivity for tiered supplier networks. These three anchors illustrate the competitive spectrum from hardware-centric to software-centric blockchain infrastructure deployment.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Samsung Electronics |
| Canaan |
| IBM |
| Oracle |
| AWS |
| Huawei |
| Accenture |
| Chronicled |
| Others |
Value Chain & Pricing Dynamics
SHA-256 hashing hardware costs cascade from GPU validation nodes through three downstream pricing tiers, with EU Green Deal compliance premiums compressing margins for tier-three suppliers lacking captive foundry relationships.
Pricing Analysis
Blockchain attestation services unbundle from physical logistics as distributors offer standalone verification subscriptions to smaller EMS providers. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth: premium tiers embed zero-knowledge proof implementations for FDA-aligned medical device traceability, while economy tiers offer basic provenance documentation without cryptographic sophistication. Pricing pressure stems from cloud-hosted ledger commoditization as AWS and Oracle compete on node-hosting economics. Tier-three semiconductor suppliers exhibit highest price sensitivity, deferring blockchain investments until OEM procurement specifications mandate verified traceability tiers.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for semiconductor assembly and testing, redirecting investment from legacy East Asian hubs. Critical wafer supply draws from Taiwan, South Korea, and the United States, with advanced packaging substrates sourcing from Japan and Germany. Single-source vulnerability concentrates in Taiwan's foundry ecosystem, where geopolitical friction threatens Western OEM access to ledger-verified components. Distribution runs through tier-one electronics distributors who now mediate blockchain platform access for smaller EMS providers lacking direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain verification margins expand as EU Green Deal deadlines force premium-tier procurement shifts, compressing cost-to-serve for cloud-hosted ledger providers while rewarding cryptographic protocol specialists.
For Market Incumbents: Acquire cryptographic protocol engineering teams to defend against specialized consultancies capturing high-margin zero-knowledge proof implementations. Samsung Electronics exemplifies manufacturing-scale integration by embedding SHA-256 hashing into captive foundry workflows; competitors must replicate this backward integration or cede tier-one OEM relationships. NVIDIA Corporation anchors high-performance validation node architecture; GPU manufacturers should extend into software-layer platform subscriptions before cloud providers commoditize node hosting.
For New Entrants and Emerging Players: Cloud-native ledger platforms offer the most penetrable entry vector for mid-tier suppliers seeking blockchain verification without captive IT infrastructure. India's PLI scheme electronics manufacturing clusters present greenfield deployment opportunities without legacy system retrofit burdens. Target medical device traceability convergence where FDA rules intersect with SEC climate disclosure mandates, offering unified compliance architectures through SaaS-delivered permissioned ledgers.
For Investors and Strategic Acquirers: Consolidation pressure builds where distributed systems engineering scarcity constrains manufacturer ability to build captive ledger infrastructure. Long-term viability favors asset-light platform providers connecting multi-tier supplier networks over capital-heavy foundry operators facing integration cost inflation. Acquisition target archetype: specialized blockchain consultancies with cryptographic protocol design expertise and existing OEM audit system relationships. Watch for EU Green Deal enforcement threshold acceleration as the inflection signal triggering rapid tier-three supplier onboarding.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Knowledge Proof Implementation | Enables component origin verification without exposing proprietary supplier yield data to competitors. |
| Cloud-Native Ledger Platform Launch | Reduces capital deployment barriers for mid-tier suppliers entering blockchain verification markets. |
| Multi-Enterprise Platform Partnership | Connects tier-three semiconductor suppliers directly to Northrop Grumman and Raytheon audit systems. |
| Smart Contract Automation Deployment | Compresses supplier onboarding cycles through automated REACH compliance rule enforcement. |
| Hybrid Cloud Infrastructure Buildout | Isolates sensitive cryptographic operations on-premises while leveraging AWS scalability for non-critical processing. |
Study Parameters
Multiple input streams — primary interviews with blockchain protocol engineers, semiconductor procurement executives, and medical device regulatory affairs leads; secondary validation through SEC climate disclosure filings, EU ECHA REACH substance databases, and FDA device traceability guidance documents; plus customs records for semiconductor trade flows — were reconciled through bottom-up and top-down triangulation across the analysis window.
Historical shipment data for permissioned ledger deployments cross-references against expert panel inputs from GPU architecture specialists and enterprise software platform architects. Segmentation dimensions modeled include technology configuration, application functional area, end-user organizational role, and deployment hosting architecture, with CAGRs derived from install-base growth rates and average revenue per node economics. Industry-specific forecast inputs incorporate EU Green Deal digital product passport enforcement timelines and aerospace prime contractor procurement specification evolution.
The model assumes a particular technology adoption path; alternative pathways for zero-knowledge proof standardization would alter the outlook for premium-tier verification service margins. Forecasts reflect assumptions about multi-enterprise platform interoperability resolution and cloud provider node-hosting cost trajectories. A small set of triggers — EU enforcement threshold acceleration, Taiwan supply disruption, or FDA traceability rule expansion — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Electromechanical Timers Market
Electronic Components
Display Port Adapters Market
Electronic Components
Global Capacitive Stylus Market
Electronic Components
Lowpass Filters Market
Electronic Components
Capacitor Kits Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Electromechanical Relay Market
Electronic Components
Gas Discharge Tube Market
Electronic Components
Europe PCB Market
Electronic Components
Global Microfluidic Components Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
USB Retimer Market
Electronic Components
Distribution Components Market
Electronic Components
Touch Screen Controllers Market
Electronic Components
North America MLCC Market