
 Resonators Market | 2026-2036
Resonators Market Size, Share, and Industry Trends Forecast 2026-2036
Resonators Market Analytics
Software-defined frequency tuning is restructuring how resonator vendors monetize hardware. Murata Manufacturing Co., Ltd. leverages its ceramic material science dominance to anchor premium positioning in surface-mount devices. Kyocera Corporation sustains vertical integration from raw crystal growth to packaged modules, controlling cost structures that competitors struggle to match. SiTime Corporation specializes in MEMS-based silicon resonators, differentiating through programmable architectures that reduce customer inventory complexity.
A resonator is a passive component that stores energy in oscillating mechanical, electrical, or acoustic modes to generate stable reference frequencies, typically specified by parameters including quality factor, frequency tolerance, and temperature coefficient. Electronic resonators employ piezoelectric crystals or MEMS structures to deliver clock signals with parts-per-million stability for synchronized digital systems. The mechanical type retains mature demand in legacy telecommunications infrastructure where quartz crystals occupy established socket positions with minimal substitution risk. MEMS silicon variants represent the fastest-expanding segment, capturing margin pools in automotive ADAS and 5G small-cell deployments where programmability and shock resistance outweigh legacy quartz performance advantages. Surface-mount form factors lead volume shipments, though integrated modules that combine resonators with oscillators or buffers are capturing higher value per socket in space-constrained consumer electronics.
The Federal Communications Commission shapes demand through spectrum allocation rules that mandate tighter frequency stability in millimeter-wave 5G equipment, while the EPA oversees hazardous substance restrictions affecting quartz mining and ceramic processing supply chains. Japan's Ministry of Economy, Trade and Industry enforces JIS standards on component reliability that constrain market access for non-compliant suppliers. Stakeholders must monitor how automotive functional-safety certifications and telecommunications infrastructure subsidy programs redirect procurement specifications before committing capacity expansion decisions.
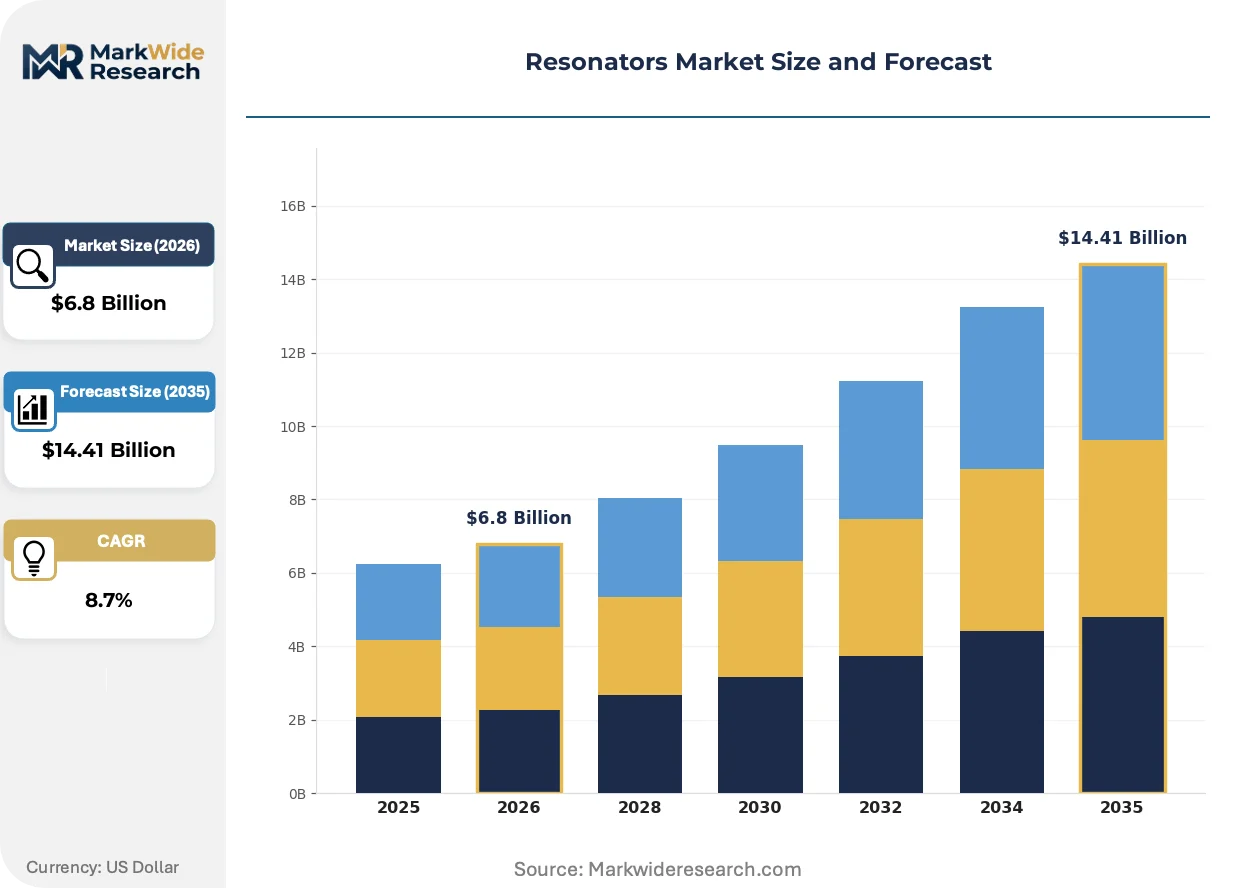
Market Dynamics
MEMS silicon resonators are compressing design cycles across telecommunications and automotive verticals, forcing legacy quartz suppliers to accelerate programmable architecture roadmaps or surrender socket positions in 5G infrastructure and ADAS modules.
Growth Catalysts
- Telecommunications spectrum mandates:FCC millimeter-wave stability requirements for 5G base stations are tightening frequency tolerance specifications, expanding addressable demand for precision timing components.
- Automotive radar proliferation:ADAS module deployments in electric vehicles require shock-resistant resonators that withstand thermal cycling and mechanical vibration without performance degradation.
- East Asian foundry clustering:Manufacturing concentration across Japan, South Korea, and Taiwan creates captive supply ecosystems that reduce procurement risk for Tier 1 OEMs.
Market Restraints
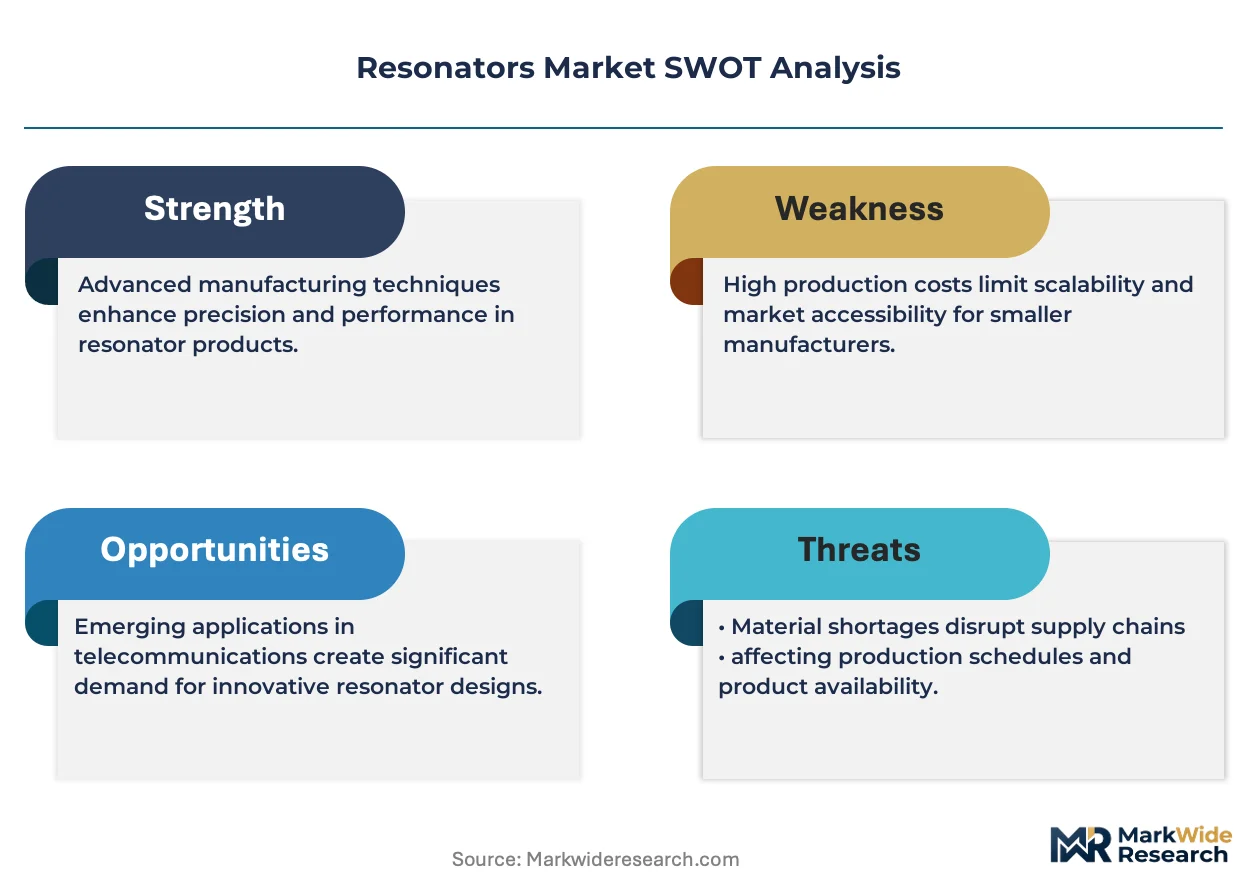
- Raw crystal supply concentration:High-purity quartz mining operations cluster in limited geographic corridors, exposing resonator manufacturers to input cost volatility and geopolitical disruption.
- Ceramic material processing constraints:Advanced ceramic substrate production requires specialized kiln infrastructure that constrains capacity expansion timelines for surface-mount device suppliers.
- Legacy socket entrenchment:Established quartz crystal positions in mature telecommunications infrastructure resist displacement due to minimal substitution incentives and recertification costs.
Strategic Opportunities
- Software-defined frequency architectures:Programmable MEMS resonators enable inventory consolidation for customers managing multiple frequency variants, reducing working capital requirements.
- Integrated module convergence:Combining resonators with oscillators and buffers into single-package solutions captures premium positioning in space-constrained consumer electronics.
- Automotive functional-safety certification:ISO 26262 compliance creates qualification barriers that favor incumbent suppliers with established automotive track records.
Industry Challenges
- MEMS process engineering scarcity:Specialized expertise in silicon resonator fabrication and wafer-level packaging commands premium compensation, constraining workforce scaling.
- Multi-standard certification complexity:Simultaneous compliance with FCC telecommunications rules, EPA hazardous substance restrictions, and JIS reliability standards extends product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resonators Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Mechanical, Electronic, Acoustic, Optical End User: Consumer Electronics, Automotive, Aerospace, Telecommunications Material: Ceramics, Metals, Polymers, Composites Form Factor: Surface Mount, Through Hole, Integrated, Discrete |
| Companies Covered | Murata Manufacturing Co., Ltd., Kyocera Corporation, Abracon LLC, SiTime Corporation, TXC Corporation, Qorvo, Inc., CTS Corporation, Renesas Electronics Corporation, Nihon Dempa Kogyo Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resonators Market Evolving Landscape
Frequency generation architectures are fragmenting across programmable silicon and precision quartz camps, with each trajectory attracting distinct buyer segments based on stability requirements, volume scale, and supply chain risk tolerance.
MEMS-based silicon resonators is electrifying timing component procurement by enabling single-SKU inventory strategies that cover multiple frequency points through software configuration. Automotive electronics buyers are adopting these architectures fastest, prioritizing supply chain simplification over absolute phase noise performance. This shift is electrifying competitive pressure on quartz specialists to demonstrate measurable stability advantages or surrender margin in programmable-capable segments.
Japan's METI JIS reliability standards are constraining market access for non-compliant suppliers while reinforcing domestic incumbent positions in high-reliability verticals. The industrial consequence is a bifurcated procurement landscape where certified suppliers command premium positioning in automotive and aerospace sockets. European telecommunications OEMs are responding by demanding equivalent reliability documentation from Asian suppliers, elevating compliance costs across the vendor base.
Consolidated procurement contracts are displacing spot-market purchasing for resonator components as OEMs seek volume commitments that secure allocation priority during supply constraints. Tier 1 automotive and telecommunications buyers are consolidating supplier relationships to three to five qualified vendors per socket category. This concentration is most visible in South Korean electronics manufacturing clusters, where chaebol-affiliated procurement teams are negotiating multi-year supply agreements with MEMS resonator specialists.
Resonators Market Segmentation
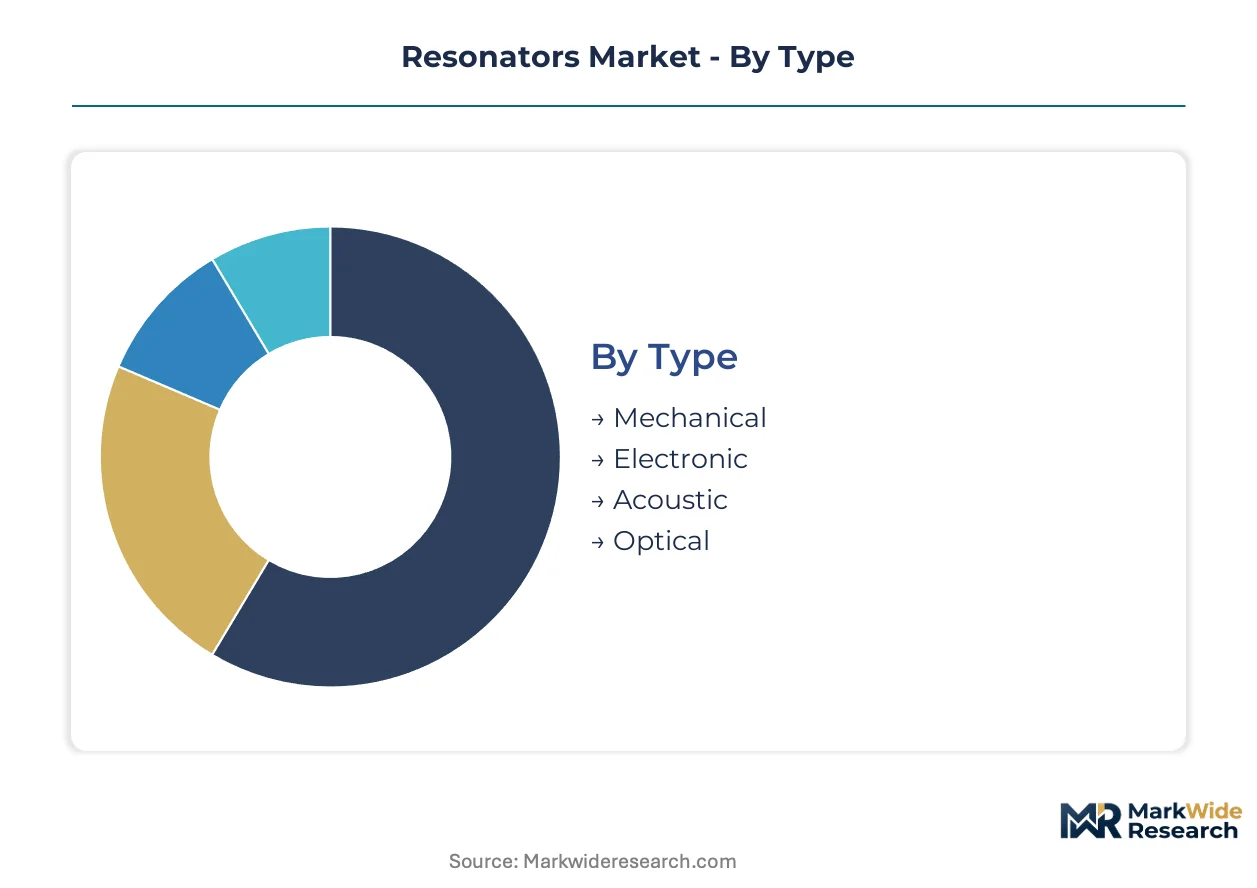
Resonator procurement patterns diverge sharply across application environments, with automotive buyers prioritizing shock tolerance while telecommunications OEMs demand phase noise stability. Material selection and form factor geometry directly determine socket eligibility in space-constrained versus high-reliability verticals.
Type:
Buyers segment by energy storage mechanism, with each architecture commanding distinct specification thresholds and qualification protocols.
- Mechanical:Quartz crystal structures oscillate at precise frequencies through piezoelectric mechanical deformation. Demand concentrates in legacy telecommunications infrastructure across Japan and South Korea, where established socket positions resist displacement due to minimal substitution incentives and recertification cost barriers.
- Electronic:MEMS silicon resonators employ micromachined structures for frequency generation with programmable tuning capabilities. Automotive radar module deployments in electric vehicles drive fastest expansion, with Tier 1 OEMs prioritizing supply chain simplification through single-SKU inventory strategies over absolute phase noise performance.
- Acoustic:Surface acoustic wave devices utilize piezoelectric substrate propagation for filtering and timing functions in RF front-end modules.
- Optical:Whispering-gallery-mode resonators exploit light confinement in microspheres or toroids for ultra-stable optical frequency references in metrology equipment.
Volume sits with Mechanical resonators; growth tilts toward Electronic architectures.
End User:
Application verticals impose divergent reliability certification requirements that filter supplier eligibility and margin capture potential.
- Consumer Electronics:Wearables and smartphones demand minimal footprint resonators with standard temperature coefficients. Procurement concentrates in East Asian manufacturing clusters spanning Taiwan and South Korea, where space constraints favor integrated module solutions combining resonators with oscillators.
- Automotive:ADAS modules and electric vehicle powertrains require ISO 26262-certified components withstand thermal cycling and mechanical vibration. Japanese and German OEMs drive specification tightening, with functional-safety documentation creating qualification barriers favoring incumbent suppliers.
- Aerospace:Satellite and avionics systems specify radiation-hardened resonators with hermetic sealing against extreme environmental exposure.
- Telecommunications:5G base stations and small-cell deployments mandate FCC millimeter-wave stability compliance with tightened frequency tolerance specifications.
Telecommunications commands current procurement volume; Automotive exhibits the steepest expansion trajectory.
Material:
Substrate composition determines thermal stability boundaries and manufacturing cost structures across resonator architectures.
- Ceramics:Aluminum oxide and zirconia substrates provide dimensional stability for surface-mount device packages. Japanese suppliers anchor premium positioning through specialized kiln infrastructure that constrains competitor capacity expansion timelines.
- Metals:Titanium and stainless steel housings deliver hermetic sealing for aerospace and automotive applications requiring environmental protection.
- Polymers:Liquid crystal polymer substrates enable thin-film resonator integration in cost-sensitive consumer electronics with moderate stability requirements.
- Composites:Ceramic-polymer hybrid materials balance thermal performance with processing economics in mid-tier telecommunications equipment.
Ceramics dominate high-reliability sockets; Polymers capture volume in cost-optimized segments.
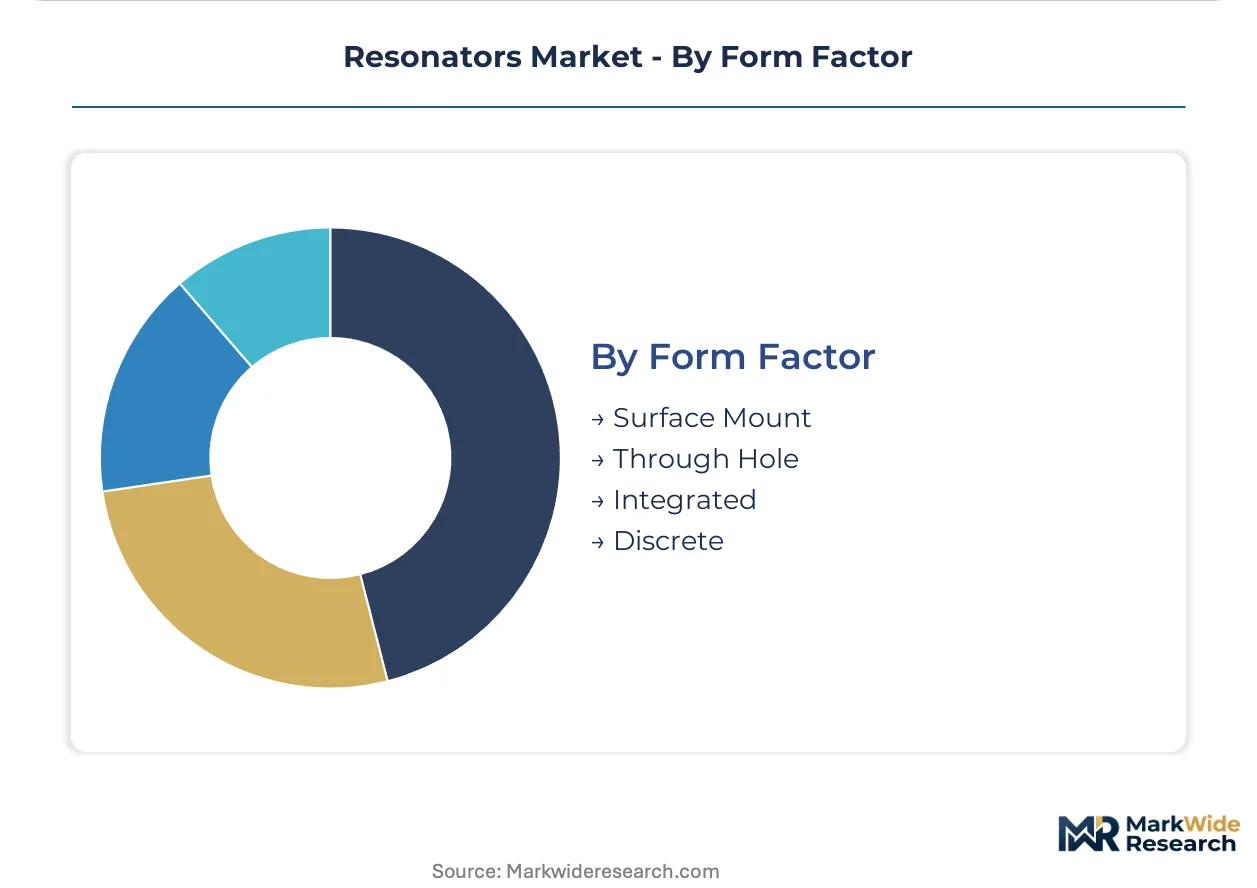
Form Factor:
Package geometry dictates board-level integration density and assembly process compatibility across manufacturing environments.
- Surface Mount:Compact rectangular packages enable high-density PCB assembly through automated pick-and-place operations. Volume concentrates in Taiwanese and South Korean contract manufacturing facilities serving smartphone and wearable OEMs.
- Through Hole:Radial and axial leaded packages persist in industrial equipment and legacy telecommunications infrastructure where manual repair accessibility outweighs density requirements.
- Integrated:Multi-chip modules combining resonators with oscillators and buffers capture premium positioning in space-constrained consumer electronics.
- Discrete:Unpackaged resonator elements serve custom oscillator designs in specialized test and measurement equipment.
Surface Mount leads shipment volume; Integrated form factors gain share fastest in premium consumer electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian fabrication clusters generate the majority of resonator output, while North American and European OEMs absorb premium-grade components for telecommunications and automotive end-uses. This geographic split concentrates upstream supply risk in Japan, South Korea, and Taiwan, even as specification-setting power resides with German automotive buyers and US regulatory bodies.
Japan
Domestic OEMs source precision quartz crystals for legacy telecommunications infrastructure and automotive radar modules. METI enforces JIS reliability standards that constrain market access for non-compliant foreign suppliers. Tokyo-Osaka industrial corridors host vertically integrated resonator manufacturers controlling raw crystal growth through packaged module assembly.
South Korea
Chaebol-affiliated electronics groups drive procurement consolidation through multi-year supply agreements with MEMS resonator specialists. The country's national telecommunications regulator mandates tightened frequency stability specifications for 5G millimeter-wave deployments. Seoul-Incheon manufacturing clusters anchor surface-mount device assembly for smartphone and wearable OEMs.
Taiwan
Contract manufacturing ecosystems consume high volumes of compact resonators for consumer electronics assembly. The island's industrial standards bureau aligns component certification with international automotive functional-safety frameworks. Hsinchu Science Park hosts foundry partnerships linking MEMS resonator design houses to wafer fabrication capacity.
United States
Telecommunications infrastructure OEMs specify FCC-compliant precision timing components for 5G base station deployments. The Federal Communications Commission shapes demand through spectrum allocation rules mandating tighter frequency stability in millimeter-wave equipment. Silicon Valley and Boston-area design centers drive architectural specifications for programmable MEMS resonator adoption.
Germany
Automotive Tier 1 suppliers demand ISO 26262-certified resonators for ADAS module integration in electric vehicle platforms. KBA vehicle type-approval processes incorporate component-level reliability documentation requirements. Stuttgart and Munich industrial corridors concentrate procurement decision-making for precision timing components across European automotive manufacturing.
Resonators Market Competitive Landscape
Top-tier vendors anchor premium positioning through material science dominance and captive supply chains, while mid-tier specialists compete on programmable architectures and inventory simplification value propositions. The vendor base stratifies across three archetypes: vertically integrated ceramic material leaders, MEMS silicon programmable specialists, and frequency control component aggregators. Capacity expansion partnerships with East Asian foundries and strategic technology licensing agreements represent the dominant competitive moves reshaping procurement relationships.
Among Japan-based fabricators, Murata Manufacturing Co., Ltd. and Kyocera Corporation exemplify vertically integrated archetypes controlling substrate processing through module assembly. SiTime Corporation occupies a position representing the programmable MEMS specialization vector, while Abracon LLC and CTS Corporation sit within the North American component aggregation tier serving diversified frequency control demand.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| Kyocera Corporation |
| Abracon LLC |
| SiTime Corporation |
| TXC Corporation |
| Qorvo, Inc. |
| CTS Corporation |
| Renesas Electronics Corporation |
| Nihon Dempa Kogyo Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap ceramic processors in Japan anchor supply discipline through multi-generational capital allocation patience, translating into sticky pricing power that resists spot-market volatility even when raw quartz costs fluctuate. Their captive kiln infrastructure and refusal to pursue leveraged expansion insulates contract pricing from the margin compression visible among private-equity-rolled competitors.
Pricing Analysis
Cost-down pressure on standard-grade surface-mount devices accelerates because Taiwanese contract manufacturers consolidate procurement volumes across smartphone OEMs. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-economy levels separates Murata's premium ceramic resonators from mid-tier MEMS offerings and commodity quartz imports. ISO 26262 certification commands 15-25% price premiums in automotive sockets, while consumer electronics buyers exhibit highest price sensitivity, treating resonators as interchangeable passives.
Supply Chain Analysis
High-purity quartz feedstock draws from limited Brazilian and Madagascan mining corridors, exposing resonator fabricators to concentrated geopolitical disruption risk. MEMS silicon wafers hinge on foundry partnerships in Taiwan and South Korea, while advanced ceramic substrates rest on proprietary Japanese kiln networks. Tariff exposure on Chinese-packaged components intensifies as OEMs dual-source to Vietnam and Mexico. Distribution runs through chaebol-affiliated procurement teams negotiating multi-year allocation agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resonator procurement is consolidating around vertically integrated suppliers controlling raw material through module assembly, with foundry partnerships and certification investments emerging as the decisive levers separating winners from margin-squeezed assemblers.
For Market Incumbents: Extend ceramic material science dominance into integrated module solutions combining resonators with oscillators, capturing premium sockets in space-constrained automotive radar. Accelerate MEMS programmable roadmaps to defend against SiTime's single-SKU inventory value proposition in 5G small-cell deployments. Lock in multi-year supply agreements with South Korean chaebols before foundry capacity tightens. For New Entrants and Emerging Players: The gap between automotive-certified premium pricing and consumer-economy spot pricing creates entry space for mid-tier MEMS specialists targeting industrial automation with functional-safety documentation. Target Taiwanese contract manufacturing ecosystems where procurement teams seek second-source alternatives to Japanese ceramic incumbents. Lead with software-defined frequency configurability to reduce customer inventory complexity. For Investors and Strategic Acquirers: Distressed-cycle entries favor MEMS design houses with taped-out automotive programs but constrained foundry access in Taiwan and South Korea. Five-to-ten-year viability hinges on securing wafer-level packaging partnerships before capacity allocation hardens. Watch for FCC spectrum rule tightening as the inflection signal accelerating programmable architecture adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Expansion | Secures wafer capacity for MEMS resonator scaling amid Taiwanese fab allocation constraints. |
| Automotive Functional-Safety Certification | ISO 26262 compliance creates qualification barriers favoring incumbents in German OEM supply chains. |
| Software-Defined Frequency Architecture | Programmable MEMS enables inventory consolidation for 5G base station and ADAS module buyers. |
| Raw Crystal Supply Integration | Backward control over Brazilian and Madagascan quartz mining insulates against input cost volatility. |
| Integrated Module Convergence | Combining resonators with oscillators captures premium positioning in South Korean smartphone manufacturing. |
Research Methodology
Document review covered SEC filings from frequency control component suppliers, METI JIS standard documentation, and FCC spectrum allocation rulings, complemented by interviews with procurement directors at Tier 1 automotive suppliers, telecommunications infrastructure OEMs, and Taiwanese contract manufacturing executives. Secondary validation drew from customs trade data, foundry capacity announcements, and automotive production databases. Bottom-up resonator shipment estimates triangulated against top-down telecommunications capital expenditure and electric vehicle production forecasts.
Segment-level projections across mechanical, electronic, acoustic, and optical resonator types were generated through the analysis window, with automotive radar and 5G infrastructure adoption curves as primary demand drivers. Modeled dimensions included end-use vertical certification requirements, material substrate composition, and form factor integration density. CAGRs were derived from elasticity-weighted substitution rates between quartz and MEMS architectures, with foundry capacity constraints and raw material supply concentration as bounding assumptions.
Inputs from Japanese resonator manufacturers and South Korean electronics groups were available through the study window; gaps in private foundry utilization rates and chaebol procurement contract terms introduce uncertainty bands around MEMS penetration forecasts. Automotive functional-safety certification timelines and FCC millimeter-wave stability rulemakings represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
North America Safety Relay and Timers Market
Electronic Components
Operational Amplifier Market
Electronic Components
GPIO Expanders Market
Electronic Components
Global Capacitor Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
Timing Relay Market
Electronic Components
Global Circuit Protection Market
Electronic Components
RAID Controller Card Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
High-Voltage Capacitor Market
Electronic Components
Silicon Capacitors Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
SAW Filters Market