
 Passive Attenuator Market | 2026-2036
Passive Attenuator Market Size, Share, and Industry Trends Forecast 2026-2036
Passive Attenuator Market Insights
Passive attenuator pricing is decoupling between precision RF grades and commodity resistor pads. Skyworks Solutions anchors the premium tier through captive GaAs foundry output and die-level integration. Mini-Circuits competes on catalog breadth and same-day fulfillment for standard fixed attenuators. Analog Devices differentiates by embedding attenuation functions within wider signal chain portfolios.
A passive attenuator is a two-port resistive network that reduces signal amplitude by a specified decibel value across a defined frequency band, typically constructed from thin-film or thick-film resistor networks on ceramic or alumina substrates. Fixed attenuators dominate volume shipments in telecommunications infrastructure, while variable attenuators capture disproportionate margin in aerospace test benches where calibration traceability commands premium pricing. Optical attenuator demand is accelerating alongside fiber-to-the-home deployments, though RF technology still occupies the largest application footprint across defense and broadcasting end users.
FCC equipment authorization rules shape product certification timelines for US-bound RF attenuators, while REACH substance restrictions in Europe constrain plating chemistry and solder formulations. The EU AI Act and emerging spectrum allocation frameworks in Asia-Pacific will pressure manufacturers to document environmental compliance across extended supply chains. Stakeholders must decide whether to absorb certification costs directly or push responsibility downstream to module integrators.
Market Dynamics
Defense procurement programs across NATO member states are expanding absorption of precision RF components, while REACH and RoHS compliance in Europe redirects material sourcing toward lead-free ceramic substrates. This dual pressure from military demand and environmental regulation is restructuring supplier qualification requirements.
Growth Catalysts
- Fiber-to-the-home deployments:Optical attenuator demand is accelerating alongside residential fiber infrastructure buildouts, particularly in markets prioritizing gigabit connectivity.
- REACH substance restrictions:European plating chemistry and solder formulation mandates are forcing substrate material upgrades that improve thermal performance in high-frequency applications.
- Munich-Nuremberg industrial corridor:Germany's concentration of test equipment OEMs creates localized demand clusters for calibration-traceable variable attenuators.
Market Restraints
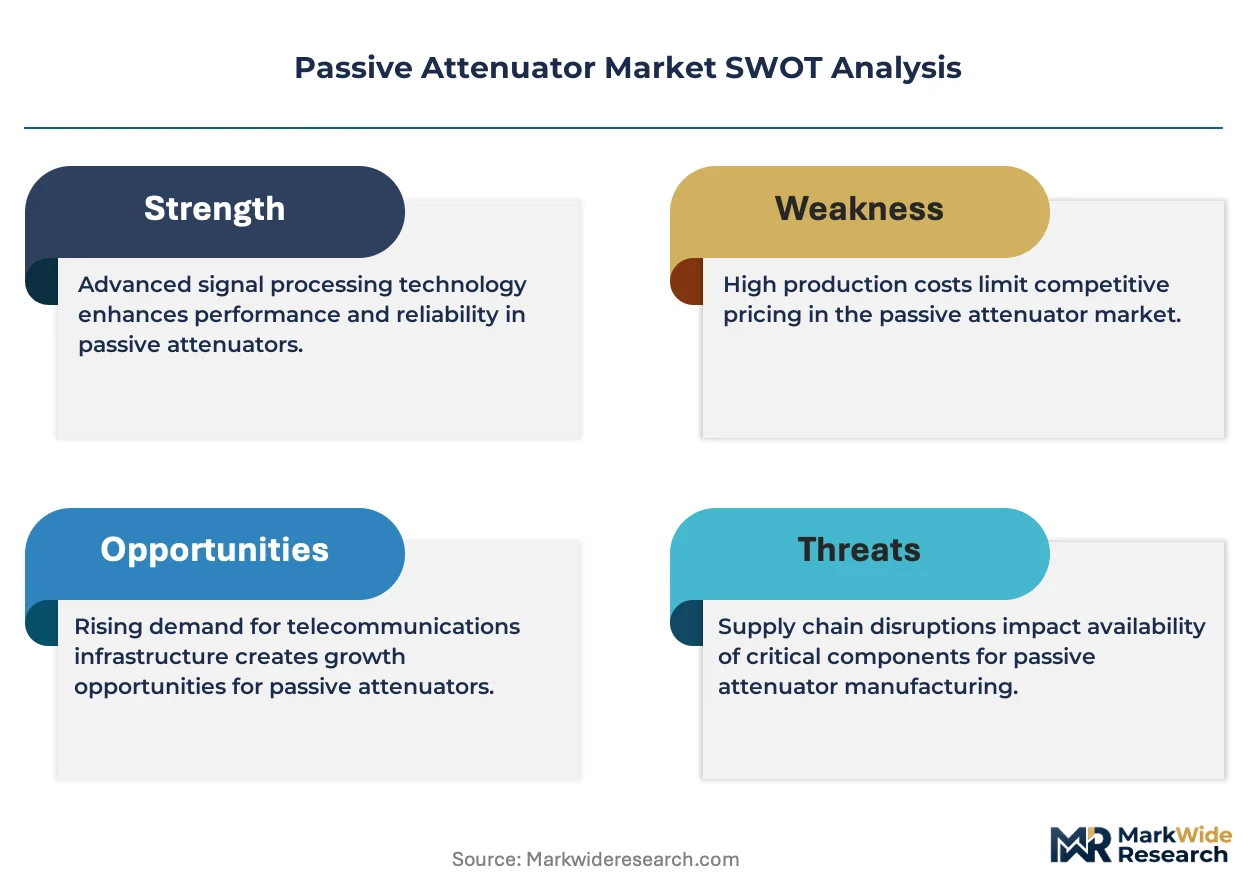
- Palladium and ruthenium price volatility:Thin-film resistor networks depend on precious metal inks whose cost swings compress margin on standard fixed attenuators.
- GaAs foundry concentration:Premium die-level integration relies on captive semiconductor fabrication capacity concentrated among a handful of suppliers.
- Substitution by active gain control:Silicon-based variable gain amplifiers threaten fixed attenuator sockets in cost-sensitive consumer electronics.
Strategic Opportunities
- Aerospace test bench expansion:Calibration-traceable variable attenuators command premium pricing in defense and satellite ground station applications.
- EU AI Act documentation requirements:Environmental compliance mandates across extended supply chains create service revenue for certification-ready suppliers.
- 5G millimeter-wave infrastructure:Die-level integration of attenuation functions within wider signal chain portfolios addresses base station density requirements.
Industry Challenges
- Thin-film process engineering talent:Specialized deposition and laser trimming expertise remains scarce as veteran technicians retire from ceramic substrate manufacturing.
- FCC equipment authorization timelines:US-bound RF attenuators face extended certification cycles that delay revenue recognition for new product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passive Attenuator Market |
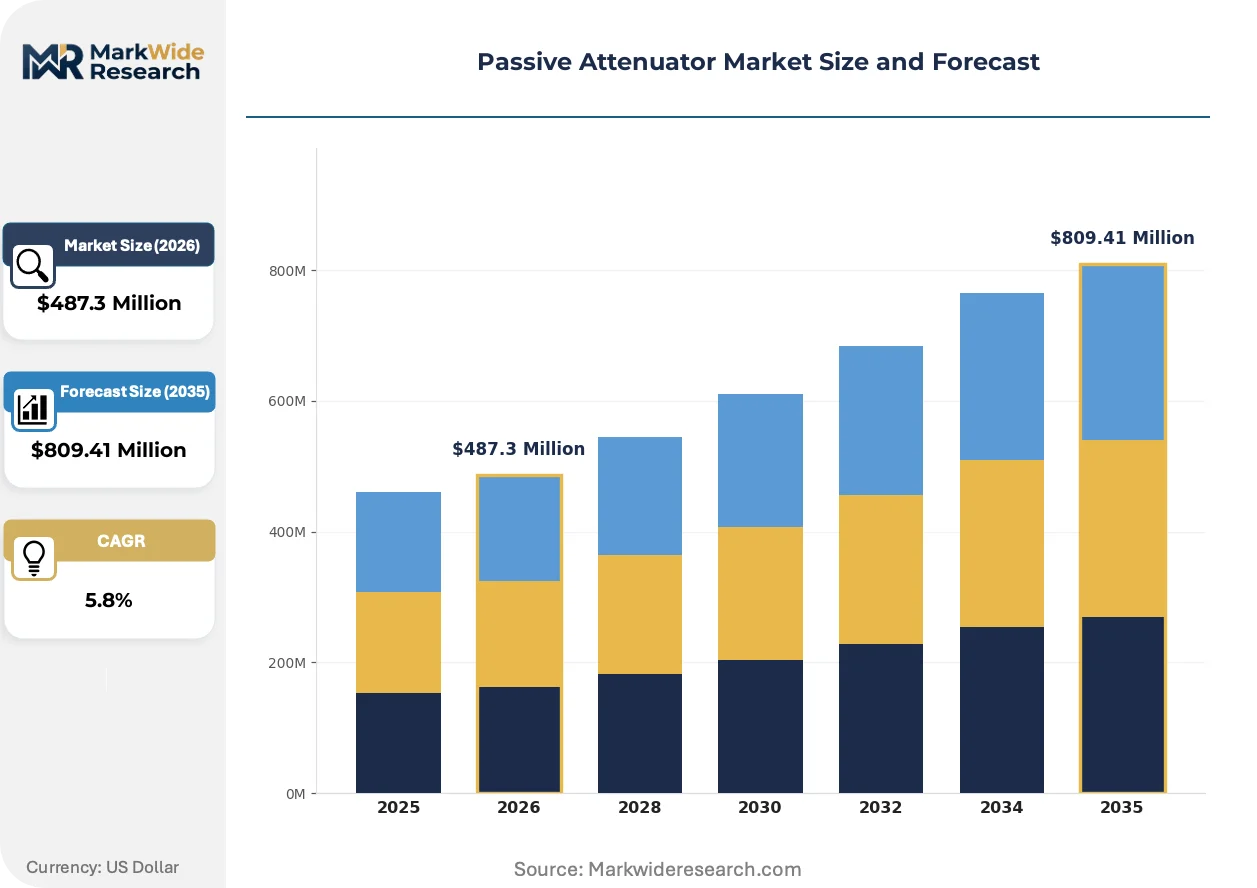
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Attenuators, Variable Attenuators, Step Attenuators, Resistor Pads Technology: Coaxial, Optical, RF, Fiber Optic End User: Telecommunications, Broadcasting, Defense, Aerospace Application: Signal Processing, Test Equipment, Circuit Design, Audio Systems |
| Companies Covered | Skyworks Solutions, Analog Devices, Keysight Technologies, Mini-Circuits, Amphenol Corp, HUBER+SUHNER, Anritsu Corporation, MACOM Technology Solutions, Bird, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passive Attenuator Market Trends and Innovations
Die-level integration and substrate material evolution are compressing form factors while expanding operating bandwidths. Regulatory documentation requirements are becoming competitive differentiators rather than mere compliance checkboxes.
Silicon-germanium BiCMOS processes are integrating attenuation, switching, and amplification functions onto single die for 5G base station front-ends. Infrastructure OEMs in South Korea and Japan are adopting these monolithic solutions at accelerating pace. This convergence is integrating previously discrete passive functions into active signal chain components, reducing bill-of-materials count.
REACH substance restrictions are constraining hexavalent chromium plating and lead-bearing solder formulations across European supply chains. Manufacturers must reformulate contact metallization and requalify thermal cycling performance. Germany's industrial test equipment sector is absorbing these compliance costs fastest due to automotive customer mandates.
Buyers are consolidating vendor lists around suppliers offering same-day fulfillment for catalog attenuators plus custom design services. Distributor inventories are shrinking as procurement teams favor direct manufacturer relationships with configurable online portals. This consolidation is most visible in North American telecommunications infrastructure, where tower companies now specify single-source attenuator strategies to simplify installation logistics.
Passive Attenuator Market Segmentation
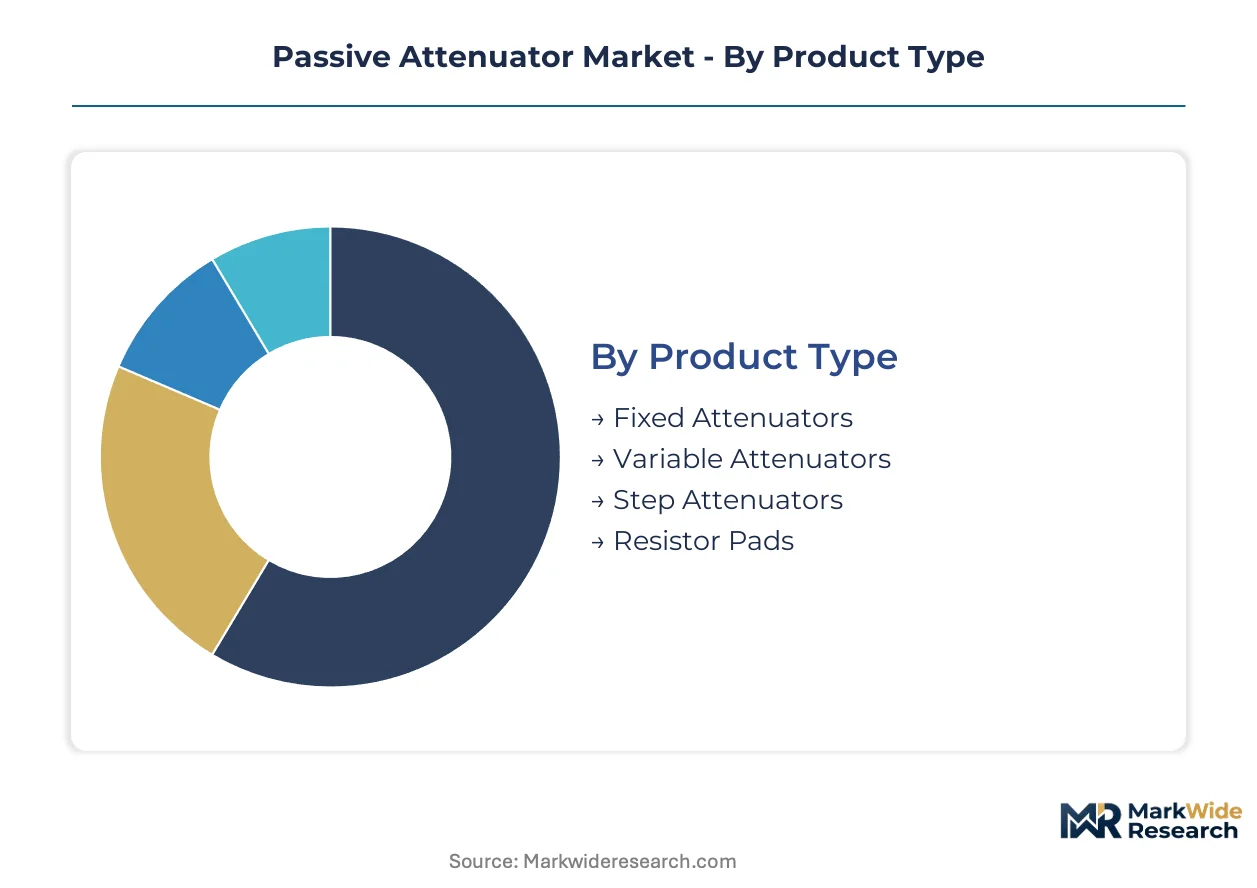
Passive attenuator segmentation reflects divergent integration paths. Standalone components serve discrete test benches and field installations, while embedded attenuation functions merge into monolithic signal chain silicon. Understanding this split clarifies where discrete suppliers defend position against semiconductor integration.
Product Type:
Fixed attenuators dominate standalone deployments in telecommunications infrastructure, while variable and step configurations embed into precision instrumentation requiring dynamic range adjustment.
- Fixed Attenuators:Thin-film resistor networks on alumina substrates provide stable attenuation values across defined frequency bands. Demand concentrates in South Korean 5G base station deployments where tower companies specify single-source procurement strategies to simplify installation logistics.
- Variable Attenuators:PIN diode or MEMS-based designs enable continuous attenuation adjustment under electronic control. Munich-Nuremberg test equipment OEMs absorb disproportionate volume for calibration-traceable aerospace applications where premium pricing reflects documentation rigor.
- Step Attenuators:Discrete switched resistor banks deliver quantized attenuation levels for laboratory environments.
- Resistor Pads:Surface-mount commodity components serve cost-sensitive consumer electronics sockets threatened by silicon-based variable gain amplifiers.
Volume placements concentrate in Fixed Attenuators; the faster expansion belongs to Variable Attenuators.
Technology:
Coaxial and RF technologies anchor established defense and broadcasting infrastructure, while optical variants capture fiber-to-the-home buildout momentum.
- Coaxial:Precision-machined connectorized assemblies handle high-power RF applications through 50-ohm and 75-ohm impedance standards. NATO defense procurement programs across Germany and Poland drive absorption of military-grade coaxial attenuators with extended temperature specifications.
- Optical:In-line fiber devices reduce optical power levels through doped fiber or micro-electromechanical shutters. Japanese residential fiber infrastructure investments accelerate demand for compact, low-insertion-loss optical attenuators in subscriber termination points.
- RF:Surface-mount and connectorized formats serve cellular infrastructure and radar systems.
- Fiber Optic:Specialized variants address submarine cable and data center interconnection requirements.
RF technology commands the largest installed base; optical formats are climbing the fastest alongside fiber access network densification.
End User:
Defense and aerospace procurement prioritizes traceability and environmental qualification, while telecommunications volume rewards fulfillment speed and catalog breadth.
- Telecommunications:Tower companies and mobile network operators consume standardized attenuator families in volume. North American infrastructure OEMs consolidate vendor lists around suppliers offering same-day fulfillment plus configurable online portals.
- Defense:Military specification attenuators require environmental stress screening and lot traceability. REACH and RoHS compliance redirects European defense contractors toward lead-free ceramic substrates from qualified German suppliers.
- Broadcasting:Terrestrial and satellite transmission facilities specify precision coaxial components.
- Aerospace:Satellite ground stations and avionics test benches demand calibration certificates and extended temperature operation.
Telecommunications generates the highest unit volumes; aerospace applications deliver the steepest margin expansion trajectory.
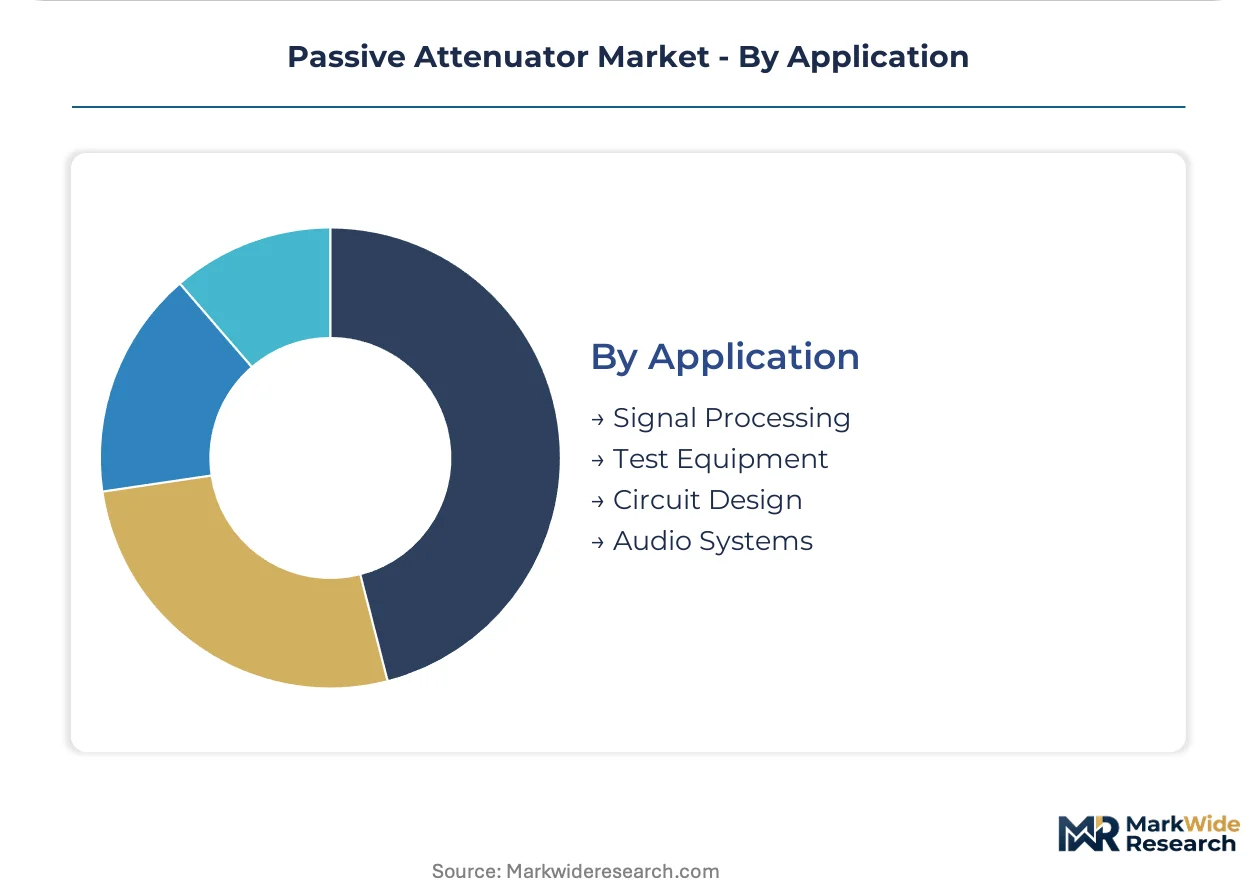
Application:
Test equipment applications command premium pricing for calibration documentation, while signal processing integration faces active silicon substitution pressure.
- Test Equipment:Vector network analyzers and spectrum analyzers require precision attenuators with verified flatness and return loss. Germany's automotive sector mandates drive fastest adoption of RoHS-compliant test bench components.
- Signal Processing:Receiver front-ends and transmitter chains embed attenuation for dynamic range management. Silicon-germanium BiCMOS integration threatens discrete passive sockets in cost-sensitive consumer equipment.
- Circuit Design:Prototyping and small-batch production absorb standard catalog attenuators.
- Audio Systems:Professional broadcast and studio equipment maintains demand for precision resistive networks.
Signal Processing captures the broadest addressable base; test equipment delivers the most durable pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Munich-Nuremberg industrial corridor anchors European precision RF component demand, with test equipment OEMs clustering around calibration-traceable variable attenuator suppliers. Defense procurement programs across NATO member states and fiber-to-the-home buildouts in Asia-Pacific are redistributing manufacturing footprints.
Germany
Bavaria's automotive and aerospace test equipment sectors absorb RoHS-compliant attenuators with verified calibration chains. REACH substance restrictions redirect plating chemistry toward hexavalent chromium alternatives. The Munich-Nuremberg corridor concentrates variable attenuator demand from Rohde & Schwarz and other precision instrumentation OEMs.
United States
FCC equipment authorization rules extend certification timelines for RF attenuators bound for defense and telecommunications infrastructure. Tower companies consolidate vendor lists around same-day fulfillment capabilities. The Boston-Washington corridor hosts precision component distributors serving 5G base station deployments.
Japan
METI-backed fiber infrastructure investments accelerate optical attenuator demand in residential subscriber termination points. NTT's gigabit connectivity mandates drive compact, low-insertion-loss component specifications. The Kanto region around Tokyo concentrates optical component manufacturing for export markets.
South Korea
5G millimeter-wave base station deployments consume surface-mount fixed attenuators in volume. Samsung and LG Uplus procurement specifications favor single-source strategies to simplify tower installation logistics. The Seoul Capital Area hosts RF component clusters serving domestic infrastructure OEMs.
Poland
NATO defense procurement programs expand absorption of military-grade coaxial attenuators with extended temperature specifications. EU structural funds support precision manufacturing upgrades in the Silesian industrial region. Wrocław and Poznań emerging as secondary sourcing locations for German defense contractors.
Passive Attenuator Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and fulfillment-speed dimensions. Skyworks Solutions anchors the premium tier through captive GaAs foundry output, while Mini-Circuits competes on catalog breadth and same-day fulfillment. Analog Devices and Keysight Technologies represent integrated signal chain and test equipment archetypes respectively. Competitive moves concentrate on die-level integration partnerships and direct distributor relationship consolidation.
Within the premium-tier vector, Skyworks Solutions occupies a position exemplifying captive semiconductor fabrication advantages. Mini-Circuits and Analog Devices represent alternative competitive archetypes—catalog breadth specialization versus embedded function integration. These three anchors illustrate how pricing stratifies across precision RF grades, standard fixed configurations, and signal-chain-embedded alternatives.
| Leading Market Players |
|---|
| Skyworks Solutions |
| Analog Devices |
| Keysight Technologies |
| Mini-Circuits |
| Amphenol Corp |
| HUBER+SUHNER |
| Anritsu Corporation |
| MACOM Technology Solutions |
| Bird |
| Others |
Pricing and Supply Chain Analysis
Precision-commodity bifurcation between calibration-traceable variable attenuators and standard fixed resistor pads reshapes both margin structures and supplier qualification requirements across NATO defense procurement and European REACH compliance channels. This tier divergence concentrates pricing power with German substrate manufacturers serving Munich-Nuremberg test equipment OEMs while compressing returns on South Korean 5G base station commodity volumes.
Pricing Analysis
Calibration-certificate value anchors premium pricing for aerospace test bench applications, with documentation rigor commanding substantial markups over catalog-standard fixed attenuators. Price differentiation rests on certification grade and volume scale, with single-source procurement strategies from tower companies squeezing margins on high-volume telecommunications shipments. Cost compression in thick-film resistor pads intensifies due to palladium ink volatility. Consumer electronics buyers exhibit highest price sensitivity; defense contractors show lowest sensitivity given traceability mandates.
Supply Chain Analysis
Thin-film process engineering talent shortages in Germany, Japan, and the United States constrain ceramic substrate manufacturing expansion as veteran technicians retire. Raw material dependencies center on alumina substrates, precious metal resistor inks, and lead-free solder formulations. Single-source vulnerability runs through captive GaAs foundry capacity concentrated among premium-tier suppliers. Distribution runs through direct manufacturer portals with configurable online interfaces, bypassing traditional distributor inventories for North American telecommunications infrastructure procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH substance restrictions and RoHS mandates erect barrier-to-entry moats for European substrate suppliers with qualified lead-free formulations.
For Market Incumbents: To counter silicon-germanium BiCMOS integration threatening discrete passive sockets, deepen captive semiconductor fabrication partnerships and accelerate die-level attenuation function embedding within wider signal chain portfolios. Prioritize certification investment for EU AI Act documentation requirements across extended supply chains. For New Entrants and Emerging Players: Launch via direct-to-tower-company distribution models targeting South Korean 5G millimeter-wave infrastructure procurement specifications favoring same-day fulfillment capabilities. White-space opportunities concentrate in optical attenuator supply for Japanese fiber-to-the-home subscriber termination points and Polish NATO defense procurement channels seeking secondary sourcing from Silesian manufacturing upgrades. For Investors and Strategic Acquirers: Re-rating potential sits with calibration-traceable variable attenuator specialists given aerospace test bench expansion and documentation-service revenue from EU environmental compliance mandates. Long-term viability favors suppliers with backward integration into ceramic substrate manufacturing and qualified REACH-compliant plating chemistry. Watch palladium price stabilization as inflection indicator for thick-film resistor network margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Die-Level Integration Partnership | Skyworks Solutions anchors premium tier through captive GaAs foundry output for 5G base station signal chains. |
| REACH-Compliant Substrate Upgrade | German suppliers redirect plating chemistry toward hexavalent chromium alternatives for automotive test equipment mandates. |
| Direct Portal Distribution Launch | Mini-Circuits consolidates North American telecommunications procurement through same-day fulfillment capabilities. |
| Calibration Documentation Service | Munich-Nuremberg OEMs absorb premium pricing for aerospace traceability requirements from qualified variable attenuator suppliers. |
| Optical Attenuator Capacity Addition | Japanese manufacturers address METI-backed fiber infrastructure investments with compact low-insertion-loss subscriber termination designs. |
Research Methodology
Multi-period observation of defense procurement program absorption rates, fiber-to-the-home deployment trajectories, and REACH compliance transition timelines anchored the trend analysis, supplemented by interviews with RF component procurement managers at telecommunications tower companies, test equipment OEM sourcing directors, defense contractor qualification engineers, ceramic substrate manufacturing technicians, and distributor channel partners. Secondary validation drew from FCC equipment authorization databases, ECHA REACH substance restriction filings, METI infrastructure investment disclosures, NATO procurement transparency reports, and customs trade flow records. Bottom-up unit demand modeling triangulated against top-down market value reconstructions.
Segment-weighting across product type, technology format, end-user industry, and application use-case drove the analytical framework throughout the projection horizon. Fixed, variable, step, and resistor pad configurations were modeled alongside coaxial, optical, RF, and fiber optic technology variants. CAGRs derived from elasticity-adjusted demand curves incorporating precious metal ink price volatility, GaAs foundry utilization rates, and silicon substitution threat vectors in consumer electronics.
Palladium price spikes, GaAs fabrication capacity constraints, and accelerated silicon-germanium integration in 5G infrastructure are the dominant revision risks to forecast assumptions. A small set of regulatory enforcement intensity, defense budget allocation shifts, and fiber access network densification pace warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Battery Holders Market
Electronic Components
Global Active Electronic Components Market
Electronic Components
Docking Station Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Impulse Relays Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
Electric Vehicle (EV) Electronic Components Market
Electronic Components
RAID Controller Card Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
High-Voltage Capacitor Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
Americas MPU Market
Electronic Components
Flash Charger Adapter Market
Electronic Components
Efuse Market
Electronic Components
Serial Device Servers Market
Electronic Components
Global Industrial Media Converters Market