
 2D Electronics Market | 2026-2036
2D Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
2D Electronics Market Analysis
Atomic-scale thickness control in van der Waals heterostructures is reconfiguring how foundries stack functional layers without traditional lithography constraints. Graphenea leverages its CVD growth expertise to supply wafer-scale graphene to device makers across Europe. Nantero, Inc. anchors its competitive position through carbon nanotube memory architectures that bypass silicon scaling limits. GlobalFoundries competes by integrating 2D channel materials into its advanced node roadmap for specialty foundry customers.
2D electronics encompasses devices built from atomically thin materials—typically below five nanometers in thickness—where charge transport occurs in a single or few-layer lattice such as graphene, transition metal dichalcogenides, or hexagonal boron nitride, fabricated through mechanical exfoliation, chemical vapor deposition, or molecular beam epitaxy for applications requiring extreme flexibility, transparency, or electrostatic gate control. Graphene technology leads in transparent conductive film production for display backplanes, while semiconductor technology captures the fastest expansion as molybdenum disulfide transistors demonstrate on-off ratios exceeding conventional thin-film alternatives. Flexible technology occupies the premium margin tier due to roll-to-roll manufacturing complexity and yield optimization challenges.
EPA nanomaterial reporting requirements in the United States and REACH substance registration in Europe impose pre-market toxicity documentation that extends qualification timelines for graphene and related 2D materials. China's SAMR enforces GB standards for nanomaterial classification that shape import protocols and domestic production licensing. Japan's METI coordinates national R&D consortia for 2D material standardization through JIS frameworks. Stakeholders must monitor how divergent national registries for nanomaterial safety data influence cross-border supply chain qualification costs and foundry partnership decisions.
Market Dynamics
Atomic-scale thickness control in van der Waals heterostructures is reconfiguring how foundries stack functional layers without traditional lithography constraints. Graphene-based transistor adoption is accelerating among medical device manufacturers in Germany and South Korea.
Growth Catalysts
- REACH compliance in Europe:Tightening material purity requirements for graphene and nanomaterials are pushing manufacturers toward higher-grade production processes that command premium positioning.
- Medical device manufacturers:German and South Korean healthcare technology firms are integrating graphene-based transistors into diagnostic equipment for enhanced sensitivity.
- East Asian semiconductor fabrication clusters:Concentrated demand in Taiwan and South Korea is driving specialized foundry capacity expansion for 2D channel materials.
Market Restraints
- Material purity requirements:China's GB standards for nanomaterials impose pre-market toxicity documentation that extends qualification timelines for graphene suppliers.
- Supply concentration risk:Wafer-scale graphene production concentrates among European CVD growth specialists, creating single-source dependencies for device makers.
- Roll-to-roll manufacturing complexity:Flexible technology yield optimization challenges elevate production costs above rigid substrate alternatives.
Strategic Opportunities
- Japan's METI coordination:National R&D consortia for 2D material standardization through JIS frameworks create first-mover advantages for qualified suppliers.
- Transparent conductive film production:Display backplane applications for graphene technology remain underpenetrated in automotive infotainment systems.
- Carbon nanotube memory architectures:Convergence with 2D electronics bypasses silicon scaling limits in edge computing devices.
Industry Challenges
- Cross-border supply chain qualification costs:Divergent national registries for nanomaterial safety data in the United States, Europe, and China force redundant testing protocols.
- Legacy silicon integration:Molybdenum disulfide transistors require specialized gate stack engineering to interface with existing CMOS infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2D Electronics Market |
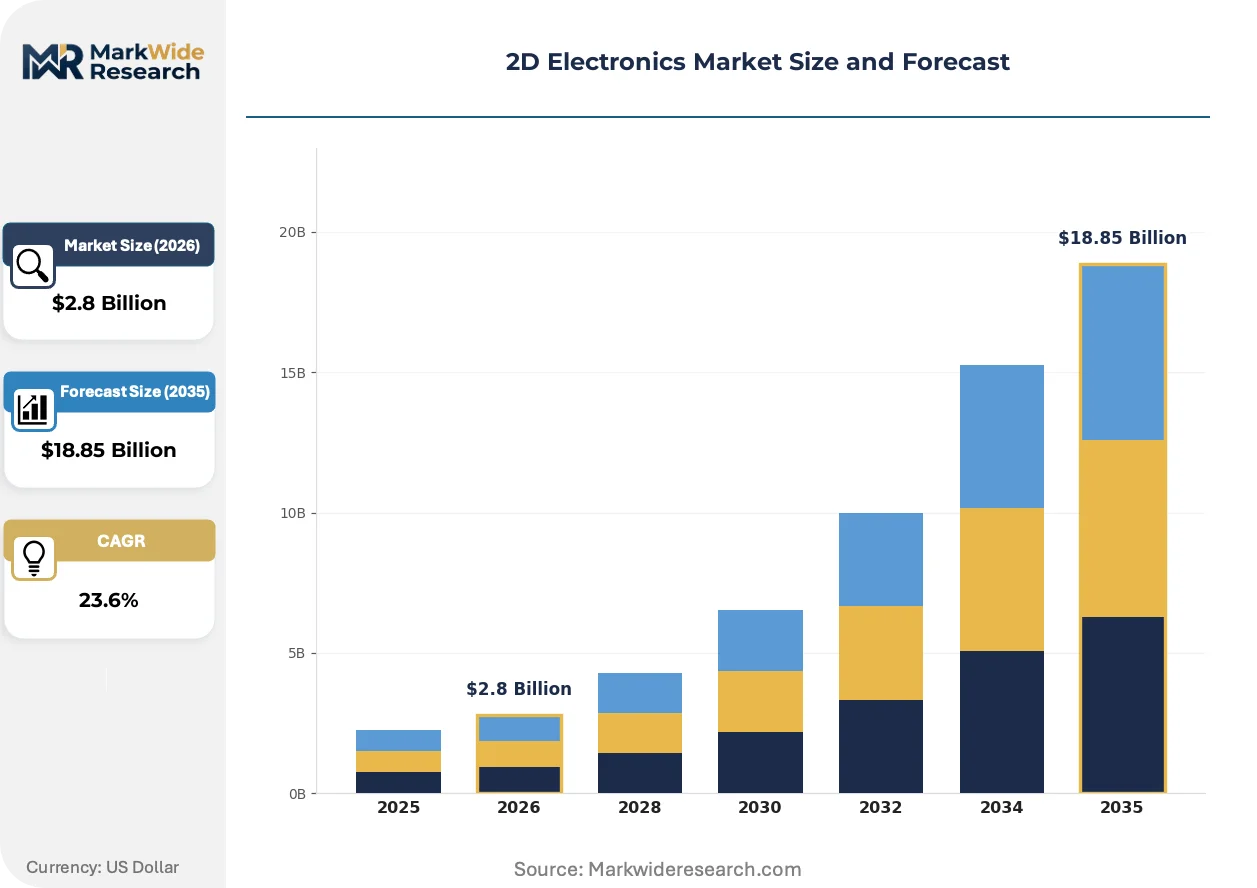
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $18.85 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Displays, Sensors, Transistors, Antennas Technology: Graphene, Semiconductor, Thin-Film, Flexible Application: Consumer Electronics, Automotive Components, Medical Devices, Wearable Technology End User: Manufacturers, Retailers, Research Institutions, Telecom Providers |
| Companies Covered | Skeleton Technologies, Aledia, 2D Semiconductors, 2D Electronic and Automation, Sanko Semiconductor Co., Ltd., Haydale Limited, Graphenea, GlobalFoundries, Nantero, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2D Electronics Market Emerging Trajectories
Device physics at the atomic limit is forcing simultaneous advances in synthesis methods, metrology protocols, and heterogeneous integration architectures. Foundries must now master precision transfer of exfoliated flakes alongside conventional thin-film deposition.
Van der Waals heterostructure engineering is hybridizing discrete material functions into unified device platforms. Samsung Advanced Institute of Technology and IMEC have demonstrated stacked graphene-hBN-TMD sandwiches that operate as tunnel transistors with sub-60 mV/decade switching. Medical imaging OEMs in South Korea are piloting these architectures for high-sensitivity biosensor arrays. The technology is hybridizing previously separate process modules for logic, memory, and sensing into monolithic 3D stacks.
EPA nanomaterial reporting requirements in the United States impose pre-market toxicity documentation that extends qualification timelines for graphene and related 2D materials. The Toxic Substances Control Act Section 8(a) rule mandates specific characterization data for materials below 100 nanometers in any dimension. Specialty chemical distributors serving the electronics sector are consolidating testing capabilities in-house to manage documentation burdens. Medical device manufacturers face the steepest compliance costs due to dual FDA and EPA jurisdiction.
Foundry service models are fragmenting as device makers seek captive 2D material synthesis rather than merchant supply. Taiwan-based semiconductor houses are negotiating long-term offtake agreements with European graphene producers to secure wafer-scale consistency. Japanese materials traders are repositioning as technical intermediaries, offering metrology and transfer services rather than commodity distribution. This restructuring concentrates procurement leverage among vertically integrated IDMs while merchant foundries absorb higher input costs.
2D Electronics Market Segmentation
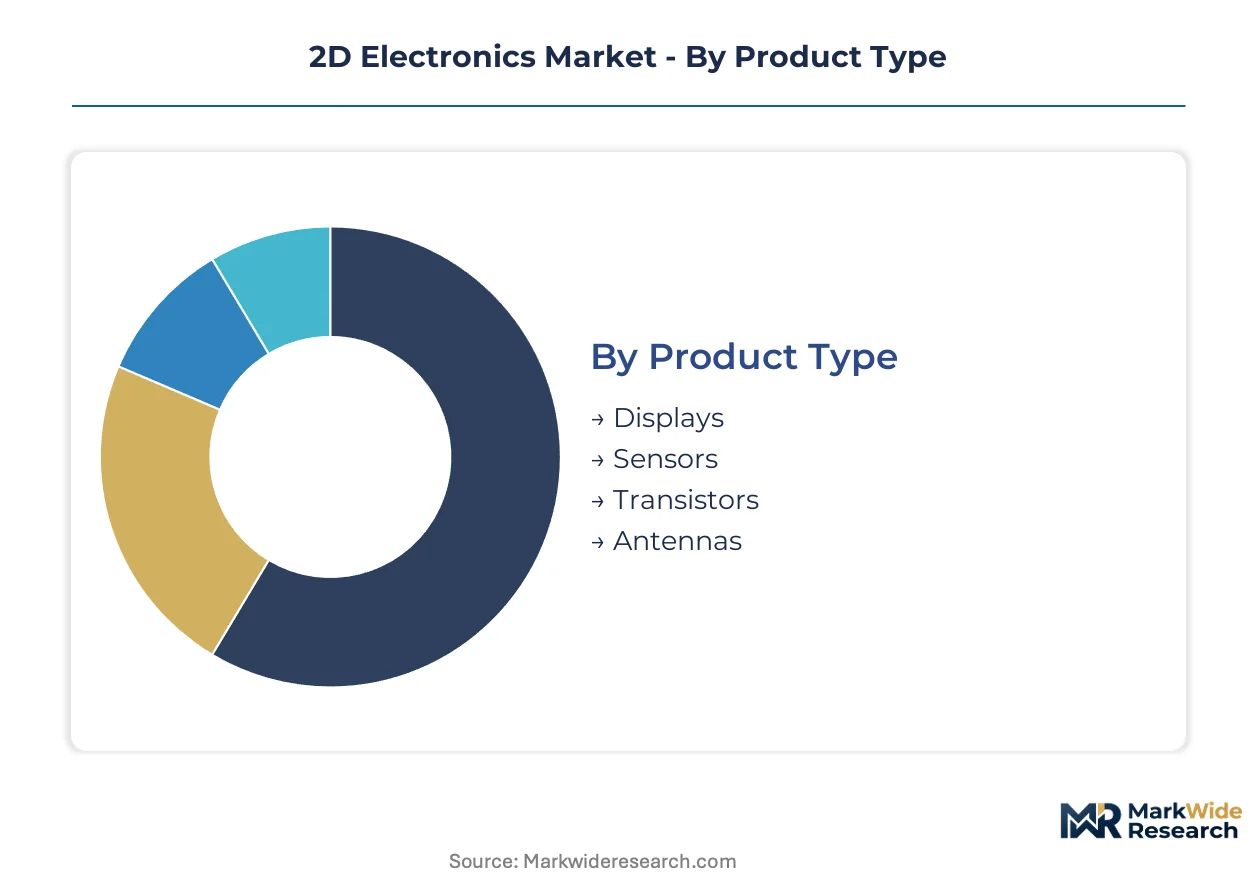
Segmentation in 2D electronics reveals how atomically thin materials traverse divergent commercialization paths. Each dimension—product architecture, synthesis method, use case, and buyer type—carries distinct qualification barriers and margin profiles that reshape supplier priorities.
Product Type:
Mature display applications coexist with emerging transistor architectures at varying yield maturities.
- Displays:Graphene-based transparent conductive films dominate backplane production for OLED and quantum-dot panels. South Korean display fabs in Gyeonggi Province consume the majority of wafer-scale CVD supply for foldable smartphone screens.
- Transistors:Molybdenum disulfide channel devices achieve on-off ratios exceeding conventional thin-film alternatives through van der Waals heterostructure engineering. Taiwan-based foundries are qualifying these for low-power logic nodes at specialty process facilities.
- Sensors:Biosensor arrays leverage graphene's surface-area-to-volume ratio for diagnostic sensitivity in German medical OEM pilot programs.
- Antennas:Flexible RF components target wearable form factors with mechanical resilience requirements that rigid substrates cannot satisfy.
Displays retains volume leadership; transistors holds the steepest expansion curve.
Technology:
Cost tiers separate laboratory-grade exfoliation from production-scale deposition methods.
- Graphene:CVD-grown monolayers on copper foils enable wafer-scale transfer to device substrates. European suppliers dominate merchant supply, though captive synthesis is rising among East Asian IDMs.
- Semiconductor:Transition metal dichalcogenide transistors—primarily MoS2 and WSe2—demonstrate sub-threshold swing below the Boltzmann limit in IMEC and Samsung Advanced Institute demonstrations. South Korean national consortia are accelerating foundry integration timelines.
- Thin-Film:Solution-processed variants serve cost-constrained applications where crystalline perfection is secondary to area coverage.
- Flexible:Roll-to-roll manufacturing of 2D heterostructures commands premium positioning due to yield optimization complexity and specialized transfer equipment requirements.
Graphene dominates current revenue; semiconductor technology is climbing the fastest as node scaling demands intensify.
Application:
Customer type fragmentation splits volume buyers from specification-driven niche adopters.
- Consumer Electronics:Foldable smartphones and tablets drive transparent conductive film consumption. Samsung Display and BOE Technology Group anchor procurement through multi-year offtake agreements with graphene producers.
- Medical Devices:Diagnostic equipment manufacturers in Germany and South Korea integrate graphene transistors for biosignal detection. Dual FDA and EPA jurisdiction in the United States elevates qualification costs for entrants.
- Automotive Components:Transparent heating elements and capacitive touch surfaces for infotainment systems remain underpenetrated relative to display sector adoption.
- Wearable Technology:Skin-conformable sensors and energy harvesters exploit mechanical flexibility that silicon cannot replicate.
Consumer electronics retains volume leadership; medical devices holds the steepest expansion curve given regulatory pathway investments.
End User:
Procurement authority concentrates among vertically integrated device makers rather than merchant distributors.
- Manufacturers:IDMs and display houses in Taiwan, South Korea, and China negotiate direct supply relationships with graphene foundries. Long-term contracts specify defect density thresholds and transfer yield guarantees.
- Research Institutions:National laboratories and university consortia in Japan, Germany, and the United States purchase small-batch exfoliated flakes for fundamental device physics studies. METI-coordinated programs in Japan standardize material characterization protocols through JIS frameworks.
- Retailers:Electronics distributors are repositioning as technical intermediaries, offering metrology and transfer services rather than commodity resale.
- Telecom Providers:Infrastructure operators are piloting graphene-based RF components for antenna miniaturization in dense urban deployments.
Manufacturers retain volume leadership; research institutions hold the steepest expansion curve as standardization investments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European graphene producers ship wafer-scale CVD supply to East Asian foundries in Taiwan and South Korea, establishing the dominant trade-flow corridor for 2D channel materials.
United States
Medical device OEMs in Massachusetts and Minnesota drive graphene transistor demand for diagnostic sensitivity. EPA Section 8(a) reporting under the Toxic Substances Control Act mandates nanomaterial characterization data that extends qualification timelines. Boston-area research consortia coordinate with the FDA on dual-jurisdiction pathways for biosensor commercialization.
Germany
Industrial automation and healthcare technology firms in Bavaria and Baden-Württemberg anchor European graphene consumption for sensor arrays. ECHA REACH substance registration tightens purity documentation requirements for imported 2D materials. The Dresden-Leipzig semiconductor cluster hosts pilot production lines for van der Waals heterostructure integration.
China
Display manufacturers BOE Technology Group and TCL CSOT in Beijing and Shenzhen consume transparent conductive films for foldable panel backplanes. SAMR-enforced GB standards for nanomaterial classification shape import protocols and domestic production licensing. The Yangtze River Delta concentration of foundry capacity drives captive graphene synthesis investments.
South Korea
Samsung Display and SK Hynix anchor demand for CVD-grown graphene in Gyeonggi Province fabrication facilities. The Ministry of Trade, Industry and Energy coordinates national consortia for 2D material foundry integration. Seoul-based medical imaging OEMs pilot biosensor arrays using stacked graphene-hBN-TMD architectures.
Japan
Materials traders in Tokyo and Osaka reposition as technical intermediaries offering metrology services rather than commodity distribution. METI coordinates JIS standardization frameworks for 2D material characterization protocols. The Tsukuba research corridor concentrates national laboratory procurement of exfoliated flakes for fundamental device physics studies.
2D Electronics Market Vendor Landscape
On the supply side, the industry is bifurcated between European CVD growth specialists and East Asian captive synthesis operations. Merchant graphene supply concentrates among wafer-scale producers with transfer expertise, while IDMs deepen backward integration into in-house material production. Two strategic archetypes dominate: technology licensors with heterogeneous integration IP, and specialty foundries qualifying 2D channel nodes. Competitive moves center on long-term offtake agreements and metrology service bundling.
Within the merchant supply tier, Graphenea and Haydale Limited represent European CVD growth capability, while GlobalFoundries exemplifies the foundry integration archetype. Graphenea anchors wafer-scale graphene supply to device makers across multiple geographies. Haydale Limited occupies a position in functionalization and dispersion services for composite applications. GlobalFoundries sits within the specialty foundry vector, integrating 2D channel materials into advanced node roadmaps for external customers.
| Leading Market Players |
|---|
| Skeleton Technologies |
| Aledia |
| 2D Semiconductors |
| 2D Electronic and Automation |
| Sanko Semiconductor Co., Ltd. |
| Haydale Limited |
| Graphenea |
| GlobalFoundries |
| Nantero, Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European CVD growth facilities is tightening wafer-scale graphene availability and amplifying supplier pricing leverage against East Asian foundries negotiating long-term offtake agreements. This utilization squeeze feeds directly into contract structures that favor volume commitments over spot purchasing.
Pricing Analysis
The technology-generation pricing gap between CVD-grown monolayers, solution-processed thin-films, and experimental van der Waals heterostructures stratifies procurement budgets across buyer tiers. Contract-based long-term offtake agreements dominate, with price differentiation driven by defect density certification and transfer yield guarantees. Cost compression in thin-film tiers is intensifying because display manufacturers are qualifying lower-grade alternatives for non-critical backplane layers. IDMs in Taiwan and South Korea show least price sensitivity due to captive synthesis investments, while merchant foundries absorb margin pressure.
Supply Chain Analysis
Extended payment terms from European graphene producers to East Asian foundries are stabilizing working capital across the value chain despite raw material volatility. Supply concentrates in Spain and Germany for CVD growth, South Korea for device integration, and Japan for metrology equipment. The chain draws from copper foil substrates, high-purity precursor gases, and specialized transfer polymers. Single-source vulnerability in wafer-scale production creates qualification bottlenecks when European facilities reach capacity limits. Distribution runs through direct IDM procurement with technical intermediaries providing metrology services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among vertically integrated IDMs in Taiwan and South Korea, fragmenting procurement leverage for merchant foundries and forcing supply-side consolidation around captive synthesis capabilities.
For Market Incumbents: Pre-empt emerging foundry competition by locking European CVD producers into exclusive wafer-scale supply arrangements before Samsung and SK Hynix complete backward integration into in-house graphene growth. Defend margin position through METI-coordinated JIS certification investments that create qualification barriers for unstandardized entrants.
For New Entrants and Emerging Players: Establish a beachhead in automotive transparent heating elements, where graphene penetration lags display applications and incumbent supply relationships remain unformed. Target German medical OEM pilot programs requiring biosensor-grade material, leveraging REACH compliance documentation as a go-to-market wedge against unqualified Asian suppliers.
For Investors and Strategic Acquirers: Capital is best deployed toward European CVD specialists with demonstrated wafer-scale transfer yields and existing offtake relationships with East Asian foundries. Over a multi-year horizon, acquisition value crystallizes around facilities achieving sub-5% defect density at 300mm scale. The signal to watch is Samsung Advanced Institute licensing activity for van der Waals heterostructure IP.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive CVD Synthesis Investment | Samsung and SK Hynix are building in-house graphene growth to bypass European merchant supply bottlenecks. |
| JIS Standardization Participation | METI-coordinated protocols create first-mover qualification advantages for compliant Japanese and foreign suppliers. |
| Long-term Offtake Agreements | Taiwan-based foundries are securing multi-year contracts specifying defect density thresholds and transfer yield guarantees. |
| Automotive Infotainment Penetration | Transparent conductive films remain underpenetrated in vehicle touch surfaces relative to smartphone displays. |
| Carbon Nanotube Memory Convergence | Nantero's architectures bypass silicon scaling limits and create hybrid 2D electronics opportunities in edge computing. |
Methodological Framework
A standing panel of CVD growth specialists, foundry process engineers, medical device procurement managers, and graphene metrology technicians provided ongoing calibration across primary interview cycles. Secondary validation drew from SAMR GB standard filings, ECHA REACH substance registrations, EPA Section 8(a) toxicity documentation, Samsung Advanced Institute technical disclosures, and IMEC process development announcements. Bottom-up capacity estimates from European CVD facilities were triangulated against top-down demand projections from East Asian display and foundry capital expenditure tracking.
Scenario-bracketing around regulatory acceleration, foundry yield maturation, and alternative material substitution framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product architecture, synthesis method, application vertical, and end-user procurement authority, with regional regulatory clusters treated as distinct demand modifiers. CAGRs were derived from capacity-expansion timelines and qualification pathway durations, incorporating van der Waals heterostructure integration milestones and medical device FDA-EPA dual-jurisdiction bottlenecks as industry-specific forecast inputs.
Sensitivities concentrate around REACH enforcement intensity, Chinese domestic production licensing acceleration, and breakthroughs in roll-to-roll manufacturing yields. Forecasts reflect documented assumptions about foundry partnership structures and regulatory qualification timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Global Flexible Electronics and Circuit Market
Electronic Components
Coaxial Coupler Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
Electromechanical Timers Market
Electronic Components
Serial Device Servers Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Gas Discharge Tube Market
Electronic Components
Lowpass Filters Market
Electronic Components
Electric Vehicle (EV) Electronic Components Market
Electronic Components
Crystal Oscillators Market
Electronic Components
Digital Isolator Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Blockchain in Electronic Component Market
Electronic Components
Structural Electronics Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
Battery Shunt Resistor Market