
 Wheat Starch Derivative Market | 2026-2036
Wheat Starch Derivative Market Size, Share, and Industry Trends Forecast 2026-2036
Wheat Starch Derivative Market Insights
Capital-intensity divergence between integrated wet-milling operators and toll-processing specialists is redrawing competitive boundaries across the wheat starch derivative value chain. Roquette Frères leverages its backward integration into European wheat supply chains to sustain margin resilience against raw material volatility. Cargill, Incorporated competes through its transcontinental grain origination network, while Ingredion Incorporated differentiates via application-specific modified starch portfolios tailored to pharmaceutical binding specifications.
Wheat starch derivatives comprise glucose polymers extracted from Triticum aestivum endosperm through wet-milling, fractionation, and enzymatic or chemical modification, yielding products with amylose-to-amylopectin ratios tunable between 15:85 and 30:70 for targeted viscosity and gelation behavior. Modified starch commands the deepest margin pools due to functional premiums in controlled-release drug delivery systems, while native starch retains volume leadership in paper & pulp sizing applications where cost efficiency dominates procurement criteria. Liquid starch formats are gaining share in beverage stabilization as cold-process compatibility reduces energy inputs during formulation.
REACH registration requirements in Europe and FDA food additive regulations in the United States constrain novel modification chemistries, channeling R&D investment toward enzymatic pathways that satisfy both frameworks. The EU Green Deal's emerging bio-based content thresholds will likely tighten market access for petrochemical-competing derivatives, favoring wheat-origin supply chains with verified sustainability credentials. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost position of imported modified starches against regionally produced alternatives.
Market Dynamics
Clean-label mandates from EFSA and FDA are forcing reformulation cycles across food and pharmaceutical applications, compressing development timelines while expanding enzymatic modification adoption.
Growth Catalysts
- EU Green Deal bio-based thresholds:Emerging mandates favor wheat-origin derivatives over petrochemical alternatives, channeling procurement toward verified sustainable supply chains.
- Controlled-release pharmaceutical demand:Modified starches with tunable amylose ratios enable precision drug delivery, expanding application in oral solid dosage forms.
- Germany's processing cluster concentration:Roquette Frères and Südzucker AG anchor wet-milling capacity that reduces logistics costs for European formulators.
Market Restraints
- Raw material volatility:Triticum aestivum prices fluctuate with Black Sea export disruptions and climate yield variability, compressing margin predictability for non-integrated processors.
- REACH registration friction:Novel chemical modification pathways face multi-year ECHA evaluation timelines, freezing innovation pipelines for smaller developers lacking regulatory affairs scale.
- Corn starch substitution pressure:Maize-derived alternatives offer lower input costs in paper sizing and adhesives, threatening volume retention in cost-sensitive industrial segments.
Strategic Opportunities
- India PLI scheme for specialty chemicals:Domestic modified starch production incentives attract capacity investment targeting pharmaceutical excipient import substitution.
- Cold-process beverage stabilization:Liquid wheat starch formats reduce energy inputs during formulation, aligning with carbon reduction targets in beverage manufacturing.
- Carbon border adjustment positioning:EU CBAM implementation creates tariff advantages for regionally produced derivatives against imported Asian supply.
Industry Challenges
- Enzymatic process engineering talent scarcity:Specialized biochemists capable of optimizing amylase-driven modification pathways command premium compensation, constraining R&D expansion.
- Legacy equipment retrofit costs:Wet-milling facilities require capital-intensive upgrades to handle diversified feedstock specifications for organic and non-GMO wheat streams.
- Dual certification complexity:Simultaneous FDA food additive and pharmaceutical excipient qualification demands parallel documentation systems, extending commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheat Starch Derivative Market |
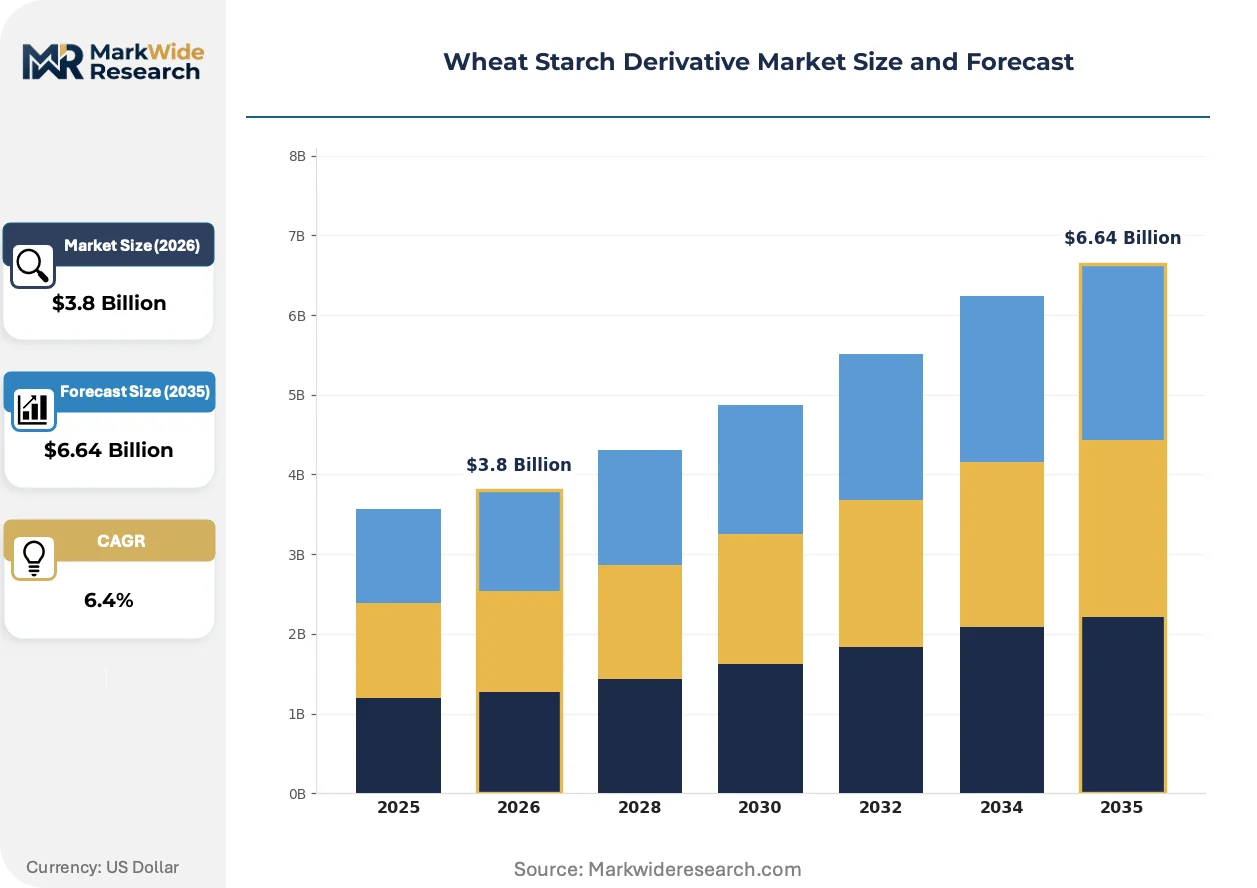
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Liquid Starch, Powdered Starch End Use Industry: Food & Beverage, Pharmaceuticals, Paper & Pulp, Textiles Application: Thickening Agent, Stabilizer, Emulsifier, Binder Packaging Type: Bulk Bags, Sachets, Cartons, Pails |
| Companies Covered | Roquette Frères, Agrana Beteiligungs-AG, Cargill, Incorporated, Manildra Group, Tate & Lyle PLC, ADM, Südzucker AG, Tereos Group, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheat Starch Derivative Market Trends and Innovations
Enzymatic modification pathways are displacing chemical processes across premium applications, while sustainability verification systems reshape supplier qualification criteria and procurement workflows.
Precision enzymatic hydrolysis is fragmenting the traditional modified starch landscape by enabling site-specific molecular tailoring without residual chemical reagents. Pharmaceutical manufacturers in Switzerland and Germany adopt these processes fastest, driven by excipient purity specifications. The technology is fragmenting competitive advantage toward biotech-enabled processors and away from conventional chemical modification specialists.
REACH authorization requirements for specific starch esterification reagents are tightening market access for legacy product lines. ECHA's expanding candidate list of substances of very high concern forces reformulation investment across European supply chains. Modified starch producers serving medical device coatings face the steepest compliance burdens, accelerating migration toward enzymatic alternatives.
Direct supplier relationships are displacing distributor-mediated procurement in large food and beverage accounts. Tier-one manufacturers in France and the Netherlands now require farm-to-facility traceability systems, bypassing traditional ingredient distributors. This pattern concentrates volume with integrated processors capable of sustainability certification at origin.
Wheat Starch Derivative Market Segmentation
Wheat starch derivative producers navigate divergent margin structures across product architectures and end-use specifications. Application-specific functional requirements in pharmaceuticals command premium pricing, while commodity paper sizing applications compress returns.
Product Type:
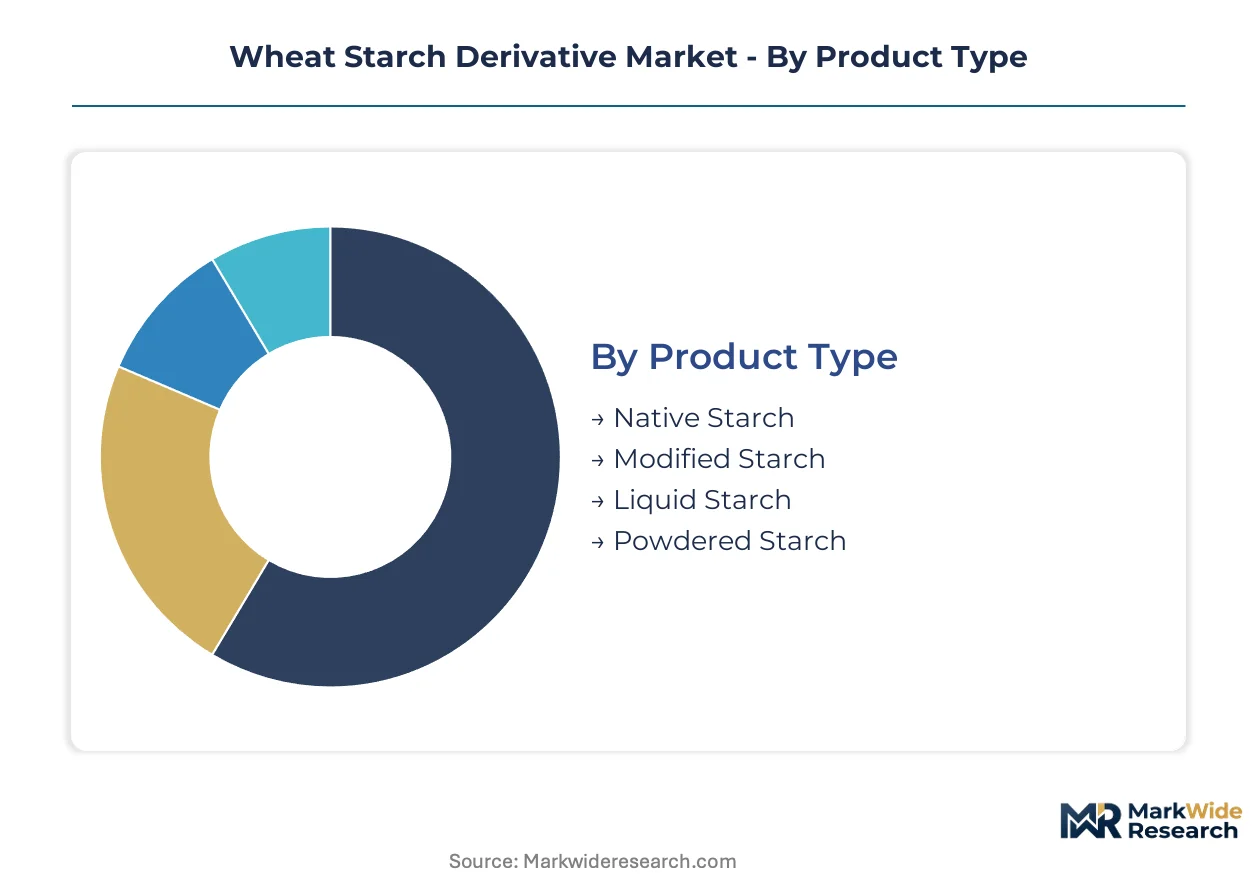
Modified starch captures the deepest margin pools through pharmaceutical and controlled-release applications, while native starch competes on volume in cost-sensitive industrial segments.
- Modified Starch:Chemical or enzymatic alteration of amylose-to-amylopectin ratios yields tunable viscosity profiles for precision drug delivery systems. Demand concentrates in German and Swiss pharmaceutical manufacturing, where excipient purity specifications favor enzymatic modification pathways over residual chemical reagents.
- Native Starch:Unmodified glucose polymers extracted through standard wet-milling retain amylose-to-amylopectin ratios of approximately 25:75. Paper and pulp sizing operations in France and the Netherlands drive procurement volumes, prioritizing cost efficiency over functional customization.
- Liquid Starch:Pre-hydrated formats enable cold-process beverage stabilization, reducing energy inputs during formulation.
- Powdered Starch:Dehydrated formats dominate dry-mix food applications and extended-shelf-life logistics.
The dominant share belongs to native starch, while modified starch is closing the gap fastest.
End Use Industry:
Customer concentration patterns split between formulation-driven sectors demanding technical service and specification-driven buyers prioritizing supply security.
- Food & Beverage:Clean-label mandates from EFSA and FDA force reformulation cycles across bakery, dairy, and convenience food applications. German manufacturers lead adoption of enzymatically modified starches to satisfy regulatory scrutiny while maintaining texture performance.
- Pharmaceuticals:Oral solid dosage forms and controlled-release coatings require excipient grades meeting both FDA food additive and pharmaceutical qualification standards. Swissmedic and EMA guidelines on residual reagent limits favor enzymatic modification suppliers.
- Paper & Pulp:Surface sizing and coating operations consume high volumes of unmodified starch where corn alternatives exert substitution pressure.
- Textiles:Warp sizing and finishing applications demand specific viscosity stability under mechanical stress and alkaline conditions.
Food and beverage holds the largest procurement volume, though pharmaceuticals deliver the steepest expansion trajectory.
Application:
Functional performance requirements determine specification granularity and supplier qualification intensity across use cases.
- Thickening Agent:Viscosity development under shear and temperature stress defines performance in soups, sauces, and dairy systems. French food manufacturers specify cold-swelling modified starches for clean-label ready meals.
- Stabilizer:Freeze-thaw stability and syneresis prevention drive adoption in frozen desserts and prepared foods. Liquid starch formats gain share in beverage manufacturing for process energy reduction.
- Emulsifier:Surface-active starch derivatives stabilize oil-water interfaces in dressings and flavor encapsulation systems.
- Binder:Tablet compression and granulation performance in pharmaceutical manufacturing demands specific particle size distributions and flow characteristics.
Thickening applications dominate current volume, with stabilization functions expanding most quickly.
Packaging Type:
Logistics economics and handling automation requirements shape format selection across customer scale tiers.
- Bulk Bags:One-tonne flexible intermediate bulk containers serve high-volume paper mills and integrated food processors with pneumatic conveying systems.
- Sachets:Pre-weighed unit doses support laboratory-scale pharmaceutical development and artisan food production.
- Cartons:Multi-wall paperboard containers balance protection with palletization efficiency for mid-scale food manufacturers.
- Pails:Rigid plastic containers with resealable lids serve liquid starch formats and moisture-sensitive modified grades.
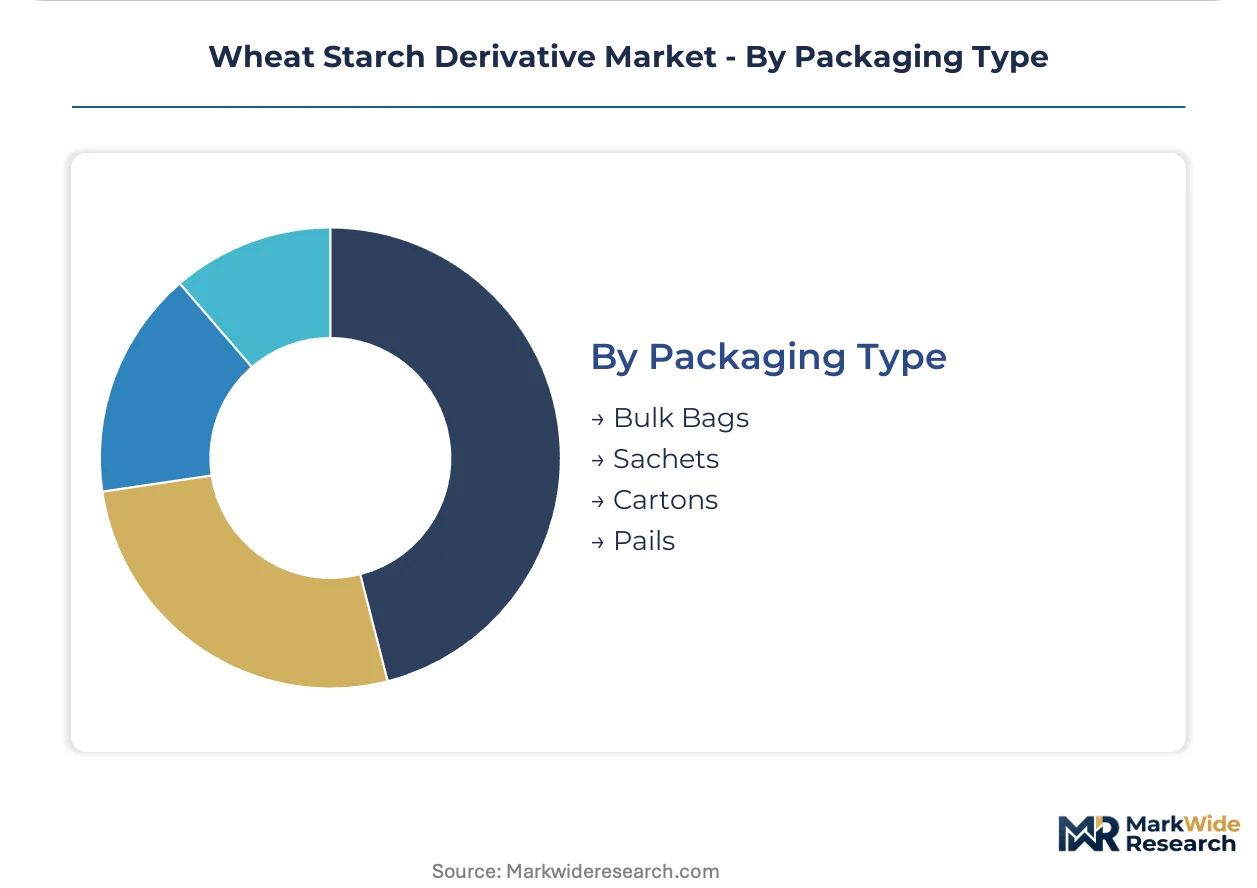
Bulk bags command the greatest tonnage throughput, while sachet formats are climbing the fastest on precision formulation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where Roquette Frères and Südzucker AG anchor integrated wet-milling capacity, while Asian suppliers face margin compression from carbon border adjustment exposure and logistics premiums into European ports.
Germany
Pharmaceutical excipient demand from Swissmedic-regulated supply chains and clean-label food reformulation drive procurement volumes. ECHA's REACH authorization timelines for starch esterification reagents force enzymatic pathway migration. The Lestrem processing cluster in northern France extends into German border regions, concentrating modified starch output for oral solid dosage forms.
United States
FDA food additive qualification requirements and pharmaceutical binding specifications create dual-certification demand from Midwest formulators. The EPA's emerging bio-based procurement preferences channel federal purchasing toward verified sustainable supply chains. Cargill's transcontinental grain origination network centers on Minneapolis-St. Paul, reducing raw material volatility for integrated processors.
India
Domestic pharmaceutical excipient import substitution and FSSAI clean-label mandates accelerate modified starch adoption in oral drug delivery. The PLI scheme for specialty chemicals attracts capacity investment toward pharmaceutical-grade production. Gujarat's chemical processing corridor near Ahmedabad hosts emerging toll-modification facilities serving CDSCO-regulated formulations.
Switzerland
Swissmedic's residual reagent limits for pharmaceutical excipients favor enzymatic modification suppliers over chemical alternatives. Precision drug delivery system manufacturers in Basel demand tunable amylose-to-amylopectin ratios for controlled-release coatings. The country's pharmaceutical manufacturing density creates premium pricing for certified excipient grades.
France
EFSA clean-label enforcement drives bakery and dairy reformulation toward enzymatically modified starches. The EU Green Deal's bio-based content thresholds channel public procurement toward wheat-origin derivatives with verified sustainability credentials. Roquette Frères' Lestrem facility anchors European wet-milling capacity, reducing logistics costs for French food manufacturers.
Wheat Starch Derivative Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the wheat starch derivative value chain. Integrated wet-milling operators with backward control over European wheat supply chains sustain margin resilience against raw material volatility, while toll-processing specialists compete on formulation flexibility for mid-scale accounts. Three archetypes dominate: integrated grain processors with captive supply, enzymatic modification technology specialists, and regional toll-modification service providers. Competitive intensity concentrates on M&A-driven consolidation of European processing capacity and strategic partnerships securing pharmaceutical excipient qualification pathways.
Within the integrated processor tier, Roquette Frères and Südzucker AG exemplify European-based operators with wet-milling scale sufficient to serve dual food and pharmaceutical demand. Cargill, Incorporated represents the transcontinental grain origination archetype, leveraging North American and European supply chain presence. These three entities occupy positions where sustainability verification and regulatory qualification capabilities determine supplier selection in clean-label and pharmaceutical applications.
| Leading Market Players |
|---|
| Roquette Frères |
| Agrana Beteiligungs-AG |
| Cargill, Incorporated |
| Manildra Group |
| Tate & Lyle PLC |
| ADM |
| Südzucker AG |
| Tereos Group |
| Ingredion Incorporated |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day inventory cycles for modified starch grades concentrate pricing power with Roquette Frères and Südzucker AG, whose German processing clusters compress logistics premiums for European pharmaceutical formulators while exposing toll-dependent competitors to Triticum aestivum volatility.
Pricing Analysis
Configured-to-order enzymatic modification commands 15-25% premiums over standard chemical-modified grades, with pharmaceutical excipient certification and residual-reagent testing as primary price differentiation drivers. Three-tier pricing structure across premium enzymatic, standard chemical-modified, and economy native starch levels stratifies procurement by application criticality. Cost compression in paper sizing grades intensifies because corn starch substitution erodes volume retention. Food and beverage manufacturers exhibit highest price sensitivity due to reformulation frequency, while Swiss pharmaceutical buyers prioritize purity specifications over unit economics.
Supply Chain Analysis
Germany and France anchor European wet-milling capacity, with Roquette Frères' Lestrem facility and Südzucker AG's Mannheim complex processing high-amylose wheat varieties for pharmaceutical and food applications. Raw material flows draw from Black Sea and French wheat belts, with amylase enzymes and esterification reagents as critical chemical inputs. Single-source vulnerability concentrates in enzymatic modification biocatalyst supply, where specialized amylase producers command allocation priority. Distribution runs through direct supplier relationships with tier-one manufacturers, bypassing traditional ingredient distributors for traceability-verified volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label regulatory fragmentation across FDA, EFSA, and FSSAI jurisdictions creates service-layer specialization opportunities, rewarding processors capable of multi-certification documentation and rapid reformulation support.
For Market Incumbents: Consolidate enzymatic modification capacity in Germany and Switzerland to defend margin pools against Asian toll-processors facing carbon border adjustment exposure. Acquire regional toll-modification specialists in India under PLI scheme incentives to preempt excipient import substitution. Backward integration into organic wheat supply chains secures sustainability verification credentials for EU Green Deal procurement thresholds.
For New Entrants and Emerging Players: Cold-process liquid starch technical service gaps in beverage manufacturing offer white-space entry, where incumbents under-serve mid-scale craft producers lacking formulation chemistry expertise. Target Indian pharmaceutical CDMOs seeking excipient qualification support for CDSCO-regulated export markets. Lead with application-specific stabilization protocol development rather than commodity volume positioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic modification infrastructure, favoring asset-light toll-processing models for portfolio diversification. Five-to-ten-year viability hinges on REACH-compliant pathway migration and pharmaceutical excipient qualification depth. Acquire enzymatic technology specialists with established ECHA registration dossiers. Monitor ECHA candidate list expansion as signal for chemical-modification asset impairment risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Capacity Expansion | REACH authorization timelines favor enzymatic pathways over chemical esterification reagents facing SVHC listing. |
| Backward Integration into Wheat Supply | Roquette Frères' captive grain origination sustains margin resilience against Black Sea export disruptions. |
| Pharmaceutical Excipient Qualification | Dual FDA food additive and Swissmedic pharmaceutical certification unlocks premium pricing in Basel manufacturing cluster. |
| Direct Supplier Relationship Development | Farm-to-facility traceability systems bypass distributors for tier-one French and Dutch food manufacturer procurement. |
| Cold-Process Liquid Starch Format Launch | Energy reduction alignment with EU Green Deal carbon targets accelerates beverage industry adoption. |
Research Methodology
Initial hypotheses were tested against primary input from wet-milling plant managers, pharmaceutical procurement leads, food manufacturer R&D directors, and enzymatic process biochemists and refined through secondary validation against ECHA registration databases, FDA food additive petitions, EU customs trade flows, and SEC 10-K filings from listed processors. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Variance decomposition across product type, end-use industry, modification technology, and regional regulatory cluster dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling and capacity utilization trajectories. Forecast inputs incorporated REACH authorization pipeline status and PLI scheme implementation pace for Indian capacity investment.
Forecasts assume regulatory continuity in FDA food additive and REACH authorization regimes; material policy shifts in ECHA SVHC listing criteria or EU carbon border adjustment scope would require re-modeling. Recalibration cycles align with material shifts in clean-label enforcement intensity and enzymatic process engineering talent availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Isoamyl Laurate Market
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
GCC Bakery Ingredients Market
Ingredients
Glucosylglycerol Market
Ingredients
Microbial Food Ingredients Market
Ingredients
Soy Protein Isolate Market
Ingredients
Food Minerals Market
Ingredients
Global Pregelatinized Starch Market
Ingredients
Precision Fermentation Ingredient Supplier Market
Ingredients
Moringa Ingredients Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
Sugar Beet Pectin Market
Ingredients
Starch Market
Ingredients
Astragalus Root Extract Market
Ingredients
Hydrogenated Starch Market
Ingredients
Egg Phosphatidylcholine Market