
 Pork Skin Gelatin Market | 2026-2036
Pork Skin Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
Pork Skin Gelatin Market Analytics
A skilled collagen-extraction workforce shortage is redrawing competitive boundaries in the pork skin gelatin industry. GELITA AG leverages its century-old German manufacturing footprint to dominate technical-grade production. Rousselot sustains global reach through integrated hide-to-gelatin operations across multiple continents. PB Leiner specializes in pharmaceutical-grade porcine gelatin, occupying the highest-margin segment of the value chain.
Pork skin gelatin comprises collagen peptides extracted through controlled acid or alkaline processing of porcine dermis, yielding Type A or Type B gelatin with bloom strengths ranging from 50 to 300 grams for specific industrial binding and gelling functions. The powder form commands the largest volume share due to its dissolution efficiency in beverage and pharmaceutical applications. Nutraceuticals represents the fastest-expanding application as soft-gel and hard-shell capsule demand accelerates among supplement providers. Food and Beverage remains the mature revenue base, though margin compression from commodity competition pushes manufacturers toward higher-specification pharmaceutical and cosmetic grades.
EMA guidelines on transmissible spongiform encephalopathies and FDA BSE regulations enforce strict sourcing documentation for porcine materials used in drug delivery systems. BIS certification requirements in India and China's NMPA gelatin monograph standards further segment market access by quality tier. Stakeholders must monitor evolving religious and dietary certification demands—halal, kosher, and vegan alternatives—as these labels increasingly determine channel eligibility and pricing power in consumer-facing applications.
Market Dynamics
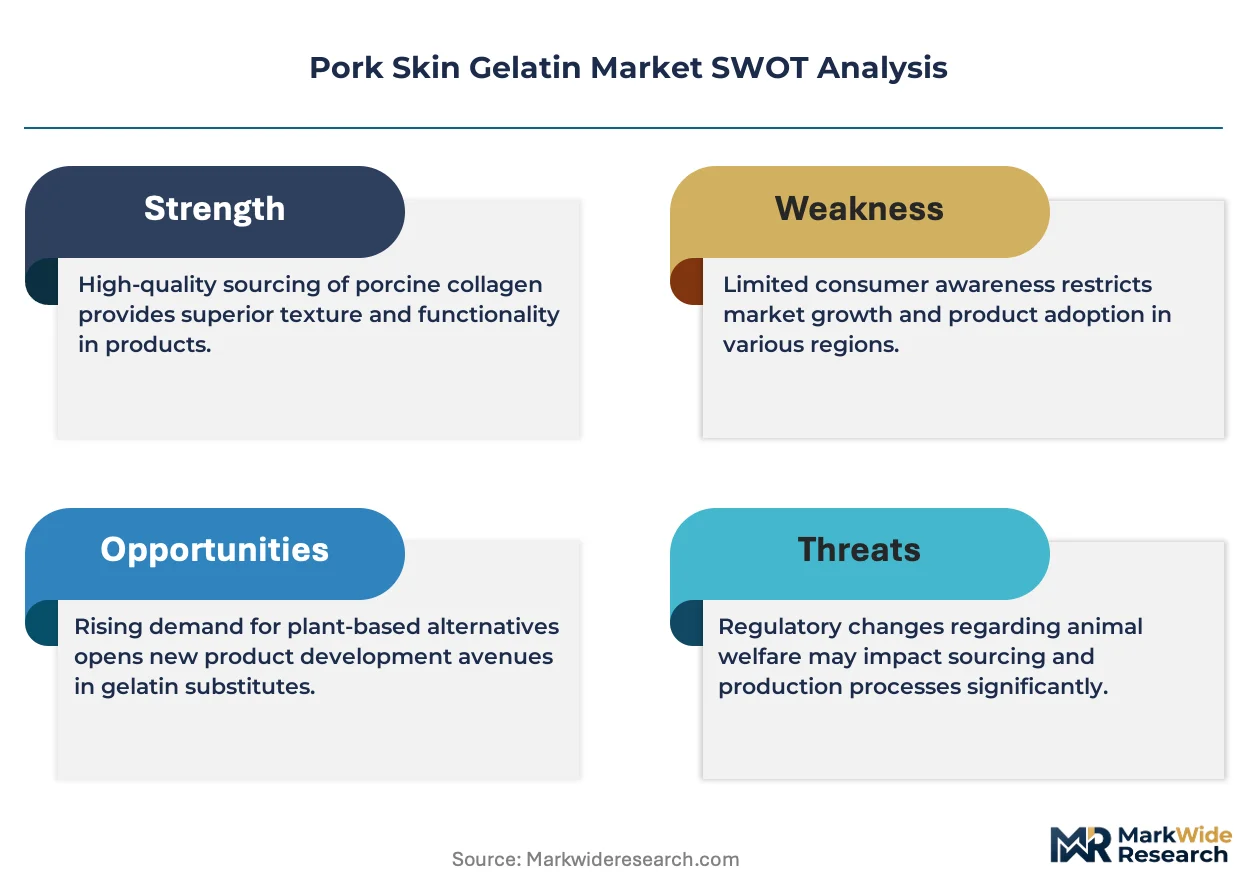
Pharmaceutical capsule demand is concentrating procurement power among gelatin buyers, forcing processors to upgrade from food-grade to pharmaceutical-grade certification while absorbing stricter EMA and FDA traceability costs.
Growth Catalysts
- Pharmaceutical capsule demand:Soft-gel and hard-shell manufacturers are expanding porcine gelatin procurement for drug delivery systems, driven by bioavailability requirements and patient compliance trends.
- EMA TSE guidelines:European regulatory enforcement of transmissible spongiform encephalopathy documentation is standardizing quality tiers and accelerating consolidation among certified suppliers.
- Collagen peptide extraction:Acid and alkaline processing advances are yielding higher-bloom gelatin (200-300g) for specialized binding applications in nutraceuticals.
Market Restraints
- Raw material concentration:Porcine dermis supply chains cluster in Germany and select EU processing hubs, creating geographic vulnerability to livestock disease outbreaks.
- Religious certification friction:Halal and kosher requirements segment addressable markets, forcing parallel production lines and inventory duplication for Muslim and Jewish consumer channels.
- Plant-based substitution:Algae-derived and microbial fermentation alternatives are penetrating cosmetic and premium food applications where label claims outweigh functional performance.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO and BIS certification pathways are opening as domestic capsule producers seek localized porcine gelatin supply to reduce import dependence.
- Cosmeceutical collagen integration:Topical and ingestible beauty formulations are converging on Type A gelatin with specific molecular weight profiles for skin hydration claims.
- China NMPA harmonization:Revised gelatin monograph standards are creating tiered market access where EU-certified processors can capture premium positioning over domestic competitors.
Industry Challenges
- Skilled extraction technician scarcity:Acid-alkali process control and bloom strength calibration require specialized training that outpaces vocational pipeline output in traditional manufacturing regions.
- Multi-certification audit burden:Simultaneous EMA, FDA, and national pharmacopeia compliance creates documentation overhead that stretches quality assurance teams across overlapping inspection cycles.
- Legacy equipment retrofit costs:Pharmaceutical-grade migration demands stainless steel processing infrastructure and cleanroom environments that strain mid-tier processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pork Skin Gelatin Market |
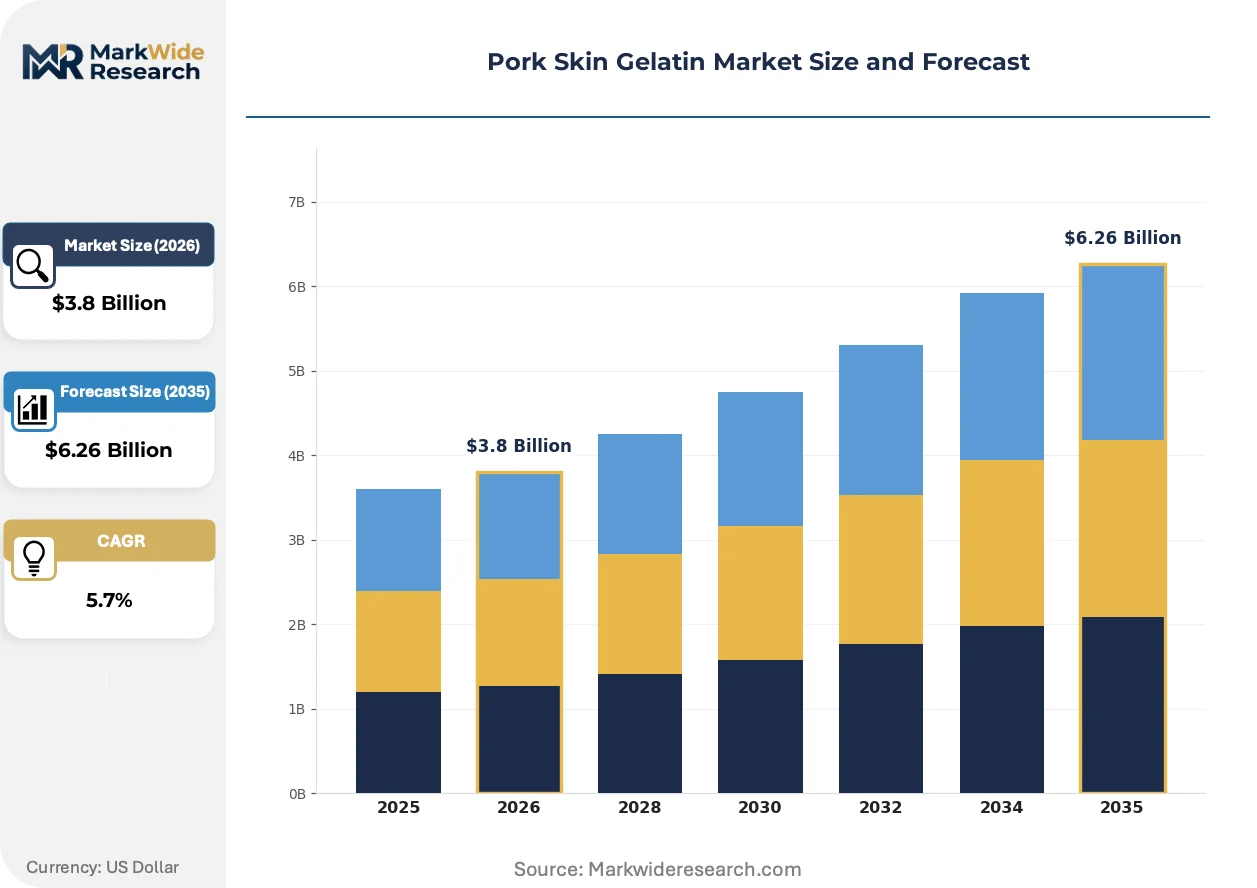
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
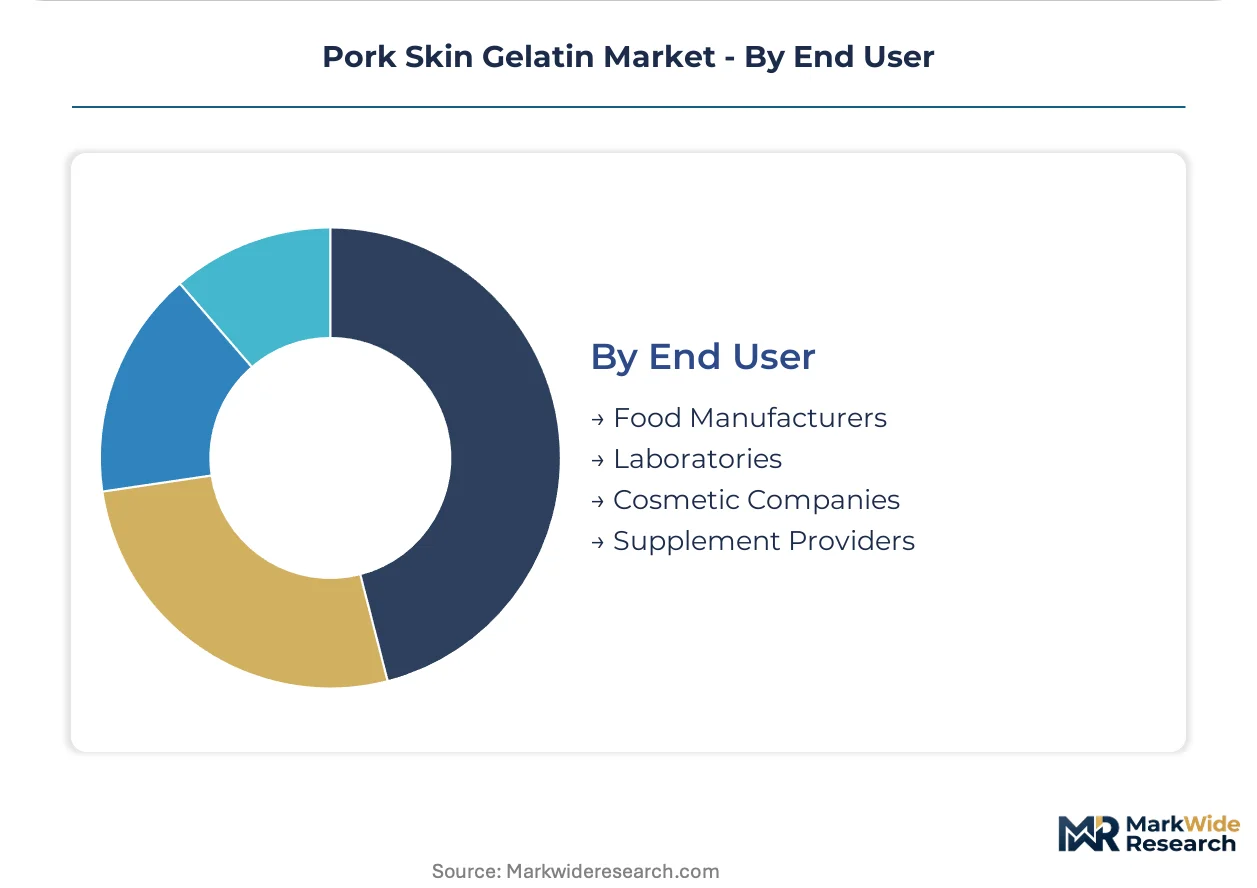
| Segmentation | Product Type: Granules, Powder, Sheets, Capsules Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Form: Liquid, Solid, Semi-Solid, Gel End User: Food Manufacturers, Laboratories, Cosmetic Companies, Supplement Providers |
| Companies Covered | GELITA AG, Nitta Gelatin Inc., Rousselot, Tessenderlo Group, Weishardt Group, Sterling Biotech Limited, Lapi Gelatine S.p.A., PB Leiner, Trobas Gelatine B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pork Skin Gelatin Market Evolving Landscape
Enzymatic hydrolysis protocols are shortening extraction cycles while preserving peptide chain integrity, reshaping capital efficiency benchmarks across gelatin processing tiers.
Membrane filtration technology is supplanting traditional evaporation and drying stages in high-purity gelatin production. Pharmaceutical manufacturers in Germany and Switzerland are adopting ceramic membrane systems to reduce thermal degradation of collagen peptides. This shift is compressing energy costs per kilogram while enabling tighter molecular weight distribution control for capsule gel strength specifications.
REACH framework updates and the EU F-Gas Regulation are tightening documentation requirements for animal-derived ingredients used in drug delivery systems. Processors must now maintain batch-level traceability from slaughterhouse through hydrolysis to finished excipient. German and Dutch gelatin manufacturers are responding by deploying blockchain-anchored supply chain verification to preempt regulatory audit failures.
Direct contracting between capsule manufacturers and certified processors is displacing spot-market gelatin purchasing in pharmaceutical applications. Large supplement brands in North America and Western Europe are negotiating multi-year supply agreements with guaranteed bloom strength tolerances and dedicated production runs. This pattern is most visible among soft-gel producers seeking to lock in Type A gelatin with specific viscosity profiles for high-potency oil formulations.
Pork Skin Gelatin Market Segmentation
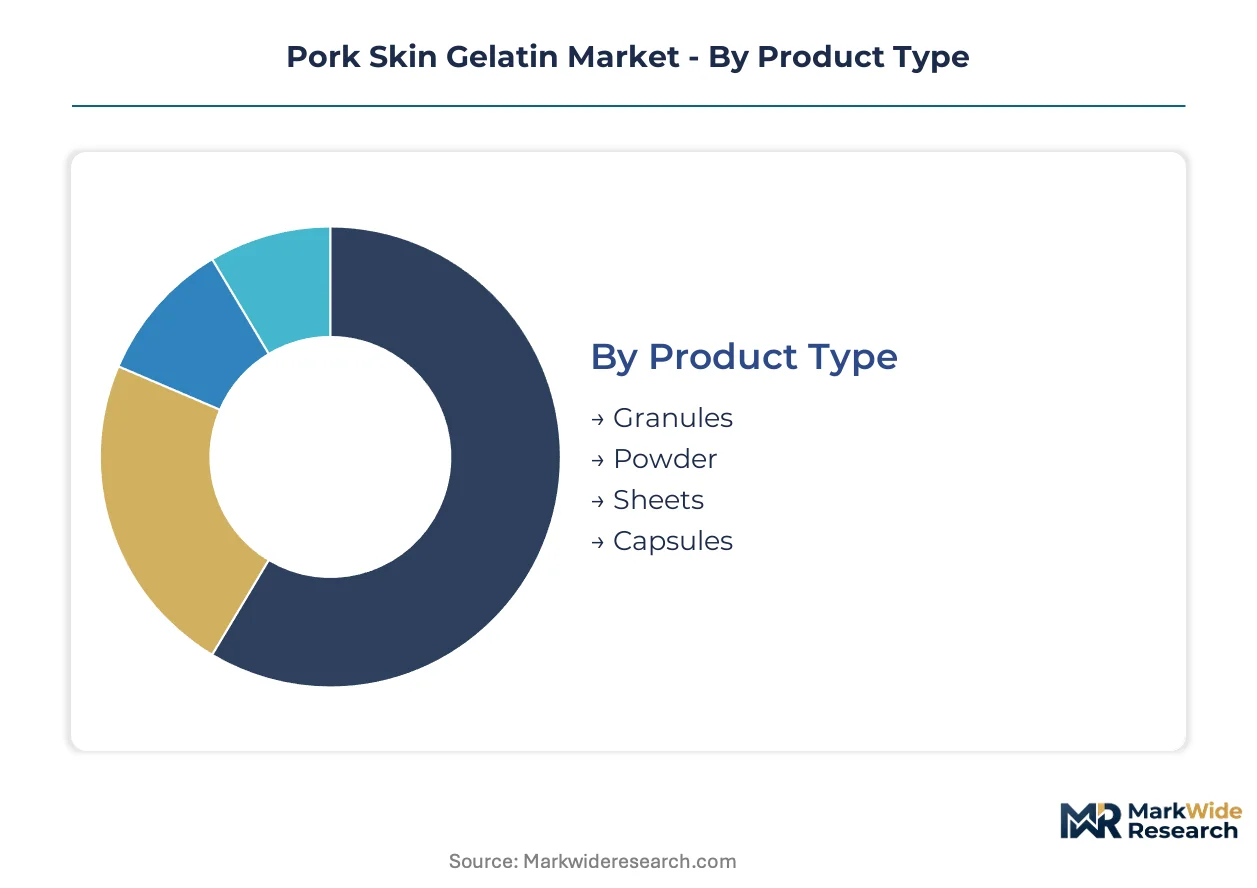
Pork skin gelatin processors must align product specifications with end-use certification tiers and substitution vulnerability. Segmentation choices determine margin capture, regulatory burden, and exposure to plant-based alternatives.
Product Type:
Powder and granule formats face divergent substitution pressures from algae-derived hydrocolloids in beverage and pharmaceutical applications.
- Powder:Fine-milled collagen peptides with dissolution profiles optimized for high-speed capsule manufacturing and instant beverage formulations. Demand concentrates among soft-gel producers in Germany and Switzerland where bloom strength tolerances of 150-250g are mandatory for oil-based drug delivery systems.
- Granules:Coarse-particle gelatin with controlled hydration kinetics for industrial-scale food processing. Confectionery manufacturers in Belgium and the Netherlands specify granule size distributions to prevent lumping in high-shear mixing environments.
- Sheets:Pre-gelatinized leaf gelatin standardized to bloom-equivalent weights for premium culinary and artisan confectionery applications.
- Capsules:Pre-formed hard-shell and soft-gel configurations requiring pharmaceutical-grade certification and EMA TSE documentation for direct drug delivery use.
Powder retains volume leadership; capsules hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity food binders from certified pharmaceutical excipients with tenfold price differentials.
- Pharmaceuticals:High-purity Type A and Type B gelatin meeting USP-NF and EP monograph standards for capsule shells and tablet binders. CDSCO in India and NMPA in China enforce parallel import substitution policies that favor domestic certification pathways.
- Nutraceuticals:Collagen peptides with specific molecular weight ranges (2,000-5,000 Da) for soft-gel dietary supplements targeting bioavailability claims. North American supplement brands are locking in multi-year supply agreements with guaranteed viscosity profiles.
- Food & Beverage:Standard-grade gelatin for confectionery, dairy, and meat applications where price sensitivity limits specification upgrading.
- Cosmetics:Low-ash hydrolyzed collagen for topical formulations and ingestible beauty products competing directly with marine and fermentation-derived alternatives.
Food & Beverage retains volume leadership; Nutraceuticals holds the steepest expansion curve.
Form:
Customer type preferences diverge between industrial processors seeking handling efficiency and laboratory users demanding precise dosing control.
- Solid:Dried gelatin with moisture content below 15% for extended shelf stability in ambient storage and bulk shipment.
- Liquid:Pre-hydrated collagen solutions for cosmetic formulators and specialized pharmaceutical coating operations.
- Gel:Set gelatin matrices for culinary applications and prototype pharmaceutical formulation testing.
- Semi-Solid:Intermediate viscosity preparations for compound pharmacies and custom supplement manufacturing.
Solid retains volume leadership; Liquid holds the steepest expansion curve.
End User:
Supply concentration among German and Dutch processors shapes procurement power across buyer categories with divergent certification requirements.
- Supplement Providers:Branded and private-label nutraceutical companies specifying halal-certified or kosher-certified gelatin for channel access in Muslim and Jewish consumer markets.
- Food Manufacturers:Large-scale confectionery and dairy processors purchasing food-grade gelatin on annual contracts with volume-based pricing tiers.
- Cosmetic Companies:Formulators seeking low-molecular-weight hydrolyzed collagen for topical anti-aging claims and ingestible beauty products.
- Laboratories:Research and quality control facilities requiring analytical-grade gelatin for cell culture media and diagnostic reagent production.
Food Manufacturers retain volume leadership; Supplement Providers holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States consume pork skin gelatin through divergent application mixes, with pharmaceutical-grade absorption dominating Central European procurement while food-grade volumes persist in North American confectionery channels.
Germany
Pharmaceutical capsule manufacturers in Baden-Württemberg and North Rhine-Westphalia drive Type A gelatin procurement for soft-gel drug delivery systems. EMA TSE documentation requirements enforce batch-level traceability from slaughterhouse through hydrolysis. GELITA AG's century-old Eberbach facility anchors technical-grade production, while specialized collagen processors in the Rhine-Neckar cluster supply pharmaceutical-grade material to Swiss and German drugmakers.
United States
Nutraceutical soft-gel producers in New Jersey and California specify porcine gelatin with bloom strengths of 150-250g for high-potency oil formulations. FDA BSE regulations mandate strict sourcing documentation for animal-derived excipients used in drug delivery systems. Direct contracting between supplement brands and certified processors is displacing spot-market purchasing, with multi-year supply agreements locking in viscosity profiles and dedicated production runs.
China
Domestic capsule manufacturers in Jiangsu and Zhejiang provinces seek localized porcine gelatin supply to reduce import dependence on European processors. NMPA gelatin monograph standards create tiered market access where EU-certified suppliers capture premium positioning over domestic competitors. Yangtze River Delta pharmaceutical clusters are upgrading from food-grade to pharmaceutical-grade certification to meet export requirements for regulated markets.
India
CDSCO and BIS certification pathways are opening for domestic capsule producers seeking to substitute imported gelatin with locally processed porcine material. Maharashtra and Gujarat house concentrated pharmaceutical manufacturing zones where excipient procurement power is concentrating among large formulation companies. Skilled extraction technician scarcity in traditional manufacturing regions is stretching quality assurance teams across overlapping EMA and FDA inspection cycles.
Switzerland
Swissmedic-enforced quality standards drive demand for the highest-bloom gelatin grades in precision drug delivery applications. Basel and Zurich pharmaceutical clusters specify Type A gelatin with molecular weight distributions controlled through ceramic membrane filtration systems. Cleanroom processing infrastructure requirements strain mid-tier processor balance sheets, favoring integrated suppliers with captive stainless steel hydrolysis capacity.
Pork Skin Gelatin Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in pork skin gelatin manufacturing. The upper tier combines hide-to-gelatin operations across multiple continents with in-house acid-alkali processing control. Specialist processors occupy narrower positions in pharmaceutical-grade certification or regional food-grade supply. Competitive moves center on backward integration into raw material sourcing and multi-certification audit capacity expansion to serve overlapping EMA, FDA, and national pharmacopeia requirements.
Within the integrated processing tier, GELITA AG and Rousselot exemplify scale-driven positions spanning technical-grade and pharmaceutical-grade production. PB Leiner occupies a specialist position focused on the highest-margin pharmaceutical-grade segment. These three companies represent contrasting archetypes: the century-old German manufacturing footprint, the multi-continental hide-to-gelatin operation, and the narrow premium-certification specialist.
| Leading Market Players |
|---|
| GELITA AG |
| Nitta Gelatin Inc. |
| Rousselot |
| Tessenderlo Group |
| Weishardt Group |
| Sterling Biotech Limited |
| Lapi Gelatine S.p.A. |
| PB Leiner |
| Trobas Gelatine B.V. |
| Others |
Value Network & Pricing Analysis
Algae-derived hydrocolloid substitution in cosmetic and premium food channels simultaneously compresses pricing power in commodity gelatin tiers while redirecting processor investment toward pharmaceutical-grade certification infrastructure in Germany and Switzerland. This dual pressure reshapes supply geography by concentrating high-margin production in EMA-regulated zones while pushing standard-grade manufacturing toward cost-optimized regions.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical procurement as soft-gel manufacturers lock in multi-year contracts with guaranteed bloom strength tolerances. Price differentiation hinges on certification tier—EMA TSE documentation commands substantial premiums over food-grade material—and volume scale, with annual contract buyers accessing preferential rates. Pricing pressure stems from plant-based alternatives penetrating cosmetic applications where label claims outweigh functional performance. Food manufacturers exhibit highest price sensitivity, while pharmaceutical capsule producers prioritize supply security over unit cost.
Supply Chain Analysis
Inventory cycles for porcine dermis extend 45-60 days from slaughterhouse to hydrolysis completion, creating working capital intensity that favors integrated processors. Raw material supply concentrates in Germany, the Netherlands, and Denmark, where centralized slaughterhouse networks feed specialized collagen extraction facilities. The chain rests on porcine hide availability, acid-alkali processing chemicals, and pharmaceutical-grade stainless steel infrastructure. Single-source vulnerability emerges from geographic clustering of EMA-certified facilities. Distribution runs through direct processor-to-manufacturer contracting, displacing traditional spot-market intermediation in pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where EMA TSE certification and multi-pharmacopeia compliance create switching costs that entrench established processors. The defensive advantage compounds as audit burden and legacy equipment retrofit requirements raise barriers for aspirant competitors.
For Market Incumbents: Secure backward integration into slaughterhouse partnerships to guarantee traceable porcine hide supply amid livestock disease outbreak risks. Expand multi-certification audit capacity to serve simultaneous EMA, FDA, and NMPA requirements, capturing premium positioning as Chinese pharmaceutical manufacturers upgrade from food-grade to pharmaceutical-grade material. Capacity addition in India addresses CDSCO certification pathways while reducing exposure to EU raw material concentration. For New Entrants and Emerging Players: Lead with enzymatic hydrolysis technology offerings that shorten extraction cycles and reduce thermal degradation, targeting mid-tier processors seeking capital efficiency gains without full pharmaceutical-grade infrastructure investment. The most penetrable white space sits in Indian domestic capsule manufacturing, where import substitution policies favor localized gelatin supply. A go-to-market angle emphasizing ceramic membrane filtration partnerships with existing processors bypasses legacy equipment retrofit barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated processors with captive raw material sourcing and multi-continental manufacturing footprints. Long-term viability hinges on regulatory entrenchment rather than volume scale alone, positioning specialized pharmaceutical-grade certification holders for sustained margin capture. The signal to watch is NMPA harmonization progress, where accelerated EU-China mutual recognition would revalue certified processor assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slaughterhouse Partnerships | Guarantees batch-level traceability required by EMA TSE guidelines and FDA BSE regulations. |
| Pharmaceutical-Grade Certification Investment | Unlocks tenfold price premiums over food-grade material in capsule and tablet binder applications. |
| Enzymatic Hydrolysis Technology Deployment | Compresses extraction cycle time while preserving peptide chain integrity for high-bloom gelatin output. |
| Ceramic Membrane Filtration Adoption | Reduces thermal degradation and enables tighter molecular weight distribution control for Swissmedic specifications. |
| Multi-Pharmacopeia Audit Capacity Expansion | Captures procurement from CDSCO and NMPA-registered manufacturers seeking single-source excipient supply. |
Research Methodology
Operator-level perspectives from gelatin plant managers, pharmaceutical procurement leads at capsule manufacturers, regulatory affairs directors, and cosmetic formulators anchored the qualitative base. These primary engagements combined with secondary validation from EMA guidance documents, FDA BSE regulations, NMPA gelatin monograph standards, and customs trade data covering porcine-derived collagen peptide flows. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across product type, application, and end-user dimensions.
Sensitivity analysis tested forecast robustness against regulatory timeline shifts and substitution technology penetration rates across the projection horizon. The analytical framework modeled segmentation across product format, certification tier, and regional regulatory cluster, with CAGRs derived from demand elasticity analysis in pharmaceutical capsule and nutraceutical soft-gel channels. Industry-specific inputs included bloom strength specification trends, enzymatic hydrolysis adoption curves, and membrane filtration capacity expansion plans.
Underlying assumptions cover sustained EMA TSE documentation enforcement, stable porcine hide supply from German and Dutch slaughterhouse networks, and gradual NMPA-EU certification harmonization, with deviation risk concentrated in livestock disease outbreaks and accelerated plant-based hydrocolloid substitution in cosmetic applications. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Edible Oil Market
Ingredients
Asia Pacific Vegetable Oil Market
Ingredients
Sea Salt Market
Ingredients
Oat Grass Powder Market
Ingredients
Fish Peptones Market
Ingredients
Guar Gum Market
Ingredients
North America Feed Yeast Market
Ingredients
Fresh Yeast Market
Ingredients
Caramel Ingredient Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Cottonseed Oil Market
Ingredients
Specialty Yeast Market
Ingredients
Feed Ingredients Market
Ingredients
Sea Buckthorn Berry Extract Market
Ingredients
Textural Food Ingredients Market
Ingredients
Gluten-Free Flour Market