
 Egg White Powder Market | 2026-2036
Egg White Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Egg White Powder Market Analysis
The capital-intensity divergence between spray-drying specialists and commodity egg processors is unwinding competitive stability in egg white powder manufacturing. Kewpie Corp. leverages its integrated poultry-to-powder operations across Japan to sustain premium-grade output for confectionery clients. Bouwhuis Enthoven BV anchors European supply through backward integration into Dutch egg farming, while Rembrandt Enterprises, Inc. competes on scale from its Midwest US production base.
Egg white powder consists of dehydrated albumen, typically containing 80-92% protein by dry weight, produced through pasteurization and spray-drying or pan-drying to preserve functional whipping and gelling properties for industrial food formulation. The foamed product type dominates bakery applications where stable aeration determines volume and texture outcomes, while the instant segment leads growth in protein supplements as fitness-oriented consumers prioritize rapid solubility. Bulk bags capture the largest margin pool from food manufacturers running continuous production lines, though sachets expand fastest through e-commerce channels targeting home cooks and small-batch restaurants.
FDA oversight of egg product safety under the Egg Products Inspection Act shapes US market access requirements, while EFSA nutrition and health claims regulation determines how European suppliers position egg white powder in protein supplement labeling. The EU F-Gas Regulation indirectly pressures drying equipment upgrades as manufacturers replace refrigerants in cold-chain and climate-controlled storage systems. Stakeholders must monitor evolving allergen labeling mandates across multiple jurisdictions and decide whether to invest in dedicated allergen-free production lines or risk exclusion from clean-label supply chains.
Market Dynamics
The EU Green Deal's decarbonization mandates are forcing spray-drying operators to overhaul energy-intensive thermal processes, reshaping capital allocation and supplier selection across the egg white powder value chain.
Growth Catalysts
- Sports Nutrition Formulation:Ready-to-mix protein brands in Germany and the Netherlands are standardizing high-foaming egg white powder for clean-label muscle recovery products, displacing whey in lactose-free portfolios.
- EU F-Gas Regulation:Refrigerant phase-down requirements are accelerating equipment modernization in climate-controlled storage, indirectly upgrading cold-chain reliability for heat-sensitive albumen derivatives.
- Industrial Bakery Automation:German bread and pastry manufacturers are specifying instant-soluble powders for continuous mixing lines, reducing hydration variability in high-throughput production.
Market Restraints
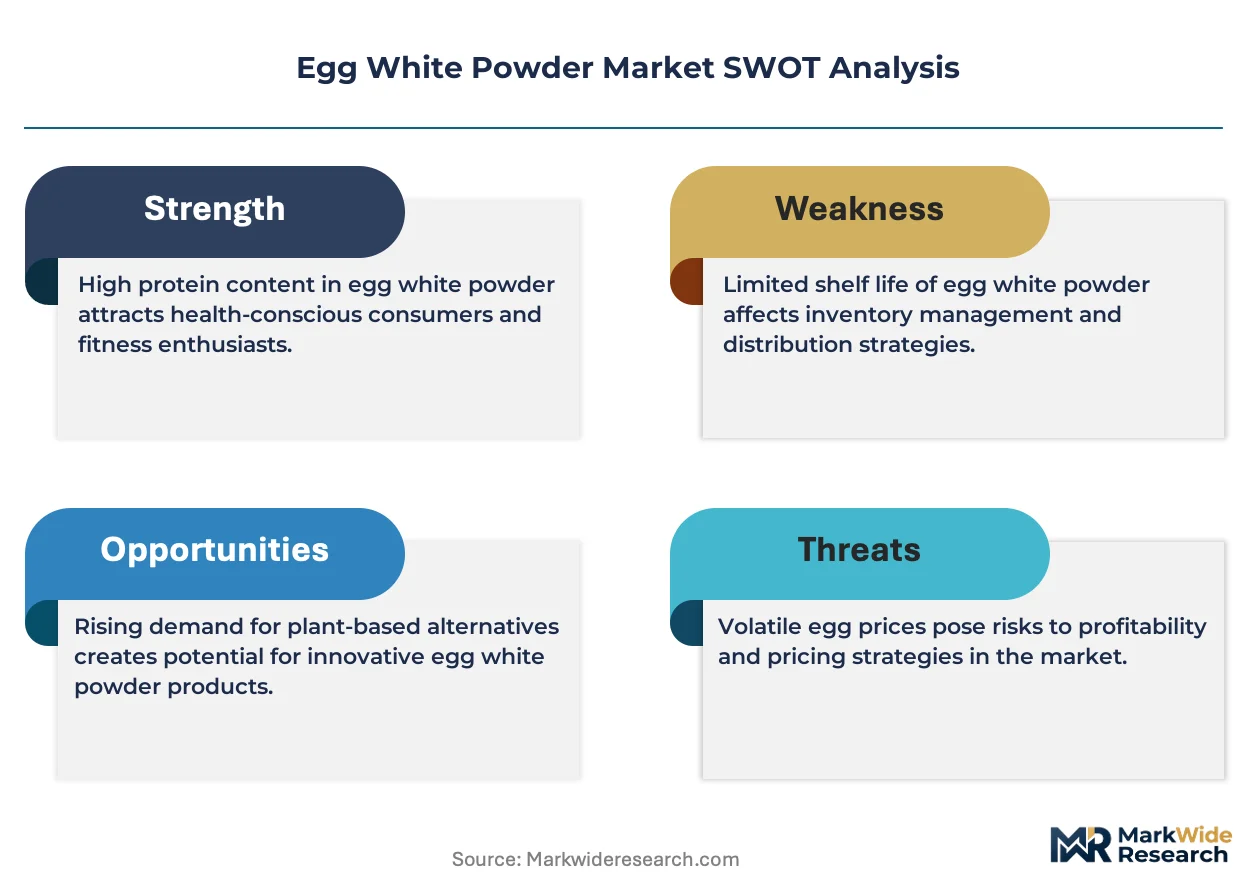
- Feed Cost Volatility:Soybean and corn price swings in the US Midwest directly compress margins for integrated egg processors dependent on captive poultry operations.
- Supply Concentration Risk:Dutch backward-integrated producers control critical foaming-grade capacity, creating single-source vulnerability for European confectionery formulators.
- Plant Protein Substitution:Pea and fava protein isolates are capturing share in vegan bakery applications where functional whipping can be partially replicated.
Strategic Opportunities
- Japanese Functional Foods:METI-supported longevity research is opening formulation demand for gelling-grade egg white powder in senior nutrition products.
- E-Commerce Sachet Channels:Direct-to-consumer platforms are enabling micro-batch penetration among home bakers and independent restaurants previously locked out of bulk purchasing.
- Renewable Thermal Integration:Biogas and solar-thermal spray-drying pilots in Denmark offer first-mover positioning for zero-carbon albumen certification.
Industry Challenges
- Spray-Drying Engineering Talent:Specialized knowledge of low-temperature albumen dehydration is concentrating among retiring European technicians, constraining plant expansion timelines.
- Allergen Line Segregation:FDA and EFSA labeling convergence is requiring dedicated production infrastructure or costly cleaning validation for clean-label supply chain access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg White Powder Market |
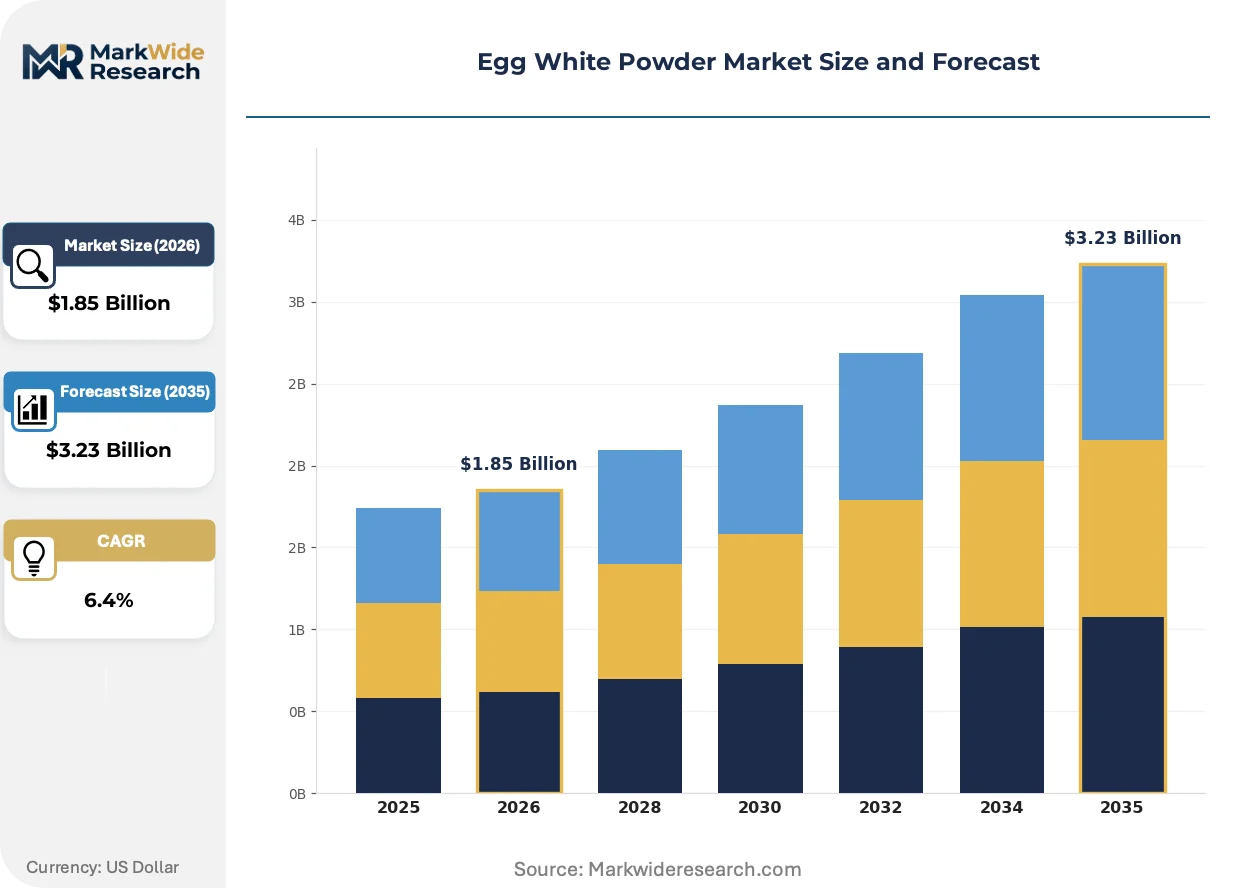
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foamed, Dried, Liquid, Instant Application: Baking, Protein Supplements, Confectionery, Sauces End User: Food Manufacturers, Fitness Centers, Restaurants, Home Cooks Packaging Type: Bulk Bags, Sachets, Canisters, Tubs |
| Companies Covered | Kewpie Corp., Bouwhuis Enthoven BV, Adriaan Goede BV, Eierhandel Wulro B.V., Interovo Egg Group BV, Ovostar Union N.V., Rembrandt Enterprises, Inc., Oskaloosa Food Products Corp., Rose Acre Farms, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg White Powder Market Emerging Trajectories
Energy recovery systems and precision dehydration controls are redefining process economics, while regulatory carbon accounting and shifting procurement priorities reshape competitive positioning across the value chain.
Membrane filtration pre-concentration is supplanting traditional evaporation stages in premium-grade production, cutting thermal load by thirty to forty percent before spray-drying. Japanese confectionery houses are piloting this configuration for delicate gelling properties. The technology is compressing energy intensity benchmarks and widening the margin gap between commodity and specialty processors.
The EU CSRD's scope-three emissions disclosure requirements are mandating granular carbon accounting across ingredient supply chains. Egg white powder importers into Europe must now document farm-level feed emissions and drying energy sources. German bakery ingredient distributors are screening suppliers on renewable thermal percentages, favoring biogas-integrated Dutch operations.
Direct procurement from spray-drying specialists is displacing traditional trader intermediation among mid-scale protein supplement brands. These buyers are negotiating specifications for solubility and microbial load directly with Japanese and Dutch producers, bypassing commodity aggregators. The shift is most visible in North American sports nutrition, where brands are building captive supplier relationships to secure traceability for influencer marketing claims.
Egg White Powder Market Segmentation
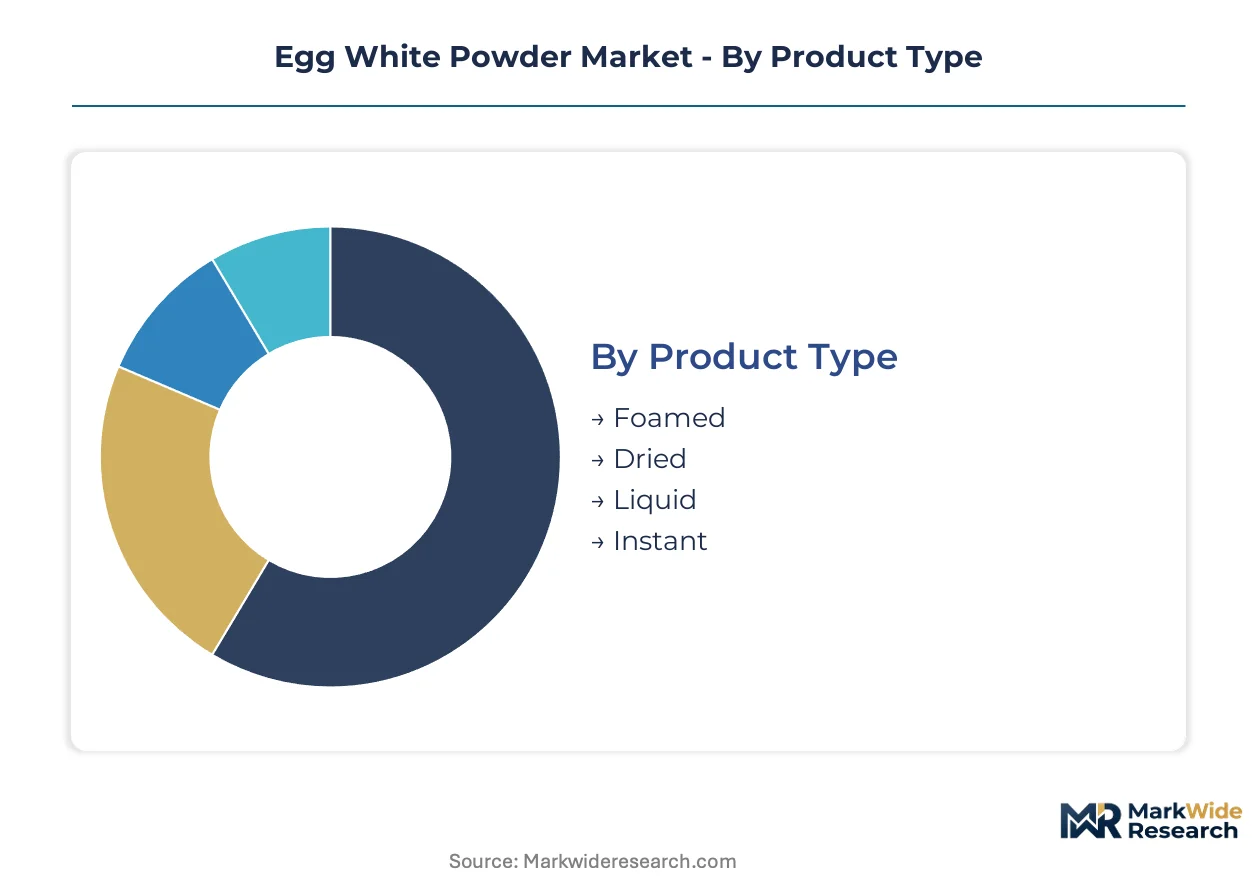
Segmentation in egg white powder manufacturing tracks how functional specifications align with distinct procurement economics across industrial and consumer channels. Each dimension reveals divergent margin structures and technical barriers that determine supplier selection and pricing power.
Product Type:
Foamed and instant grades command the deepest margin pools due to their specialized dehydration protocols and premium positioning in performance nutrition and confectionery.
- Foamed:Produced through controlled whipping and low-temperature dehydration, this grade retains stable aeration properties critical for sponge cake and meringue volume. German industrial bakeries specify foamed powder for continuous bread lines where hydration consistency determines yield.
- Instant:Agglomerated particles engineered for rapid cold-water dispersion without mechanical shear. North American sports nutrition brands are standardizing instant grades for ready-to-mix protein formats targeting lactose-intolerant consumers.
- Dried:Standard pan-dried or spray-dried albumen with basic solubility characteristics serves commodity baking applications where cost minimization outweighs functional precision.
- Liquid:Pasteurized liquid egg white concentrate requires refrigerated distribution and offers extended functionality for sauce emulsification in foodservice operations.
Foamed powder holds installed capacity in European confectionery supply chains. Instant is rotating up the share rankings through direct-to-consumer protein brand procurement.
Application:
Volume concentration sits with baking, while value extraction concentrates in protein supplements where formulation premiums justify specialized sourcing.
- Baking:Industrial bread and pastry production consumes the largest tonnage, with German manufacturers specifying high-foaming grades for automated mixing systems that demand predictable hydration kinetics.
- Protein Supplements:Clean-label sports nutrition brands in the Netherlands and Germany are displacing whey with egg white powder in lactose-free muscle recovery products, capturing formulation premiums.
- Confectionery:Japanese chocolate and candy houses source gelling-grade powder for aerated fillings and nougat structures where heat stability determines texture outcomes.
- Sauces:Mayonnaise and hollandaise manufacturers leverage egg white powder for emulsion stability in shelf-stable retail and foodservice formats.
Baking dominates absolute volume throughput. Protein supplements are climbing the fastest on per-kilogram value realization.
End User:
Procurement scale and specification intensity separate food manufacturers from fragmented downstream channels with diverging technical requirements.
- Food Manufacturers:Continuous production lines for bread, confectionery, and processed foods demand bulk supply contracts with validated microbial specifications and lot traceability for EFSA compliance.
- Restaurants:Independent and chain foodservice operators source mid-volume formats for sauce consistency and dessert preparation where labor reduction justifies powder over shell eggs.
- Fitness Centers:Gyms and CrossFit affiliates retail branded protein supplements to members, sourcing sachet formats through distributor networks rather than direct manufacturer relationships.
- Home Cooks:E-commerce platforms are unlocking micro-batch access for amateur bakers and health-conscious consumers previously excluded from industrial minimum order quantities.
Food manufacturers anchor long-term supply agreements. Home cooks are expanding most quickly through digital channel penetration.
Packaging Type:
Format economics separate industrial efficiency from consumer convenience, with bulk and sachet formats capturing opposite ends of the value chain.
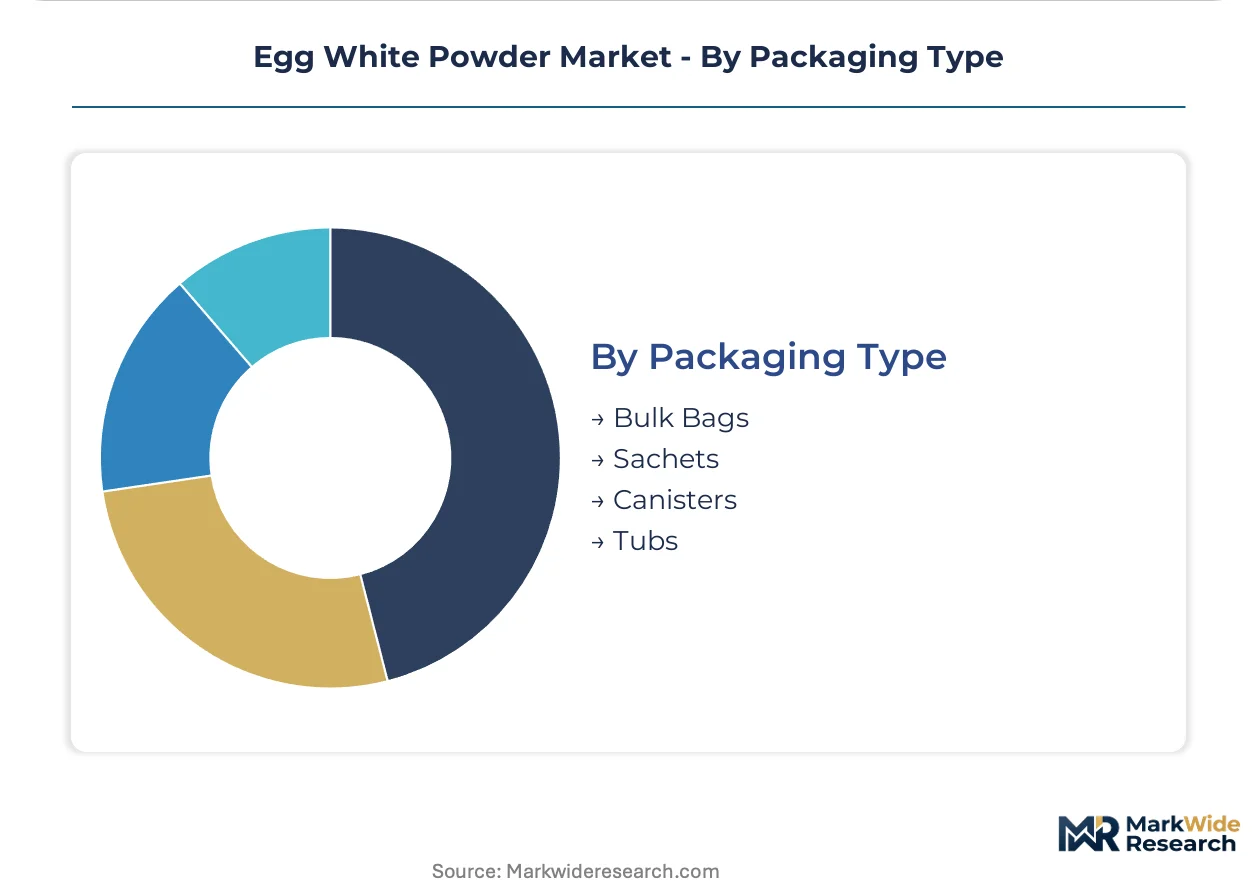
- Bulk Bags:25-kilogram multi-wall paper or polyethylene sacks serve continuous manufacturing lines where pneumatic handling systems minimize labor and contamination risk.
- Sachets:Single-serve foil pouches target fitness consumers and home bakers through Amazon and specialty retailer channels, enabling trial and portability.
- Canisters:Rigid plastic containers with resealable lids serve high-frequency home bakers and small restaurants prioritizing shelf stability and measured dispensing.
- Tubs:Large-format polyethylene tubs support mid-scale foodservice operations and institutional kitchens with moderate throughput and storage capacity.
Bulk bags retain manufacturing supply dominance. Sachets are gaining share fastest through influencer-marketed direct-to-consumer protein brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Dutch and Japanese producers commanding premium foaming-grade premiums, while Midwest US suppliers compete on throughput scale. German bakery manufacturers absorb the highest landed costs in Europe due to specification intensity and renewable energy compliance.
United States
Midwest integrated poultry operations supply bulk instant-grade powder to North American sports nutrition brands seeking lactose-free protein alternatives. FDA Egg Products Inspection Act enforcement shapes cold-chain documentation requirements for cross-state distribution. Iowa and Minnesota production clusters anchor Rembrandt Enterprises' scale-driven supply base for continuous manufacturing lines.
Germany
Industrial bread and pastry automation drives specification-intensive demand for high-foaming powders with validated hydration kinetics. EU Green Deal decarbonization mandates pressure spray-drying operators to document renewable thermal percentages in supplier audits. Bavarian confectionery houses source gelling-grade material through Dutch backward-integrated channels, accepting premium pricing for lot traceability compliance.
Netherlands
Backward integration into captive egg farming secures critical foaming-grade capacity for European confectionery and bakery supply chains. EFSA nutrition and health claims regulation determines permissible protein supplement labeling for export formulations. Gelderland province hosts Bouwhuis Enthoven's integrated operations, where biogas-integrated drying pilots target zero-carbon albumen certification.
Japan
METI-supported longevity research opens formulation demand for gelling-grade powder in senior nutrition and functional food applications. Confectionery houses pilot membrane filtration pre-concentration configurations to preserve delicate heat-sensitive properties. Kanto region production clusters around Kewpie Corp.'s poultry-to-powder integration, sustaining premium-grade output for domestic and export markets.
China
Domestic bakery chain expansion absorbs commodity-grade dried albumen for cost-sensitive sponge cake and bread production. National food safety standards under SAMR jurisdiction govern pasteurization and microbial load specifications for industrial ingredient distribution. Shandong province poultry processing agglomerations supply regional baking conglomerates with basic solubility grades for automated mixing systems.
Egg White Powder Market Vendor Landscape
Concentration sits with backward-integrated European and Japanese operators controlling premium foaming-grade capacity, while North American players compete on throughput scale in commodity instant segments. The vendor base separates into three strategic archetypes: integrated poultry-to-powder specialists, standalone spray-drying processors, and commodity egg product traders. Dominant competitive moves include renewable thermal equipment upgrades to satisfy EU carbon accounting requirements and direct procurement relationships displacing traditional trader intermediation among mid-scale protein supplement brands.
Among Dutch integrated operators, Bouwhuis Enthoven BV and Adriaan Goede BV exemplify the backward-integrated archetype with captive egg farming securing supply chain control. Japanese specialists Kewpie Corp. occupy a parallel position in Asian markets through poultry-to-powder integration. At the North American scale-driven end, Rembrandt Enterprises, Inc. represents commodity-grade throughput competition from Midwest production bases.
| Leading Market Players |
|---|
| Kewpie Corp. |
| Bouwhuis Enthoven BV |
| Adriaan Goede BV |
| Eierhandel Wulro B.V. |
| Interovo Egg Group BV |
| Ovostar Union N.V. |
| Rembrandt Enterprises, Inc. |
| Oskaloosa Food Products Corp. |
| Rose Acre Farms, Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Dutch integrated producers and German bakery ingredient distributors lock in multi-year supply access while capping price volatility exposure for both parties. These arrangements tether procurement economics to renewable thermal compliance thresholds under EU Green Deal audits, embedding carbon accounting into contract valuation.
Pricing Analysis
Configured-to-order pricing for gelling-grade foamed powder commands spreads over standard instant grades due to specialized low-temperature dehydration protocols and validated lot traceability. Three-tier pricing structure across premium foaming, standard instant, and economy dried levels stratifies by functional performance and certification grade. Pricing pressure stems from soybean and corn feed cost volatility compressing margins for Midwest US integrated operators. Small-batch home cooks through e-commerce sachet channels exhibit highest price sensitivity, while Japanese confectionery houses demonstrate lowest sensitivity due to formulation lock-in requirements.
Supply Chain Analysis
Container availability constraints on Rotterdam-Hamburg trade lanes elevate inbound logistics costs for German manufacturers dependent on Dutch foaming-grade supply. Production concentrates in the Netherlands, Japan, and the US Midwest, with each hub serving distinct specification tiers. Feed grain inputs, pasteurization equipment, and spray-drying energy supply constitute critical upstream dependencies. Single-source vulnerability around Dutch backward-integrated foaming capacity represents the dominant structural risk. Distribution runs through bulk bag direct procurement for food manufacturers and sachet-format e-commerce platforms for consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through EFSA nutrition claims and FDA Egg Products Inspection Act compliance creates durable barriers to unvalidated entrants.
For Market Incumbents: Secure renewable thermal certification for spray-drying operations to maintain access to German bakery distributor procurement audits under EU Green Deal mandates. Deepen upstream control over captive egg farming to insulate margin structures from feed grain price swings threatening Midwest competitors. For New Entrants and Emerging Players: Differentiate on zero-carbon albumen certification through biogas-integrated drying pilots targeting Dutch and Danish sustainability procurement criteria. Penetrate the North American sports nutrition sachet segment where direct-to-consumer brands bypass established trader intermediation and prioritize traceability claims for influencer marketing. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated specialists with validated foaming-grade capacity and renewable thermal infrastructure already operational. The five-to-ten year viability window favors operators with EU F-Gas Regulation-compliant cold-chain systems and EFSA labeling entrenchment. Watch for feed cost volatility spikes as inflection indicators compressing commodity-grade processor margins and triggering consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Thermal Integration | Biogas spray-drying pilots in Gelderland position Dutch operators for zero-carbon certification under EU CSRD scope-three disclosure. |
| Membrane Filtration Pre-Concentration | Japanese confectionery houses cut thermal load by thirty to forty percent before dehydration, widening specialty processor margins. |
| Direct Procurement Relationship Building | North American sports nutrition brands bypass commodity aggregators to negotiate solubility specifications directly with spray-drying specialists. |
| Allergen Line Segregation Investment | Dedicated production infrastructure satisfies FDA and EFSA labeling convergence requirements for clean-label supply chain access. |
| E-Commerce Sachet Channel Expansion | Amazon and specialty retailer platforms unlock micro-batch penetration among home bakers previously excluded from industrial minimums. |
Methodological Framework
A spread of perspectives from spray-drying plant managers, bakery procurement leads at German industrial manufacturers, sports nutrition brand formulators, and Dutch egg farming operators converged on the working assumptions driving supply and demand modeling. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of integrated poultry processors, EFSA nutrition claims registers, and EU F-Gas Regulation implementation reports. Bottom-up capacity assessments across Netherlands, Japan, and US Midwest production clusters triangulated against top-down demand decomposition by application segment.
Segmentation dimensions modeled include product type tier, application intensity, end-user procurement scale, and packaging format economics across the projection horizon. CAGRs were derived from iterative reconciliation of volume throughput estimates with value realization by specification grade. Forecast inputs incorporated EU Green Deal decarbonization compliance timelines and METI-supported functional food research trajectories in Japanese senior nutrition markets.
Material uncertainties — feed grain price volatility, regulatory refrigerant phase-down acceleration, and plant protein substitution rates in vegan bakery applications — sit outside the modeled envelope. Forecasts reflect documented assumptions about renewable thermal adoption curves and allergen labeling mandate harmonization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Refined Coconut Oil Market
Ingredients
Pork Skin Gelatin Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Peanut Flour Market
Ingredients
Yeast Flakes Market
Ingredients
Fruit Powder Market
Ingredients
Hops Derivative Market
Ingredients
Cocoa Solids Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Passion Fruit Powder Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Tuberose Extract Market
Ingredients
Egg Replacement Ingredients Market
Ingredients
Casein Hydrolysate Market