
 Drum to Hopper Blends Premix Market | 2026-2036
Drum to Hopper Blends Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Drum to Hopper Blends Premix Market Foresight
REACH compliance for chemical handling and worker exposure limits is realigning the cost-of-entry calculus for European drum-to-hopper premix suppliers. Glanbia Plc leverages its dairy-derived nutrient premix infrastructure to compete in pharmaceutical-grade powder blending. BASF SE anchors its position through captive production of excipient-grade custom formulations. Koninklijke DSM N.V. differentiates via precision micronutrient premixes engineered for continuous manufacturing lines.
Drum to hopper blends premix denotes a pre-weighed, homogeneous mixture of active and inactive ingredients transferred from sealed drums directly into processing hoppers, typically achieving particle size distributions below 250 microns and moisture content under 5 percent to prevent caking during pneumatic conveyance. Powder blends dominate current volume due to their compatibility with high-shear granulation and direct compression tableting, while liquid blends are gaining share in parenteral and liquid-dose applications where solubility enhancement drives formulation value. Custom formulations command the widest margin pools as pharmaceutical clients outsource complex multi-component premix development to specialized toll manufacturers.
FDA CGMP enforcement for pharmaceutical intermediates and EMA's updated excipient risk assessment guidelines are tightening traceability requirements for drum-to-hopper transfer protocols, compelling manufacturers to validate contamination control strategies. BIS certification for food-grade premix imports into India and China's NMPA registration pathways for imported drug master files add layered compliance costs for cross-border suppliers. Stakeholders must monitor evolving pharmacopeial standards for blend uniformity testing, as USP Chapter <905> revisions could redefine acceptance criteria for hopper-fed batch consistency.
Market Dynamics
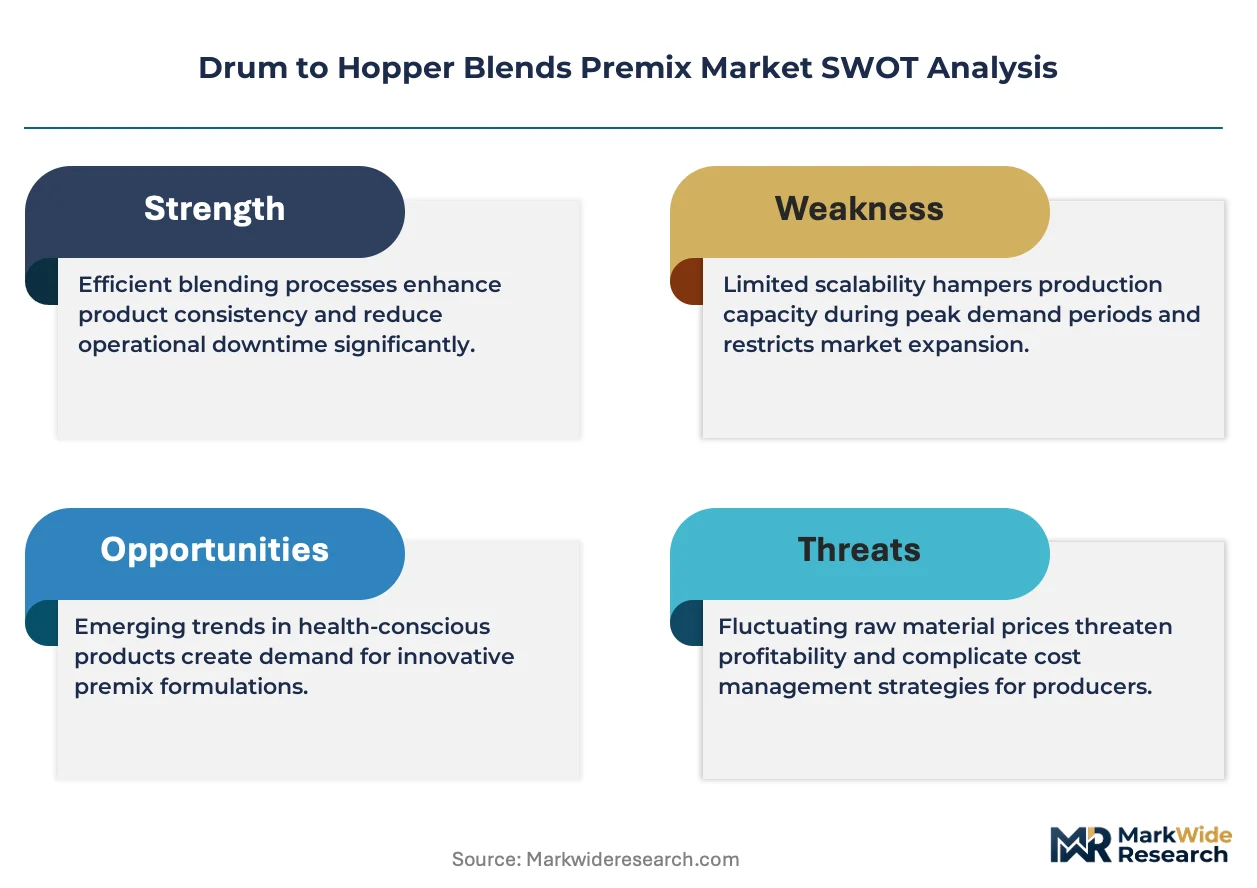
Continuous manufacturing adoption in pharmaceutical production is compressing batch cycle times and forcing drum-to-hopper premix suppliers to engineer real-time release testing compatibility into every formulation.
Growth Catalysts
- FDA CGMP Intermediate Guidelines:Updated enforcement protocols for pharmaceutical powder handling are mandating sealed drum-to-hopper transfer validation, expanding specialized premix demand among contract manufacturers.
- High-Shear Granulation Expansion:Solid-dose formulators are retrofitting direct compression lines with hopper-fed premix stations to eliminate intermediate weighing steps and reduce cross-contamination risk.
- German CMO Retrofitting Wave:Contract manufacturing organizations in Baden-Württemberg and Bavaria are converting batch blending suites to continuous hopper-fed architectures, creating localized demand concentration for validated premix supply.
Market Restraints
- Excipient Grade Volatility:Pharmaceutical-grade lactose and microcrystalline cellulose spot prices fluctuate with dairy commodity cycles, compressing premix margin predictability for toll manufacturers.
- Specialized Blender Capacity Concentration:GMP-validated drum-to-hopper processing equipment is concentrated among a handful of European and North American OEMs, extending lead times for capacity expansion.
- Substitution by In-House Blending:Vertically integrated pharmaceutical majors with captive micronization capabilities are internalizing simple binary premix production, narrowing the addressable market for external suppliers.
Strategic Opportunities
- Indian BIS Certification Pathway:Food-grade premix suppliers achieving Bureau of Indian Standards certification for pharmaceutical-grade conversion can access contract manufacturing demand from Mumbai and Hyderabad formulation clusters.
- Continuous Manufacturing Convergence:Integration of real-time particle sizing with hopper-fed premix delivery is unifying blend uniformity assurance with process analytical technology deployment.
- Parenteral Liquid Blends:Solubility-enhanced liquid premix formulations for injectable doses represent an underdeveloped category with higher technical barriers and pricing power than standard powder blends.
Industry Challenges
- Process Analytical Technology Integration:Embedding PAT sensors into drum-to-hopper transfer lines requires specialized automation engineering talent that remains scarce in traditional blending operations.
- Multi-Pharmacopeial Validation:Simultaneous compliance with USP, EP, and JP blend uniformity testing protocols extends qualification timelines for international premix suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drum to Hopper Blends Premix Market |
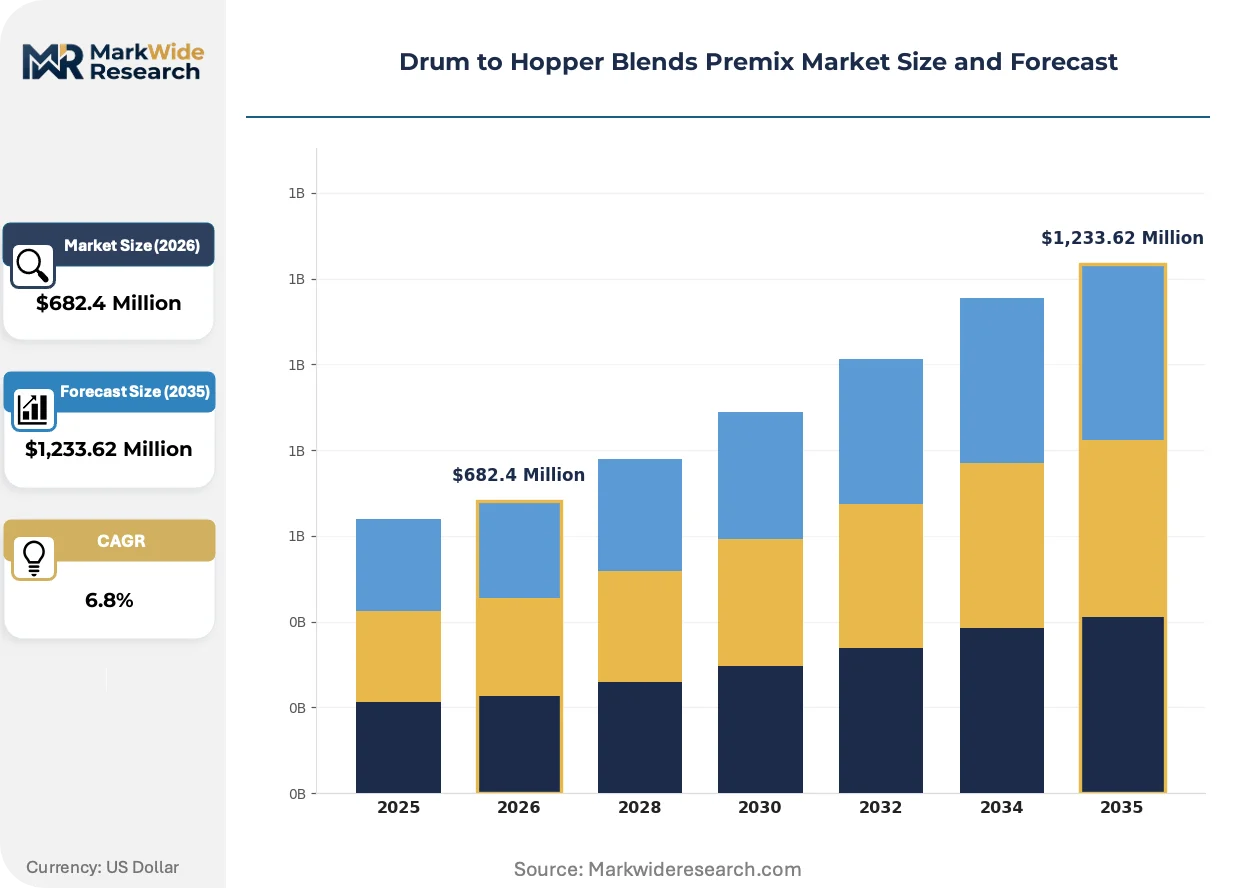
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,233.62 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder Blends, Liquid Blends, Granular Blends, Custom Formulations Application: Food Processing, Pharmaceutical Manufacturing, Nutraceuticals, Personal Care Products End User: Manufacturers, Distributors, Retailers, Wholesalers Packaging Type: Bulk Bags, Containers, Drums, Pails |
| Companies Covered | Jubilant Life Sciences, Prinova Group LLC, Glanbia Plc, Barentz International, Watson Inc., Archer Daniels Midland Company, BASF SE, Cargill, Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drum to Hopper Blends Premix Market Shifts & Advancements
Real-time release testing and continuous processing architectures are converging to redefine drum-to-hopper premix specifications, with particle engineering and digital traceability emerging as the primary vectors of competitive differentiation.
Near-infrared spectroscopy integrated into hopper feed systems is unifying blend uniformity verification with transfer operations, eliminating offline sampling delays. Solid-dose manufacturers in the United States are deploying these systems at pilot scale ahead of commercial line retrofits. This convergence is compressing batch release timelines from days to hours while raising the technical floor for premix supplier qualification.
REACH chemical safety dossier requirements for powder handling intermediates are tightening worker exposure documentation across European drum-to-hopper operations. The regulation is compelling manufacturers to invest in contained transfer technologies and occupational exposure banding studies. German and Swiss toll manufacturers are responding fastest, using compliance as a competitive filter against lower-cost non-European suppliers.
Buyers are consolidating premix procurement under single-source technical service agreements rather than multi-vendor spot purchasing. Large pharmaceutical formulators in North America are awarding three-to-five-year exclusive supply contracts to premix partners willing to co-locate technical staff at manufacturing sites. This shift is most visible among oncology and high-potency product manufacturers where contamination control documentation carries the highest regulatory weight.
Drum to Hopper Blends Premix Market Segmentation
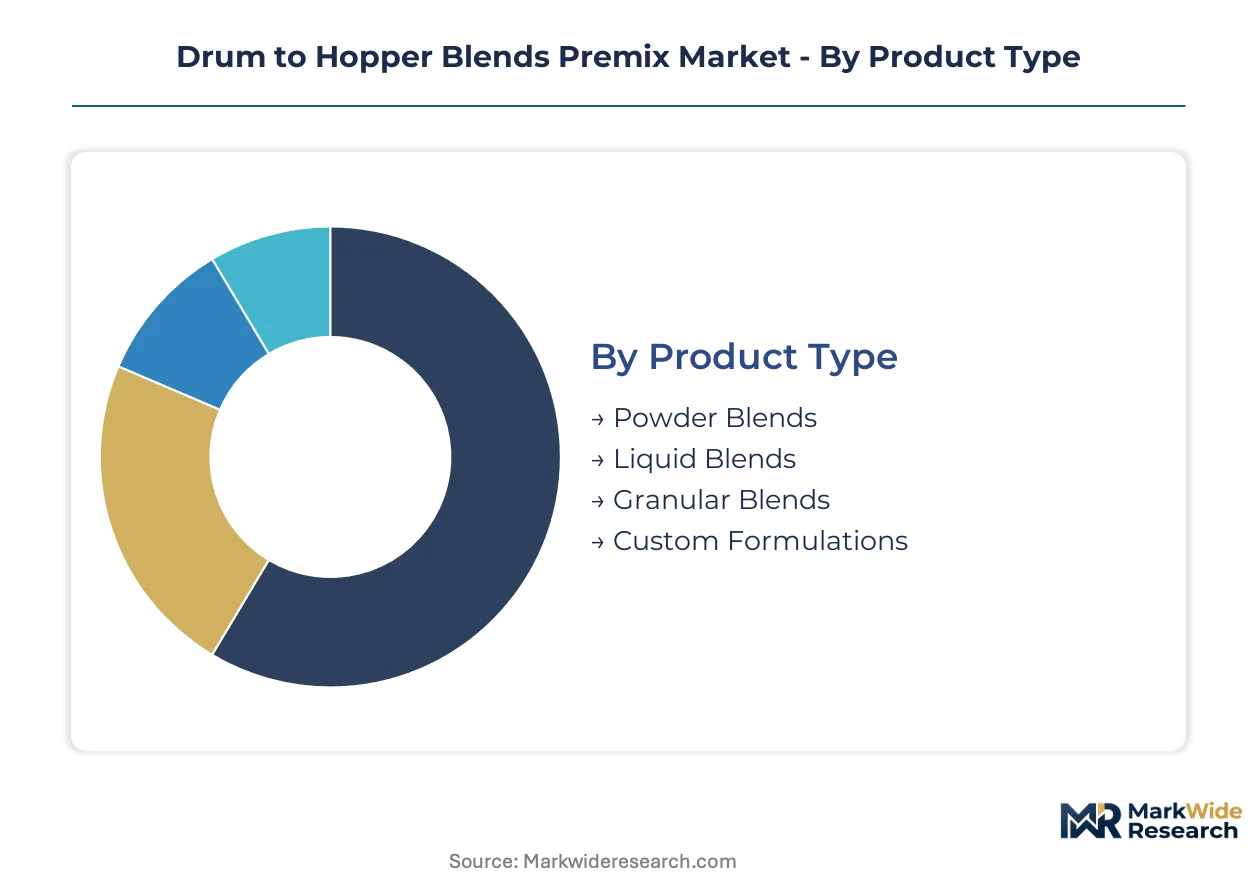
Segmentation in drum-to-hopper premix markets reveals where capital deployment concentrates and which technical specifications command premium positioning. Manufacturers allocate blending infrastructure based on particle engineering requirements and regulatory validation tiers.
Product Type:
Powder Blends demand the heaviest capital commitment due to micronization equipment, containment suites, and GMP-validated cleanroom infrastructure required for sub-250-micron specifications.
- Powder Blends:Homogeneous mixtures of active and inactive ingredients with particle size distributions below 250 microns and moisture content under 5 percent. Pharmaceutical manufacturers in Germany are retrofitting high-shear granulation lines with hopper-fed powder premix stations to eliminate intermediate weighing steps and reduce cross-contamination exposure.
- Custom Formulations:Client-specific multi-component premixes developed through toll manufacturing partnerships with specialized technical service agreements. North American oncology formulators are consolidating procurement under single-source contracts requiring co-located technical staff and real-time release testing compatibility.
- Liquid Blends:Solubility-enhanced formulations for parenteral and liquid-dose applications where injectable specifications drive technical barriers.
- Granular Blends:Intermediate particle-size mixtures bridging powder flowability and liquid handling requirements in select solid-dose applications.
Powder Blends absorb the bulk of installed capacity; Custom Formulations is expanding most quickly.
Application:
Application segmentation tracks where formulation complexity and regulatory burden intersect, with pharmaceutical-grade validation representing the highest cost tier.
- Pharmaceutical Manufacturing:CGMP-compliant premix supply for solid-dose, parenteral, and biologic applications requiring validated contamination control and batch documentation. FDA enforcement for pharmaceutical intermediates is mandating sealed drum-to-hopper transfer protocols, expanding specialized premix demand among contract manufacturers in Baden-Württemberg and Bavaria.
- Food Processing:Nutrient fortification premixes for dairy, bakery, and beverage applications with FSSAI and BIS certification pathways. Indian food-grade premix suppliers achieving Bureau of Indian Standards certification for pharmaceutical-grade conversion are accessing contract manufacturing demand from Mumbai and Hyderabad formulation clusters.
- Nutraceuticals:Dietary supplement premixes bridging food-grade and pharmaceutical-grade specifications with evolving USP and EP compliance requirements.
- Personal Care Products:Cosmetic and topical formulation premixes with lower regulatory barriers but specialized stability and sensory requirements.
Pharmaceutical Manufacturing commands the steepest expansion trajectory; Food Processing holds the broadest installed base.
End User:
End-user structure reflects supply chain position and technical service intensity, with direct manufacturers capturing the most value-added relationships.
- Manufacturers:Formulation companies integrating premix directly into finished product lines with validated drum-to-hopper transfer systems. Large pharmaceutical formulators in the United States are awarding three-to-five-year exclusive supply contracts to premix partners willing to embed process analytical technology into transfer operations.
- Distributors:Technical intermediaries managing inventory and logistics for multi-site manufacturing networks with regional compliance expertise.
- Wholesalers:Volume-focused intermediaries serving commodity-grade premix segments with standardized specifications.
- Retailers:End-channel suppliers for small-scale or specialty premix requirements with limited technical service components.
Manufacturers absorb the bulk of installed capacity; Distributors are climbing the fastest as procurement consolidates under technical service agreements.
Packaging Type:
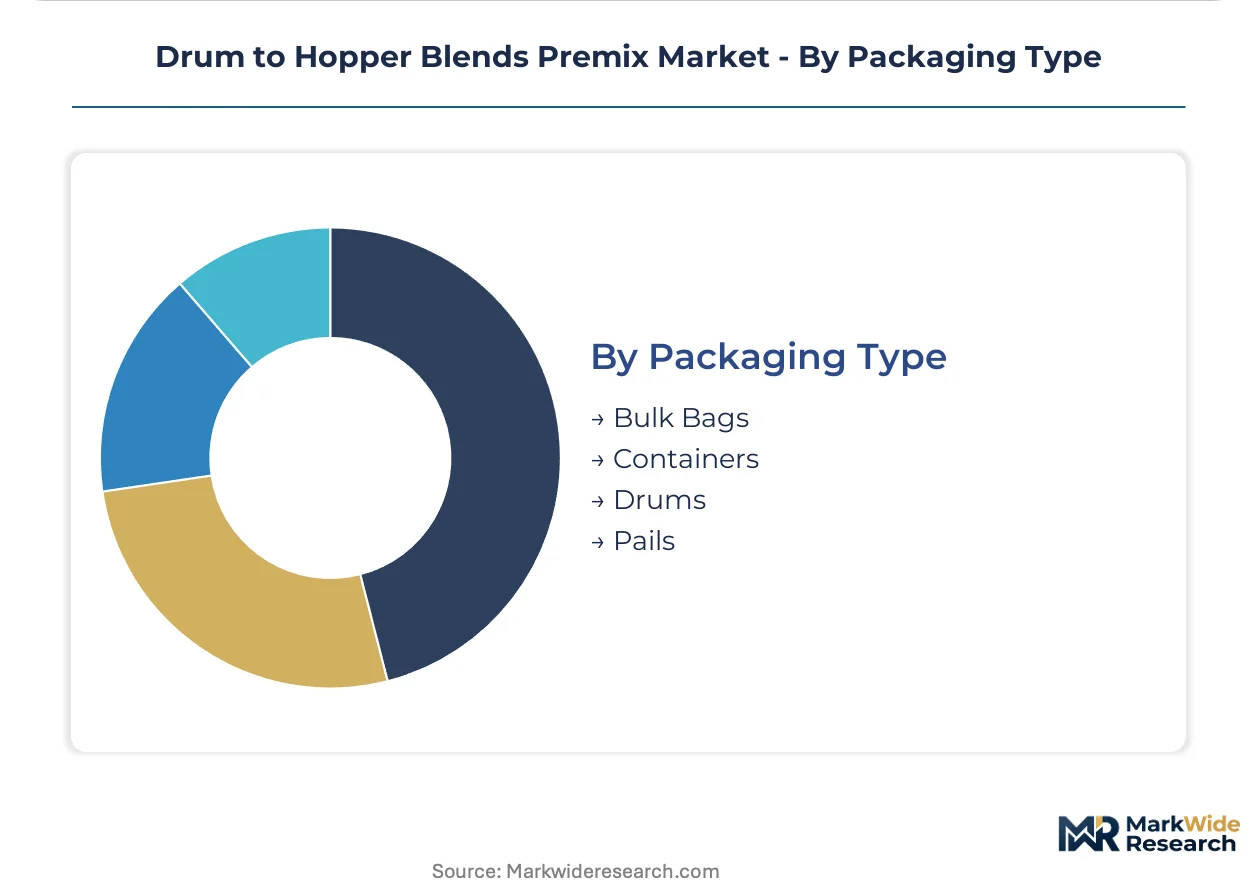
Packaging segmentation aligns with transfer automation requirements and contamination control tiers, with sealed drum systems representing the highest capital investment.
- Drums:Sealed steel or fiber containers enabling validated drum-to-hopper transfer with integrated containment and pneumatic conveyance compatibility. REACH chemical safety dossier requirements are compelling European manufacturers to invest in contained drum transfer technologies and occupational exposure banding studies.
- Bulk Bags:Flexible intermediate bulk containers for high-volume powder handling with reduced per-unit packaging costs.
- Containers:Rigid intermediate packaging for liquid and semi-solid premix formulations with specialized liner systems.
- Pails:Small-volume rigid packaging for specialty formulations and pilot-scale manufacturing requirements.
Drums absorb the bulk of installed capacity; Bulk Bags are gaining share fastest in high-volume food and nutraceutical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Maharashtra and Telangana concentrate pharmaceutical premix demand through tax incentives for contract manufacturing. These zones attract drum-to-hopper premix suppliers seeking proximity to formulation clusters.
United States
Oncology and high-potency drug manufacturers in Massachusetts and New Jersey drive specialized premix demand for contamination-controlled transfer systems. FDA CGMP enforcement for pharmaceutical intermediates mandates sealed drum-to-hopper validation protocols. Boston-Cambridge biotech corridor companies are retrofitting continuous manufacturing lines with real-time release testing compatibility.
Germany
Contract manufacturing organizations in Baden-Württemberg and Bavaria retrofit hopper-fed blending suites for solid-dose formulations. REACH chemical safety dossier requirements tighten worker exposure documentation for powder handling operations. Heidelberg and Mannheim formulation clusters source validated premix supply from regional toll manufacturers with contained transfer technologies.
India
Food-grade premix suppliers in Mumbai and Hyderabad pursue pharmaceutical-grade conversion through Bureau of Indian Standards certification. FSSAI and CDSCO dual compliance pathways add layered regulatory costs for cross-border suppliers. Maharashtra pharmaceutical zones and Telangana life sciences clusters generate concentrated demand for drum-to-hopper premix infrastructure.
Switzerland
Precision micronutrient premix engineering serves continuous manufacturing lines for high-value solid-dose applications. Swissmedic pharmacopeial standards align with EMA excipient risk assessment guidelines for traceability documentation. Basel and Zurich pharmaceutical manufacturing networks validate contamination control strategies for hopper-fed batch consistency.
China
NMPA registration pathways for imported drug master files structure market entry for foreign premix suppliers. Yangtze River Delta formulation clusters expand drum-to-hopper adoption to streamline active ingredient batching. Shanghai and Suzhou pharmaceutical manufacturers integrate pneumatic conveyance systems with sub-250-micron particle specifications.
Drum to Hopper Blends Premix Market Competitive Landscape
European producers anchor one tier through REACH-compliant contained transfer technologies; North American specialists hold another through FDA-validated real-time release testing integration. The market structures around three tiers: multinational excipient suppliers with captive formulation capabilities, toll manufacturers with GMP-validated blending infrastructure, and regional nutrient premix converters. Consolidation pressure concentrates among contract manufacturing segments where technical service intensity determines procurement decisions. Strategic moves center on co-location agreements with pharmaceutical formulators and backward integration into micronization capacity.
Within the multinational tier, BASF SE and Koninklijke DSM N.V. exemplify divergent positioning archetypes. BASF anchors through captive production of excipient-grade custom formulations leveraging integrated chemical manufacturing. DSM occupies a position emphasizing precision micronutrient premixes engineered for continuous manufacturing compatibility. Glanbia Plc represents the conversion archetype, repurposing dairy-derived nutrient premix infrastructure toward pharmaceutical-grade powder blending specifications. These three patterns illustrate how raw material origin and processing heritage shape competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Jubilant Life Sciences |
| Prinova Group LLC |
| Glanbia Plc |
| Barentz International |
| Watson Inc. |
| Archer Daniels Midland Company |
| BASF SE |
| Cargill |
| Koninklijke DSM N.V. |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade lactose and microcrystalline cellulose spot prices fluctuate with dairy commodity cycles, compressing premix margin predictability as these inputs flow through toll manufacturers into CGMP-validated pricing tiers for contract manufacturing organizations.
Pricing Analysis
Lead-time premiums for GMP-validated drum-to-hopper equipment compress pricing elasticity, with short-lead-time orders commanding substantial markups over standard inventory positions. Three-tier pricing structure across premium, standard, and economy levels separates validated continuous-manufacturing-compatible formulations from batch-grade powder blends and commodity nutrient premixes. Pricing pressure stems from excipient grade volatility as dairy commodity cycles destabilize input cost forecasting. Large pharmaceutical formulators in Massachusetts and New Jersey exhibit lowest price sensitivity due to contamination control documentation requirements, while Indian food-grade converters face acute margin compression from BIS certification compliance costs.
Supply Chain Analysis
Domestic-content mandates in India's Maharashtra and Telangana pharmaceutical zones reshape sourcing patterns, compelling foreign premix suppliers to establish local blending infrastructure or forfeit contract manufacturing awards. Supply concentrates in Germany, Switzerland, and the United States for GMP-validated drum-to-hopper processing equipment, with Baden-Württemberg and Bavaria hosting specialized toll manufacturers. Raw material dependencies center on pharmaceutical-grade lactose, microcrystalline cellulose, and precision micronutrients. Single-source vulnerability in European OEM equipment supply extends lead times for capacity expansion. Distribution runs through technical service agreements rather than spot purchasing, with three-to-five-year exclusive contracts dominating oncology and high-potency product procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around technical service intensity as FDA CGMP enforcement and REACH compliance costs force undercapitalized regional nutrient premix converters toward exit or acquisition.
For Market Incumbents: Cement market position through backward integration into captive micronization capacity in Germany and Switzerland, eliminating dependency on third-party particle engineering. Defend margin structure by co-locating technical staff at Boston-Cambridge and Heidelberg formulation clusters, converting procurement relationships into exclusive multi-year agreements before emerging toll manufacturers achieve GMP validation. Threat substitution by vertically integrated pharmaceutical majors with captive blending capabilities demands preemptive lock-in through real-time release testing compatibility investments. For New Entrants and Emerging Players: The price-point gap between premium continuous-manufacturing-compatible formulations and economy-grade food premixes creates entry space for mid-tier pharmaceutical-grade converters. Target Indian BIS certification pathways as the most penetrable regulatory entry point, leveraging Mumbai and Hyderabad formulation cluster demand for drum-to-hopper infrastructure. Solubility-enhanced liquid premix formulations for parenteral applications represent underserved white space with higher technical barriers and pricing power than commoditized powder blends. Go-to-market execution should emphasize PAT integration partnerships with regional contract manufacturing organizations. For Investors and Strategic Acquirers: Distressed-cycle entries favor GMP-validated toll manufacturers with contained transfer technologies in Baden-Württemberg and Bavaria, where REACH compliance investments have already been amortized. Long-term viability over the next decade rests on continuous manufacturing convergence and real-time release testing integration capabilities. Acquisition target archetype: mid-cap European toll manufacturers with validated hopper-fed blending lines and established pharmaceutical customer relationships. Signal to watch: FDA USP Chapter revisions redefining blend uniformity acceptance criteria, which would trigger replacement demand for non-compliant premix suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Micronization | Eliminates third-party particle engineering dependency for sub-250-micron specifications. |
| PAT Sensor Integration Partnership | Embeds process analytical technology into drum-to-hopper transfer lines for real-time release. |
| BIS Certification Conversion | Unlocks pharmaceutical-grade contract manufacturing demand from Mumbai and Hyderabad clusters. |
| Co-location Technical Service Agreements | Converts procurement relationships into exclusive multi-year supply contracts with oncology formulators. |
| Contained Transfer Technology Investment | Satisfies REACH worker exposure documentation requirements as competitive filter against non-European suppliers. |
Research Methodology
Multi-period observation of FDA enforcement patterns, EMA excipient risk assessment guideline revisions, and contract manufacturing organization retrofitting activity anchored the trend analysis, supplemented by interviews with pharmaceutical formulation executives, toll manufacturing operations directors, regulatory affairs specialists, and powder handling equipment OEM technical leads. Secondary validation drew from FDA CGMP guidance documents, ECHA REACH chemical safety dossiers, BIS certification pathway records, and USP pharmacopeial revision notices. Bottom-up segmentation modeling triangulated against top-down macro pharmaceutical production indicators.
Input-output matrix frameworks mapped premix demand across product type, application grade, end-user supply chain position, and packaging transfer automation requirements over the projection horizon. CAGRs derived from regression analysis against pharmaceutical continuous manufacturing adoption curves and contract manufacturing organization capacity expansion timelines. Forecast inputs incorporated excipient commodity price volatility indices and regulatory qualification timeline distributions for multi-pharmacopeial validation.
Inputs from primary stakeholder interviews and published regulatory guidance were available through the study window; gaps in real-time contract manufacturing procurement transaction data introduce uncertainty bands around near-term volume allocations. Forecasts reflect modeling assumptions regarding FDA CGMP enforcement intensity and REACH implementation consistency across European member states. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Cold-Pressed Citrus Seed Oil Ingredients Market
Ingredients
China Corn Glucose Market
Ingredients
Egg Membrane Powder Market
Ingredients
Cacao Bean Market
Ingredients
Centella Asiatica Extract Market
Ingredients
Icing Shortening Market
Ingredients
Egg Albumin Protein Market
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market
Ingredients
Peanut Ingredients Market
Ingredients
Philippines Edible Oils & Fats Market
Ingredients
North America Gluten Free Flour Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Pet Food Premix Market
Ingredients
Carob Powder Market