
 Global Dietary Fibers Market | 2026-2036
Global Dietary Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dietary Fibers Market Analysis
Synthetic hydrocolloid stabilizers is shifting toward soluble fiber alternatives in reduced-sugar beverage applications, compressing cost premiums for clean-label reformulations. Cargill, Incorporated leverages its corn wet-milling infrastructure to anchor supply of soluble fibers across North American beverage accounts. Tate & Lyle competes through specialty starch-fiber hybrid systems that sustain texture functionality in low-calorie products. BENEO GmbH specializes in chicory root-derived inulin and oligofructose, dominating European prebiotic fiber supply chains.
Dietary fibers encompass carbohydrate polymers with ten or more monomeric units that resist digestion in the human small intestine, typically delivering viscosity modification, bulking, or fermentability with caloric values below two kilocalories per gram. Their primary commercial purpose spans digestive health positioning, glycemic management, and satiety enhancement across packaged food and supplement formulations. Soluble fibers lead value capture due to premium pricing in beverage and dairy applications where transparency and mouthfeel control command margin pools. Functional fibers represent the fastest-growing product type as manufacturers engineer novel extraction processes from agricultural sidestreams to meet label-friendly demand. Prebiotic fibers concentrate growth in supplement applications where microbiome science drives consumer willingness to pay.
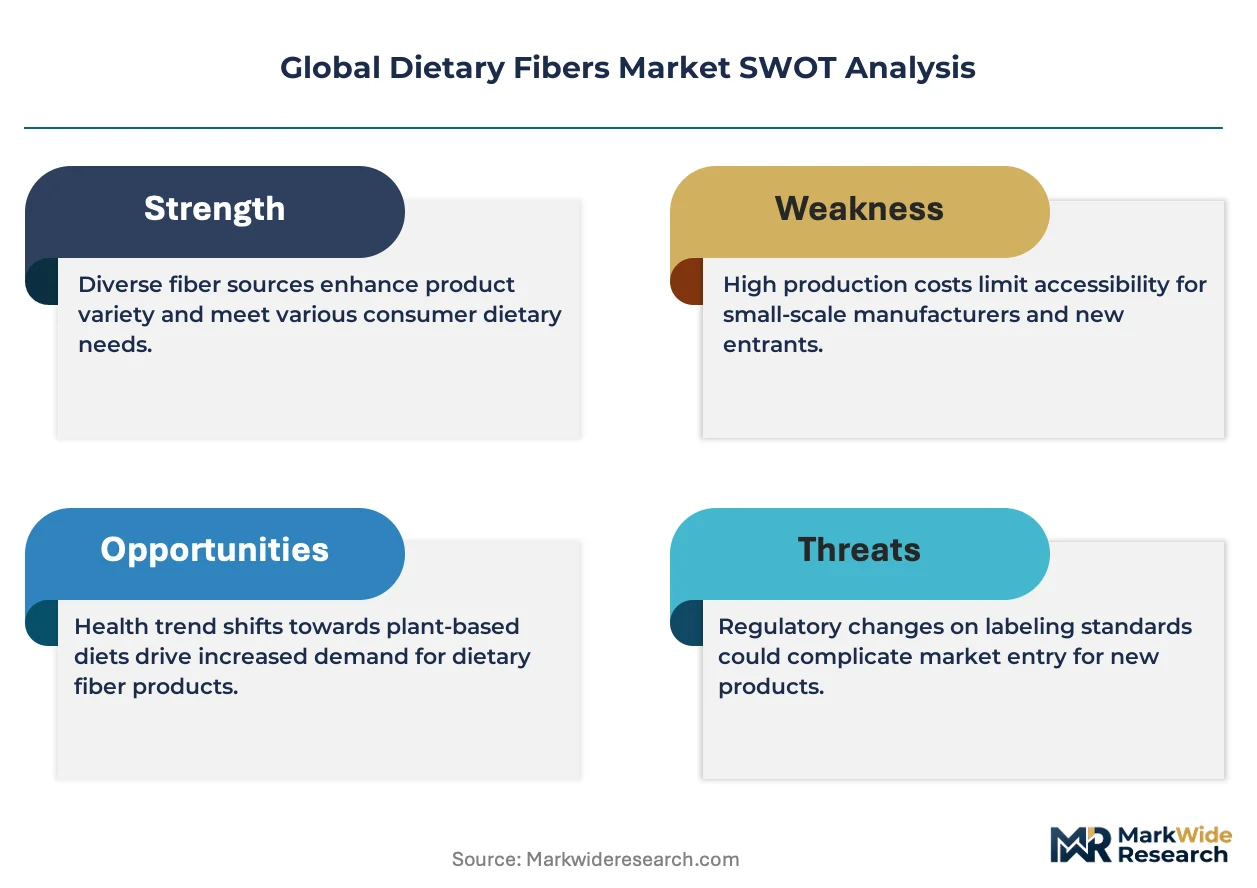
The FDA's updated definition of dietary fiber under Nutrition Facts labeling rules shapes which isolated and synthetic fibers qualify for declaration, directly affecting formulation decisions by U.S. manufacturers. EFSA's health claim authorization process under EU Regulation 1924/2006 creates a bifurcated market where substantiated prebiotic and bowel function claims unlock premium positioning in European retail channels. Japan's Foods with Function Claims system, administered by the Consumer Affairs Agency, offers an alternative regulatory pathway that Japanese and export-oriented suppliers monitor for claim architecture strategies. Stakeholders must decide whether to prioritize jurisdictions with stringent claim substantiation or pursue emerging markets with evolving fiber fortification standards.
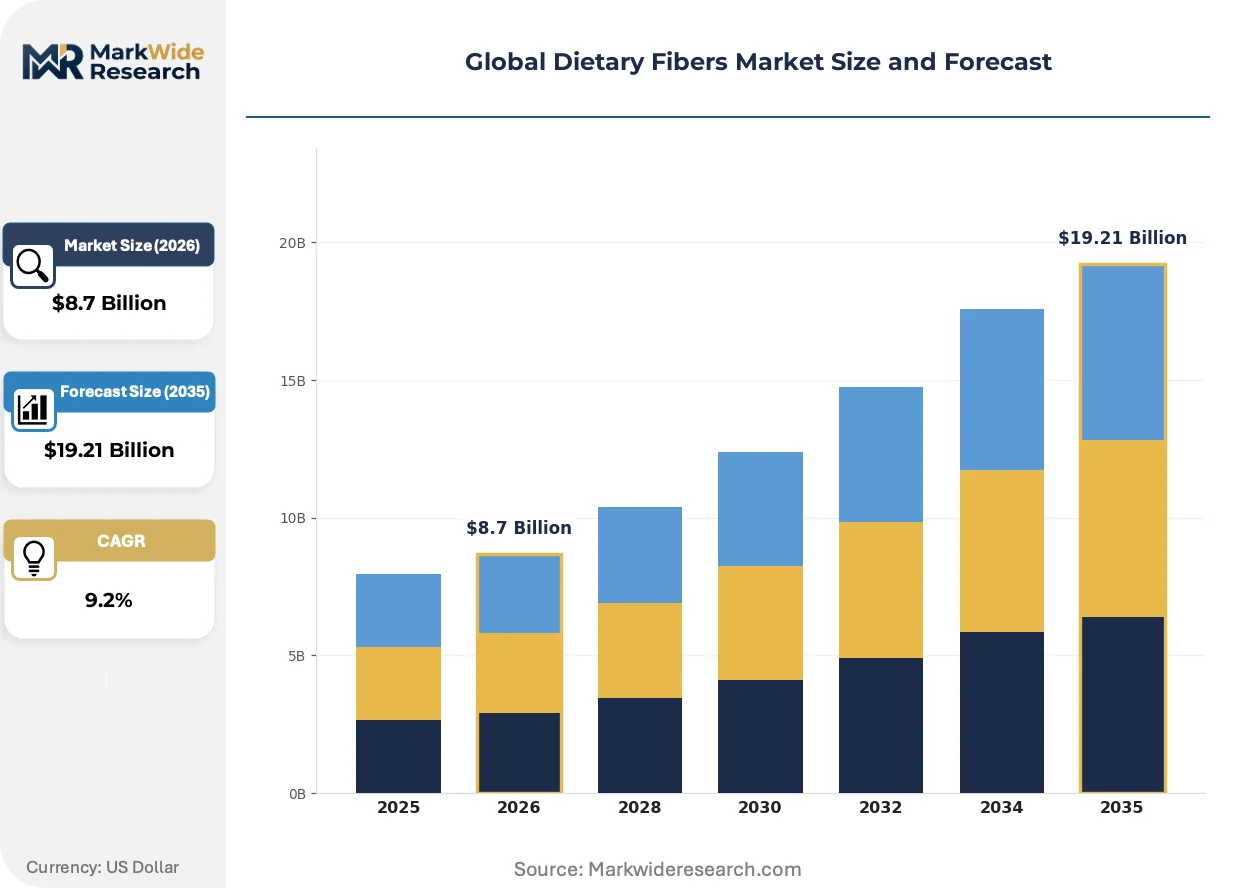
Market Dynamics
Clean-label beverage reformulation is compressing synthetic hydrocolloid demand as soluble fiber alternatives capture formulation budgets across reduced-sugar product lines. This substitution pressure concentrates supply chain influence among wet-milling operators with captive starch and fiber extraction infrastructure.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:Tightened substantiation requirements for prebiotic and bowel function claims create competitive moats for suppliers with clinical dossiers, concentrating premium positioning among established European fiber producers.
- Functional beverage manufacturing:North American and European drink brands actively replace synthetic stabilizers with chicory-derived inulin and soluble corn fiber to meet transparency demands while maintaining mouthfeel functionality in low-calorie formulations.
- Microbiome science advancement:Fermentation research validating specific fiber structures for gut health outcomes drives supplement manufacturer willingness to pay premium prices for characterized prebiotic ingredients with documented bifidogenic effects.
Market Restraints
- Chicory root supply concentration:European inulin production clusters in Belgium and northern France create geographic vulnerability to weather-driven raw material disruptions and seasonal harvest volatility.
- FDA fiber definition uncertainty:Isolated and synthetic fiber qualification under updated Nutrition Facts labeling rules forces U.S. manufacturers into costly reformulation cycles when previously approved ingredients lose declaration eligibility.
- Technical functionality gaps:Soluble fiber alternatives struggle to replicate the shear-thinning and freeze-thaw stability of gum arabic and carrageenan in certain dairy and frozen dessert applications, limiting complete substitution.
Strategic Opportunities
- Agricultural sidestream valorization:Citrus peel, sugar beet pulp, and oat hull extraction technologies unlock label-friendly fiber sourcing from waste streams, appealing to sustainability-positioned food brands seeking circular supply narratives.
- Japan Foods with Function Claims system:The Consumer Affairs Agency's alternative regulatory pathway offers export-oriented suppliers a template for claim architecture strategies that bypass lengthier EFSA authorization timelines.
- Specialty starch-fiber hybrid systems:Converging modified starch and soluble fiber technologies enable texture functionality in reduced-calorie bakery and dairy that single-ingredient solutions cannot achieve.
Industry Challenges
- Clinical substantiation capacity:Human intervention studies required for EFSA Article 13.5 and 14 health claim approvals demand specialized nutrition science talent that ingredient suppliers struggle to recruit and retain.
- Clean-label certification timelines:Non-GMO Project verification and organic certification processes extend new product commercialization cycles by twelve to eighteen months, compressing innovation-to-revenue windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dietary Fibers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soluble Fibers, Insoluble Fibers, Functional Fibers, Prebiotic Fibers Application: Food & Beverage, Dietary Supplements, Animal Feed, Pharmaceuticals Source: Natural Sources, Synthetic Sources, Cereals, Fruits End User: Adults, Children, Elderly, Athletes |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, DuPont de Nemours Inc., Ingredion Incorporated, Tate & Lyle, BENEO GmbH, Roquette Frères, Kerry Group plc, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dietary Fibers Market Emerging Trajectories
Membrane filtration and enzymatic extraction technologies are unlocking novel fiber structures from underutilized plant matrices. These process innovations reshape competitive positioning by enabling smaller suppliers to bypass capital-intensive wet-milling infrastructure.
Precision enzymatic hydrolysis is automating the production of targeted molecular weight inulin fractions from chicory root. Beverage manufacturers in Germany and the Netherlands adopt these characterized ingredients at accelerating pace. The technology is automating quality consistency that previously required batch-to-batch manual adjustment, compressing premium pricing power for standardized grades.
EFSA's evolving interpretation of "significant" effects under Regulation 1924/2006 is tightening the evidentiary threshold for glycemic response claims. This regulatory recalibration forces reformulation toward fibers with stronger human clinical data packages. Reduced-sugar bakery applications in France and Italy face the most acute compliance pressure, driving supplier investment in proprietary intervention studies.
Direct supplier relationships with mid-sized functional food brands are displacing traditional ingredient distributor networks for prebiotic fiber procurement. This channel compression concentrates order consolidation among manufacturers offering technical service support alongside raw material supply. The shift is most visible in Scandinavian markets where smaller brands prioritize formulation partnership over commodity purchasing.
Global Dietary Fibers Market Segmentation
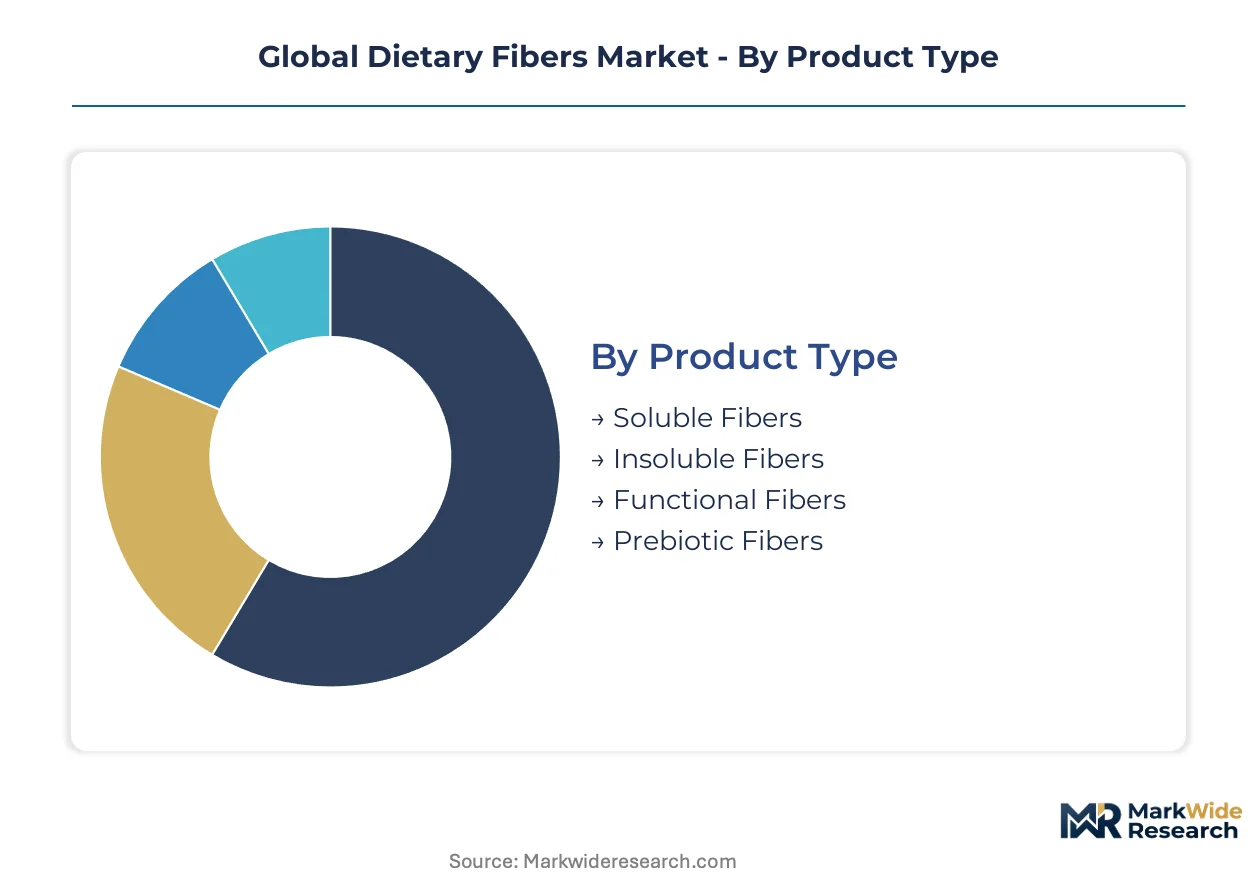
Segmentation in dietary fibers determines which regulatory pathways manufacturers must navigate. EFSA health claim substantiation requirements vary sharply across product categories, creating divergent margin structures and R&D investment priorities.
Product Type:
Certification burden concentrates on prebiotic and functional fiber segments, where EFSA Article 13.5 and 14 claims demand human intervention studies. Soluble and insoluble categories face lighter documentation requirements under general dietary fiber declarations.
- Soluble Fibers:Corn wet-milling and chicory root extraction yield inulin, oligofructose, and resistant maltodextrin. Beverage formulators in Germany and the Netherlands source these for viscosity control in reduced-sugar lines, though freeze-thaw stability gaps persist against synthetic hydrocolloids.
- Prebiotic Fibers:Characterized by documented bifidogenic effects validated through clinical trials. Supplement manufacturers command premium pricing for ingredients with EFSA-substantiated bowel function claims, concentrating procurement among Belgian and French chicory processors with established dossiers.
- Insoluble Fibers:Wheat bran, cellulose, and oat hull derivatives deliver bulking functionality with minimal regulatory documentation.
- Functional Fibers:Novel extraction from agricultural sidestreams requires evolving FDA qualification under updated Nutrition Facts labeling rules.
Soluble fibers sit at the top of the volume ranking, with prebiotic fibers climbing the fastest.
Application:
Cost tier separation drives procurement patterns, with pharmaceutical and supplement channels absorbing premium pricing for clinically substantiated ingredients while food and beverage segments prioritize cost-efficient soluble alternatives.
- Food & Beverage:Clean-label reformulation compresses synthetic stabilizer budgets as chicory-derived inulin and soluble corn fiber capture formulation spend. Cargill's wet-milling infrastructure anchors North American supply for reduced-calorie dairy and bakery applications.
- Dietary Supplements:Microbiome science advancement validates specific fiber structures for gut health outcomes. Direct supplier relationships displace traditional distributor networks as Scandinavian brands prioritize technical service partnership over commodity purchasing.
- Animal Feed:Gut health positioning in livestock nutrition drives adoption of fermentable fibers.
- Pharmaceuticals:Excipient-grade specifications require GMP certification and documented purity profiles.
Food and beverage commands the largest volume position, with dietary supplements expanding most quickly.
Source:
Supply concentration shapes geographic sourcing strategies, with European chicory clusters and North American corn wet-milling infrastructure defining competitive access to premium raw material streams.
- Natural Sources:Chicory root, sugar beet, and citrus peel extraction dominates European supply chains. BENEO GmbH and Roquette Frères anchor production clusters in Belgium and northern France, creating weather-driven vulnerability to harvest volatility.
- Cereals:Oat beta-glucan and wheat bran processing leverages existing grain milling infrastructure across the US Midwest and Canadian prairies.
- Fruits:Apple and citrus pectin recovery from juice processing sidestreams.
- Synthetic Sources:Polydextrose and resistant maltodextrin face FDA definition uncertainty under updated fiber qualification rules.
Natural sources dominate volume rankings, with cereals gaining share fastest.
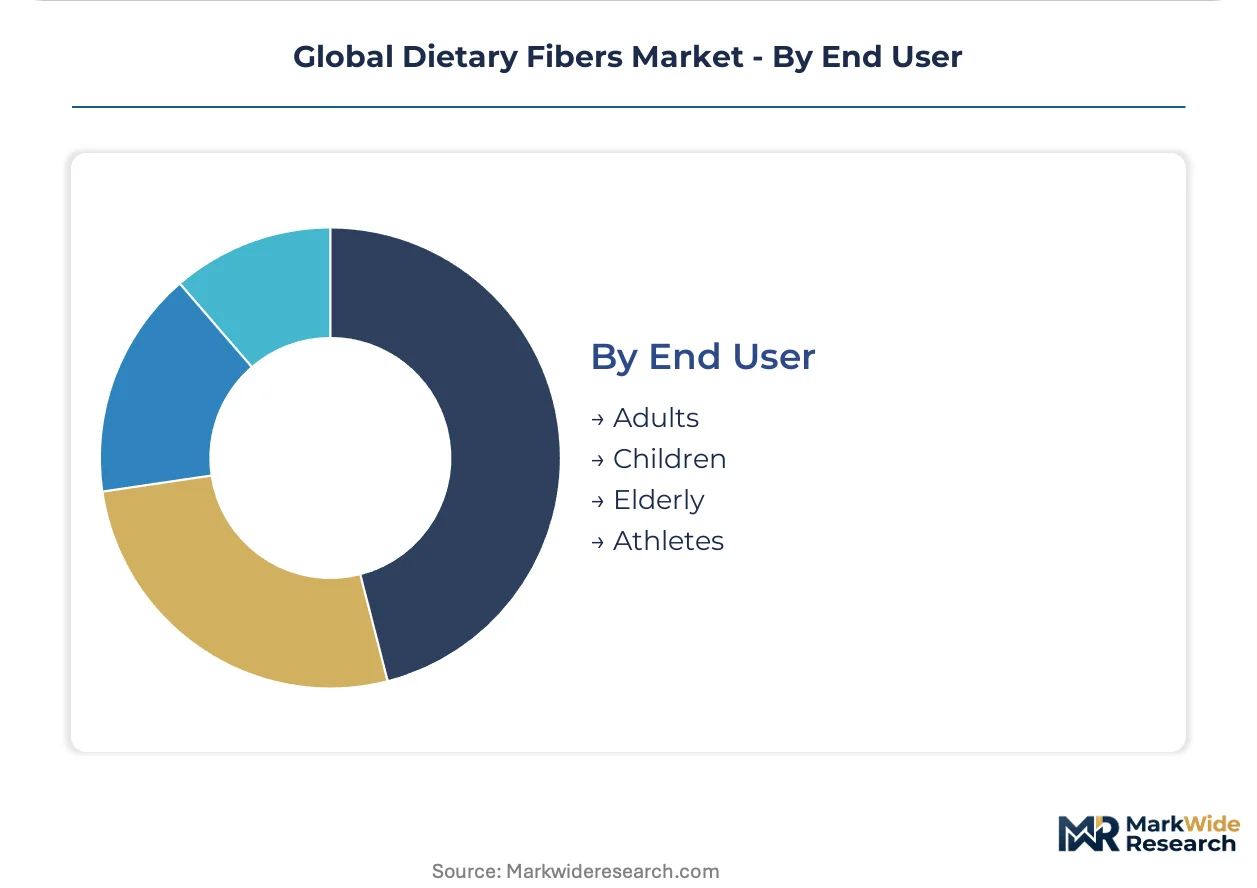
End User:
Customer type determines formulation complexity and claim architecture, with elderly and athlete segments requiring specialized delivery formats and substantiation packages.
- Adults:General wellness positioning drives bulk of soluble fiber consumption across food and supplement applications. Satiety and glycemic management claims concentrate demand in reduced-calorie bakery and beverage formats.
- Elderly:Digestive health and bowel function claims align with EFSA-approved prebiotic positioning. Formulation requires texture-modified delivery systems for swallowing safety compliance.
- Children:Palatability constraints favor soluble fiber integration over insoluble alternatives.
- Athletes:Gut microbiome optimization and sustained energy claims drive prebiotic fiber adoption in sports nutrition.
Adults represent the largest volume segment, with elderly users climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian chicory processing clusters anchor global inulin supply chains, with wet-milling infrastructure in the US Midwest and enzymatic extraction facilities in the Netherlands completing the dominant production triangle. Regulatory divergence across FDA, EFSA, and Japan's Consumer Affairs Agency shapes regional formulation strategies. Climate vulnerability in northern European harvest zones concentrates sourcing risk.
United States
Reduced-sugar beverage reformulation drives soluble corn fiber demand from Cargill's wet-milling network across Iowa and Illinois. FDA's updated Nutrition Facts labeling rules force manufacturers into qualification reviews for isolated fiber ingredients. Minneapolis-St. Paul anchors North American technical service capabilities for clean-label stabilizer substitution.
Germany
Prebiotic supplement manufacturers command premium pricing for EFSA-substantiated bowel function claims. BENEO GmbH's Mannheim facility dominates chicory root inulin output for European beverage accounts. The country's national food safety regulator enforces strict health claim documentation under EU Regulation 1924/2006.
Netherlands
Precision enzymatic hydrolysis adoption accelerates among Rotterdam-area ingredient processors targeting characterized inulin fractions. The country's central food authority aligns with EFSA interpretations on glycemic response claim thresholds. Wageningen University corridors concentrate fermentation research validating bifidogenic fiber structures.
Japan
Foods with Function Claims system offers export-oriented suppliers accelerated regulatory pathways compared to EFSA timelines. Tokyo-based supplement brands prioritize microbiome science positioning for elderly digestive health segments. Osaka-Kobe industrial zones house specialized extraction equipment for citrus peel fiber recovery.
France
Roquette Frères' Lestrem production cluster faces weather-driven chicory root supply volatility from northern French agricultural zones. Reduced-sugar bakery applications in Paris and Lyon face acute EFSA compliance pressure on glycemic claims. The national health safety agency enforces evolving "significant effects" thresholds for fiber-related positioning.
Global Dietary Fibers Market Vendor Landscape
Capacity expansion dominates the current landscape as wet-milling operators retrofit corn processing lines for soluble fiber output. The vendor base stratifies across three tiers: multinational agribusiness conglomerates with captive starch infrastructure, European chicory specialists with clinical dossier libraries, and emerging enzymatic extraction technology providers. Two strategic archetypes command attention: integrated agricultural processors leveraging backward control over raw material streams, and science-forward prebiotic specialists investing in human intervention studies. M&A activity concentrates on mid-sized extraction technology acquisitions, while geographic expansion targets Southeast Asian beverage manufacturing clusters.
Within the integrated processor tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning through Midwest wet-milling networks. BENEO GmbH occupies a specialized position as a European GmbH-structured entity focused on chicory root-derived ingredients. These three anchors demonstrate how regulatory dossier depth and raw material proximity determine competitive access to premium formulation budgets across beverage and supplement channels.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| DuPont de Nemours Inc. |
| Ingredion Incorporated |
| Tate & Lyle |
| BENEO GmbH |
| Roquette Frères |
| Kerry Group plc |
| Lonza Group |
| Others |
Supply Flow & Price Mechanics
Captive wet-milling infrastructure in the US Midwest and Belgian chicory processing clusters anchors supply positions and pricing power for soluble fiber grades. Cargill's backward integration into corn wet-milling and BENEO's control over northern European chicory harvests create divergent cost structures that downstream beverage formulators must navigate. The interaction between these integration patterns and EFSA substantiation requirements produces tiered margin capture across prebiotic and standard fiber categories.
Pricing Analysis
Input-cost pass-through from chicory root harvest volatility and corn wet-milling energy intensity shapes contract negotiations for European and North American buyers. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-substantiated prebiotic grades from commodity soluble fibers and unqualified functional fibers. Price differentiation hinges on clinical dossier depth and organic certification status. Cost compression in standard soluble grades is intensifying because synthetic hydrocolloid substitution pressure forces volume discounts. Pharmaceutical and supplement channels exhibit lowest price sensitivity due to claim substantiation requirements, while mass-market beverage brands drive hardest bargain.
Supply Chain Analysis
Dual-sourcing requirements from major beverage manufacturers mandate multi-supplier qualification across Belgian, French, and US Midwest production clusters. Geographic supply concentrates in Belgium, northern France, and Iowa-Illinois corn belt. Raw material dependencies center on chicory root, corn starch, and citrus peel sidestreams. Single-source vulnerability runs through Belgian chicory processors exposed to weather-driven harvest disruption. Distribution runs through direct supplier relationships with mid-sized functional food brands displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where clean-label reformulation has shifted demand toward EFSA-substantiated prebiotic specifications that command durable premium positioning.
For Market Incumbents: Deploy clinical substantiation investment to deepen regulatory moats against enzymatic extraction technology entrants. Defensive moves should prioritize backward integration into chicory root cultivation in Poland and Ukraine to diversify geographic exposure, and accelerate certification timelines through pre-submission engagement with EFSA's Article 13.5 evaluation panels. The threat of membrane filtration technology providers bypassing wet-milling capital requirements demands preemptive capacity lock-ups with mid-sized Scandinavian brands.
For New Entrants and Emerging Players: Precision enzymatic hydrolysis equipment offers a technology-first wedge into characterized inulin fraction supply for Dutch and German beverage accounts. White-space targets include citrus peel fiber extraction for Japan's Foods with Function Claims system and oat hull beta-glucan recovery from Canadian prairie milling sidestreams. The most penetrable segment is mid-sized Scandinavian supplement brands prioritizing technical service partnership. Go-to-market angle should emphasize rapid EFSA-equivalent dossier development through contract research organization partnerships.
For Investors and Strategic Acquirers: Roll-up economics work for European prebiotic specialists with clinical dossier libraries because EFSA authorization timelines create acquisition premiums for approved claim assets. Long-term viability over the coming decade rests on microbiome science validation deepening consumer willingness to pay for characterized ingredients. Target acquisition archetype: Belgian or French chicory processors with established bowel function claims and underutilized extraction capacity. Signal to watch: EFSA's evolving interpretation of "significant" glycemic effects forcing reformulation toward clinically validated fibers.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Dossier Investment | EFSA Article 13.5 approvals unlock premium positioning in European retail channels against unqualified competitors. |
| Agricultural Sidestream Valorization | Citrus peel and oat hull extraction technologies appeal to sustainability-positioned brands seeking circular supply narratives. |
| Precision Enzymatic Hydrolysis Adoption | Targeted molecular weight inulin fractions automate quality consistency previously requiring manual batch adjustment. |
| Direct Supplier Relationship Expansion | Technical service partnerships with Scandinavian brands displace traditional distributor networks for prebiotic procurement. |
| Geographic Diversification into Eastern Europe | Polish and Ukrainian chicory cultivation reduces weather-driven concentration risk in Belgian and northern French zones. |
Methodological Framework
Direct dialogue with ingredient procurement managers at functional beverage manufacturers, regulatory affairs directors at European fiber suppliers, chicory processing plant managers in Belgium, and supplement brand formulators in Scandinavia grounded qualitative insights. Secondary validation drew from EFSA health claim register entries, FDA Nutrition Facts labeling guidance documents, Japan Consumer Affairs Agency Foods with Function Claims notifications, and EU agricultural harvest statistics. Bottom-up volume estimates from individual production facilities triangulated against top-down category spending analysis from food and beverage formulation budgets.
Bottom-up modeling aggregated capacity utilization rates across named production clusters while top-down analysis tracked formulation budget shifts from synthetic hydrocolloids to soluble fiber alternatives. Segmentation dimensions spanned product type, application channel, source origin, and end-user demographic. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points. Industry-specific forecast inputs included chicory root harvest yield volatility and EFSA evaluation queue backlogs.
The model holds under stable EFSA interpretation of substantiation requirements; deviation in regulatory threshold tightening or FDA fiber definition expansion would shift volume trajectories materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Marine Collagen Ingredients Market
Ingredients
Pig Protein Concentrate Market
Ingredients
Europe Potato Protein Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Macleaya Cordata Extract Market
Ingredients
PHO Oils Market
Ingredients
Stock Cubes Market
Ingredients
Bulk Food Ingredients Market
Ingredients
Bromelain Ingredient Market
Ingredients
China Beer Adjuncts Market
Ingredients
USA Yeast Extracts Market
Ingredients
Encapsulated Salt Market
Ingredients
Cocoa Derivatives Market
Ingredients
Seaweed Extracts Market
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
Modified Flour Market