
 Food Grade Hydrolyzed Casein Market | 2026-2036
Food Grade Hydrolyzed Casein Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Hydrolyzed Casein Market Insights
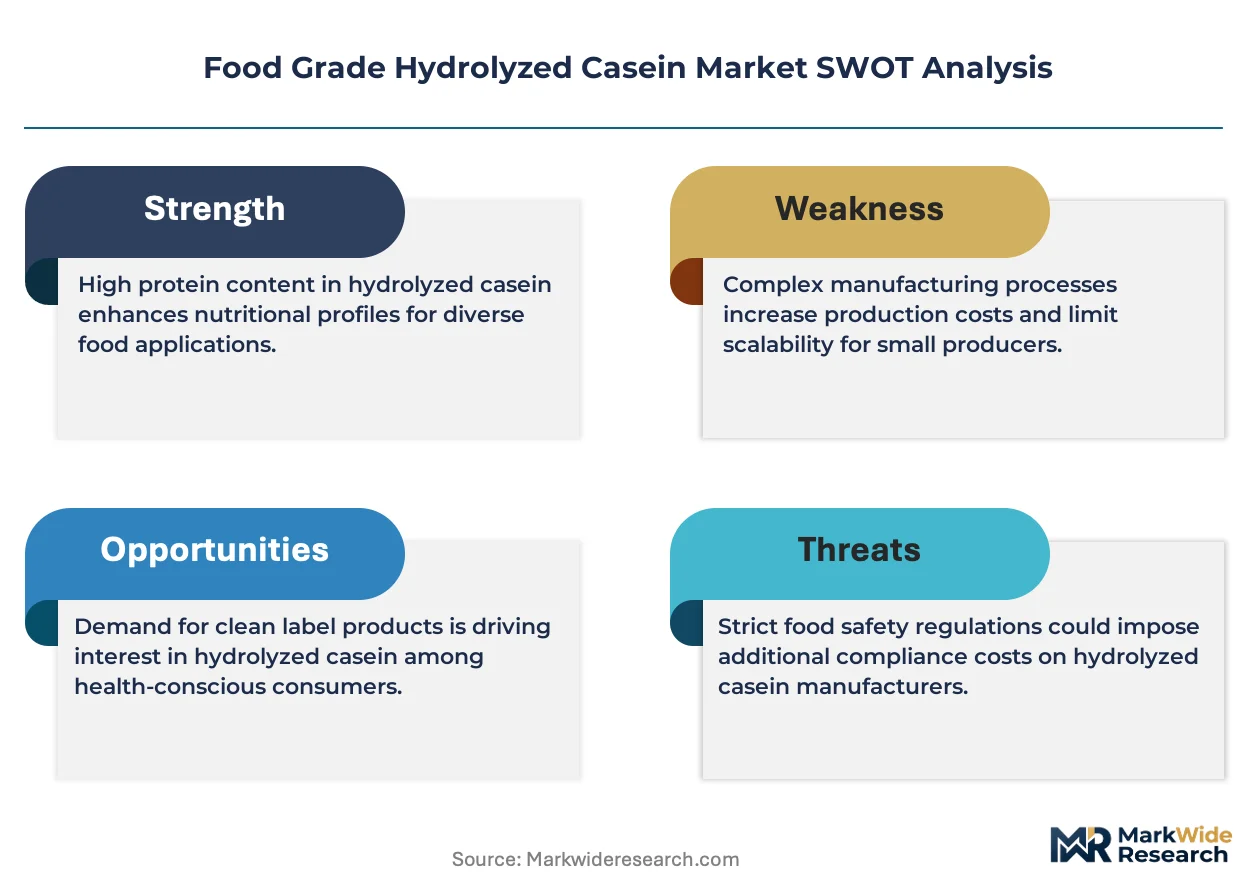
Plant-based protein isolates are displacing conventional dairy inputs in select beverage categories, yet hydrolyzed casein is consolidating its position in premium performance nutrition where amino acid completeness matters. AMCO Proteins leverages its Midwest dairy supply base to anchor domestic manufacturing scale. Lactalis Ingredients competes through backward integration into French and Italian milk collections. Fonterra Co-operative Group dominates Oceania-origin exports with vertically controlled processing from farm to ingredient.
Food grade hydrolyzed casein comprises enzymatically fragmented casein micelles yielding peptides typically below 10 kilodaltons, manufactured via controlled proteolysis followed by membrane filtration and spray drying for use as a rapid-digesting protein source in clinical and athletic nutrition. Caseinates retain the largest volume share among product types due to their functional stability in retort applications and established bakery presence. Sports nutrition represents the fastest-expanding end user segment as endurance and resistance-training formulations shift toward timed-release protein matrices. Infant formula applications command premium positioning through stringent mineral-binding and hypoallergenic specifications.
FDA GRAS self-affirmation requirements and EFSA novel food consultations shape formulation standards and market access timelines for hydrolyzed dairy ingredients entering European and American jurisdictions. China's NMPA and national food safety standards impose additional registration burdens on imported hydrolyzed proteins destined for infant nutrition. Stakeholders must monitor evolving peptide-length regulations and regional allergen labeling mandates to preserve formulation flexibility across destination markets.
Market Dynamics
Enzymatic hydrolysis efficiency gains are compressing production costs while peptide length standardization is fragmenting supplier tiers into specification-grade strata. These dual forces are restructuring procurement relationships between ingredient manufacturers and finished goods formulators.
Growth Catalysts
- GRAS Self-Affirmation Pathway:The FDA's streamlined notification process accelerates novel peptide formulation launches in US sports nutrition applications.
- Timed-Release Protein Matrices:Endurance and resistance-training brands specify hydrolyzed casein for overnight muscle protein synthesis support.
- Shanghai Cluster Concentration:Domestic infant formula manufacturers in China's Yangtze River Delta are qualifying local hydrolyzed protein suppliers to reduce import dependency.
Market Restraints
- Fresh Milk Input Volatility:Casein production ties directly to fluid milk commodity cycles, exposing margins to feed cost and weather shocks.
- Plant Protein Substitution:Pea and fava bean isolates capture share in ready-to-drink beverages where amino acid completeness is deprioritized.
- Novel Food Consultation Timelines:EFSA's extended safety assessment periods delay European market entry for innovative peptide profiles.
Strategic Opportunities
- Medical Nutrition Expansion:Enteral feeding and post-surgical recovery formulations specify hypoallergenic hydrolyzed casein for compromised digestive systems.
- Clean-Label Certification Tailwinds:EU Green Deal alignment and CSRD reporting requirements favor transparent, farm-traceable dairy protein sourcing.
- E-Commerce Direct Procurement:Sports nutrition brands source ingredients through B2B platforms, bypassing traditional distributor markups.
Industry Challenges
- Peptide Analytics Talent Scarcity:Mass spectrometry and chromatography specialists command premium compensation, constraining quality control scale-up.
- Infant Formula Registration Burden:China's NMPA requires extensive clinical documentation, extending product approval cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Hydrolyzed Casein Market |
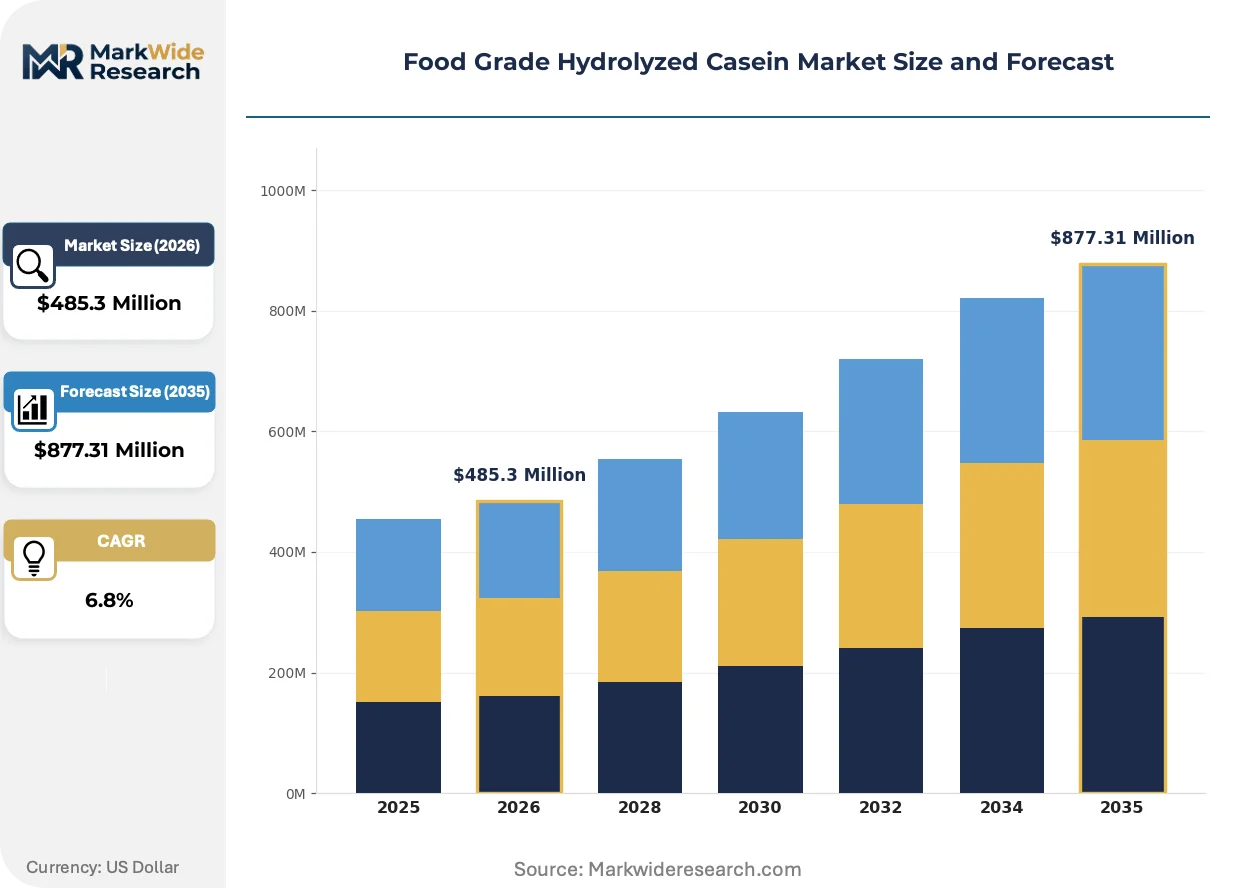
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $877.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Casein, Caseinates, Isolated Casein, Cheese Protein End User: Food & Beverage, Nutraceuticals, Sports Nutrition, Infant Formula Application: Dairy Products, Supplements, Protein Enrichments, Bakery Goods Distribution Channel: Online, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | AMCO Proteins, Lactalis Ingredients, FrieslandCampina Ingredients, MEGGLE GmbH & Co.KG, Kerry Group, Fonterra Co-operative Group, Tatua Co-operative Dairy Company, Erie Foods International, Arla Foods Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Hydrolyzed Casein Market Trends and Innovations
Membrane filtration advances and precision proteolysis are enabling peptide length customization that matches specific absorption kinetics to end-use requirements. These capabilities are differentiating suppliers beyond basic protein content metrics.
Electrodialysis demineralization is electrifying the production of low-ash hydrolyzed casein for infant formula applications. European and Oceania processors deploy this technology to meet mineral-binding specifications demanded by hypoallergenic formulations. The process is compressing the supplier base to those with capital-intensive purification infrastructure.
EFSA's evolving novel food consultations are extending safety data requirements for hydrolyzed dairy peptides entering European sports nutrition. Formulators must commission toxicology studies and dietary exposure assessments before commercialization. Premium positioning now depends on preemptive regulatory dossier preparation rather than post-launch compliance.
Athlete and clinical nutrition buyers now specify peptide molecular weight distributions in procurement contracts, shifting quality verification upstream to ingredient suppliers. Third-party certification bodies validate these specifications, replacing spot-testing by finished goods manufacturers. This pattern concentrates purchasing power with brands possessing in-house analytical capabilities.
Food Grade Hydrolyzed Casein Market Segmentation
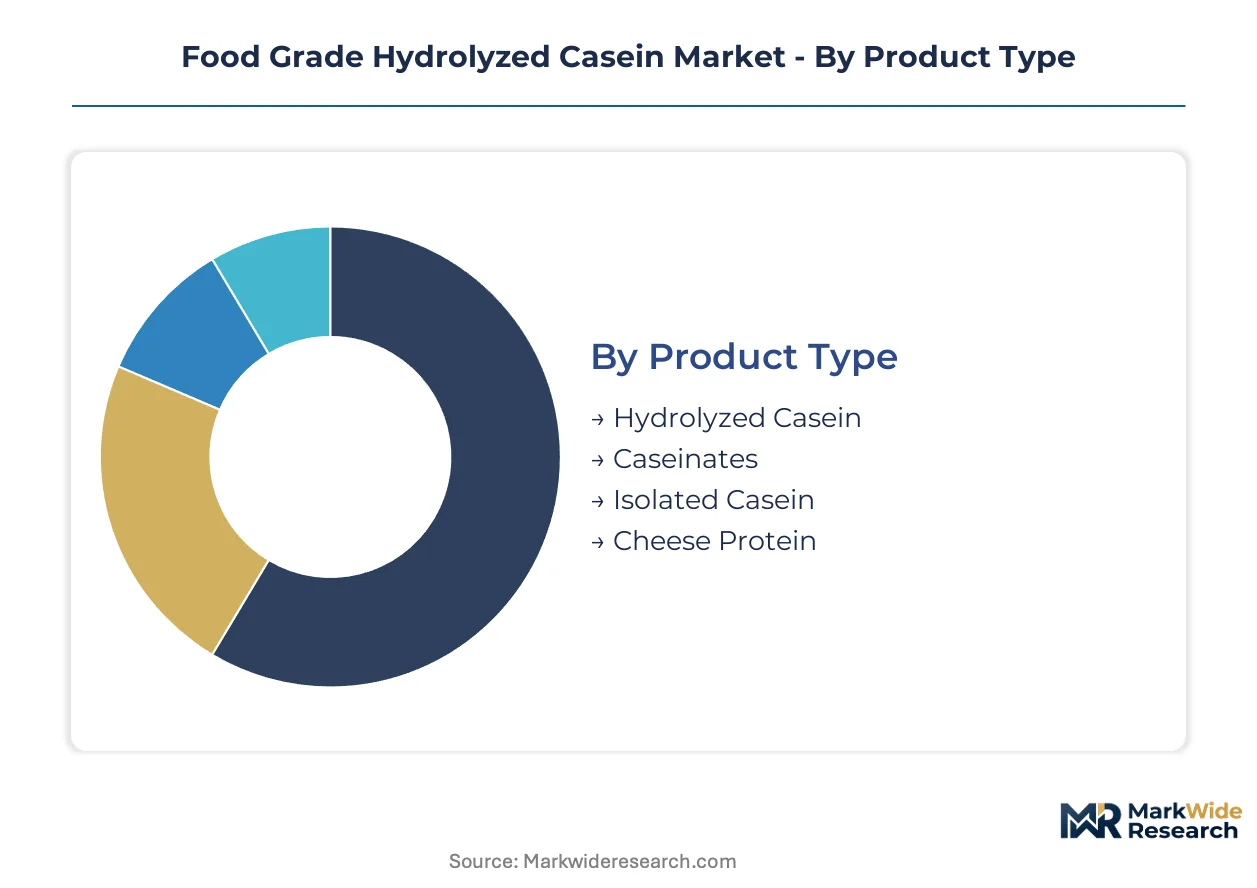
Segmentation in the Food Grade Hydrolyzed Casein Market reveals how regulatory requirements fragment across use cases. Infant formula and sports nutrition applications face divergent approval pathways from FDA GRAS self-affirmation to China's NMPA registration mandates.
Product Type:
Certification burdens vary sharply by product type, with hydrolyzed casein for infant formula requiring EFSA novel food consultations while caseinates for bakery applications navigate simpler self-affirmation routes.
- Hydrolyzed Casein:Enzymatically fragmented casein micelles yielding peptides below 10 kilodaltons, manufactured via controlled proteolysis followed by membrane filtration. Demand concentrates in China's Yangtze River Delta where domestic infant formula manufacturers qualify local suppliers to reduce import dependency amid NMPA registration requirements.
- Caseinates:Functional derivatives retaining micellar stability in retort applications and established bakery presence. Sports nutrition brands in the United States specify sodium and calcium caseinates for timed-release protein matrices, leveraging FDA's streamlined GRAS notification pathway for rapid formulation launches.
- Isolated Casein:High-purity fractions requiring capital-intensive purification infrastructure.
- Cheese Protein:Co-products from cheese manufacturing with variable peptide profiles.
Leading the category by volume: Caseinates. Growing fastest: Hydrolyzed Casein.
End User:
Customer type determines margin structure, with infant formula commanding premium positioning through stringent mineral-binding specifications while food and beverage applications compete on cost efficiency.
- Food & Beverage:Volume-driven applications spanning dairy beverages and processed foods where protein enrichment meets clean-label demands. European manufacturers align procurement with EU Green Deal traceability requirements.
- Nutraceuticals:Clinical nutrition segments including enteral feeding and post-surgical recovery formulations. Electrodialysis demineralization enables low-ash specifications for compromised digestive systems.
- Sports Nutrition:Fastest-expanding segment as endurance and resistance-training brands shift toward timed-release protein matrices. EFSA's extended safety assessment periods delay European market entry for innovative peptide profiles.
- Infant Formula:Premium positioning through hypoallergenic specifications and mineral-binding properties. China's NMPA imposes 18-24 month approval cycles with extensive clinical documentation requirements.
Highest margin capture: Infant Formula. Steepest expansion trajectory: Sports Nutrition.
Application:
Application maturity shapes supply relationships, with dairy products and bakery goods relying on established procurement channels while supplements and protein enrichments drive e-commerce direct sourcing.
- Dairy Products:Traditional integration of casein derivatives into processed cheese and yogurt systems.
- Supplements:Powder and capsule formats where peptide molecular weight distributions now appear in procurement contracts. Third-party certification bodies validate specifications, concentrating purchasing power with analytically capable brands.
- Protein Enrichments:Functional additions to bars, RTD beverages, and meal replacements. B2B platform procurement is bypassing traditional distributor markups in this application.
- Bakery Goods:Functional stability in retort applications sustains established demand.
Most mature application: Bakery Goods. Gaining share fastest: Supplements.
Distribution Channel:
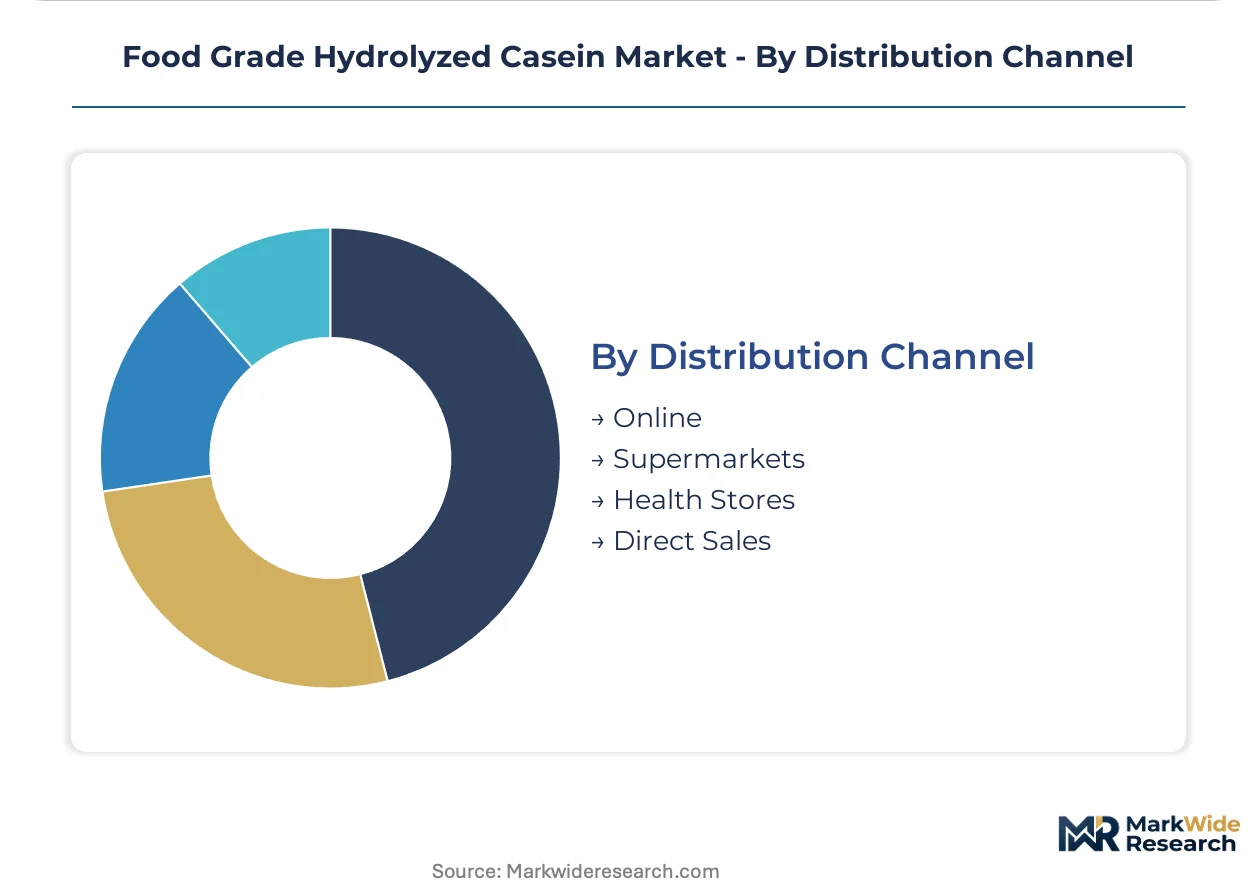
Channel configuration reflects customer scale and specification complexity, with direct sales dominating high-volume infant formula contracts while online platforms fragment sports nutrition ingredient procurement.
- Online:B2B platforms enabling sports nutrition brands to source hydrolyzed casein directly, compressing traditional distributor margins. E-commerce penetration is highest among mid-tier peptide suppliers seeking market access.
- Supermarkets:Retail shelf presence for finished consumer goods rather than bulk ingredients.
- Health Stores:Specialty retail channel for premium-positioned sports nutrition finished products.
- Direct Sales:Long-term contracts between ingredient manufacturers and infant formula producers. Shanghai-based domestic manufacturers leverage direct relationships to secure localized high-specification protein sources.
Dominant by contract value: Direct Sales. Expanding most quickly: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates hydrolyzed casein demand through its domestic infant formula manufacturers seeking localized protein sources. The United States and Germany anchor sports nutrition formulation activity, while France and New Zealand maintain processing infrastructure tied to dairy collection networks.
United States
Sports nutrition brands in the United States specify hydrolyzed casein for timed-release protein matrices targeting overnight muscle recovery. FDA's GRAS self-affirmation pathway accelerates novel peptide launches, compressing formulation-to-market timelines. Midwest dairy supply bases around Wisconsin and Minnesota anchor domestic manufacturing scale for ingredient processors.
China
Domestic infant formula manufacturers in China's Yangtze River Delta drive qualification of local hydrolyzed protein suppliers to reduce import dependency. NMPA registration mandates impose 18-24 month approval cycles with extensive clinical documentation requirements. Shanghai-based producers leverage direct procurement relationships to secure high-specification protein sources meeting hypoallergenic standards.
Germany
Clinical nutrition formulators in Germany specify low-ash hydrolyzed casein for enteral feeding applications serving compromised digestive systems. EFSA novel food consultations extend safety assessment timelines for innovative peptide profiles entering European markets. Bavarian and North Rhine-Westphalia processing clusters deploy electrodialysis demineralization to meet mineral-binding specifications.
France
Lactalis Ingredients competes through backward integration into French and Italian milk collections, securing fluid milk inputs for casein derivative production. EU Green Deal alignment and CSRD reporting requirements favor transparent, farm-traceable dairy protein sourcing. Normandy and Brittany dairy basins concentrate enzymatic hydrolysis capacity serving premium nutrition segments.
New Zealand
Fonterra Co-operative Group dominates Oceania-origin exports with vertically controlled processing from farm to ingredient, spanning spray drying and membrane filtration infrastructure. The country's national food safety regulator maintains stringent purity benchmarks for dairy-derived ingredients destined for infant formula applications. Canterbury and Waikato dairy regions anchor production scale for Asia-Pacific export markets.
Food Grade Hydrolyzed Casein Market Competitive Landscape
Capacity expansion dominates the current landscape as processors deploy electrodialysis and precision proteolysis infrastructure to capture specification-grade tiers. The supplier base stratifies between capital-intensive multinationals with captive dairy supply and regional specialists focused on peptide length customization. Two archetypes define positioning: vertically integrated dairy cooperatives controlling farm-to-ingredient chains, and ingredient technology firms leveraging enzymatic efficiency gains. M&A activity and strategic partnerships concentrate procurement relationships with analytically capable brands.
Among dairy cooperative processors, Fonterra Co-operative Group and Lactalis Ingredients exemplify the integrated archetype through upstream control over milk collection networks. Kerry Group occupies a position within the ingredient technology tier, representing enzyme and formulation capability specialization. FrieslandCampina Ingredients anchors European supply capacity with Netherlands-based processing infrastructure. These three entities collectively illustrate how geographic proximity to dairy basins and regulatory dossier preparation differentiate competitive positioning across infant formula and sports nutrition end uses.
| Leading Market Players |
|---|
| AMCO Proteins |
| Lactalis Ingredients |
| FrieslandCampina Ingredients |
| MEGGLE GmbH & Co.KG |
| Kerry Group |
| Fonterra Co-operative Group |
| Tatua Co-operative Dairy Company |
| Erie Foods International |
| Arla Foods Ingredients |
| Others |
Pricing and Supply Chain Analysis
Mass spectrometry specialists in Bavaria and Wisconsin command premium compensation that widens spreads between specification-grade hydrolyzed casein and commodity caseinates. FDA GRAS self-affirmation costs and EFSA novel food consultation fees further stratify pricing tiers as buyers sort by regulatory preparation depth.
Pricing Analysis
Volume concentrates in caseinates for bakery and retort applications while margins pool in hydrolyzed casein for infant formula and medical nutrition. Three-tier pricing structure across premium, standard, and economy levels separates electrodialysis-dematerialized infant-grade peptides from sports nutrition intermediates and industrial caseinates. Pricing pressure stems from plant protein substitution in ready-to-drink beverages where amino acid completeness carries less weight. Food and beverage manufacturers exhibit highest price sensitivity while infant formula producers absorb premiums for hypoallergenic certification.
Supply Chain Analysis
Fresh milk supply rests on French, Italian, and New Zealand dairy cooperatives with backward integration into farm collection networks. Enzymatic inputs draw from Danish and Dutch specialty enzyme producers while membrane filtration equipment sources from German and Japanese engineering firms. Single-source vulnerability concentrates in electrodialysis demineralization capacity where only European and Oceania processors maintain installed base. Distribution runs through direct sales contracts for infant formula and B2B platforms for sports nutrition procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: electrodialysis demineralization capacity limits low-ash hydrolyzed casein output, propping pricing for specification-grade tiers against commodity caseinate erosion.
For Market Incumbents: Lock in captive dairy supply through long-term milk collection agreements in Normandy, Brittany, and Canterbury to defend against input volatility. Expand electrodialysis capacity ahead of NMPA registration waves from Shanghai-based infant formula manufacturers. Prioritize mass spectrometry talent acquisition in Bavaria and Wisconsin analytical clusters to sustain peptide-length certification advantages. For New Entrants and Emerging Players: E-commerce direct procurement routes offer lowest barrier entry for mid-tier sports nutrition peptide suppliers bypassing traditional distributor networks. Target China's Yangtze River Delta domestic qualification programs where import substitution policies favor local hydrolyzed protein sourcing. Lead with peptide length customization capabilities validated by third-party certification bodies to differentiate from commodity caseinate suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with enzyme technology specialists given precision proteolysis efficiency gains compressing production costs across the analysis window. Long-term viability favors processors with dual capability in membrane filtration and electrodialysis serving both sports nutrition and infant formula end uses. Watch NMPA registration approval velocity as inflection indicator for China demand realization.| Strategic Initiative | Industry Significance |
|---|---|
| Electrodialysis Capacity Expansion | Enables low-ash hydrolyzed casein production for NMPA-registered infant formula applications. |
| Backward Integration into Dairy Collections | Secures fluid milk inputs in Normandy and Canterbury against feed cost volatility. |
| Precision Proteolysis Technology Licensing | Compresses enzymatic hydrolysis costs while standardizing peptide length distributions. |
| Third-Party Peptide Certification Program | Validates molecular weight specifications for B2B platform procurement contracts. |
| Direct Sales Channel Development | Bypasses distributor markups in Shanghai cluster infant formula procurement relationships. |
Research Methodology
Multi-period observation of NMPA registration timelines, EFSA novel food consultation outcomes, and enzymatic hydrolysis capacity deployments anchored the trend analysis, supplemented by interviews with ingredient procurement managers at infant formula manufacturers, sports nutrition brand formulators, dairy cooperative processing directors, and peptide analytics laboratory heads. Secondary validation drew from FDA GRAS notification databases, EFSA novel food opinions, Chinese national food safety standards, and customs trade data for hydrolyzed protein imports. Bottom-up segment sizing triangulated against top-down dairy protein production estimates.
Segment-weighting across product type, end user, application, and distribution channel dimensions structured the analytical framework. CAGRs were derived from fitted growth curves applied to base-year estimates across the projection horizon. Industry-specific forecast inputs incorporated peptide length regulation evolution, electrodialysis capacity expansion schedules, and China import substitution policy implementation velocity.
The model holds under stable regulatory consultation timelines and intact dairy cooperative supply structures; deviation in NMPA approval velocity or fresh milk input shocks would shift volume and value trajectories. A small set of named triggers warrants ongoing watch: EFSA peptide safety data requirements, China domestic supplier qualification rates, and enzyme cost compression curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Wheat Starch Derivative Market
Ingredients
Liquid Feed Market
Ingredients
Barley Malt Extract Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Yeast Flakes Market
Ingredients
Protein Hydrolysate Market
Ingredients
Resistant Starch Market
Ingredients
Vital Wheat Gluten Market
Ingredients
Plant Sterols and Esters Market
Ingredients
Fruit Powder Market
Ingredients
Sweet Almond Oil Market
Ingredients
US Choline Bitartrate Market
Ingredients
Asia-Pacific Carrageenan Market
Ingredients
Mastic Gum Market
Ingredients
Licorice Root Market
Ingredients
Cacao Bean Market