
 Asia-Pacific Prebiotic Ingredients Market | 2026-2036
Asia-Pacific Prebiotic Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Prebiotic Ingredients Market Outlook
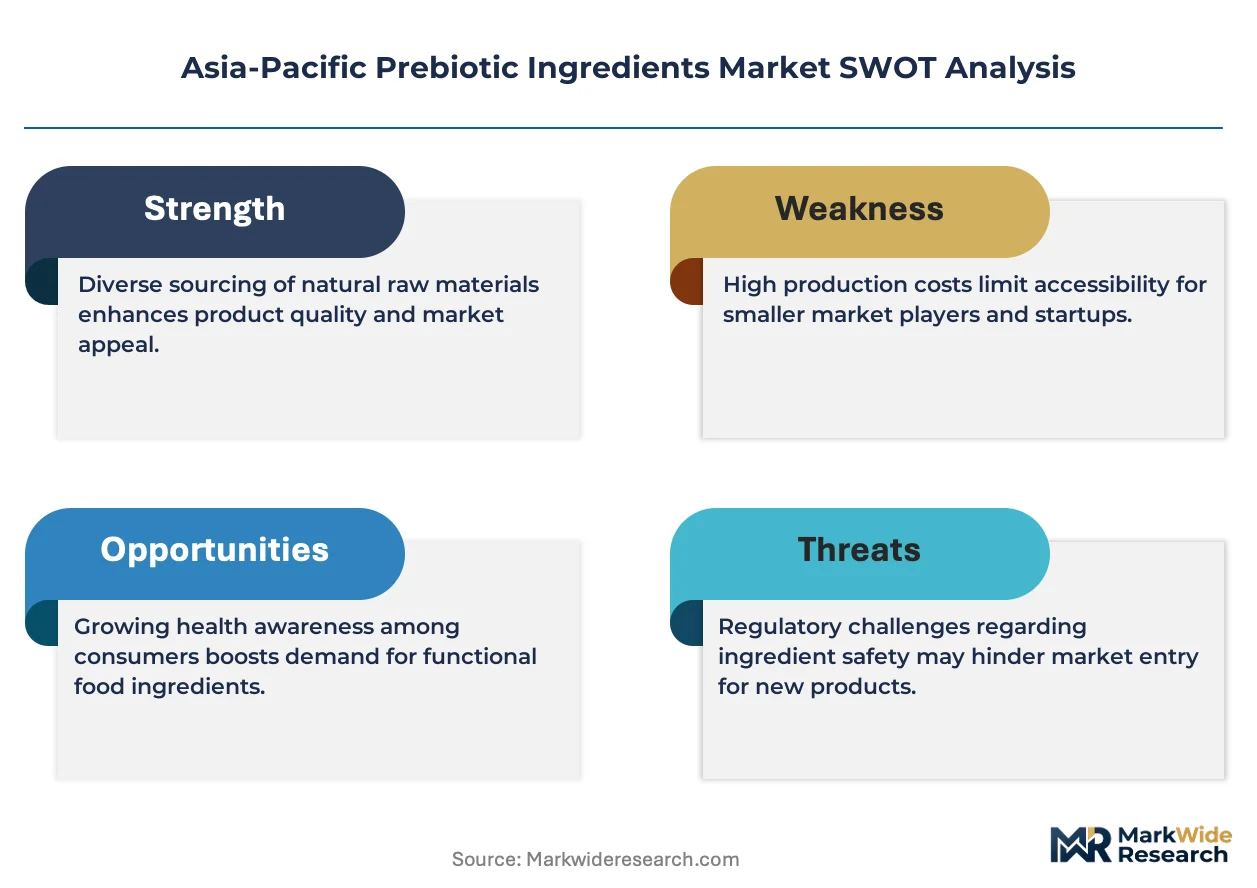
Ingredient formulation services is tilting from generic commodity supply toward customized synbiotic blends and clinical substantiation packages. BENEO GmbH leverages its Belgian-Chinese joint manufacturing footprint to dominate chicory-derived inulin supply across East Asia. CJ CheilJedang Corp. anchors its position through captive fermentation capacity for galacto-oligosaccharides at scale. Nexira SAS differentiates via acacia gum prebiotic extraction tied to clean-label positioning in Australian and Japanese markets.
Asia-Pacific prebiotic ingredients comprise non-digestible food components—typically inulin chains of degree of polymerization 2-60, or galacto-oligosaccharides with β-1,4 and β-1,6 glycosidic linkages—that selectively stimulate beneficial colonic microbiota. These compounds undergo enzymatic synthesis or plant extraction before incorporation into functional foods, infant nutrition, and companion animal diets. Inulin commands the largest volume share among product types due to its established tolerance data and dual solubility profile, while galacto-oligosaccharides represent the fastest-expanding category driven by infant formula regulatory approvals in China and Southeast Asia. Application demand in dietary supplements carries the highest margin pool per kilogram, though food and beverages still absorbs the dominant tonnage across the region.
China's National Health Commission and Japan's Consumer Affairs Agency enforce divergent prebiotic health claim frameworks, with the former requiring clinical trial dossiers for new oligosaccharide approvals while the latter operates under Foods for Specified Health Uses standards. Australia's Therapeutic Goods Administration and Food Standards Australia New Zealand jointly govern borderline products, creating compliance complexity for exporters. India's FSSAI has begun aligning with Codex Alimentarius prebiotic definitions, signaling forthcoming category formalization. Stakeholders must monitor which regulator moves first on harmonized substantiation requirements, as this will determine where formulation R&D investment flows and which ingredient suppliers secure preferred supplier status with multinational brand owners.
Market Dynamics
China's National Health Commission revised food additive standards for oligosaccharide inclusion, creating immediate formulation demand across infant formula manufacturers while forcing ingredient suppliers to rebuild clinical substantiation dossiers for market access.
Growth Catalysts
- Regulatory pathway formalization:China's National Health Commission now permits expanded oligosaccharide categories in infant nutrition, triggering reformulation cycles across Southeast Asian contract manufacturers serving domestic brands.
- Fermentation capacity expansion:Captive galacto-oligosaccharide production facilities in South Korea and Japan are reducing import dependency for core prebiotic feedstocks.
- Clean-label extraction demand:Australian and Japanese functional food brands now specify acacia gum and chicory-derived inulins with verified sustainable sourcing credentials.
Market Restraints
- Chicory root supply concentration:Belgian and Dutch agricultural processors control over 70% of global inulin raw material, exposing East Asian formulators to euro-denominated input volatility and shipping disruptions through Suez corridor bottlenecks.
- Clinical trial cost barriers:China's National Health Commission mandates full dossier submissions for novel oligosaccharide approvals, pricing smaller ingredient innovators out of regulatory access.
- Enzymatic synthesis yield limitations:Current β-galactosidase biocatalysts achieve sub-optimal conversion rates for specific GOS chain length distributions required by premium infant formula specifications.
Strategic Opportunities
- India's category formalization window:India's FSSAI alignment with Codex Alimentarius prebiotic definitions will open first-mover positioning for suppliers establishing local technical service infrastructure before standards harden.
- Synbiotic formulation convergence:Pairing validated prebiotic fibers with documented probiotic strains creates differentiated positioning in Japanese Foods for Specified Health Uses applications.
- Vietnam and Indonesia infant nutrition penetration:Breastfeeding advocacy fatigue and urban income growth are expanding addressable market for prebiotic-fortified follow-on formulas in second-tier cities.
Industry Challenges
- Microbiome assay standardization gaps:Inconsistent in vitro fermentation protocols across contract research organizations delay substantiation timelines for novel oligosaccharide submissions to Japan's Consumer Affairs Agency.
- Dual-use facility capex requirements:Food-grade and pharmaceutical-grade prebiotic production lines demand segregated cleanroom investments that strain mid-tier ingredient processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Prebiotic Ingredients Market |
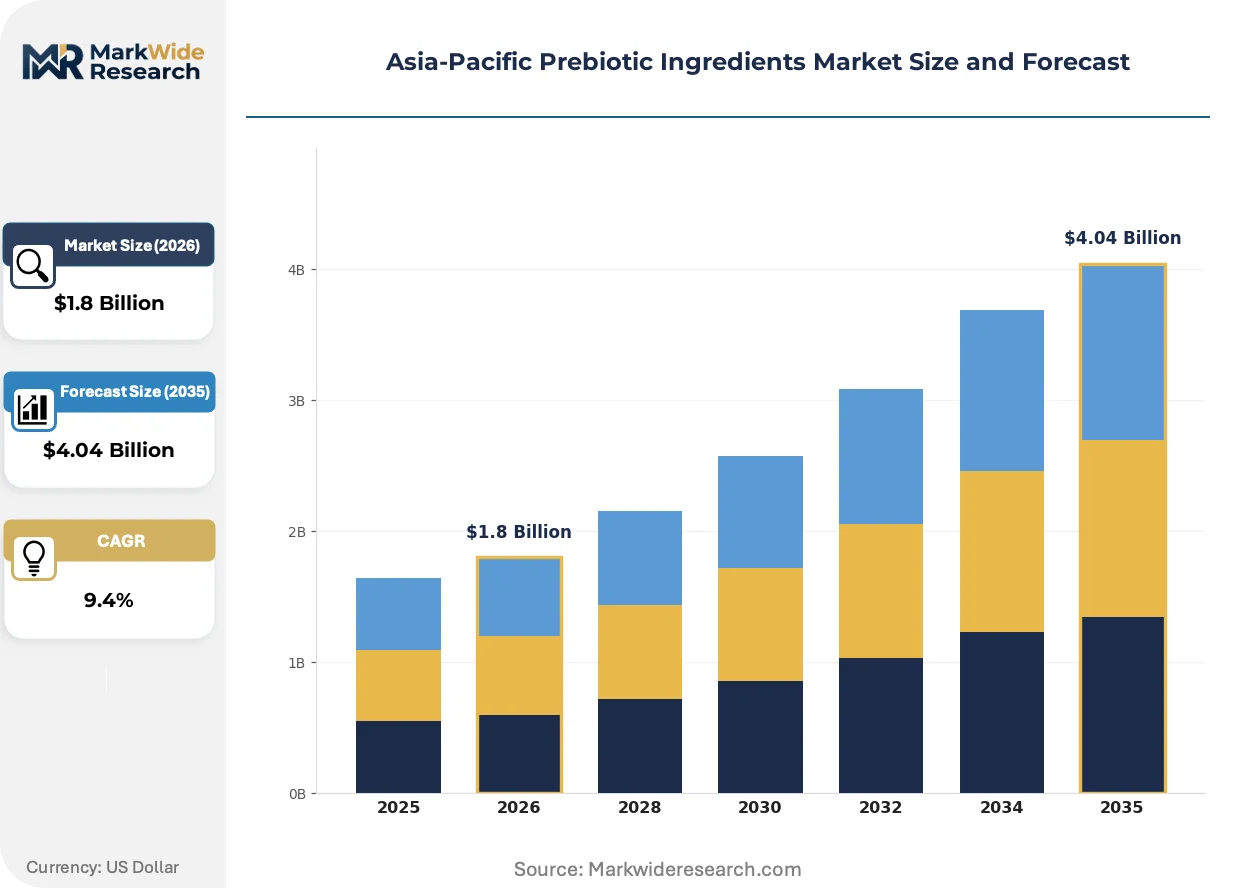
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Oligofructose, Galacto-oligosaccharides, Polydextrose Application: Food & Beverages, Dietary Supplements, Animal Feed, Pharmaceutical End User: Food Manufacturers, Nutraceutical Companies, Healthcare Providers, Consumers Form: Powder, Liquid, Granular, Tablets |
| Companies Covered | Ingredion Incorporated, BENEO GmbH, Fonterra Co-operative Group Limited, Sensus, Nexira SAS, Baolingbao Biology Co., Ltd., Cargill Incorporated, Shandong Bailong Group Co., CJ CheilJedang Corp., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Prebiotic Ingredients Market Strategic Shifts
Prebiotic ingredient supply is fragmenting from commodity bulk sales toward integrated formulation partnerships where technical service teams co-develop finished product applications with brand owners.
Enzymatic synthesis is migrating from batch fermentation toward continuous bioprocessing systems. Japanese and South Korean ingredient houses now deploy immobilized enzyme columns for galacto-oligosaccharide production, cutting cycle times by half. This shift is compressing capital requirements for new market entrants while raising quality consistency thresholds that commodity traders cannot meet.
Australia's Therapeutic Goods Administration and Food Standards Australia New Zealand have tightened borderline product classifications, forcing exporters to commit to single regulatory pathways before shipment. Dietary supplement brands now face reclassification risk if prebiotic dosage claims drift into therapeutic territory. The region's contract manufacturers are responding by bifurcating production lines into distinct food and listed medicine streams.
Ingredient specification practices are hardening around chain-length distribution certificates rather than simple purity metrics. Infant formula procurement teams in China and Southeast Asia now require detailed degree-of-polymerization profiles for inulin batches. This behavioral shift is elevating suppliers with in-house analytical capabilities while disqualifying traders lacking technical documentation infrastructure.
Asia-Pacific Prebiotic Ingredients Market Segmentation
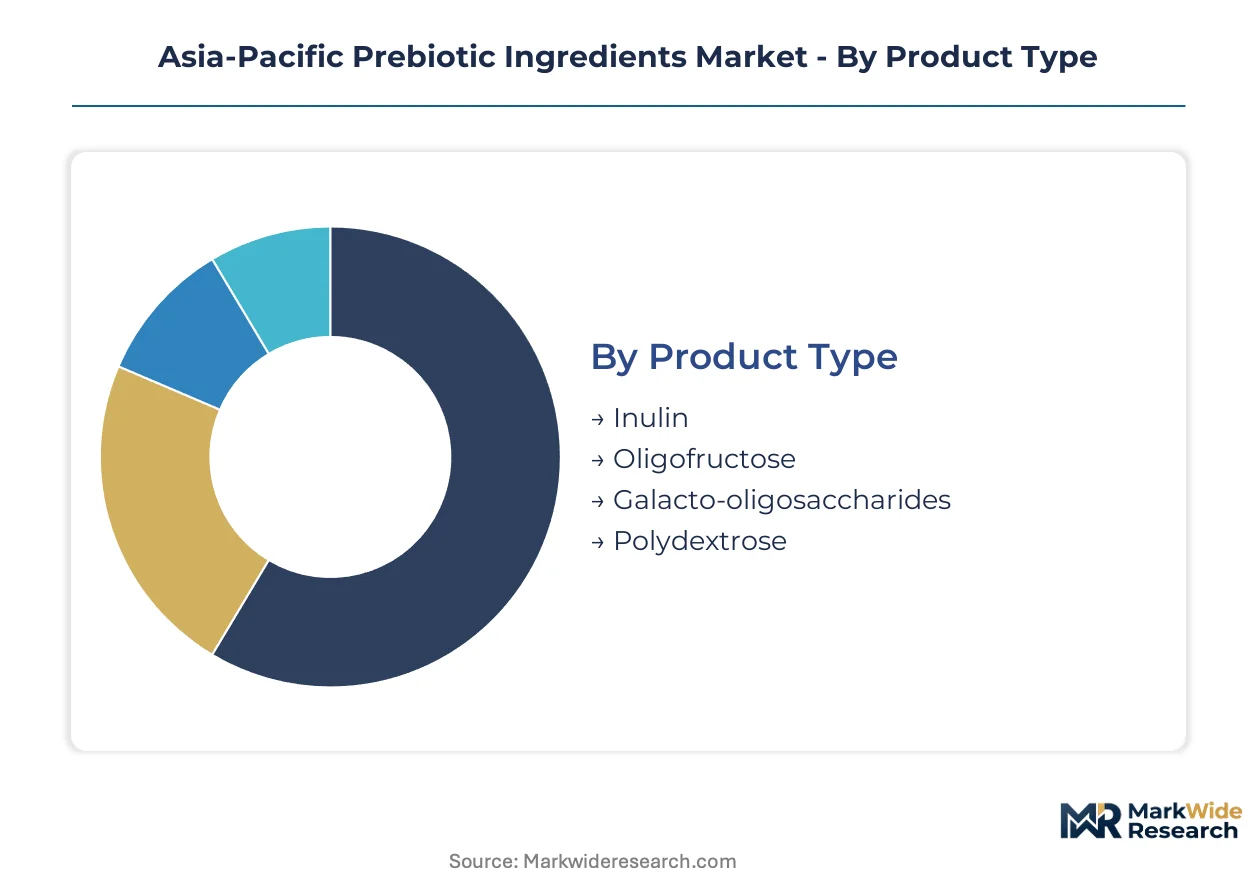
Prebiotic ingredient procurement patterns diverge sharply across product chemistry, application dosage requirements, and end-user technical sophistication. Segment boundaries determine which suppliers capture margin versus volume, and where regulatory substantiation investments concentrate.
Product Type:
Reformulation cycle times vary dramatically—some prebiotic fibers require months of digestive tolerance validation, while others slot into existing formulations immediately.
- Inulin:Long-chain fructan with degree of polymerization spanning 2-60 units, extracted primarily from chicory root. Chinese infant formula manufacturers in Shanghai and Guangzhou specify inulin for its established tolerance database and dual solubility profile, though Belgian-Dutch supply concentration creates currency and logistics exposure for East Asian formulators.
- Galacto-oligosaccharides:Short-chain oligosaccharides synthesized via β-galactosidase enzymatic conversion of lactose. Southeast Asian contract manufacturers serving domestic brands are expanding GOS fortification programs fastest, driven by China's National Health Commission expanded oligosaccharide approvals and shorter regulatory substantiation timelines versus novel fibers.
- Oligofructose:Shorter-chain fructan fraction with accelerated fermentation kinetics. Japanese functional beverage brands specify oligofructose for rapid onset of bifidogenic effect in Foods for Specified Health Uses applications.
- Polydextrose:Synthetic glucose polymer with reduced caloric density. Australian clean-label brands avoid polydextrose due to synthetic process stigma, limiting penetration outside pharmaceutical bulking applications.
Inulin dominates installed base. Galacto-oligosaccharides are where expansion concentrates.
Application:
Margin structure inverts across applications—high-volume food channels sacrifice per-kilogram returns for throughput security, while specialized channels reward technical service intensity.
- Food & Beverages:Dominant tonnage absorption channel spanning fortified dairy, bakery, and functional beverages. Chinese tier-one city retailers demand prebiotic claims with visible chain-length certificates, elevating suppliers with in-house analytical laboratories over commodity traders.
- Dietary Supplements:Highest margin pool per kilogram driven by dosage flexibility and premium positioning. Japan's Consumer Affairs Agency Foods for Specified Health Uses framework rewards clinical substantiation investment with price premiums unavailable in standard food channels.
- Animal Feed:Companion animal diets in South Korea and Japan incorporate prebiotic fibers for gut health positioning. Regulatory requirements remain lighter than human nutrition, attracting second-tier suppliers lacking pharmaceutical-grade cleanroom infrastructure.
- Pharmaceutical:Excipient and active pharmaceutical ingredient applications demand segregated production lines. Australia's Therapeutic Goods Administration borderline classifications force exporters to commit to single regulatory pathways before shipment.
Food and beverages commands volume leadership. Dietary supplements capture margin expansion.
End User:
Technical capability gaps between customer types determine where formulation partnerships replace transactional supply.
- Food Manufacturers:Multinational and domestic brand owners with dedicated R&D functions. Southeast Asian contract manufacturers serving domestic Chinese brands now require suppliers to co-develop synbiotic finished products rather than deliver raw materials alone.
- Nutraceutical Companies:Specialized firms bridging supplement and functional food boundaries. India's emerging prebiotic category draws nutraceutical companies seeking first-mover positioning before FSSAI standards harden.
- Healthcare Providers:Clinical nutrition and medical food channels. Japanese hospital formulary committees specify prebiotic fibers with documented microbiome modulation in peer-reviewed literature.
- Consumers:Direct-to-purchase behavior concentrated in China's tier-one cities where functional food penetration runs deepest. E-commerce platforms enable ingredient specification transparency previously unavailable to retail buyers.
Food manufacturers anchor procurement volume. Nutraceutical companies are climbing fastest on technical service intensity.
Form:
Physical state selection trades off manufacturing integration ease against stability and dosing precision requirements.
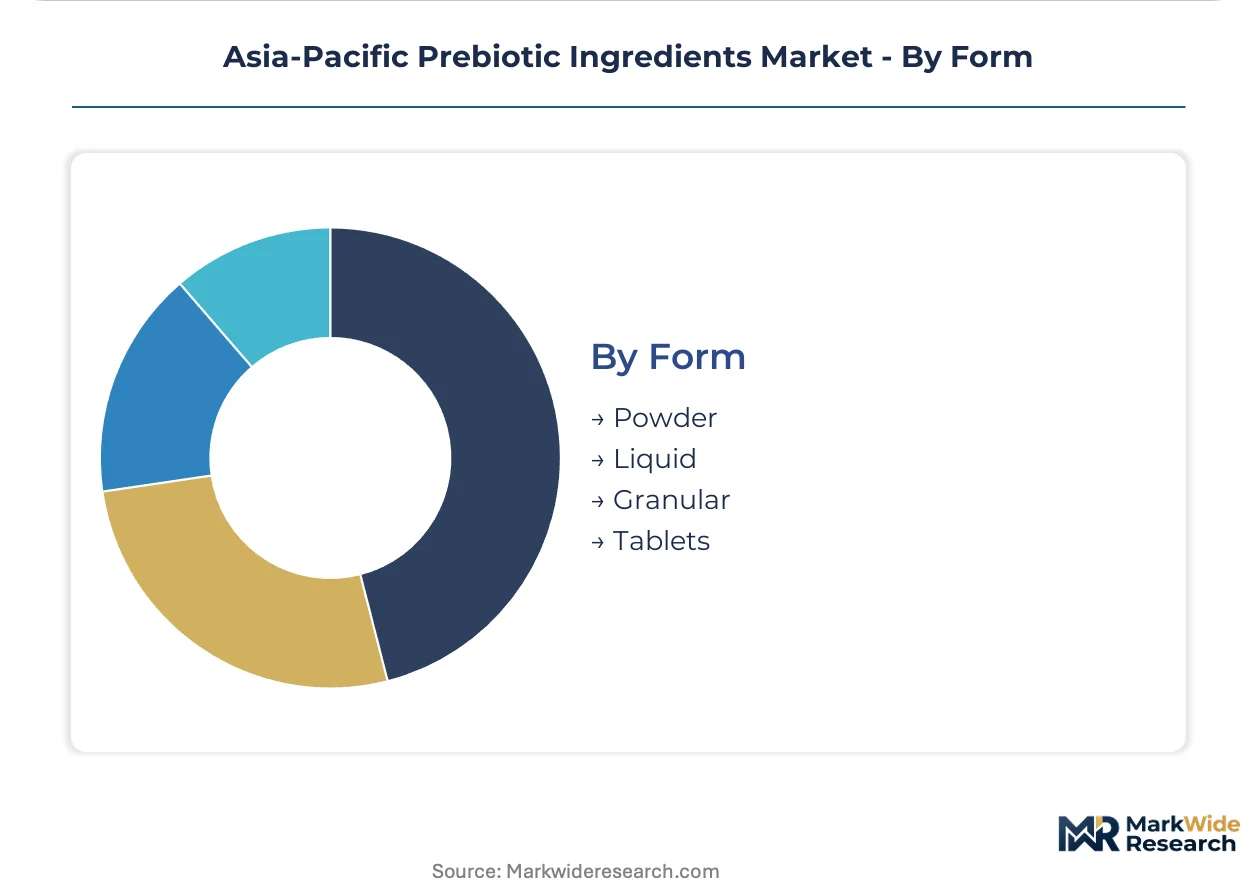
- Powder:Dominant format for bulk ingredient supply and dry blend applications. Chinese infant formula producers specify powder inulin with verified particle size distribution for homogeneous fortification.
- Liquid:Preferred for beverage integration and reduced dust exposure. Japanese fermentation houses deploy liquid galacto-oligosaccharide for direct dosing into continuous processing lines.
- Granular:Intermediate flow properties for tableting and capsule filling. Australian supplement brands specify granular acacia gum for clean-label positioning with mechanical handling advantages.
- Tablets:Finished dosage form bypassing manufacturer integration. South Korean direct-to-consumer channels show emerging tablet preference for convenience positioning in probiotic-prebiotic combination products.
Powder holds installed base dominance. Liquid formats are gaining share fastest on processing efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the region. Japanese and Australian buyers absorb premium pricing for substantiated ingredients, while Southeast Asian formulators prioritize cost-efficient GOS supply chains.
China
Shanghai and Guangzhou infant formula manufacturers drive volume demand for inulin with verified chain-length certificates. The National Health Commission mandates clinical dossiers for novel oligosaccharide approvals, elevating suppliers with regulatory affairs infrastructure. Yangtze River Delta fermentation houses are expanding captive GOS capacity to reduce Belgian-Dutch import dependency.
Japan
Tokyo and Osaka functional beverage brands specify oligofructose for rapid bifidogenic onset in Foods for Specified Health Uses applications. The Consumer Affairs Agency enforces microbiome assay standards that delay novel fiber substantiation timelines. Kanto region contract manufacturers now bifurcate production lines into food and listed medicine streams to manage TGA-aligned borderline classifications.
India
Maharashtra and Gujarat nutraceutical companies are establishing technical service infrastructure ahead of FSSAI alignment with Codex Alimentarius definitions. The national regulator's pending category formalization is attracting first-mover capital from synbiotic formulation specialists. Mumbai-based contract manufacturers are scouting prebiotic suppliers with in-house analytical laboratories.
Australia
Sydney and Melbourne clean-label brands specify acacia gum with verified sustainable sourcing credentials. The Therapeutic Goods Administration and Food Standards Australia New Zealand jointly govern borderline products, forcing exporters to commit to single regulatory pathways before shipment. Queensland extraction facilities are upgrading chain-length distribution certification capabilities to meet Chinese procurement specifications.
South Korea
Seoul Capital Area fermentation houses deploy immobilized enzyme columns for GOS production, cutting cycle times versus batch systems. The Ministry of Food and Drug Safety maintains lighter requirements for companion animal prebiotic applications, attracting second-tier suppliers lacking pharmaceutical-grade infrastructure. Busan-Ulsan industrial corridors are expanding dual-use facility investments to serve both food and clinical nutrition channels.
Asia-Pacific Prebiotic Ingredients Market Competitive Environment
Capability concentration sits with European extraction specialists; scale advantage sits with Asian fermentation houses. The market structures around three tiers: Belgian-Dutch agricultural processors controlling chicory root supply, Japanese and South Korean biotech houses with captive enzymatic synthesis, and Chinese state-backed conglomerates integrating backward into fermentation feedstocks. Dominant competitive moves include strategic partnerships for regulatory dossier sharing and capacity expansion in Vietnam and Indonesia to capture infant nutrition growth.
Within the European extraction tier, BENEO GmbH and Nexira SAS occupy positions anchored to chicory and acacia supply chains respectively. Among Asian fermentation specialists, CJ CheilJedang Corp. exemplifies the scale-driven archetype through South Korean captive production infrastructure. Baolingbao Biology Co., Ltd. represents the Chinese state-integrated model with Shandong-based manufacturing consolidation. These three anchors illustrate how geographic supply concentration maps to competitive positioning across the region.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| BENEO GmbH |
| Fonterra Co-operative Group Limited |
| Sensus |
| Nexira SAS |
| Baolingbao Biology Co., Ltd. |
| Cargill Incorporated |
| Shandong Bailong Group Co. |
| CJ CheilJedang Corp. |
| Others |
Value Chain & Pricing Dynamics
Belgian-Dutch chicory root concentration exposes East Asian formulators to euro-denominated input volatility and Suez corridor bottlenecks, compressing margin spreads between premium chain-length-certified inulin and commodity-grade alternatives while forcing procurement teams toward captive fermentation investments and regional GOS synthesis partnerships.
Pricing Analysis
Regulatory dossier bundling with technical service contracts drives lifetime value capture across the ingredient supply base. Three-tier pricing structure separates pharmaceutical-grade certified prebiotics from food-grade standard offerings and economy-grade commodity fibers. Price differentiation hinges on chain-length distribution documentation and clinical substantiation completeness. Cost compression in standard-grade inulin intensifies as Chinese infant formula manufacturers consolidate procurement volumes. Southeast Asian contract manufacturers exhibit highest price sensitivity; Japanese FOSHU-positioned brands absorb premium positioning.
Supply Chain Analysis
Extended payment terms from Belgian agricultural processors strain working capital for mid-tier East Asian formulators lacking supply-chain finance facilities. Geographic supply concentration centers on Belgium and the Netherlands for chicory-derived inulin, South Korea and Japan for enzymatic GOS synthesis, and China for captive fermentation feedstocks. Raw material dependencies include chicory root biomass, lactose feedstock for β-galactosidase conversion, and acacia gum resin. Single-source vulnerability runs through Suez-dependent European inulin shipments. Distribution runs through regional fermentation houses serving Southeast Asian contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Postbiotic and synbiotic finished formulations threaten standalone prebiotic ingredient margins, requiring incumbents to defend through integrated clinical substantiation and regulatory dossier control.
For Market Incumbents: Build regulatory dossier libraries as the primary moat against postbiotic substitution threats. Secure backward integration into chicory root processing or captive β-galactosidase fermentation capacity to reduce euro-denominated input exposure. Invest in chain-length distribution certification infrastructure to disqualify commodity traders from Chinese infant formula procurement. For New Entrants and Emerging Players: India's FSSAI category formalization window represents the most penetrable entry point before standards harden and incumbent technical service infrastructure dominates. Vietnam and Indonesia infant nutrition penetration in second-tier cities offers parallel white-space expansion. Lead with synbiotic formulation partnerships rather than commodity fiber supply to bypass established Belgian-Dutch extraction networks. For Investors and Strategic Acquirers: China's National Health Commission clinical trial mandate reshapes the acquisition landscape toward suppliers with regulatory affairs infrastructure and completed dossier portfolios. Five-to-ten-year viability favors Asian fermentation houses with immobilized enzyme column technology over European extraction-dependent models. Watch for FSSAI's Codex alignment announcement as the signal for first-mover capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | Captive lactose supply secures GOS production against commodity price swings. |
| Clinical Substantiation Partnership | Joint microbiome assay investment accelerates Japan CFSHU approval timelines. |
| Dual-Use Facility Certification | Pharmaceutical-grade cleanroom access opens clinical nutrition margin pools. |
| Regional Technical Service Expansion | Mumbai and Jakarta laboratories capture India's prebiotic category formalization. |
| Immobilized Enzyme Column Deployment | Continuous GOS bioprocessing halves cycle times versus batch fermentation. |
Study Parameters
The analysis maps inulin extraction, GOS enzymatic synthesis, oligofructose fractionation, and acacia gum processing segments, each validated through fermentation technology directors, infant formula procurement managers, regulatory affairs specialists at national health commissions, and contract manufacturing executives. Primary interview findings triangulate against secondary sources including NMPA food additive filings, FSSAI draft standards, MFDS companion animal regulations, TGA borderline classification determinations, and Codex Alimentarius prebiotic definition consultations. Bottom-up capacity and demand modeling cross-checks against top-down market sizing across ingredient chemistry tiers.
Assumptions held fixed include China's National Health Commission oligosaccharide approval pathway continuity, Belgian-Dutch chicory root supply dominance, and Japan's FOSHU framework stability; variables tested include FSSAI alignment timing, Suez corridor disruption frequency, and β-galactosidase yield improvement trajectories. Segmentation dimensions span product chemistry chain length, application dosage requirements, end-user technical sophistication, and regional regulatory cluster stringency. CAGRs derive from installed base growth rates adjusted for reformulation cycle timing and capacity expansion announcements. Forecast inputs incorporate infant formula birth rate projections and functional beverage penetration curves across tier-one Chinese cities.
Macroeconomic conditions sit as an overlay; deviation in euro-yuan exchange rates, Suez canal throughput capacity, or Chinese birth rate trajectories would shift the trajectory. Forecasts reflect documented assumptions; regulatory pathway acceleration, novel postbiotic technology displacement, or microbiome assay standardization breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Carotenes Market
Ingredients
Soy Derivatives Market
Ingredients
Virginiamycin Market
Ingredients
Mustard Oil Market
Ingredients
Europe Amino Acid Market
Ingredients
Coconut Derivatives Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Modified Maize Starch Market
Ingredients
Alkalized Cocoa Powder Market
Ingredients
China Corn Glucose Market
Ingredients
North America Fats and Oils Market
Ingredients
Amaranth Seed Oil Market
Ingredients
White Wheat Malt Market
Ingredients
Europe Agar Market
Ingredients
North America Rice Bran Oil Market