
 Grapefruit Peel Market | 2026-2036
Grapefruit Peel Market Size, Share, and Industry Trends Forecast 2026-2036
Grapefruit Peel Market Foresight
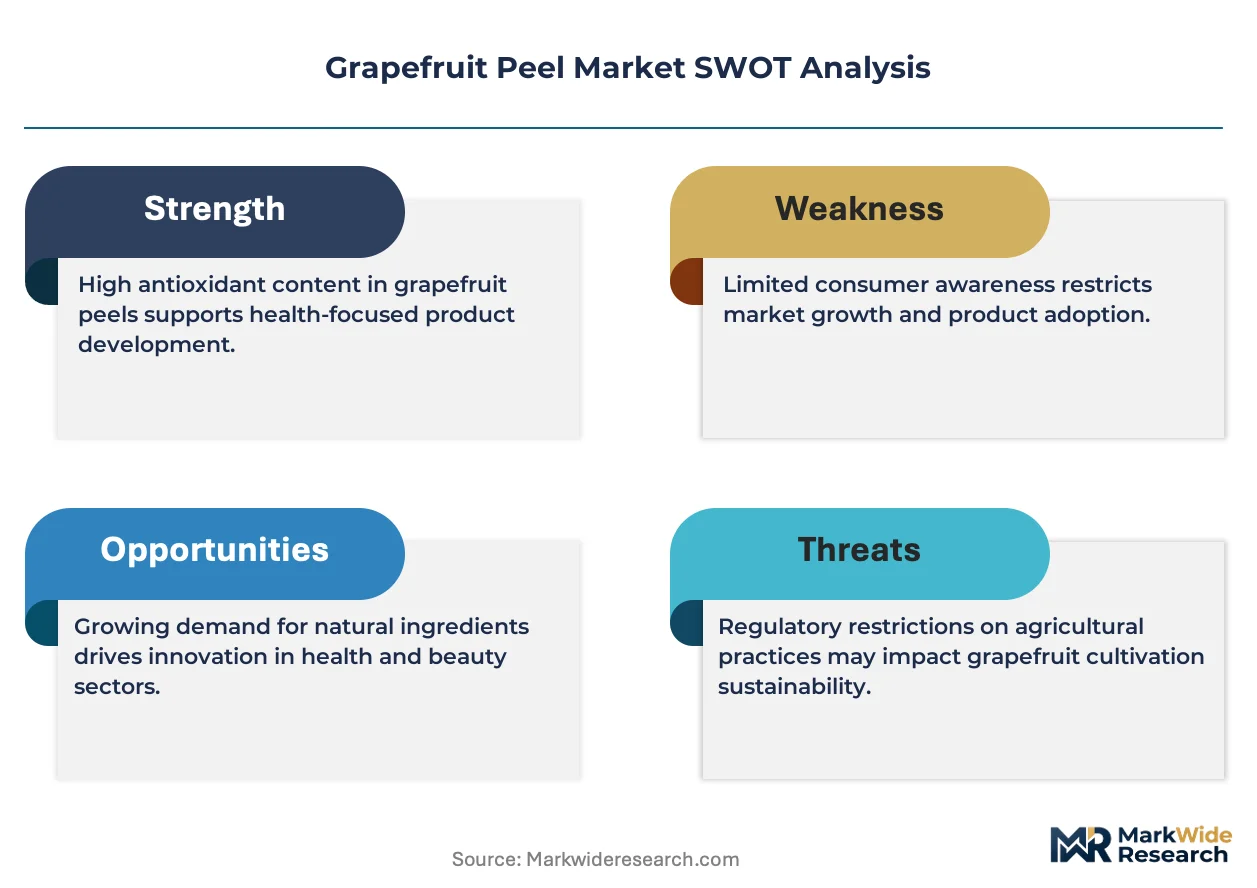
Premium cold-pressed essential oil grade is collapsing the commodity-conventional divide as buyers demand terpene profiles above 90% purity. Lionel Hitchen Limited leverages its English distillation heritage to anchor European aromatherapy supply chains. Symrise AG competes through captive citrus sourcing in subtropical growing belts. Mountain Rose Herbs differentiates via certified organic peel procurement networks spanning domestic and international growers.
Grapefruit peel comprises the flavedo and albedo layers of Citrus paradisi fruit, with cold-pressed oils yielding 0.5-1.0% by weight and dried peels containing 10-15% pectin by mass; manufacturers process this biomass into essential oils, pectin, flavonoid extracts, and dietary fiber additives for food, cosmetic, and pharmaceutical applications. Extract formats command the deepest margin pools due to concentrated bioactive content and pharmaceutical off-take. Powdered peel growth outpaces fresh formats as shelf-stable ingredients penetrate functional food formulations. Cosmetics application leads volume through clean-label preservative demand, though dietary supplements extract the highest per-kilogram value.
FDA GRAS status governs food-grade grapefruit peel oil in the United States, while EFSA Novel Food evaluations constrain new extract introductions in Europe; REACH registration requirements filter non-compliant suppliers from EU cosmetic ingredient channels. USDA organic certification and EPA pesticide residue limits further structure import eligibility for peel-derived products. Stakeholders must monitor evolving solvent residue thresholds and carbon accounting rules that will determine which extraction technologies retain market access.
Market Dynamics
Supercritical CO2 extraction is compressing the cost premium between solvent-based and clean-label extraction methods, forcing capital reallocation across European processing facilities as REACH compliance timelines tighten.
Growth Catalysts
- Clean-label cosmetic preservatives:Formulators in Germany and France now specify grapefruit peel extracts to replace synthetic parabens in skin-care formulations, pulling volume through Hamburg-based flavor houses.
- F-Gas Regulation:The EU mandate on fluorinated greenhouse gases is accelerating facility upgrades toward closed-loop CO2 systems in Spanish and Italian extraction plants.
- Pectin recovery from albedo:Food technologists deploy enzymatic hydrolysis to isolate high-methoxyl pectin for functional gelling applications in reduced-sugar confectionery.
Market Restraints
- Citrus greening disease:Huanglongbacterium infection in Florida and Texas groves is constraining fresh peel supply to domestic processors, forcing reliance on Brazilian and Mexican imports.
- Terpenene oxidation sensitivity:Cold-pressed oils degrade within 12-18 months without nitrogen blanketing, limiting just-in-time inventory models for small-batch aromatherapy buyers.
- REACH registration costs:ECHA dossier preparation for novel flavonoid extracts exceeds €100,000 per substance, filtering mid-tier suppliers from EU cosmetic channels.
Strategic Opportunities
- Pharmaceutical-grade naringin isolation:Korean and Japanese drug manufacturers now specify grapefruit peel-derived flavonoids for metabolic disorder research programs.
- USDA Organic certification arbitrage:Domestic peel processors can capture 40-60% price premiums by securing certified organic status for dried peel exports to European natural products distributors.
- Dietary fiber fortification:Bakery and snack manufacturers in California and New York are reformulating with insoluble peel fiber to achieve FDA-approved fiber content claims.
Industry Challenges
- Supercritical equipment operator scarcity:Extraction facilities in California and Texas struggle to recruit technicians certified in high-pressure CO2 system maintenance and safety protocols.
- Multi-jurisdiction residue testing:Exporters must reconcile EPA pesticide limits with EU maximum residue levels for citrus oils, creating analytical bottlenecks at third-party laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grapefruit Peel Market |
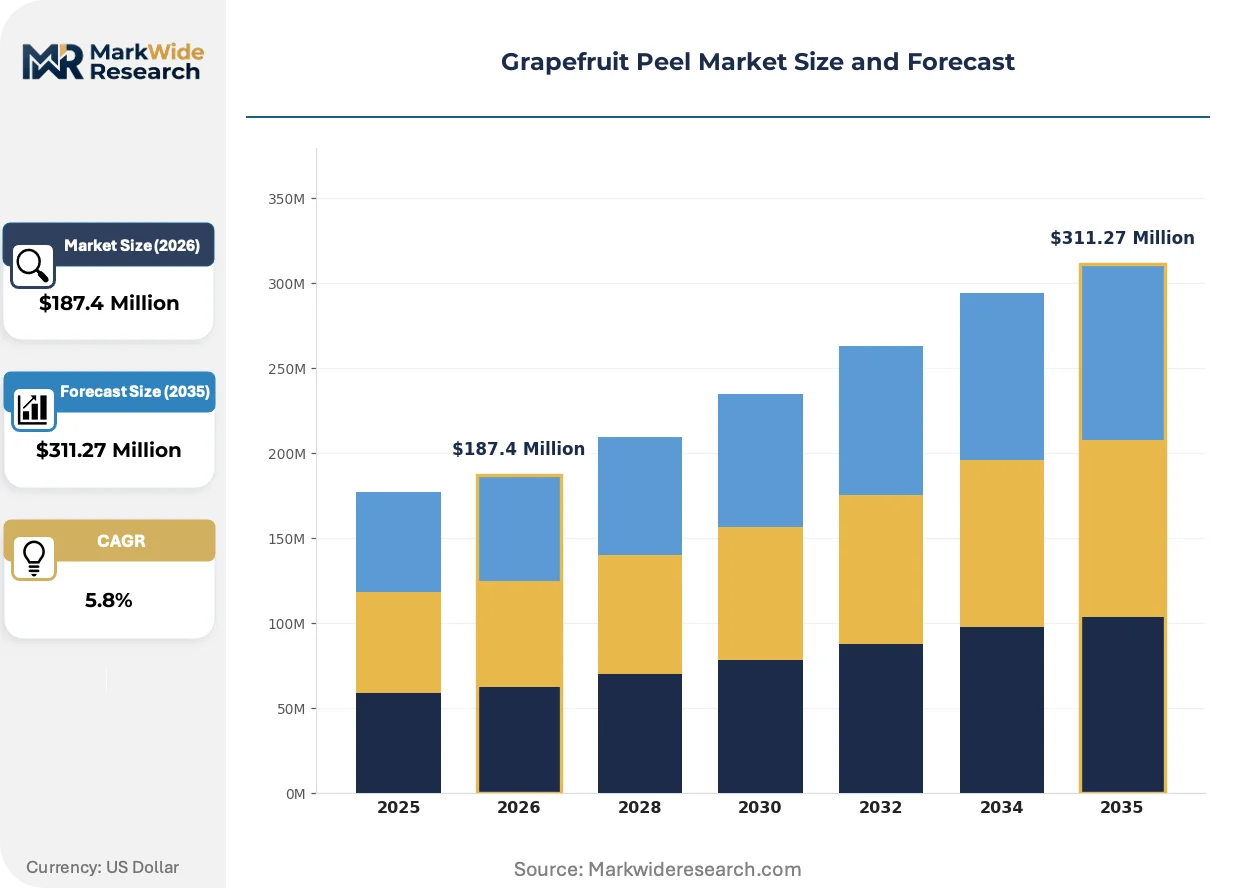
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Peel, Dried Peel, Powdered Peel, Extract Application: Cosmetics, Dietary Supplements, Food Additives, Pharmaceuticals Distribution Channel: Online Stores, Supermarkets, Health Food Stores, Specialty Shops End User: Manufacturers, Retailers, Wholesalers, Consumers |
| Companies Covered | BSG CraftBrewing, Mountain Rose Herbs, Lionel Hitchen Limited, Spices Inc., Vita Pakt Citrus Products, Symrise AG, doTERRA International, Young Living Essential Oils, Citrus and Allied Essences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grapefruit Peel Market Shifts & Advancements
Processing technology convergence with sustainability mandates is compressing extraction timelines while fragmenting buyer specifications across pharmaceutical, cosmetic, and food-grade purity tiers.
Supercritical CO2 extraction with integrated terpene fractionation is supplanting traditional steam distillation for high-value cosmetic applications. Premium aromatherapy brands now specify CO2-select grades with no detectable solvent residues. This shift is compressing margins for conventional distillation operators while creating two-year payback windows for upgraded Spanish and Italian facilities.
REACH registration deadlines for existing cosmetic ingredients are forcing extract suppliers to submit full toxicological dossiers to ECHA by 2026. Small-scale Mediterranean processors lacking regulatory affairs capacity are exiting the EU market. German and French buyers are consolidating supplier panels to three REACH-compliant sources per extract category.
Direct-procurement contracts between cosmetic formulators and citrus cooperatives are displacing traditional broker-mediated spot purchasing. Clean-label brands in California and New York now require peel provenance documentation back to individual groves. This behavioral shift is most visible in certified organic channels, where blockchain-traceable supply chains command 25-35% contract premiums over conventional equivalents.
Grapefruit Peel Market Segmentation
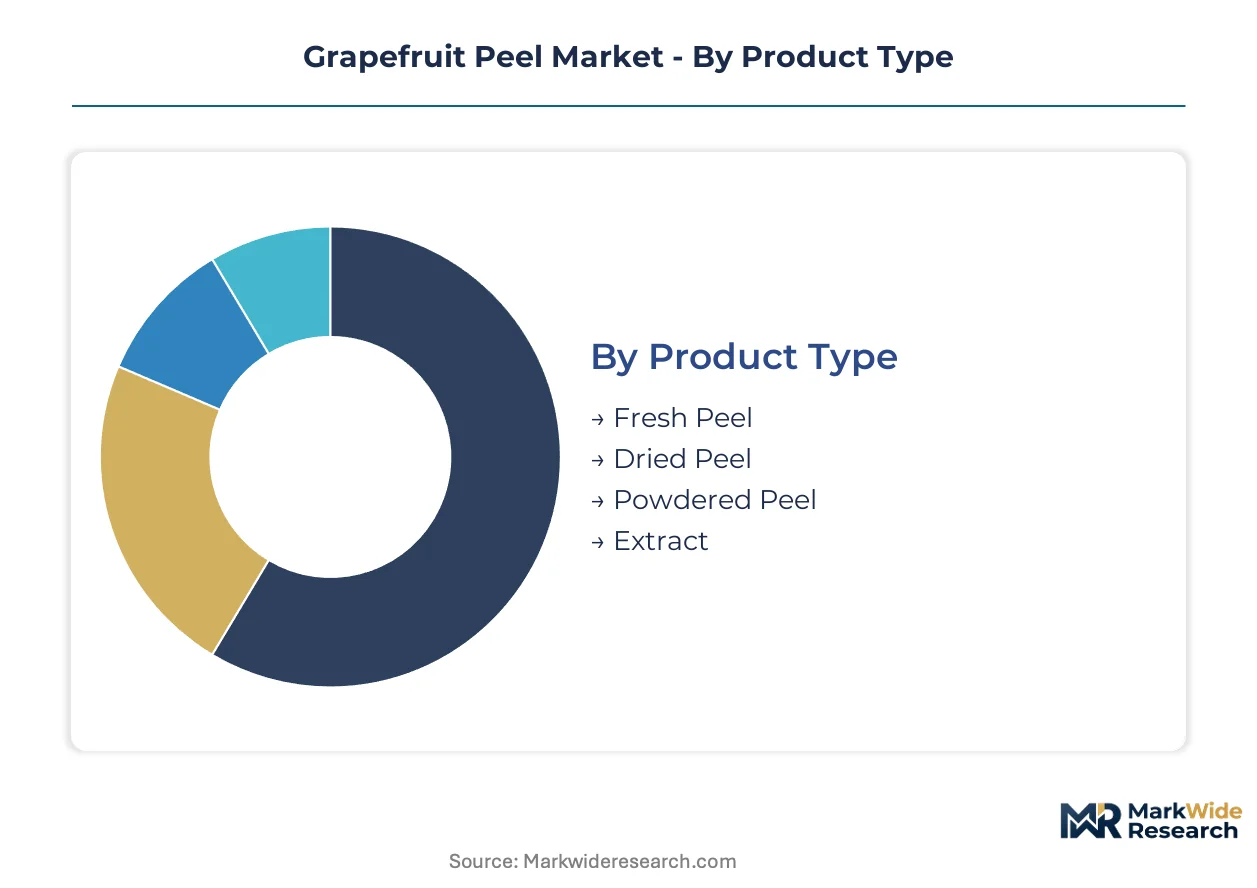
Segmentation in grapefruit peel markets exposes how regulatory thresholds fragment procurement specifications across food, cosmetic, and pharmaceutical channels. Buyers now source distinct grades—each with dedicated extraction protocols and compliance dossiers—rather than purchasing undifferentiated commodity peel.
Product Type:
FDA GRAS status and EFSA Novel Food evaluations create divergent purity requirements across formats, with pharmaceutical and cosmetic channels demanding residue documentation that commodity grades cannot supply.
- Fresh Peel:Cold-pressed within 48 hours of harvest to preserve terpene integrity above 90% purity. Hamburg-based flavor houses and California cosmetic formulators dominate procurement for immediate extraction into essential oils, though perishability constrains inventory models.
- Extract:Supercritical CO2 and solvent-based methods yield concentrated flavonoids and pectin for pharmaceutical off-take. Korean and Japanese drug manufacturers now specify grapefruit peel-derived naringin for metabolic disorder research, compressing cost premiums against conventional extraction.
- Dried Peel:Shelf-stable format with 10-15% pectin content enables cross-border shipment to European processors.
- Powdered Peel:Functional food manufacturers in New York and California deploy this format for fiber fortification claims.
Extract handles the majority of throughput; Powdered Peel is the fastest mover on share.
Application:
End-use concentration determines margin capture, with pharmaceutical and cosmetic channels extracting per-kilogram value multiples above food-grade applications.
- Cosmetics:Clean-label preservative demand from German and French formulators specifies grapefruit peel extracts to replace synthetic parabens. REACH-compliant supply chains through Hamburg flavor houses anchor European procurement.
- Dietary Supplements:Highest per-kilogram value segment driven by bioactive flavonoid concentration. EFSA Novel Food evaluations constrain new extract introductions, filtering non-compliant suppliers from EU channels.
- Food Additives:Pectin recovery from albedo layers supplies reduced-sugar confectionery gelling applications.
- Pharmaceuticals:Naringin isolation commands premium pricing for metabolic research programs.
Cosmetics leads absolute volume; Dietary Supplements climbs the fastest on value concentration.
Distribution Channel:
Channel selection reflects buyer scale and certification requirements, with large manufacturers bypassing retail intermediaries for direct cooperative contracts.
- Online Stores:Certified organic peel procurement networks leverage blockchain traceability for 25-35% contract premiums. Mountain Rose Herbs and comparable distributors dominate this channel for aromatherapy and small-batch cosmetic buyers.
- Specialty Shops:Premium cold-pressed essential oil grades reach European aromatherapy markets through English distillation heritage suppliers like Lionel Hitchen Limited.
- Supermarkets:Mass-market dried peel for culinary applications.
- Health Food Stores:Mid-tier organic peel for domestic consumers.
Online Stores handles the majority of throughput; Specialty Shops is the fastest mover on certified organic premium capture.
End User:
Procurement concentration among manufacturers is displacing traditional broker-mediated spot purchasing as clean-label brands mandate grove-level provenance documentation.
- Manufacturers:Cosmetic formulators in California and New York now require direct contracts with citrus cooperatives, bypassing intermediaries. Symrise AG and comparable operators leverage captive subtropical sourcing to secure volume commitments.
- Wholesalers:Consolidating supplier panels to three REACH-compliant sources per extract category as ECHA deadlines approach.
- Retailers:Mid-tier distributors facing margin pressure from direct procurement trends.
- Consumers:Small-volume aromatherapy and culinary purchases.
Manufacturers handles the majority of throughput; Wholesalers is the fastest mover on consolidation-driven efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt toward peel deficit in temperate manufacturing economies and surplus in subtropical growing belts. Germany and the United States run structural import dependence for cosmetic-grade extracts. Brazil, Mexico, and Spain supply raw peel and cold-pressed oils through Hamburg, Rotterdam, and Long Beach port clusters.
Germany
Flavor houses around Hamburg specify REACH-compliant grapefruit peel extracts for clean-label cosmetic preservatives. ECHA registration deadlines filter mid-tier suppliers from cosmetic ingredient channels. The Hamburg-rotterdam corridor anchors European procurement consolidation.
United States
California and New York cosmetic formulators drive demand for certified organic peel with blockchain-traceable supply chains. FDA GRAS status governs food-grade oil while EPA pesticide residue limits structure import eligibility. Florida citrus greening constrains domestic supply, forcing Brazilian and Mexican import reliance.
Brazil
Subtropical growing belts supply raw peel and cold-pressed oils to European and North American processors. The country's national agricultural regulator enforces residue limits that align with EU maximum residue levels for citrus oils. São Paulo state clusters concentrate harvesting and initial processing for export.
Spain
Mediterranean processors upgrade facilities toward supercritical CO2 extraction as EU F-Gas Regulation tightens. EFSA Novel Food evaluations constrain new extract introductions for dietary supplement channels. Valencia and Murcia regions host extraction plants serving German and French cosmetic formulators.
Mexico
Growing belt expansion supplies fresh peel to United States processors within 48-hour harvest windows. The country's national food safety regulator coordinates with EPA on pesticide residue reconciliation. Veracruz and Tamaulipas states concentrate cultivation for cross-border shipment.
Grapefruit Peel Market Competitive Landscape
Concentration sits with integrated flavor houses and certified organic distributors. Mid-tier Mediterranean processors face exit pressure from REACH compliance costs. Three archetypes dominate: captive citrus sourcing operators, certified organic procurement networks, and English distillation heritage suppliers. Capacity upgrades toward supercritical CO2 systems and direct-procurement contracts with citrus cooperatives represent the dominant competitive moves.
Within the heritage distillation tier, Lionel Hitchen Limited occupies a position anchoring European aromatherapy supply chains. Among certified organic specialists, Mountain Rose Herbs exemplifies procurement network models spanning domestic and international growers. At the integrated flavor house end, Symrise AG represents captive citrus sourcing strategies in subtropical growing belts.
| Leading Market Players |
|---|
| BSG CraftBrewing |
| Mountain Rose Herbs |
| Lionel Hitchen Limited |
| Spices Inc. |
| Vita Pakt Citrus Products |
| Symrise AG |
| doTERRA International |
| Young Living Essential Oils |
| Citrus and Allied Essences |
| Others |
Supply & Pricing Matrix
Supercritical CO2 extraction replacing solvent-based methods is compressing cost premiums between clean-label and conventional grades while redrawing procurement geography toward Spanish and Italian facilities with F-Gas Regulation compliance. This substitution dynamic concentrates pricing power with REACH-registered suppliers as mid-tier Mediterranean processors exit, forcing buyers toward consolidated German and French supply panels.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates certified organic cold-pressed oils from conventional steam-distilled grades and commodity dried peel, with REACH registration and carbon accounting compliance commanding 25-35% contract premiums. Cost compression in the standard tier is intensifying because supercritical equipment upgrades compress extraction timelines. Small-batch aromatherapy buyers exhibit highest price sensitivity due to terpene oxidation constraints limiting inventory models.
Supply Chain Analysis
Brazil and Mexico supply raw peel and cold-pressed oils to North American and European processors. The supply chain draws from subtropical growing belts, REACH-compliant extraction facilities, and blockchain-traceable procurement networks. Single-source vulnerability concentrates in Florida citrus greening-affected regions forcing Brazilian and Mexican import reliance. Distribution runs through Hamburg, Rotterdam, and Long Beach port clusters anchoring flavor house and cosmetic formulator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The grapefruit peel market represents high-growth disruption as EU F-Gas Regulation and REACH compliance timelines force capital reallocation toward supercritical CO2 extraction, filtering non-compliant suppliers and consolidating buyer panels.
For Market Incumbents: Compound defensive positioning through captive citrus sourcing in subtropical growing belts and backward integration into certified organic peel procurement networks. The REACH registration cost barrier exceeding six figures per substance filters mid-tier competitors, creating consolidation leverage for ECHA-dossier-ready operators with existing German and French buyer relationships. For New Entrants and Emerging Players: Lead with pharmaceutical-grade naringin isolation targeting Korean and Japanese drug manufacturer specifications for metabolic disorder research programs. The dietary supplements channel offers penetrable white space given EFSA Novel Food evaluation constraints filtering incumbent extract portfolios. A go-to-market angle anchored in USDA Organic certification arbitrage captures 40-60% price premiums for dried peel exports to European natural products distributors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Mediterranean extraction facilities facing REACH compliance-driven exit pressure. Long-term viability over a five-to-ten year window favors operators with integrated terpene fractionation capabilities and direct cooperative contracts with citrus growers. The signal to monitor is ECHA registration deadline adherence as a binary inflection determining EU market access retention.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Spanish and Italian facilities upgrade to meet EU F-Gas Regulation compliance timelines. |
| Backward Integration into Organic Sourcing | Cosmetic formulators secure direct contracts with citrus cooperatives for provenance documentation. |
| REACH Registration Dossier Investment | ECHA-compliant suppliers consolidate German and French buyer panels as mid-tier processors exit. |
| Pharmaceutical-Grade Naringin Isolation | Korean and Japanese drug manufacturers specify grapefruit peel-derived flavonoids for metabolic research. |
| Blockchain-Traceable Supply Chain Deployment | Certified organic channels command 25-35% contract premiums through grove-level documentation. |
Research Methodology
Initial hypotheses were tested against primary input from extraction facility operators, cosmetic formulator procurement leads, regulatory affairs specialists at flavor houses, and citrus cooperative managers and refined through secondary validation. Primary fieldwork combined structured interviews with supply chain stakeholders and technical assessments of supercritical CO2 system deployments. Secondary sources included ECHA registration databases, EU F-Gas Regulation compliance filings, USDA organic certification records, EPA pesticide residue monitoring data, and customs trade flows through Hamburg and Long Beach ports. Bottom-up volume modeling triangulated against top-down market sizing across extraction technology tiers.
Variance decomposition across the projection horizon isolates volume drivers by product format, application end-use, and regional regulatory cluster. Segmentation dimensions modeled include extraction method, certification status, purity grade, and buyer channel. CAGRs derive from time-series analysis of historical trade volumes and forward-looking procurement commitments from pharmaceutical and cosmetic off-takers. Industry-specific inputs incorporate citrus greening disease impact assessments and supercritical equipment operator scarcity constraints in California and Texas.
Forecasts assume regulatory continuity in EU REACH and F-Gas regimes, FDA GRAS status maintenance, and EPA pesticide limit stability; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Gold Kiwifruit Market
Fruits and Vegetables
Sea Buckthorn Market
Fruits and Vegetables
Jackfruit Market
Fruits and Vegetables
Spain Table Grape Market
Fruits and Vegetables
Argentina Fruits & Vegetables Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Europe Canned Fruits Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Global Fresh Fruits and Vegetables Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Japan Frozen Fruit Puree Market