
 Hydroxytyrosol Market | 2026-2036
Hydroxytyrosol Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxytyrosol Market Outlook
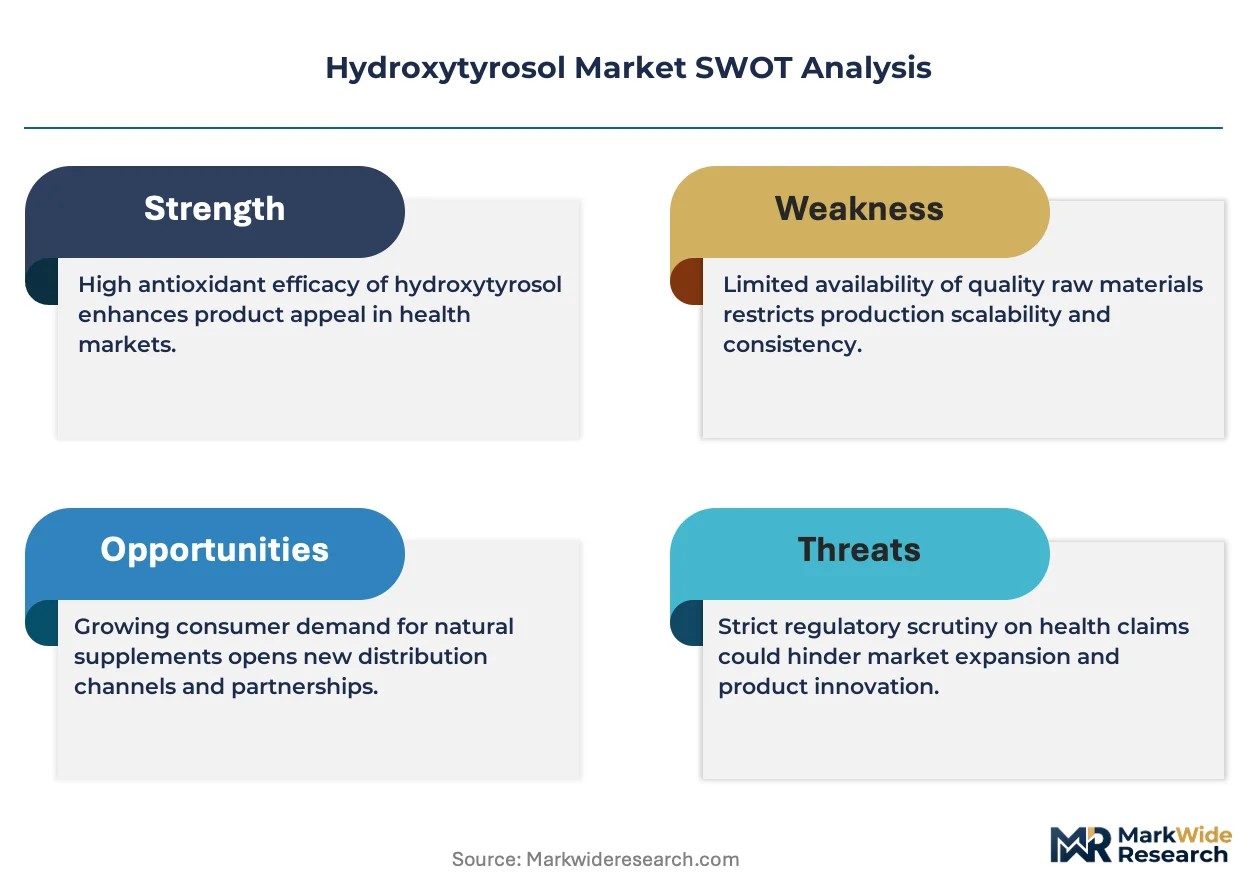
Spain is narrowing its position as the dominant extraction hub for hydroxytyrosol, with Andalusian olive processors expanding refining capacity to serve pharmaceutical-grade demand. Nutrafur SA leverages captive olive leaf supply from southern Spain to sustain vertical integration through the value chain. Indena anchors European botanical extraction leadership with advanced purification protocols for polyphenol isolation. Wacker Chemie AG competes through synthetic biology routes that bypass agricultural feedstock constraints.
Hydroxytyrosol is a diphenolic compound derived from olive biomass, typically comprising 5-20% concentration in standardized extracts depending on purification grade; manufacturers employ solvent extraction followed by chromatographic refinement to achieve pharmaceutical purity tiers for anti-inflammatory and antioxidant applications. Natural Hydroxytyrosol commands premium positioning in nutraceutical channels where EFSA-validated health claims justify ingredient cost premiums, while Synthetic Hydroxytyrosol is displacing botanical sources in cosmetic formulations where batch consistency outweighs natural provenance. The Application dimension shows Nutraceuticals and Cosmetics capturing margin pools as clean-label positioning intensifies across European and North American consumer markets.
EFSA polyphenol health claim frameworks and REACH chemical registration requirements shape product standards for hydroxytyrosol suppliers seeking European market access, with purity thresholds and toxicological documentation creating compliance barriers for unstandardized extractors. FDA New Dietary Ingredient notifications and FSSC 22000 food safety certifications further govern entry into US nutritional applications. Stakeholders must monitor evolving EFSA opinion updates on polyphenol dosage thresholds and emerging state-level dietary supplement regulations in the US that could fragment compliance requirements across jurisdictions.
Market Dynamics
EFSA's tightening purity thresholds for olive oil polyphenol health claims are forcing ingredient suppliers to upgrade extraction infrastructure, concentrating procurement power among Andalusian processors with certified chromatographic refinement capabilities.
Growth Catalysts
- EFSA-validated oxidation protection claims:Nutraceutical formulators in Germany and Spain now specify pharmaceutical-grade hydroxytyrosol for cardiovascular positioning, tightening supplier qualification criteria.
- Synthetic biology routes:Microbial fermentation platforms bypass olive harvest volatility, enabling year-round production with batch-to-batch consistency for cosmetic applications.
- Mediterranean olive processing infrastructure:Andalusian clusters leverage existing solvent extraction capacity to pivot toward high-margin polyphenol isolation.
Market Restraints
- Oleuropein feedstock concentration:Spain controls over 70% of EU olive leaf supply, creating geographic single-point vulnerability for natural extraction routes.
- REACH registration costs:Synthetic hydroxytyrosol manufacturers face toxicological documentation burdens exceeding EUR 200,000 per substance, freezing out mid-scale entrants.
- Batch-to-batch polyphenol variability:Natural extracts suffer seasonal concentration swings of 8-15 percentage points, complicating pharmaceutical formulation stability.
Strategic Opportunities
- US dietary supplement channel:FDA New Dietary Ingredient notification pathways remain underutilized by European suppliers, creating first-mover positioning for EFSA-compliant entrants.
- Clean-label cosmetic convergence:Natural hydroxytyrosol captures premium positioning as formulators phase out synthetic antioxidants in prestige skincare lines.
- EU Green Deal bioeconomy incentives:Olive biomass valorization projects in southern Italy qualify for circular economy funding, offsetting capital deployment for integrated processors.
Industry Challenges
- Chromatographic purification talent scarcity:Pharmaceutical-grade polyphenol isolation requires specialized analytical chemists concentrated in Basel and Milan contract research organizations.
- FSSC 22000 certification timelines:Food safety management system audits for hydroxytyrosol suppliers average 14-18 months, delaying commercial launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxytyrosol Market |
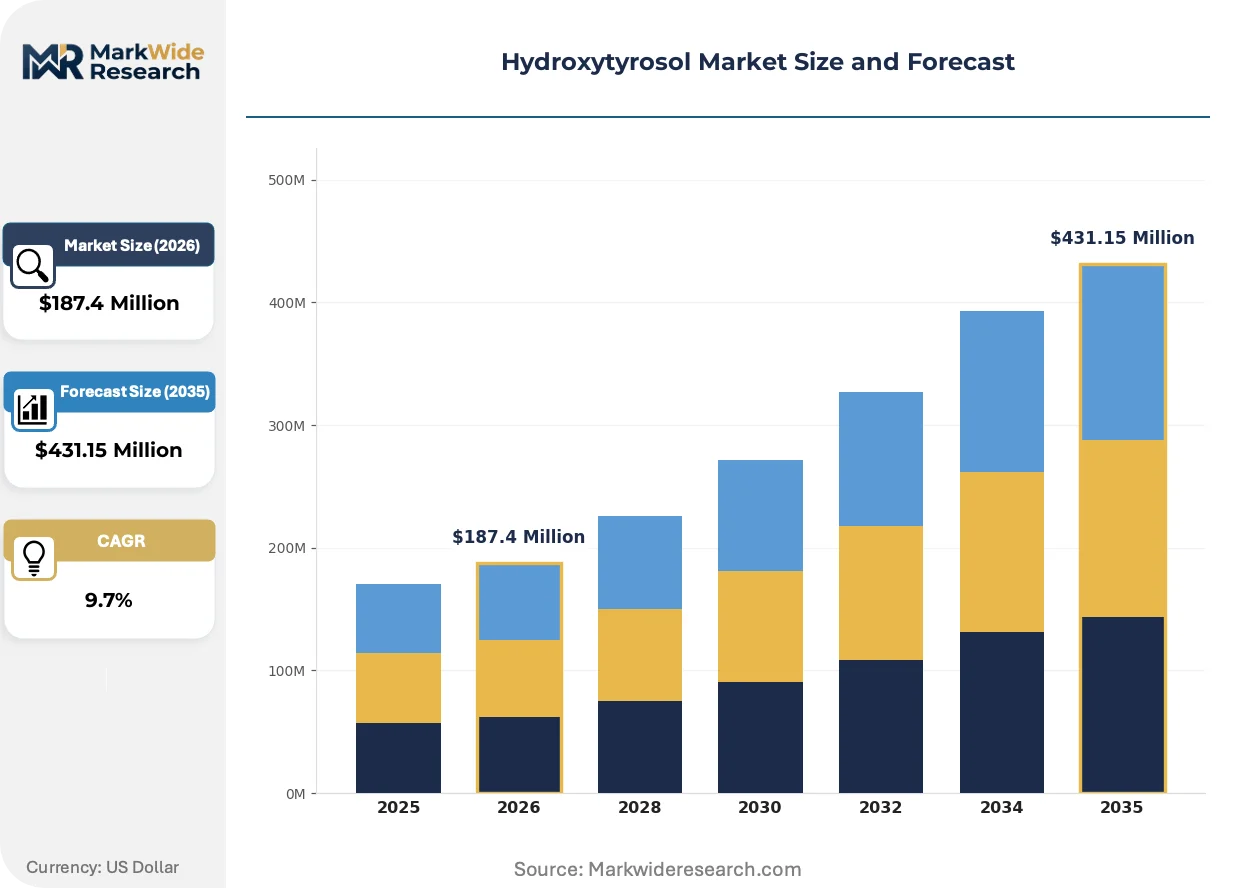
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Hydroxytyrosol, Synthetic Hydroxytyrosol, Standardized Extracts, Powdered Form Application: Food & Beverages, Nutraceuticals, Cosmetics, Pharmaceuticals Source: Olive Oil, Olive Leaves, Other Plant Sources, Laboratory Synthesis End User: Food Manufacturers, Cosmetic Companies, Dietary Supplement Providers, Research Institutions |
| Companies Covered | Nutrafur SA, Indena, Wacker Chemie AG, Bioenutra, DSM, Genosa, Alvinesa, Andy Biotech, Seprox BIOTECH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxytyrosol Market Strategic Shifts
Process analytical technology and synthetic biology are compressing the traditional agricultural dependency of polyphenol supply chains, while regulatory validation frameworks increasingly determine competitive access rather than production scale alone.
Supercritical CO2 extraction combined with simulated moving bed chromatography is digitizing yield optimization across Spanish and Italian processing facilities. Nutraceutical contract manufacturers now mandate real-time purity monitoring dashboards from ingredient suppliers. This convergence is compressing qualification cycles from 24 months to 12 months for pharmaceutical-grade entrants.
REACH authorization requirements for synthetic hydroxytyrosol intermediates are tightening toxicological data obligations through ECHA's 2024 substance evaluation work program. Manufacturers must submit extended one-generation reproductive toxicity studies for registration dossier updates. Cosmetic ingredient suppliers with pre-2023 registrations face accelerated compliance deadlines versus food-grade competitors.
Formulator procurement patterns are consolidating around certified extraction partnerships rather than spot-market commodity purchasing. German and Swiss nutraceutical brands now require chain-of-custody documentation from olive grove to final isolate. This behavioral shift concentrates volume with Andalusian processors holding dual EFSA and FSSC 22000 credentials.
Hydroxytyrosol Market Segmentation
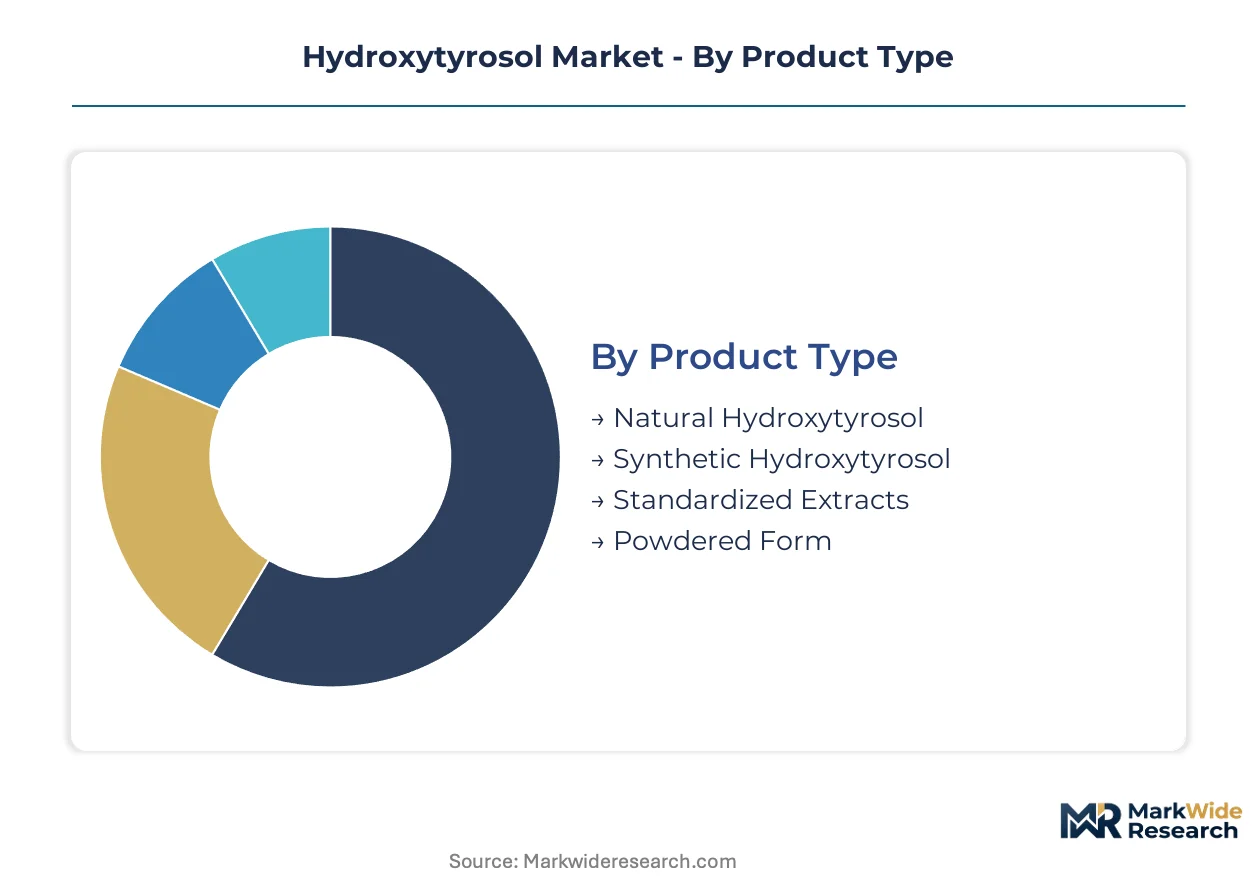
Hydroxytyrosol procurement patterns diverge sharply across purity grades and application channels. EFSA-validated health claims and REACH compliance requirements create tiered qualification barriers that reshape supplier-customer matching across each segment boundary.
Product Type:
Mature extraction technologies coexist with emerging synthetic biology platforms across the product spectrum, creating divergent margin structures and regulatory pathways.
- Natural Hydroxytyrosol:Isolated from olive biomass through solvent extraction and chromatographic refinement, typically achieving 5-20% concentration in standardized grades. German and Spanish nutraceutical formulators specify pharmaceutical-grade material for cardiovascular positioning, paying premiums validated by EFSA oxidation protection claims.
- Synthetic Hydroxytyrosol:Manufactured via microbial fermentation or chemical synthesis, delivering batch-to-batch consistency that cosmetic formulators prioritize over natural provenance. Wacker Chemie AG and fermentation specialists are expanding capacity to bypass agricultural feedstock constraints.
- Standardized Extracts:Intermediate purity grades serving functional food applications where EFSA threshold compliance is not required.
- Powdered Form:Convenience format for tablet and capsule manufacturing, with moisture stability specifications varying by customer quality tier.
Natural Hydroxytyrosol retains volume leadership; Synthetic Hydroxytyrosol holds the steepest expansion curve.
Application:
Cost tier differentiation separates premium pharmaceutical positioning from mass-market functional food incorporation, with compliance documentation costs driving stratification.
- Nutraceuticals:Capsule, tablet, and liquid supplement formats leveraging EFSA-validated health claims for antioxidant and cardiovascular positioning. German contract manufacturers now mandate chain-of-custody documentation from olive grove to isolate, consolidating procurement with certified Andalusian processors.
- Cosmetics:Skincare and anti-aging formulations where clean-label positioning drives natural hydroxytyrosol adoption despite higher ingredient costs. Prestige brands in Switzerland and France are phasing out synthetic antioxidants in favor of botanical alternatives.
- Food & Beverages:Functional olive oil enrichment and beverage applications operating below EFSA claim thresholds, prioritizing cost over pharmaceutical-grade purity.
- Pharmaceuticals:Drug development and clinical trial material requiring full toxicological documentation and GMP manufacturing compliance.
Nutraceuticals capture the dominant revenue pool; Cosmetics are climbing the fastest as clean-label positioning intensifies.
Source:
Supply concentration in Mediterranean olive processing infrastructure creates geographic dependency patterns that synthetic routes seek to disrupt.
- Oil Leaves:Primary feedstock for commercial extraction, with oleuropein concentration varying 8-15 percentage points seasonally. Spain controls over 70% of EU supply, creating single-point vulnerability for natural extraction routes.
- Olive Oil:Secondary source with lower polyphenol concentration, typically reserved for premium traceability claims and protected designation of origin positioning.
- Other Plant Sources:Experimental feedstocks including olive pomace and secondary olive biomass streams qualifying for EU Green Deal circular economy incentives.
- Laboratory Synthesis:Microbial and chemical production platforms eliminating harvest volatility, with REACH registration costs exceeding EUR 200,000 freezing out mid-scale synthetic entrants.
Olive Leaves retain volume leadership; Laboratory Synthesis holds the steepest expansion curve.
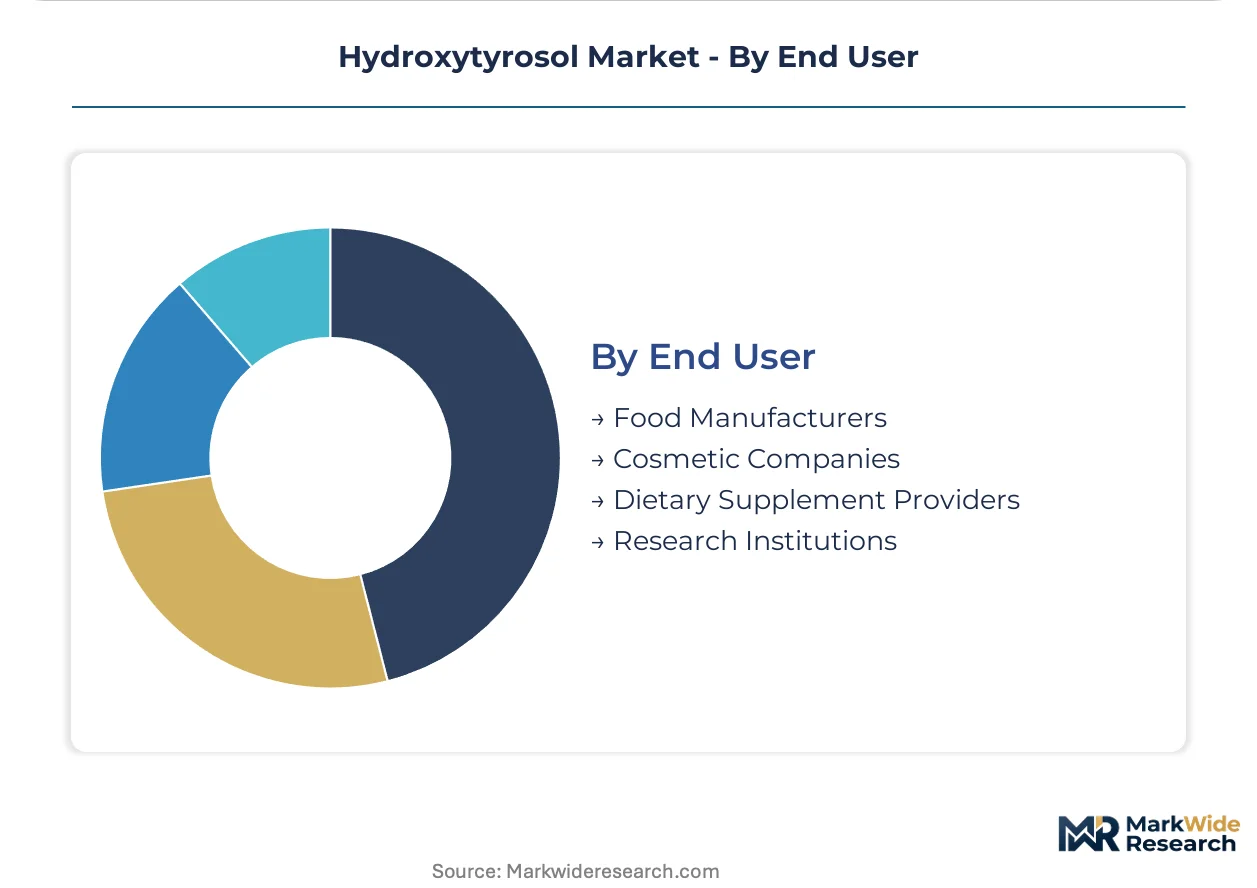
End User:
Customer type determines qualification intensity, with dietary supplement providers imposing the most stringent certification requirements.
- Dietary Supplement Providers:Brands and contract manufacturers requiring FSSC 22000 food safety certification and EFSA-compliant health claim documentation. Audit timelines average 14-18 months, delaying commercial launch schedules for new suppliers.
- Cosmetic Companies:Formulators prioritizing batch consistency and clean-label positioning, with prestige skincare lines driving natural hydroxytyrosol premiums.
- Food Manufacturers:Functional food and beverage producers operating below pharmaceutical purity thresholds, with procurement decisions driven by cost and basic safety compliance.
- Research Institutions:Academic and clinical trial material buyers requiring small-batch pharmaceutical-grade supply with full analytical characterization.
Dietary Supplement Providers retain volume leadership; Cosmetic Companies are expanding most quickly as clean-label convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seventy percent of EU olive leaf supply originates from Spanish processors, concentrating extraction infrastructure around Andalusian solvent-refining clusters while synthetic biology platforms in Germany and Switzerland seek to bypass this geographic dependency.
Spain
Andalusian olive processors dominate pharmaceutical-grade hydroxytyrosol output, with Sevilla and Jaén clusters expanding chromatographic refinement capacity to serve EFSA-validated nutraceutical demand. Spain's national food safety agency enforces strict polyphenol purity documentation under EU food law harmonization. Captive olive leaf supply from southern estates sustains backward integration through extraction and isolation stages.
Germany
German contract manufacturers now mandate chain-of-custody documentation from grove to isolate, consolidating procurement with certified Mediterranean suppliers. The Federal Office of Consumer Protection and Food Safety monitors REACH compliance for synthetic hydroxytyrosol intermediates entering cosmetic applications. Munich and Frankfurt nutraceutical formulators specify pharmaceutical-grade material for cardiovascular positioning.
Italy
Southern Italian processors qualify for EU Green Deal circular economy funding through olive biomass valorization projects in Puglia and Calabria. The Ministry of Health oversees novel food ingredient approvals for hydroxytyrosol-enriched functional foods. Integrated extraction facilities in Bari are pivoting from bulk olive oil production to high-margin polyphenol isolation.
Switzerland
Swiss prestige skincare brands are phasing out synthetic antioxidants in favor of botanical hydroxytyrosol despite higher ingredient costs. Swissmedic regulates cosmetic ingredient safety assessments for polyphenol-based formulations. Basel contract research organizations concentrate the specialized analytical chemists required for pharmaceutical-grade polyphenol isolation.
United States
FDA New Dietary Ingredient notification pathways remain underutilized by European suppliers, creating first-mover positioning for EFSA-compliant entrants. California dietary supplement brands are specifying certified extraction partnerships rather than spot-market commodity purchasing. Los Angeles and San Diego cosmetic formulators prioritize batch consistency for clean-label anti-aging lines.
Hydroxytyrosol Market Competitive Environment
Botanical extraction specialists and synthetic biology platforms split the market into divergent margin structures, with natural-route players commanding premium pricing validated by EFSA health claims while fermentation-based manufacturers compete on batch consistency. The vendor base concentrates around Andalusian processors with certified chromatographic capabilities and German chemical conglomerates with REACH-registered synthetic routes. Strategic archetypes include vertically integrated olive processors, contract research organization partnerships, and microbial fermentation specialists. Competitive moves center on capacity expansion in pharmaceutical-grade purification and strategic partnerships securing captive feedstock supply.
Within the botanical extraction tier, Nutrafur SA and Indena exemplify European leadership in polyphenol isolation, with the former representing Spanish vertical integration into olive leaf supply and the latter anchoring Italian contract extraction expertise. Wacker Chemie AG occupies a position among synthetic biology practitioners seeking to bypass agricultural feedstock constraints through microbial fermentation platforms. These three companies illustrate the competitive tension between natural provenance and batch consistency that defines procurement decisions across nutraceutical and cosmetic end uses.
| Leading Market Players |
|---|
| Nutrafur SA |
| Indena |
| Wacker Chemie AG |
| Bioenutra |
| DSM |
| Genosa |
| Alvinesa |
| Andy Biotech |
| Seprox BIOTECH |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Andalusian chromatographic refinement facilities is tightening supplier pricing power while forcing German nutraceutical buyers into longer qualification cycles and premium contract terms. EFSA-validated health claim requirements concentrate procurement among certified processors, compressing margin flexibility for mid-tier extractors unable to achieve pharmaceutical-grade purity thresholds.
Pricing Analysis
EFSA health claim regulations dictate the pricing tier structure across the hydroxytyrosol market, separating pharmaceutical-grade natural isolates from standard cosmetic-grade synthetics. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity: EFSA-compliant nutraceutical material commands the highest premiums, REACH-registered synthetic routes occupy the mid-tier, and unstandardized extracts compete on cost in functional food channels. Cost compression in standard-grade tiers is intensifying because synthetic biology platforms are expanding fermentation capacity, eroding the agricultural feedstock cost advantage. Dietary supplement providers show the least price sensitivity due to health claim validation requirements, while food manufacturers operating below EFSA thresholds exhibit the highest price elasticity.
Supply Chain Analysis
Extended payment terms from Spanish olive processors to Andalusian leaf suppliers are stabilizing working capital across the upstream value chain. Supply concentrates in Spain, Italy, and Greece for olive leaf feedstock, with synthetic biology platforms emerging in Germany and Switzerland as alternative production nodes. The supply chain draws from oleuropein-rich olive leaves, chromatographic purification resins, and pharmaceutical-grade solvents as critical inputs. Single-source vulnerability in Spanish olive leaf supply creates structural exposure to harvest volatility and climate disruption. Distribution runs through certified extraction partnerships rather than spot-market commodity channels, with chain-of-custody documentation now mandatory for German and Swiss nutraceutical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydroxytyrosol market is approaching a platform-economics inflection as EFSA-validated health claim frameworks create interoperability standards that consolidate procurement around certified data infrastructures rather than commodity spot markets.
For Market Incumbents: Harden EFSA certification moats by accelerating FSSC 22000 audit completion and securing captive olive leaf supply through estate partnerships in Andalusia. Synthetic biology entrants threaten natural-route incumbents with batch consistency advantages; defend through vertical integration into chromatographic refinement capacity and real-time purity monitoring dashboards that compress customer qualification cycles. For New Entrants and Emerging Players: US dietary supplement channels with underutilized FDA New Dietary Ingredient notification pathways represent the most penetrable entry point for EFSA-compliant European suppliers. Cosmetic applications in Swiss prestige skincare lines offer secondary white-space as clean-label positioning intensifies. A go-to-market angle anchored in chain-of-custody documentation and certified extraction partnerships differentiates against commodity spot-market competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Andalusian processors with dual EFSA and FSSC 22000 credentials serving German contract manufacturers. Long-term viability over a multi-year window favors acquisition targets with integrated extraction infrastructure and captive feedstock supply rather than toll-processing dependent models. The signal to watch is EFSA opinion updates on polyphenol dosage thresholds that could fragment compliance requirements and reshape competitive access.| Strategic Initiative | Industry Significance |
|---|---|
| Chromatographic Capacity Expansion | Andalusian processors upgrading purification infrastructure capture EFSA-validated nutraceutical demand from German formulators. |
| Captive Feedstock Integration | Estate-level olive leaf supply agreements insulate natural extraction routes from harvest volatility and geographic concentration risk. |
| Synthetic Biology Platform Development | Microbial fermentation specialists bypass Spanish agricultural dependency while meeting REACH registration requirements for cosmetic applications. |
| Chain-of-Custody Certification | FSSC 22000 and EFSA dual credentials compress customer qualification timelines and consolidate procurement power. |
| US Regulatory Pathway Navigation | FDA New Dietary Ingredient notification completion unlocks first-mover positioning in underpenetrated American supplement channels. |
Study Parameters
Cross-validation between primary interviews with extraction facility managers, nutraceutical procurement directors, and cosmetic formulators and secondary validation through EFSA opinion databases, REACH registration dossiers, and FSSC 22000 certification records anchors the qualitative findings. Customs data on olive leaf trade flows, SEC filings from publicly listed ingredient suppliers, and EU Green Deal circular economy funding disclosures provide quantitative grounding. Bottom-up capacity assessments across Andalusian processing clusters triangulate against top-down demand estimates from German and Swiss contract manufacturers.
Calibration against historical EFSA health claim adoption curves and polyphenol ingredient price trajectories informs the projection framework. Segmentation dimensions modeled include product type (natural, synthetic, standardized extracts), application channel (nutraceuticals, cosmetics, food and beverages, pharmaceuticals), purity grade tier, and regional regulatory cluster. CAGRs derive from weighted average growth assumptions across these segments, with olive harvest volatility indices and synthetic biology capacity buildout schedules as industry-specific forecast inputs across the analysis window.
Practitioners should monitor EFSA dosage threshold revisions, REACH authorization timeline accelerations, and synthetic biology platform scale-up milestones for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
United Arab Emirates Sunflower Oil Market
Ingredients
Food Colors Market
Ingredients
High Protein Flour Market
Ingredients
North America Agar Market
Ingredients
Fresh Yeast Market
Ingredients
Commercial Amino Acids Market
Ingredients
Europe Agar Market
Ingredients
South America Fermented Ingredients Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Textured Wheat Protein Market
Ingredients
Cocoa Butter Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Dark Yeast Extract Market
Ingredients
Bean Ingredients Market
Ingredients
Corn Oil Market
Ingredients
South America Malt Ingredient Market